
 Instant Noodle Vending Machine Market | 2026-2036
Instant Noodle Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Noodle Vending Machine Market Insights
The instant noodle vending machine category is pivoting toward two distinct performance tiers. Premium units now integrate induction heating and customizable broth dispensers, while commodity machines retain basic boil-and-dispense mechanics at lower price points. Nissin Foods leverages its brand recognition in Japan to anchor high-traffic station deployments. Fuji Electric Co., Ltd. sustains manufacturing scale through captive production of thermal control systems. Yo-Kai Express differentiates with AI-driven inventory management that reduces spoilage in unmanned locations.
An instant noodle vending machine is a self-service commercial appliance that stores pre-packaged noodle portions, heats water to temperatures between 85°C and 100°C, and dispenses finished bowls within 45 to 90 seconds. These units serve high-frequency, low-labor food service environments where speed and minimal staffing override full kitchen infrastructure. Gourmet and spicy product type configurations command margin premiums in urban Asian markets where flavor novelty drives repeat purchases. Mobile deployment segments are expanding fastest in festival and construction site applications, while fixed location installations retain volume dominance at transportation hubs. Healthy variants remain nascent but attract premium positioning among office worker end users seeking reduced-sodium options.
Japan's METI enforces appliance energy conservation standards that compel manufacturers to adopt heat-pump water systems or face market exclusion. South Korea's MFDS mandates food contact material safety certifications for all heated dispensing surfaces, creating compliance barriers for imported equipment. China's SAMR implements GB standards for electrical safety in unattended food service machinery that affect cross-border supply arrangements. Stakeholders must monitor how divergent certification timelines across these three markets reshape sourcing strategies and localization requirements.
Market Dynamics
Japan's METI energy efficiency mandates are compressing thermal system architectures across the instant noodle vending machine supply base, forcing manufacturers to abandon resistive heating in favor of heat-pump water modules or exit the market entirely.
Growth Catalysts
- Induction heating modules:South Korea's transit corridor operators are retrofitting existing fleets with electromagnetic water heating that cuts standby power draw by half. This technology satisfies MFDS surface safety certifications while accelerating serve times.
- University campus deployments:Japan's higher education institutions are expanding 24-hour automated food access to reduce cafeteria labor costs. These installations prioritize machines with customizable broth dispensers for student flavor variety.
- Mobile deployment configurations:Festival and construction site applications in dense Asian urban centers are driving demand for trailer-mounted units with self-contained water filtration and waste management systems.
Market Restraints
- Heat-pump component concentration:Captive production of thermal control systems by established Japanese electronics suppliers creates supply bottlenecks for new market entrants seeking compliant heating modules.
- Stainless steel input volatility:Food-grade 304 stainless steel for heated dispensing surfaces faces price swings tied to nickel ore supply disruptions from Indonesian export restrictions.
- Substitution by ghost kitchen micro-delivery:South Korean urban consumers increasingly substitute vending machine purchases with app-ordered fresh noodle delivery competing on speed and customization.
Strategic Opportunities
- Reduced-sodium product lines:Japan's office worker demographic is creating pull for healthy variants with broth reformulation, commanding premium positioning in central business district installations.
- AI-driven spoilage reduction:Machine learning inventory management that predicts demand patterns by location and weather is opening unmanned deployment in low-traffic secondary transit nodes.
- China's GB electrical safety standards:SAMR certification harmonization is creating a pathway for compliant manufacturers to access cross-border supply arrangements across Northeast Asian markets.
Industry Challenges
- Embedded systems firmware integration:Retrofitting legacy vending fleets with IoT payment and telemetry modules requires scarce firmware engineering talent familiar with both thermal hardware and financial transaction protocols.
- Multi-jurisdiction certification sequencing:Manufacturers face misaligned timelines between Japan's METI energy conservation approvals, South Korea's MFDS food contact certifications, and China's SAMR electrical safety reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Noodle Vending Machine Market |
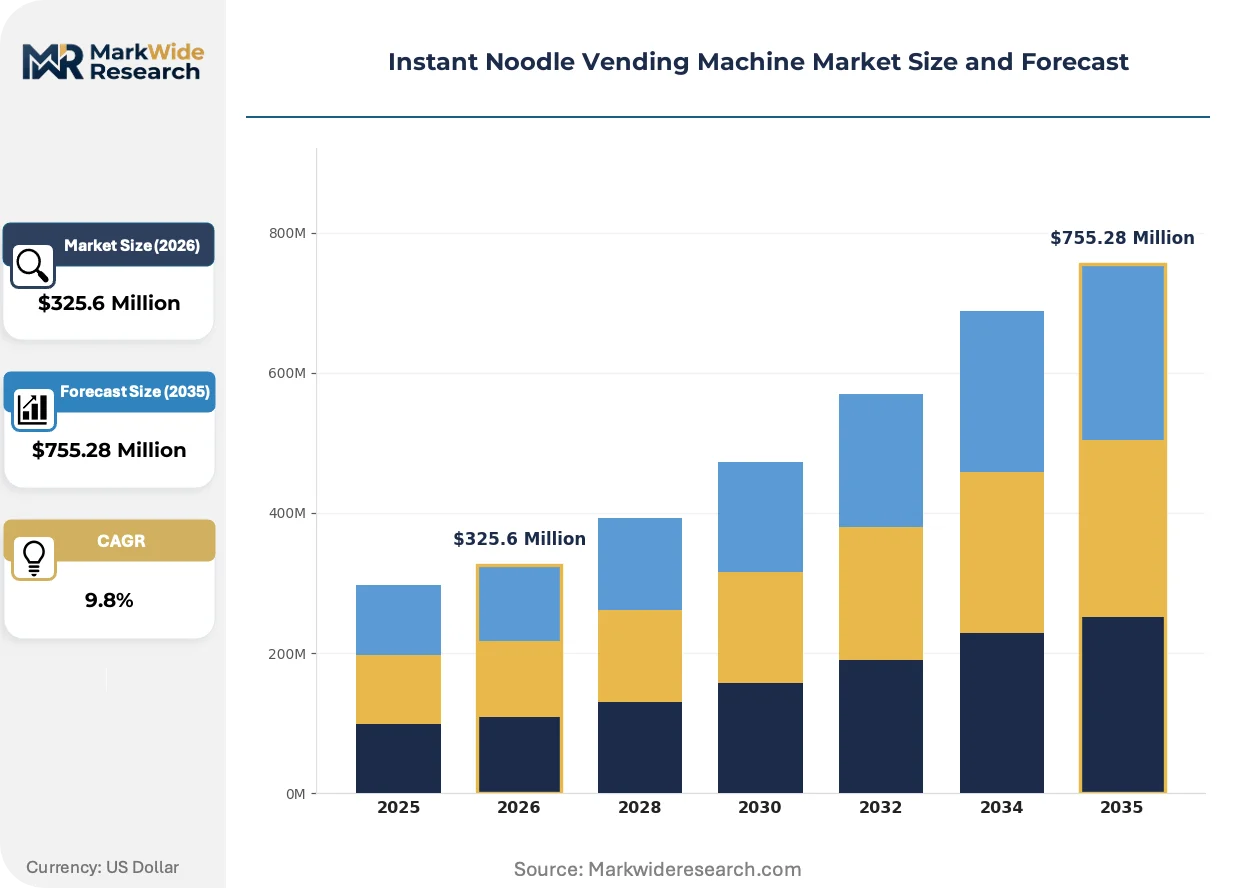
| Market Size in 2026 | $325.6 Million |
| Market Size in 2035 | $755.28 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Gourmet, Healthy, Spicy Deployment: On-Premise, Mobile, Fixed Location, Event-Based End User: College Students, Office Workers, Tourists, Family Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Nissin Foods, Maruchan, Inc., Fuji Electric Co., Ltd., Crane Merchandising Systems, Sanden Holdings Corporation, Evoca Group, Seaga Manufacturing Inc., Azkoyen Group, Yo-Kai Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Noodle Vending Machine Market Trends and Innovations
Equipment architectures are fragmenting into performance tiers while regulatory pressure on thermal efficiency accelerates component substitution cycles across Northeast Asian supply chains.
Induction coil water heating is modularizing the thermal core of premium vending units, allowing rapid field replacement of heating elements without full machine decommissioning. Transit operators in Seoul and Tokyo are adopting these swappable modules to minimize downtime during peak ridership hours. This modularity is compressing maintenance contract structures from annual service agreements toward component-level subscription models.
Japan's METI appliance energy conservation standards are forcing heat-pump water system adoption across all commercial vending equipment categories. Manufacturers without captive thermal engineering capabilities face market exclusion or dependency on licensed subsystem suppliers. South Korean and Chinese import entrants are responding by establishing local joint ventures with established Japanese thermal control producers.
Flavor novelty procurement is displacing single-brand loyalty in urban Asian vending locations, with operators diversifying machine inventory across multiple noodle suppliers to sustain repeat purchase frequency. This portfolio approach is fragmenting exclusive supply agreements that historically anchored high-traffic station deployments. The shift is most visible in Seoul's subway network and Osaka's regional rail corridors.
Instant Noodle Vending Machine Market Segmentation
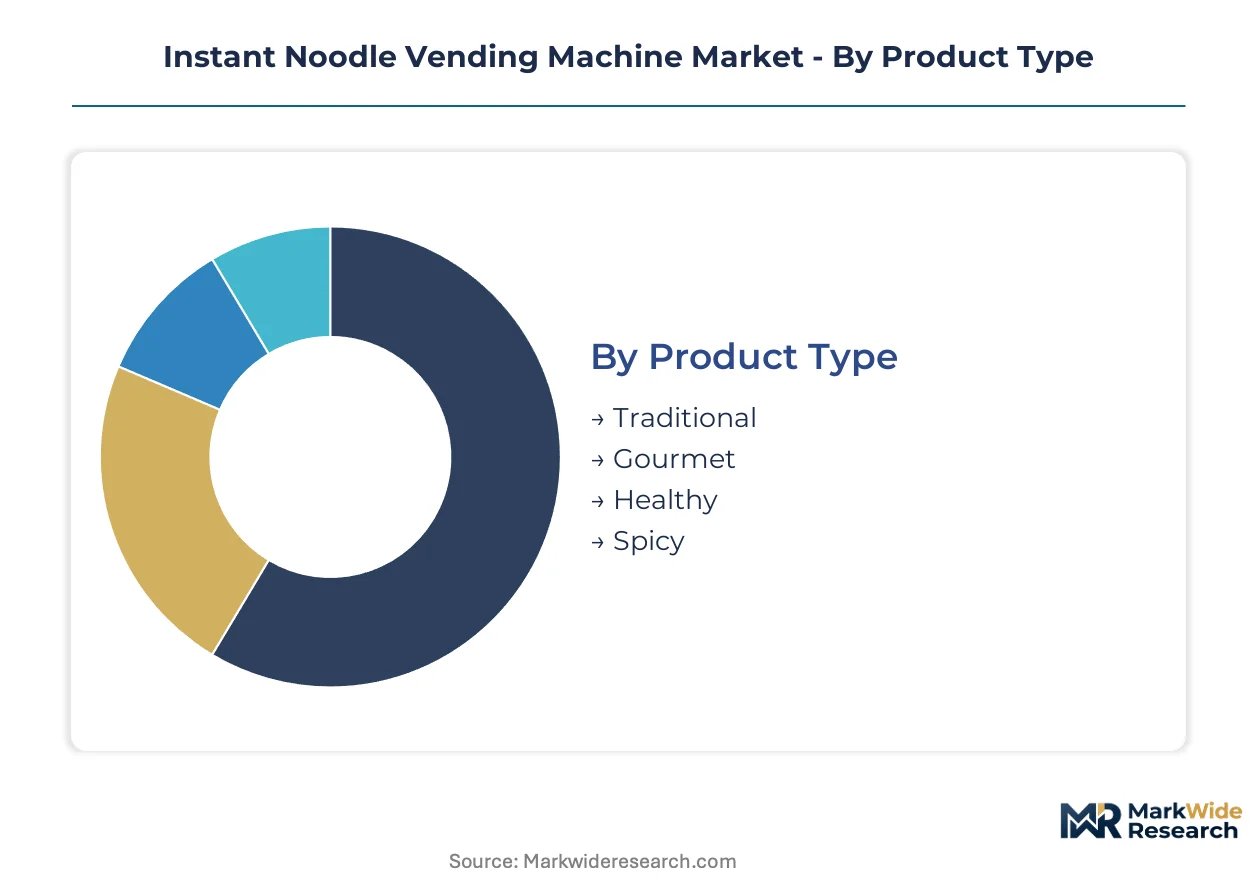
Segmentation in the instant noodle vending machine market determines capital allocation, regulatory pathway complexity, and operational model selection. Equipment specifications vary sharply across deployment contexts and end-user expectations.
Product Type:
Capital intensity escalates with flavor customization depth and ingredient handling complexity.
- Gourmet:Units integrate induction heating modules and multi-broth dispensers supporting temperature precision within 2°C variance. Japan's university campuses and Seoul's premium transit nodes absorb these installations where flavor novelty commands repeat traffic.
- Spicy:Configurations incorporate separate chili oil and seasoning injectors with residue-resistant dispensing surfaces to prevent flavor cross-contamination. South Korea's MFDS mandates enhanced food contact material certifications for these heated additive pathways.
- Traditional:Boil-and-dispense mechanics dominate legacy fleet deployments with minimal electronic control overhead.
- Healthy:Reduced-sodium broth systems require reformulated concentrate storage and adjusted heating profiles for preservative-free formulations.
Gourmet absorbs the bulk of installed capacity; Spicy is expanding most quickly.
Deployment:
Fixed infrastructure demands diverge from mobile configurations in power supply, water management, and permitting burden.
- Fixed Location:Permanent installations at Japan's rail hubs and South Korean subway corridors anchor volume throughput. These units connect to municipal water and three-phase power, requiring METI-compliant heat-pump thermal systems for regulatory approval.
- Mobile:Trailer-mounted units with self-contained filtration and waste tanks serve festival circuits and construction sites across dense Asian urban centers. The configuration trades throughput capacity for placement flexibility in temporary demand clusters.
- On-Premise:Corporate and institutional installations prioritize payment integration with existing facility access systems.
- Event-Based:Seasonal rental fleets deploy for cultural festivals and sporting events with rapid setup protocols.
Fixed Location captures the majority of unit economics; Mobile is climbing the fastest.
End User:
Consumption patterns and price sensitivity shape machine specification requirements across demographic segments.
- College Students:Japan's higher education institutions deploy 24-hour units with customizable broth options to replace cafeteria labor. These installations prioritize volume throughput over premium margin extraction.
- Office Workers:Central business district placements in Tokyo and Osaka target reduced-sodium healthy variants. The segment commands premium positioning for wellness-positioned product lines.
- Tourists:Transit hub machines emphasize multilingual interfaces and familiar brand recognition.
- Family:Highway service area and suburban retail installations accommodate multi-portion dispensing.
College Students represent the largest addressable base; Office Workers is gaining share fastest.
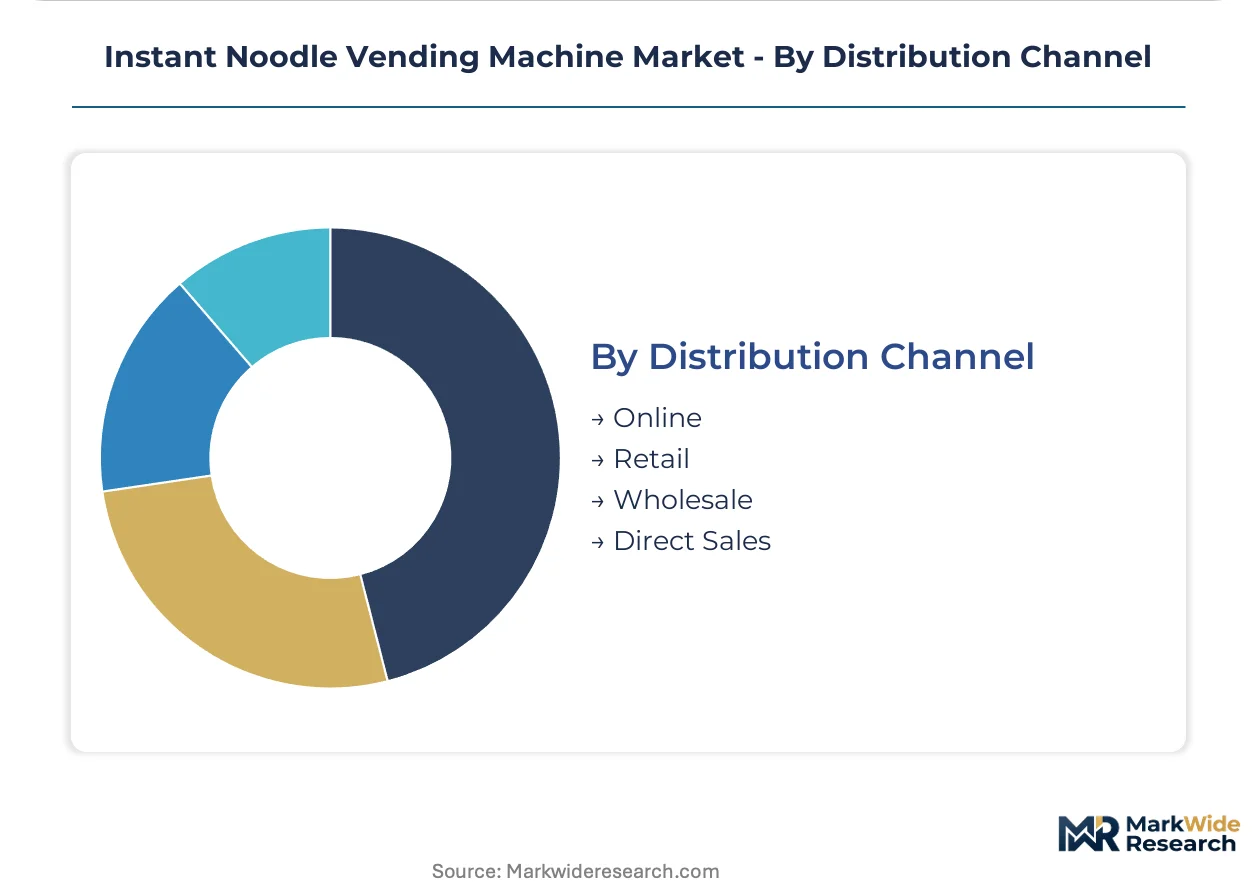
Distribution Channel:
Channel selection determines service intensity, margin structure, and geographic reach constraints.
- Direct Sales:Manufacturers maintain captive relationships with major rail and transit operators across Japan and South Korea. These contracts bundle equipment, maintenance, and exclusive supply agreements.
- Wholesale:Distributor networks serve secondary transit nodes and regional retail chains with standardized machine configurations.
- Retail:Equipment dealers cater to independent operators and small-format convenience stores.
- Online:Digital procurement channels support replacement parts, retrofit kits, and small-scale mobile unit purchases.
Direct Sales dominates transaction value; Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's dense transit corridors anchor the world's most concentrated instant noodle vending machine deployments, with regulatory pressure from Japan's METI reshaping equipment standards across Northeast Asian supply chains.
Japan
University campuses and rail hubs in Osaka and Nagoya drive fixed-location demand for customizable broth dispensers. METI's tightened energy efficiency standards compel manufacturers toward heat-pump water modules or market exclusion. The Kansai corridor sustains high machine density through 24-hour commuter traffic patterns.
South Korea
Seoul's subway network and Busan's transit terminals absorb premium units with induction heating retrofit programs. MFDS mandates food contact material certifications for heated dispensing surfaces, creating compliance barriers for imported equipment. The Seoul Capital Area commands the region's highest per-machine utilization rates.
China
Festival circuits and construction sites in the Yangtze River Delta fuel mobile deployment expansion. SAMR implements GB standards for electrical safety in unattended food service machinery, affecting cross-border supply arrangements. Shanghai's dense urban clusters test AI-driven inventory management at secondary transit nodes.
United States
Corporate campuses in California and Texas pilot healthy variant lines targeting reduced-sodium office worker demand. FDA oversight of food contact surfaces intersects with state-level energy efficiency codes for commercial equipment. The Pacific Northwest tests trailer-mounted units for seasonal tech campus events.
Germany
Industrial zones in Bavaria and North Rhine-Westphalia evaluate mobile units for manufacturing site catering. REACH compliance for food contact materials and CE marking for electrical safety create dual certification pathways. Munich's central business district attracts premium positioning for wellness-oriented product configurations.
Instant Noodle Vending Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated equipment landscape. The market structures around three tiers: integrated thermal system manufacturers, brand-licensed deployment specialists, and component-focused fabricators. Consolidation pressure concentrates among heat-pump module suppliers where captive production creates supply bottlenecks. Dominant competitive moves include vertical integration into thermal control subsystems and geographic expansion through local joint ventures.
Among Japan-based integrated manufacturers, Fuji Electric Co., Ltd. and Nissin Foods occupy positions spanning thermal engineering and brand-anchored deployment. Sanden Holdings Corporation represents the specialist fabricator archetype focused on captive component production. These three entities exemplify how regulatory pressure from METI and MFDS reshapes competitive positioning toward energy-compliant thermal architectures.
| Leading Market Players |
|---|
| Nissin Foods |
| Maruchan, Inc. |
| Fuji Electric Co., Ltd. |
| Crane Merchandising Systems |
| Sanden Holdings Corporation |
| Evoca Group |
| Seaga Manufacturing Inc. |
| Azkoyen Group |
| Yo-Kai Express |
| Others |
Pricing and Supply Chain Analysis
Food-grade 304 stainless steel for heated dispensing surfaces flows from Indonesian nickel ore through Japanese thermal subsystem fabricators into finished machine pricing tiers. METI-compliant heat-pump water modules command premium positioning against resistive-heating commodity units, while nickel export restrictions compress margins across all performance levels.
Pricing Analysis
Throughput-based pricing anchors contracts for premium induction-heating units deployed in Seoul's subway network and Tokyo's university campuses. Pricing stratifies across premium, standard, and economy tiers based on thermal efficiency certification grade and after-sales service bundling. Cost compression in economy-tier boil-and-dispense mechanics intensifies as Chinese manufacturers gain SAMR electrical safety approvals. Transit operators show lowest price sensitivity; independent festival circuit renters exhibit highest.
Supply Chain Analysis
Refurbishment flows for induction coil modules create secondary supply channels that extend machine lifecycle economics in Japanese and South Korean fleets. Captive production of thermal control systems concentrates in Japan, with component sourcing from South Korean electronics suppliers and Chinese stainless steel fabricators. Single-source vulnerability sits with heat-pump compressor suppliers facing METI energy conservation redesign cycles. Distribution runs through direct sales contracts with major rail operators and wholesale networks serving secondary transit nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive thermal engineering capabilities determine regulatory survival. Players without in-house heat-pump module production face dependency on licensed Japanese subsystem suppliers.
For Market Incumbents: Cement control over heat-pump water system supply through backward integration into compressor manufacturing or exclusive licensing arrangements with established Japanese thermal control producers. Ghost kitchen micro-delivery substitution in South Korean urban corridors threatens repeat purchase frequency; defend through AI-driven inventory management that reduces spoilage and extends unmanned deployment viability. For New Entrants and Emerging Players: The mid-tier price gap between premium induction-heating units and economy boil-and-dispense machines offers white-space entry for MFDS-certified spicy variant configurations targeting South Korea's transit corridor retrofit programs. Mobile deployment configurations for festival and construction site applications present the most penetrable segment given lower certification sequencing complexity. Pursue joint venture structures with established Japanese thermal engineering firms to bypass captive supply bottlenecks. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-focused fabricators with SAMR electrical safety approvals and existing relationships with Chinese stainless steel suppliers. Long-term viability across the analysis window hinges on regulatory compliance breadth across METI, MFDS, and SAMR jurisdictions. Monitor Indonesian nickel ore export policy announcements as inflection indicators for input cost volatility and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Thermal System Integration | METI energy conservation mandates force adoption or market exclusion for non-compliant manufacturers. |
| AI-Driven Inventory Management Deployment | Yo-Kai Express models demonstrate spoilage reduction that sustains unmanned secondary transit node economics. |
| Multi-Jurisdiction Certification Sequencing | Misaligned METI, MFDS, and SAMR timelines reshape sourcing strategies toward localized joint ventures. |
| Mobile Configuration Capability Buildout | Festival and construction site applications in dense Asian urban centers drive fastest-expanding deployment segment. |
| Reduced-Sodium Product Line Development | Japan's office worker demographic commands premium positioning for wellness-oriented broth reformulations. |
Research Methodology
Document review covered METI appliance energy conservation standards, MFDS food contact material regulations, and SAMR GB electrical safety frameworks, complemented by interviews with thermal engineering directors at Japanese vending equipment manufacturers, procurement leads at South Korean transit operators, and facilities managers at Japanese university campuses. Secondary validation drew from customs trade data, SEC filings of publicly traded component suppliers, and industry association reports on commercial food service equipment. Bottom-up unit deployment estimates triangulated against top-down market value reconstruction.
Historical deployment patterns across Japanese rail hubs and South Korean subway corridors were cross-referenced against panel input from transit authority planning officers and university facilities directors. Segmentation modeling incorporated product type, deployment configuration, end user demographic, and distribution channel dimensions throughout the forecast period. CAGRs were derived from trajectory fitting against regulatory compliance timelines and technology substitution cycles. Forecast inputs included nickel ore price volatility indices and METI energy efficiency standard revision schedules.
Inputs from Japanese thermal subsystem suppliers and South Korean transit operators were available through the study window; gaps in Chinese mobile deployment utilization data introduce uncertainty bands around festival and construction site segment projections. Forecasts reflect documented assumptions regarding regulatory harmonization progress and substitution elasticity between vending machine purchases and ghost kitchen delivery. Practitioners should monitor Indonesian nickel export restriction announcements and MFDS certification backlog durations for early signals of margin pressure and market access timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Online Catering Market
Food Service
Haute Cuisine Market
Food Service
Spain Food Service Market
Food Service
Steam Stew Pot Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Europe Airline Catering Services Market
Food Service
India Foodservice Market
Food Service
Limited-Service Restaurants Market
Food Service
Galley Equipment Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Restaurant Takeout Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
North America Online Grocery Delivery Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Bar Refrigeration Market
Food Service
Commercial Tableware Services Market