
 Sardine and Anchovy Umami Concentrate Systems Market | 2026-2036
Sardine and Anchovy Umami Concentrate Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sardine and Anchovy Umami Concentrate Systems Market Insights
Soy sauce powder is hardening its position as a cost-competitive benchmark against premium fish-derived concentrates in mid-market seasoning formulations. Nikken Foods leverages proprietary enzymatic hydrolysis infrastructure to sustain supply continuity for Japanese foodservice distributors. Kerry Group anchors European demand through backward integration into North Atlantic pelagic fisheries. Symrise differentiates via sensory science investments that map specific nucleotide profiles to regional palate preferences.
Sardine and anchovy umami concentrate systems comprise thermally or enzymatically processed fish biomass refined into standardized flavor-active formulations, typically quantified by equivalent umami concentration relative to monosodium glutamate benchmarks. These systems deliver kokumi depth and nucleotide synergy to processed foods where clean-label positioning displaces synthetic enhancers. Anchovy extract dominates current volume flows due to higher inosinate content and established supply chains in Mediterranean and East Asian waters. Enzymatic hydrolysis represents the fastest-expanding technology segment as manufacturers pursue lower thermal degradation of sulfur compounds and tighter molecular weight distribution control. Spray drying commands the largest installed capacity base but faces margin compression from energy intensity relative to membrane-assisted vacuum concentration.
FDA GRAS self-determination pathways shape US market entry timelines for novel hydrolysate formulations, while EFSA novel food assessments govern European commercialization of non-traditional enzymatic processes. Japan's Ministry of Health, Labour and Welfare maintains positive-list oversight of fish-derived food additives, directly influencing export certification burdens for Korean and Chinese producers. Stakeholders must monitor divergence between Codex Alimentarius draft guidelines and national enforcement practices to anticipate harmonization risks or compliance multiplication.
Market Dynamics
Enzymatic hydrolysis infrastructure is decentralizing production capacity away from traditional thermal processing hubs, forcing incumbents to retool or lose contract volumes to nimble regional processors.
Growth Catalysts
- Clean-label mandates:The EU Green Deal's sustainable fisheries certification requirements are accelerating displacement of synthetic flavor enhancers in European processed foods.
- Meal kit proliferation:South Korean meal kit suppliers are driving bulk purchasing of standardized umami concentrates for instant soup bases.
- Enzymatic processing:Lower thermal degradation of sulfur compounds is improving yield economics for anchovy-derived nucleotide extraction.
Market Restraints
- Pelagic biomass volatility:Sardine stock fluctuations off the Peruvian coast are compressing margin predictability for hydrolysate producers dependent on single-source procurement.
- Energy intensity:Spray drying operations face margin compression from natural gas price spikes relative to membrane-assisted vacuum concentration alternatives.
- Soy sauce powder substitution:Cost-competitive fermented soybean extracts are capturing mid-market seasoning formulation share from premium fish-derived concentrates.
Strategic Opportunities
- Indian food processing:FSSAI clean-label guidelines are creating first-mover advantage for enzymatic hydrolysate suppliers entering commercial sauce manufacturing.
- Precision fermentation convergence:Hybrid processes combining enzymatic hydrolysis with biomass fermentation are opening novel nucleotide ratio customization for regional palate mapping.
- Direct-to-manufacturer channels:E-procurement platforms are disintermediating traditional ingredient distributors for mid-sized Southeast Asian noodle producers.
Industry Challenges
- Novel food assessment timelines:EFSA's evaluation protocols for non-traditional enzymatic processes are extending European commercialization lead times by 18-24 months.
- Cross-border certification burden:Japan's Ministry of Health, Labour and Welfare positive-list oversight creates redundant testing requirements for Korean exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sardine and Anchovy Umami Concentrate Systems Market |
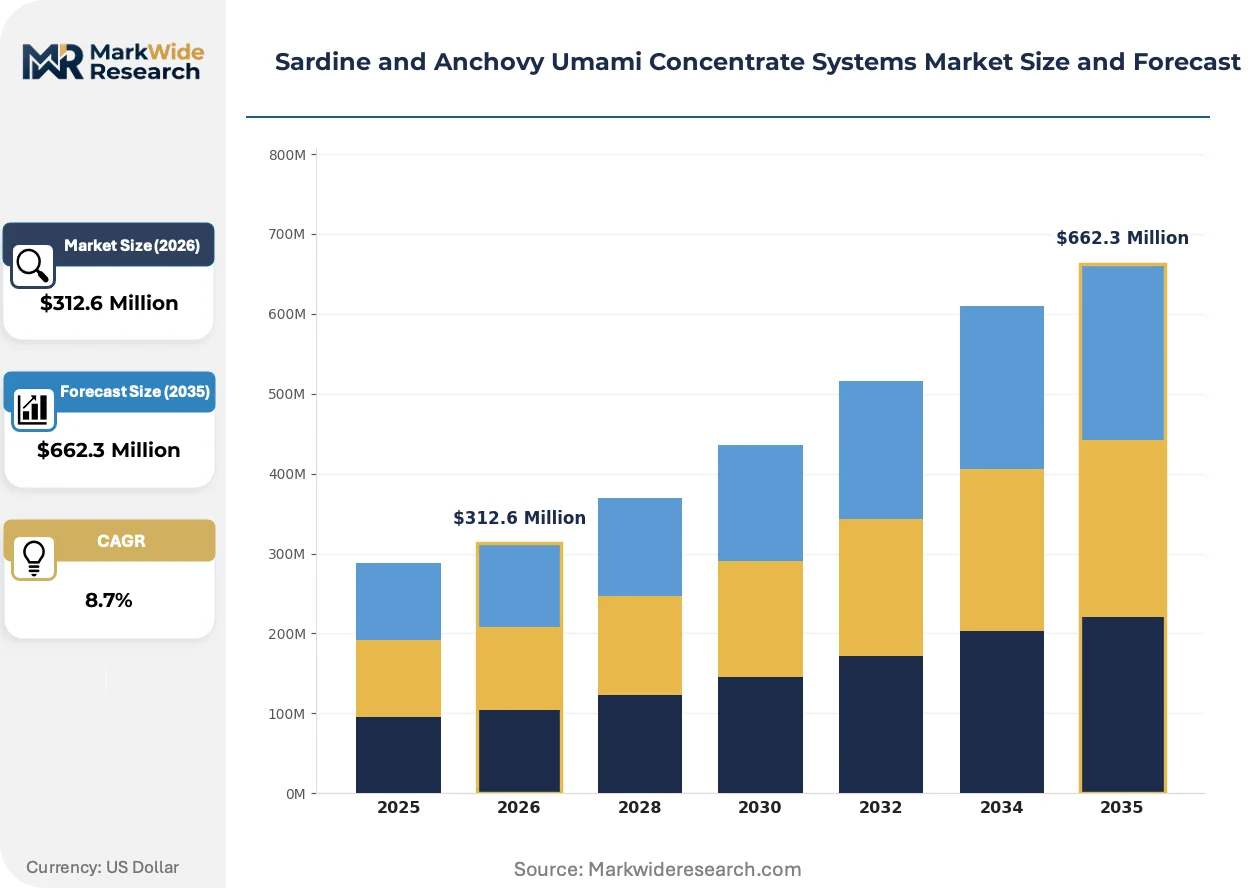
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sardine Concentrate, Anchovy Extract, Fish-Based Seasoning, Natural Flavor Enhancer, Meat Alternative Additive Technology: Ultrafiltration, Enzymatic Hydrolysis, Vacuum Concentration, Membrane Separation, Spray Drying Application: Processed Meat Flavoring, Snack Seasoning, Culinary Sauces, Ready-to-Eat Meals, Marinades End User: Food & Beverage Manufacturers, Seasoning Producers, Meal Kit Suppliers, Gourmet Retailers |
| Companies Covered | Nikken Foods, Sokol & Company, Del-Val Food Ingredients, Shanghai Hensin Industry, Dalian YSK Bio-Technology, DOBE IND., Symrise, Kerry Group, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sardine and Anchovy Umami Concentrate Systems Market Trends and Innovations
Processing technology and regulatory frameworks are converging to reshape competitive advantage around molecular precision rather than scale economies alone.
Membrane-assisted vacuum concentration is decentralizing thermal processing dominance by enabling smaller-batch production with tighter molecular weight distribution control. Regional processors in Vietnam and Thailand are adopting modular skid-mounted units to serve local sauce manufacturers. This technology is decentralizing supply chain power from large-scale Mediterranean spray-drying facilities toward agile Asian coastal processors.
REACH authorization requirements for processing aids are forcing reformulation of traditional thermal extraction protocols across European concentrate suppliers. Manufacturers must now document substance safety profiles for enzymatic catalysts previously grandfathered under legacy thermal process exemptions. The burden falls heaviest on Spanish and Portuguese anchovy processors seeking to maintain EU market access.
Buyer consolidation among multinational foodservice distributors is compressing supplier negotiation cycles from annual to quarterly recontracting. Long-term volume commitments are giving way to flexible offtake agreements indexed to raw material spot prices. This pattern is most visible in Japanese and South Korean trading relationships, where procurement teams now demand real-time price adjustment clauses.
Sardine and Anchovy Umami Concentrate Systems Market Segmentation
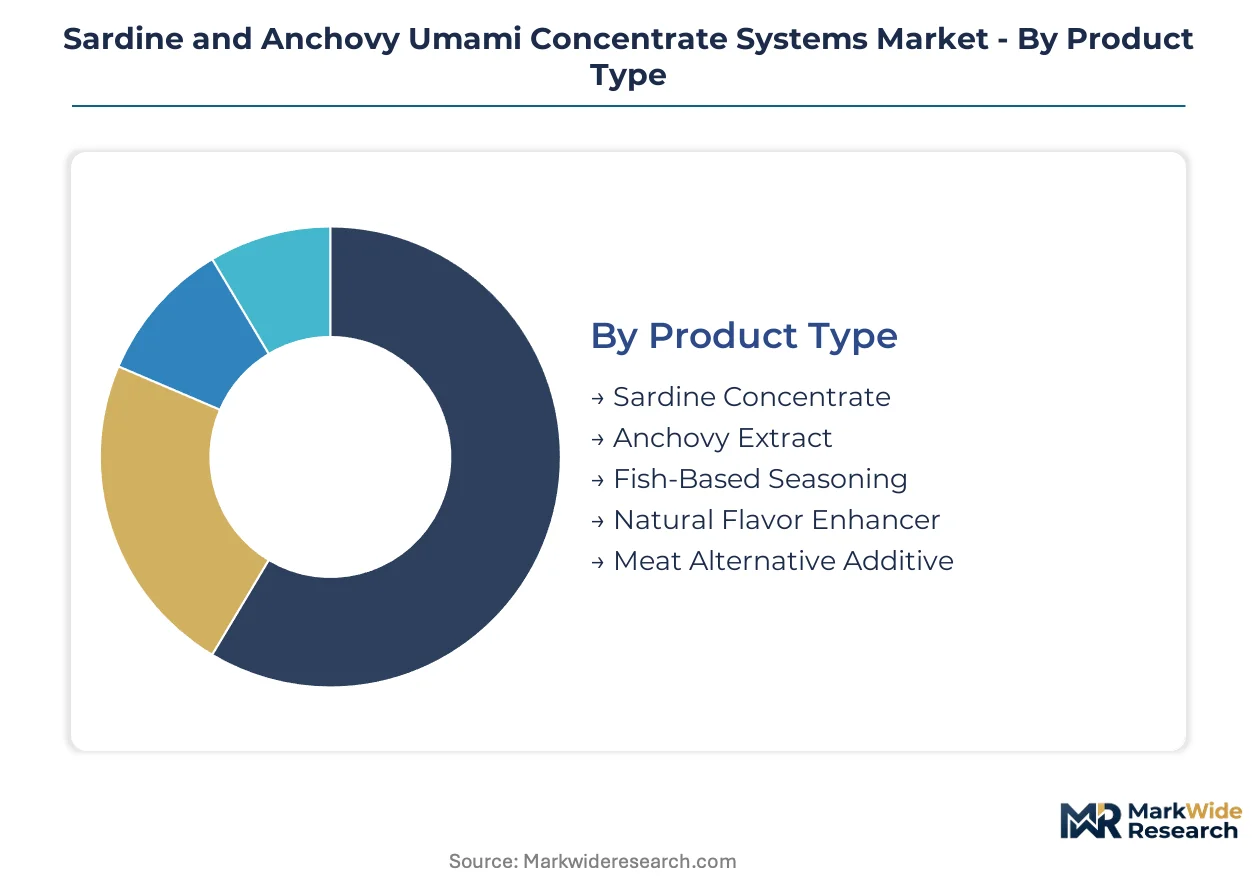
Segmentation in sardine and anchovy umami concentrates reveals how molecular precision, processing economics, and end-use specifications fragment commercial opportunity. Manufacturers configure product portfolios across customization depth and standardization scale to capture diverging buyer requirements.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade extracts to engineered nucleotide ratios for proprietary formulations.
- Anchovy Extract:Higher inosinate content delivers superior nucleotide synergy for clean-label applications. Japanese instant noodle manufacturers and South Korean meal kit suppliers anchor procurement volumes for this segment, though Mediterranean supply chain maturity limits price volatility exposure.
- Sardine Concentrate:Thermal or enzymatically processed biomass with pronounced sulfur compound profiles suited to fermented sauce applications. Peruvian coastal stock fluctuations compress margin predictability for hydrolysate producers dependent on single-source procurement.
- Fish-Based Seasoning:Standardized blends targeting mid-market seasoning houses seeking drop-in umami solutions.
- Natural Flavor Enhancer:Concentrated nucleotide fractions for synthetic MSG displacement in premium positioning.
- Meat Alternative Additive:Emerging application segment supplying kokumi depth to plant-based protein matrices.
Leading the category by volume: Anchovy Extract. Growing fastest: Meat Alternative Additive.
Technology:
Cost tier stratification separates capital-intensive centralized operations from modular regional installations.
- Enzymatic Hydrolysis:Protease-catalyzed protein cleavage preserves heat-labile sulfur aromatics while enabling tighter molecular weight distribution control. Vietnamese and Thai coastal processors deploy skid-mounted units to serve local sauce manufacturers, decentralizing supply chain power from Mediterranean spray-drying hubs.
- Spray Drying:Atomized thermal dehydration commands the largest installed base but faces margin compression from natural gas price spikes relative to membrane alternatives.
- Ultrafiltration:Pressure-driven membrane separation for protein fractionation prior to concentration.
- Vacuum Concentration:Reduced-temperature evaporation protecting volatile compound integrity.
- Membrane Separation:Selective permeability systems enabling smaller-batch production with precise molecular cutoff control.
Enzymatic Hydrolysis commands the steepest expansion trajectory as manufacturers retrofit thermal assets. Spray Drying retains the largest revenue base.
Application:
Customer type differentiation separates bulk commodity buyers from specification-driven premium purchasers.
- Culinary Sauces:Anchovy-derived nucleotides provide kokumi foundation for fermented soybean and tomato matrices. European sauce manufacturers under EU Green Deal sustainable fisheries mandates drive specification tightening for raw material traceability.
- Ready-to-Eat Meals:Standardized umami concentrates enable consistent flavor delivery across distributed production networks.
- Processed Meat Flavoring:Thermal extracts reinforcing savory notes in cured and emulsified products.
- Snack Seasoning:Cost-optimized powder concentrates for high-volume coating applications.
- Marinades:Liquid hydrolysates with controlled salt load for injection and tumbling systems.
Culinary Sauces generate the highest revenue concentration. Ready-to-Eat Meals are climbing the fastest on meal kit proliferation.
End User:
Supply concentration patterns align with procurement scale and technical service requirements.
- Food & Beverage Manufacturers:Integrated R&D teams demanding customized nucleotide ratios and documented allergen control. Japanese trading houses now enforce quarterly recontracting with real-time price adjustment clauses indexed to raw material spot markets.
- Meal Kit Suppliers:Rapid formulation cycles requiring standardized concentrates with batch-to-batch consistency guarantees.
- Seasoning Producers:Mid-volume buyers blending fish-derived nucleotides with complementary flavor systems.
- Gourmet Retailers:Small-batch artisan positioning with emphasis on single-origin sourcing narratives.
Food & Beverage Manufacturers dominate procurement volume. Meal Kit Suppliers are expanding most quickly on channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Busan-Jinhae Free Economic Zone anchors East Asian concentrate production capacity through preferential tariff treatment on enzymatic hydrolysis equipment imports. Japanese trading houses and South Korean meal kit suppliers cluster procurement operations within this zone to minimize cross-border logistics friction.
Japan
Instant noodle manufacturers in Kanto drive bulk anchovy extract procurement for clean-label soup bases. The Ministry of Health, Labour and Welfare maintains positive-list oversight of fish-derived additives, forcing Korean exporters into redundant certification cycles. Tokyo-based trading houses now enforce quarterly recontracting with real-time price adjustment clauses indexed to raw material spot markets.
South Korea
Meal kit suppliers and instant noodle producers concentrate demand in Seoul Capital Area for standardized umami concentrates. MFDS enforcement of clean-label guidelines accelerates displacement of synthetic flavor enhancers in processed foods. Busan-Jinhae coastal processors deploy modular enzymatic hydrolysis units to serve local sauce manufacturers.
Spain
Mediterranean anchovy processors in Cantabria face REACH authorization burdens for enzymatic catalysts previously grandfathered under thermal process exemptions. The EU Green Deal's sustainable fisheries certification requirements reshape raw material sourcing protocols across Iberian concentrate suppliers. Barcelona-based distributors consolidate procurement from smaller-batch regional processors.
Peru
Sardine stock fluctuations off the Chimbote coast compress margin predictability for hydrolysate producers dependent on single-source procurement. The country's national fisheries regulator tightens seasonal quota enforcement following biomass collapse events. Lima-based exporters diversify supply contracts toward Southeast Asian enzymatic processors to reduce concentration risk.
Vietnam
Commercial sauce manufacturers in Ho Chi Minh City adopt membrane-assisted vacuum concentration to serve mid-market seasoning formulations. The country's food safety authority implements FSSAI-aligned clean-label guidelines for imported hydrolysate ingredients. Mekong Delta coastal processors install skid-mounted enzymatic units to capture regional procurement from Thai and Cambodian buyers.
Sardine and Anchovy Umami Concentrate Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enzymatic hydrolysis capability concentrating among Japanese and European incumbents while thermal processing fragments across Southeast Asian regional players. Three archetypes dominate: integrated flavor houses with backward integration into pelagic fisheries, specialist hydrolysate processors serving single-application buyers, and trading houses arbitraging spot raw material markets. Capacity expansion and technology licensing represent the dominant competitive moves, as incumbents retrofit spray-drying assets toward enzymatic infrastructure or license membrane separation patents to regional processors.
Among Asia-Pacific specialists, Nikken Foods and Dalian YSK Bio-Technology exemplify the enzymatic processing archetype, while Kerry Group anchors European demand through upstream control over North Atlantic pelagic fisheries. Symrise occupies a position within the sensory science tier, mapping nucleotide profiles to regional palate preferences without disclosing specific formulation investments.
| Leading Market Players |
|---|
| Nikken Foods |
| Sokol & Company |
| Del-Val Food Ingredients |
| Shanghai Hensin Industry |
| Dalian YSK Bio-Technology |
| DOBE IND. |
| Symrise |
| Kerry Group |
| Givaudan |
| Others |
Pricing and Supply Chain Analysis
Enzymatic hydrolysis infrastructure decentralization simultaneously compresses thermal processing margins and fragments supply chain power toward agile coastal processors. Busan-Jinhae Free Economic Zone equipment imports and Vietnamese skid-mounted unit proliferation are redrawing procurement geography while membrane-assisted vacuum concentration erodes spray-drying cost advantages.
Pricing Analysis
Volume concentration in anchovy extract trades against margin compression in sardine concentrate as Peruvian stock volatility disrupts single-source procurement economics. Three-tier pricing structure across premium enzymatic hydrolysates, standard thermal extracts, and economy-grade spray-dried powders reflects certification grade and molecular weight distribution control. Pricing pressure stems from natural gas cost spikes hitting spray-drying operations hardest. Mid-market seasoning houses exhibit highest price sensitivity while Japanese instant noodle manufacturers absorb premium nucleotide premiums.
Supply Chain Analysis
Reverse-logistics flows for enzymatic catalyst recovery and spent biomass valorization remain underdeveloped across Mediterranean thermal processing hubs. Raw material sourcing concentrates in Peru, Spain, and Vietnam with seasonal quota enforcement tightening biomass access. Processing draws from North Atlantic pelagic fisheries, Mediterranean anchovy shoals, and Southeast Asian coastal landings. Single-source vulnerability to Chimbote coast sardine stock collapse threatens margin predictability. Distribution runs through Japanese trading houses, South Korean meal kit platforms, and European sauce manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH authorization requirements for enzymatic catalysts erect compliance moats that thermal incumbents cannot cross without 18-24 month EFSA novel food assessment investments, entrenching first-mover enzymatic processors.
For Market Incumbents: Acquire modular enzymatic hydrolysis units in Vietnam and Thailand to preempt regional processor capture of Southeast Asian sauce manufacturing demand. Retrofit Spanish and Portuguese spray-drying assets toward membrane separation infrastructure before REACH authorization deadlines grandfather out legacy thermal exemptions. Kerry Group's North Atlantic pelagic control demonstrates upstream anchoring against Peruvian sardine volatility.
For New Entrants and Emerging Players: Indian commercial sauce manufacturers under FSSAI clean-label guidelines represent the most penetrable buyer archetype for first-mover enzymatic hydrolysate suppliers. Precision fermentation convergence for nucleotide ratio customization opens white-space in meat alternative additive applications. Direct e-procurement platform relationships with mid-sized Southeast Asian noodle producers bypass distributor margin extraction.
For Investors and Strategic Acquirers: Exit pathways concentrate in enzymatic capability acquisition by integrated flavor houses seeking backward integration into pelagic sourcing without EFSA assessment timelines. Long-term viability favors processors with dual thermal-enzymatic asset flexibility across the analysis window. Monitor EFSA novel food assessment queue lengths as inflection signal for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Busan-Jinhae coastal processors capture Korean meal kit supplier procurement with modular unit deployment. |
| Backward Integration into North Atlantic Fisheries | Kerry Group anchors European demand through captive pelagic biomass supply security. |
| Membrane Separation Technology Licensing | Vietnamese regional processors gain molecular weight precision without spray-drying energy intensity. |
| Precision Fermentation Convergence R&D | Hybrid processes enable nucleotide ratio customization for Japanese palate-specific formulations. |
| Direct-to-Manufacturer E-Procurement Platform | Mid-sized Thai and Cambodian noodle producers disintermediate traditional ingredient distributors. |
Research Methodology
Document review covered EFSA novel food assessment filings, Japanese Ministry of Health positive-list additive registrations, and Peruvian national fisheries quota enforcement records, complemented by interviews with enzymatic hydrolysis plant managers, European sauce manufacturer procurement leads, South Korean meal kit supplier R&D directors, and Southeast Asian trading house category buyers. Secondary validation drew from customs trade data, EU Green Deal sustainable fisheries certification databases, and SEC filings of listed flavor house parents. Bottom-up volume triangulation against top-down expenditure modeling anchored forecast integrity.
Cross-referencing historical enzymatic processing adoption curves against expert panel input on clean-label displacement timelines shaped the analytical framework. Segmentation dimensions modeled include extraction technology type, nucleotide concentration tier, end-use application intensity, and regional regulatory cluster strictness. CAGRs derived from spline-fitting historical volume trajectories to projected clean-label mandate enforcement phases. Forecast inputs incorporated seasonal biomass availability patterns and natural gas price volatility assumptions.
Revisions become necessary when EFSA assessment timelines extend beyond modeled ranges, Peruvian sardine stock collapses trigger quota emergency measures, or EU Green Deal certification requirements tighten raw material traceability burdens beyond current processor documentation capabilities. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
European Frozen Seafood Market
Seafood
Herring Market
Seafood
Europe Salmon Market
Seafood
Mussel Extract Market
Seafood
Organic Shrimp Market
Seafood
Fresh Fish Market
Seafood
Trout Market
Seafood
Caviar Market
Seafood
Dry-Packaged Scallops Market
Seafood
Food Clamshells Market
Seafood
Lobster Market
Seafood
Asia-Pacific Shrimp Market
Seafood
United States Plant-Based Seafood Market
Seafood
Global Smoked Fish Market
Seafood
Salmon Fish Market
Seafood
Japan Lobster Market