
 Mead Beverage Market | 2026-2036
Mead Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Mead Beverage Market Analysis
Subscription-based mead-of-the-month clubs and membership-driven tasting programs is recalibrating how producers monetize repeat consumption. Redstone Meadery leverages direct-to-consumer shipping to sustain margins across state lines. Superstition Meadery anchors its position through barrel-aged specialty releases that command premium positioning.
Mead is an alcoholic beverage fermented from honey and water, typically containing 8-20% alcohol by volume, with optional additions of fruits, spices, or hops to create variant styles. Its primary commercial purpose centers on serving as a distinctive craft alternative to wine and beer in specialty beverage retail. Traditional Mead retains the largest volume footprint among product types, while Melomel commands expanding interest through fruit-forward formulations that attract crossover consumers from craft cider and wine categories. Sparkling variants within the flavor profile dimension represent the fastest-growing margin pool, as effervescence aligns with premium positioning and on-premise cocktail integration.
The Alcohol and Tobacco Tax and Trade Bureau governs label approval, formula classification, and interstate commerce for United States producers, while the FDA oversees ingredient safety and allergen disclosure requirements. State-level alcohol beverage control boards create fragmented licensing requirements that shape market access patterns for direct sales and distribution. Producers must monitor evolving excise tax treatment of honey-based fermented beverages relative to grape wine and malt beverage categories, as reclassification risks alter competitive economics across channels.
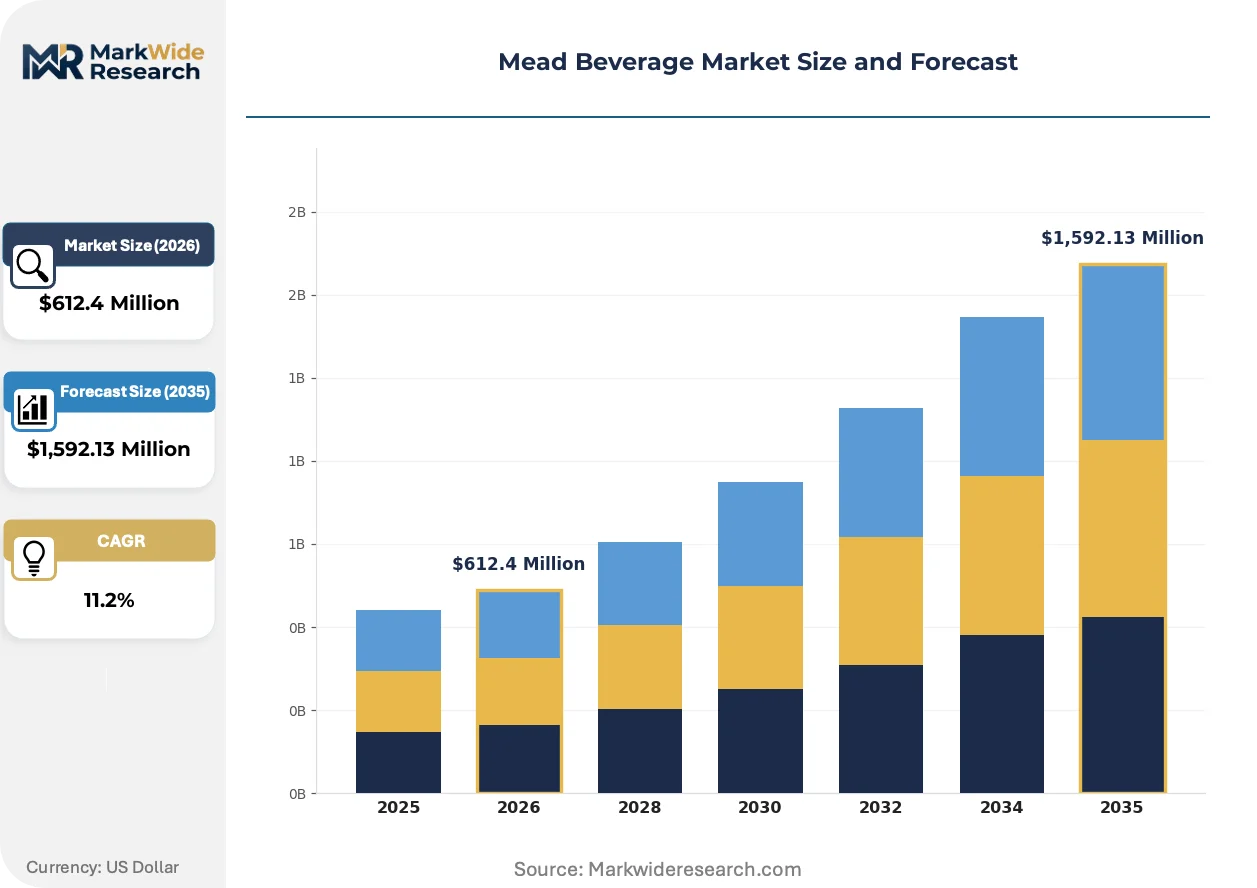
Market Dynamics
Direct-to-consumer shipping permissions are fragmenting state-by-state across the United States, forcing mead producers to rebuild distribution strategies around tasting room economics and subscription clubs rather than traditional three-tier wholesaler networks.
Growth Catalysts
- Craft Beverage Tourism:Pacific Northwest cluster cities including Portland and Seattle anchor concentrated consumption hubs where tasting room density creates network effects for visitor traffic.
- TTB Formula Modernization:Evolving Alcohol and Tobacco Tax and Trade Bureau classification guidance for honey-based fermented beverages reduces regulatory friction for interstate commerce expansion.
- Barrel-Aging Techniques:Oak and spirit cask maturation protocols borrowed from craft distilling enable premium price positioning that sustains producer margins.
Market Restraints
- Honey Input Volatility:Colony collapse disorder and climate stress on pollinator populations concentrate supply risk among domestic apiary operators in California and Florida.
- Excise Tax Asymmetry:Federal and state alcohol tax frameworks treat honey wine at higher rates than grape wine or malt beverages in multiple jurisdictions, compressing competitive economics.
- Production Scale Limitations:Batch fermentation cycles for traditional mead extend 6-18 months, constraining inventory turnover relative to beer or cider alternatives.
Strategic Opportunities
- Ready-to-Drink Cocktail Integration:Sparkling mead formulations are penetrating on-premise bar programs as low-ABV alternatives to prosecco and spritz categories.
- State-Level Shipping Liberalization:Direct-to-consumer legislation in Texas, Pennsylvania, and New York creates whitespace for producer-controlled revenue capture.
- Melomel Crossover Positioning:Fruit-forward variants attract craft cider and natural wine consumers through shared flavor profiles and agricultural storytelling.
Industry Challenges
- Master Brewer Talent Scarcity:Fermentation science expertise specific to honey must and yeast strain management remains concentrated among legacy craft producers.
- Label Approval Timelines:TTB formula and label review queues create 90-180 day delays for seasonal and limited-release product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mead Beverage Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,592.13 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Mead, Melomel, Cyser, Metheglin Flavor Profile: Dry, Semi-Sweet, Sweet, Sparkling Packaging Type: Bottle, Can, Keg, Tetra Pak Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Restaurants |
| Companies Covered | Redstone Meadery, Wild Blossom Meadery, B. Nektar Meadery, Dansk Mjød, Superstition Meadery, Schramm's Mead, Sap House Meadery, Cornish Mead Co., Moonlight Meadery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mead Beverage Market Emerging Trajectories
Carbonation technology and packaging format experimentation are compressing the traditional mead production cycle while expanding consumption occasions beyond ceremonial or seasonal contexts.
Forced carbonation systems using precision CO2 injection are converging with canning line automation to enable shelf-stable sparkling mead at price points accessible to mainstream craft beverage buyers. Regional producers in Oregon and Washington are adopting these systems at 15-30 barrel weekly volumes. The technology is converging with mobile canning services to reduce capital barriers for small-batch producers entering retail distribution.
State alcohol beverage control boards in California, New York, and Illinois are implementing tiered licensing frameworks that distinguish farm winery, craft distillery, and honey wine producer categories. These classifications determine direct sales permissions, self-distribution limits, and tasting room operating hours. Pacific Northwest producers are responding by securing multiple license types to maximize channel flexibility.
Subscription-based mead clubs are displacing traditional wholesale relationships as the primary repeat purchase mechanism for established producers. Tasting room visitors in Seattle, Portland, and Denver are converting to monthly shipment programs at rates exceeding 25% of first-time buyers. This pattern concentrates in metropolitan markets with mature craft beverage cultures and permissive direct shipping regulations.
Mead Beverage Market Segmentation
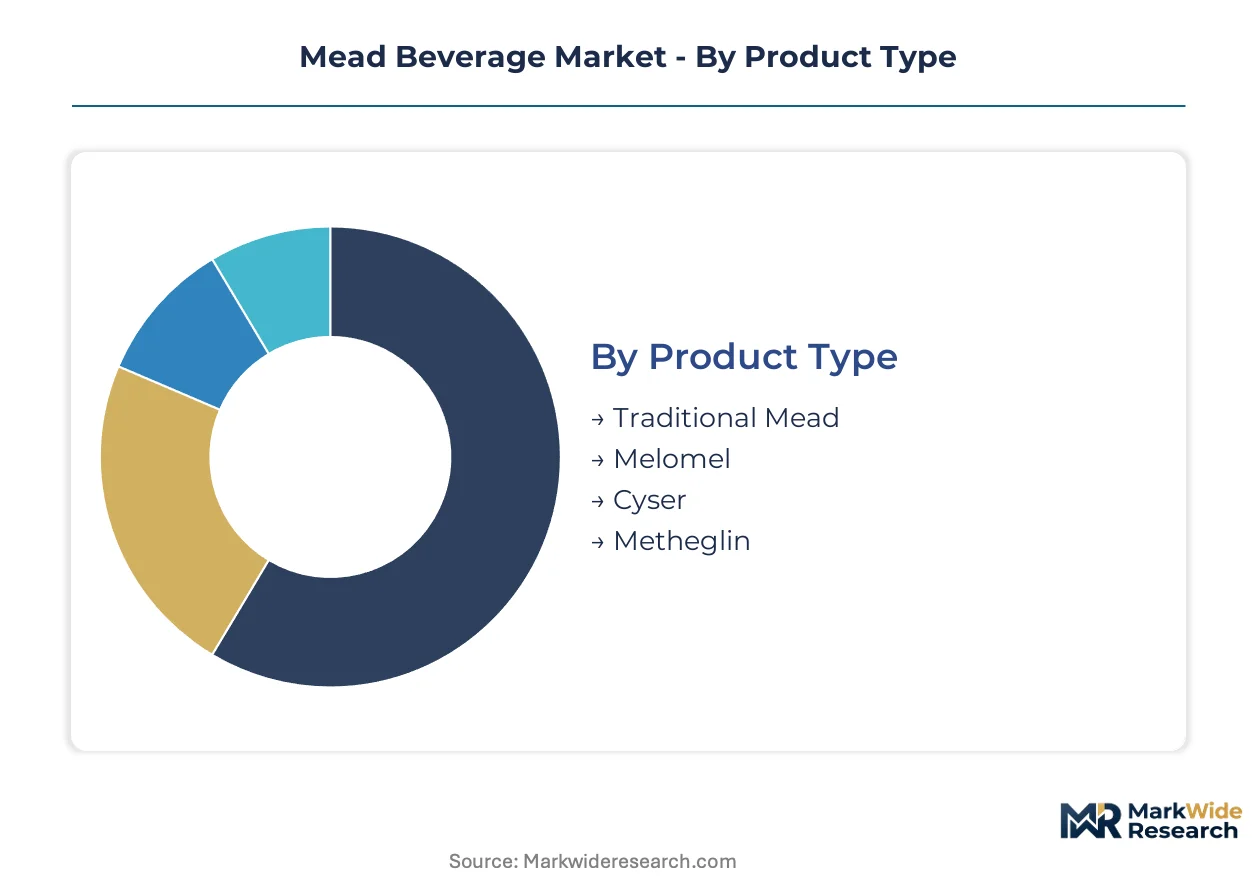
Segmentation in the Mead Beverage Market determines regulatory pathway complexity and margin architecture. Producers select positioning based on fermentation protocols, packaging investments, and channel access permissions that vary dramatically across state and national boundaries.
Product Type:
TTB formula classification requirements vary sharply by honey base composition and adjunct ingredients, with some variants triggering distilled spirits oversight rather than wine classification.
- Traditional Mead:Fermented exclusively from honey and water without fruit or spice additions. Pacific Northwest tasting rooms anchor volume concentration here, as extended aging protocols align with visitor education narratives and premium pricing.
- Melomel:Honey base fermented with fruit additions creating color and acid complexity. Demand concentrates in crossover consumers migrating from craft cider and natural wine categories, drawn by agricultural storytelling and terroir expression.
- Cyser:Apple juice and honey co-fermentation yielding tart, sessionable profiles. Common in Northeast orchard-adjacent producers.
- Metheglin:Spice and herb infused variants requiring additional FDA ingredient safety documentation. Popular in holiday seasonal releases.
Traditional Mead sits at the top of the volume ranking, with Melomel climbing the fastest.
Flavor Profile:
Residual sugar levels and carbonation status determine excise tax brackets and on-premise placement opportunities in most jurisdictions.
- Dry:Final gravity below 1.010, positioning alongside craft wine and cider in restaurant programs. TTB labeling requires accurate residual sugar disclosure.
- Semi-Sweet:Balanced profiles attracting the widest consumer trial in tasting room settings. Oregon and Washington producers dominate this positioning.
- Sweet:Higher residual sugar commanding dessert wine pricing tiers. Limited distribution due to shelf stability concerns.
- Sparkling:Forced or bottle-conditioned carbonation enabling cocktail program integration and canning line economics. Fastest margin expansion trajectory in the category.
Semi-Sweet captures the broadest consumer base, while Sparkling posts the steepest expansion trajectory.
Packaging Type:
Capital intensity and supply chain partnerships differentiate format selection, with mobile canning services reducing barriers for small-batch producers.
- Bottle:Standard 750ml wine bottles dominating tasting room and gift channel sales. Higher per-unit margin offset by logistics complexity.
- Can:12oz and 16oz formats penetrating outdoor recreation and casual consumption occasions. Mobile canning partnerships enable entry without capital investment.
- Keg:On-premise draft programs in craft-focused bars and restaurants. Requires cold chain infrastructure and account-level service.
- Tetra Pak:Aseptic cartons for value-tier export markets and festival sampling programs. Minimal adoption in domestic premium positioning.
Bottle retains volume leadership, with Can gaining share fastest through outdoor recreation channel expansion.
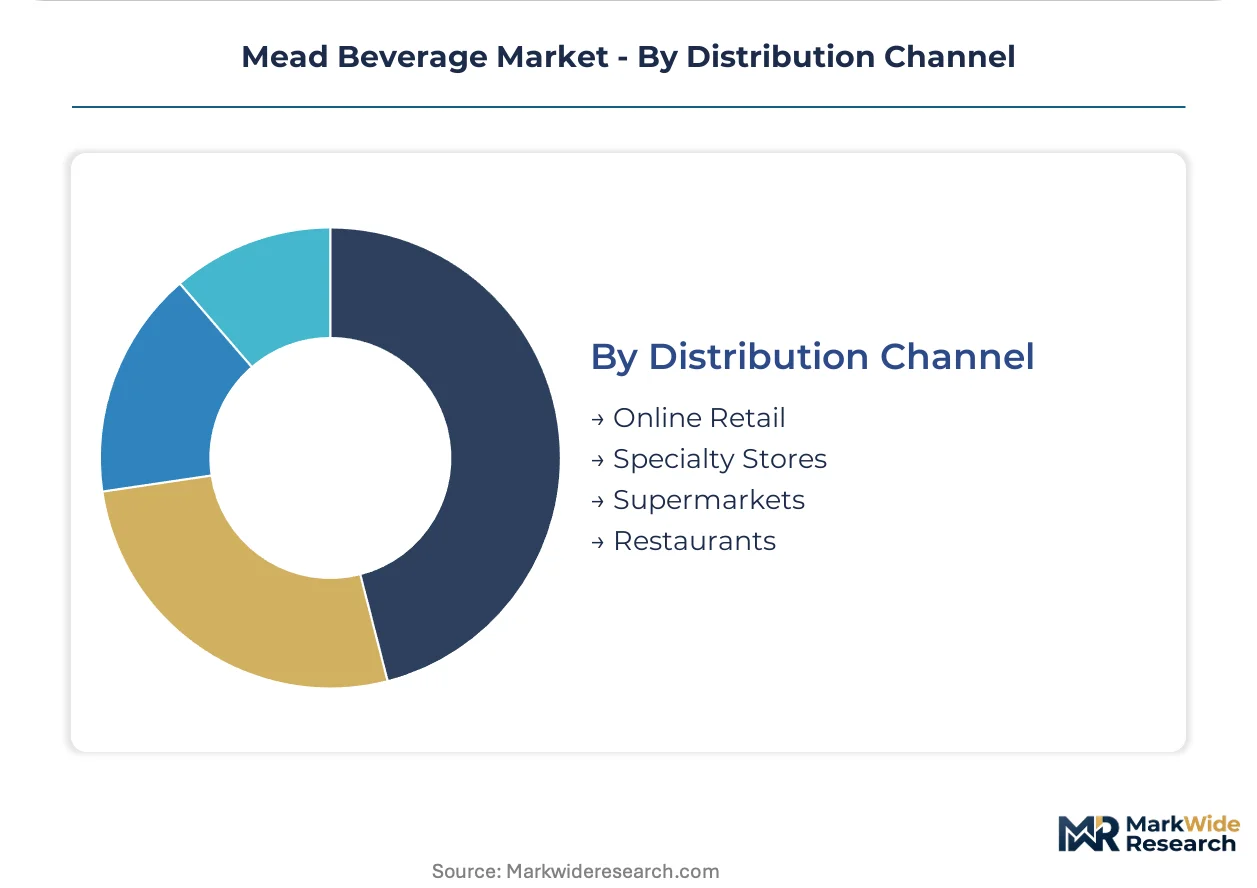
Distribution Channel:
Direct shipping permissions and three-tier system constraints fragment channel economics across state boundaries.
- Online Retail:Subscription clubs and direct-to-consumer shipping sustaining producer margins. Texas, Pennsylvania, and New York legislative openings create whitespace.
- Specialty Stores:Independent wine shops and craft beverage retailers expanding shelf space in Portland, Seattle, and Denver metropolitan clusters.
- Supermarkets:Limited penetration due to category education requirements and slotting fee structures. Concentrated in Pacific Northwest grocery chains with local sourcing mandates.
- Restaurants:On-premise placement driving trial through by-the-glass programs and craft cocktail integration. Barrel-aged releases command sommelier attention.
Specialty Stores anchor current volume, with Online Retail expanding most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production location decisions as mead producers migrate toward jurisdictions with streamlined alcohol licensing and favorable excise tax treatment for honey-based fermented beverages.
United States
The Pacific Northwest tasting room cluster in Portland and Seattle generates concentrated visitor traffic that converts to subscription club memberships. TTB formula classification requirements create compliance cost differentials across state lines. Barrel-aging specialists in Colorado and Michigan are expanding production capacity to serve direct-to-consumer shipping markets.
Canada
Provincial liquor board distribution monopolies in Ontario and British Columbia constrain market access for small-batch producers. Health Canada allergen disclosure regulations add labeling complexity for spiced metheglin variants. Farm winery license categories in British Columbia's Okanagan Valley enable vertical tasting room operations that bypass traditional wholesale channels.
Germany
Reinheitsgebot-adjacent consumer expectations create positioning challenges for fruit-forward melomel formulations. ECHA chemical safety documentation requirements govern additive use in flavored variants. Bavarian craft beverage tourism circuits around Munich are incorporating mead producers into established brewery trail infrastructure.
United Kingdom
HM Revenue and Customs excise duty structures for honey wine remain less favorable than cider and perry tax bands. Cornish and Devon-based producers leverage agricultural provenance narratives in specialty retail positioning. The Soil Association organic certification pathway attracts premium-tier producers seeking differentiation in London metropolitan distribution.
Poland
Revived traditional mead consumption patterns in Mazovia and Podlaskie Voivodeships support heritage-style production scaling. EU geographical indication frameworks for Polish mead create export credential advantages. Warsaw-based distributors are consolidating regional brands for Central European market development.
Mead Beverage Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with craft producers controlling premium positioning while mobile canning services enable private-label entry. The vendor base clusters around three strategic archetypes: barrel-aging premium specialists, fruit-forward melomel innovators, and subscription-driven direct-to-consumer operators. Competitive moves concentrate on securing multi-state shipping permissions and securing exclusive apiary partnerships for honey supply security.
Within the barrel-aging premium tier, Superstition Meadery and Schramm's Mead exemplify positioning strategies built on extended maturation protocols and limited-release scarcity economics. Redstone Meadery anchors the direct-to-consumer shipping archetype through state-by-state license accumulation. These producers occupy positions that illustrate how regulatory navigation capabilities and supply chain control differentiate competitive outcomes in fragmented craft alcohol markets.
| Leading Market Players |
|---|
| Redstone Meadery |
| Wild Blossom Meadery |
| B. Nektar Meadery |
| Dansk Mjød |
| Superstition Meadery |
| Schramm's Mead |
| Sap House Meadery |
| Cornish Mead Co. |
| Moonlight Meadery |
| Others |
Supply Flow & Price Mechanics
Captive apiary partnerships in the Pacific Northwest anchor supply security and pricing power for barrel-aging specialists who command premium positioning through controlled honey sourcing. This backward integration into beekeeping operations insulates producers from colony collapse disorder volatility while supporting direct-to-consumer margin structures that bypass three-tier distribution markups.
Pricing Analysis
Direct-to-consumer shipping discounts eliminate distributor margin layers that traditionally absorb 25-30 points in craft beverage economics. Pricing stratifies across barrel-aged reserve tiers, seasonal fruit-forward releases, and entry-level session formats, with excise tax asymmetry compressing competitive positioning in jurisdictions treating honey wine above grape wine rates. Cost pressure intensifies in keg formats where cold chain logistics and account-level service erode per-unit economics. Restaurant buyers exhibit highest price sensitivity due to by-the-glass program margin requirements, while subscription club members accept premium positioning for exclusive access.
Supply Chain Analysis
Refrigerated freight costs from California and Florida apiary zones concentrate supply risk for producers without multi-source honey contracts. Domestic beekeeping operations in the Pacific Northwest, Colorado, and Michigan feed raw material pipelines, with fermentation equipment and oak cooperage drawn from established craft distilling supplier networks. Single-source vulnerability around colony health management threatens vintage consistency. Distribution runs through a hybrid structure combining tasting room direct sales, mobile canning partnerships for retail-ready formats, and state-by-state shipping permissions that fragment downstream economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mead category reads as a late-cycle quality story where craft beverage tourism and barrel-aged scarcity economics justify premium positioning as consumers migrate toward experiential drinking occasions with agricultural provenance narratives.
For Market Incumbents: Cement apiary supply control through exclusive regional partnerships or captive beekeeping operations to defend against honey input volatility from colony collapse pressures. Deepen vertical integration into mobile canning services and cold chain logistics to capture margin pools currently leaking to third-party providers. Channel control through accumulated multi-state shipping licenses remains the priority defensive lever against emerging subscription-first competitors.
For New Entrants and Emerging Players: Crossover craft cider consumers migrating toward fruit-forward melomel formulations represent the most penetrable buyer archetype with minimal brand loyalty and openness to agricultural storytelling. Target Texas and Pennsylvania direct-to-consumer shipping liberalization as whitespace geography with permissive regulatory frameworks and concentrated urban demand. A tasting room-first go-to-market angle with immediate subscription conversion programs outperforms traditional wholesale buildout in early-stage capital deployment.
For Investors and Strategic Acquirers: Roll-up economics work for barrel-aging specialists with established apiary partnerships because honey supply security and extended maturation protocols create durable competitive moats that resist commoditization. Platform consolidation around direct-to-consumer shipping infrastructure and multi-state license portfolios offers medium-term viability as regulatory arbitrage advantages compress. Watch TTB formula modernization timelines as the signal indicating when interstate commerce friction reduction will eliminate regional producer protectionism.
| Strategic Initiative | Industry Significance |
|---|---|
| Apiary Partnership Securement | Exclusive honey sourcing contracts with Pacific Northwest beekeepers insulate against colony collapse volatility and support vintage consistency claims. |
| Multi-State Shipping License Accumulation | Direct-to-consumer permissions in Texas, Pennsylvania, and New York unlock producer-controlled revenue capture outside three-tier distribution economics. |
| Barrel-Aging Capacity Expansion | Oak and spirit cask maturation protocols borrowed from craft distilling enable premium price positioning that sustains margins above commodity wine alternatives. |
| Mobile Canning Service Integration | Partnerships with regional mobile canning operators reduce capital barriers for small-batch producers entering retail distribution without fixed line investment. |
| Subscription Club Infrastructure Buildout | Monthly shipment programs convert tasting room visitors at rates exceeding 25% of first-time buyers in mature craft beverage markets. |
Methodological Framework
Direct dialogue with meadery owners, TTB compliance officers, apiary operators, craft beverage distributors, and tasting room managers grounded qualitative insights in operational reality across production, regulatory, and channel functions. Secondary validation drew from Alcohol and Tobacco Tax and Trade Bureau formula filings, state alcohol beverage control board licensing databases, FDA ingredient safety documentation, and regional customs records tracking honey import flows. Bottom-up production volume estimates triangulated against top-down consumption surveys to anchor forecast confidence intervals.
Bottom-up modeling aggregated producer-level capacity and utilization rates across identified craft meaderies, while top-down analysis calibrated category penetration against craft cider and natural wine adoption curves over the projection horizon. Segmentation dimensions included product type classification, residual sugar and carbonation status, packaging format capital intensity, and channel access permissions varying by state regulatory cluster. CAGRs derived from vintage-to-vintage shipment data and subscription club growth trajectories, with barrel-aging inventory cycles and honey harvest seasonality incorporated as industry-specific timing inputs.
Inputs from apiary operators and state licensing authorities were available through the study window; gaps in real-time colony health surveillance and pending TTB guidance revisions introduce uncertainty bands around supply security and interstate commerce expansion assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Commercial Wine Dispenser Market