
 Europe Online Grocery Market | 2026-2036
Europe Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Grocery Market Intelligence
The EU Green Deal is realigning how European grocers structure fulfillment networks and packaging protocols. Tesco leverages its proprietary distribution infrastructure to sustain next-day coverage across British postcodes. Carrefour anchors its multi-format strategy through hyperlocal dark stores in Parisian arrondissements. Ocado Group differentiates via automated warehouse robotics that compress order-to-door timelines.
Europe online grocery denotes the digital retailing of food staples, fresh produce, and household consumables through web platforms and mobile applications, typically involving temperature-controlled logistics, real-time inventory synchronization, and scheduled or on-demand fulfillment. The category serves time-constrained consumers seeking to replace physical supermarket visits with curated digital basket building and doorstep receipt of perishables. Home delivery and same-day delivery models command the largest revenue pools as urban density and subscription loyalty programs deepen order frequency. Click & collect retains structural importance in suburban and rural catchments where delivery economics remain constrained by distance and route fragmentation.
REACH and the EU Green Deal shape packaging material compliance and carbon accounting obligations for cross-border grocery fulfillment. EFSA guidelines on food contact materials and cold-chain integrity standards filter directly into warehouse design and last-mile vehicle specifications. Stakeholders must monitor how CSRD disclosure requirements will force visibility into Scope 3 emissions from third-party delivery fleets and supplier agriculture inputs.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing retailers to redesign last-mile logistics around reusable containers and electric vehicle fleets. Dual-income urban households across France, Germany, and the United Kingdom now treat digital grocery channels as default weekly shopping infrastructure.
Growth Catalysts
- REACH compliance frameworks:Chemical safety standards for food contact materials are accelerating warehouse automation investments to reduce human handling contamination risks.
- Dark store micro-fulfillment:Hyperlocal inventory positioning in Parisian and Berlin arrondissements compresses delivery windows below two hours for fresh categories.
- CSRD disclosure mandates:Scope 3 carbon accounting requirements are pushing retailers to consolidate supplier bases and favor regional agriculture inputs over air-freighted imports.
Market Restraints
- Last-mile labor costs:Driver wage inflation in German and Dutch urban corridors consumes 18-22% of order value, constraining unit economics outside dense catchments.
- Perishable shrinkage:Temperature excursions in multi-drop routes degrade fresh produce margins, particularly for berries and leafy greens requiring 2-4°C chains.
- Single-use packaging bans:France's AGEC law and similar national implementations impose deposit-return complexity that slows checkout conversion rates.
Strategic Opportunities
- Subscription loyalty programs:Annual membership models in UK metropolitan zones lock in predictable demand density and reduce customer acquisition costs.
- Rural click-and-collect penetration:Underdeveloped Spanish and Italian provincial markets retain structural importance where delivery radius economics fail.
- AI-driven demand forecasting:Machine learning convergence with IoT shelf sensors is cutting food waste by 30-40% in pilot Scandinavian operations.
Industry Challenges
- Cold-chain engineering talent:Refrigeration systems design and thermal packaging expertise scarcity delays warehouse retrofit timelines by 8-14 months.
- Legacy ERP integration:Real-time inventory synchronization between web platforms and physical store systems requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Grocery Market |
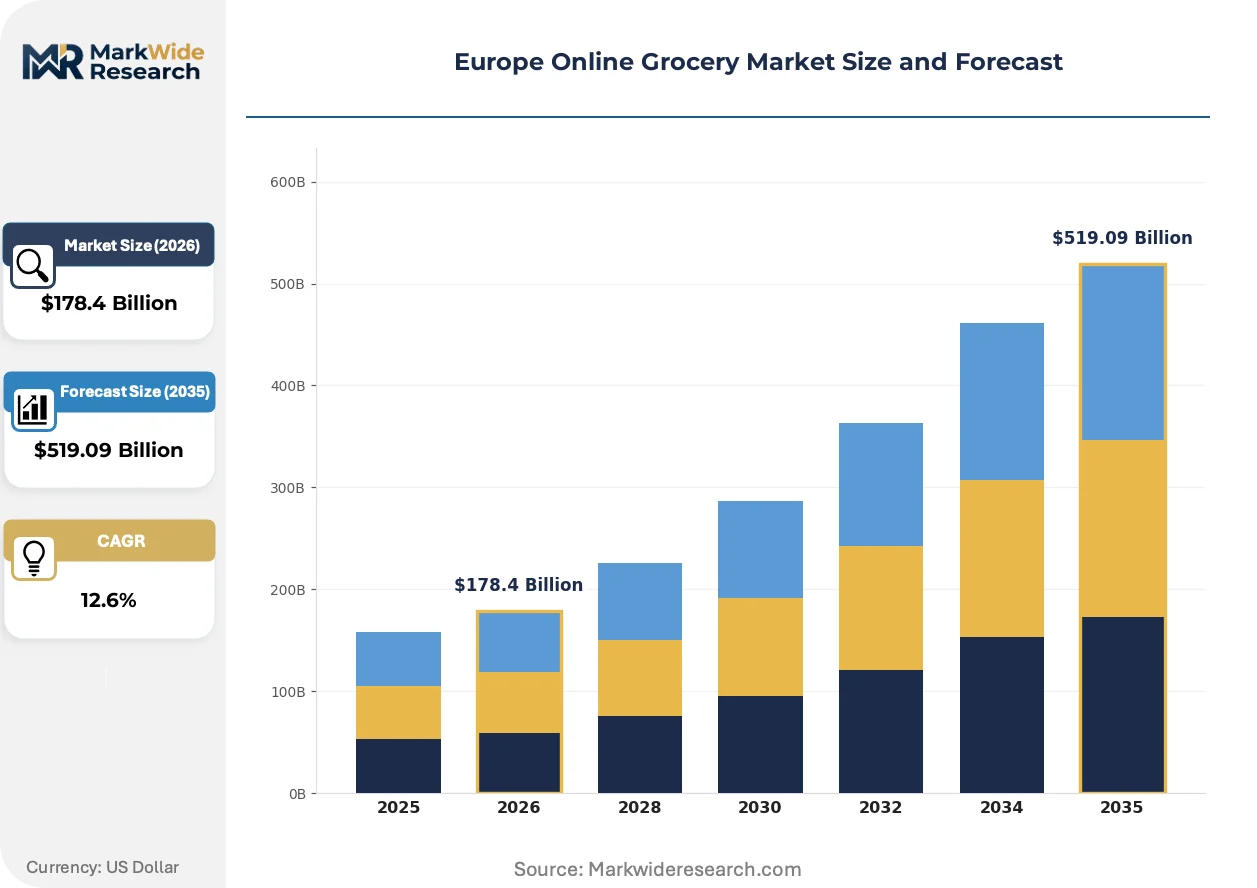
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $519.09 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
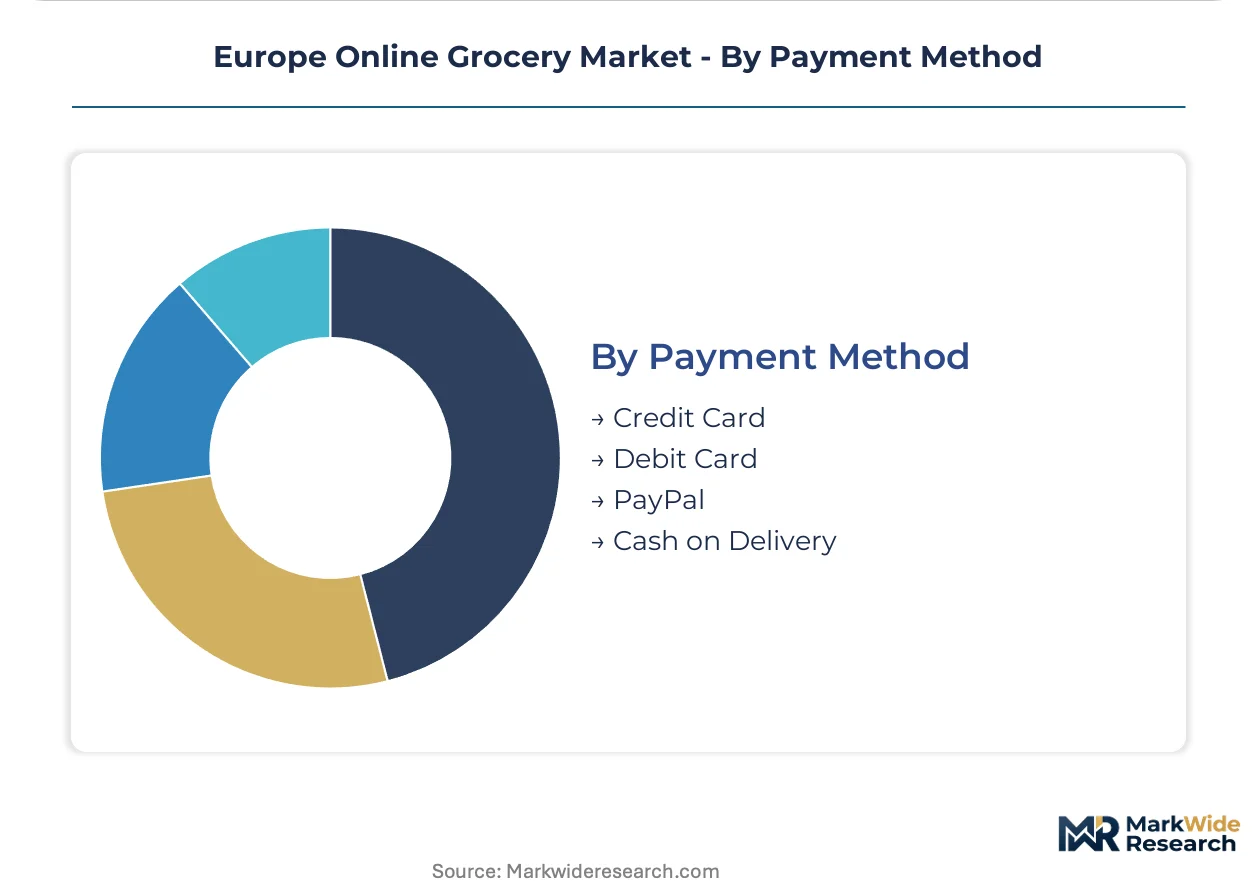
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Beverages Customer Type: Households, Professionals, Students, Seniors Delivery Model: Home Delivery, Click & Collect, Scheduled Delivery, Same-Day Delivery Payment Method: Credit Card, Debit Card, PayPal, Cash on Delivery |
| Companies Covered | Koninklijke Ahold Delhaize, Edeka, Tesco, Auchan, Sainsbury's, Ocado Group, REWE, ICA Gruppen, Carrefour, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Grocery Market Strategic Shifts & Innovations
Automated fulfillment robotics and AI-powered demand forecasting are compressing order-to-door timelines while regulatory pressure on packaging waste forces material science innovation. These forces are reconfiguring capital allocation across warehouse infrastructure and last-mile fleet specifications.
Automated storage and retrieval systems with robotic pick arms are unifying previously fragmented warehouse workflows. German and French retailers are deploying these systems at scale to handle 3,000-4,000 SKUs with 99.5% pick accuracy. This technology is unifying inventory management with direct-to-consumer fulfillment, eliminating intermediate distribution centers.
EFSA guidelines on food contact materials are tightening specifications for recycled content in primary packaging. Manufacturers must now validate migration limits for contaminants across temperature fluctuations from -18°C to ambient. Fresh produce and ready-meal segments face the steepest compliance curves, driving substitution toward fiber-based barrier coatings.
Urban consumers are consolidating weekly purchases into fewer, larger digital baskets rather than frequent top-up trips. Subscription models with predictable delivery slots are displacing on-demand impulse ordering in London, Paris, and Amsterdam. This pattern concentrates demand into Tuesday-Thursday windows, requiring dynamic capacity pricing to smooth fulfillment peaks.
Europe Online Grocery Market Segmentation
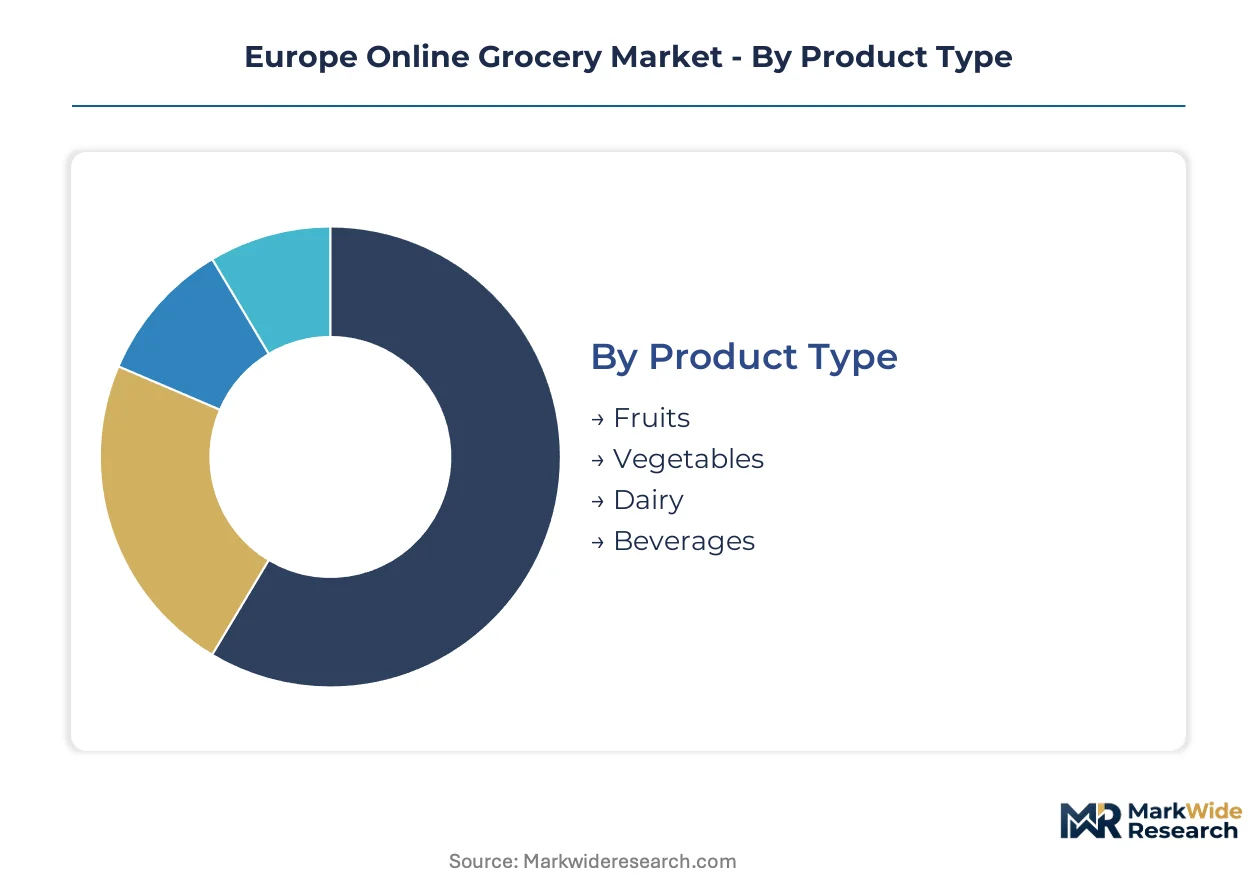
European grocers configure fulfillment networks differently across product freshness requirements and customer time constraints. Segmentation clarity determines warehouse automation investments and last-mile fleet specifications.
Product Type:
Freshness tolerance dictates replenishment cadence and cold-chain infrastructure spend across each category.
- Fruits:Temperature excursions above 4°C accelerate ripening and shrinkage losses. Berry and stone fruit demand clusters in German and British metropolitan zones where subscription programs lock in weekly purchase patterns.
- Vegetables:Leafy greens require continuous cold chains from harvest to doorstep, driving retailer investment in refrigerated dark stores. French and Dutch households show highest penetration for organic vegetable subscriptions.
- Dairy:Chilled distribution networks with 2-6°C maintenance.
- Beverages:Ambient-stable categories with lower logistics complexity.
Volume placements concentrate in Vegetables; the faster expansion belongs to Fruits.
Customer Type:
Life stage and income stability shape basket size predictability and loyalty program design.
- Households:Dual-income families generate the largest average order values and lowest cancellation rates. British and French household subscriptions anchor demand density for Tuesday-Thursday delivery slots.
- Professionals:Time-constrained urban workers prioritize same-day and scheduled evening delivery windows. Berlin and Amsterdam show highest professional segment penetration for app-based reordering.
- Students:Price-sensitive demand concentrated in shared accommodation corridors.
- Seniors:Growing digital adoption driven by accessibility features and telephone support integration.
Revenue gravity sits with Households; the steepest expansion trajectory belongs to Professionals.
Delivery Model:
Urban density and route economics determine which fulfillment modes achieve unit viability.
- Home Delivery:Full-service doorstep receipt with temperature-controlled vehicles. Paris and London postcodes sustain 2-hour fresh delivery windows through hyperlocal micro-fulfillment.
- Same-Day Delivery:Express fulfillment promising receipt within 4-8 hours. German urban corridors lead adoption where dark store density supports rapid pick-pack cycles.
- Click & Collect:Customer pickup from designated points addressing rural and suburban coverage gaps.
- Scheduled Delivery:Fixed-slot bookings optimizing fleet utilization through demand smoothing.
Transaction volume clusters in Home Delivery; the fastest share gains belong to Same-Day Delivery.
Payment Method:
Checkout friction and trust frameworks vary across demographic and national contexts.
- Credit Card:Dominant in British and Nordic markets with established e-commerce trust.
- Debit Card:Preferred in German and Dutch markets with lower revolving credit penetration.
- PayPal:Strong adoption among younger demographics seeking purchase protection.
- Cash on Delivery:Retains importance in Southern European markets with lower card penetration.
Credit Card transactions lead volume; PayPal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentration in automated fulfillment technology clusters contrasts with consumption gravity across metropolitan France, Germany, and the United Kingdom. Nordic cold-chain engineering capabilities supply warehouse infrastructure southward. Southern European markets retain fragmented logistics networks with lower digital penetration.
Germany
Dual-income households in Berlin and Munich drive subscription loyalty program adoption with predictable weekly basket patterns. REACH compliance frameworks for food contact materials accelerate automation investments to reduce contamination risks. The Rhine-Ruhr corridor hosts dense dark store networks enabling sub-two-hour fresh delivery windows.
United Kingdom
London postcodes sustain the continent's highest grocery e-commerce penetration with next-day coverage anchored by proprietary distribution infrastructure. CSRD disclosure mandates force visibility into Scope 3 emissions from third-party delivery fleets. The Southeast England logistics cluster concentrates automated warehouse robotics deployment at scale.
France
Parisian arrondissements anchor hyperlocal micro-fulfillment with refrigerated dark stores compressing delivery timelines. The AGEC law imposes deposit-return complexity on single-use packaging that slows checkout conversion rates. Île-de-France organic vegetable subscriptions show the region's highest household penetration rates.
Netherlands
Amsterdam and Rotterdam professionals prioritize app-based reordering with scheduled evening delivery windows. EFSA guidelines on cold-chain integrity standards filter directly into last-mile vehicle specifications. The Randstad urban corridor leads pilot programs for AI-driven demand forecasting cutting food waste.
Spain
Barcelona and Madrid concentrate professional segment demand while provincial markets retain structural importance for click-and-collect models. National packaging waste directives under EU Green Deal implementation lag Northern European timelines. Andalusian agriculture inputs supply regional fulfillment networks reducing air-freighted imports.
Europe Online Grocery Market Key Industry Players
The competitive structure tilts toward multi-format retailers with proprietary logistics infrastructure. British and Dutch markets show higher consolidation around subscription-anchored platforms. Three archetypes dominate: legacy supermarket chains with digital extensions, pure-play online specialists with automated fulfillment, and cooperative retail federations with regional density. Consolidation through dark store network expansion and strategic technology licensing partnerships represent the dominant competitive vectors.
Among British-based retailers, Tesco and Sainsbury's occupy positions within the legacy-digital hybrid archetype, leveraging store footprints for fulfillment coverage. Ocado Group exemplifies the pure-play automation specialist tier with warehouse robotics differentiation. Koninklijke Ahold Delhaize anchors the cooperative-federation model across Benelux markets with regional supply chain density.
| Leading Market Players |
|---|
| Koninklijke Ahold Delhaize |
| Edeka |
| Tesco |
| Auchan |
| Sainsbury's |
| Ocado Group |
| REWE |
| ICA Gruppen |
| Carrefour |
| Others |
Cost & Logistics Intelligence
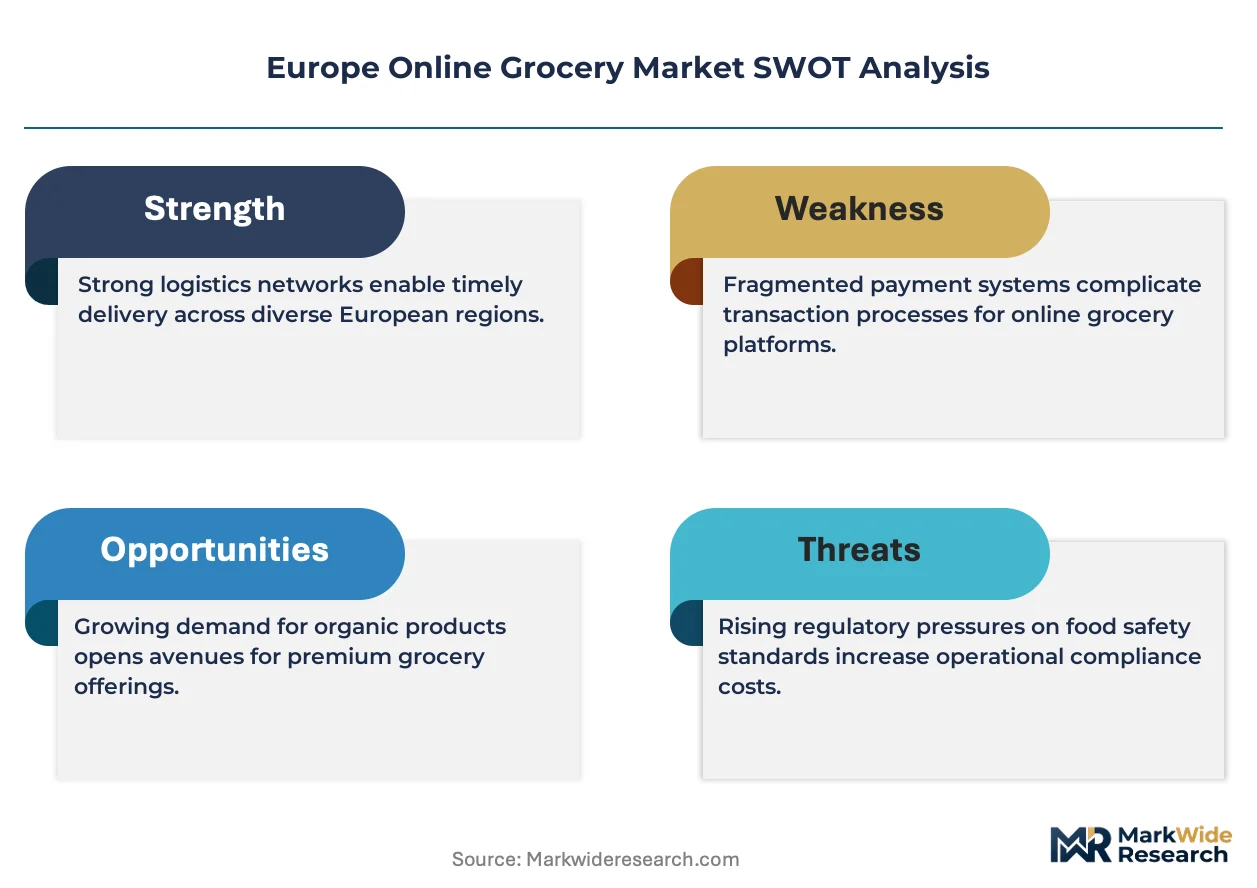
Captive control of refrigerated last-mile fleets anchors pricing power for European grocers confronting EU Green Deal compliance costs. Retailers with in-house cold-chain logistics command premium positioning against outsourced competitors facing driver wage inflation and perishable shrinkage penalties.
Pricing Analysis
Margin tightening in express delivery tiers reflects last-mile labor cost absorption and temperature-controlled vehicle depreciation. Three-tier pricing structure across premium, standard, and economy levels segments by delivery speed and cold-chain assurance, with subscription households showing lowest price sensitivity and student segments demanding economy positioning. Cost compression accelerates as France's AGEC law imposes deposit-return overhead on checkout flows.
Supply Chain Analysis
Dual-sourcing mandates from EFSA-compliant retailers require qualified suppliers across Germany, France, and the Netherlands for cold-chain equipment and thermal packaging materials. Raw material dependencies center on refrigeration compressors, fiber-based barrier coatings, and electric vehicle battery systems. Single-source vulnerability concentrates in automated warehouse robotics sourced from German engineering clusters. Distribution runs through hyperlocal dark stores feeding metropolitan delivery zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into automated fulfillment infrastructure defines competitive positioning as retailers race to compress order-to-door timelines while absorbing regulatory compliance costs.
For Market Incumbents: Hedge against margin erosion by consolidating dark store networks in Parisian and Berlin arrondissements where route density sustains unit economics. Invest in REACH-compliant automation to reduce contamination risk and labor dependency. Prioritize proprietary cold-chain fleets over third-party logistics to capture Scope 3 carbon accounting visibility. For New Entrants and Emerging Players: Capture white-space in Spanish and Italian provincial click-and-collect corridors where delivery radius economics remain unviable for incumbents. Target professional segments in Amsterdam and Rotterdam with app-based scheduled evening windows. Enter through AI-driven demand forecasting partnerships with regional agriculture cooperatives. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing deals for automated storage and retrieval systems. Long-term viability favors pure-play automation specialists with proven 99.5% pick accuracy metrics. Watch for inflection signals in CSRD disclosure mandates forcing consolidation of supplier bases toward regional agriculture inputs.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Hyperlocal micro-fulfillment in Paris and Berlin compresses fresh delivery below two hours. |
| Automated Warehouse Robotics Deployment | German and French retailers achieve 3,000-4,000 SKU handling with 99.5% pick accuracy. |
| Subscription Loyalty Program Launch | British metropolitan households lock in Tuesday-Thursday demand density and reduce acquisition costs. |
| Electric Fleet Cold-Chain Conversion | EU Green Deal packaging directives force last-mile logistics redesign around reusable containers. |
| AI-Driven Demand Forecasting Integration |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with grocery chain logistics directors, cold-chain equipment procurement leads, dark store operations managers, and EFSA regulatory compliance officers combined with secondary validation from EU Green Deal implementation documents, REACH chemical safety databases, and national packaging waste directive records. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation reconciled volume estimates.
Reconciliation of customs import records against retailer capex disclosures and fleet registration databases verified infrastructure investment trajectories across the projection horizon. Segmentation dimensions modeled include product freshness tier, customer life stage, delivery speed requirement, and urban density cluster. CAGRs derived from logistic curve fitting to subscription penetration patterns and dark store rollout timelines. Cold-chain engineering talent scarcity and legacy ERP integration costs informed capacity constraint assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement timelines and electric vehicle subsidy durability. Forecasts reflect documented assumptions around dual-income household digital adoption saturation and perishable shrinkage rate improvements. Deviation in REACH compliance cost pass-through or driver wage inflation trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Inflight Catering Market
Food Service
Online Catering Market
Food Service
Ship Catering Service Market
Food Service
Global Combi Ovens Market
Food Service
Commercial Charbroiler Market
Food Service
Kuwait Food Service Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
India Full Service Restaurants Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Wok Market
Food Service
Europe Food Away from Home Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Air Fryer Market
Food Service
Self-Heating Hot Pot Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Food Service Utensils Market