
 Singapore Food Service Market | 2026-2036
Singapore Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Food Service Market Insights
The capital-intensity divergence between legacy full-service operators and asset-light digital-native brands is unwinding competitive dynamics across Singapore. McDonald's Corporation leverages its captive supply chain and real estate footprint to sustain cost advantages in high-traffic zones. Paradise Group Holdings Pte Ltd anchors its portfolio around experiential dining formats that differentiate through regional Chinese cuisine specialization.
Food service encompasses the commercial preparation, sale, and delivery of prepared meals and beverages through institutional or retail channels, governed by HACCP protocols and NEA hygiene grading from A to D. Its primary purpose is to satisfy out-of-home consumption demand across consumer and institutional buyer segments. Quick service restaurants lead volume throughput in the service type dimension, while online delivery channels capture the fastest structural expansion in distribution. Corporate clients represent a concentrated margin pool within end users, as contract catering yields predictable procurement cycles and bulk pricing leverage.
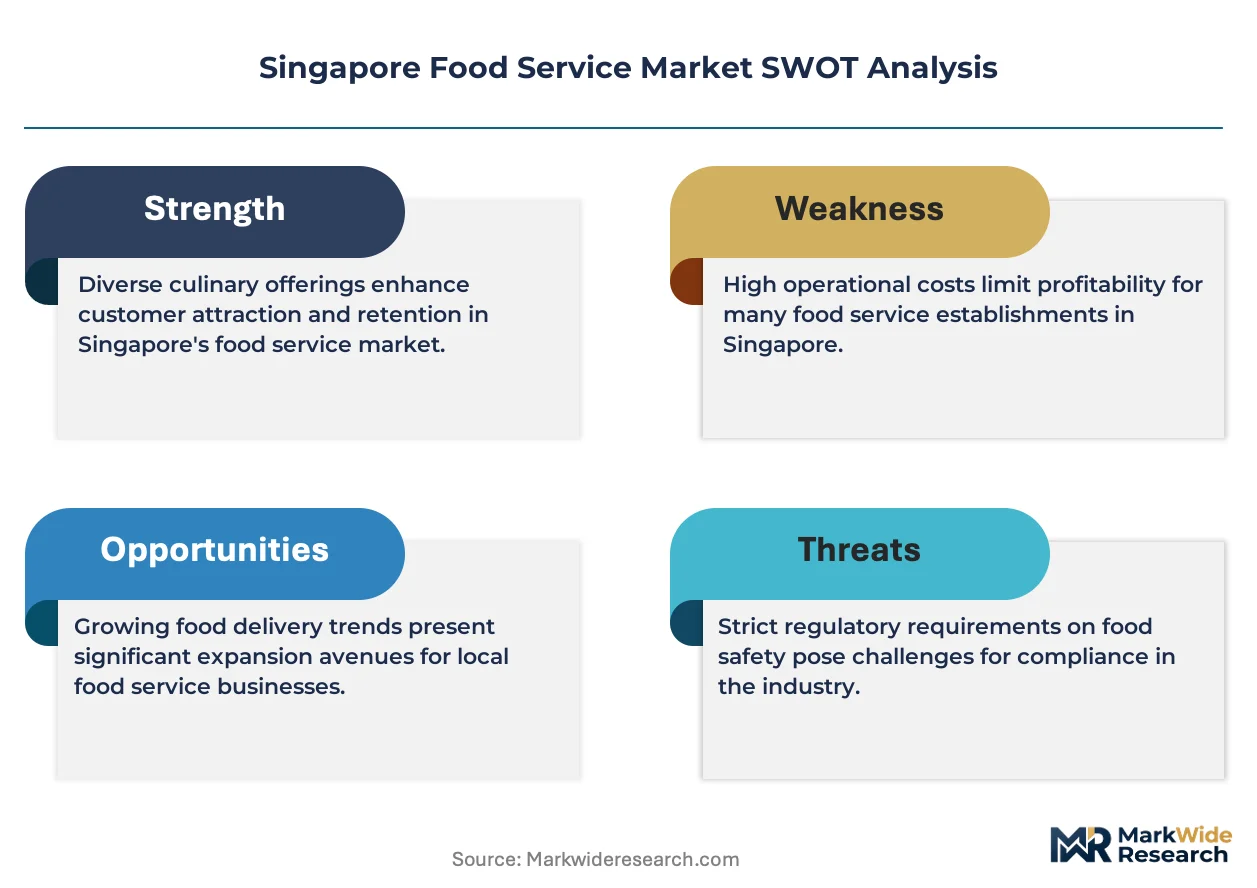
NEA food hygiene grading, FSSAI-aligned import standards for raw materials, and SFA licensing requirements collectively shape operational compliance burdens and market access thresholds for new entrants. These frameworks elevate capital requirements for kitchen infrastructure and staff certification, filtering out sub-scale operators. Stakeholders must monitor how tightening sustainability disclosure obligations under Singapore's Green Plan intersect with packaging and waste management costs across delivery-heavy formats.
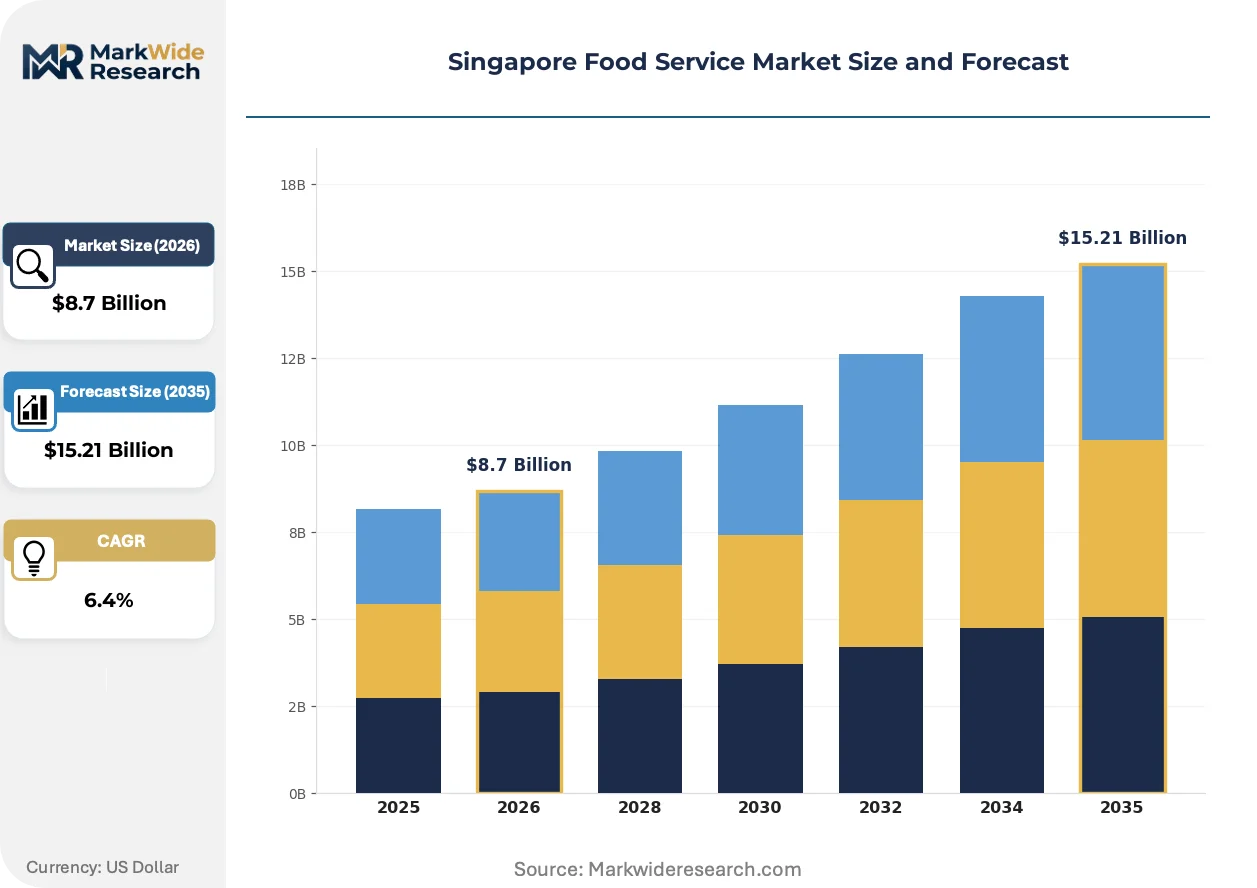
Market Dynamics
Cloud kitchen proliferation across Singapore's residential zones is compressing the traditional restaurant real estate model, while NEA hygiene grading enforcement tightens capital requirements for physical kitchen infrastructure.
Growth Catalysts
- NEA Food Hygiene Grading:Mandatory A-to-D certification drives kitchen modernization investments, filtering out sub-scale operators and elevating industry standards.
- Quick Service Restaurant Segment:Digital ordering platforms capture dominant customer interface share, accelerating throughput velocity and reducing front-of-house labor dependency.
- Singapore Green Plan:Sustainability disclosure obligations intersect with delivery-heavy formats, creating competitive differentiation through packaging innovation and waste reduction protocols.
Market Restraints
- Central Kitchen Input Costs:FSSAI-aligned import standards for raw materials elevate procurement complexity and compliance overhead for cross-border supply chains.
- SFA Licensing Requirements:Staff certification mandates and infrastructure inspections extend market access timelines for new entrants, concentrating operational expertise among incumbents.
- Cloud Kitchen Saturation:Residential zone density limits and zoning enforcement in mature districts constrain expansion runway for digital-native brands.
Strategic Opportunities
- Institutional Catering Contracts:Corporate client procurement cycles yield predictable revenue streams and bulk pricing leverage within Singapore's dense commercial district concentration.
- Regional Chinese Cuisine Specialization:Experiential dining formats command premium positioning through differentiated menu architecture and service theater.
- HACCP Protocol Integration:Food safety management system certification enables institutional channel access and export qualification for prepared meal manufacturing.
Industry Challenges
- Kitchen Infrastructure Capex:NEA Grade A compliance demands ventilation, refrigeration, and sanitation equipment investments that strain working capital for emerging operators.
- Digital Platform Commission Structures:Third-party delivery aggregates extract 15-30% per order, compressing net margins across price-sensitive segments and forcing direct channel development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Food Service Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafés, Caterers End User: Residential Consumers, Corporate Clients, Educational Institutions, Hospitals Product Type: Food, Beverages, Desserts, Snacks Distribution Channel: Dine-In, Takeaway, Online Delivery, Food Trucks |
| Companies Covered | McDonald's Corporation, Starbucks Corporation, KFC, Paradise Group Holdings Pte Ltd, Jollibee Foods Corporation, Burger King, Subway, Crystal Jade Culinary Concepts Holding, Hai Di Lao Hot Pot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Food Service Market Trends and Innovations
Automation and data analytics are reconfiguring operational workflows across Singapore's food service landscape, compressing labor dependency while intensifying compliance precision.
Automated kitchen equipment is displacing manual food preparation stations in high-volume quick service environments. Chains operating across Singapore's transit-adjacent locations deploy robotic cooking lines to standardize output consistency and reduce headcount exposure to tight labor markets. This capital substitution is compressing break-even timelines for new outlet launches while elevating throughput ceilings during peak demand windows.
Singapore's Green Plan sustainability disclosure obligations are mandating packaging material transitions and waste audit transparency across food service operators. The National Environment Agency enforces progressive reporting thresholds that cascade from large enterprises to mid-scale chains through 2030. Cloud kitchen operators face acute cost pressure as biodegradable packaging premiums intersect with thin delivery margins, accelerating supplier consolidation around certified sustainable material providers.
Corporate procurement departments are consolidating catering contracts around multi-year frameworks with embedded performance metrics and sustainability riders. Large financial services and technology employers in Singapore's Central Business District now require vendor ESG disclosure as a mandatory evaluation criterion, displacing transactional spot purchasing. This contract formalization favors operators with captive supply chain visibility and documented carbon accounting across their ingredient sourcing networks.
Singapore Food Service Market Segmentation
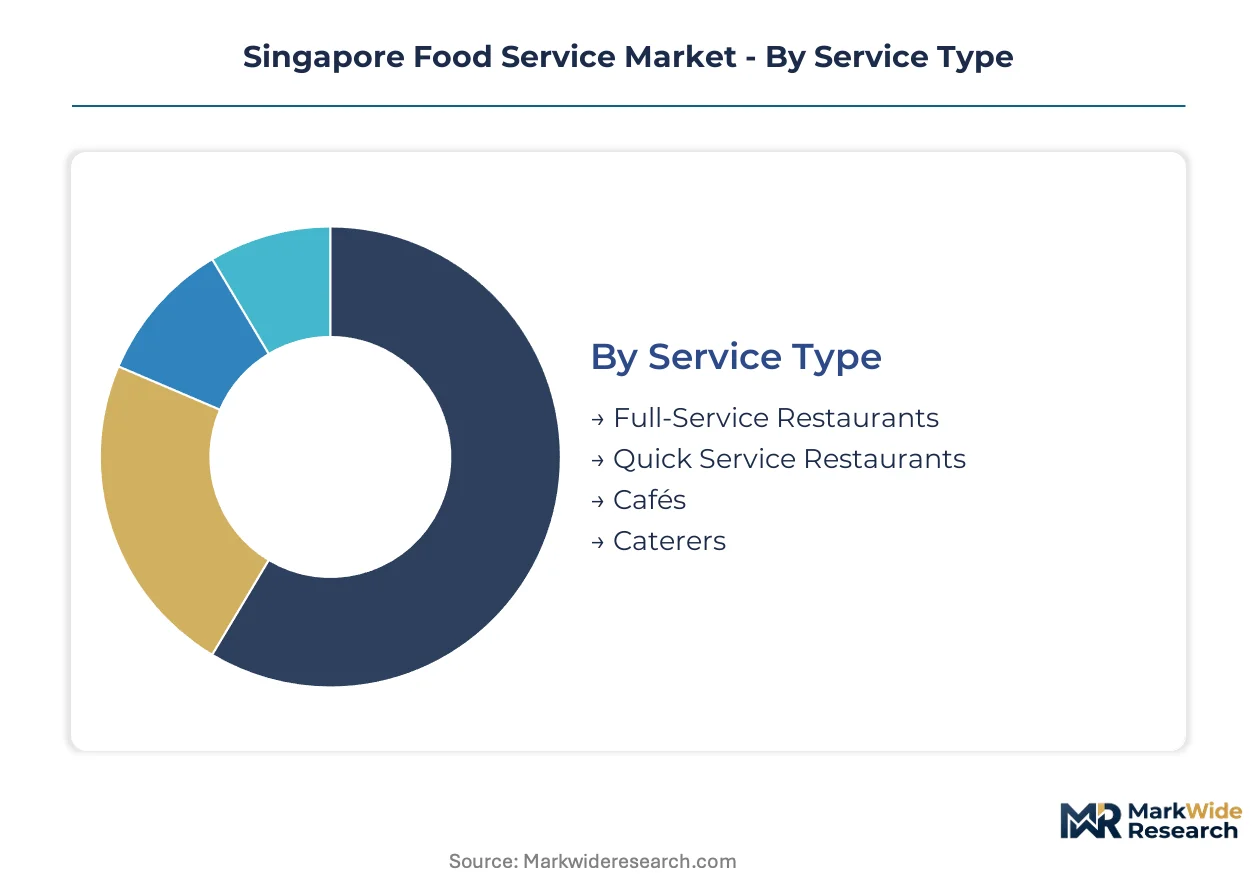
Segmentation in Singapore's food service market reveals how capital intensity, regulatory compliance, and channel economics partition competitive advantage. Each dimension exposes distinct margin structures and operational scale requirements that determine viable entry strategies.
Service Type:
Channel-mix dynamics concentrate volume throughput in formats optimized for Singapore's high-density urban environment and digital-first consumer behavior.
- Full-Service Restaurants:Table-service formats with front-of-house labor intensity and experiential positioning. Demand clusters in Marina Bay and Orchard Road hospitality corridors where tourist and premium residential traffic sustains higher check averages and extended dwell times.
- Quick Service Restaurants:Limited-menu, high-velocity formats with standardized preparation protocols. These dominate hawker centre adjacencies and transit-hub locations where NEA Grade A compliance and automated production lines compress unit economics to serve Singapore's time-constrained workforce.
- Cafés:Beverage-forward formats with light food accompaniment and extended seating models. Remote-work patterns in Tampines and Jurong East sub-regions sustain mid-day occupancy cycles distinct from meal-rush economics.
- Caterers:Off-premise production for events and institutional contracts with batch-cooking infrastructure. Wedding and corporate event concentration in Sentosa and downtown convention venues drives seasonal demand volatility.
By volume, Quick Service Restaurants lead. By growth pace, Caterers are expanding most quickly through institutional contract consolidation.
End User:
Customer-type segmentation exposes diverging procurement patterns across contract stability, price sensitivity, and compliance documentation requirements.
- Residential Consumers:Individual and household purchasers accessing food service through discretionary spending. Digital platform penetration in HDB heartland zones has normalized app-based ordering as the default interface for daily meal solutions.
- Corporate Clients:Business purchasers with formalized vendor onboarding and multi-year catering frameworks. Singapore's Central Business District financial and technology employers now mandate ESG disclosure and carbon accounting from contracted operators.
- Educational Institutions:School and university food service with nutritionally regulated menus and volume-scale procurement. MOE canteen tender processes favor operators with HACCP certification and documented supply chain transparency.
- Hospitals:Healthcare food service with therapeutic diet specialization and stringent hygiene protocols. SingHealth and National University Health System procurement prioritizes NEA Grade A operators with clinical nutrition capabilities.
Corporate Clients deliver the most predictable revenue streams. Residential Consumers show the steepest channel shift toward digital intermediaries.
Product Type:
Margin concentration varies sharply across preparation complexity, ingredient cost volatility, and perishability windows.
- Food:Prepared meal items spanning proteins, grains, and vegetables with full kitchen production requirements. Hawker heritage dishes and regional Chinese cuisine command premium positioning in experiential dining formats.
- Beverages:Coffee, tea, and specialty drink preparations with lower capital intensity and higher repeat purchase frequency. Local kopi culture and third-wave coffee formats coexist across distinct price tiers in Tiong Bahru and Tanjong Pagar clusters.
- Desserts:Sweet course items with occasion-driven demand and Instagram-native marketing dependency. Artisanal gelato and traditional kueh operators target divergent demographic segments within the same retail corridors.
- Snacks:Small-portion, grab-and-go items with extended shelf stability and impulse purchase economics. MRT station kiosks and convenience store partnerships dominate distribution for this category.
Food commands absolute revenue share. Beverages achieve the highest velocity per square foot in premium locations.
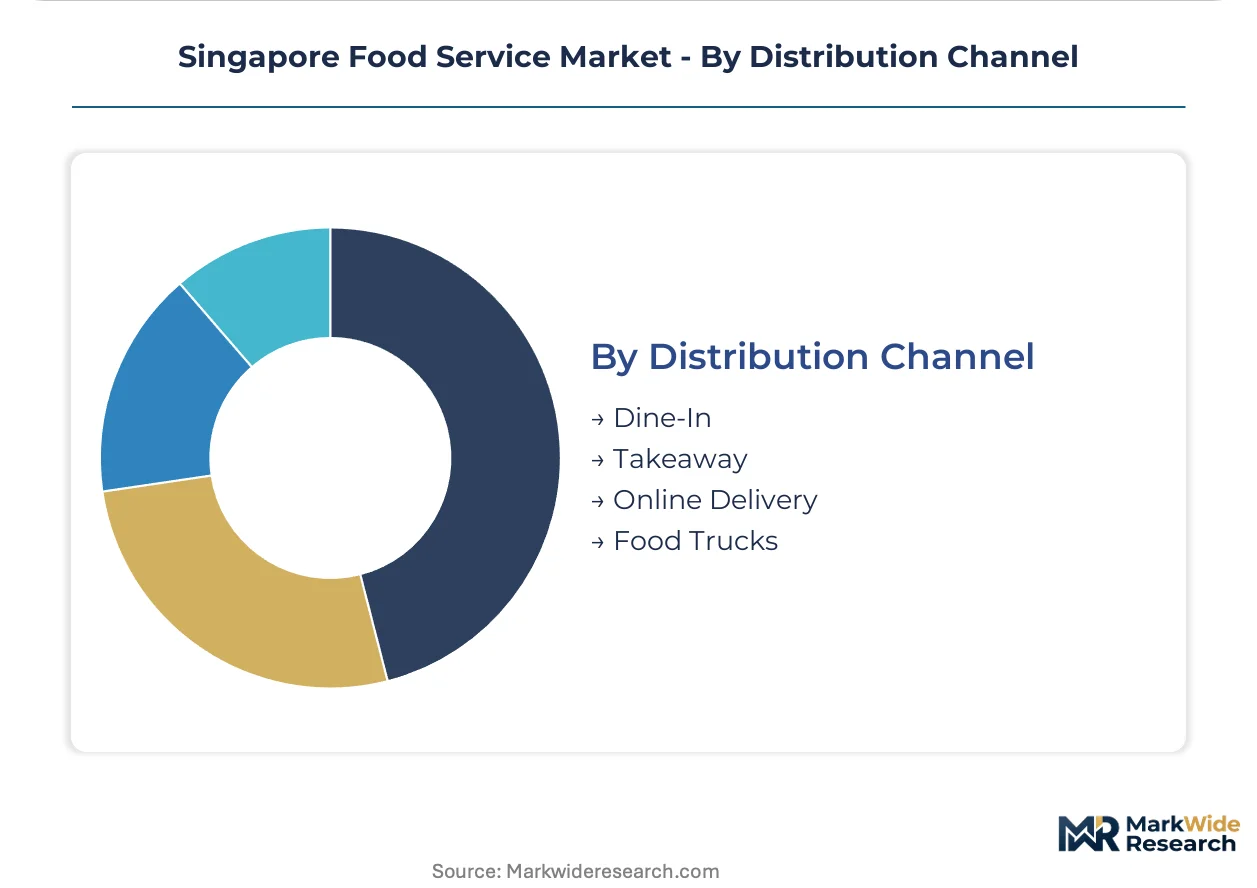
Distribution Channel:
Channel economics determine working capital intensity, customer acquisition cost, and exposure to platform commission structures.
- Dine-In:On-premise consumption with full service or self-service models and fixed real estate overhead. Traditional shophouse conversions in Joo Chiat and Katong leverage heritage aesthetics to differentiate against standardized chain formats.
- Takeaway:Customer-collected orders with minimal front-of-house service and packaging cost absorption. Hawker centre operators rely on this channel to maintain throughput without seating expansion in space-constrained locations.
- Online Delivery:Platform-mediated or direct-channel delivery with 15-30% commission drag or captive logistics investment. Cloud kitchen proliferation in Punggol and Sengkang residential zones has built density around this channel exclusively.
- Food Trucks:Mobile units with rotating locations and event-dependent scheduling. NEA licensing and zoning restrictions limit deployment to designated clusters near business parks and weekend markets.
Online Delivery is gaining share fastest. Dine-In retains margin superiority where location premiums justify fixed costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Singapore's Central Business District, where corporate catering contracts command premium rates, while residential zone operators in Punggol and Sengkang compete on volume through cloud kitchen density.
Central Region
Marina Bay and Orchard Road hospitality corridors sustain full-service restaurant premiums through tourist traffic and extended dwell times. NEA Grade A compliance mandates drive kitchen modernization investments among operators in Raffles Place and Tanjong Pagar. The CBD's financial services employers now require vendor ESG disclosure as mandatory evaluation criteria for catering contracts.
Northeast Region
Punggol and Sengkang residential zones host dense cloud kitchen clusters serving HDB heartland demand through platform-mediated delivery. SFA licensing requirements and staff certification mandates extend market access timelines for new entrants in these maturing districts. Food service automation is compressing break-even timelines for operators deploying robotic cooking lines near transit-adjacent locations.
East Region
Tampines and Changi Business Park sub-regions sustain café occupancy cycles through remote-work patterns distinct from meal-rush economics. The Singapore Green Plan's sustainability disclosure obligations mandate packaging material transitions and waste audit transparency for operators across this corridor. Heritage shophouse conversions in Joo Chiat and Katong leverage aesthetic differentiation against standardized chain formats.
West Region
Jurong East and one-north business parks concentrate institutional catering demand from technology and biomedical employers. MOE canteen tender processes favor operators with HACCP certification and documented supply chain transparency in educational clusters. Hawker centre adjacencies in Jurong West maintain throughput through takeaway channels without seating expansion.
North Region
Woodlands and Yishun residential zones exhibit emerging cloud kitchen saturation as zoning enforcement constrains expansion runway. NEA hygiene grading enforcement tightens capital requirements for physical kitchen infrastructure across these developing districts. MRT station kiosk networks dominate snack category distribution through impulse purchase economics.
Singapore Food Service Market Competitive Landscape
Concentration sits with multinational quick-service chains that leverage captive supply chains and real estate footprints to sustain cost advantages in high-traffic zones. The vendor base spans three tiers: global brands with standardized protocols, regional experiential dining specialists, and local cloud-native digital operators. Strategic moves center on backward integration into central kitchen infrastructure and direct-channel development to bypass platform commission structures.
Among global quick-service operators, McDonald's Corporation and Starbucks Corporation exemplify scale-driven archetypes with transit-hub location strategies. Paradise Group Holdings Pte Ltd and Crystal Jade Culinary Concepts Holding occupy positions within the experiential dining tier, anchoring portfolio differentiation around regional Chinese cuisine specialization. Jollibee Foods Corporation represents the regional expansion archetype, leveraging format portability across Southeast Asian markets.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Starbucks Corporation |
| KFC |
| Paradise Group Holdings Pte Ltd |
| Jollibee Foods Corporation |
| Burger King |
| Subway |
| Crystal Jade Culinary Concepts Holding |
| Hai Di Lao Hot Pot |
| Others |
Pricing and Supply Chain Analysis
Long-term catering contracts with embedded price adjustment clauses lock in supply access for institutional clients while insulating operators from raw material volatility across NEA-regulated kitchen networks. These frameworks concentrate purchasing power among corporate buyers in Singapore's Central Business District, compressing margin buffers for operators without backward integration into central kitchen infrastructure.
Pricing Analysis
The customization-premium spread separates experiential dining formats commanding table-service premiums from standardized quick-service transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by NEA hygiene grade certification and location traffic density, with Grade A operators in Marina Bay corridors capturing the widest spreads. Price erosion runs through cloud kitchen tiers as platform commission structures extract fifteen to thirty percent per order, forcing direct-channel investments. Corporate catering contracts exhibit lowest price sensitivity due to procurement budget insulation, while residential delivery segments face acute sensitivity to packaging cost pass-throughs under Singapore Green Plan compliance.
Supply Chain Analysis
Inventory lead-times for temperature-controlled proteins and specialty Asian condiments stretch procurement planning horizons beyond standard dry-goods cycles. Malaysia, Indonesia, and Australia anchor Singapore's raw material sourcing for poultry, seafood, and premium beef, with FSSAI-aligned import standards elevating documentation burdens. Single-source vulnerability concentrates in specialty sauce manufacturing and regional Chinese ingredient categories where Malaysian suppliers dominate. Distribution runs through central kitchen consolidation points serving multiple cloud kitchen endpoints, with SFA-licensed cold chain logistics operators controlling last-mile integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's food service market represents a service-attach opportunity where recurring revenue from corporate catering contracts and subscription meal programs expands faster than transactional dine-in volumes. After-sales layers including kitchen equipment maintenance contracts and staff certification training programs deepen customer lifetime value beyond initial equipment sales.
For Market Incumbents: Fortify margin position by deepening backward integration into central kitchen infrastructure and securing exclusive supply agreements with Malaysian protein processors. Cloud kitchen saturation in Punggol and Sengkang threatens volume growth; counter by locking multi-year institutional catering frameworks with ESG disclosure capabilities before tender processes formalize carbon accounting requirements. For New Entrants and Emerging Players: Anchor in Jurong East and one-north technology corridor sub-regions where biomedical and digital employers lack established catering relationships. White-space concentration sits in HACCP-certified prepared meal manufacturing for educational institutions, with MOE canteen tender processes favoring documented supply chain transparency. Go-to-market through direct-channel delivery apps bypassing third-party commission structures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors operators with captive central kitchen infrastructure and NEA Grade A compliance portfolios. Long-term viability across the analysis window hinges on regulatory compliance moats and direct-channel customer relationships. Acquisition target archetype: mid-scale caterers with institutional contract books and underutilized kitchen capacity. Signal to watch: tightening zoning enforcement in mature residential districts accelerating cloud kitchen operator distress.| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Infrastructure Expansion | Captive production capacity insulates margin from platform commission extraction and raw material volatility. |
| Direct-Channel Delivery Platform Development | Proprietary apps bypass GrabFood and Foodpanda fees that compress net margins fifteen to thirty percent. |
| NEA Grade A Certification Investment | Highest hygiene tier unlocks hospital and institutional procurement channels with multi-year contract stability. |
| Corporate Catering Contract Consolidation | CBD financial employers now mandate ESG disclosure as mandatory vendor evaluation criterion. |
| Sustainable Packaging Supplier Partnership | Biodegradable material sourcing addresses Singapore Green Plan disclosure obligations before 2030 thresholds. |
Research Methodology
Cross-validation between primary interviews with cloud kitchen operators and secondary validation through NEA hygiene grading databases anchors the qualitative findings. Stakeholder conversations encompassed central kitchen facility managers, corporate catering procurement officers at CBD financial institutions, SFA licensing compliance consultants, and platform delivery operations leads. Secondary sources integrated NEA food hygiene grading records, SFA import permit filings, Singapore Green Plan sustainability disclosure frameworks, and hawker centre tenancy data. Bottom-up outlet counting across Punggol, Sengkang, and Jurong East clusters triangulated against top-down market sizing from food service expenditure surveys.
Sensitivity analysis around platform commission rate assumptions and central kitchen utilization thresholds tested forecast robustness. Segmentation modeling spanned service type, end-user archetype, product category, and distribution channel dimensions across the projection horizon. CAGRs derived from outlet expansion trajectories, transaction frequency trends, and average check evolution in quick-service versus full-service formats. Industry-specific inputs incorporated NEA compliance cost inflation curves and Singapore Green Plan packaging transition timelines.
Material uncertainties — regulatory enforcement intensity around residential zone cloud kitchen zoning, platform commission structure negotiations, and FSSAI import standard alignment costs — sit outside the modeled envelope. Forecasts reflect assumptions about sustained corporate return-to-office patterns and institutional catering contract renewal rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Asia Pacific Airline Catering Services Market
Food Service
GCC Food Service Market
Food Service
Egypt Food Service Market
Food Service
Contract Blending Services Market
Food Service
Pizza Oven Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Hospital Food Services Market
Food Service
Vacuum Flask Market
Food Service
International Food Subscription Box Service Market
Food Service
Commercial Tableware Services Market
Food Service
Restaurant Takeout Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Bar Refrigeration Market
Food Service
Spain Food Service Market
Food Service
Chile Food Delivery Market
Food Service
Beverage Napkins Market