
 Saudi Arabia Pizza Restaurants Market | 2026-2036
Saudi Arabia Pizza Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pizza Restaurants Market Analytics
Quick-service restaurant penetration among young adult consumers is expanding across Saudi Arabia's urban centers. Domino's Pizza Inc. leverages its centralized supply hub in Riyadh to sustain consistent delivery radius coverage. Yum! Brands Inc. anchors its multi-brand portfolio through KFC co-location strategies that share last-mile infrastructure. Papa John's International Inc. differentiates through localized topping menus that accommodate regional flavor preferences.
Saudi Arabia pizza restaurants comprise commercial foodservice establishments preparing and retailing yeast-leavened flatbread topped with tomato sauce, cheese, and variable ingredients, typically baked in deck ovens at 260-290°C for 8-12 minutes. These operations serve immediate consumption demand across dine-in, takeaway, and delivery channels. Traditional product lines occupy the highest volume tier due to price accessibility for mass-market families, while gourmet segments command margin concentration in Riyadh and Jeddah premium zones. Delivery service types are capturing the fastest trajectory as mobile-first ordering platforms integrate with restaurant POS systems. Mid-range price tiers dominate transaction frequency, though luxury positioning is emerging in entertainment district clusters.
SFDA food safety standards govern ingredient sourcing, cold chain maintenance, and labeling requirements across all pizza restaurant operations in the Kingdom. Municipal licensing authorities in Riyadh, Jeddah, and Dammam enforce health inspection protocols and commercial zoning compliance. The General Authority for Competition monitors franchise agreement terms and supplier exclusivity arrangements. Stakeholders must track evolving localization mandates under the National Food Security Strategy and assess kitchen automation investments against labor quota regulations.
Market Dynamics
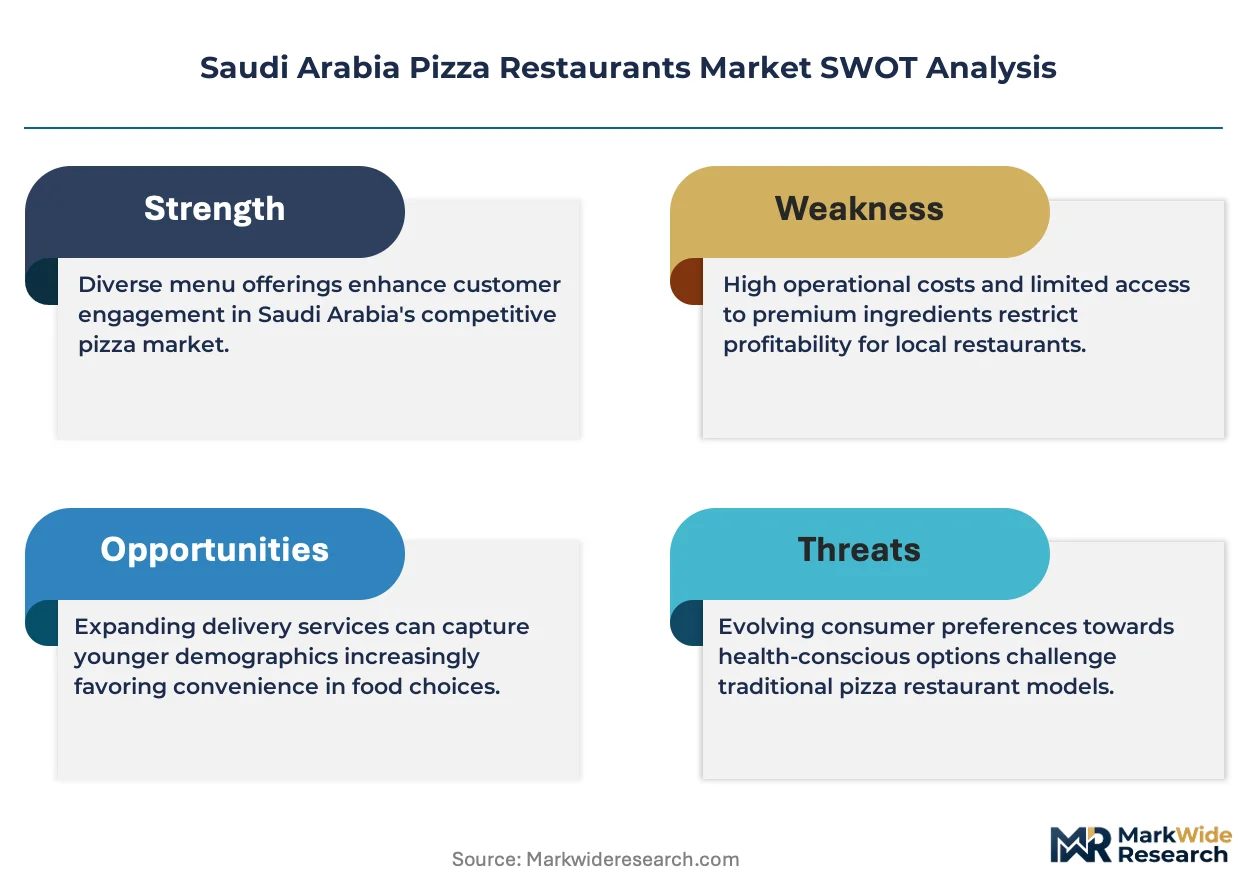
Mobile-first ordering platforms are compressing delivery windows across Riyadh and Jeddah while SFDA cold chain mandates force kitchen-level infrastructure upgrades. This dual pressure is restructuring operational cost profiles and franchise capital deployment priorities.
Growth Catalysts
- SFDA Food Safety Modernization:Updated cold chain protocols mandate real-time temperature monitoring from supplier to oven, driving equipment upgrades that reduce spoilage and extend delivery radius economics.
- Neom and Qiddiya Entertainment Clusters:Mega-project hospitality corridors concentrate high-frequency dining demand in purpose-built zones with captive foot traffic and integrated last-mile logistics.
- Cloud Kitchen Proliferation:Delivery-only operations eliminate front-of-house capital requirements while enabling rapid geographic expansion into secondary Saudi cities without traditional retail footprint.
Market Restraints
- Flour and Cheese Input Volatility:Global wheat futures and dairy commodity swings compress margin predictability for operators locked into fixed-price franchise agreements.
- Riyadh Supply Hub Concentration:Centralized distribution networks create single-point vulnerability for nationwide delivery coverage during logistics disruptions or extreme heat events.
- Home Meal Kit Substitution:Retail pizza dough and sauce combinations positioned at supermarket price points capture budget-conscious family occasions.
Strategic Opportunities
- Tabuk and Hail Underpenetration:Secondary northern cities lack premium pizza density despite rising disposable income and limited independent competitor presence.
- Vision 2030 Localization Mandates:Government procurement preferences and workforce nationalization incentives reward operators achieving Saudi-owned supply chain tiers.
- AI-Driven Dynamic Pricing:Machine learning platforms integrating traffic patterns, weather data, and event calendars enable real-time menu pricing that captures demand spikes.
Industry Challenges
- Certified Kitchen Technician Scarcity:SFDA-mandated food handler credentials face training pipeline gaps, extending onboarding timelines for new outlet launches.
- Legacy POS Integration Friction:Third-party delivery platform APIs conflict with franchise-mandated point-of-sale systems, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pizza Restaurants Market |
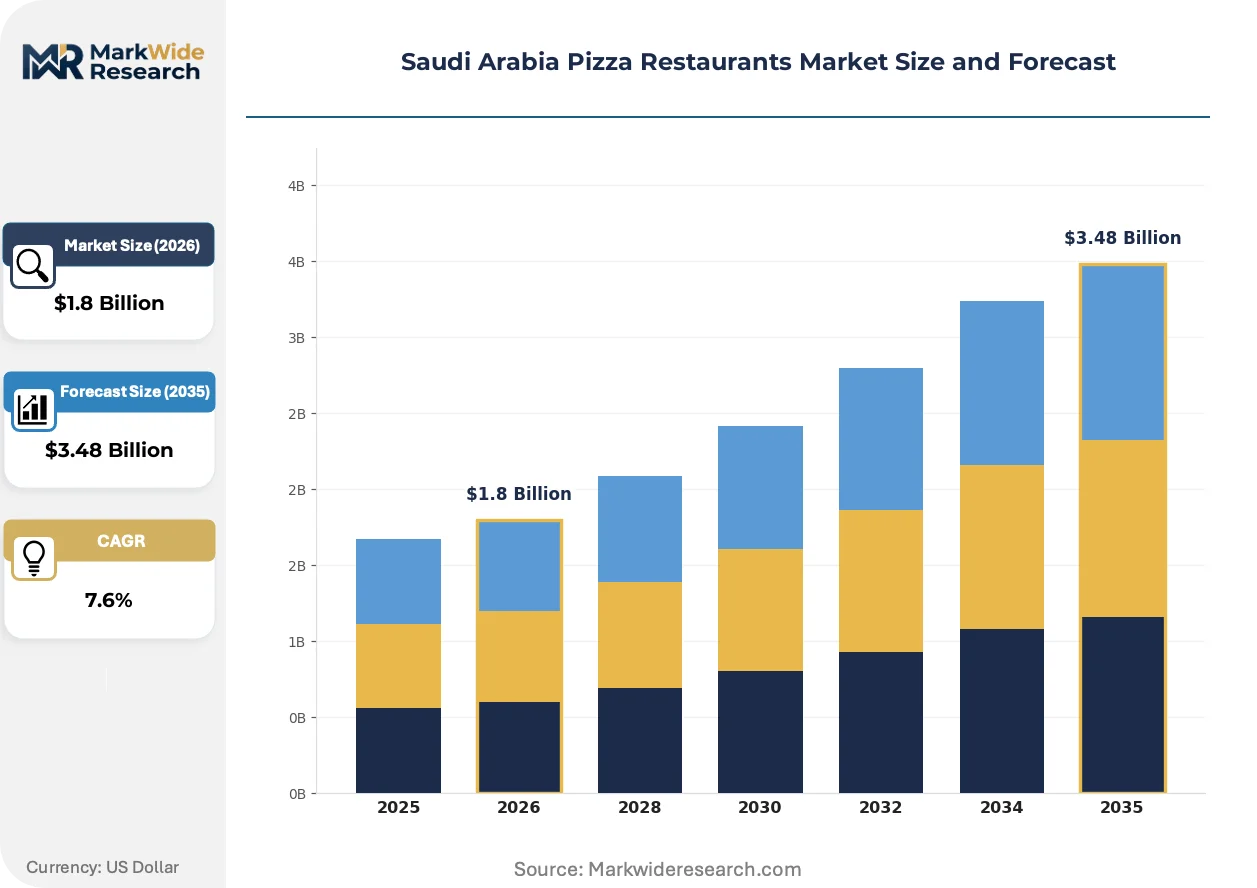
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Gourmet, Frozen, Gluten-Free Service Type: Dine-In, Takeaway, Delivery, Catering Customer Type: Families, Young Adults, Office Workers, Tourists Price Tier: Economical, Mid-Range, Premium, Luxury |
| Companies Covered | Papa John's International Inc., Rave Restaurant Group, Domino's Pizza Inc., Majestas, Sbarro LLC, Yum! Brands Inc., Little Caesar Enterprises Inc., Russo's New York Pizzeria, Daily Food Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pizza Restaurants Market Evolving Landscape
Operational digitization and regulatory precision are converging to redefine kitchen economics and customer interface standards across the Kingdom's pizza segment. Three distinct vectors are compressing legacy operating models.
Smart oven telemetry is converging with predictive maintenance platforms to transform equipment uptime. Deck ovens embedded with IoT sensors transmit thermal performance data to centralized monitoring dashboards. Franchise operators in Riyadh's entertainment district cluster are adopting these systems fastest, reducing unplanned downtime that previously disrupted peak-hour throughput.
SFDA labeling transparency mandates now require ingredient origin disclosure and allergen cross-contamination protocols on all digital menus. This regulatory pressure is forcing supply chain documentation upgrades from farm-level suppliers through to point-of-sale displays. Gourmet-positioned operators in Jeddah's coastal corridor are responding fastest, converting compliance overhead into premium positioning through blockchain-verified provenance claims.
Subscription-based meal plans are displacing transactional ordering among young adult households in Riyadh and Jeddah. Fixed-weekly pizza allocations with loyalty-integrated customization options capture predictable revenue streams. Quick-service operators with centralized production capacity are capturing this shift most aggressively, locking in frequency that insulates against competitor promotional cycles.
Saudi Arabia Pizza Restaurants Market Segmentation
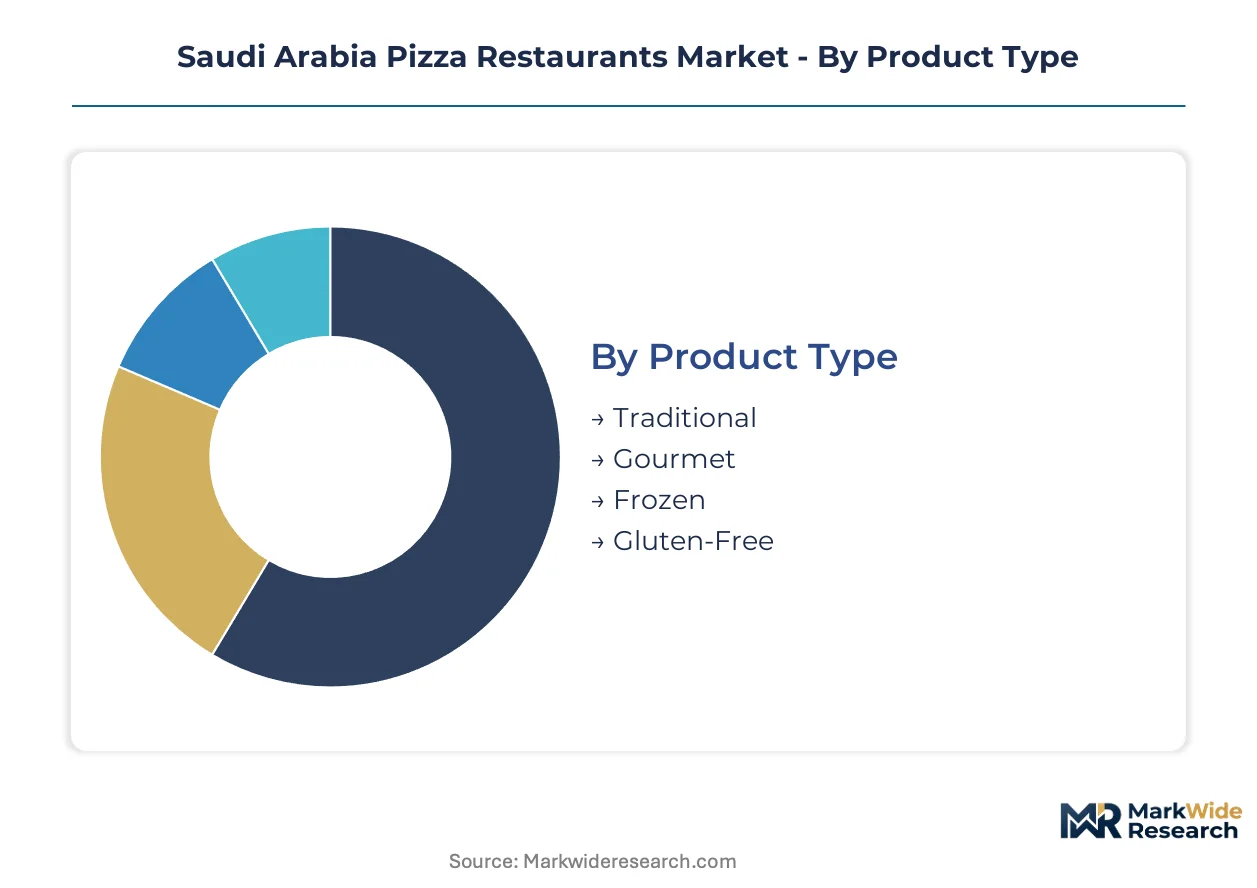
Pizza restaurant operators in Saudi Arabia navigate distinct demand profiles across product formats, service modes, and customer cohorts. Segmentation precision determines kitchen equipment allocation, real estate footprint, and digital platform investment priorities.
Product Type:
Price accessibility drives the mass-market purchase decision across Saudi Arabia's family-dominant pizza consumption patterns.
- Traditional:Yeast-leavened flatbread with tomato sauce and mozzarella, baked in deck ovens at 260-290°C. Volume concentrates in Riyadh's residential districts and Jeddah's working-class corridors where family meal budgets prioritize familiarity over experimentation. SFDA labeling mandates on cheese sourcing and flour fortification add compliance overhead that smaller independents struggle to absorb.
- Gourmet:Artisanal dough fermentation, imported specialty cheeses, and premium protein toppings command margin concentration. Demand clusters in Riyadh's entertainment district cluster and Jeddah's coastal hospitality corridor where young adult consumers prioritize Instagram-worthy presentation and ingredient provenance storytelling.
- Frozen:Pre-assembled pizzas distributed through retail freezer channels for home baking. Supermarket placement in Danube and Carrefour outlets captures budget-conscious family occasions without restaurant markup.
- Gluten-Free:Alternative flour bases using rice, almond, or tapioca formulations. Health-conscious segments in Riyadh's diplomatic quarter and Jeddah's expatriate enclaves sustain niche demand despite 40-60% price premiums over traditional equivalents.
Traditional leads on scale; gourmet leads on momentum.
Service Type:
Channel selection determines capital intensity and labor deployment models across the Kingdom's urban centers.
- Delivery:Mobile-first ordering platforms integrate with restaurant POS systems to compress fulfillment windows. Riyadh and Jeddah's young adult households drive frequency through aggregator apps like HungerStation and Jahez, with cloud kitchen proliferation eliminating front-of-house costs.
- Dine-In:Full-service seating with table turnover management and ambient experience design. Entertainment district clusters in Riyadh and Jeddah's coastal hospitality corridor sustain premium positioning through location-integrated dining occasions.
- Takeaway:Counter-service pickup optimized for speed and order accuracy. Office worker demand in Riyadh's central business district and Jeddah's industrial zones favors this channel for lunch-hour efficiency.
- Catering:Bulk order fulfillment for corporate events, school functions, and hospitality venues. Vision 2030 entertainment mega-projects at Qiddiya and Neom generate institutional contract opportunities with volume guarantees.
Delivery climbs the fastest; dine-in retains margin concentration.
Customer Type:
Demographic targeting shapes menu localization and promotional calendar timing across Saudi Arabia's urban markets.
- Families:Multi-generational meal occasions with value-oriented combo pricing and child-friendly topping options. Riyadh's suburban residential zones generate highest transaction frequency during Thursday-Friday weekend clusters.
- Young Adults:Digitally native consumers aged 18-34 driving dine-out frequency through social discovery and loyalty app engagement. Jeddah's university districts and Riyadh's boulevard entertainment zones concentrate this cohort.
- Office Workers:Time-constrained lunch demand favoring takeaway and delivery with corporate account pricing. Riyadh's King Abdullah Financial District and Jeddah's port authority corridor sustain weekday volume.
- Tourists:Transient demand from religious pilgrimage and leisure travel segments. Makkah and Madinah corridor proximity drives seasonal spikes, while Jeddah's cruise terminal expansion diversifies source markets.
Families dominate transaction volume; young adults drive digital adoption velocity.
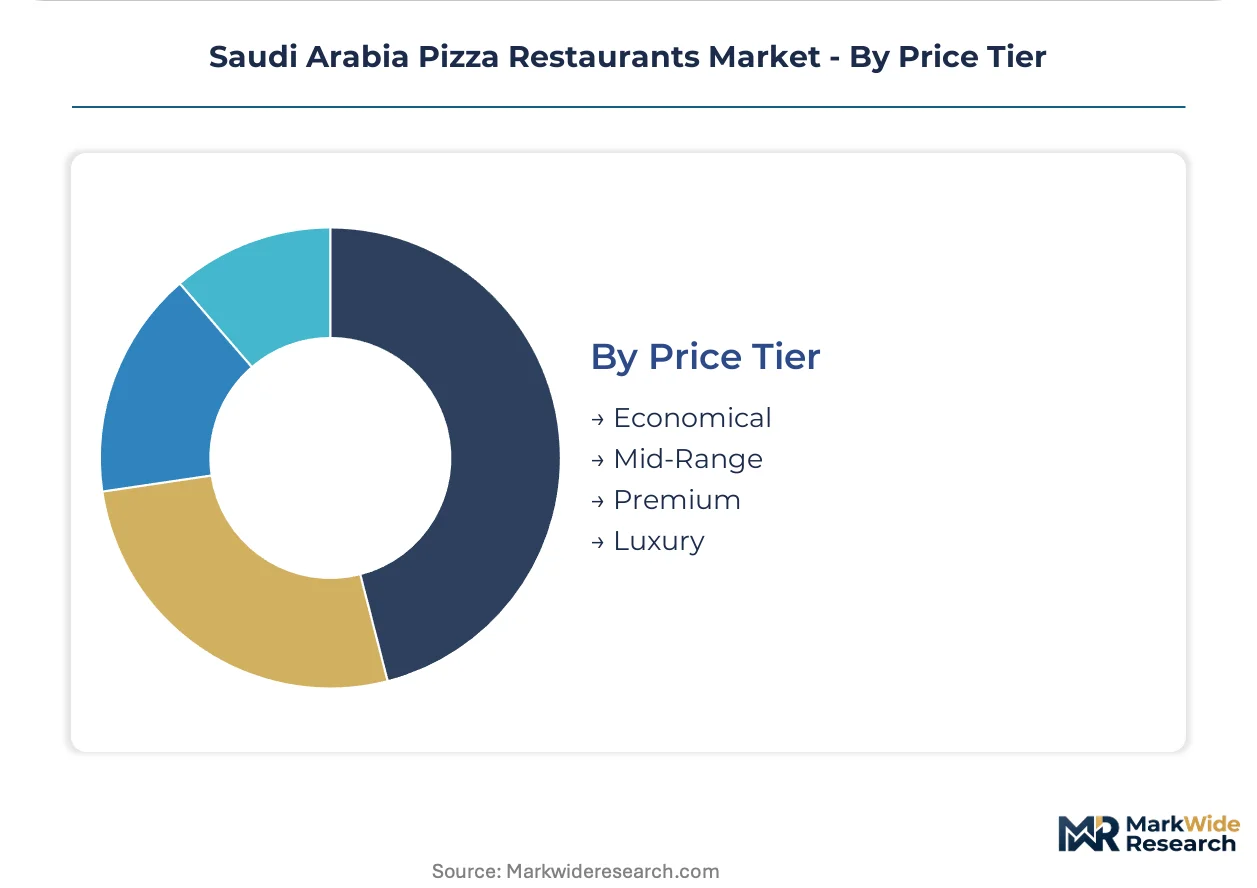
Price Tier:
Positioning strategy determines ingredient sourcing tiers and real estate selection across the Kingdom's income-stratified markets.
- Mid-Range:Balanced quality-price positioning with localized topping menus and consistent portion standards. This tier captures highest transaction frequency across Riyadh and Jeddah's middle-income neighborhoods.
- Economical:Value-engineered offerings with reduced cheese coverage and simplified topping combinations. Budget-conscious family occasions in secondary cities like Dammam and Khobar sustain this tier's relevance.
- Premium:Upscale ingredients and service standards with 25-40% price elevation over mid-range equivalents. Jeddah's coastal hospitality corridor and Riyadh's diplomatic quarter concentrate demand.
- Luxury:Ultra-premium positioning with imported specialty ingredients, chef-attended preparation, and venue-integrated experiences. Entertainment district clusters at Riyadh's Boulevard World and Jeddah's waterfront developments host limited outlets.
Mid-range leads on transaction frequency; luxury gains share fastest in entertainment zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around SFDA compliance costs is concentrating investment in Riyadh's centralized infrastructure, while secondary cities exploit lower municipal licensing overhead to attract cloud kitchen operators seeking margin preservation.
Riyadh
Entertainment district clusters at Boulevard World and Diriyah Gate generate captive dine-out demand from young adult consumers. SFDA food safety modernization mandates real-time temperature monitoring systems that favor capital-rich operators with centralized supply hubs. The King Abdullah Financial District anchors corporate catering contracts and premium delivery radius economics.
Jeddah
Coastal hospitality corridors along the Corniche concentrate gourmet-positioned outlets targeting Instagram-driven discovery. Municipal health inspection protocols in Jeddah enforce stricter cold chain documentation than secondary cities, raising compliance barriers for independents. The cruise terminal expansion diversifies tourist demand beyond religious pilgrimage seasons.
Eastern Province
Dammam and Khobar sustain mid-range transaction frequency through petrochemical sector employment clusters. Labor quota regulations under Saudization policies constrain kitchen technician availability, extending onboarding timelines for new outlet launches. The Dammam industrial zone generates office worker lunch demand favoring takeaway-optimized formats.
Tabuk
Rising disposable income in this northern secondary city lacks matching premium pizza density, creating whitespace for delivery-first entrants. Lower commercial zoning compliance costs relative to Riyadh attract cloud kitchen operators testing geographic expansion. Limited independent competitor presence reduces customer acquisition friction for branded chains.
NEOM Northwest
The Qiddiya entertainment mega-project concentrates institutional catering demand with volume guarantees for early-mover operators. Vision 2030 localization mandates reward Saudi-owned supply chain tiers, privileging operators with domestic ingredient sourcing relationships. Purpose-built logistics infrastructure reduces last-mile delivery costs versus retrofitting legacy urban networks.
Saudi Arabia Pizza Restaurants Market Competitive Landscape
Capacity expansion dominates the current landscape as operators race to secure entertainment district real estate ahead of Qiddiya and Neom hospitality corridor openings. The market structures around a tiered competitive field with global franchisors, regional multi-brand operators, and delivery-native cloud kitchens occupying distinct capital intensity bands. Strategic archetypes separate centralized supply hub operators from localized menu adapters and subscription revenue innovators. Geographic expansion into secondary cities and AI-driven dynamic pricing integration represent the two dominant competitive moves reshaping franchise capital deployment.
Among global franchisors, Domino's Pizza Inc., Yum! Brands Inc., and Papa John's International Inc. anchor the premium-tier positioning through scale advantages in supply chain infrastructure and last-mile logistics integration. These operators exemplify the centralized hub archetype that Riyadh's regulatory environment increasingly favors, while their localized menu adaptation capabilities accommodate regional flavor preferences without sacrificing operational standardization.
| Leading Market Players |
|---|
| Papa John's International Inc. |
| Rave Restaurant Group |
| Domino's Pizza Inc. |
| Majestas |
| Sbarro LLC |
| Yum! Brands Inc. |
| Little Caesar Enterprises Inc. |
| Russo's New York Pizzeria |
| Daily Food Co. |
| Others |
Value Network & Pricing Analysis
Wheat futures volatility and mozzarella commodity benchmarks cascade through Saudi Arabia's pizza value chain, compressing margins at the economical tier while premium operators absorb input swings through ingredient substitution flexibility. This cost pressure stratifies pricing power across the market, with centralized supply hub operators leveraging volume leverage against fragmented independents.
Pricing Analysis
Franchise royalty layers and aggregator commission structures dominate margin allocation across Saudi Arabia's pizza channels. Three-tier pricing structure across premium, standard, and economy levels segments buyers by occasion type and location density. Cost compression in the economy tier intensifies because home meal kit substitution captures budget-conscious family demand. Families exhibit highest price sensitivity, while young adult consumers in entertainment districts show lowest elasticity for Instagram-positioned gourmet offerings.
Supply Chain Analysis
Kitchen technician scarcity across Riyadh, Jeddah, and Dammam constrains outlet expansion velocity and extends equipment installation timelines. Saudi Arabia's pizza supply chain draws from Italian and Turkish flour mills, New Zealand and European dairy suppliers, and regional tomato paste processors. Single-source vulnerability concentrates in the Riyadh distribution hub, where extreme heat events disrupt nationwide cold chain integrity. Distribution runs through franchise-mandated supply hubs to company-owned outlets and licensed operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's pizza restaurants market compounds steadily through Vision 2030 entertainment infrastructure buildout, which generates captive dining demand in purpose-built hospitality corridors.
For Market Incumbents: Acquire cloud kitchen real estate in Tabuk and Hail before municipal zoning restrictions tighten. Consolidate position by securing exclusive supplier agreements with Saudi-owned dairy processors to meet localization mandates. Defend against delivery-native entrants by integrating AI-driven dynamic pricing platforms that capture demand spikes during event calendars. For New Entrants and Emerging Players: Enter via delivery-only formats in secondary northern cities where premium pizza density lags disposable income growth. Target Tabuk's rising middle-income households with mid-range subscription meal plans that lock in weekly frequency. Leverage lower commercial licensing costs versus Riyadh to test localized topping menus before scaling. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud kitchen operators possessing integrated last-mile logistics and Saudization-compliant workforce structures. Five-to-ten-year viability favors entities with domestic supply chain tiers under National Food Security Strategy procurement preferences. Watch SFDA enforcement intensity around cold chain documentation as the signal for compliance-cost barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Expansion | Eliminates front-of-house capital requirements while enabling rapid geographic penetration into secondary Saudi cities. |
| AI-Driven Dynamic Pricing | Integrates traffic patterns, weather data, and Qiddiya event calendars to capture real-time demand spikes. |
| Localization Compliance Investment | Secures government procurement preferences under Vision 2035 workforce nationalization incentives. |
| Subscription Meal Plan Launch | Locks in predictable revenue streams from young adult households insulated from competitor promotional cycles. |
| Smart Oven Telemetry Integration | Reduces unplanned downtime in Riyadh entertainment district clusters through IoT-enabled predictive maintenance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered franchise operations directors, SFDA compliance officers, municipal licensing authorities in Riyadh and Jeddah, third-party delivery platform executives, and supply chain managers at centralized distribution hubs. Secondary validation drew from SFDA regulatory filings, municipal health inspection records, Vision 2030 policy documents, and aggregator app market data. Bottom-up outlet counting and top-down consumption estimation triangulated market sizing.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions modeled include product type, service mode, customer cohort, price tier, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for entertainment corridor development timelines and cloud kitchen penetration curves. Forecast inputs incorporated SFDA modernization enforcement schedules and wheat futures volatility assumptions.
The model holds under stable regulatory enforcement and commodity price bands; deviation in SFDA mandate acceleration or extreme heat event frequency would shift expansion economics. Forecasts reflect documented assumptions about localization compliance timelines and aggregator commission structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Japan Foodservice Market
Food Service
Foodservice Coffee Market
Food Service
Lunch Takeout Market
Food Service
Online Catering Market
Food Service
US Food Trucks Services Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Wok Market
Food Service
Online Food Delivery Market
Food Service
Global Waffle Maker Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Switzerland Food Service Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Europe Online Grocery Market
Food Service
Food Delivery Services Market
Food Service
Global Food Retail Market
Food Service
Egypt Food Service Market