
 Latin America Inflight Catering Market | 2026-2036
Latin America Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Inflight Catering Market Foresight
The EU Green Deal's extraterritorial sustainability reporting requirements for airline supply chains is restructuring procurement priorities for Latin American carriers serving European routes. Gate Gourmet leverages its centralized procurement networks to source certified sustainable proteins across multiple South American airports. LSG Sky Chefs anchors its regional competitiveness through temperature-controlled logistics infrastructure at key Brazilian and Colombian hubs. Newrest Group differentiates via specialized meal programs tailored to long-haul Latin American carrier profiles.
Latin America inflight catering encompasses the preparation, assembly, and delivery of meals, snacks, and beverages to commercial aircraft, with operations governed by HACCP protocols and strict cold-chain maintenance between 1°C and 5°C for perishable components. The primary purpose centers on passenger satisfaction and ancillary revenue generation for airlines while meeting aviation safety standards for galley-loaded consumables. Meals and beverages command the dominant share of service type revenue given their centrality to premium cabin positioning, while the vegan and halal food type segments are expanding fastest as carriers respond to diversifying passenger demographics on transatlantic and Middle Eastern routes. Economy class and business class together absorb the bulk of customer type volume, though charter flight catering is gaining structural importance as private aviation grows across Brazil and Mexico.
ANAC in Brazil, DGAC in Mexico, and Colombia's Aerocivil enforce divergent food safety certification requirements that create compliance complexity for multi-country operators. REACH-aligned chemical standards for food contact materials and EU MDR-equivalent traceability expectations are elevating documentation burdens for caterers supplying international flag carriers. Stakeholders must monitor regulatory harmonization pressures between Mercosur aviation authorities and European safety benchmarks to anticipate certification cost trajectories.
Market Dynamics
Full-service carriers across Latin America are upgrading cabin experiences to capture premium passenger segments, forcing caterers to retool production lines for multi-course meal programs while maintaining HACCP compliance across dispersed airport facilities.
Growth Catalysts
- ANAC Nutritional Mandates:Brazil's ANAC labeling requirements for airline food are standardizing ingredient disclosure practices, pushing caterers toward transparent supply chains that attract health-conscious travelers.
- Temperature-Controlled Logistics:Cold-chain infrastructure investments between 1°C and 5°C for perishable components are expanding operational reach to secondary airports across Colombia and Chile.
- Private Aviation Expansion:Charter flight demand is accelerating across Brazil and Mexico, creating specialized catering requirements for executive terminals outside traditional hub structures.
Market Restraints
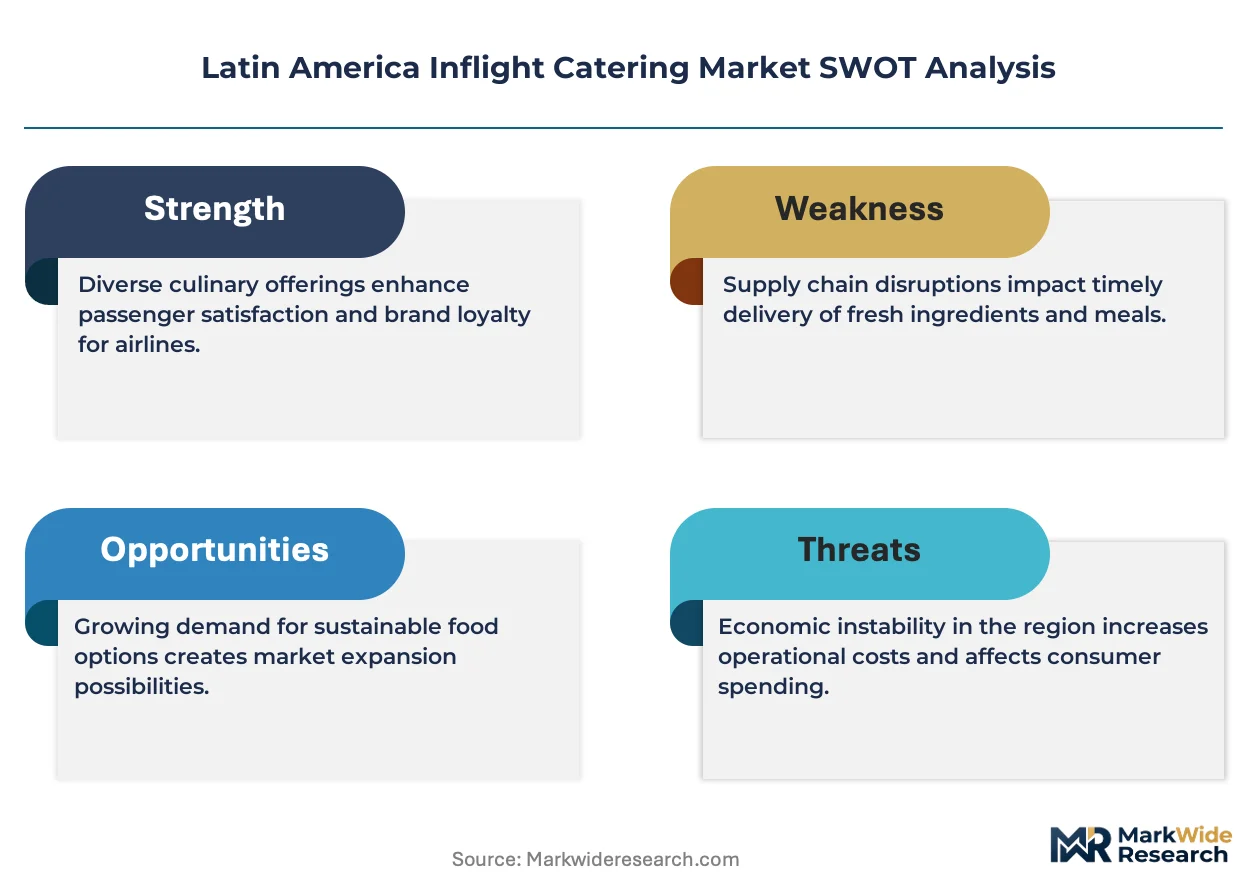
- Input Cost Volatility:Sustainable protein certification costs are compressing margins for caterers supplying European routes under EU Green Deal extraterritorial requirements.
- Supply Concentration Risk:São Paulo-Guarulhos and Rio de Janeiro-Galeão dominate hub catering clusters, creating geographic vulnerability for operators dependent on southeast Brazil infrastructure.
- Regulatory Fragmentation:Divergent food safety certification requirements between ANAC, DGAC, and Aerocivil multiply compliance costs for multi-country operators.
Strategic Opportunities
- Secondary Airport Penetration:Colombian and Chilean regional hubs remain underserved by premium meal programs, offering first-mover positioning for specialized caterers.
- REACH-Aligned Material Upgrades:Chemical standards for food contact materials are creating procurement differentiation opportunities for caterers ahead of Mercosur-European harmonization.
- Vegan and Halal Segments:Diversifying passenger demographics on transatlantic and Middle Eastern routes are expanding fastest-growing food type categories with limited incumbent specialization.
Industry Challenges
- Certification Timeline Compression:EU MDR-equivalent traceability expectations are elevating documentation burdens faster than legacy quality management systems can adapt.
- Cold-Chain Capex Requirements:Galley-loaded consumable standards demand continuous refrigeration infrastructure investment at airports with unreliable power grids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Inflight Catering Market |
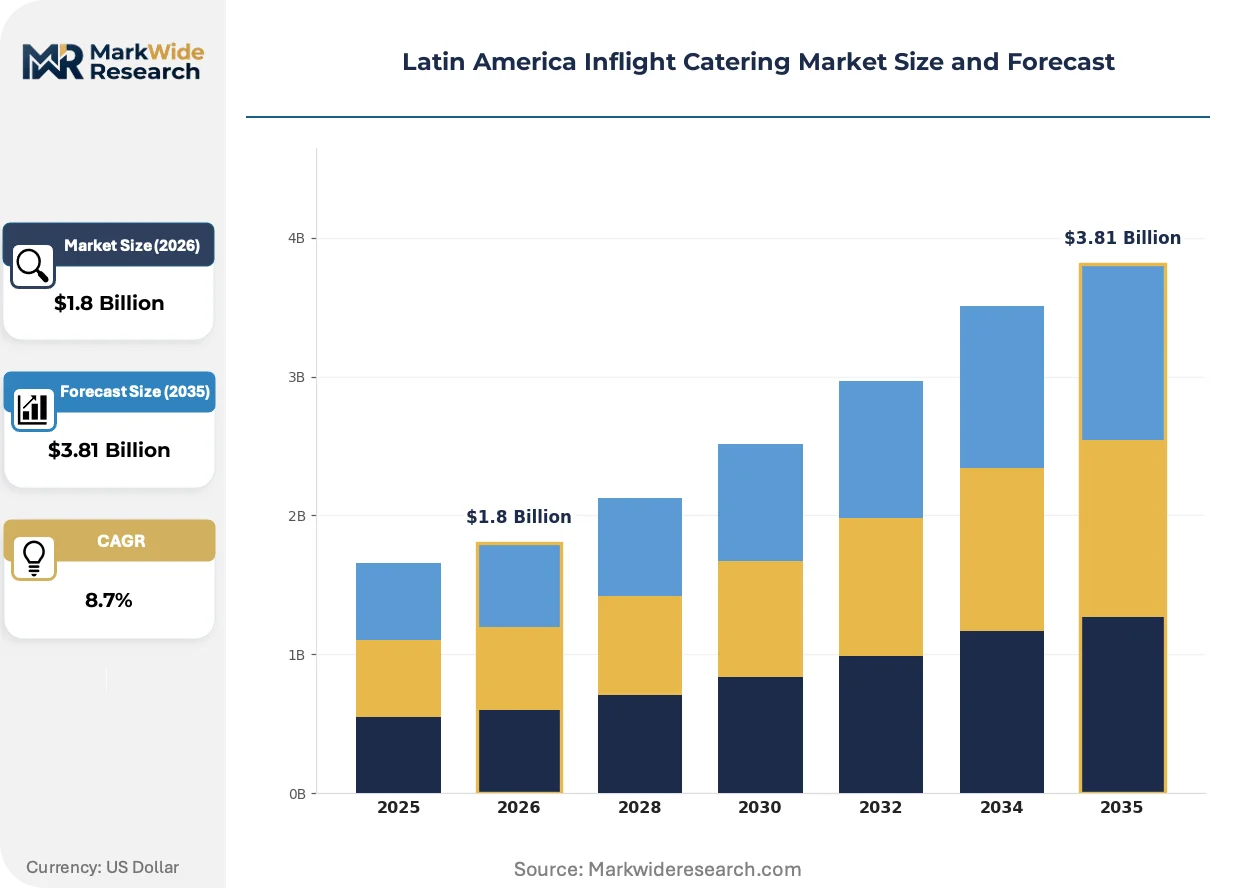
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meals, Snacks, Beverages, Treats Food Type: Vegetarian, Non-Vegetarian, Vegan, Halal Distribution Channel: Airlines, Third-Party Providers, Catering Companies, In-House Services Customer Type: Economy Class, Business Class, First Class, Charter Flights |
| Companies Covered | Air Culinaire Worldwide LLC, Gate Gourmet, LSG Sky Chefs, Dnata, Flying Food Groups, Gategroup, Newrest Group, Emirates Flight Catering, GCG Catering, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Inflight Catering Market Shifts & Advancements
Digital traceability systems and sustainable packaging materials are actively reshaping how Latin American caterers document provenance and reduce environmental liability across international supply chains.
Blockchain-enabled ingredient tracking is converging with automated temperature logging to create immutable cold-chain records. Full-service carriers adopting these systems are compressing audit preparation timelines from weeks to hours. The structural consequence is converging with procurement requirements from European flag carriers, forcing regional caterers to upgrade IT infrastructure or lose route contracts.
EU Green Deal supply chain disclosure mandates are restructuring procurement priorities for caterers serving transatlantic routes. Carriers must now document carbon intensity across protein sourcing, packaging, and logistics tiers. Brazilian and Colombian operators supplying European destinations are most affected, responding by centralizing supplier certification through third-party sustainability auditors.
Passenger preference data is driving unbundled meal pre-ordering systems that displace traditional load-factor estimation. Business class travelers increasingly select specific dietary options 48 hours pre-departure, compressing production planning windows. This pattern is most visible on Brazil-Europe and Mexico-United States routes where premium cabin load factors support predictive kitchen scheduling.
Latin America Inflight Catering Market Segmentation
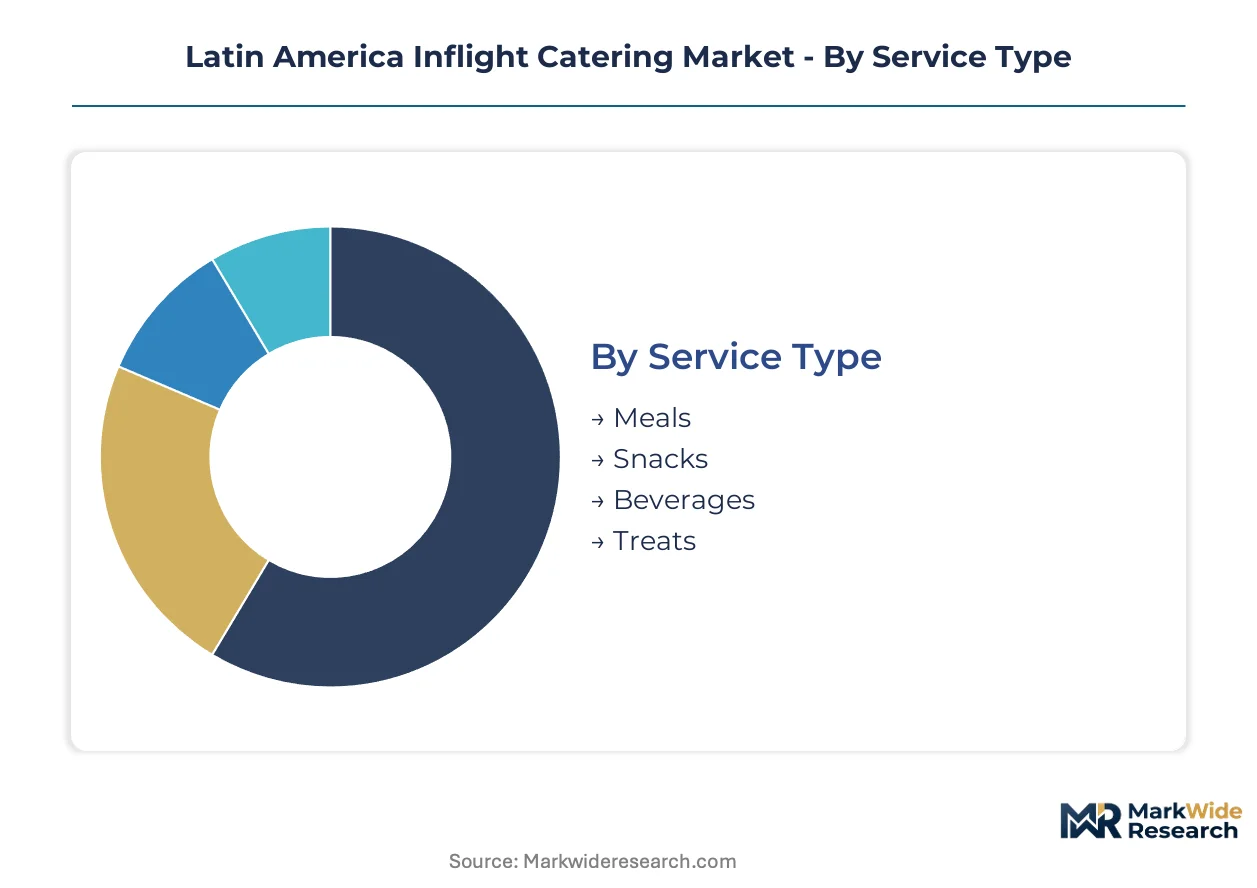
Latin American carriers are segmenting catering portfolios to match cabin upgrade investments with passenger willingness-to-pay curves. Each segmentation dimension reveals distinct procurement patterns and margin structures that caterers must align against to secure multi-year airline contracts.
Service Type:
Carriers are replacing legacy meal programs with modular service tiers that align with fleet modernization cycles and galley retrofit timelines.
- Meals:Multi-course offerings dominate premium cabin positioning on Brazil-Europe and Mexico-United States routes. São Paulo-Guarulhos and Rio de Janeiro-Galeão clusters concentrate production for full-service carriers upgrading business class dining experiences under ANAC nutritional disclosure mandates.
- Beverages:Wine and spirits selection now functions as a competitive differentiator for LATAM and Aeromexico long-haul fleets. Cold-chain requirements between 1°C and 5°C for chilled wines are driving temperature-controlled infrastructure investment at Colombian and Chilean secondary airports.
- Snacks:Pre-packaged options serve regional routes and economy cabins where cost-per-passenger constraints dominate procurement.
- Treats:Dessert and specialty items support premium positioning on charter flights across Brazilian executive aviation terminals.
Meals sit at the top of the volume ranking, with beverages climbing the fastest as carriers expand wine cellar investments for transatlantic competitive positioning.
Food Type:
Procurement teams are diversifying supplier bases to capture dietary preference premiums while managing certification complexity across ANAC, DGAC, and Aerocivil jurisdictions.
- Non-Vegetarian:Conventional protein menus retain dominance on domestic Brazilian and Mexican routes where passenger demographics skew toward traditional preferences. Cold-chain protocols for raw meat handling create operational barriers for secondary airport penetration.
- Vegan:Plant-based meal programs are expanding most quickly on transatlantic routes serving European destinations under EU Green Deal supply chain disclosure requirements. Gate Gourmet and LSG Sky Chefs are certifying sustainable protein suppliers across multiple South American hubs to capture this demand.
- Vegetarian:Lacto-ovo options serve intermediate demand segments on Caribbean and Central American leisure routes.
- Halal:Religious certification requirements are creating specialized procurement needs for Middle Eastern carrier codeshares and Muslim passenger segments on Brazil-Gulf routes.
Non-Vegetarian commands the highest absolute volume, while vegan offerings are gaining share fastest as sustainability-linked procurement criteria harden.
Distribution Channel:
Airlines are restructuring catering procurement to balance unit economics against supply chain resilience, with channel selection reflecting fleet scale and route network complexity.
- Airlines:In-house catering operations concentrate at São Paulo-Guarulhos and Rio de Janeiro-Galeão for LATAM and Gol, capturing scale efficiencies on high-frequency domestic trunk routes. ANAC food safety certification investments create fixed cost barriers that favor volume concentration.
- Third-Party Providers:Specialized operators like Gate Gourmet leverage centralized procurement networks across Brazilian, Colombian, and Mexican airports to serve carriers without captive catering infrastructure.
- Catering Companies:Independent regional specialists target charter flight demand at executive terminals outside traditional hub structures.
- In-House Services:Low-cost carriers with standardized meal programs maintain direct supplier relationships to compress procurement margins.
Airlines retain the largest volume share, with third-party providers expanding most quickly as mid-size carriers abandon captive catering investments.
Customer Type:
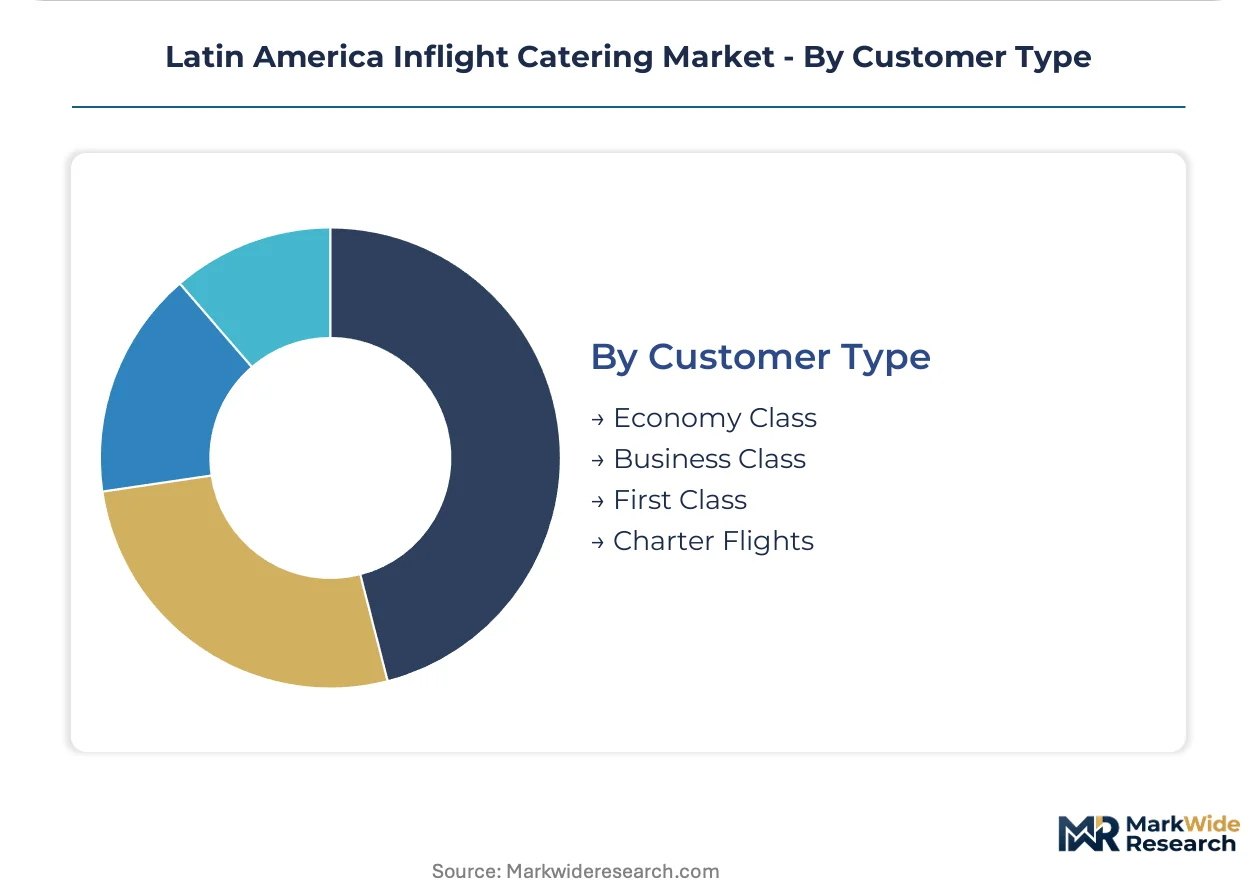
Cabin class segmentation directly determines production complexity, with business and first class requiring multi-course capabilities that economy and charter segments do not.
- Business Class:Full-service carriers are upgrading lie-flat seat dining experiences on Brazil-Europe routes, forcing caterers to retool production lines for multi-course meal programs while maintaining HACCP compliance. Pre-order systems compressing 48-hour production windows are most visible in this segment.
- Economy Class:Standardized tray setups dominate volume across LATAM, Aeromexico, and Avianca narrow-body fleets, with cost-per-passenger targets limiting menu innovation.
- First Class:Ultra-premium personalization requirements serve limited routes on flagship aircraft, with chef-curated programs creating margin concentration for specialized caterers.
- Charter Flights:Private aviation expansion across Brazil and Mexico is generating specialized demand at executive terminals, with Newrest Group and regional specialists tailoring meal programs to long-haul Latin American carrier profiles.
Economy class sits at the top of the volume ranking, with charter flights climbing the fastest as private aviation infrastructure expands beyond traditional hub geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Culinary workforce clusters in São Paulo and Rio de Janeiro anchor Latin America's inflight catering infrastructure, with specialized cold-chain technicians and HACCP-certified kitchen staff concentrated around Brazil's primary aviation hubs.
Brazil
ANAC nutritional labeling mandates are standardizing ingredient disclosure across full-service carrier networks. The regulator's food safety protocols create fixed-cost barriers that favor high-volume production concentration. São Paulo-Guarulhos and Rio de Janeiro-Galeão host the dominant hub catering clusters where LATAM and Gol maintain captive operations for domestic trunk routes.
Mexico
DGAC certification requirements govern cold-chain maintenance between 1°C and 5°C for perishable galley components. The country's national aviation regulator enforces divergent standards from Brazilian ANAC protocols, multiplying compliance burdens for cross-border operators. Mexico City International Airport concentrates third-party catering infrastructure serving Aeromexico's long-haul fleet upgrades.
Colombia
Aerocivil food safety benchmarks are elevating documentation requirements for caterers supplying Avianca's international codeshares. The national civil aviation authority's traceability expectations lag EU MDR-equivalent standards, creating upgrade pressure for European route operators. Bogotá-El Dorado anchors temperature-controlled logistics investments by LSG Sky Chefs and Gate Gourmet.
Chile
Secondary airport penetration opportunities concentrate in Santiago and regional hubs where premium meal programs remain underserved. The country's aviation regulator aligns partially with Mercosur safety frameworks while maintaining distinct cold-chain inspection protocols. Arturo Merino Benítez International hosts specialized vegan and halal certification facilities for trans-Pacific carrier demand.
Argentina
Economic volatility compresses procurement budgets for Aerolíneas Argentinas catering contracts while sustaining demand at executive aviation terminals. The national civil aviation administration enforces food contact material standards below REACH-aligned thresholds, creating future harmonization costs. Buenos Aires-Ezeiza maintains legacy hub infrastructure with limited temperature-controlled modernization.
Latin America Inflight Catering Market Competitive Landscape
Capital-heavy producers with captive airport kitchens compete with asset-light logistics specialists outsourcing production to certified commissaries. The vendor base organizes around three strategic archetypes: global network operators leveraging centralized procurement, regional specialists targeting charter and private aviation terminals, and carrier-affiliated in-house services capturing scale on high-frequency routes. Consolidation pressures favor M&A activity among mid-tier Brazilian and Mexican operators, while technology licensing partnerships accelerate digital traceability adoption.
Among global network operators, Gate Gourmet and LSG Sky Chefs exemplify the centralized procurement archetype, with Newrest Group occupying a specialized position in long-haul carrier meal programs. These three entities represent contrasting geographic origins and structural approaches to Latin American market coverage, with each anchoring distinct competitive vectors around sustainability certification, temperature-controlled infrastructure, or executive aviation specialization.
| Leading Market Players |
|---|
| Air Culinaire Worldwide LLC |
| Gate Gourmet |
| LSG Sky Chefs |
| Dnata |
| Flying Food Groups |
| Gategroup |
| Newrest Group |
| Emirates Flight Catering |
| GCG Catering |
| Others |
Supply & Pricing Matrix
Sustainable protein certification costs flow from EU Green Deal supply chain auditors through to transatlantic route caterers, compressing margins at the premium tier while economy segments absorb standardized ingredient cost fluctuations. Cold-chain energy expenditures between 1°C and 5°C for perishable components anchor cost structures across Brazilian and Colombian hub operations, with ANAC nutritional disclosure mandates adding fixed compliance layers that favor volume concentration.
Pricing Analysis
The bundled-vs-unbundled service split separates full-service carrier multi-course programs from low-cost carrier pre-packaged offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and galley retrofit investment recovery timelines. Pricing pressure stems from REACH-aligned food contact material upgrades required for European route access. Economy class travelers exhibit highest price sensitivity, while charter flight clients demonstrate lowest elasticity for chef-curated personalization.
Supply Chain Analysis
Logistics costs for temperature-controlled ground transport between production kitchens and aircraft galleys concentrate procurement gravity around São Paulo-Guarulhos and Rio de Janeiro-Galeão clusters. Raw material dependencies span certified sustainable proteins, specialized packaging materials, and HACCP-compliant cleaning agents. Single-source vulnerability runs through southeast Brazil cold-chain infrastructure serving LATAM and Gol captive operations. Distribution runs through hub-and-spoke networks anchored at primary airports with secondary penetration limited by power grid reliability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ANAC nutritional disclosure mandates in Brazil create compliance cost differentials against DGAC-regulated Mexican operations, rewarding multi-country operators with centralized certification management.
For Market Incumbents: Extend temperature-controlled logistics infrastructure to Colombian and Chilean secondary airports before regional competitors consolidate first-mover positions. Gate Gourmet and LSG Sky Chefs should deepen backward integration into sustainable protein sourcing to defend margin position against EU Green Deal certification cost compression. ANAC-DGAC regulatory divergence threatens operational efficiency for cross-border players. For New Entrants and Emerging Players: Launch via executive aviation terminal specialization at underserved Brazilian and Mexican private aviation hubs where incumbent global network operators maintain limited presence. Charter flight catering at facilities outside São Paulo-Guarulhos and Rio de Janeiro-Galeão clusters offers the most penetrable white space. Vegan and halal certification capabilities provide differentiated go-to-market positioning for transatlantic and Middle Eastern route contracts. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Brazilian and Mexican regional specialists because ANAC food safety certification investments create fixed-cost barriers that favor scale concentration over fragmented independent operations. Acquisition targets should demonstrate captive airport kitchen access or specialized dietary certification capabilities. The signal to watch is Mercosur-European regulatory harmonization momentum, which would accelerate consolidation pressure among sub-scale operators lacking documentation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Airport Cold-Chain Expansion | Captures underserved Colombian and Chilean regional hub demand ahead of competitor infrastructure deployment. |
| Sustainable Protein Supplier Certification | Secures EU Green Deal compliance for transatlantic route contracts with European flag carriers. |
| Digital Traceability Platform Deployment | Compresses audit preparation timelines from weeks to hours for blockchain-enabled cold-chain documentation. |
| Executive Aviation Terminal Specialization | Targets private aviation growth across Brazilian and Mexican markets outside traditional hub structures. |
| REACH-Aligned Packaging Material Upgrade | Creates procurement differentiation ahead of Mercosur-European chemical standard harmonization. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Argentina, with primary inputs from each national aviation authority jurisdiction combined with secondary validation. Interviews with catering operations directors, airline procurement managers, cold-chain logistics specialists, and HACCP compliance officers informed demand-side and supply-side perspectives. Secondary sources include ANAC regulatory filings, DGAC certification databases, Aerocivil traceability guidelines, customs records for food contact material imports, and SEC disclosures from listed catering operators. Bottom-up facility capacity modeling and top-down route demand estimation provided triangulation checks.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include service type, food type, distribution channel, customer type, and airport hub tier. CAGRs derived from fitted trend analysis against historical production data and announced fleet expansion schedules. Industry-specific forecast inputs encompass galley retrofit timelines for LATAM and Aeromexico business class upgrades, plus charter flight registration growth in Brazilian executive aviation.
Several conditions sit outside the modeled scope, including abrupt regulatory harmonization between Mercosur and European aviation authorities, sustained energy price volatility affecting cold-chain operations, and pandemic-scale demand disruptions. Forecasts reflect assumptions about continued premium cabin investment by full-service carriers and stable ANAC-DGAC-Aerocivil regulatory divergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Malaysia Food Service Market
Food Service
Singapore Food Service Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Tabletop Pizza Oven Market
Food Service
Sandwich Toasters Market
Food Service
Commercial Tableware Services Market
Food Service
Cambodia Foodservice Market
Food Service
Clear Ice Maker Market
Food Service
North America Online Food Delivery Market
Food Service
Belgium HRI Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Benelux Foodservice Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Nigeria Food Service Market
Food Service
United Kingdom Full Service Restaurants Market