
 Qatar Food Service Market | 2026-2036
Qatar Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Food Service Market Insights
Corporate catering is restructuring procurement priorities as Qatar's non-oil workforce expands and foreign firms establish regional headquarters. M.H. Alshaya Co. WLL leverages its multi-brand portfolio to dominate mall-based dining across Doha Festival City and Place Vendôme. Al Jassim Group anchors institutional catering contracts with government and energy sector clients. Americana Restaurants International PLC competes through localized menu adaptation while sustaining operational scale across Gulf Cooperation Council markets.
Qatar Food Service encompasses the preparation, distribution, and sale of meals and beverages through commercial outlets operating under HACCP-aligned temperature controls and halal certification requirements, serving consumers outside permanent residential kitchens. The sector spans dine-in, takeaway, delivery, and online ordering service types, with delivery platforms capturing disproportionate growth as smartphone penetration exceeds regional averages. Ready-to-eat and frozen meals product categories concentrate margin pools through centralized commissary production, while beverage segments face saturation in premium mall locations. Restaurants and cafés end-user channels absorb the majority of capital deployment, though catering services command superior contract visibility from recurring event and institutional volumes.
The Ministry of Public Health enforces food safety standards through licensing inspections and HACCP compliance audits, while Qatar Tourism Authority mandates sustainability benchmarks for hospitality-linked operators. These frameworks elevate capital requirements for new entrants and accelerate consolidation among mid-scale independents. Stakeholders must monitor regulatory alignment between municipal zoning approvals and national tourism masterplans as supply capacity comes online across Lusail and Msheireb districts.
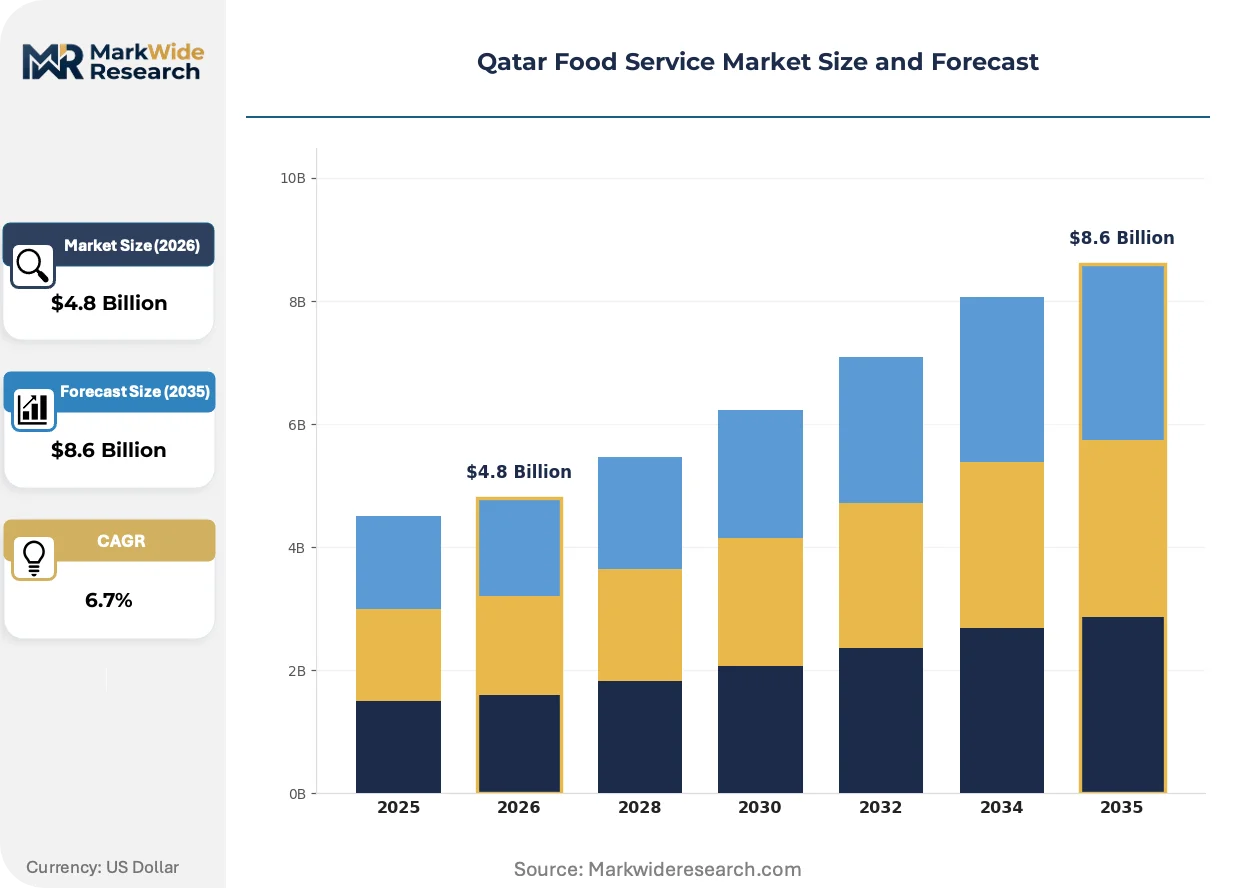
Market Dynamics
Qatar's food service sector is restructuring around cold-chain compliance mandates from the Ministry of Public Health as tourism infrastructure scales and procurement channels consolidate toward institutional and hospitality buyers.
Growth Catalysts
- Halal certification standardization:Unified HACCP-aligned protocols from the Ministry of Public Health reduce supplier onboarding friction for international hotel chains entering Doha and Lusail.
- Delivery platform density:Smartphone penetration above regional averages is compressing order-to-delivery cycles and expanding addressable demand beyond mall-based catchments.
- Energy sector procurement:Government and energy institutional contracts anchor recurring catering volumes with superior payment visibility compared to consumer-facing operations.
Market Restraints
- Perishable input volatility:Fresh produce and protein imports through Hamad Port face seasonal price swings and currency exposure that compress QSR margin structures.
- Commissary concentration:Centralized production capacity clusters in Doha's industrial zone, creating last-mile cost penalties for West Bay and Lusail operators.
- Cold-chain capex floors:Ministry of Public Health temperature-control mandates require refrigeration infrastructure investments that exclude sub-scale entrants.
Strategic Opportunities
- Msheireb district buildout:New commercial and residential clusters in Doha's downtown regeneration zone concentrate daytime food traffic with limited incumbent supply.
- Qatar Tourism Authority sustainability benchmarks:Early compliance with hospitality-linked environmental standards secures preferred supplier status for FIFA-legacy event venues.
- Ghost kitchen convergence:Cloud kitchen infrastructure combined with aggregator platforms enables asset-light market entry without premium mall rents.
Industry Challenges
- Halal certification timelines:Ministry of Public Health audit backlogs delay licensing for new concepts, compressing launch windows ahead of tourism peaks.
- Commissary-to-outlet coordination:Temperature-controlled logistics between centralized production and dispersed service points strain operational consistency across the West Bay-Lusail corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Food Service Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Frozen Meals, Snacks, Beverages End User: Restaurants, Cafés, Catering Services, Food Trucks Service Type: Dine-In, Takeaway, Delivery, Online Ordering Customer Type: Families, Young Adults, Tourists, Corporates |
| Companies Covered | M.H. Alshaya Co. WLL, Al Jassim Group, Al Mana Restaurants & Food Company, Jollibee Foods Corp., Alamar Foods Co., Almuftah Group, Teatime, Sterling Restaurants, Americana Restaurants International PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Food Service Market Trends and Innovations
Digital ordering infrastructure and regulatory compliance technology are displacing traditional front-of-house and manual safety protocols across Qatar's food service value chain.
Kitchen display systems integrated with aggregator APIs are automating order routing and prep sequencing for high-volume QSR operators in Doha Festival City and Place Vendôme. Mall-based chains with above-average delivery mix have deployed these systems to compress ticket times and reduce labor dependency during peak hours. The technology is automating coordination between third-party delivery platforms and internal kitchen workflows, shrinking error rates and refund exposure.
The Ministry of Public Health's HACCP compliance audit digitization mandates real-time temperature logging and automated documentation for cold-chain operators. This regulatory shift forces commissary and outlet operators to adopt IoT sensor networks and cloud-based record retention. Full-service restaurants with institutional contracts face the steepest compliance investment, while independent operators in saturated mall locations struggle to absorb the capital burden.
Corporate catering buyers in West Bay's financial district are consolidating vendor relationships toward multi-service contracts covering breakfast, lunch, and event hospitality. Energy sector and government procurement teams now favor single-source arrangements with guaranteed halal compliance and sustainability documentation over fragmented supplier pools. This concentration pattern is most pronounced among foreign firms establishing regional headquarters with standardized global procurement protocols.
Qatar Food Service Market Segmentation
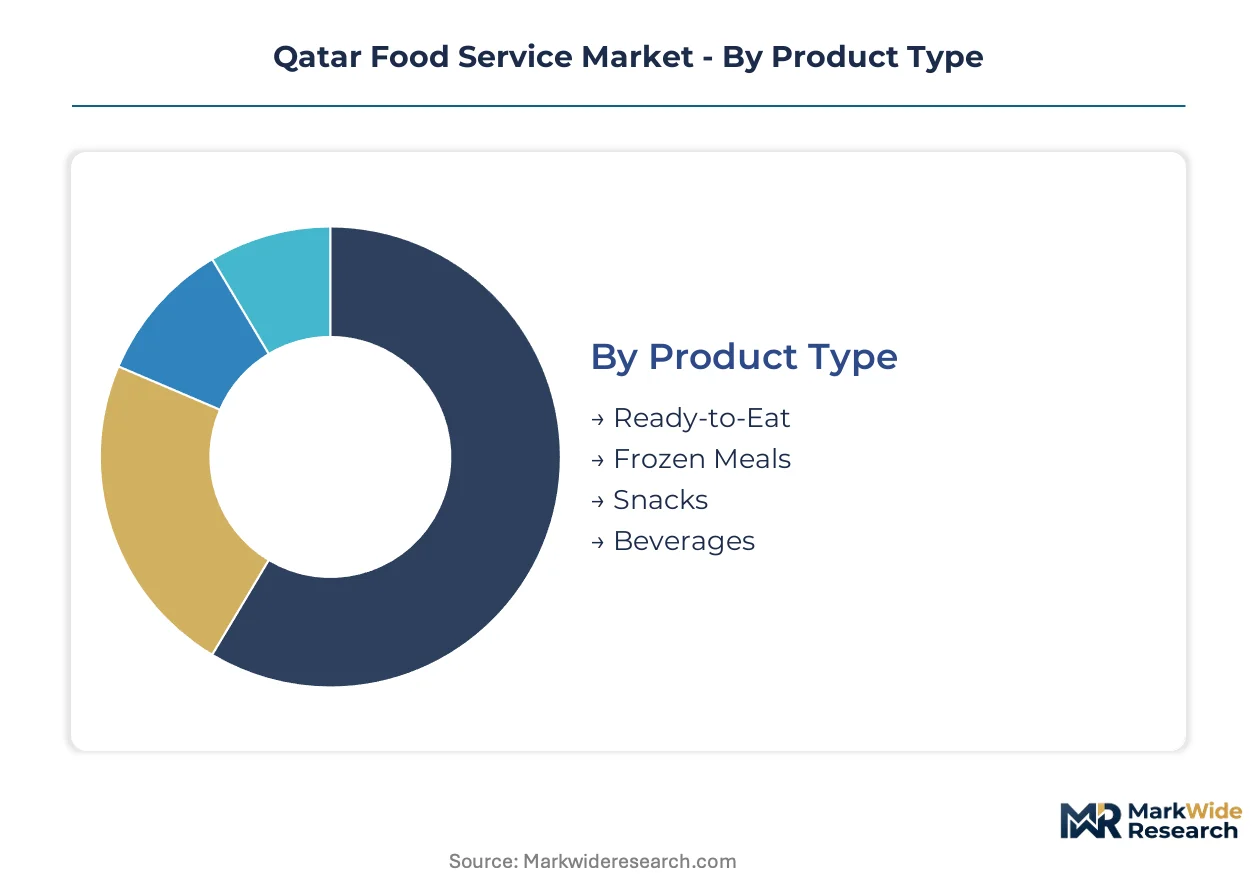
Segmentation reveals where capital deployment concentrates and which channels absorb regulatory compliance costs. Qatar's food service structure shows sharp divergence between asset-heavy production formats and digitally intermediated service models.
Product Type:
Capital intensity varies dramatically across production formats, with centralized commissary operations demanding refrigeration infrastructure that excludes sub-scale entrants.
- Ready-to-Eat:Fresh-prepared meals requiring HACCP-aligned cold-chain from production through retail. Demand clusters in West Bay corporate catering and Lusail hospitality procurement, where institutional buyers mandate batch-traceable sourcing.
- Frozen Meals:Blast-frozen products with extended shelf stability reducing spoilage exposure. Centralized production in Doha's industrial zone supplies retail and foodservice channels, though last-mile frozen logistics to West Bay and Lusail operators incur cost penalties.
- Snacks:Shelf-stable formats with lower refrigeration burden and faster inventory turns.
- Beverages:Premium mall locations face saturation while delivery-optimized formats expand.
Ready-to-Eat absorbs the bulk of installed capacity; Frozen Meals is expanding most quickly.
End User:
Customer concentration patterns determine contract visibility and payment reliability across the sector.
- Restaurants:Full-service and limited-service outlets absorbing majority capital deployment across Doha Festival City and Place Vendôme mall locations. West Bay-Lusail corridor expansion concentrates new supply where daytime and evening traffic volumes justify premium rents.
- Catering Services:Institutional and event contracts with government and energy sector clients anchoring recurring volumes. Ministry of Public Health halal certification requirements and Qatar Tourism Authority sustainability benchmarks elevate qualification barriers for new entrants.
- Cafés:Beverage-forward formats with lower kitchen capital requirements.
- Food Trucks:Mobile operations constrained by municipal zoning and commissary access.
Restaurants command the deepest capital commitment; Catering Services delivers superior contract visibility.
Service Type:
Digital infrastructure requirements separate scalable formats from location-dependent operations.
- Delivery:Platform-mediated ordering capturing disproportionate growth as smartphone penetration exceeds regional averages. Aggregator APIs compress order-to-delivery cycles and expand addressable demand beyond traditional catchments.
- Online Ordering:Direct-to-consumer digital channels reducing aggregator commission exposure for established operators. Kitchen display systems automate prep sequencing for high-volume QSR formats in mall locations.
- Dine-In:Front-of-house labor and real estate intensive formats facing rent pressure in premium locations.
- Takeaway:Counter-service models with lower technology burden but limited expansion potential.
Delivery dominates new customer acquisition; Online Ordering climbs the fastest as operators seek margin recovery.
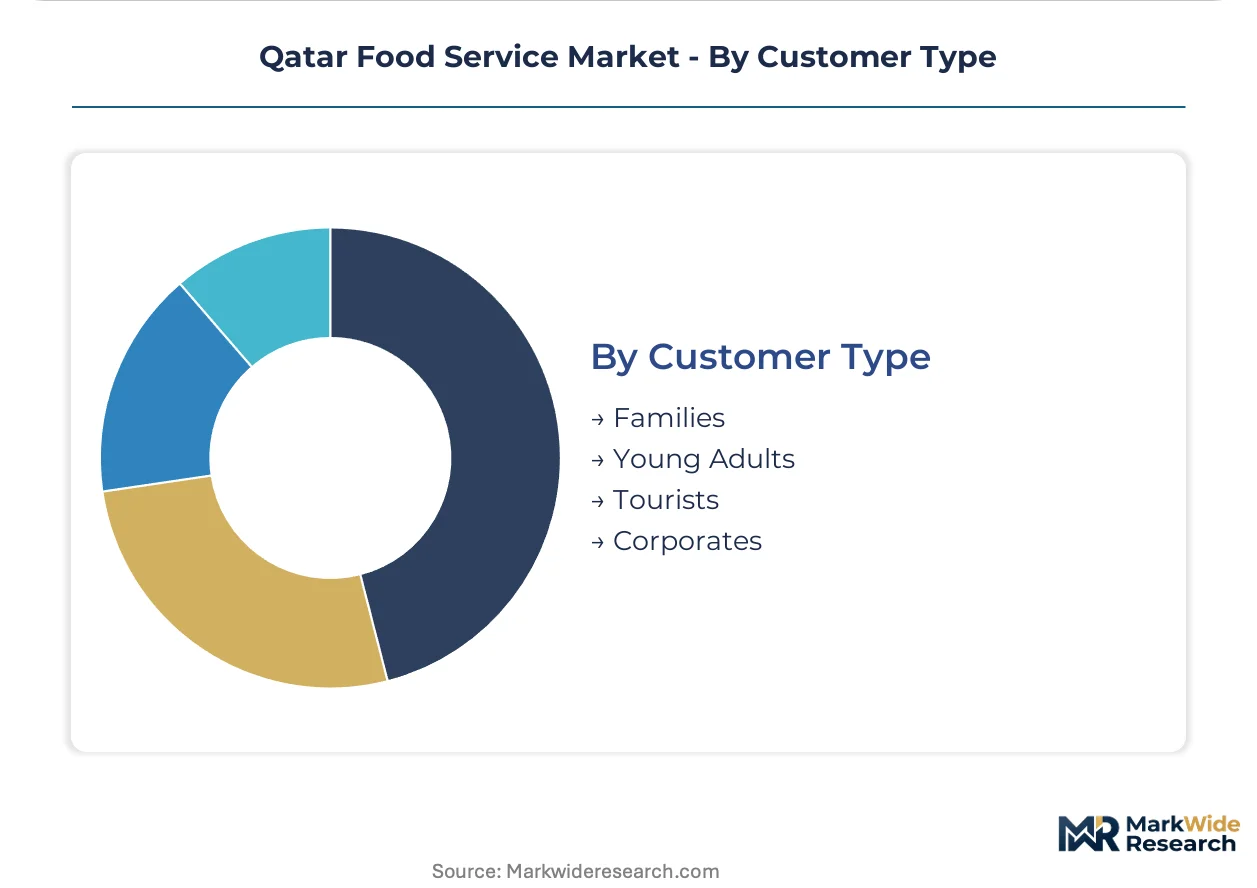
Customer Type:
Procurement consolidation patterns vary sharply across buyer segments with divergent price sensitivity and compliance requirements.
- Corporates:West Bay financial district buyers consolidating vendor relationships toward multi-service contracts covering breakfast, lunch, and event hospitality. Foreign firms establishing regional headquarters favor single-source arrangements with guaranteed halal compliance.
- Tourists:FIFA-legacy event venues and hospitality-linked operations facing Qatar Tourism Authority sustainability benchmarks. Early compliance secures preferred supplier status for recurring event volumes.
- Families:Weekend and occasion-driven demand concentrating in mall-based dining clusters.
- Young Adults:Platform-native ordering behavior driving delivery and ghost kitchen adoption.
Corporates anchor the most stable revenue base; Tourists show the steepest volume volatility around event cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qatar Free Zones Authority's Ras Bufontas and Um Alhoul zones accelerate food service supplier concentration through customs duty exemptions and streamlined licensing for cold-chain operators.
Doha West Bay
Corporate catering contracts from foreign regional headquarters drive premium food service procurement. Ministry of Public Health HACCP audits enforce real-time temperature logging across commissary operations. The financial district's daytime workforce concentration supports multi-service vendor arrangements covering breakfast, lunch, and hospitality events.
Lusail
New residential and commercial clusters generate concentrated evening and weekend food traffic. Qatar Tourism Authority sustainability benchmarks elevate qualification barriers for hospitality-linked operators. The Lusail Marina and Entertainment City districts absorb capital deployment from mall-based chains seeking expansion beyond saturated Doha Festival City catchments.
Msheireb Downtown Doha
Urban regeneration concentrates daytime food demand with limited incumbent supply. Municipal zoning approvals align with national tourism masterplans to prioritize pedestrian-friendly dining formats. The mixed-use development's corporate tenants favor single-source catering contracts with guaranteed halal compliance.
Al Wakrah and Al Khor
Industrial zone commissary production serves dispersed outlet networks across southern and northern corridors. Hamad Port proximity reduces perishable import lead times for protein and produce inputs. Centralized blast-freezing capacity supplies retail and foodservice channels, though last-mile frozen logistics incur cost penalties for remote operators.
Industrial Area Doha
Centralized production infrastructure clusters refrigeration-dependent ready-to-eat and frozen meal capacity. Ministry of Public Health cold-chain mandates exclude sub-scale entrants through capex floors. Ghost kitchen convergence with aggregator platforms enables asset-light market entry without premium mall rents.
Qatar Food Service Market Competitive Landscape
Top-tier vendors anchor institutional and hospitality procurement, while mid-scale independents face consolidation pressure from regulatory compliance costs. The market structure shows sharp tiering between multi-brand portfolio operators and single-concept specialists. Three archetypes dominate: mall-based retail food service, energy sector institutional catering, and platform-native delivery formats. Competitive moves concentrate on strategic partnerships with real estate developers and backward integration into commissary production.
Within the multi-brand retail tier, M.H. Alshaya Co. WLL and Al Jassim Group exemplify contrasting scale strategies. Alshaya leverages portfolio breadth across Doha Festival City and Place Vendôme mall locations, while Al Jassim anchors government and energy sector contracts with superior payment visibility. Americana Restaurants International PLC occupies a position emphasizing Gulf Cooperation Council operational scale with localized menu adaptation.
| Leading Market Players |
|---|
| M.H. Alshaya Co. WLL |
| Al Jassim Group |
| Al Mana Restaurants & Food Company |
| Jollibee Foods Corp. |
| Alamar Foods Co. |
| Almuftah Group |
| Teatime |
| Sterling Restaurants |
| Americana Restaurants International PLC |
| Others |
Pricing and Supply Chain Analysis
Qatar Tourism Authority sustainability benchmarks gate qualified supply access and premium-tier pricing power for hospitality-linked operators, compressing margins for non-compliant vendors while elevating certified players into preferred supplier tiers for FIFA-legacy venues.
Pricing Analysis
Short lead-time premiums dominate protein and produce procurement through Hamad Port, where spot inventory discounts widen during seasonal import surges. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant levels reflects Ministry of Public Health HACCP audit status as the primary differentiation driver. Cost compression in the economy tier is intensifying because sub-scale independents struggle to absorb cold-chain capex floors. Corporate catering buyers in West Bay show the least price sensitivity, while mall-based QSR operators face the most acute margin pressure from aggregator commission exposure.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification for protein inputs, with approved vendor lists drawing from Brazil, Australia, and New Zealand for beef and lamb. Fresh produce hinges on seasonal flows from India, Turkey, and Egypt, while dairy and frozen products rest on European Union and Saudi Arabian supply corridors. Single-source vulnerability concentrates in specialized halal-certified ingredients where Ministry of Public Health audit backlogs delay new supplier onboarding. Distribution runs through Hamad Port cold-chain facilities into Doha's industrial zone commissaries, with last-mile temperature-controlled logistics serving the West Bay-Lusail corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Qatar food service market reads as a cost-of-compliance story where Ministry of Public Health HACCP-aligned temperature control mandates erect a barrier-to-entry moat that rewards early-certified operators with institutional contract access.
For Market Incumbents: Extend backward integration into captive commissary production to defend margin structures against perishable input volatility and aggregator platform disintermediation. Anchor multi-service corporate catering contracts across West Bay financial district towers before foreign regional headquarters consolidate vendor pools. Prioritize Qatar Tourism Authority sustainability certification investment to lock in preferred supplier status for recurring event volumes at FIFA-legacy venues.
For New Entrants and Emerging Players: Aggregator platform partnerships offer the fastest path to addressable demand without premium mall rent burdens. Ghost kitchen infrastructure in Doha's industrial zone represents the most penetrable entry point, enabling asset-light market testing before physical outlet commitment. Target Msheireb Downtown Doha's limited incumbent supply with delivery-optimized formats serving daytime corporate traffic.
For Investors and Strategic Acquirers: Ministry of Public Health audit digitization mandates are the leading indicator that compliance technology vendors and certified commissary operators will command acquisition premiums. The five-to-ten-year viability window favors operators with institutional contract visibility over consumer-facing mall tenants. Target acquisition candidates with anchored energy sector or government catering relationships and embedded halal certification infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Capacity Expansion | Centralized blast-freezing infrastructure in Doha's industrial zone reduces last-mile cost penalties for West Bay operators. |
| HACCP Compliance Technology Deployment | IoT sensor networks and cloud-based documentation satisfy Ministry of Public Health real-time temperature logging mandates. |
| Multi-Service Corporate Contract Consolidation | Single-source arrangements covering breakfast, lunch, and event hospitality capture foreign regional headquarters procurement. |
| Ghost Kitchen Infrastructure Partnership | Cloud kitchen convergence with aggregator APIs enables asset-light market entry without Place Vendôme premium rents. |
| Sustainability Certification Program | Early Qatar Tourism Authority benchmark compliance secures preferred supplier status for hospitality-linked event venues. |
Research Methodology
Independent corroboration across food service operations executives, Ministry of Public Health compliance officers, and corporate catering procurement managers underwrites the qualitative findings. Primary interviews with commissary production directors, mall-based chain development leads, and aggregator platform commercial heads combined with secondary validation from Qatar Tourism Authority sustainability filings, Ministry of Public Health licensing databases, and customs import records through Hamad Port. Bottom-up outlet count triangulation against top-down tourism and workforce demand estimates anchors volume assumptions.
Rate-of-change decomposition across the analysis window separates volume growth from mix shift and pricing evolution. Segmentation dimensions modeled include product type, end-user channel, service format, and customer archetype, with regional corridor differentiation across West Bay, Lusail, and Msheireb districts. CAGRs derive from trend extrapolation of smartphone penetration effects on delivery platform density and institutional procurement consolidation patterns. Industry-specific forecast inputs incorporate Qatar Tourism Authority event calendar density and Ministry of Public Health audit capacity constraints.
Caveats apply where Ministry of Public Health licensing backlogs or Qatar Tourism Authority sustainability benchmark revisions could materially shift the outlook. Forecasts reflect assumptions around cold-chain infrastructure buildout timing and institutional contract renewal rates. Deviation in perishable import lead times or currency exposure would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smart Food Logistics Market
Food Service
Food Service Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Pasteurized Eggs Market
Food Service
Europe Food Service Market
Food Service
China Inflight Catering Market
Food Service
Instant Grocery Market
Food Service
Air Fryer Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Breakfast Takeout Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Takeout Dinner Market
Food Service
Food and Grocery Retail Market
Food Service
Street Vendors Market