
 Gourmet Street Food Market | 2026-2036
Gourmet Street Food Market Size, Share, and Industry Trends Forecast 2026-2036
Gourmet Street Food Market Foresight
The corporate catering vertical is pivoting toward gourmet street food formats for employee dining programs and event hospitality. Gurmeo leverages its centralized kitchen infrastructure to supply multiple urban food truck pods with consistent quality. Moda Food anchors its competitive position through direct sourcing relationships with regional ingredient cooperatives. Mochinut differentiates via proprietary mochi-dough hybrid formulations that command repeat visitation in high-foot-traffic locations.
Gourmet street food denotes prepared-to-order artisanal cuisine distributed through mobile or semi-permanent outdoor vending platforms, typically featuring chef-driven menus, premium ingredient sourcing, and Instagram-optimized presentation formats. Equipment specifications center on compact high-BTU propane ranges, ventless exhaust systems, and refrigerated prep tables meeting NSF/ANSI food equipment standards. The food type dimension shows tacos and dumplings capturing the largest volume share, while the serving style segment reveals food truck and pop-up formats outpacing traditional takeaway in revenue per square foot. Pricing model segmentation indicates premium tiers concentrating in coastal metropolitan markets, whereas budget and mid-range brackets dominate secondary city expansion.
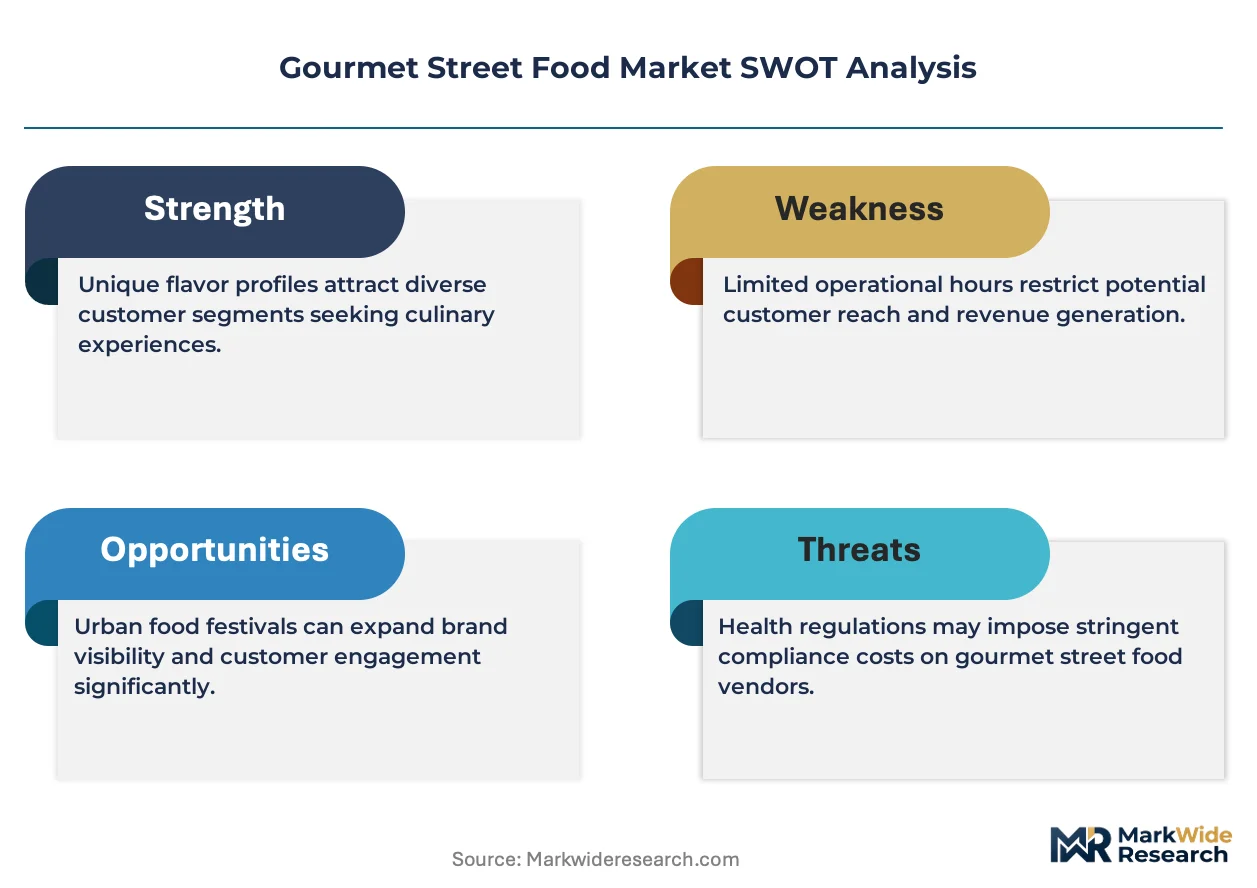
The FDA Food Code governs mobile food unit sanitation protocols across the United States, while the EU General Food Law Regulation establishes traceability requirements for street food operators in European member states. Local health departments in emerging markets are tightening licensing frameworks, forcing unregistered vendors toward formalization or exit. Stakeholders must monitor evolving municipal zoning ordinances that alternately restrict or incentivize street food clustering in central business districts.
Market Dynamics
Mobile kitchen technology upgrades and municipal health department compliance mandates are compressing vendor operating margins while simultaneously raising barriers to informal market entry. This structural force is bifurcating the vendor base between capitalized operators with centralized kitchen infrastructure and unregistered street food sellers facing regulatory displacement.
Growth Catalysts
- Urban Millennial Demand:Dense metropolitan zones in Bangkok, Mexico City, and Dubai generate concentrated foot traffic for premium street food formats. Disposable income growth in these corridors sustains chef-driven menu pricing.
- FDA Food Code Alignment:Mobile food unit sanitation protocols across the United States are forcing vendor formalization. Compliance creates pathway to corporate catering contracts and event hospitality revenue streams.
- Propane Range Efficiency:Compact high-BTU cooking systems reduce energy costs per cover. NSF/ANSI certified equipment enables faster permit approval cycles in contested zoning districts.
Market Restraints
- Input Cost Volatility:Premium protein and specialty ingredient sourcing faces price pressure from agricultural commodity fluctuations. Regional ingredient cooperatives concentrate supply risk in specific growing zones.
- Zoning Ordinance Fragmentation:Municipal clustering restrictions in central business districts limit prime location access. Permitting timelines vary unpredictably across city jurisdictions.
- Ventless Exhaust Limitations:Technical constraints on grease and particulate capture restrict menu complexity. High-heat cooking applications face equipment certification bottlenecks.
Strategic Opportunities
- Corporate Catering Pivot:Employee dining programs and event hospitality represent underpenetrated B2B channel. Direct supply relationships bypass traditional food service intermediaries.
- EU General Food Law Traceability:European member state requirements for ingredient documentation create competitive moat for compliant operators. Formalized vendors capture market share from informal sellers.
- Instagram-Optimized Formats:Visual presentation standards converge with mobile ordering platforms. Food truck pods in high-foot-traffic locations monetize social media discovery mechanics.
Industry Challenges
- Refrigerated Prep Table Capex:NSF/ANSI food equipment standards require substantial capital investment for temperature-controlled mobile units. Financing access constrains vendor expansion velocity.
- Health Department Certification Timelines:Local licensing frameworks in emerging markets impose extended approval cycles. Unregistered vendors face forced exit before revenue generation begins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gourmet Street Food Market |
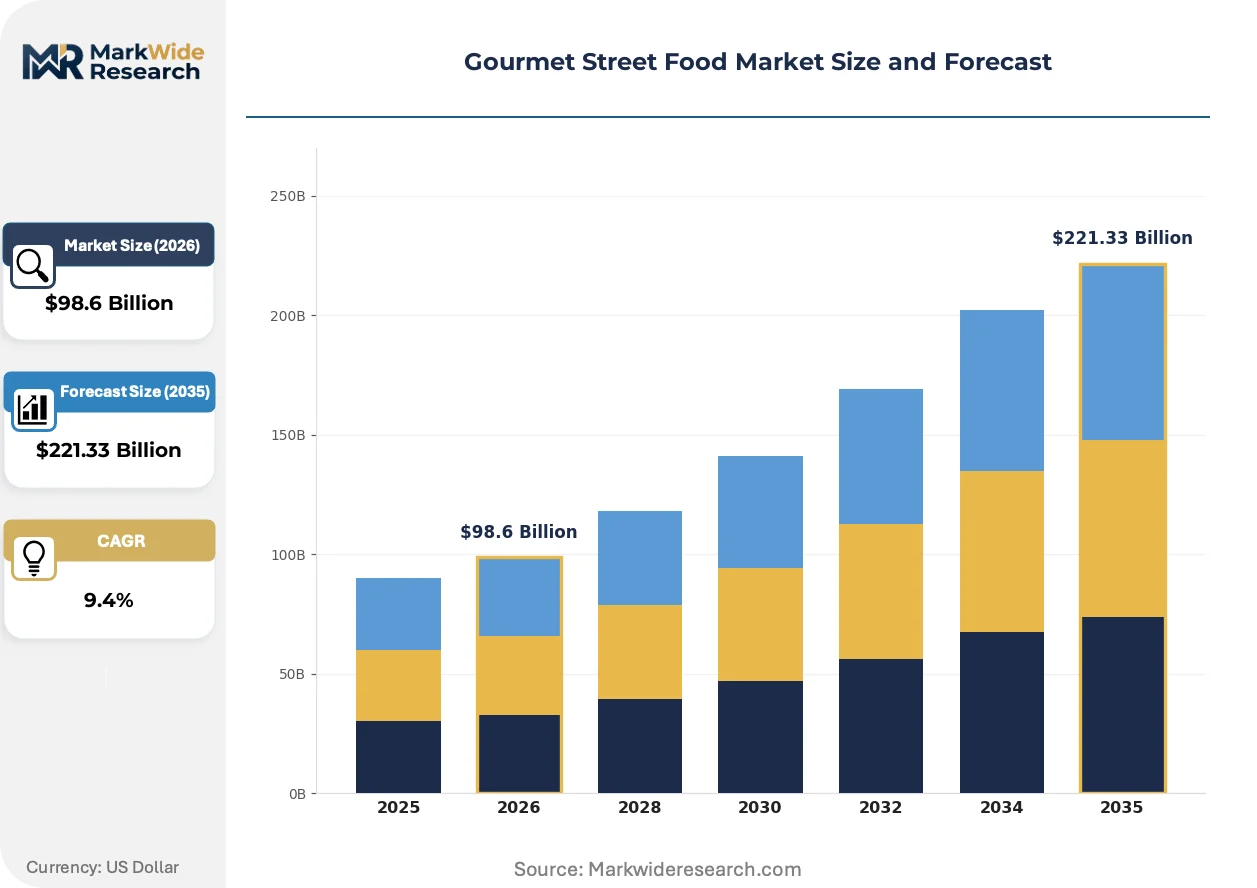
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Food Type: Tacos, Dumplings, Waffles, Burgers Serving Style: Takeaway, Sit-down, Food Truck, Pop-up Pricing Model: Premium, Budget, Mid-range, Seasonal Customer Type: Locals, Tourists, Foodies, Families |
| Companies Covered | Moda Food, Gurmeo, Mooddìca, Mongardemanger, Crema, Mochinut, Effusion, Agrooe, Emilia Food Love, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gourmet Street Food Market Shifts & Advancements
Technology convergence between mobile kitchen systems and digital ordering platforms is restructuring how gourmet street food reaches consumers. This shift compresses the traditional relationship between physical location and customer acquisition.
Cloud-connected propane monitoring systems track fuel consumption and equipment performance in real time. High-density metropolitan operators adopt these sensors to optimize route planning and prevent service interruptions. This telemetry infrastructure is converging with predictive maintenance platforms to reduce downtime in competitive food truck pods.
The EU General Food Law Regulation mandates ingredient traceability documentation for street food operators across member states. Compliance systems now require digital record-keeping from farm to final preparation. Mobile vendors in France, Germany, and Italy face the steepest adaptation curves as enforcement tightens in urban corridors.
Consumption patterns among Gen Z buyers favor discovery-driven purchasing over brand loyalty. Food truck aggregators and pop-up location apps displace traditional foot-traffic dependence in Bangkok, São Paulo, and Riyadh. This behavioral shift concentrates revenue volatility in operators lacking digital presence or social media optimization capabilities.
Gourmet Street Food Market Segmentation
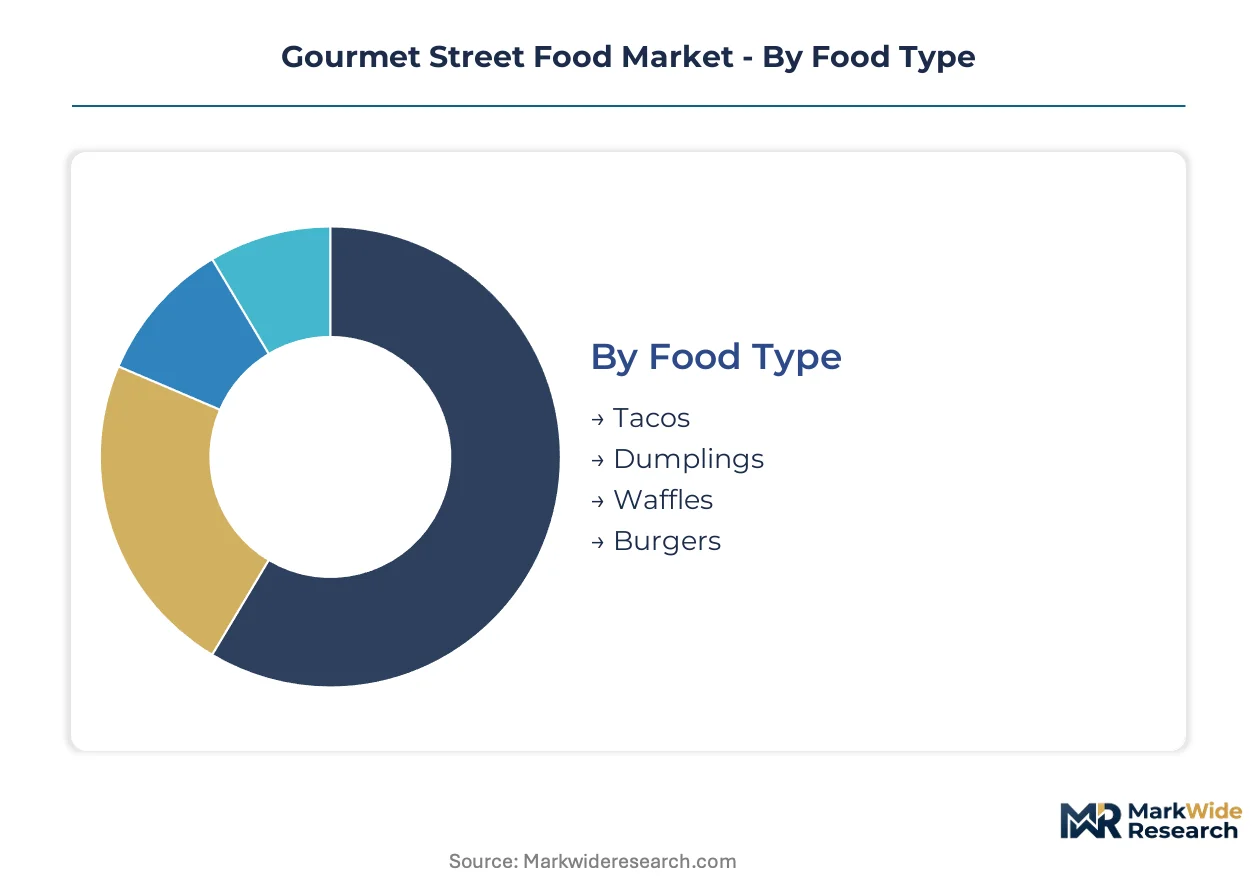
Segmentation in gourmet street food reveals how format choices dictate capital requirements, regulatory exposure, and margin architecture. Vendors optimize across these dimensions to match local demand density with operational feasibility.
Food Type:
Equipment refresh cycles and ingredient handling protocols vary sharply by food type, driving differential replacement timelines across vendor portfolios.
- Tacos:Corn and flour tortilla production demands compact griddle systems with precise temperature calibration. Demand clusters in Mexico City, Los Angeles, and Bangkok where masa-based formats command repeat visitation from urban millennials seeking authentic regional expression.
- Dumplings:Steam-intensive preparation requires ventless exhaust certification and specialized holding cabinets. Shanghai, Seoul, and London generate concentrated volume for hand-folded and machine-formed variants alike.
- Waffles:Batter-based formats utilize cast-iron or rotating Belgian presses with NSF/ANSI electrical certification. Brunch-oriented positioning in European capitals sustains premium pricing tiers.
- Burgers:High-BTU propane ranges and refrigerated prep tables dominate equipment profiles. Smash-style techniques in Dubai and Riyadh food truck pods drive throughput optimization.
Volume placements concentrate in Tacos; the faster expansion belongs to Dumplings.
Serving Style:
Real estate cost structures and permit complexity separate scalable formats from location-constrained alternatives.
- Food Truck:Mobile units with cloud-connected propane monitoring enable route optimization across high-foot-traffic corridors. Municipal zoning in Austin, Portland, and Berlin alternately restricts or incentivizes clustering near central business districts.
- Pop-up:Temporary installations leverage event hospitality and seasonal demand spikes. Lower capital barriers attract chef-entrepreneurs testing proprietary formulations before fixed-location commitment.
- Takeaway:Counter-service formats minimize front-of-house labor. Compact footprints suit high-rent metropolitan cores where speed of service determines throughput.
- Sit-down:Semi-permanent outdoor seating extends dwell time and beverage attach rates. Weather dependency constrains year-round viability in temperate climates.
Revenue per square foot peaks in Food Truck; the steepest expansion trajectory sits with Pop-up.
Pricing Model:
Customer willingness-to-pay thresholds segment along disposable income gradients and occasion type.
- Premium:Chef-driven menus with direct-sourced proteins and Instagram-optimized presentation. Coastal metropolitan markets in the United States and Western Europe sustain pricing multiples over standard tiers.
- Mid-range:Balanced quality-positioning for office worker lunch occasions. Corporate catering contracts in dense business districts favor this bracket for employee dining programs.
- Budget:Volume-driven formats with simplified ingredient sourcing. Secondary city expansion and university-adjacent locations concentrate demand here.
- Seasonal:Limited-time offerings tied to ingredient availability or festival calendars. Revenue volatility demands working capital flexibility.
Margin concentration rests in Premium; the broadest addressable market sits in Mid-range.
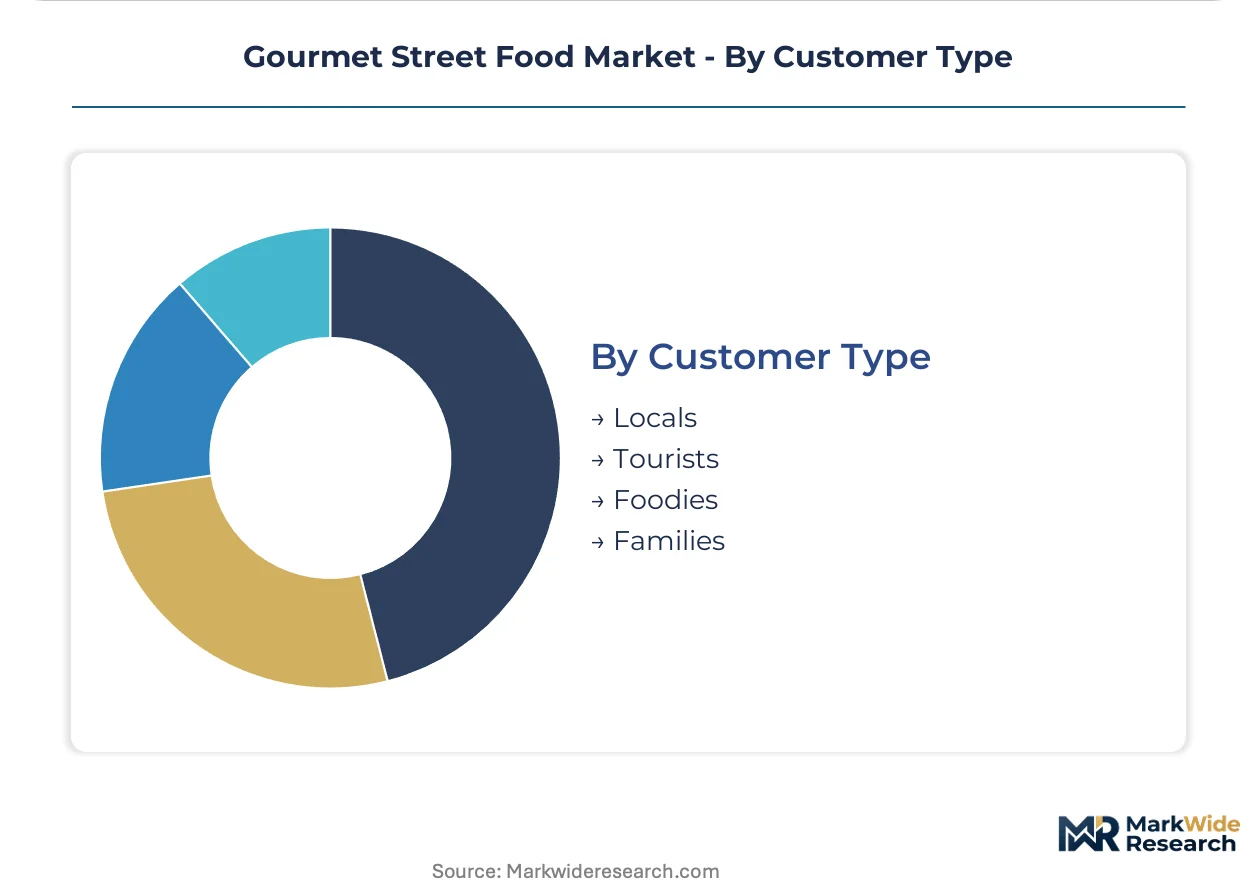
Customer Type:
Behavioral patterns around discovery, loyalty, and price sensitivity diverge across these groups.
- Foodies:Discovery-driven purchasers prioritize novelty and social media shareability. Mobile ordering platforms and aggregator apps displace traditional foot-traffic dependence for this segment.
- Urban Millennials:Dense metropolitan zones generate habitual repeat visitation. Disposable income growth in Southeast Asian and Middle Eastern corridors sustains chef-driven menu pricing.
- Tourists:Location-based search behavior concentrates demand near transit hubs and cultural landmarks. Language-agnostic visual presentation reduces friction.
- Families:Group-sized portions and allergen transparency drive selection. Weekend and holiday occasion concentration creates demand spikes.
Frequency of purchase peaks among Foodies; the largest untapped pool resides in Families.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangkok, Dubai, and Mexico City accelerate vendor clustering through reduced permitting friction and centralized health inspection protocols. These designated corridors concentrate mobile kitchen infrastructure investment and attract chef-entrepreneurs seeking streamlined regulatory pathways.
United States
Urban millennials in Austin, Portland, and Los Angeles sustain premium pricing for chef-driven taco and burger formats. The FDA Food Code governs mobile food unit sanitation protocols, creating compliance pathways toward corporate catering contracts. Food truck pods near central business districts in Austin generate concentrated foot traffic through municipal clustering incentives.
Thailand
Dense metropolitan zones in Bangkok and Chiang Mai drive habitual repeat visitation for dumpling and taco variants among domestic consumers and tourists. The country's national food safety regulator enforces street vendor licensing frameworks that displace unregistered sellers toward formalization. Night markets along Sukhumvit and Ratchada corridors anchor high-volume mobile kitchen operations.
Mexico
Masa-based taco formats command authentic regional expression demand in Mexico City, Guadalajara, and Monterrey. Municipal health departments tighten licensing frameworks, compressing informal vendor margins while elevating capitalized operators. The Coyoacán and Roma Norte districts concentrate Instagram-optimized food truck pods with direct sourcing from regional ingredient cooperatives.
United Arab Emirates
Expatriate professionals and tourists in Dubai and Abu Dhabi sustain premium-tier pricing for smash-style burgers and mochi-dough hybrids. MOHAP establishes mobile food unit traceability requirements that favor vendors with centralized kitchen infrastructure. Food truck clusters near Dubai Marina and JBR Beach monetize high-foot-traffic locations through social media discovery mechanics.
Germany
Brunch-oriented waffle formats and dumpling variants capture urban millennial demand in Berlin, Munich, and Hamburg. The EU General Food Law Regulation mandates ingredient traceability documentation, creating competitive moats for compliant operators. Street food markets at Markthalle Neun in Berlin and Werksviertel in Munich anchor chef-driven pop-up installations.
Gourmet Street Food Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning with centralized kitchen infrastructure, while mid-scale operators compete through regional ingredient cooperative relationships. The vendor base stratifies across capitalized formalized entities, chef-entrepreneur pop-up specialists, and informal sellers facing regulatory displacement. Strategic archetypes include infrastructure-heavy suppliers, direct-sourcing specialists, and proprietary formulation innovators. Dominant competitive moves encompass municipal permit aggregation and corporate catering contract acquisition.
Within the infrastructure-heavy supplier tier, Gurmeo exemplifies centralized kitchen architecture enabling multi-pod supply consistency. Moda Food occupies a position among direct-sourcing specialists leveraging regional ingredient cooperative relationships. Mochinut anchors the proprietary formulation archetype through mochi-dough hybrid differentiation that commands repeat visitation.
| Leading Market Players |
|---|
| Moda Food |
| Gurmeo |
| Mooddìca |
| Mongardemanger |
| Crema |
| Mochinut |
| Effusion |
| Agrooe |
| Emilia Food Love |
| Others |
Supply & Pricing Matrix
Cloud-connected propane monitoring systems and predictive maintenance platforms are compressing operating cost variability while concentrating supplier power among equipment-integrated service providers. This technological shift simultaneously reduces energy waste per cover and locks vendors into proprietary telemetry ecosystems that reshape procurement economics.
Pricing Analysis
Short lead-time premiums for NSF/ANSI-certified mobile kitchen equipment command substantial markups over spot-market alternatives with extended delivery windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic delivery cost, with coastal metropolitan buyers showing lowest price sensitivity. Cost compression in the budget tier is intensifying because unregistered vendor displacement floods secondary markets with depreciated equipment. Corporate catering buyers demonstrate highest price sensitivity due to contract volume negotiations, while tourist-facing food truck pods absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements for high-BTU propane ranges and ventless exhaust systems mandate multi-supplier qualification across NSF/ANSI-certified manufacturers in the United States, Germany, and South Korea. Regional ingredient cooperatives in Mexico, Thailand, and Italy anchor specialty sourcing for masa, rice flour, and wheat derivatives. Single-source vulnerability concentrates in cloud-connected telemetry modules where proprietary protocols limit interchangeability. Distribution runs through specialized food service equipment distributors with municipal permit consulting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile kitchen infrastructure capacity constraints prop pricing power for centralized kitchen operators, as NSF/ANSI certification bottlenecks and municipal permit backlogs limit rapid vendor expansion.
For Market Incumbents: Lock in centralized kitchen capacity in Bangkok, Dubai, and Mexico City before municipal zoning incentives expire. Acquire regional ingredient cooperative relationships to defend against direct-sourcing specialists. Prioritize FDA Food Code and EU General Food Law traceability investments to capture corporate catering contracts from informal competitors facing regulatory displacement. For New Entrants and Emerging Players: The mid-range pricing gap between premium chef-driven formats and budget volume operators presents the most penetrable white space. Target secondary city expansion in university-adjacent corridors with simplified ingredient sourcing and compact refrigerated prep table configurations. Launch through pop-up formats to test proprietary formulations before fixed-location capital commitment. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure-heavy suppliers with multi-pod supply networks and direct-sourcing specialists holding cooperative exclusives. Long-term viability favors operators with backward integration into ingredient procurement and captive compliance capabilities. Watch for FDA Food Code alignment acceleration in emerging markets as the inflection signal for formalization-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Kitchen Infrastructure Expansion | Multi-pod supply consistency in Bangkok and Dubai captures corporate catering contract volume. |
| Regional Ingredient Cooperative Acquisition | Direct sourcing relationships in Mexico and Italy secure specialty masa and wheat flour supply. |
| NSF/ANSI Certification Investment | Faster permit approval cycles in contested Austin and Portland zoning districts accelerate deployment. |
| Cloud-Connected Telemetry Integration | Predictive maintenance platforms reduce downtime in competitive food truck pods. |
| Corporate Catering Channel Development | Employee dining programs bypass traditional food service intermediaries for margin capture. |
Research Methodology
Independent corroboration across mobile kitchen equipment manufacturers, municipal health department licensing officers, and regional ingredient cooperative managers underwrites the qualitative findings. Primary interviews with food truck operators, centralized kitchen facility directors, and corporate catering procurement leads combined with secondary validation from FDA Food Code guidance documents, EU General Food Law regulatory filings, and municipal zoning ordinance databases. Bottom-up vendor enumeration and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across food type, serving style, pricing model, and customer type dimensions structures the analytical framework throughout the forecast period. CAGRs derive from segment-level growth trajectories weighted by base-year revenue contribution. Industry-specific forecast inputs incorporate propane range efficiency curves and health department certification timeline distributions.
Inputs from equipment certification bodies and municipal permitting databases were available through the study window; gaps in informal vendor economic data introduce uncertainty bands around secondary market estimates. Forecasts reflect assumptions regarding regulatory enforcement intensity and technology adoption curves. Deviation in FDA Food Code state-level implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Supermarkets Market
Food Service
Plates Market
Food Service
Food Service Gloves Market
Food Service
Train Catering Service Market
Food Service
Steam Tables and Food Well Market
Food Service
Global Digital Grocery Market
Food Service
Full-Service Restaurants Market
Food Service
Europe Online Grocery Market
Food Service
France Foodservice Market
Food Service
Self-Heating Hot Pot Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Brazil Foodservice Market
Food Service
Europe Airline Catering Services Market
Food Service
Haute Cuisine Market