
 Global Food Platform-To-Consumer Delivery Market | 2026-2036
Global Food Platform-To-Consumer Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Platform-To-Consumer Delivery Market Foresight
AI-powered dispatch algorithms and dynamic batching is reconfiguring how delivery platforms optimize rider utilization and restaurant throughput. Meituan Dianping leverages its super-app infrastructure to sustain dominance across meal delivery and adjacent local services. DoorDash anchors North American operations through dense suburban coverage and merchant onboarding scale. Delivery Hero competes across fragmented European, Latin American, and Middle Eastern markets through portfolio brands.
Food platform-to-consumer delivery denotes a digitally intermediated service architecture connecting restaurants, grocery merchants, or specialty food producers with end consumers via mobile applications and web interfaces, utilizing GPS-enabled logistics coordination and real-time inventory APIs to fulfill orders within contracted time windows. The primary commercial purpose centers on reducing friction in food access while capturing transaction economics through commission structures and service fees. Meal delivery occupies the largest value pool within the application dimension, though grocery dispatch is expanding fastest as platforms extend frequency through basket-size expansion. Bicycle and motorcycle modes dominate the delivery mode mix in dense Asian and European cities, while car-based fulfillment prevails in sprawling North American metros where per-mile economics favor larger vehicle capacity.
The EU Digital Services Act imposes transparency obligations on algorithmic ranking and data usage for platforms operating across member states, while the FDA and USDA maintain jurisdiction over food safety standards and labeling requirements affecting cross-border and interstate operations in the United States. China's SAMR enforces antitrust and pricing discipline on domestic super-apps, constraining exclusive merchant agreements that once locked in restaurant supply. Stakeholders must monitor how divergent data-localization mandates and gig-worker classification rulings across jurisdictions reshape operating cost structures and platform liability exposure.
Market Dynamics
Algorithmic dispatch systems are compressing delivery windows while EU regulatory mandates force platforms to expose ranking logic and audit data flows, fundamentally altering how operators balance speed against compliance costs.
Growth Catalysts
- GDPR-Driven Data Infrastructure Upgrades:European platforms are rebuilding consumer data architectures to meet transparency mandates, creating competitive moats through certified privacy stacks that attract enterprise meal-program clients.
- Smartphone Penetration in Dense Urban Clusters:Indian metro corridors are generating order frequency levels that justify dedicated dark kitchen infrastructure and motorcycle-based micro-fulfillment networks.
- Dynamic Batching Algorithms:Machine learning models that group multiple orders into single rider routes are improving per-trip economics and reducing fleet idle time during off-peak windows.
Market Restraints
- Fuel Price Volatility:Car-dependent fulfillment in sprawling North American metros exposes operators to diesel and gasoline cost swings that erode per-mile margins.
- Gig-Worker Reclassification Risk:Jurisdictional rulings in California, the United Kingdom, and the Netherlands threaten to convert variable contractor costs into fixed employment liabilities.
- Platform Commission Caps:SAMR enforcement in China limits the percentage restaurants can be charged, compressing the primary revenue model that funds logistics subsidies.
Strategic Opportunities
- Grocery Basket Expansion:Platforms are extending beyond prepared meals into fresh produce and pantry staples, capturing higher-frequency purchase cycles and larger average order values.
- Corporate Meal Program Integration:Enterprise clients are consolidating vendor relationships onto single platforms, creating predictable volume commitments that stabilize demand forecasting.
- EU Digital Services Act Compliance Services:Specialized audit and algorithmic transparency tools represent a nascent B2B revenue stream as platforms seek external verification of ranking systems.
Industry Challenges
- Cross-Border Data Localization Conflicts:Divergent mandates on where consumer transaction records must be stored complicate platform architecture for operators spanning multiple jurisdictions.
- Restaurant Supply Concentration:Exclusive agreements with high-volume chains create dependency risks if those merchants develop in-house delivery capabilities or switch to competitor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Platform-To-Consumer Delivery Market |
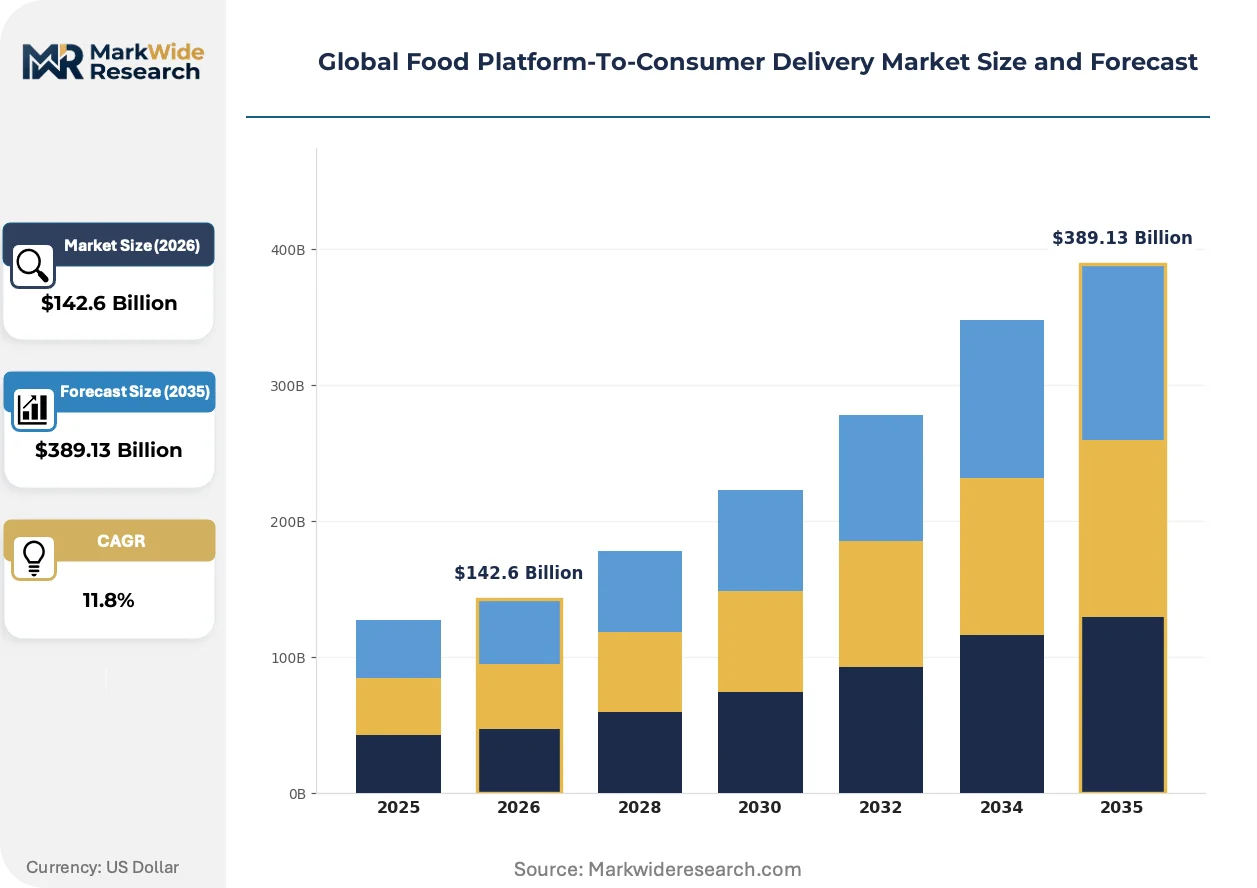
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $389.13 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Order Management, Payment Processing, Real-Time Tracking, Customer Support, Restaurant Integration Delivery Mode: Bicycle, Motorcycle, Car, Drone, On-Foot Customer Type: Individual Consumers, Corporate Clients, Food Vendors, Event Organizers, Catering Services Application: Meal Delivery, Grocery Dispatch, Alcohol Distribution, Prescription Food, Specialty Diets |
| Companies Covered | Uber Eats, DoorDash, Meituan Dianping, Deliveroo, Grubhub, Zomato, Swiggy, Delivery Hero, Just Eat Takeaway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Platform-To-Consumer Delivery Market Shifts & Advancements
Real-time coordination layers are replacing static scheduling systems, while regulatory transparency mandates and shifting corporate procurement patterns are forcing platforms to rebuild their technical and commercial architectures from the ground up.
AI-powered dispatch engines are digitizing how delivery platforms match orders to riders across variable demand curves. Quick-service restaurant chains in Southeast Asian megacities are deploying these systems to compress fulfillment windows below thirty minutes. The technology is digitizing traditional logistics planning by replacing human dispatchers with predictive models that anticipate order spikes before they materialize.
The EU Digital Services Act imposes algorithmic audit obligations on platforms operating across member states, requiring disclosure of how ranking systems prioritize certain restaurants or delivery options. Food delivery operators must now maintain explainable decision trails for every automated choice affecting merchant visibility. Mid-tier platforms in Germany and France are responding by hiring dedicated compliance engineering teams and publishing transparency reports that detail ranking methodology.
Corporate procurement departments are consolidating meal benefit programs onto single-platform contracts, displacing fragmented reimbursement models that allowed employees to choose any provider. Large employers in the United States and United Kingdom are negotiating enterprise rates in exchange for exclusive platform access across their workforce. This concentration is most visible in financial services and technology sectors where hybrid work policies have normalized subsidized lunch programs as a retention tool.
Global Food Platform-To-Consumer Delivery Market Segmentation
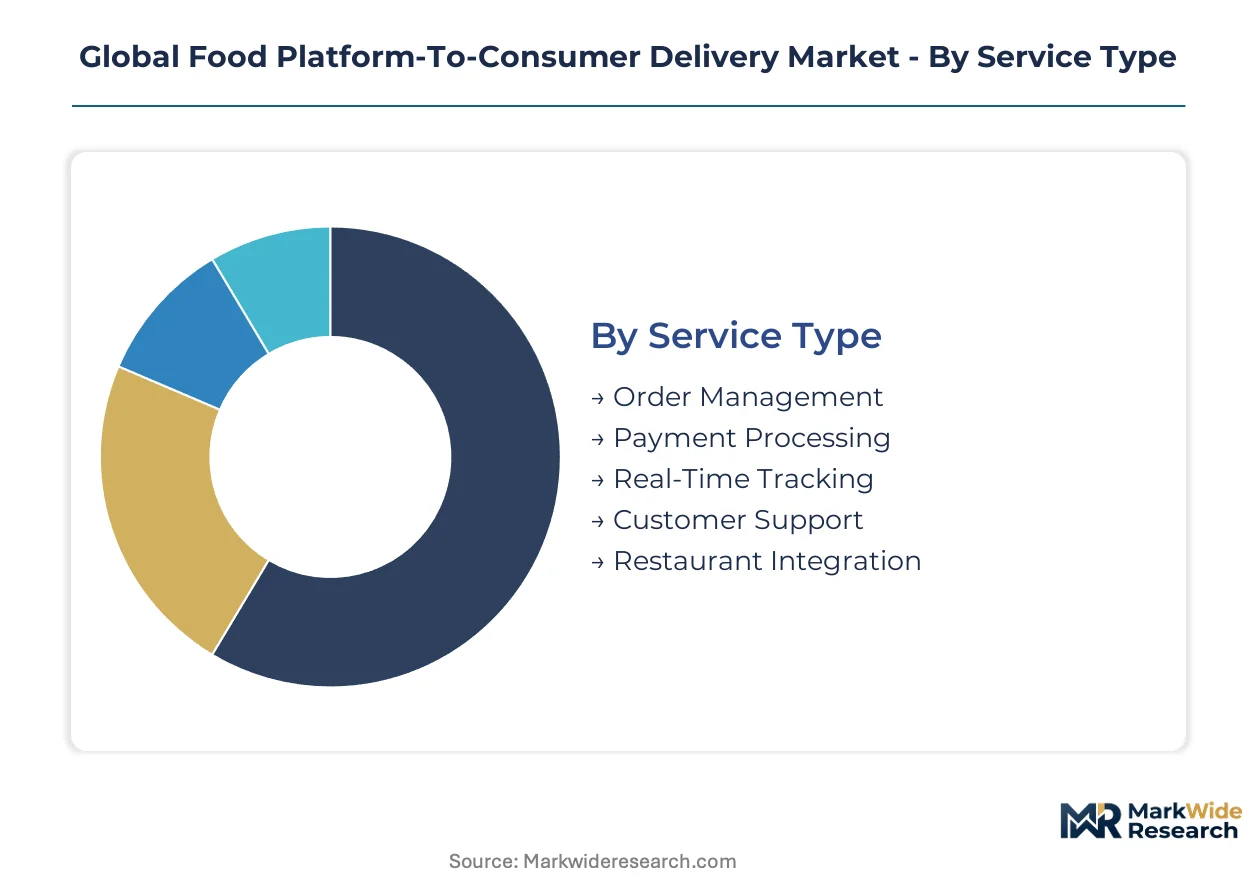
Platform-to-consumer delivery operators configure service architectures around distinct operational layers, each demanding specialized technology stacks and partnership structures. Segmentation reveals where capital concentrates and which capability gaps create competitive vulnerability.
Service Type:
Restaurant chains and grocery merchants impose divergent technical requirements across the service layer, forcing platforms to modularize or consolidate.
- Order Management:Centralized inventory APIs synchronize menu availability across aggregator interfaces and merchant POS systems. Quick-service operators in Indian metro corridors demand sub-second latency for high-frequency order windows during lunch rushes.
- Payment Processing:Multi-rail architectures accommodate digital wallets, credit networks, and buy-now-pay-later schemes across fragmented regulatory environments. European platforms invest heavily in PCI-DSS Level 1 certification and GDPR-compliant tokenization to satisfy enterprise procurement standards.
- Real-Time Tracking:GPS-enabled logistics layers expose rider location and estimated arrival to consumers and merchant dashboards alike.
- Customer Support:Hybrid chatbot-human escalation paths handle refund disputes and order modifications at scale.
- Restaurant Integration:White-label tablet and kitchen display systems embed platforms into merchant workflows.
The dominant share belongs to Order Management, while Payment Processing is closing the gap fastest as regulatory complexity deepens platform moats.
Delivery Mode:
Vehicle selection follows urban density patterns and fuel cost structures rather than platform preference.
- Bicycle:Zero-emission fulfillment dominates Amsterdam, Copenhagen, and central Paris where congestion pricing and narrow street grids penalize motorized alternatives. Battery-assisted cargo bikes extend range for grocery basket expansion.
- Motorcycle:Two-wheeler fleets achieve thirty-minute windows across Jakarta, Bangkok, and Ho Chi Minh City through lane-splitting permissions and minimal parking friction. Indonesian platforms operate dedicated motorcycle maintenance depots to sustain fleet availability.
- Car:Four-wheel fulfillment prevails in Houston, Phoenix, and other sprawling US metros where per-mile economics favor larger vehicle capacity and insulated trunk space protects order integrity.
- Drone:Autonomous aerial delivery operates under FAA Part 107 waivers in suburban Dallas-Fort Worth and FAA-BVLOS trials in rural North Carolina, constrained by battery range and population density regulations.
- On-Foot:Pedestrian couriers serve ultra-dense Hong Kong island districts and Singapore's central business district high-rises.
Motorcycle deployment generates the highest order velocity, though Drone infrastructure is expanding most quickly where regulatory sandboxes permit.
Customer Type:
Procurement centralization is redrawing account management investment and pricing architecture.
- Individual Consumers:Price-sensitive, frequency-driven users generate volume but erode margin through promotional stacking and single-order economics.
- Corporate Clients:Enterprise meal programs in London, New York, and Singapore negotiate committed volumes in exchange for subsidized per-employee pricing and consolidated billing. Financial services firms treat platform contracts as retention infrastructure for hybrid workforces.
- Food Vendors:Independent restaurants and dark kitchen operators constitute the supply side rather than demand, though some platforms now reverse the flow with vendor-facing SaaS tools.
- Event Organizers:Stadiums, conference centers, and festival operators demand surge-capable fulfillment with dedicated staging areas.
- Catering Services:B2B meal preparation firms use platforms as overflow capacity during contract spikes.
Individual Consumers still account for the largest order volume, yet Corporate Clients are gaining share fastest as HR departments consolidate vendor relationships.
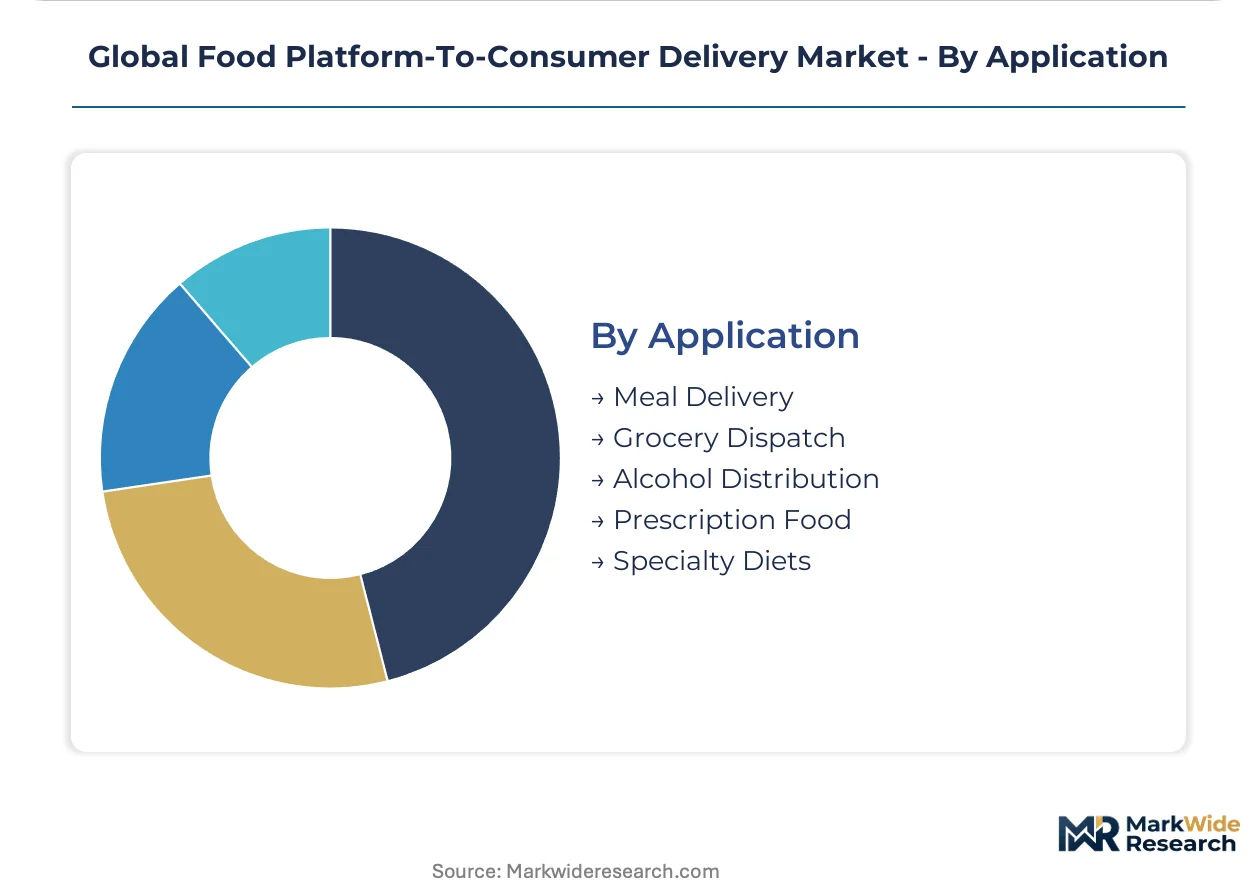
Application:
Frequency and basket size vary dramatically across food category, reshaping fleet configuration and merchant onboarding priorities.
- Meal Delivery:Prepared food from quick-service and full-service restaurants remains the core revenue pool, though commission rate compression in China and commission caps under SAMR enforcement constrain monetization.
- Grocery Dispatch:Fresh produce, pantry staples, and household essentials generate higher-frequency purchase cycles and larger average order values. São Paulo and Mexico City operators are building dedicated dark store networks to support fifteen-minute windows for produce and dairy.
- Alcohol Distribution:Age-verification requirements and licensing fragmentation create operational friction.
- Prescription Food:Medically tailored meals for diabetes and renal conditions serve insured populations through hospital system partnerships.
- Specialty Diets:Halal, kosher, and allergen-free preparation protocols demand certified kitchen separation and rider training.
Meal Delivery retains the dominant revenue position, though Grocery Dispatch is climbing the fastest as platforms compete on purchase frequency rather than occasion-based ordering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform-to-consumer delivery markets exhibit divergent trade balances: India and China generate substantial domestic order volumes with limited cross-border service exports, while the United States and Germany operate as net importers of delivery technology and operational expertise from Asia-Pacific operators.
United States
Dense suburban sprawl and car-dependent logistics infrastructure sustain four-wheel fulfillment networks across Houston, Phoenix, and Dallas-Fort Worth. The FAA regulates drone delivery trials under Part 107 waivers in suburban Texas corridors. California's gig-worker classification rulings threaten to restructure contractor cost models statewide.
China
Urban density in Shanghai, Beijing, and Shenzhen supports motorcycle-based micro-fulfillment achieving sub-thirty-minute windows. SAMR enforces commission caps and antitrust discipline on super-app operators. The Yangtze River Delta corridor hosts the world's largest concentration of dark kitchen infrastructure.
India
Smartphone penetration and metro corridor density in Mumbai, Bangalore, and Delhi-NCR justify dedicated dark store networks and battery-assisted cargo bike fleets. FSSAI mandates food safety certification for cloud kitchen operators. Hyderabad and Pune are emerging as secondary logistics hubs for southern and western coverage expansion.
Germany
Bicycle and cargo bike fulfillment dominates Berlin, Hamburg, and Munich under congestion pricing and low-emission zone regulations. The EU Digital Services Act imposes algorithmic transparency obligations on platforms operating across member states. The Rhine-Ruhr corridor sustains the highest per-capita delivery frequency in continental Europe.
Brazil
São Paulo and Mexico City operators are building dedicated dark store networks for fifteen-minute grocery windows. ANVISA regulates food safety standards for delivery-intermediated prepared meals. The São Paulo metropolitan area generates the highest order velocity in Latin America through motorcycle-based lane-splitting logistics.
Global Food Platform-To-Consumer Delivery Market Competitive Landscape
On the supply side, the industry is consolidating around super-app ecosystems and specialized regional aggregators, with mid-tier operators facing margin compression from algorithmic efficiency gaps. Three archetypes dominate: vertically integrated super-apps controlling merchant supply and logistics, pure-play delivery specialists optimizing dense urban networks, and grocery-retail hybrids leveraging existing store footprints. Competitive moves center on exclusive merchant contracting and dynamic pricing infrastructure deployment.
Within the super-app tier, Meituan Dianping exemplifies the vertically integrated model spanning meal delivery and adjacent local services. Among North American specialists, DoorDash and Uber Eats occupy positions defined by suburban coverage density and merchant onboarding scale. Delivery Hero represents the multi-brand portfolio approach across fragmented European, Latin American, and Middle Eastern markets.
| Leading Market Players |
|---|
| Uber Eats |
| DoorDash |
| Meituan Dianping |
| Deliveroo |
| Grubhub |
| Zomato |
| Swiggy |
| Delivery Hero |
| Just Eat Takeaway |
| Others |
Supply & Pricing Matrix
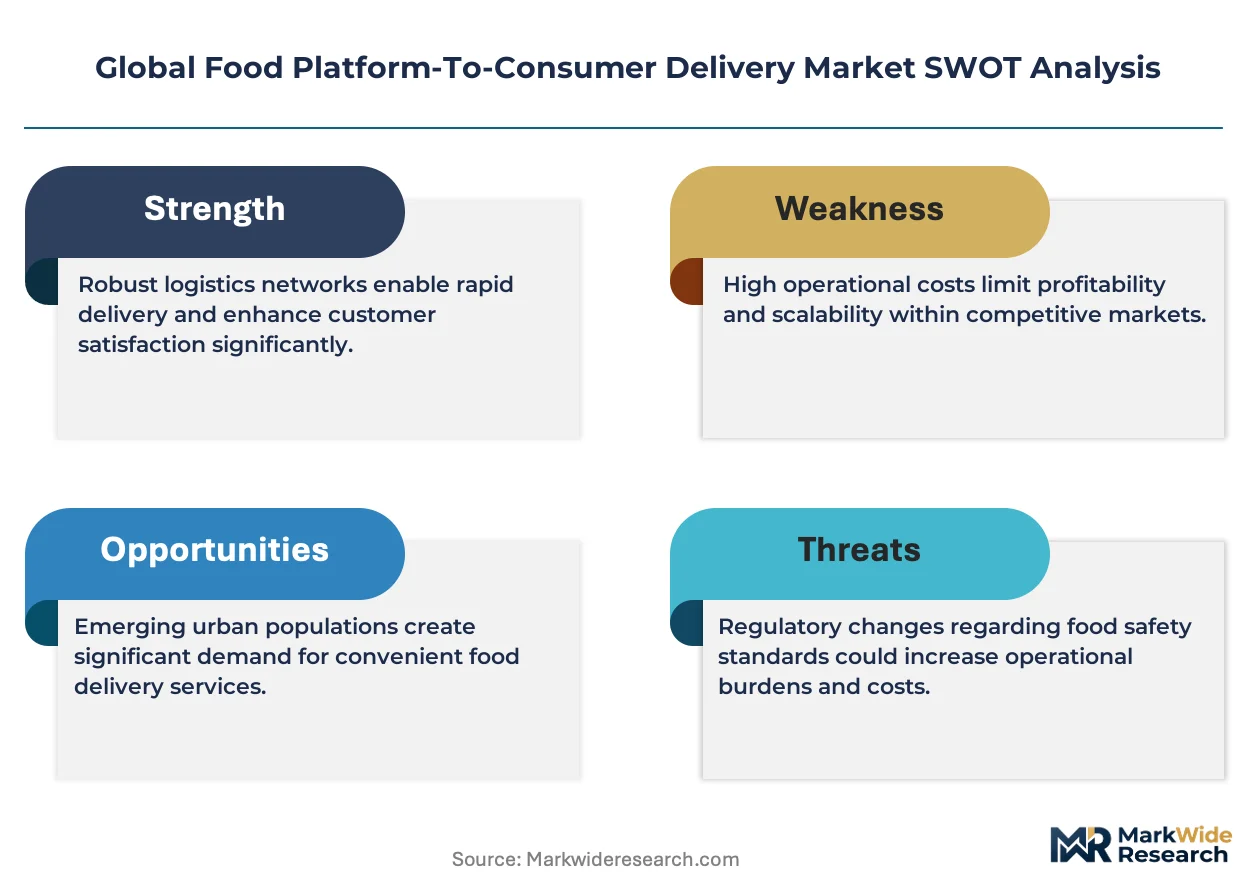
The Yangtze River Delta corridor anchors dark kitchen capacity expansion across Shanghai, Suzhou, and Hangzhou, where concentrated cloud kitchen infrastructure grants platforms downstream pricing leverage over restaurant commission negotiations. This supply density enables volume-based rate compression that independent operators in fragmented markets cannot match.
Pricing Analysis
Legacy dispatch platforms face margin compression against AI-native competitors deploying next-generation dynamic batching. Pricing stratifies across premium, standard, and economy tiers differentiated by delivery speed guarantees and enterprise certification levels. Cost compression in the economy tier intensifies as fuel volatility and gig-worker reclassification rulings erode per-mile economics. Individual consumers exhibit highest price sensitivity through promotional stacking, while corporate procurement departments accept premium rates for consolidated billing and dedicated account management.
Supply Chain Analysis
Extended payment terms from 30 to 90 days strain restaurant cash flow across India, Brazil, and Indonesia, where platforms leverage supply-chain finance facilities to lock in merchant exclusivity. Fleet operations draw from motorcycle manufacturing concentrated in China, India, and Vietnam, with battery cell supply anchored in South Korean and Japanese production. Single-source vulnerability in GPS-enabled logistics hardware creates chokepoint exposure. Distribution runs through urban micro-fulfillment nodes rather than centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward corporate procurement departments consolidating enterprise meal programs onto single-platform contracts, fragmenting the previously dispersed individual consumer base that platforms competed to acquire.
For Market Incumbents: Entrench algorithmic efficiency advantages through exclusive merchant contracting in high-frequency corridors, while building GDPR-compliant data architectures that attract enterprise clients facing EU Digital Services Act audit requirements. Dark kitchen vertical integration in the Yangtze River Delta and Mumbai-Bangalore corridors locks in supply capacity that emerging competitors cannot replicate. For New Entrants and Emerging Players: Secondary Indian metro corridors including Hyderabad, Pune, and Chennai offer underpenetrated density for motorcycle-based micro-fulfillment networks. Target grocery basket expansion in São Paulo and Mexico City where fifteen-minute produce delivery remains undersupplied. A white-label SaaS positioning toward independent restaurants bypasses direct platform competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated super-apps with captive logistics infrastructure over pure-play delivery specialists facing margin compression. Long-term viability hinges on algorithmic dispatch moats and enterprise contract concentration. Watch gig-worker reclassification rulings in California, the United Kingdom, and the Netherlands as inflection indicators for cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Batching Algorithm Deployment | Meituan Dianping and DoorDash compress fulfillment windows below thirty minutes through machine learning route optimization. |
| Dark Kitchen Infrastructure Buildout | Dedicated cloud kitchen networks in Shanghai and Mumbai reduce real estate costs while enabling menu specialization. |
| GDPR Compliance Certification | European platforms attract enterprise procurement contracts through auditable privacy stacks meeting EU Digital Services Act mandates. |
| Corporate Meal Program Integration | Financial services firms in London and New York consolidate subsidized lunch benefits onto single-platform contracts. |
| Grocery Basket Expansion | São Paulo operators build dedicated dark stores for fifteen-minute produce and dairy windows. |
Research Methodology
Operator-level perspectives from fleet dispatch managers, restaurant supply chain directors, corporate procurement officers, and regulatory compliance leads anchored the qualitative base. Primary interviews triangulated against secondary sources including EU Digital Services Act filings, SAMR enforcement disclosures, FSSAI cloud kitchen registrations, and platform transparency reports. Bottom-up order volume estimates from metro corridor operators combined with top-down market sizing across service type, delivery mode, and customer segments.
Scenario-bracketing around regulatory enforcement intensity and fuel cost volatility framed the projection horizon. Segmentation dimensions modeled include service architecture layer, vehicle type, procurement centralization level, and application category across meal delivery and grocery dispatch. CAGRs derived from logistic function adoption curves fitted to smartphone penetration and urban density thresholds. Forecast inputs incorporated gig-worker classification ruling trajectories and dark kitchen capacity buildout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by super-app ecosystems or grocery-retail hybrids would shift outcomes. Macroeconomic contraction, accelerated gig-worker reclassification, or algorithmic transparency mandate expansion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Bahrain Food Service Market
Food Service
Rotisseries Market
Food Service
Virtual Kitchen Market
Food Service
Food Away from Home Market
Food Service
Bar Refrigeration Market
Food Service
Food Trucks Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Charbroiler Market
Food Service
Africa Foodservice Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Lunch Takeout Market
Food Service
Global Digital Grocery Market
Food Service
Foodservice Coffee Market
Food Service
Food Service Market
Food Service
Europe Airline Catering Services Market