
 Fresh Food Residue Testing Market | 2026-2036
Fresh Food Residue Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Food Residue Testing Market Insights
Market Context
Skilled analytical chemist availability is bifurcating competitive outcomes in fresh food residue testing, as laboratories with certified mass spectrometry specialists secure preferred supplier status with major retailers. Thermo Fisher Scientific leverages its chromatography portfolio to dominate instrument supply for high-throughput pesticide screening facilities. Eurofins Scientific anchors its position through geographic density of ISO-accredited labs across premium produce sourcing regions. SGS SA differentiates via integrated farm-to-retail audit and testing bundles that reduce client procurement complexity.
Technical Definition and Segment Structure
Fresh food residue testing encompasses quantitative and qualitative analytical procedures that detect chemical contaminants, pathogenic organisms, and quality degradation markers in unprocessed agricultural commodities, typically achieving detection thresholds at parts-per-billion levels through chromatographic separation coupled with mass-selective detection. The primary commercial purpose is to verify compliance with statutory maximum residue limits and contractual food safety specifications before products enter retail distribution or export channels. Pesticide testing commands the largest revenue share due to expanding MRL schedules, while mass spectrometry methods represent the fastest-growing technology segment as laboratories replace immunoassay workflows for multi-residue panels. Dairy residue analysis constitutes a concentrated margin pool because perishable logistics demand rapid turnaround testing at premium pricing.
Regulatory Framework
The EPA and FDA in the United States enforce pesticide tolerance levels under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU Green Deal and Farm to Fork Strategy mandate 50% pesticide reduction targets that intensify residue surveillance across member states. EFSA scientific opinions and REACH chemical registration requirements shape the analytical target lists that laboratories must validate, directly determining instrument configuration and reagent demand. Stakeholders must monitor evolving MRL harmonization negotiations between the EU and Codex Alimentarius, as divergence in regulatory limits forces dual-method validation investments or market exclusion decisions.
Market Dynamics
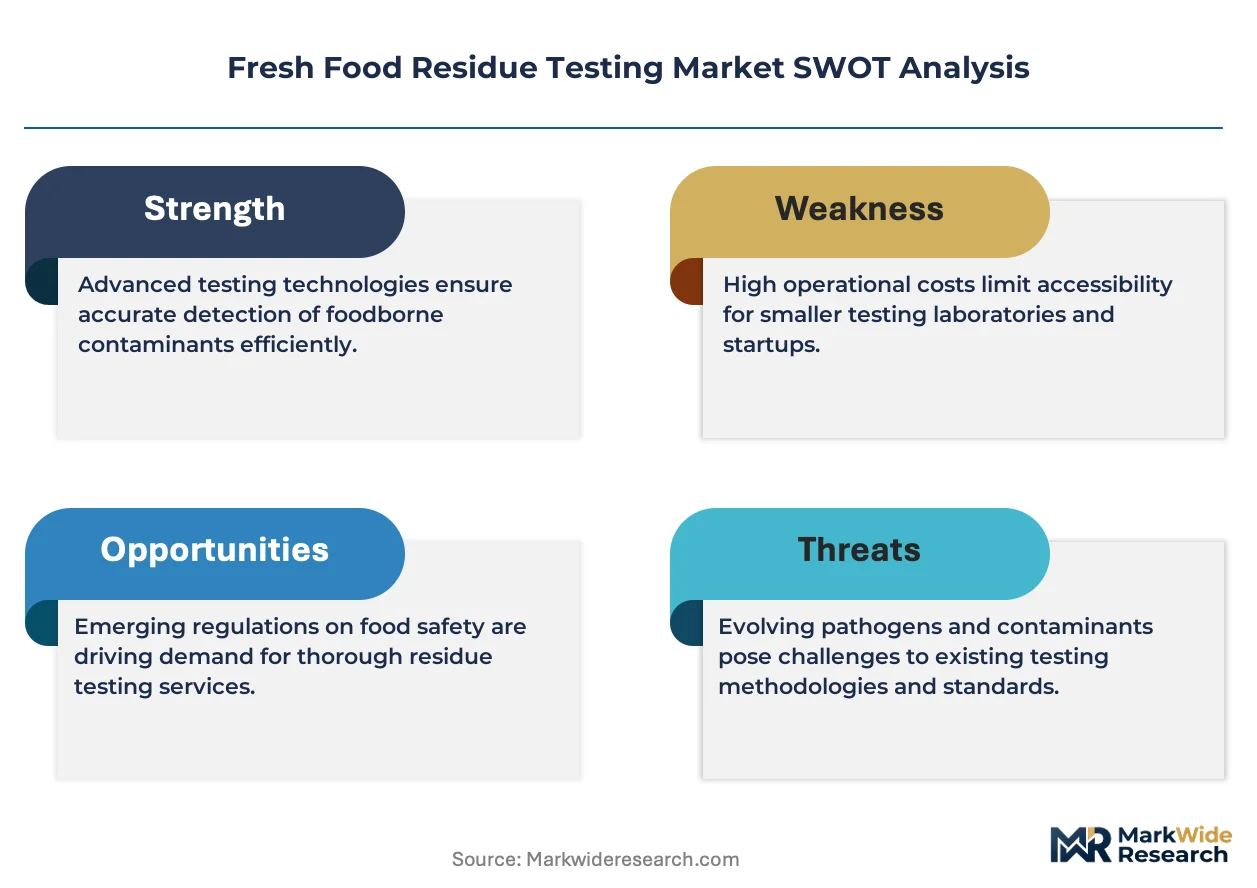
Mass spectrometry instrumentation costs are concentrating testing capacity among capital-rich laboratories, while smaller regional facilities face displacement or forced consolidation into multi-site networks.
Growth Catalysts
- EU Farm to Fork pesticide reduction mandates:Member states are expanding surveillance programs to verify compliance with 50% reduction targets, multiplying analytical sample volumes across national reference laboratories.
- Retail chain certification requirements:German supermarket operators now mandate third-party residue documentation for all fresh produce suppliers, creating contractual testing demand independent of statutory minimums.
- High-resolution mass spectrometry adoption:Orbitrap and Q-TOF platforms enable simultaneous screening of 500+ residues in single injections, replacing sequential immunoassay workflows.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems depend on helium carrier gas, with price spikes and allocation shortages disrupting laboratory operations in regions lacking alternative gas infrastructure.
- Reference standard procurement delays:Certified pesticide reference materials from national metrology institutes face 12-18 month backlogs, delaying method validation and accreditation renewal.
- Regulatory divergence between EU and Codex Alimentarius:Non-harmonized maximum residue limits force exporters to maintain dual analytical methods or abandon specific export markets.
Strategic Opportunities
- India FSSAI modernization:The Food Safety and Standards Authority is upgrading state laboratory networks with LC-MS/MS capacity, creating equipment and training service demand.
- Blockchain-integrated testing documentation:Immutable chain-of-custody records from farm to retail are attracting premium pricing from traceability-focused organic distributors.
- Biosensor-MS hybrid workflows:Electrochemical pre-screening combined with confirmatory mass spectrometry reduces instrument time per sample by 40% in high-throughput vegetable processing facilities.
Industry Challenges
- Mass spectrometry specialist scarcity:ISO 17025-accredited analytical chemists with multi-residue method development experience command salaries 35% above general laboratory staff, constraining expansion timelines.
- Legacy LIMS integration complexity:New chromatography data systems require costly middleware development to connect with decade-old laboratory information management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Food Residue Testing Market |
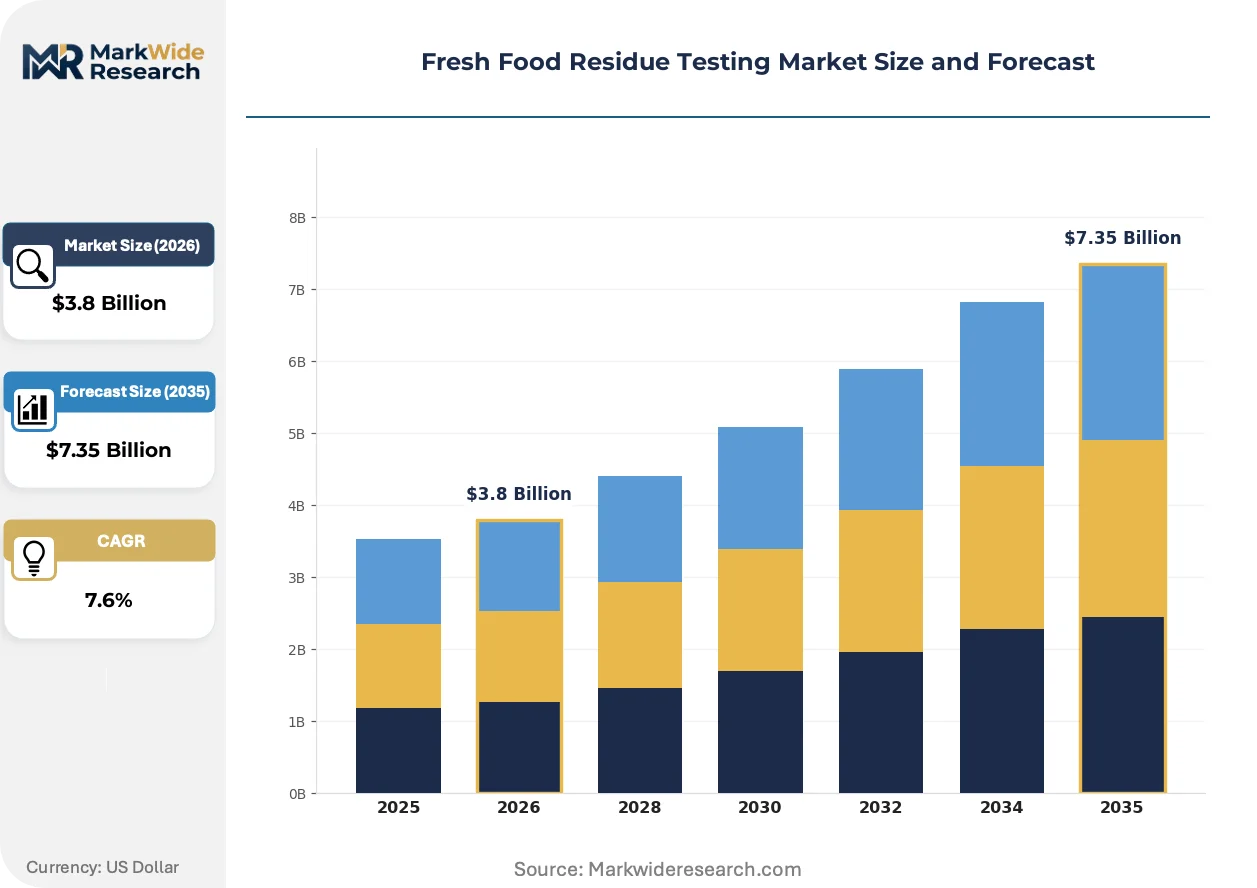
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Pesticide Testing, Heavy Metal Analysis, Microbial Testing, Quality Control Food Type: Fruits, Vegetables, Grains, Dairy End User: Food Manufacturers, Retailers, Regulatory Agencies, Research Institutions Testing Method: Mass Spectrometry, Liquid Chromatography, PCR, Immunoassay |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Shimadzu Corporation, Waters Corporation, Eurofins Scientific, SGS SA, Bureau Veritas, Intertek Group plc, Mérieux NutriSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Food Residue Testing Market Trends and Innovations
Artificial intelligence is penetrating residue data interpretation, with machine learning algorithms now flagging suspicious chromatographic patterns before human review. This automation wave is compressing turnaround times while raising questions about liability allocation for false negative releases.
High-resolution accurate mass spectrometry is bifurcating the analytical services market. Capital-intensive laboratories in the Netherlands and Switzerland are deploying full-scan HRMS for unknown screening, capturing premium pricing from organic importers seeking comprehensive contaminant profiles. Routine contract labs without such instrumentation are relegated to commodity pesticide panel testing with thin margins.
REACH chemical registration requirements are expanding the analytical target list for European laboratories. ECHA substance evaluation dossiers now mandate monitoring of transformation products and metabolites alongside parent compounds, forcing method redevelopment and reagent portfolio expansion. Specialty crop exporters to the EU are responding by pre-positioning testing capacity in Rotterdam and Hamburg port zones.
Consolidated procurement through retail buying cooperatives is squeezing independent laboratory margins. French and Belgian supermarket alliances now negotiate multi-year testing contracts with volume guarantees, displacing fragmented supplier relationships. This concentration is visible most acutely in the Benelux region, where three retail groups control 80% of fresh produce distribution.
Fresh Food Residue Testing Market Segmentation
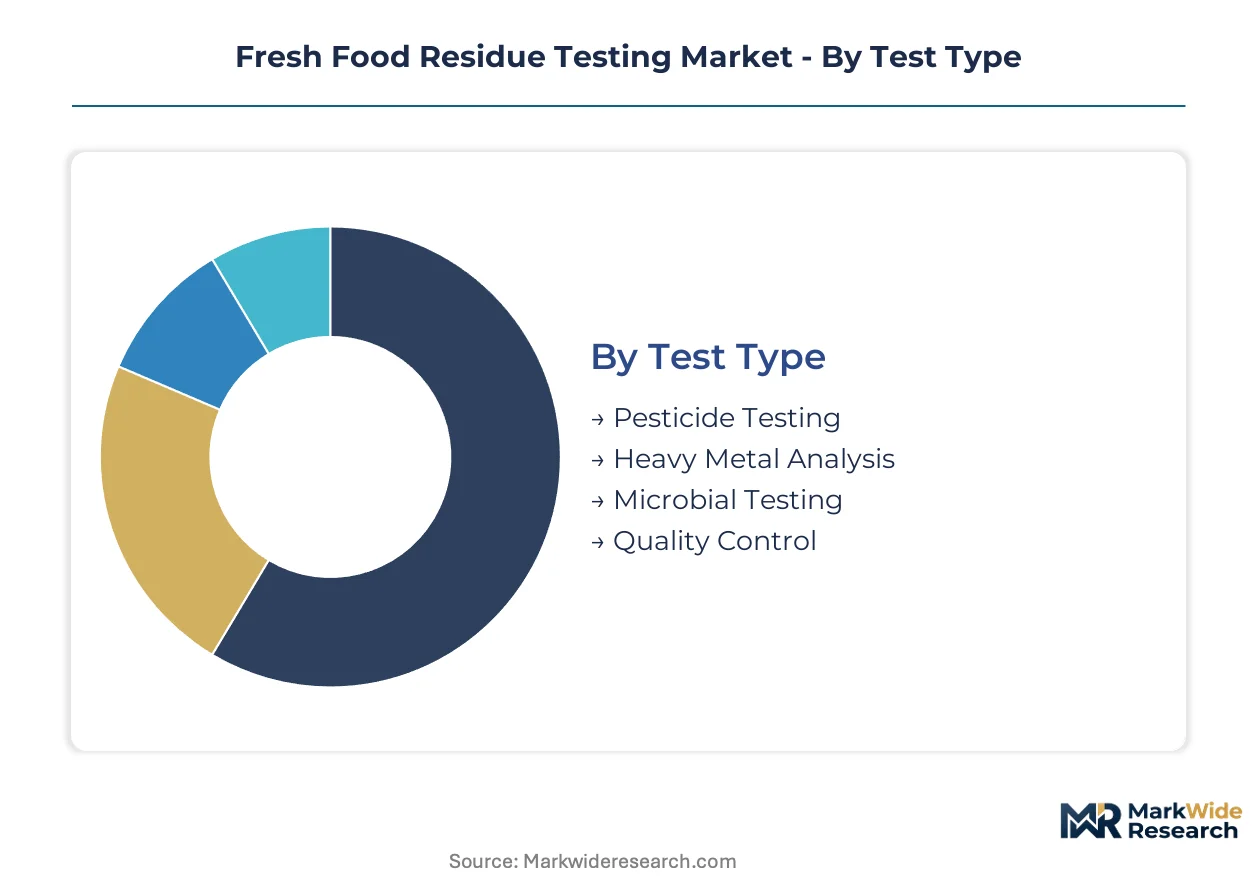
Segmentation in fresh food residue testing reflects divergent regulatory stringency across contaminant classes and the capital requirements of analytical instrumentation. Laboratories configure service portfolios around specific residue panels to secure accreditation scope and retailer contracts.
Test Type:
Regulatory differentiation between contaminant classes determines laboratory accreditation investment priorities and pricing power across residue panels.
- Pesticide Testing:Multi-residue panels detect hundreds of active ingredients simultaneously using LC-MS/MS and GC-MS/MS workflows. EFSA MRL schedules and EPA tolerance tables mandate this testing for EU and US market access, with German retail chains demanding third-party certification beyond statutory minimums.
- Heavy Metal Analysis:Atomic absorption and ICP-MS methods quantify lead, cadmium, mercury, and arsenic at parts-per-billion thresholds. Seafood and rice importers in Japan and China drive concentrated demand due to national contamination incidents and consumer litigation exposure.
- Microbial Testing:Pathogen detection for Salmonella, Listeria, and E. coli targets fresh-cut produce and sprouted seeds. Rapid PCR methods are displacing culture-based confirmation in high-volume processing facilities.
- Quality Control:Physicochemical assays measure moisture, pH, and spoilage markers to verify shelf-life specifications. Contract manufacturers serving private-label retailers maintain in-house capacity for routine release testing.
Pesticide testing handles the majority of throughput; microbial testing is gaining share fastest as ready-to-eat salad consumption expands.
Food Type:
Perishability and contamination risk profiles create tiered pricing structures across commodity categories.
- Fruits:Berry and citrus imports face intensive organophosphate and fungicide screening at EU border control posts. Spanish and Italian stone fruit exporters pre-position testing capacity in Rotterdam to accelerate customs clearance.
- Vegetables:Leafy greens and brassicas absorb systemic pesticides and accumulate heavy metals from soil. California's Central Valley vegetable processors negotiate multi-year testing contracts with ISO-accredited laboratories.
- Grains:Mycotoxin and pesticide residue testing protects flour milling and brewing supply chains. Ukrainian and Argentine grain exporters to the EU require dual-method validation for aflatoxin and ochratoxin panels.
- Dairy:Antibiotic and hormone residue testing commands premium pricing due to perishable logistics demanding 24-hour turnaround. Dutch and Irish dairy cooperatives operate captive laboratories at processing plants.
Vegetables generate the highest sample volumes; dairy commands the steepest per-test pricing premiums.
End User:
Procurement authority and compliance liability distribute testing demand across distinct organizational archetypes.
- Food Manufacturers:Integrated processors of canned, frozen, and dried products maintain in-house chromatography capacity for HACCP verification. Nestlé and Unilever operate centralized analytical facilities serving multiple production sites.
- Retailers:Supermarket chains impose contractual residue limits stricter than regulatory minimums to protect brand equity. French and Belgian buying cooperatives consolidate testing procurement across affiliated stores.
- Regulatory Agencies:National reference laboratories conduct surveillance sampling and method validation under ISO 17025. India's FSSAI is upgrading state laboratory networks with LC-MS/MS instrumentation.
- Research Institutions:Universities and agricultural extension services develop novel detection methods and monitor emerging contaminants. Wageningen University and ETH Zurich publish reference methods adopted by commercial laboratories.
Retailers are expanding testing mandates fastest; regulatory agencies anchor method standardization.
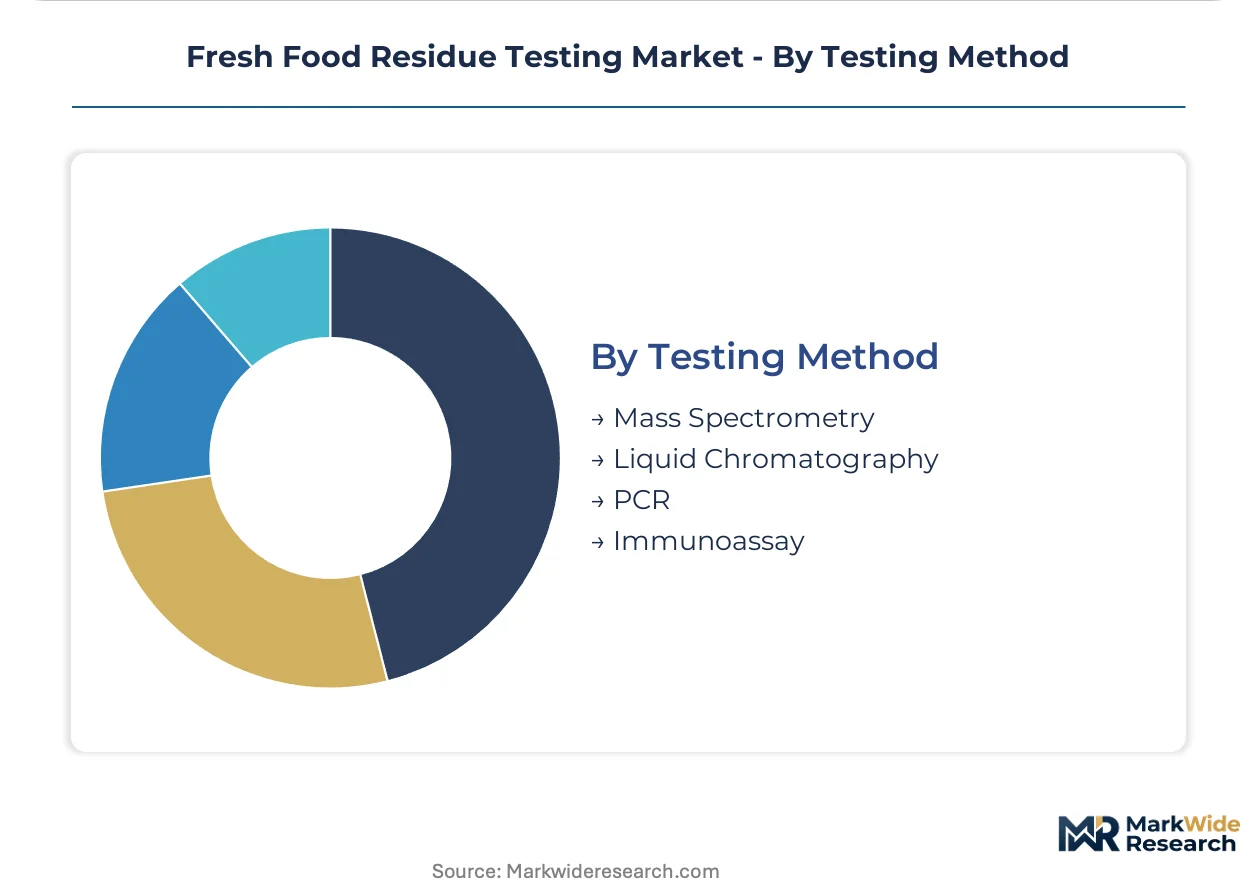
Testing Method:
Capital intensity and analytical capability stratify the competitive landscape between instrument classes.
- Mass Spectrometry:LC-MS/MS, GC-MS/MS, and high-resolution Orbitrap platforms enable simultaneous quantification of 500+ residues. Thermo Fisher and Agilent dominate instrument supply to high-throughput screening facilities.
- Liquid Chromatography:HPLC with UV or fluorescence detection remains cost-effective for single-analyte panels in resource-constrained settings. Brazilian and Indian regional laboratories rely on this technology for routine compliance.
- PCR:Nucleic acid amplification targets pathogen DNA and genetically modified organism sequences. Rapid cycling instruments reduce microbial confirmation from days to hours.
- Immunoassay:ELISA and lateral flow devices provide cost-effective pre-screening before confirmatory chromatography. Field-deployable kits support farm-gate testing in remote sourcing regions.
Mass spectrometry absorbs the largest capital investment; PCR is climbing fastest on share as pathogen detection expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany applies residue testing most intensively for retail certification, while India deploys it primarily for regulatory modernization and export compliance. The United States balances statutory enforcement with private-label brand protection. China focuses on import screening and domestic food safety incidents. Brazil concentrates on export-oriented pre-clearance for EU-bound agricultural commodities.
Germany
German supermarket chains mandate third-party residue documentation beyond EU statutory minimums, creating contractual testing demand independent of regulatory surveillance. The EU Green Deal and Farm to Fork Strategy drive 50% pesticide reduction targets that laboratories must verify through expanded sample volumes. Testing capacity concentrates in Hamburg and Rotterdam port zones where Spanish and Italian exporters pre-position analytical services.
United States
Food manufacturers maintain in-house chromatography capacity for HACCP verification while retailers impose stricter contractual limits than FDA enforcement requires. The EPA and FDA enforce pesticide tolerance levels under FIFRA, with California's Central Valley vegetable processors negotiating multi-year testing contracts. Greater Boston and Pacific Northwest clusters host centralized analytical facilities serving multiple production sites.
India
The FSSAI is upgrading state laboratory networks with LC-MS/MS capacity, creating equipment and training service demand for export-oriented agricultural sectors. Maharashtra and Gujarat house the densest concentration of ISO-accredited facilities supporting spice and rice exporters to the EU. Telangana and Karnataka are emerging as secondary hubs for pharmaceutical residue testing tied to active pharmaceutical ingredient manufacturing.
China
SAMR and national food safety standards mandate expanded surveillance following domestic contamination incidents, concentrating demand in Yangtze River Delta import inspection points. Shanghai and Ningbo customs laboratories deploy high-resolution mass spectrometry for unknown screening of organic imports. Pearl River Delta vegetable processors are adopting rapid PCR methods for pathogen detection in ready-to-eat salad supply chains.
Brazil
São Paulo and Paraná agricultural cooperatives maintain captive testing capacity for soy and coffee exports facing EU MRL compliance requirements. ANVISA registration requirements and EU border control post inspections force dual-method validation investments. Minas Gerais dairy processors command premium pricing for 24-hour antibiotic residue turnaround due to perishable logistics constraints.
Fresh Food Residue Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-rich laboratories consolidating testing capacity while regional facilities face displacement or forced network integration. Thermo Fisher Scientific and Agilent Technologies anchor the instrument supply segment, dominating chromatography platform sales to high-throughput screening facilities. Three strategic archetypes define competitive positioning: integrated multi-service conglomerates bundling audit and testing workflows, pure-play analytical laboratories competing on accreditation scope and turnaround speed, and instrument manufacturers capturing recurring consumables revenue through installed base expansion. Dominant competitive moves include geographic density expansion through laboratory acquisitions and technology licensing partnerships that embed vendor platforms into retailer-mandated testing protocols.
Among integrated testing service providers, Eurofins Scientific, SGS SA, and Bureau Veritas exemplify the multi-service conglomerate archetype through geographic coverage and bundled service offerings. Eurofins Scientific occupies a position defined by ISO-accredited lab density across premium produce sourcing regions. SGS SA anchors the farm-to-retail audit integration segment, reducing procurement complexity for multinational food manufacturers. Bureau Veritas sits within the certification and compliance verification tier, leveraging its global inspection infrastructure to capture cross-border trade testing demand.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Shimadzu Corporation |
| Waters Corporation |
| Eurofins Scientific |
| SGS SA |
| Bureau Veritas |
| Intertek Group plc |
| Mérieux NutriSciences |
| Others |
Pricing and Supply Chain Analysis
Helium-to-hydrogen carrier gas substitution in chromatography systems is redistributing testing capacity toward regions with alternative gas infrastructure while compressing margins for laboratories locked into legacy GC-MS configurations. This input transition simultaneously elevates capital requirements for instrument retrofitting and creates geographic arbitrage in per-test pricing between established and emerging laboratory clusters.
Pricing Analysis
Long-term multi-year offtake contracts dominate procurement between retail buying cooperatives and ISO-accredited laboratories, displacing spot transactional arrangements in Germany and the Benelux. Pricing stratifies across premium, standard, and economy tiers based on accreditation scope and turnaround guarantees, with dairy residue panels commanding steepest premiums due to perishable logistics. Cost compression in commodity pesticide screening intensifies because consolidated retail procurement squeezes independent laboratory margins. Small regional facilities exhibit highest price sensitivity, while capital-rich multi-site networks absorb volume discounts without margin erosion.
Supply Chain Analysis
Just-in-time reagent procurement prevails among high-throughput screening facilities, though strategic stockpiling of certified reference materials is spreading amid 12-18 month backlogs from national metrology institutes. Supply concentrates in Germany, the Netherlands, and Switzerland for high-resolution mass spectrometry instrumentation, while India and Brazil anchor regional reagent formulation. The supply chain rests on helium and high-purity solvent inputs alongside specialized chromatography columns. Single-source vulnerability in reference standard production creates accreditation renewal risk. Distribution runs through port-zone laboratory clusters in Rotterdam and Hamburg serving pre-clearance export workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025-accredited analytical chemists with multi-residue method development expertise command compensation premiums that constrain laboratory expansion timelines, making human capital the binding constraint on market growth rather than instrument availability.
For Market Incumbents: Secure preferred supplier status with retail buying cooperatives through geographic density expansion in Rotterdam and Hamburg port zones. Defend margin position by embedding mass spectrometry platforms into retailer-mandated testing protocols via technology licensing partnerships that create switching costs for contract laboratories. For New Entrants and Emerging Players: Anchor in India's FSSAI laboratory modernization program, where state network upgrades create equipment and training service white space absent incumbent saturation. Target blockchain-integrated testing documentation for organic distributors seeking immutable chain-of-custody records, leveraging this traceability angle to bypass established commodity pesticide screening competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed analytical laboratory networks that consolidated regional facilities but now face helium supply volatility and specialist scarcity compressing EBITDA margins. Platform investments in biosensor-MS hybrid workflows offer 5-10 year viability given 40% instrument time reduction potential. Monitor EFSA MRL schedule expansion velocity as inflection signal for reagent demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Acquisition | Eurofins and SGS capture ISO-accredited facility density in premium produce sourcing regions. |
| Technology Licensing Partnership | Thermo Fisher embeds Orbitrap platforms into German retailer-mandated testing protocols. |
| Geographic Expansion | Indian state laboratories deploy LC-MS/MS capacity under FSSAI modernization funding. |
| Backward Integration | Dutch dairy cooperatives operate captive laboratories to secure 24-hour turnaround guarantees. |
| Platform Integration | Blockchain-integrated testing documentation attracts premium pricing from organic distributors. |
Research Methodology
Cross-validation between primary interviews with laboratory directors and regulatory affairs specialists and secondary validation through EFSA scientific opinions and EPA tolerance tables anchors the qualitative findings. Conversations with mass spectrometry instrument procurement officers, ISO 17025 accreditation auditors, retail category buyers, and reagent supply chain managers informed operational constraints. Secondary sources include customs data on chromatography instrument imports, SEC filings from listed testing service providers, FSSAI laboratory upgrade announcements, and EU Green Deal implementation progress reports. Bottom-up testing volume estimates triangulate against top-down market value reconstructions.
Sensitivity analysis around helium price volatility and reference material availability shapes the projection framework across the analysis window. Segmentation dimensions modeled include contaminant class, food category perishability, end-user procurement authority, and analytical method capital intensity. CAGRs derive from laboratory capacity expansion announcements and retail chain certification mandate adoption curves. Industry-specific inputs incorporate EFSA MRL harmonization negotiations and FSSAI state laboratory network upgrade timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Farm to Fork enforcement and stable helium supply allocation; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside projected retail certification expansion and mass spectrometry specialist labor market tightness. Revision becomes warranted when EFSA-Codex Alimentarius MRL divergence crosses thresholds forcing dual-method validation investments or market exclusion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Amylase Testing Market