
 Street Vendors Market | 2026-2036
Street Vendors Market Size, Share, and Industry Trends Forecast 2026-2036
Street Vendors Market Outlook
Multi-source procurement of mobile kitchen equipment and branded food concepts is expanding as vendors diversify beyond single-cart operations. Halal Guys leverages its brick-and-mortar expansion model to sustain brand recognition across fixed and mobile formats. Kogi BBQ anchors the Korean-Mexican fusion segment through social-media-driven route scheduling. Coolhaus competes on artisanal ice cream sandwiches with proprietary recipes and co-branded retail partnerships.
Street vendors are independent mobile or semi-fixed commercial operators selling prepared food, beverages, or goods directly to consumers in public spaces, typically utilizing compact equipment with rapid setup and breakdown cycles designed for high-turnover, low-overhead service. The primary purpose is delivering affordable, convenient consumption options in dense pedestrian corridors where permanent retail infrastructure is limited or cost-prohibitive. Food trucks within the service type dimension dominate margin pools due to higher average transaction values and menu complexity, while pop-up stalls lead volume in emerging markets where capital barriers remain lowest. Mobile vendors specializing in beverage service occupy the fastest-growing structural position as coffee and fresh-juice concepts attract younger demographics.
FDA food code standards and municipal health department permitting shape operational compliance costs and market access thresholds across United States jurisdictions. India's FSSAI licensing requirements and local municipal corporation vending committees determine zone allocation and hygiene certification for street food entrepreneurs. Brazil's ANVISA sanitary surveillance protocols and municipal prefecture concession systems regulate equipment specifications and operating hours. Stakeholders must monitor evolving digitization of permit applications and real-time location tracking requirements that will reshape competitive dynamics between informal operators and formalized vendor networks.
Market Dynamics
Municipal digitization of vendor permitting is compressing approval timelines while tightening real-time location tracking requirements, forcing informal operators toward formalized network structures or exit.
Growth Catalysts
- Transit-adjacent zoning liberalization:Urban planners in Brazil, Thailand, and India are designating high-footfall corridors near metro stations and university districts for semi-fixed vendor placement, expanding addressable demand pools.
- FSSAI certification digitization:India's centralized food safety licensing platform reduces compliance friction for street food entrepreneurs, accelerating formalization of previously informal operators.
- Mobile kitchen equipment leasing:Specialized finance providers are deploying asset-light procurement models that lower capital barriers for multi-cart expansion beyond single-unit operations.
Market Restraints
- Stainless steel and LPG input volatility:Mobile kitchen fabrication depends on commodity metals and fuel systems whose price swings compress equipment margins and extend replacement cycles.
- ANVISA equipment specification rigidity:Brazil's sanitary surveillance protocols mandate fixed design standards that limit vendor customization flexibility and slow format innovation.
- Permanent retail substitution in premium zones:Shopping mall food courts and cloud kitchen aggregators are capturing transaction volume in dense metropolitan corridors where street vendors face permit caps.
Strategic Opportunities
- Festival circuit route optimization:Mobile vendors leveraging GPS-enabled scheduling algorithms can capture episodic demand spikes at music and cultural events across India and Brazil's seasonal calendar.
- Co-branded retail partnerships:Artisanal concepts are securing fixed-location placement within grocery and convenience chains, creating hybrid fixed-mobile revenue architectures.
- Municipal smart city integration:Real-time occupancy sensors and digital payment rails in Thai and Indian cities enable dynamic zone allocation that rewards high-compliance vendors with preferential positioning.
Industry Challenges
- Food safety auditor certification scarcity:Qualified hygiene inspectors are concentrated in major metropolitan areas, creating compliance bottlenecks for vendors expanding into secondary cities.
- Permit-to-operation timeline compression:Municipal vending committees in India and Brazil maintain multi-month approval windows that mismatch working capital cycles and seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street Vendors Market |
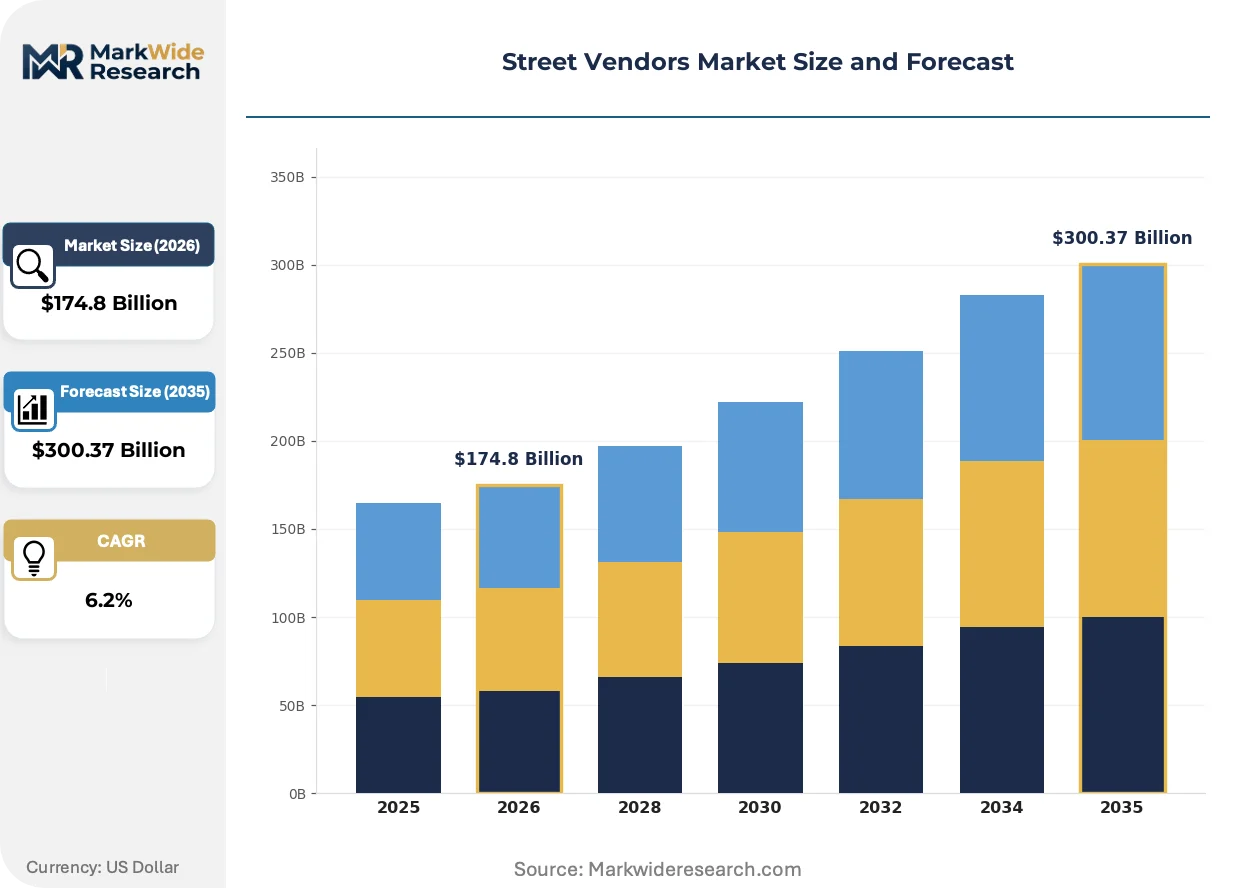
| Market Size in 2026 | $174.8 Billion |
| Market Size in 2035 | $300.37 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverages, Crafts, Accessories Service Type: Mobile Vendors, Pop-up Stalls, Food Trucks, Market Stands Customer Type: Local Residents, Tourists, Students, Office Workers Distribution Channel: Street Markets, Festivals, Parking Lots, Events |
| Companies Covered | Roaming Hunger, Wafels & Dinges, Dippin' Dots, Big Gay Ice Cream, Coolhaus, Halal Guys, Curry Up Now, Mister Softee, Kogi BBQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street Vendors Market Strategic Shifts
Digital route management and embedded payment infrastructure are reconfiguring how mobile vendors capture demand, shifting competitive advantage from location intuition toward data-driven positioning algorithms.
Solar-assisted refrigeration and battery-powered cooking systems are expanding into beverage and frozen dessert segments previously constrained by generator noise and fuel logistics. Younger vendor cohorts in Thai and Brazilian urban markets are adopting these systems faster than established operators, compressing the technical viability gap between food trucks and lighter pop-up formats.
FDA food code modernization and municipal health department digitization are mandating real-time temperature logging and GPS traceability for licensed mobile operators. The industrial consequence is a compliance cost wedge favoring networked vendor fleets with centralized back-office infrastructure over solo operators. Food truck segments in US jurisdictions with active digitization mandates are consolidating permit holdings faster than pop-up and cart formats.
Consumer preference for Instagram-optimized presentation and transparent ingredient sourcing is rotating demand toward vendors with visible preparation theater and documented supply chain provenance. University districts and festival circuits are rewarding concepts that invest in aesthetic differentiation and narrative packaging, displacing purely price-driven selection criteria in these channels. This shift is most visible in Brazilian and Indian metropolitan youth corridors where social media discovery drives trial behavior.
Street Vendors Market Segmentation
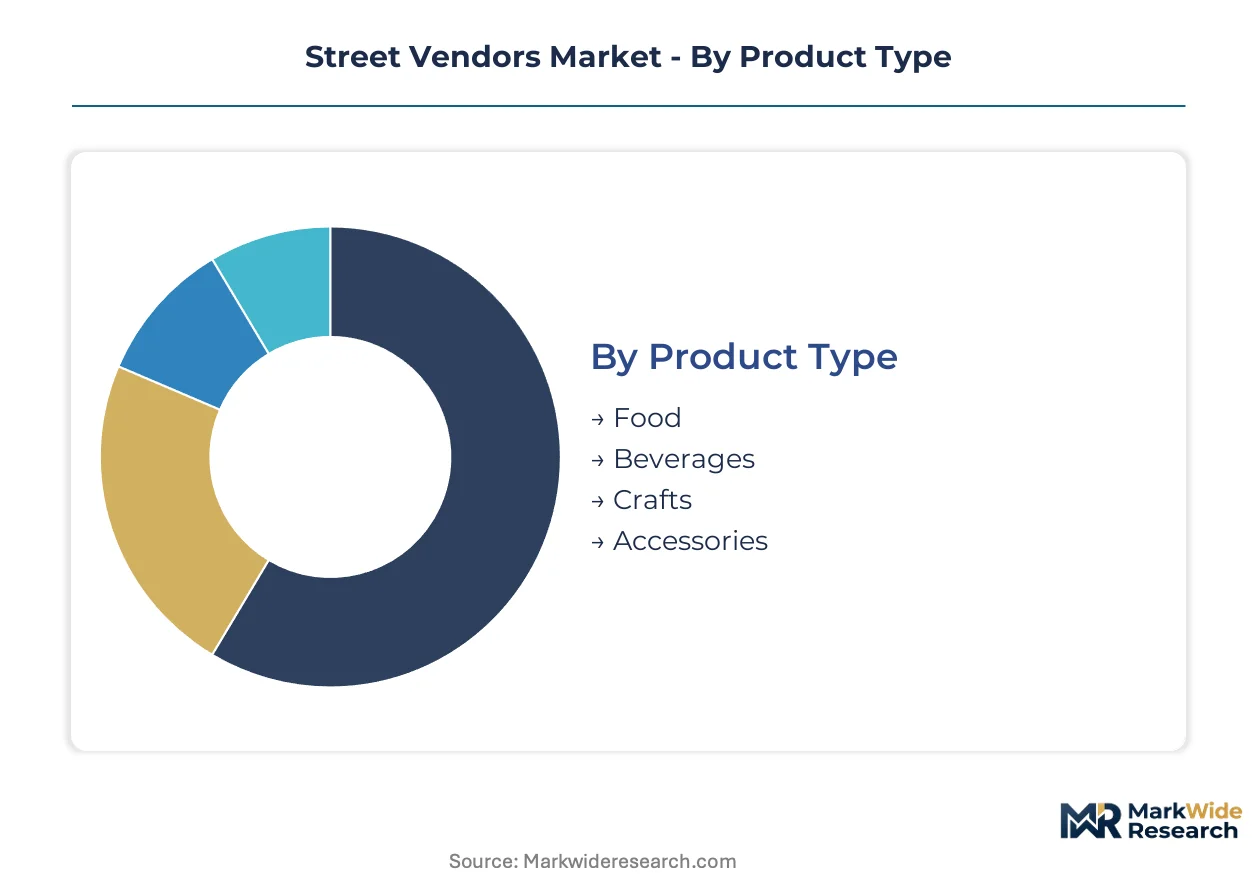
Street vendor segmentation reveals how capital intensity, mobility constraints, and customer occasion shape profitability. Each dimension carries distinct regulatory exposure and route optimization requirements that determine competitive viability across urban corridors.
Product Type:
Buyers differentiate by margin structure and perishability risk rather than purchase frequency alone.
- Food:Prepared meals and snacks dominate transaction volume with highest average ticket values. Demand concentrates near transit hubs in India and Brazil where FSSAI and ANVISA compliance costs filter out informal operators.
- Beverages:Coffee, fresh juice, and specialty drinks attract younger demographics with lowest capital barriers. Solar-assisted refrigeration is expanding technical viability in Thai urban markets faster than established formats.
- Crafts:Handcrafted goods and artisan products occupy episodic demand windows at festival circuits and cultural events. Inventory holding costs and seasonal revenue concentration define vendor economics.
- Accessories:Mobile phone accessories, jewelry, and fashion items operate on rapid inventory turnover with minimal equipment investment. Price competition from e-commerce aggregators compresses margins in dense metropolitan zones.
Volume sits with Food; growth tilts toward Beverages.
Service Type:
Format selection traces working capital availability and regulatory tolerance across vendor cohorts.
- Mobile Vendors:Lightweight carts and walking sellers achieve lowest entry barriers with rapid relocation flexibility. Battery-powered cooking systems are compressing the viability gap against heavier formats in Brazilian youth corridors.
- Food Trucks:Self-contained kitchens with full equipment suites command premium positioning and menu complexity. GPS-enabled route scheduling captures episodic demand spikes at music festivals across India and Brazil.
- Pop-up Stalls:Semi-fixed structures with rapid assembly cycles lead emerging market volume where permit digitization remains incomplete. Municipal zoning liberalization near university districts is expanding addressable placement.
- Market Stands:Designated positions within organized street markets offer customer traffic predictability with reduced mobility. Real-time occupancy sensors in Thai smart city pilots reward high-compliance vendors with preferential positioning.
Revenue concentrates in Food Trucks; format innovation is accelerating most quickly in Mobile Vendors.
Customer Type:
Purchase occasion and price sensitivity separate segments more than demographic labels alone.
- Local Residents:Repeat purchase behavior and relationship-driven vendor selection characterize neighborhood corridor economics. Loyalty formation depends on consistent location presence and transparent ingredient sourcing.
- Tourists:Experience-seeking visitors prioritize Instagram-optimized presentation and narrative packaging over price. Social media discovery drives trial behavior in Brazilian and Indian metropolitan tourism districts.
- Students:University district concentration creates dense demand pools with high snack-frequency and limited budgets. Aesthetic differentiation and visible preparation theater displace purely price-driven selection.
- Office Workers:Compressed lunch windows and convenience prioritization support premium pricing for speed and quality. Cloud kitchen aggregators are capturing transaction volume in dense corridors where street vendors face permit caps.
Transaction frequency peaks with Local Residents; margin expansion tilts toward Tourists.
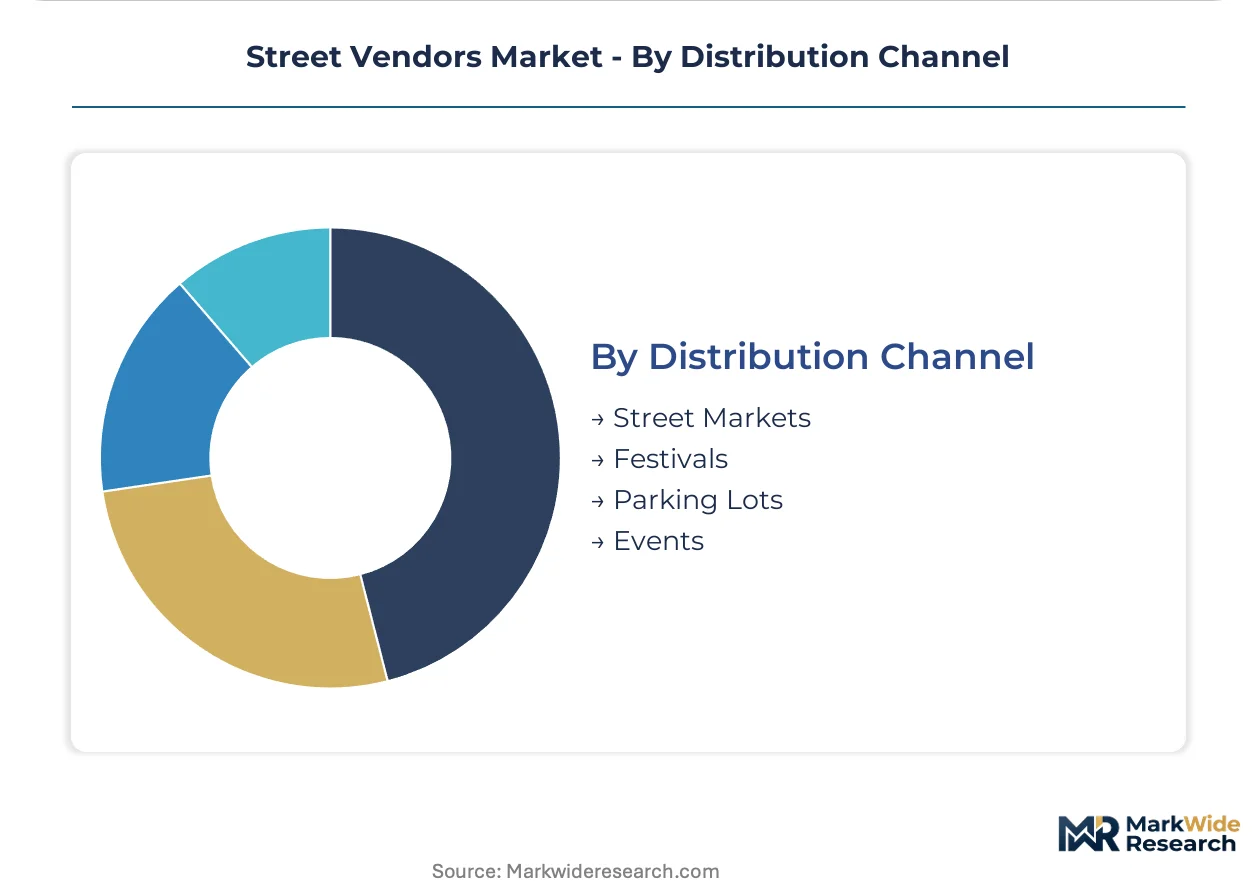
Distribution Channel:
Channel access determines demand predictability and regulatory compliance intensity.
- Street Markets:Organized vendor clusters with municipal designation offer footfall concentration and infrastructure sharing. ANVISA equipment specification rigidity in Brazil limits customization flexibility within these zones.
- Festivals:Episodic high-density events generate revenue spikes requiring specialized route optimization algorithms. GPS-enabled scheduling is reconfiguring competitive advantage from location intuition toward data-driven positioning.
- Parking Lots:Transit-adjacent and commercial periphery placement captures automobile-accessible demand with lower rent structures. Zoning enforcement variability creates operational uncertainty across jurisdictions.
- Events:Corporate gatherings, sports fixtures, and private functions provide contracted revenue with advance planning requirements. Permit-to-operation timeline compression mismatches working capital cycles and seasonal demand windows.
Volume aggregates in Street Markets; revenue volatility is highest in Festivals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LPG supply corridors in Gujarat and stainless steel fabrication clusters in São Paulo anchor equipment sourcing for mobile kitchen manufacturers serving vendor networks across high-growth urban corridors.
United States
Festival circuit density and transit-adjacent zoning liberalization drive demand concentration in Austin, Portland, and Los Angeles. FDA food code digitization mandates real-time temperature logging and GPS traceability, elevating compliance costs. The Halal Guys exemplifies brick-and-mortar expansion sustaining brand recognition across fixed and mobile formats in dense metropolitan zones.
India
University district footfall and railway station corridor density create addressable demand pools in Mumbai, Delhi, and Bangalore. FSSAI certification digitization accelerates formalization of previously informal operators through centralized licensing platforms. Solar-assisted refrigeration adoption is compressing technical viability gaps in beverage-focused vendor cohorts.
Brazil
ANVISA equipment specification rigidity shapes mobile kitchen fabrication standards while restricting customization flexibility for vendors in São Paulo and Rio de Janeiro. Municipal prefecture concession systems regulate operating hours and zone allocation. Battery-powered cooking systems are penetrating youth corridors faster than established operator cohorts.
Thailand
Smart city integration pilots in Bangkok deploy real-time occupancy sensors and digital payment rails enabling dynamic zone allocation. Younger vendor demographics adopt solar-assisted refrigeration faster than legacy operators. High-compliance vendors receive preferential positioning through municipal digitization programs.
Germany
CE marking requirements and municipal health department digitization shape equipment import standards for mobile kitchen fabricators serving Berlin and Munich clusters. Festival circuit route optimization algorithms capture episodic demand at music and cultural events. Co-branded retail partnerships with grocery chains create hybrid fixed-mobile revenue architectures.
Street Vendors Market Competitive Environment
Portfolio diversification dominates the current landscape as vendors expand beyond single-cart operations into multi-unit networks and hybrid fixed-mobile formats. The market structure fragments across solo operators, networked fleets, and brick-and-mortar-backed mobile concepts. Three archetypes define positioning: social-media-native fusion brands, artisanal specialty concepts, and legacy ice cream and snack specialists. Geographic expansion through festival circuit penetration and strategic partnerships with municipal smart city programs constitute the dominant competitive vectors.
Among US-based mobile food specialists, Kogi BBQ and Coolhaus exemplify contrasting archetype positioning. Kogi BBQ anchors the Korean-Mexican fusion segment through social-media-driven route scheduling and episodic demand capture. Coolhaus occupies the artisanal ice cream sandwich tier through proprietary recipes and co-branded retail partnerships with grocery chains. Halal Guys represents the brick-and-mortar-backed mobile expansion model, leveraging fixed-location brand recognition to sustain cross-format presence.
| Leading Market Players |
|---|
| Roaming Hunger |
| Wafels & Dinges |
| Dippin' Dots |
| Big Gay Ice Cream |
| Coolhaus |
| Halal Guys |
| Curry Up Now |
| Mister Softee |
| Kogi BBQ |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FSSAI-licensed food trucks and unregistered pop-up carts manifests in both pricing power and sourcing configurations across Indian metropolitan corridors. Premium-tier vendors bundle real-time GPS traceability and temperature logging into service contracts, while economy operators absorb commodity volatility in stainless steel and LPG inputs without pricing recourse.
Pricing Analysis
Warranty and maintenance bundling separates food truck leasing packages from bare-equipment procurement for pop-up stalls. Three-tier pricing structure across premium, standard, and economy levels reflects FSSAI certification status, equipment specification tier, and route optimization software inclusion. Pricing pressure stems from cloud kitchen aggregators capturing office-worker lunch volume in permit-capped zones. Students and local residents exhibit highest price sensitivity; tourists and corporate event buyers show lowest.
Supply Chain Analysis
Domestic-content mandates in Brazil's ANVISA equipment specifications and India's FSSAI fabrication standards are reshaping mobile kitchen sourcing toward local stainless steel clusters in São Paulo and Gujarat. Component dependencies center on LPG fuel systems, battery-powered cooking modules, and solar-assisted refrigeration units. Single-source vulnerability concentrates in Chinese-manufactured battery cells. Distribution runs through municipal vending committee allocations and specialized equipment leasing networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FSSAI digitization and ANVISA specification rigidity erect barrier-to-entry moats favoring capitalized, networked vendor fleets over solo operators.
For Market Incumbents: Deepen backward integration into equipment leasing subsidiaries to capture margin pools currently flowing to third-party finance providers. Fortify permit holdings through municipal smart city partnerships in Thai and Indian pilot cities before zoning liberalization saturates high-footfall corridors. Cloud kitchen substitution in premium office districts represents the primary demand threat. For New Entrants and Emerging Players: Launch via festival circuit route optimization algorithms targeting episodic demand spikes in Brazilian and Indian seasonal calendars. Beverage-focused mobile formats with solar-assisted refrigeration offer lowest capital barriers and fastest payback cycles in university districts. Co-branded retail partnerships with grocery chains provide hybrid fixed-mobile revenue architectures. For Investors and Strategic Acquirers: Re-rating potential sits with networked vendor fleets possessing centralized back-office infrastructure given FDA and FSSAI digitization mandates elevating compliance costs. Long-term viability favors operators with multi-unit density across transit-adjacent zones. Monitor municipal permitting timeline compression as inflection signal for working capital stress among informal operators.| Strategic Initiative | Industry Significance |
|---|---|
| Festival Circuit Route Optimization | GPS-enabled scheduling algorithms capture episodic demand spikes at Brazilian music events. |
| Co-Branded Retail Partnerships | Artisanal concepts secure fixed-location placement within Thai and Indian grocery chains. |
| Municipal Smart City Integration | Real-time occupancy sensors in Bangkok reward FSSAI-compliant vendors with preferential positioning. |
| Mobile Kitchen Equipment Leasing | Asset-light procurement models lower capital barriers for multi-cart expansion beyond single units. |
| Solar-Assisted Refrigeration Adoption | Battery-powered cooling systems expand technical viability for beverage vendors in São Paulo youth corridors. |
Study Parameters
Multi-period observation of municipal permitting timelines, equipment procurement patterns, and vendor formalization rates anchored the trend analysis, supplemented by interviews with street vendor association leaders, mobile kitchen fabricators, municipal health department officials, and food safety auditors. Secondary validation drew from FSSAI licensing databases, ANVISA equipment specification filings, municipal vending committee records, and smart city pilot program disclosures. Bottom-up vendor census data triangulated against top-down hospitality sector expenditure estimates.
Input-output matrices mapped product type, service format, customer occasion, and distribution channel segmentation across the projection horizon. CAGRs were derived from trend extrapolation of formalization rates, zoning liberalization schedules, and equipment cost curves. Industry-specific forecast inputs included FSSAI digitization rollout pace, ANVISA specification amendment cycles, and solar-assisted refrigeration adoption curves in Thai and Brazilian urban markets.
Regulatory enforcement variance, commodity price volatility in stainless steel and LPG, and permit-to-operation timeline compression are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Restaurant Griddle Market
Food Service
Malaysia Food Service Market
Food Service
Virtual Kitchen Market
Food Service
Restaurants in Belgium Market
Food Service
Steam Tables and Food Well Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Food Trays Market
Food Service
Inflight Catering Market
Food Service
Pizza Foodservice Market
Food Service
Commercial Air Fryer Market
Food Service
US Food Trucks Services Market
Food Service
Contract Catering Market
Food Service
Bangladesh Food Service Market
Food Service
Workplace Service Market
Food Service
Catering Food Warmers Market