
 Portion Cups Market | 2026-2036
Portion Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Portion Cups Market Intelligence
A strategic shift from single-vendor sourcing to multi-vendor procurement models is broadening supply chain resilience for large foodservice chains. Pactiv Evergreen Inc. leverages its extensive North American manufacturing scale to serve major national accounts. Huhtamäki Oyj specializes in innovative fiber-based and sustainable packaging solutions across Europe and Asia. Dart Container Corporation competes on a vast product portfolio, including foam and plastic options, catering to diverse price points.
Portion cups are small, single-serving containers, typically manufactured from plastic, paper, or aluminum through processes like thermoforming or injection molding. These containers are engineered for precise portion control of sauces, dressings, and medications in commercial and clinical settings. Plastic materials currently dominate due to cost-effectiveness, but biodegradable alternatives are showing significant uptake. The foodservice application holds the largest share, while the pharmaceutical segment requires higher-grade, sterilized products.
Food-contact material regulations, including standards set by the US FDA and the European Union's EFSA, dictate material safety and migration limits. Environmental mandates like the EU's Single-Use Plastics Directive and China's dual carbon goals are accelerating the shift toward recyclable or compostable materials. Navigating these divergent regulatory pressures on hygiene, cost, and sustainability will define future material development strategies for all manufacturers.
Market Dynamics
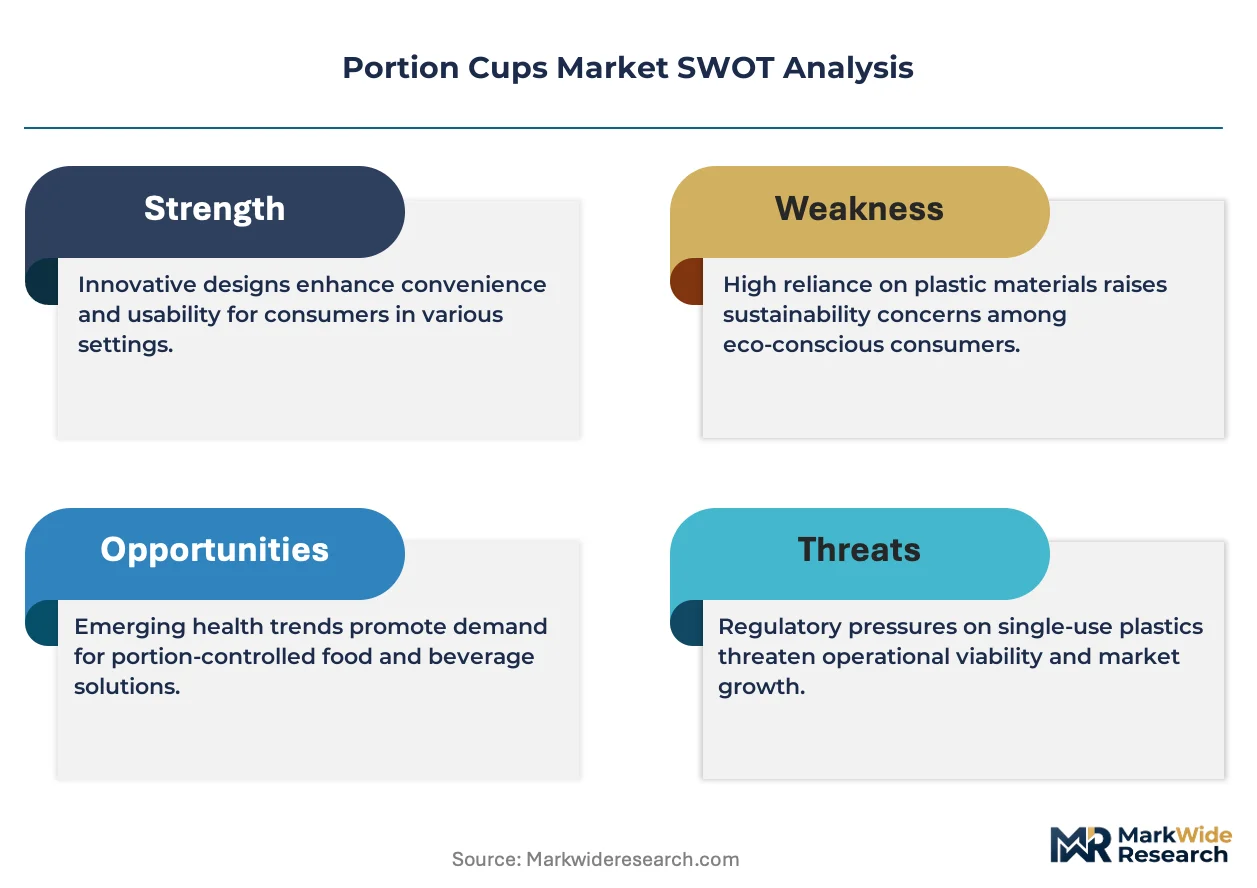
The central structural force shaping the portion cup market is the direct conflict between the historical dominance of low-cost, petroleum-based plastics and the escalating regulatory and consumer pressure for sustainable, circular material alternatives like PLA and molded fiber.
Growth Catalysts
- Food Delivery Expansion:The rapid growth of the food delivery ecosystem, particularly in dense urban centers across India and Southeast Asia, creates sustained demand for single-serving containers for condiments, sauces, and sides.
- Clinical Portion Control:A heightened focus on hygiene and precise dosage in healthcare drives adoption in clinical and pharmaceutical settings for medication distribution, where single-use, sterilized cups prevent cross-contamination.
- Biodegradable Polymer Innovation:Advances in materials science, specifically with polylactic acid (PLA) and polyhydroxyalkanoates (PHA), are improving the performance and cost-competitiveness of compostable alternatives to traditional plastics like polystyrene and polypropylene.
Market Restraints
- Resin Price Volatility:The market's cost structure is highly sensitive to fluctuations in the price of polymer resins, including polypropylene and PET, which are tied to volatile petrochemical feedstock markets.
- Performance Gaps in Alternatives:Certain biodegradable and paper-based materials exhibit lower tolerance to heat, moisture, and acidic contents compared to their plastic counterparts, limiting their application for some hot-fill or long-shelf-life products.
- Substitution from Flexible Packaging:Low-cost flexible packaging, such as single-use sachets and pouches, presents a significant substitution threat, especially in price-sensitive segments and for non-viscous liquids where a rigid cup is not essential.
Strategic Opportunities
- Pharmaceutical-Grade Products:There is an opportunity to develop and market high-margin, sterilized portion cups for pharmaceutical compounding and unit-dose medication systems in hospitals, particularly in markets upgrading healthcare infrastructure.
- Smart Packaging Integration:Incorporating QR codes or NFC tags onto cups enables enhanced traceability for medication administration in clinical environments or provides detailed nutritional and allergen information for consumers in foodservice settings.
- Circular Economy Solutions:Developing closed-loop collection and composting programs in partnership with large venues, corporate campuses, or municipalities creates a key service-based differentiator and aligns with corporate sustainability goals.
Industry Challenges
- Divergent Regulatory Compliance:Manufacturers face significant complexity in navigating a fragmented global regulatory landscape, balancing the US FDA's food-contact safety standards against the EU's Single-Use Plastics Directive and material-specific mandates.
- Capital Investment for Retooling:Shifting production from established thermoforming or injection molding processes for plastics to newer technologies for molded fiber or PLA requires substantial capital expenditure and workforce retraining.
- Inadequate Composting Infrastructure:The environmental benefit of compostable cups depends on the availability of commercial composting facilities, the lack of which in many regions presents a major obstacle to achieving genuine circularity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portion Cups Market |
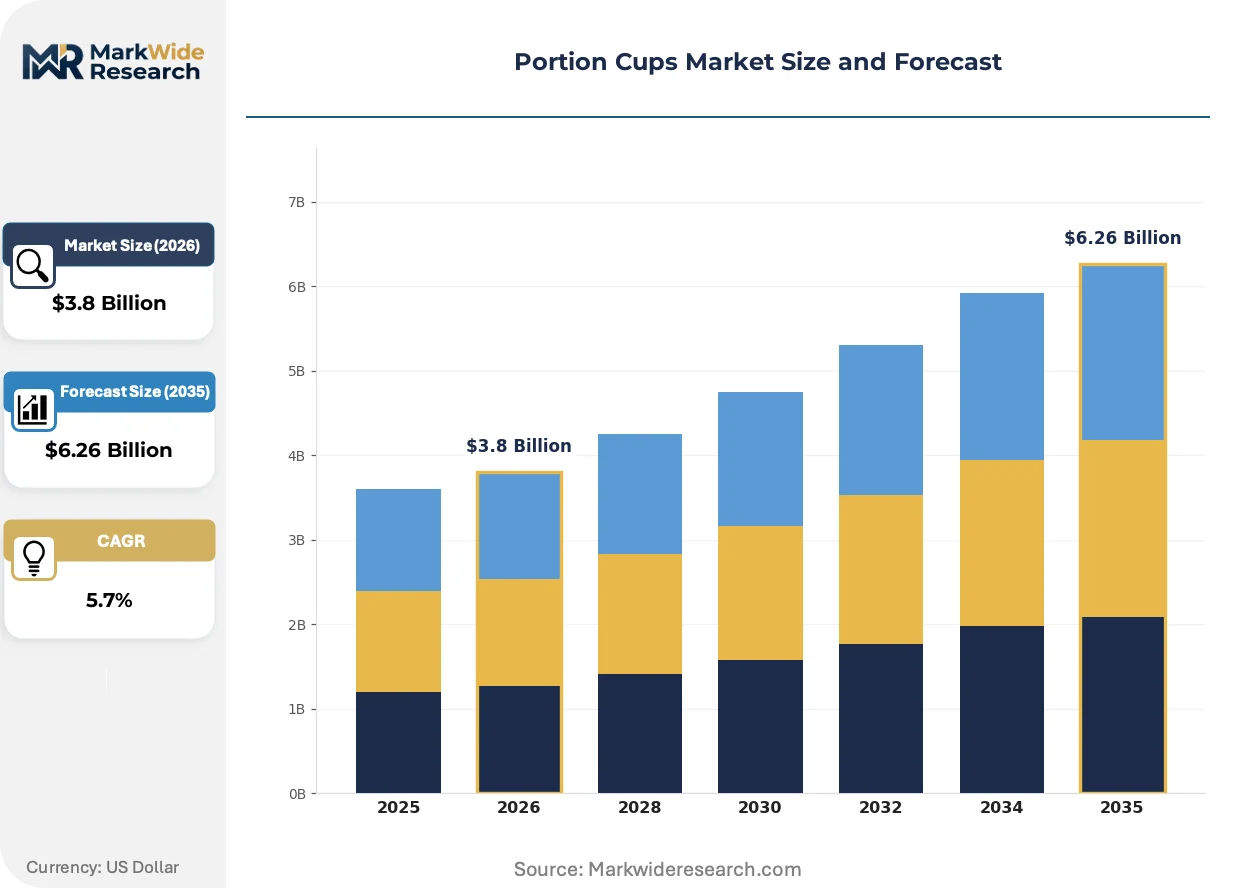
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Aluminum, Paper, Biodegradable, Foam Capacity: 5 ml, 10 ml, 15 ml, 20 ml, 30 ml Application: Foodservice, Personal Care, Pharmaceutical, Laboratory, Hospitality End User: Restaurants, Caterers, Clinics, Research Centers, Hotels |
| Companies Covered | Pactiv Evergreen Inc., Greiner Packaging, Huhtamäki Oyj, Benders Paper Cups, Genpak, Dart Container Corporation, WestRock Company, Graphic Packaging International, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portion Cups Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from prioritizing pure cost-efficiency to balancing material performance, regulatory adherence, and verifiable sustainability. This re-evaluation of value is influencing material science, manufacturing processes, and supply chain strategies.
Molded fiber technology, which uses pulp to form rigid, paper-based containers, is gaining traction as a direct substitute for plastic. Quick-service restaurants and institutional foodservice operators are adopting these products to meet corporate sustainability targets. This material innovation is absorbing market share from expanded polystyrene (EPS) foam, which faces regulatory bans in numerous jurisdictions worldwide.
Regulations such as China's "dual carbon" goals and associated national policies to reduce single-use plastic waste are accelerating material substitution. These directives create stringent restrictions on specific plastic products, compelling manufacturers to pivot their production capabilities. The foodservice sector in China's Tier 1 and Tier 2 cities is most impacted, creating a surge in local demand for paper, PLA, and other compliant materials.
A notable behavioral shift is visible as large foodservice operators move from single-source contracts to multi-vendor procurement models to enhance supply chain resilience. This strategy marks a departure from prioritizing maximum volume discounts from a single supplier. The change is most evident in North America and Europe, where recent disruptions have highlighted the vulnerabilities of geographically concentrated supply chains.
Portion Cups Market Segmentation
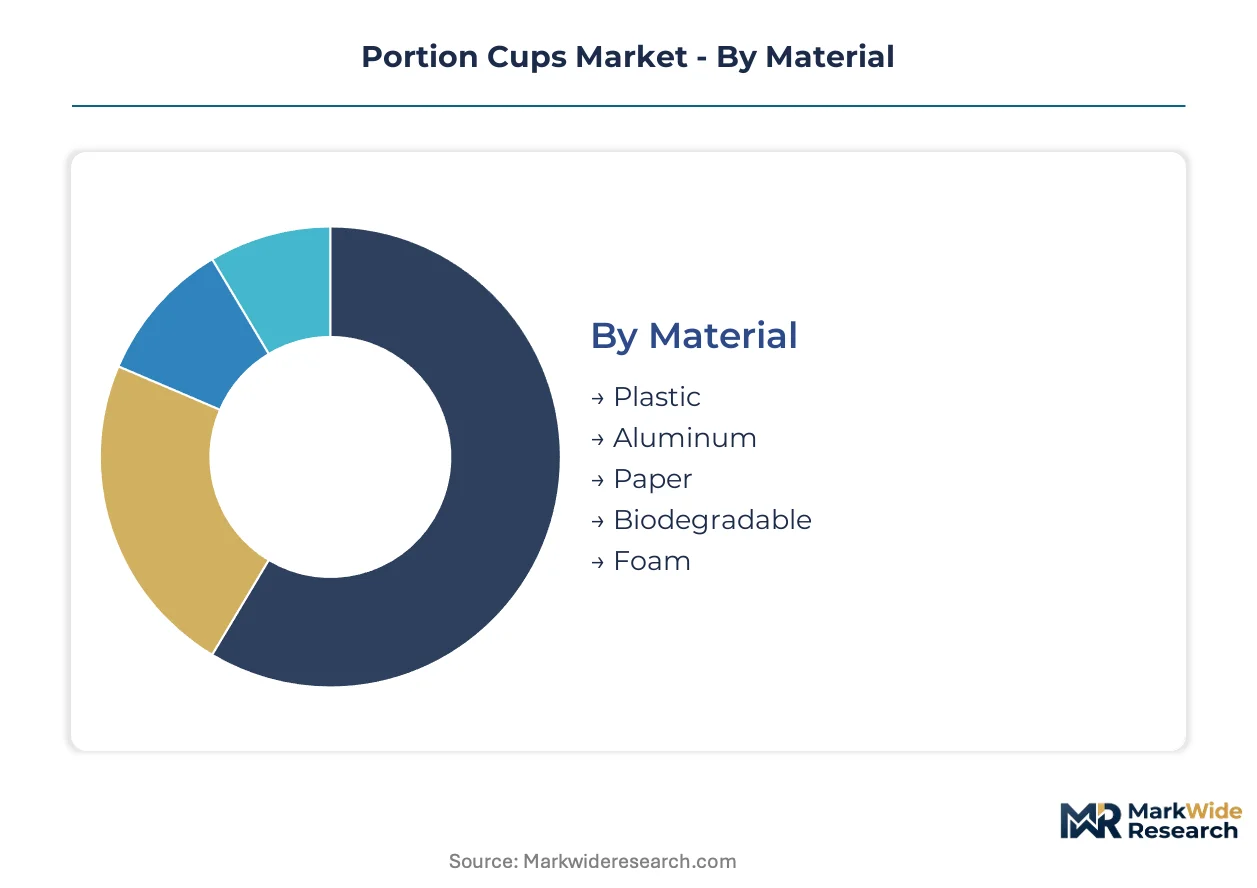
Understanding the portion cups market through segmentation reveals the nuanced interplay of material innovation, precise capacity needs, varied application environments, and distinct end-user demands. This granular analysis helps manufacturers align product development with specific industry requirements and evolving regulatory landscapes.
Material:
The material segment highlights the ongoing tension between cost-driven standardization and the increasing demand for customized, sustainable solutions.
- Plastic:These cups are typically manufactured from polypropylene (PP) or polyethylene terephthalate (PET) through thermoforming or injection molding processes. Their cost-effectiveness and versatility ensure widespread use across foodservice, notably for condiments in quick-service restaurants in North America and Europe.
- Biodegradable:Composed of materials like polylactic acid (PLA) or molded fiber, these alternatives offer environmental benefits. Demand is concentrating in regions with stringent single-use plastic regulations, such as the European Union, driven by directives like the Single-Use Plastics Directive.
- Aluminum:These containers are often used for products requiring extended shelf life or specific barrier properties, such as certain pharmaceutical formulations.
- Paper:Paper-based cups offer a renewable and often recyclable option, commonly used for dry goods or short-term liquid containment.
- Foam:Expanded polystyrene (EPS) foam provides insulation properties but faces increasing regulatory bans and public scrutiny in numerous global jurisdictions.
Leading the category by volume: Plastic. Growing fastest: Biodegradable.
Capacity:
Capacity segmentation directly reflects the precise volume requirements across diverse end-use applications, from micro-dosing to standard condiment portions.
- 10 ml:These small-volume cups are a standard for single-serve condiments and sauces in the foodservice sector. Their compact size makes them ideal for takeout and food delivery services, particularly in dense urban centers.
- 30 ml:Representing a larger single-serve volume, 30 ml cups find application in both pharmaceutical settings for medication doses and in foodservice for more substantial condiment portions. This size supports a wider range of viscous and non-viscous liquids.
- 5 ml:Primarily utilized in laboratory and pharmaceutical settings for precise liquid measurement or very small doses of medication.
- 15 ml:A common size for individual servings of salad dressings, creamers, and other liquid accompaniments in the hospitality industry.
- 20 ml:These cups often serve mid-range portion control needs in clinical environments or for specific food service items like individual jam servings.
The 10 ml capacity segment commands the largest market share. The 30 ml capacity segment exhibits the steepest expansion trajectory.
Application:
Application areas dictate specific performance requirements and regulatory compliance, differentiating standard commercial use from highly specialized environments.
- Foodservice:This segment dominates the market, encompassing quick-service restaurants, cafeterias, and institutional catering for condiments, sauces, and side dishes. Foodservice applications prioritize cost-effectiveness and high-volume production.
- Pharmaceutical:This segment demands sterile, high-grade materials for precise medication dispensing and compounding in hospitals and pharmacies. Stringent regulations from bodies like the US FDA and Europe's EMA govern product safety and material integrity.
- Personal Care:Portion cups in personal care are used for product samples, travel-sized toiletries, or single-use cosmetic applications.
- Laboratory:Research and clinical laboratories utilize portion cups for sample collection, reagent mixing, and precise measurement in controlled environments.
- Hospitality:Hotels, airlines, and cruise lines use portion cups for in-room amenities, mini-bar items, and individual food or beverage servings.
Foodservice constitutes the dominant application segment. Pharmaceutical applications are gaining share most rapidly.
End User:
End-user categories showcase varied purchasing power and operational scales, influencing material choice and supply chain dynamics.
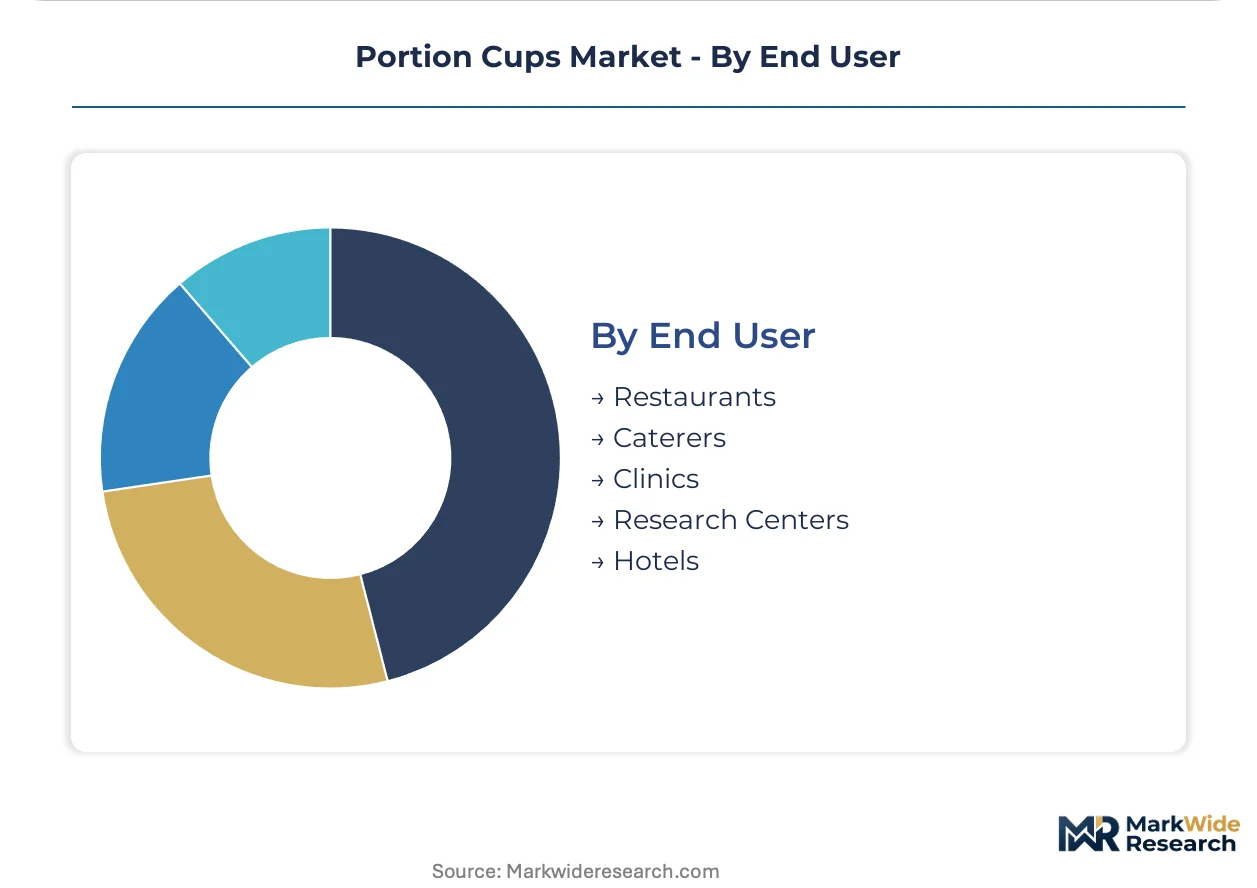
- Restaurants:This category includes quick-service, casual dining, and fine dining establishments, driving high-volume demand for condiment and side dish portioning. Restaurants prioritize efficiency and consistent product delivery.
- Clinics:Clinics, hospitals, and long-term care facilities rely on portion cups for medication administration, sample collection, and maintaining hygiene standards. Patient safety and regulatory compliance are paramount for these users.
- Caterers:Catering services utilize portion cups for large events, corporate functions, and meal delivery, requiring versatile and often disposable packaging solutions.
- Research Centers:Academic and industrial research centers use specialized portion cups for experiments, material handling, and precise scientific applications.
- Hotels:Hotels employ portion cups for breakfast buffets, in-room dining, and complimentary amenities, focusing on guest convenience and presentation.
Restaurants represent the largest end-user group by volume. Clinics are increasing their procurement of specialized portion cups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer resin production in the United States anchors the global supply chain for traditional plastic portion cups. This concentration supports extensive manufacturing capabilities for foodservice and medical applications. The country's strong domestic market drives innovation in both material science and production efficiency.
United States
United States foodservice demand for condiments and sauces, coupled with clinical needs, drives significant portion cup consumption. US FDA food-contact material regulations ensure product safety and material integrity for all applications. Major manufacturing hubs in the Midwest, including Illinois, optimize distribution for national quick-service restaurant chains.
Germany
German demand for portion cups stems from its robust foodservice sector and advanced pharmaceutical packaging needs. The EU's Single-Use Plastics Directive accelerates the shift towards sustainable alternatives across the nation. Bavaria's advanced manufacturing sector actively develops innovative molded fiber solutions for various European markets.
India
India's rapid food delivery ecosystem growth creates sustained demand for single-serving condiment and sauce containers. The Bureau of Indian Standards (BIS) governs material safety and quality for food packaging. Dense urban centers like Mumbai and Delhi experience surging demand for convenient, portion-controlled packaging solutions.
China
Chinese quick-service restaurants and pharmaceutical unit-dose systems fuel substantial demand for portion cups. China's dual carbon goals and plastic reduction policies compel manufacturers to adopt sustainable materials. Foodservice operators in Tier 1 and Tier 2 cities increasingly adopt paper and PLA alternatives.
Japan
Japanese demand for portion cups emphasizes high hygiene standards within its foodservice sector and precise medical dosage. The Pharmaceuticals and Medical Devices Agency (PMDA) sets stringent guidelines for medical packaging. Tokyo's advanced food processing industry integrates specialized portion control solutions for both domestic and export markets.
Portion Cups Market Key Industry Players
Global majors compete with regional champions across supply chain resilience and material innovation within the portion cups market. The market structure is tiered, featuring large integrated players alongside specialized innovators. Strategic archetypes include large-scale plastic manufacturers, sustainable packaging solution providers, and cost-focused commodity producers. Companies engage in capacity expansion for new materials and strategic partnerships to develop circular economy solutions.
At the scale-driven end, Pactiv Evergreen Inc. exemplifies extensive North American manufacturing capabilities, serving major national accounts with a focus on cost-effective, high-volume production. Finland-based Huhtamäki Oyj represents a leader in innovative fiber-based and sustainable packaging solutions, particularly across European and Asian markets, aligning with growing environmental mandates. Dart Container Corporation occupies a position as a broad product portfolio provider, offering both foam and plastic options, catering to diverse price points and application needs within the foodservice sector. These companies collectively demonstrate the varied approaches to market penetration, from geographic scale to material innovation.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Greiner Packaging |
| Huhtamäki Oyj |
| Benders Paper Cups |
| Genpak |
| Dart Container Corporation |
| WestRock Company |
| Graphic Packaging International |
| Berry Global Inc. |
| Others |
Cost & Logistics Intelligence
Molded fiber technology adoption reshapes portion cup cost economics by introducing new material inputs and manufacturing processes. This transition simultaneously reconfigures supply concentration away from traditional plastic resin producers.
Pricing Analysis
After-sales service bundling for portion cups is minimal, with pricing primarily reflecting per-unit transactional costs for standard orders. Long-term contract-based offtake agreements offer volume discounts to large foodservice chains. Price differentiation stems from material quality, such as sterile pharmaceutical-grade cups, and regulatory certifications like US FDA food-contact approval. Cost compression intensifies due to volatile polymer resin prices and competition from flexible packaging, making foodservice operators highly price-sensitive compared to pharmaceutical buyers who prioritize product integrity.
Supply Chain Analysis
Large distributors and direct sales channels manage portion cup supply to major foodservice and pharmaceutical clients. Geographic supply concentrates manufacturing capabilities in the United States and China, with Europe leading in molded fiber innovation. The supply chain draws heavily from polymer resins like PP and PET, along with pulp for paper-based alternatives. A structural risk involves commodity price volatility for petrochemical feedstocks, directly impacting plastic cup costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portion cups market is undergoing a technology-transition phase, driven by molded fiber technology displacing legacy expanded polystyrene foam. This shift redefines material performance expectations and manufacturing investments.
For Market Incumbents:Cement market leadership by investing in capacity expansion for molded fiber and PLA production, especially in regions with stringent single-use plastic regulations like the EU. Develop strategic partnerships for closed-loop collection and composting programs to counter regulatory bans on traditional plastics. Diversify material portfolios beyond foam and conventional plastics.
For New Entrants and Emerging Players:Begin with specialized product lines, such as high-margin, sterilized pharmaceutical-grade cups for hospitals in upgrading healthcare infrastructures. Target smart packaging integration with QR codes for enhanced traceability in clinical environments. Focus on niche segments where performance and regulatory compliance outweigh initial cost, establishing a strong reputation for innovation.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquiring specialized sustainable packaging solution providers with proprietary molded fiber or biopolymer technologies. The market demonstrates long-term viability, driven by essential portion control functions across foodservice and healthcare, but material innovation is critical. Watch for increasing capital investment in commercial composting infrastructure, indicating genuine circular economy readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Molded Fiber Production Capacity | Meets growing demand from foodservice for sustainable alternatives and addresses regulatory mandates. |
| Develop Pharmaceutical-Grade Biopolymers | Captures high-margin opportunities in clinical settings requiring sterile, precise dosage solutions. |
| Form Closed-Loop Composting Partnerships | Establishes a service-based differentiator and aligns with corporate sustainability goals for circularity. |
| Integrate Smart Packaging Technologies | Enhances product traceability for medication or provides consumer information, adding value beyond containment. |
| Diversify Polymer Resin Sourcing | Mitigates supply chain risks from petrochemical price volatility and single-source dependencies. |
Research Approach
Document review covered US FDA guidelines, EU Single-Use Plastics Directive, BIS standards, and company annual reports, complemented by interviews with foodservice procurement managers and pharmaceutical packaging specialists. Material scientists and regulatory compliance officers also provided insights. This approach combined primary and secondary data, employing both bottom-up and top-down triangulation for validation.
Volume and value projections were generated through an analytical framework applied across the analysis window. The model segmented the market by material type, capacity, application, end-user, and regional regulatory framework. Compound annual growth rates were derived from historical trends and projected shifts in material adoption. Key forecast inputs included polymer resin price volatility and food delivery ecosystem growth rates.
Underlying measurement precision varies by segment; pharmaceutical applications carry tighter precision than foodservice. Forecasts reflect assumptions regarding regulatory changes and material science breakthroughs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food and Grocery Retail Market
Food Service
Commercial Kitchen Appliances Market
Food Service
South Africa Fast Food Market
Food Service
Integrated Stove Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Food Trays Market
Food Service
Vacuum Flask Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Vietnam Food Service Market
Food Service
India Inflight Catering Market
Food Service
Food Service Market
Food Service
Restaurant Takeout Market
Food Service
A La Carte Market
Food Service
Commercial Tandoor Oven Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Commercial Tableware Services Market