
 Netherlands Food Service Market | 2026-2036
Netherlands Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Food Service Market Insights
Corporate buyers and institutional clients is unwinding the historical dominance of individual consumers in Dutch food service procurement. Compass Group plc leverages its scale across hospital and university contracts to sustain recurring revenue streams. Sodexo SA anchors its position through facility management bundles that integrate catering with workplace services. McDonald's Corporation competes by controlling real estate in high-traffic Dutch retail corridors.
Food service encompasses the commercial preparation and delivery of meals outside domestic kitchens, spanning from quick-service counters to full-service restaurants with standardized portion controls and cold-chain logistics. The sector supplies nourishment to workplaces, educational campuses, travel hubs, and leisure venues through centralized procurement and distributed service points. Delivery and takeaway channels are capturing margin pools as digital ordering platforms reshape Dutch consumption habits, while dine-in formats face pressure from labor scarcity in the Randstad. Catering directed at corporate and institutional customer types retains pricing power through long-term contracts, whereas consumer-facing fast food segments battle on speed and location density.
The Netherlands Food and Consumer Product Safety Authority (NVWA) enforces hygiene protocols that dictate kitchen design and staff certification across all Dutch food service establishments. The Dutch National Protein Strategy and EU Farm to Fork targets under the European Green Deal are mandating measurable reductions in animal protein procurement for publicly contracted caterers. Stakeholders must decide whether to absorb compliance costs or pass them through contract renegotiations.
Market Dynamics
The Dutch National Protein Strategy is decomposing traditional menu structures across contract catering, forcing procurement officers to rebalance supplier relationships toward plant-forward portfolios while maintaining cost discipline in Randstad institutional kitchens.
Growth Catalysts
- EU Farm to Fork targets:Mandatory animal protein reduction quotas for publicly contracted caterers are accelerating reformulation investments across hospital and university food service operations.
- Employer on-site meal programs:Corporate cafeterias are expanding as Dutch firms prioritize retention through workplace amenities, generating recurring institutional revenue streams.
- Randstad corridor density:Amsterdam, Rotterdam, and Utrecht concentrate food service transactions through overlapping commuter flows and high-frequency business districts.
Market Restraints
- Input cost volatility:Plant protein ingredient prices fluctuate with European agricultural yields, compressing margins on reformulated menus before contract renegotiation windows open.
- Labor scarcity concentration:Randstad urban centers face acute kitchen staff shortages, limiting service point expansion regardless of capital availability.
- Regulatory compliance friction:NVWA hygiene certification timelines extend equipment procurement cycles for new establishment openings.
Strategic Opportunities
- Digital ordering platforms:Delivery and takeaway channel infrastructure enables margin capture beyond fixed-location constraints, reshaping last-mile economics.
- Facility management bundles:Integrated workplace services create pricing power through multi-year contracts spanning catering, cleaning, and security.
- Protein diversification mandates:Government procurement rules favor caterers with verified plant-based supply chains, rewarding early compliance investment.
Industry Challenges
- Cold-chain logistics reconfiguration:Dual inventory streams for animal and plant proteins strain warehouse capacity and temperature-controlled distribution networks.
- Kitchen equipment retrofitting:Separated preparation zones for allergen management and protein cross-contamination prevention demand capital deployment before operational savings materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Food Service Market |
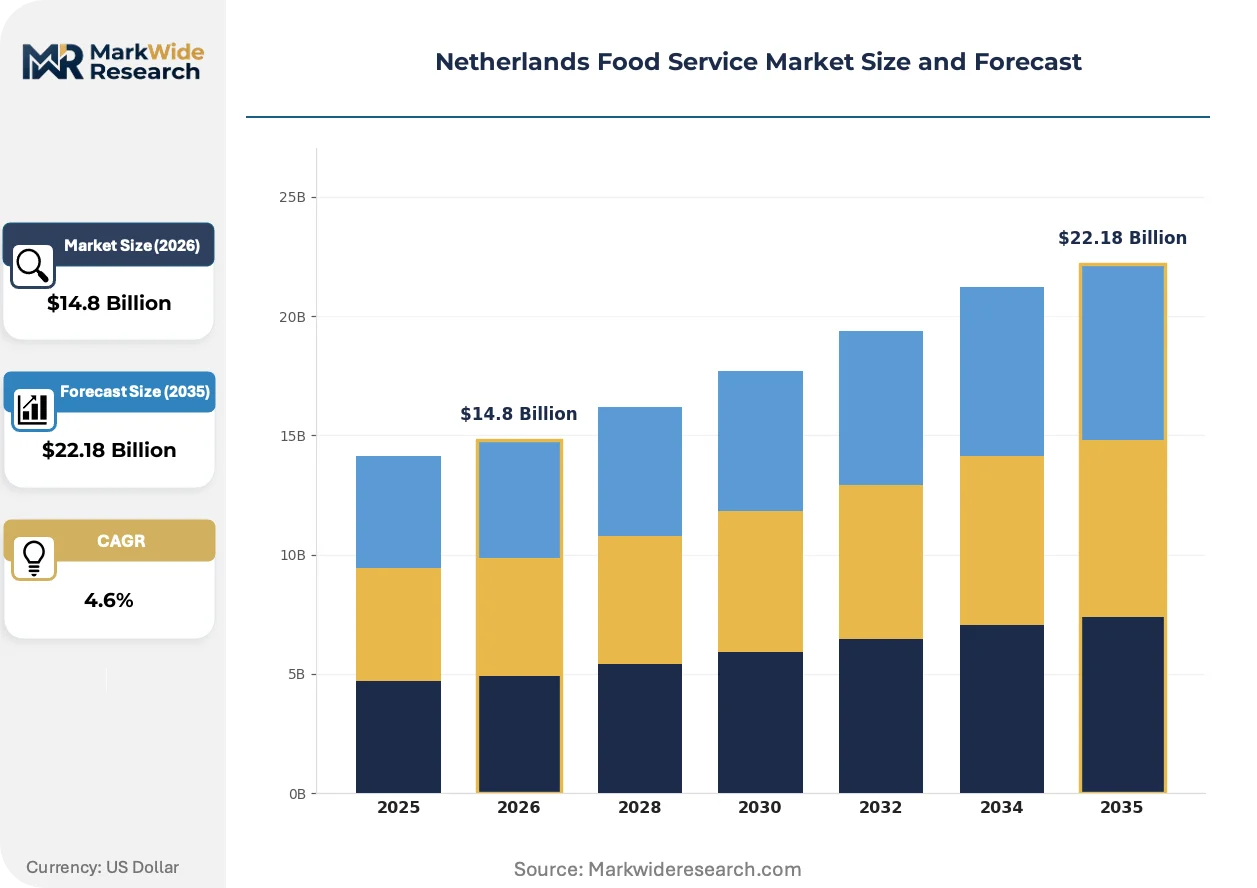
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Takeaway, Catering, Delivery Customer Type: Consumers, Corporates, Event Planners, Institutions Food Type: Vegetarian, Vegan, Organic, Fast Food Distribution Channel: Online, Offline, Franchise, Direct |
| Companies Covered | Compass Group plc, McDonald's Corporation, Sodexo SA, Starbucks Corporation, Domino's Pizza Enterprises Ltd., Yum! Brands, Inc., Restaurant Brands International Inc., Alsea SAB de CV, Autogrill SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Food Service Market Trends and Innovations
Kitchen automation and digital ordering infrastructure are compressing traditional service models while regulatory protein mandates rewrite procurement specifications across Dutch institutional contracts.
Robotic food preparation systems are decomposing labor-dependent kitchen operations in high-volume Randstad catering facilities. Hospital and university contract caterers deploy automated cooking lines to offset staff shortages. This technology is decomposing the historical trade-off between portion consistency and labor cost, enabling centralized production with distributed service points.
The Dutch National Protein Strategy imposes measurable animal protein reduction targets on publicly funded caterers, triggering supplier base restructuring. Contract caterers must verify plant-based procurement shares through audited supply chain documentation. Hospital and education segments face the steepest compliance curves, with procurement officers already disqualifying vendors lacking certified alternative protein portfolios.
Workplace meal subsidies are consolidating individual consumer purchasing into employer-negotiated institutional contracts. Corporate buyers now specify nutritional benchmarks and sustainability credentials that override individual preference diversity. This concentration is most visible in Amsterdam and Rotterdam financial districts, where large employers bundle food service into comprehensive facility management agreements.
Netherlands Food Service Market Segmentation
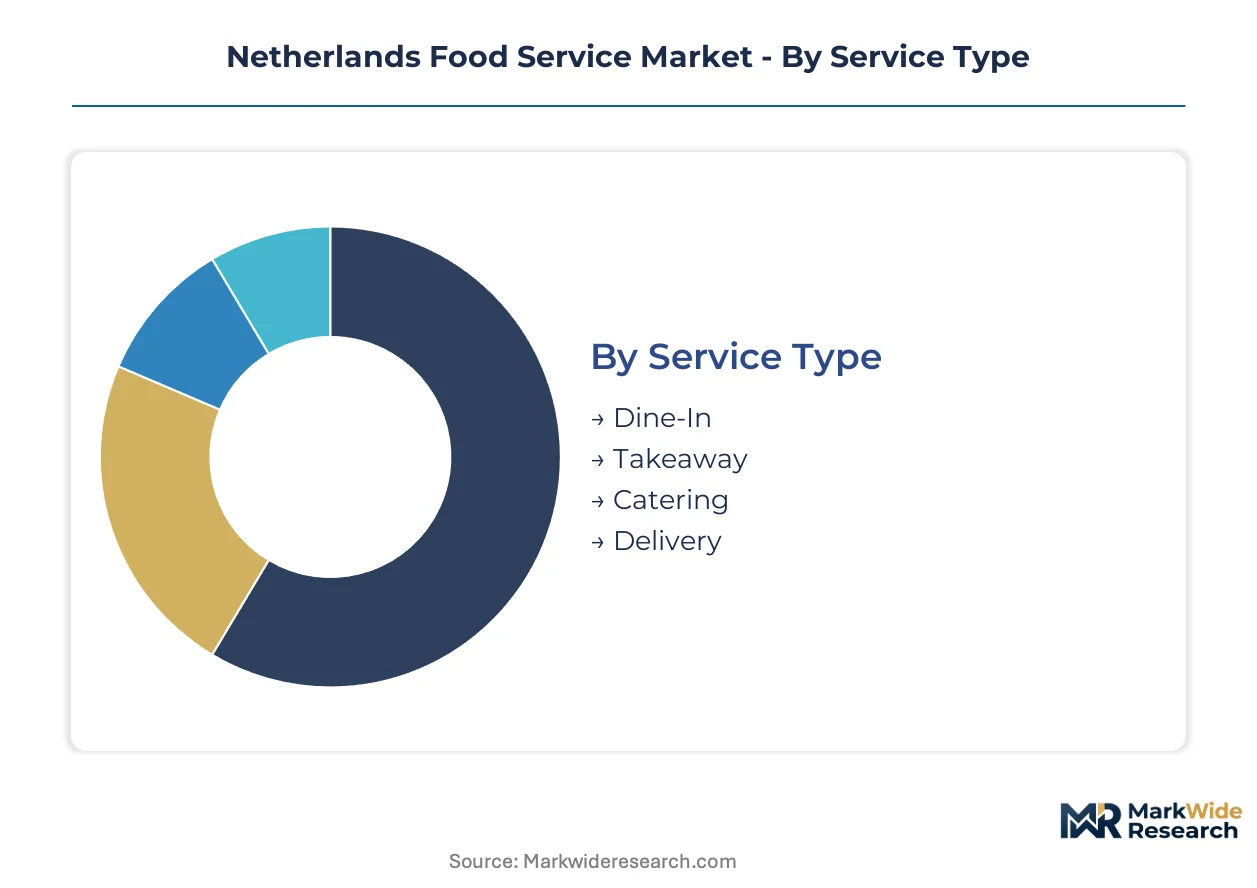
Dutch food service segmentation reveals how procurement concentration and regulatory protein mandates are restructuring traditional demand patterns. Service configuration and customer type now determine margin durability more than location density alone.
Service Type:
Catering and delivery segments serve predominantly domestic institutional clients, while dine-in and takeaway formats balance local consumption with cross-border tourism flows in Amsterdam and Rotterdam corridors.
- Dine-In:Full-service restaurants with standardized portion controls and NVWA-certified kitchen layouts dominate Amsterdam's canal district and Utrecht's historic core. Labor scarcity in Randstad urban centers constrains table turnover expansion despite capital availability for new establishment openings.
- Takeaway:Counter-service formats with cold-chain handoff protocols capture commuter flows in Rotterdam's port district and The Hague's government quarter. Digital ordering integration enables margin capture beyond fixed-location constraints.
- Catering:Corporate cafeterias and institutional meal programs supply workplaces, hospitals, and universities through long-term contracts with protein diversification mandates.
- Delivery:Platform-mediated last-mile logistics reshape consumption habits in dense Randstad postal codes, though rider wage regulations compress unit economics.
Dine-In commands the established base. The steepest expansion runs through Catering as employer on-site meal programs consolidate procurement.
Customer Type:
Cost tier stratification separates volume-driven institutional contracts from premium-priced individual transactions, with corporate buyers extracting sustainability credentials through negotiated benchmarks.
- Consumers:Individual purchasers selecting from quick-service counters or full-service restaurants based on speed and location density. Digital platforms fragment loyalty across competing aggregator apps.
- Corporates:Employer-negotiated contracts specifying nutritional benchmarks and plant-based procurement shares override individual preference diversity in Amsterdam and Rotterdam financial districts.
- Event Planners:Temporary catering contracts for conferences and exhibitions concentrate in Rotterdam Ahoy and Amsterdam RAI exhibition complexes.
- Institutions:Hospitals, universities, and government facilities face steepest compliance curves under Dutch National Protein Strategy mandates, disqualifying vendors lacking certified alternative protein portfolios.
Institutions command the established base. The steepest expansion runs through Corporates as workplace amenities prioritize retention.
Food Type:
Supply concentration for certified plant proteins centers on Dutch agricultural processing regions, while fast food sourcing maintains broader European supplier networks.
- Vegetarian:Lacto-ovo menu formulations with verified dairy and egg supply chains satisfy institutional procurement officers rebalancing portfolios toward plant-forward options.
- Vegan:Exclusion of all animal derivatives demands segregated preparation zones and allergen management protocols in Randstad institutional kitchens.
- Organic:EU organic certification requirements extend procurement cycles for publicly contracted caterers seeking compliant ingredient streams.
- Fast Food:Standardized portion controls and centralized procurement enable location density strategies in high-traffic retail corridors.
Fast Food commands the established base. The steepest expansion runs through Vegan as government procurement rules favor verified plant-based supply chains.
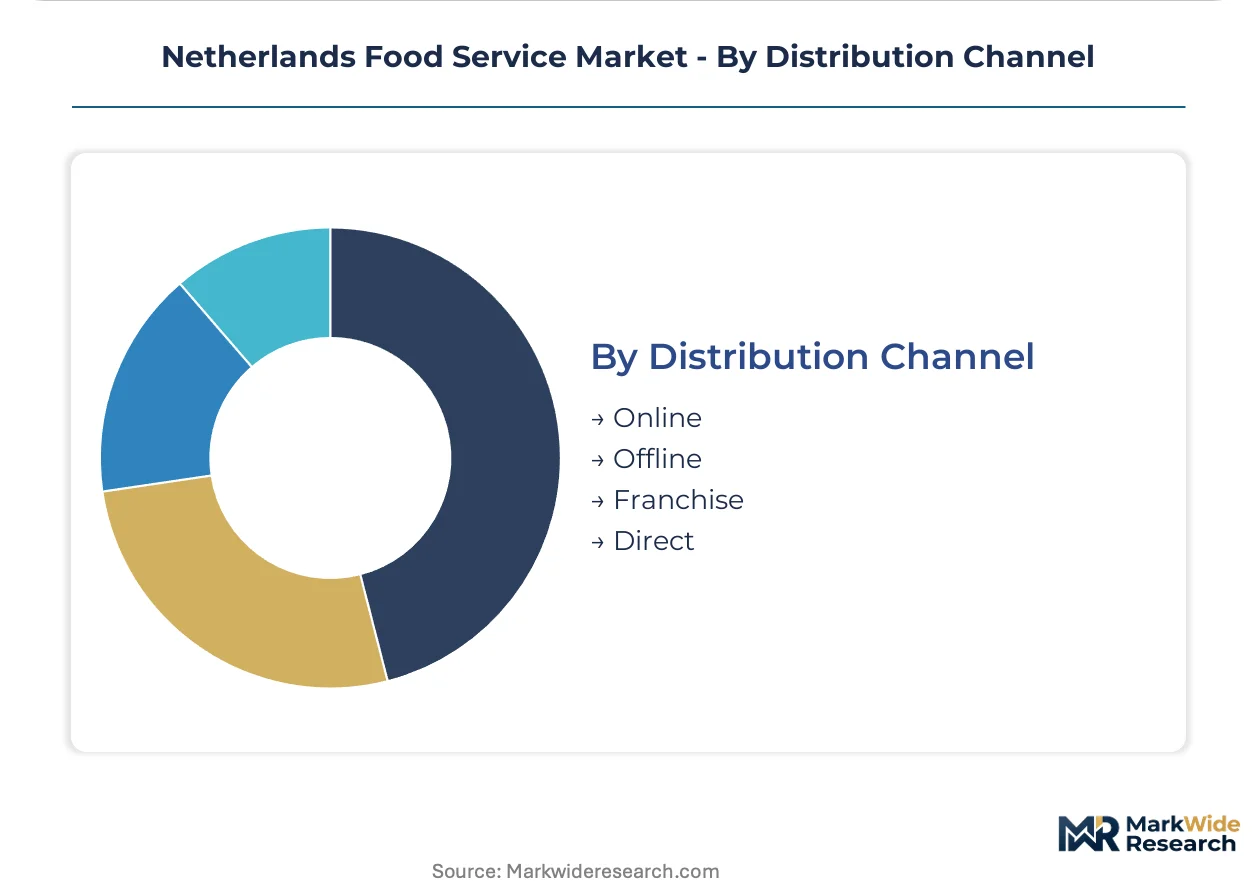
Distribution Channel:
Margin structure varies sharply between capital-light digital intermediation and asset-heavy franchise networks, with direct sales retaining pricing power in institutional segments.
- Online:Aggregator platforms capture transaction fees from digital ordering infrastructure while reshaping last-mile economics beyond fixed-location constraints.
- Offline:Physical service points with NVWA hygiene certification sustain dine-in and takeaway demand in Randstad urban centers.
- Franchise:Branded format replication with standardized supply agreements enables rapid location density in high-traffic Dutch retail corridors.
- Direct:Unmediated institutional contracts spanning catering, cleaning, and security create pricing power through multi-year facility management bundles.
Offline commands the established base. The steepest expansion runs through Online as delivery and takeaway channels capture margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure anchors the Netherlands' food service distribution, with refrigerated container throughput connecting Dutch institutional kitchens to European agricultural suppliers.
Randstad Corridor
Amsterdam, Rotterdam, and Utrecht concentrate employer-negotiated corporate cafeteria contracts and platform-mediated delivery density. The Dutch National Protein Strategy mandates measurable animal protein reductions for publicly contracted caterers operating in these financial districts. Hospital and university food service operations in Leiden and Delft face steepest compliance curves under audited supply chain documentation requirements.
Brabant
Eindhoven's high-tech campus employers prioritize on-site meal programs as retention tools, consolidating individual purchasing into institutional procurement. NVWA hygiene certification timelines extend equipment procurement cycles for new establishment openings in this manufacturing belt. Tilburg and Breda host centralized production facilities serving distributed corporate catering contracts across the southern provinces.
Northern Netherlands
Groningen and Leeuwarden exhibit lower delivery platform penetration, preserving dine-in format dominance in historic cores. The region's university hospitals face Dutch National Protein Strategy mandates with limited local plant-protein supplier density. Dairy processing clusters in Friesland supply lacto-ovo menu formulations to institutional procurement officers rebalancing portfolios.
Netherlands Food Service Market Competitive Landscape
Listed leaders compete with private specialists across contract tenure, with publicly traded caterers leveraging balance sheet capacity for multi-year facility management bundles while private operators exploit nimble menu reformulation. The vendor base fragments across service type, with scale advantages concentrating in institutional catering and location density dominating quick-service formats. Two strategic archetypes prevail: integrated facility managers bundling catering with workplace services, and format specialists controlling real estate in high-traffic retail corridors. M&A activity targets plant-forward supply chain capabilities, while strategic partnerships secure cold-chain logistics capacity.
Within the integrated facility management tier, Compass Group plc and Sodexo SA occupy positions defined by hospital and university contract scale. McDonald's Corporation anchors the format specialist archetype through real estate control in Dutch retail corridors. These three entities exemplify the competitive divergence between institutional pricing power and consumer-facing location density strategies.
| Leading Market Players |
|---|
| Compass Group plc |
| McDonald's Corporation |
| Sodexo SA |
| Starbucks Corporation |
| Domino's Pizza Enterprises Ltd. |
| Yum! Brands, Inc. |
| Restaurant Brands International Inc. |
| Alsea SAB de CV |
| Autogrill SpA |
| Others |
Pricing and Supply Chain Analysis
Centralized production capacity at Dutch institutional catering facilities generates scale economies that compress per-unit preparation costs while simultaneously concentrating supplier bargaining power among Randstad contract caterers. This capacity concentration establishes price floors for plant-based menu reformulation that smaller operators cannot match without multi-year procurement commitments.
Pricing Analysis
Volume-discount tiering structures dominate Dutch institutional catering contracts, with corporate cafeterias and hospital food service operations capturing preferential rates through multi-year procurement commitments. Pricing stratifies across premium certified-organic tiers, standard NVWA-compliant baselines, and economy-grade bulk supply agreements. Cost compression in economy tiers is intensifying because plant protein ingredient prices fluctuate with European agricultural yields. Individual consumers at quick-service counters exhibit highest price sensitivity, while integrated facility management bundles insulate corporate buyers from spot market volatility.
Supply Chain Analysis
Rotterdam Port cold-chain infrastructure serves as the critical chokepoint connecting Dutch institutional kitchens to European agricultural suppliers. The Netherlands draws from Belgian and German processing centers for certified plant proteins, while dairy supply chains feed from Friesland's domestic processing clusters. Single-source vulnerability concentrates in temperature-controlled distribution networks serving Randstad urban centers. Distribution runs through centralized production facilities with satellite service points rather than distributed kitchen models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch corporate procurement officers who negotiate multi-year facility management bundles spanning catering, cleaning, and security services. This consolidation fragments pricing power away from individual consumer-facing operators toward institutional contract specialists.
For Market Incumbents: Compound defensible positions by securing NVWA certification for segregated plant-protein preparation zones before competitor retrofitting cycles complete. Extend backward integration into Friesland dairy processing clusters to capture captive supply of lacto-ovo menu ingredients. Facility management bundling threatens standalone caterers who lack workplace services integration.
For New Entrants and Emerging Players: Lead with digital ordering infrastructure targeting underpenetrated Brabant manufacturing corridors where delivery platform density lags Randstad saturation. Corporate cafeteria outsourcing in Eindhoven's high-tech campus cluster offers the most penetrable entry point. Position through subscription-based meal programs that consolidate individual purchasing into employer-negotiated contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract caterers with hospital and university tenure exceeding five years. Long-term viability hinges on verified plant-based supply chain documentation that satisfies Dutch National Protein Strategy audit requirements. Watch for NVWA enforcement actions against non-compliant operators as inflection indicators for market share redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Supply Chain Certification | NVWA audit documentation satisfies Dutch National Protein Strategy procurement mandates for institutional contracts. |
| Kitchen Automation Deployment | Robotic preparation lines offset Randstad labor scarcity while enabling centralized production with distributed service points. |
| Facility Management Bundling | Integrated workplace services spanning catering, cleaning, and security create multi-year contract pricing power. |
| Digital Ordering Platform Integration | Aggregator partnerships reshape last-mile economics beyond fixed-location constraints in dense postal codes. |
| Cold-Chain Logistics Partnership | Rotterdam Port refrigerated container throughput secures temperature-controlled distribution capacity for plant-protein inventory streams. |
Research Methodology
Operator-level perspectives from contract catering procurement officers, NVWA compliance auditors, facility management executives, and university food service directors anchored the qualitative base. Primary interview insights combined with secondary validation from Dutch Customs trade records, EU Farm to Fork implementation reports, hospital procurement databases, and SEC filings of listed catering operators. Bottom-up segment sizing triangulated against top-down market value estimates across service type, customer type, and food type dimensions.
Sensitivity analysis tested volume and value outputs against protein price volatility scenarios and labor availability constraints across the projection horizon. Segmentation dimensions modeled include service configuration, customer archetype, protein sourcing category, and distribution channel complexity. CAGRs derived from historical trajectory analysis adjusted for regulatory mandate acceleration and digital adoption curves. Forecast inputs incorporated employer meal program expansion rates and cold-chain logistics capacity utilization at Rotterdam Port.
Underlying assumptions cover Dutch National Protein Strategy enforcement timelines and Randstad labor market tightness persistence, with deviation risk concentrated in plant protein ingredient price spikes and NVWA certification processing delays. Practitioners should keep alternative scenarios live as EU Farm to Fork target revisions and workplace amenity investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
GCC Online Grocery Market
Food Service
South Korea Foodservice Market
Food Service
Gourmet Street Food Market
Food Service
Stirrers Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Switzerland Food Service Market
Food Service
Commercial Tableware Services Market
Food Service
United Kingdom Foodservice Market
Food Service
Restaurant Takeout Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Gas Fryers Market
Food Service
Latin America Online Grocery Market
Food Service
Smokeless Grill Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Kamado Grill Market