
 Contract Blending Services Market | 2026-2036
Contract Blending Services Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Blending Services Market Outlook
The capital-intensity divergence between large-scale chemical distributors and boutique formulation houses is bifurcating competitive dynamics across contract blending. Brenntag AG leverages its integrated supply network and tank farm infrastructure to sustain cost advantages in liquid blending volumes. Univar Solutions Inc. anchors its position through technical service capabilities that extend beyond blending into regulatory documentation and shelf-life testing. IMCD Group differentiates by occupying specialty formulations where formulation chemistry expertise commands premium positioning.
Contract blending services encompass the outsourced mechanical and chemical integration of multiple raw materials into homogeneous intermediate or finished products, typically achieving particle size distributions below 100 microns for powder blends or viscosity specifications within 5% tolerance for liquid systems, serving manufacturers that lack in-house compounding capacity or seek variable cost structures. Liquid blending dominates current service revenues due to established tankage infrastructure and shorter batch cycle times, while specialty formulations capture expanding margin pools as nutraceutical and cosmeceutical brands outsource complex active-delivery systems. Batch processing remains the prevailing technology architecture, though automated systems are gaining share in pharmaceutical-grade facilities where electronic batch records and process analytical technology reduce deviation rates.
FDA Current Good Manufacturing Practice regulations for dietary supplements and REACH substance registration requirements in Europe elevate compliance costs and favor contract partners with established quality management systems and regulatory dossier capabilities. ISO 9001 certification and HACCP implementation function as baseline market-access credentials rather than differentiators in pharmaceutical and food-grade segments. Stakeholders must evaluate whether captive blending investments or external partnerships better align with portfolio volatility and geographic regulatory fragmentation.
Market Dynamics
Automated batch processing systems with electronic batch records are compressing deviation rates in pharmaceutical-grade facilities, forcing contract blenders to retool quality infrastructure or exit high-margin segments entirely.
Growth Catalysts
- REACH substance registration:ECHA's tightening purity documentation requirements in Europe push brand owners toward established contract partners with dossier capabilities rather than in-house compounding investments.
- Nutraceutical specialty formulations:Complex active-delivery systems for cosmeceutical brands demand formulation chemistry expertise that boutique houses command premium positioning for.
- German chemical processing clusters:Concentrated tank farm infrastructure and pharmaceutical manufacturing density around Ludwigshafen and Leverkusen create favorable variable-cost economics for outsourced liquid blending.
Market Restraints
- API input cost volatility:Active pharmaceutical ingredient prices fluctuate with Chinese export quotas and energy-intensive synthesis constraints, compressing margin predictability for fixed-price blending contracts.
- ISO 9001 certification baseline:Quality management system credentials function as table stakes rather than differentiators, eroding pricing power for mid-tier facilities lacking pharmaceutical-grade accreditation.
- Tankage infrastructure concentration:Liquid blending capacity clusters with large-scale chemical distributors, limiting boutique formulators' ability to compete on volume economics in commodity segments.
Strategic Opportunities
- Particle engineering convergence:Integration of spray-drying and hot-melt extrusion technologies enables contract blenders to offer finished dosage form capabilities beyond intermediate powders.
- India pharmaceutical outsourcing:CDSCO's harmonization with ICH guidelines attracts multinational brands seeking cost-advantaged clinical trial material production with equivalent quality documentation.
- Process analytical technology mandates:FDA's push for real-time release testing creates service revenue streams for blenders investing in PAT-enabled continuous processing lines.
Industry Challenges
- Cross-contamination protocol complexity:Dedicated suite requirements for hormonal and cytotoxic compounds extend changeover timelines and reduce asset utilization rates in multi-product facilities.
- Electronic batch record integration:Legacy MES systems in acquired facilities resist seamless data migration, delaying compliance with 21 CFR Part 11 audit trail requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Blending Services Market |
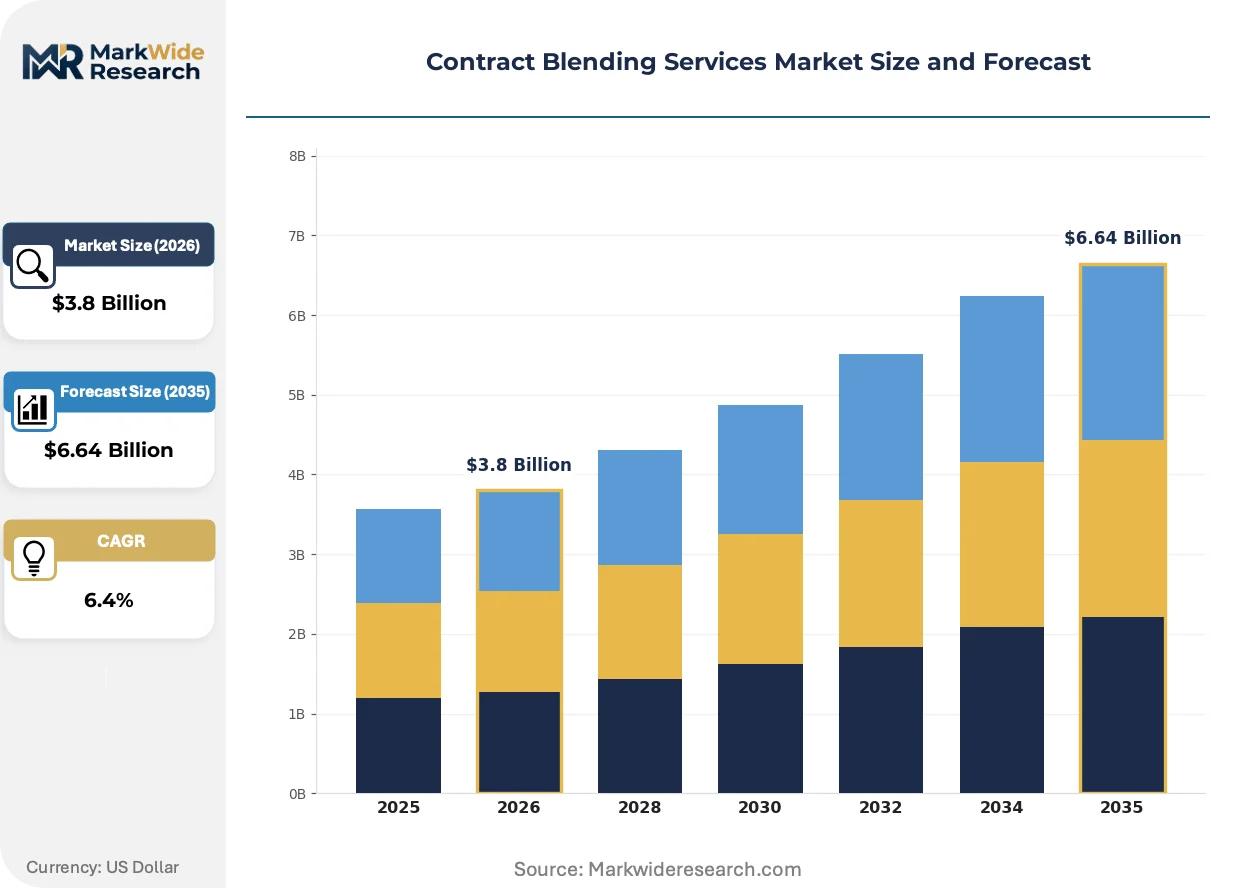
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Liquid Blending, Powder Blending, Specialty Formulations, Custom Blending End Use Industry: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Technology: Batch Processing, Continuous Processing, Automated Systems, Manual Blending Packaging Type: Bags, Drums, Bulk Containers, Jars |
| Companies Covered | Brenntag AG, Univar Solutions Inc., IMCD Group, Azelis, Caldic B.V., Barentz International, DKSH Holding Ltd., Royal Chemical Company, Advanced Blending, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Blending Services Market Strategic Shifts
Digital quality systems and modular processing equipment are compressing the traditional trade-off between batch flexibility and continuous throughput economics in contract manufacturing.
Single-use containment technologies for potent compound handling are miniaturizing cleanroom footprint requirements while maintaining OEL compliance. Biopharma contract manufacturers in Switzerland and Massachusetts are retrofitting existing suites with disposable isolators rather than constructing dedicated facilities. This technology is miniaturizing the capital barrier for entry into high-potency blending services, enabling mid-tier players to capture orphan drug formulation work previously monopolized by vertically integrated pharmaceutical giants.
FDA's evolving guidance on dietary supplement Current Good Manufacturing Practice elevates documentation burdens for contract blenders serving nutraceutical brands. Electronic batch records and supplier qualification protocols now function as competitive filters rather than baseline compliance. Small-scale formulation houses in California and Florida are consolidating or exiting as the cost of 483-response remediation exceeds projected contract margins.
Brand owners are unbundling technical service packages from pure blending execution, creating a two-tier procurement structure. Large chemical distributors compete on tankage access and logistics integration while boutique specialists capture premium pricing for formulation development and stability testing. This bifurcation is most visible in German and Dutch markets where pharmaceutical clustering enables efficient specialist-sourcing for complex delivery systems.
Contract Blending Services Market Segmentation
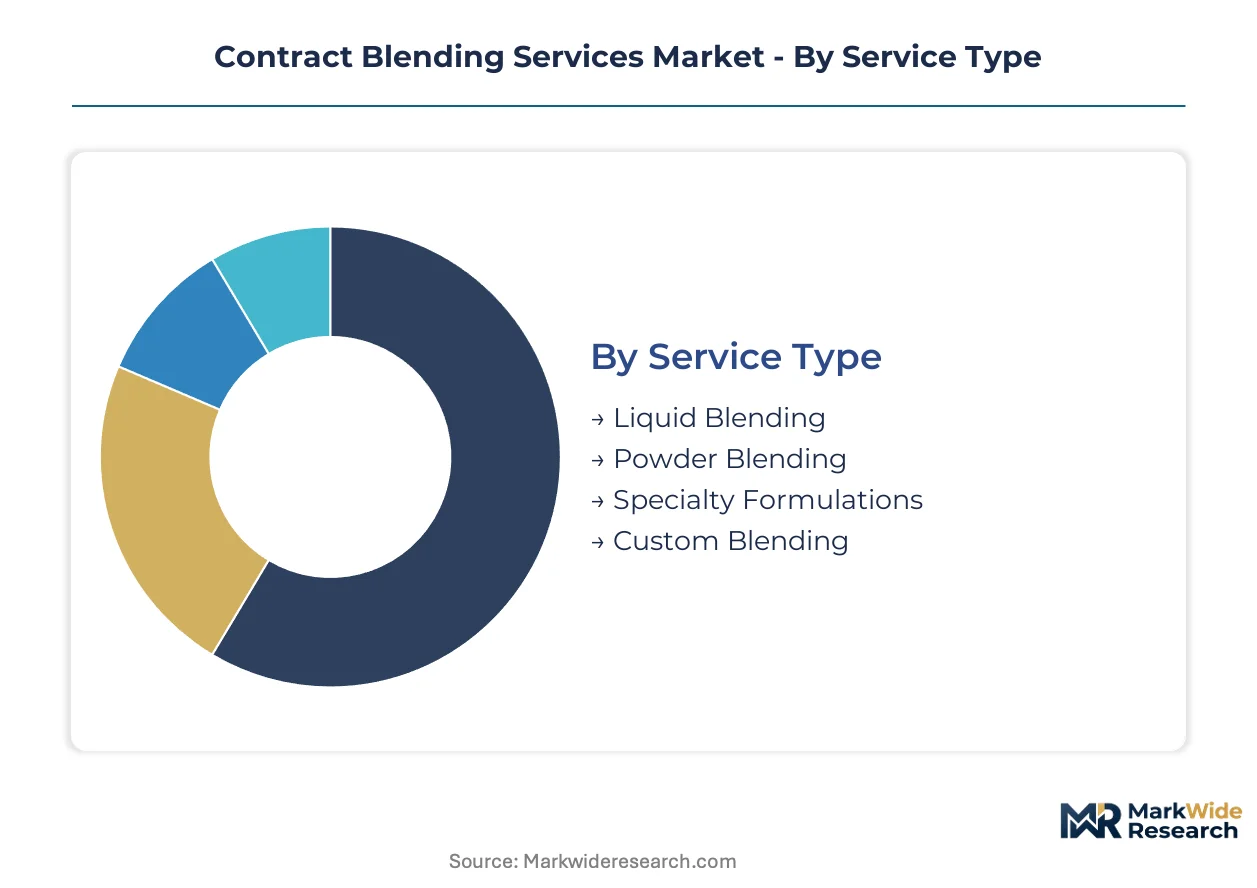
Contract blending services fragment across service capabilities, regulatory intensity, and automation architecture. Each segmentation dimension carries distinct margin profiles and capital requirements that reshape vendor selection criteria for brand owners.
Service Type:
FDA dietary supplement CGMP and REACH substance registration create divergent compliance burdens across service categories, elevating documentation infrastructure from cost center to competitive moat.
- Liquid Blending:Tank farm infrastructure achieves viscosity specifications within 5% tolerance through automated dosing systems. Demand concentrates in Germany's Ludwigshafen and Leverkusen clusters where pharmaceutical manufacturing density supports variable-cost economics for outsourced compounding.
- Specialty Formulations:Complex active-delivery systems for nutraceutical brands demand formulation chemistry expertise with particle size distributions below 100 microns. Boutique houses in Swiss and Massachusetts biopharma corridors command premium positioning for cosmeceutical applications.
- Powder Blending:Mechanical integration of multiple raw materials into homogeneous intermediates serves manufacturers lacking in-house compounding capacity.
- Custom Blending:Project-specific formulation development accommodates portfolio volatility and geographic regulatory fragmentation for mid-scale brand owners.
Established volume favors liquid blending; emerging adoption favors specialty formulations.
End Use Industry:
Customer procurement patterns split between commodity chemical distributors and boutique technical service providers based on formulation complexity thresholds.
- Pharmaceuticals:Electronic batch records and process analytical technology reduce deviation rates in facilities serving CDSCO-harmonized clinical trial material production. Indian regulatory alignment with ICH guidelines attracts multinational brands seeking cost-advantaged quality documentation.
- Nutraceuticals:FDA evolving guidance on dietary supplement CGMP elevates supplier qualification protocols as competitive filters. Small-scale California and Florida formulation houses face consolidation pressure as 483-response remediation costs exceed contract margins.
- Cosmetics:Cosmeceutical active-delivery systems drive outsourcing of complex formulation chemistry.
- Food & Beverage:HACCP implementation functions as baseline market-access credential with limited differentiation potential.
Regulatory stringency concentrates procurement in pharmaceuticals; margin expansion climbs fastest in nutraceuticals.
Technology:
Capital deployment intensity separates batch-flexible operations from continuous-throughput investments with divergent payback horizons.
- Automated Systems:Electronic batch records and process analytical technology compress deviation rates in pharmaceutical-grade facilities. FDA real-time release testing mandates create service revenue streams for PAT-enabled continuous processing lines.
- Batch Processing:Prevailing technology architecture maintains flexibility for multi-product facilities despite longer cycle times and higher labor intensity.
- Continuous Processing:Modular equipment configurations challenge traditional trade-offs between flexibility and throughput economics.
- Manual Blending:Limited to low-volume specialty applications where changeover frequency defeats automation returns.
Asset utilization favors batch processing; capability premiums accrue to automated systems.
Packaging Type:
Logistics integration requirements and contamination risk profiles determine packaging selection across liquid and powder service lines.
- Bulk Containers:Tankage infrastructure concentration with large-scale chemical distributors enables volume economics in commodity liquid segments.
- Drums:Standard intermediate packaging for multi-modal chemical distribution with established handling protocols.
- Bags:Powder blend applications with particle size specifications below 100 microns require moisture-barrier configurations.
- Jars:Finished goods packaging for cosmeceutical and nutraceutical direct-to-brand fulfillment.
Throughput scale favors bulk containers; specialty positioning favors jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in active pharmaceutical ingredients and specialty chemicals are redirecting contract blending demand toward jurisdictions with regulatory equivalence and cost-advantaged manufacturing infrastructure.
United States
Nutraceutical brands in California and Florida are consolidating supplier bases as FDA dietary supplement CGMP enforcement intensifies. The agency's evolving guidance elevates electronic batch records from operational convenience to competitive necessity. Small-scale formulation houses face exit pressure as 483-response remediation costs exceed projected contract margins.
Germany
Chemical processing infrastructure around Ludwigshafen and Leverkusen concentrates liquid blending capacity with favorable variable-cost economics. ECHA REACH substance registration requirements push brand owners toward established contract partners with dossier capabilities rather than in-house compounding investments. Pharmaceutical manufacturing density in these clusters supports outsourced compounding for both domestic consumption and re-export.
Switzerland
Biopharma contract manufacturers are retrofitting existing suites with single-use containment technologies for potent compound handling. Swissmedic oversight maintains stringent occupational exposure limit compliance while disposable isolators miniaturize capital barriers for high-potency blending services. Basel and Zürich corridors attract orphan drug formulation work through this technology transition.
India
CDSCO harmonization with ICH guidelines attracts multinational brands seeking cost-advantaged clinical trial material production. The regulator's alignment with international standards enables equivalent quality documentation at reduced cost points. Hyderabad and Ahmedabad pharmaceutical clusters are expanding contract blending capacity to capture this outsourcing migration.
China
Active pharmaceutical ingredient export quotas and energy-intensive synthesis constraints are compressing margin predictability for fixed-price blending contracts. NMPA oversight of contract manufacturing organizations is tightening documentation requirements for imported excipients. Shanghai and Jiangsu province chemical parks are upgrading quality infrastructure to maintain access to European and North American brand owner procurement.
Contract Blending Services Market Competitive Environment
Concentration sits with large-scale chemical distributors possessing integrated tank farm infrastructure and established logistics networks. The vendor base separates into volume-driven commodity blenders and premium-positioned formulation specialists. Three archetypes dominate: integrated distributors with tankage assets, boutique houses with formulation chemistry expertise, and regional players with regulatory dossier capabilities. Competitive moves center on M&A consolidation of mid-tier facilities and strategic partnerships bridging technical service gaps.
Within the integrated distributor tier, Brenntag AG and Univar Solutions Inc. exemplify scale-driven positioning through tank farm infrastructure and technical service extensions. IMCD Group occupies a specialty formulations position where formulation chemistry expertise commands premium pricing. These three entities represent the structural bifurcation between commodity volume economics and boutique technical service premiums.
| Leading Market Players |
|---|
| Brenntag AG |
| Univar Solutions Inc. |
| IMCD Group |
| Azelis |
| Caldic B.V. |
| Barentz International |
| DKSH Holding Ltd. |
| Royal Chemical Company |
| Advanced Blending |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with pharmaceutical-grade facilities lock in both API supply access and margin visibility for nutraceutical brand owners navigating FDA dietary supplement CGMP enforcement volatility. These contract structures insulate buyers from spot market fluctuations in active pharmaceutical ingredient pricing while committing blenders to dedicated tankage capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in contract blending services. Price differentiation rests on certification grade—FDA pharmaceutical-tier versus ISO 9001 food-grade—and volume scale commitments. Cost compression in standard-tier liquid blending is intensifying because tankage infrastructure concentration favors large-scale chemical distributors with fixed-cost absorption. Mid-tier facilities lacking electronic batch record capabilities face the steepest price sensitivity as brand owners consolidate supplier bases.
Supply Chain Analysis
Shanghai port congestion and customs processing delays for REACH-registered excipients underwrite supply vulnerability for European contract blenders dependent on Chinese API inputs. Active pharmaceutical ingredient supply concentrates in India, China, and Switzerland, with formulation chemistry expertise clustering in Basel and Massachusetts biopharma corridors. Raw material dependencies span spray-dried excipients, hot-melt extrusion polymers, and single-use containment systems. Distribution runs through integrated tank farm networks for liquid volumes and specialized cold-chain logistics for temperature-sensitive powder blends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract blending services function as a regulatory entrenchment story where established quality management systems create switching costs that exceed the capital requirements for facility buildout. Dossier capabilities and FDA inspection histories accumulate as defensive moats that new entrants cannot replicate quickly.
For Market Incumbents: Fortify position through backward integration into spray-drying and hot-melt extrusion technologies that extend service offerings beyond intermediate powders into finished dosage forms. Expand tankage capacity in Germany's Ludwigshafen and Leverkusen clusters to capture re-export demand from REACH-compliant brand owners. Single-use containment retrofit investments neutralize boutique competitor threats in high-potency orphan drug segments. For New Entrants and Emerging Players: Lead with particle engineering capabilities in India where CDSCO harmonization with ICH guidelines attracts multinational clinical trial material production seeking cost-advantaged quality documentation. Target nutraceutical specialty formulations in California and Florida where FDA 483-response remediation costs are forcing incumbent exits. Position around formulation chemistry expertise for cosmeceutical active-delivery systems rather than commodity liquid blending. For Investors and Strategic Acquirers: Boutique formulation houses with FDA pharmaceutical-grade accreditation and established electronic batch record infrastructure represent the most defensible acquisition targets. Long-term viability hinges on regulatory dossier capabilities becoming scarcer as enforcement intensifies. Watch for CDSCO inspection capacity expansion as the signal indicating India's contract manufacturing cost advantage is stabilizing rather than eroding.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Particle Engineering | Enables finished dosage form capabilities beyond intermediate powders for nutraceutical brands. |
| Single-Use Containment Retrofit | Reduces capital barriers for high-potency blending services under Swissmedic oversight. |
| Long-term Supply Agreement | Locks in tankage capacity for liquid blending volumes in Germany's chemical processing clusters. |
| Regulatory Dossier Investment | Builds REACH compliance capabilities that ECHA tightening elevates as competitive moats. |
| Geographic Expansion | Captures CDSCO-harmonized clinical trial material production migrating to Hyderabad and Ahmedabad. |
Study Parameters
Operator-level perspectives from plant managers at contract blending facilities, procurement leads at nutraceutical brand owners, regulatory affairs directors navigating FDA dietary supplement CGMP, and technical R&D heads specializing in particle engineering anchored the qualitative base. Secondary validation drew from FDA 483 inspection databases, ECHA REACH registration filings, SEC 10-K disclosures from integrated chemical distributors, and customs trade data for active pharmaceutical ingredient flows. Bottom-up capacity utilization assessments and top-down market sizing triangulated volume estimates across service type and end-use industry segments.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and API price volatility assumptions over the projection horizon. Segmentation dimensions modeled encompassed service type, end-use industry, technology architecture, and packaging format, with regional regulatory cluster effects layered as an overlay. CAGRs were derived from weighted capacity expansion pipelines, brand owner outsourcing propensity indices, and historical deviation rate improvements from PAT-enabled continuous processing adoption.
Forecasts assume regulatory continuity in FDA dietary supplement CGMP enforcement and ECHA REACH substance registration requirements; material policy shifts would require re-modeling. Specific risk factors include API export quota disruptions from Chinese synthesis constraints and accelerated FDA inspection frequency for contract manufacturers. Practitioners should keep alternative scenarios live as CDSCO inspection capacity and single-use containment technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Meal Voucher Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Bar Refrigeration Market
Food Service
Commercial Griddle Market
Food Service
Commercial Grills Market
Food Service
Bangladesh Food Service Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Europe Barbeque Grill Market
Food Service
Africa Foodservice Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
India Full Service Restaurants Market
Food Service
Online Food Delivery Market
Food Service
West Africa Food Services Market
Food Service
India Inflight Catering Market