
 Europe Aluminium Powder Market | 2026-2036
Europe Aluminium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aluminium Powder Market Intelligence
The performance gap between premium atomized grades and commodity flake powders is broadening across European supply chains. Höganäs AB anchors its position through captive atomization capacity in Sweden, while ECKA Granules differentiates via specialized paste formulations for coatings. ALTANA AG leverages its pigment technology heritage to dominate decorative flake segments. GKN Powder Metallurgy sustains automotive component leadership through precision powder consistency.
Aluminium powder consists of finely divided metallic aluminium particles, typically produced through air or inert gas atomization, with particle sizes ranging from sub-micron to several hundred microns and purity grades from technical to high-purity. The material serves primarily as a feedstock for powder metallurgy, chemical reactions, pyrotechnics, and surface coatings where reactivity, reflectivity, or sinterability are required. Atomized aluminium commands the largest volume share across European consumption, driven by metal injection molding and additive manufacturing uptake. Flake aluminium retains margin concentration in coatings and electronics applications where optical properties determine value. Aluminium powder paste is gaining traction in chemical processing and explosives formulations as handlers seek reduced dust exposure.
REACH registration requirements and the EU Green Deal carbon accounting frameworks are reshaping supplier qualification protocols across the continent. ECHA substance evaluations and CE marking obligations for processed aluminium products are pushing producers toward documented lifecycle transparency. Germany's Federal Environment Agency and France's ANSES coordinate national enforcement of these standards. Buyers must now verify upstream energy sources and waste treatment methods before qualifying new suppliers. Stakeholders should monitor evolving battery-grade powder specifications as European cell manufacturing scales.
Market Dynamics
REACH substance evaluations and EU Green Deal carbon accounting frameworks are forcing atomization facilities to document upstream energy sources and waste treatment protocols before buyers will qualify new suppliers.
Growth Catalysts
- Automotive powder metallurgy:Germany's automotive corridor is expanding metal injection molding capacity for lightweight drivetrain components. Tier-1 suppliers are qualifying new atomized powder grades to meet lightweighting mandates.
- REACH registration tiering:The 2024-2025 tonnage band deadlines for aluminium powder registration are pushing non-compliant producers out of the market. Surviving suppliers are capturing displaced volume.
- Inert gas atomization:Nitrogen and argon atomization systems are displacing air atomization for high-purity grades. Aerospace additive manufacturers in France are specifying inert-processed feedstock for safety-critical parts.
Market Restraints
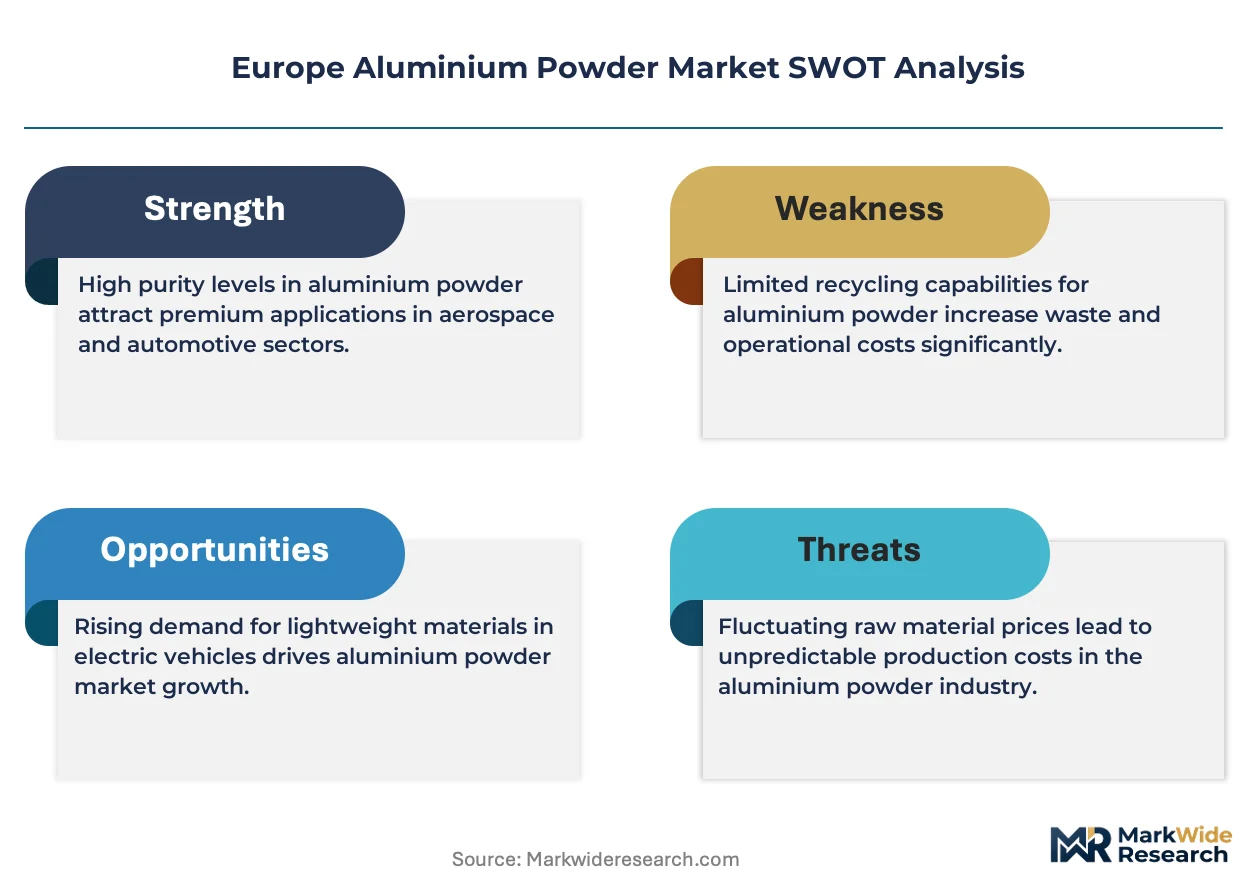
- Energy cost volatility:Natural gas and electricity price spikes since 2022 have compressed margins at European atomization facilities. Producers in Germany and Italy face input cost structures 40% above historical baselines.
- Scrap aluminium concentration:Secondary aluminium supply chains concentrate in Southern Europe, creating geographic mismatch with Northern European powder demand. Transportation premiums erode competitiveness of recycled feedstock.
- Flake powder substitution:Pearlescent pigments and interference pigments are displacing decorative aluminium flake in automotive coatings. Formulators at major paint producers are reducing metal content in basecoat layers.
Strategic Opportunities
- Battery-grade specification development:European cell manufacturing scale-up is creating demand for ultra-high-purity spherical aluminium powder. Producers with existing atomization assets can retrofit for battery anode applications.
- Paste formulation expansion:Aluminium powder paste is gaining share in chemical processing and explosives as handlers prioritize dust exposure reduction. Formulators can capture margin by shifting customers from dry powder to paste delivery.
- CSRD disclosure preparation:The Corporate Sustainability Reporting Directive mandates supply chain carbon transparency from 2024. First-mover producers documenting Scope 3 emissions will qualify for premium procurement contracts.
Industry Challenges
- Additive manufacturing metallurgy expertise:Powder bed fusion and directed energy deposition require specialized lot-to-lot consistency that commodity atomizers struggle to deliver. Technical hiring in Sweden and Germany is competitive.
- REACH dossier maintenance:Substance evaluation updates and new hazard classifications require ongoing toxicology investment. Mid-tier producers face six-figure annual registration costs without guaranteed volume returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aluminium Powder Market |
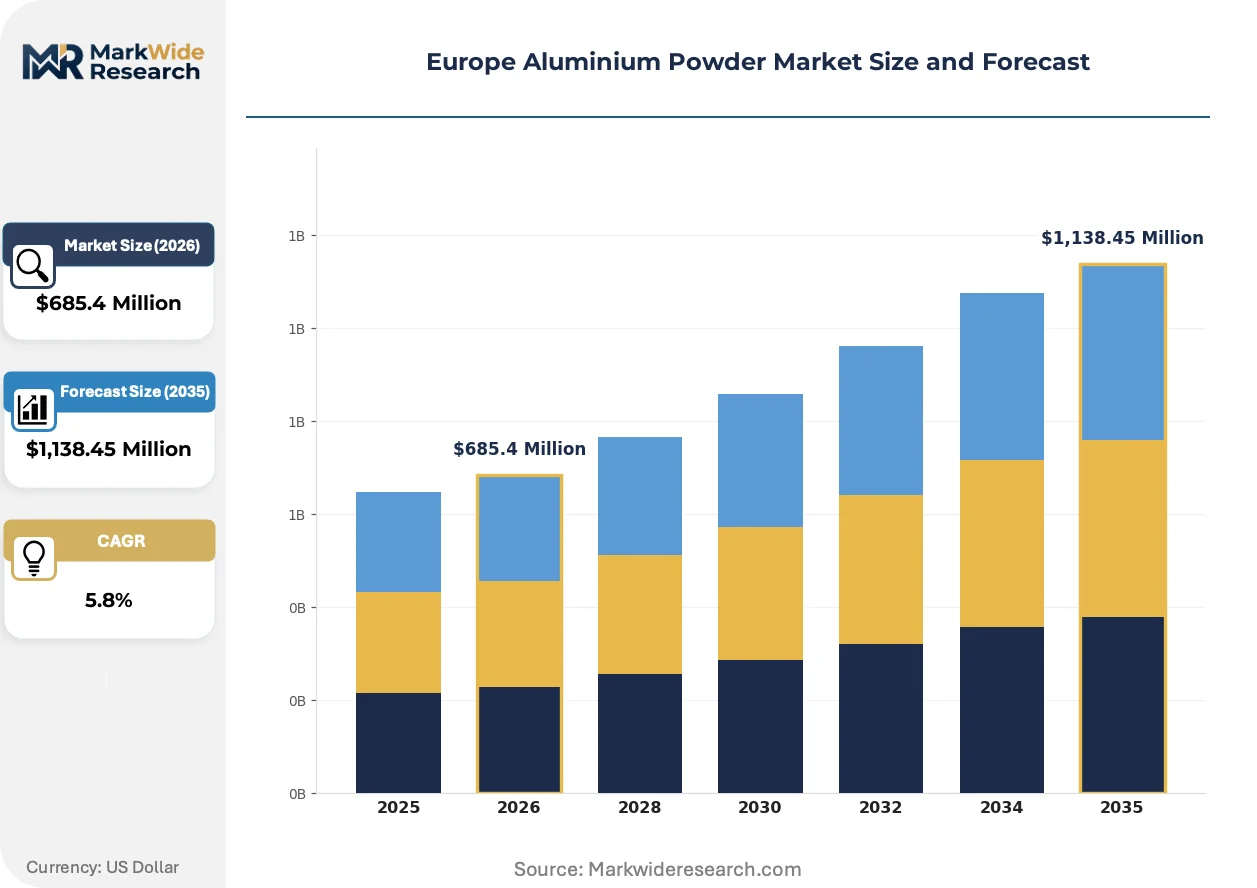
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Aluminium, Flake Aluminium, Granulated Aluminium, Aluminium Powder Paste End User: Aerospace, Automotive Components, Electronics, Chemicals Application: Additives, Coatings, Explosives, Metal Injection Molding Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | ALTANA AG, AMG Advanced Metallurgical Group NV, Höganäs AB, Carlfors Bruk AB, ECKA Granules, AMG Alpoco, Sandvik AB, GKN Powder Metallurgy, Rio Tinto Metal Powders, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aluminium Powder Market Strategic Shifts & Innovations
Closed-loop atomization systems and real-time particle sizing are compressing quality variability while regulatory pressure on carbon intensity is reshaping feedstock sourcing priorities across the value chain.
Plasma rotating electrode process technology is automating the production of spherical aluminium powder with tighter particle size distribution than conventional gas atomization. Aerospace additive manufacturers in Germany are adopting PREP feedstock for laser powder bed fusion of structural brackets. This precision is automating the elimination of post-process hot isostatic pressing for certain safety-critical applications.
ECHA substance evaluation protocols under REACH are tightening purity benchmarks for atomized aluminium grades used in food contact and cosmetics. The 2024-2025 evaluation wave is forcing producers to eliminate trace heavy metal contaminants below 10 ppm thresholds. Battery-grade powder specifications are emerging as the most stringent category, with European cell manufacturers requiring documented absence of specific transition metals.
Direct long-term contracting is displacing spot market purchases among large automotive powder metallurgy consumers. Tier-1 drivetrain suppliers in France and Germany are negotiating three-to-five-year offtake agreements with fixed volume tiers and price adjustment mechanisms. This shift is most visible in the transmission component segment, where just-in-time delivery requirements favor supplier stability over price optimization.
Europe Aluminium Powder Market Segmentation
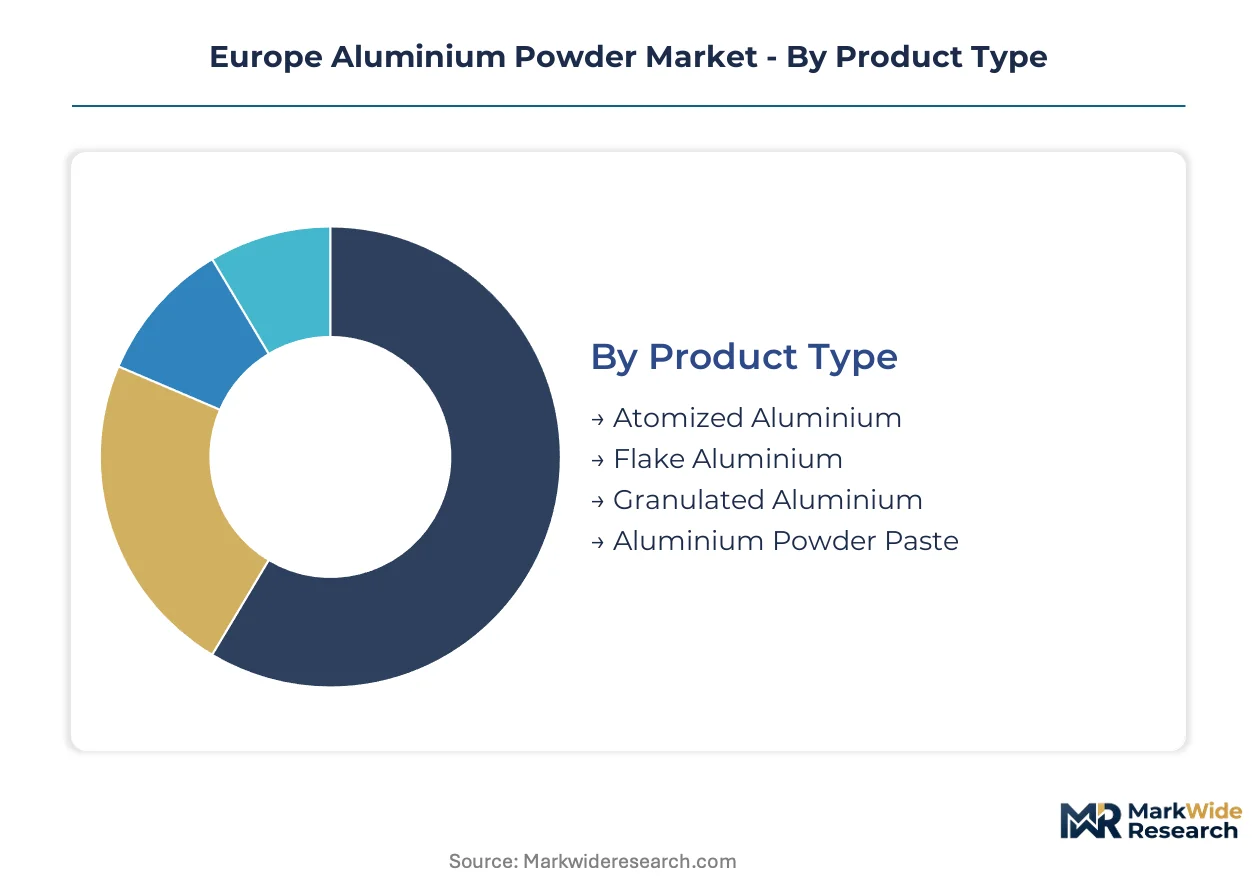
Segmentation in the Europe Aluminium Powder Market reveals how regulatory burden concentrates in high-purity grades while cost pressure shapes commodity categories. Buyers in Germany and France now qualify suppliers differently based on end-use certification requirements.
Product Type:
REACH registration tiering and EU Green Deal carbon accounting impose divergent compliance costs across product categories, with inert-processed grades facing the heaviest documentation burden.
- Atomized Aluminium:Spherical particles produced through nitrogen or argon atomization, with purity grades from technical to high-purity. Demand concentrates in Germany's automotive powder metallurgy corridor as Tier-1 suppliers qualify feedstock for lightweight drivetrain components under tightening lightweighting mandates.
- Flake Aluminium:Lamellar particles manufactured through ball milling of atomized feedstock, prized for reflectivity and coverage. France's aerospace additive manufacturers specify inert-processed flake for safety-critical applications, though pearlescent pigment substitution erodes share in automotive coatings.
- Granulated Aluminium:Agglomerated particles for controlled reactivity applications. Chemical processors in Belgium prefer granulated grades for predictable reaction kinetics.
- Aluminium Powder Paste:Dispersions in mineral spirits or water reducing dust exposure. Explosives formulators across Eastern Europe are converting from dry powder to paste delivery systems.
Leading the category by volume: Atomized Aluminium. Expanding most quickly: Aluminium Powder Paste.
End User:
Customer concentration determines contract structure, with automotive and aerospace buyers negotiating multi-year offtake agreements while chemical and electronics purchasers retain spot-market flexibility.
- Aerospace:Safety-critical structural brackets and additive components requiring lot-to-lot consistency. French and German manufacturers specify PREP-processed spherical powder for laser powder bed fusion, eliminating post-process hot isostatic pressing for certain applications.
- Automotive Components:Transmission gears, valve seats, and chassis parts via metal injection molding. Germany's Federal Environment Agency enforces REACH compliance for powder metallurgy suppliers serving domestic OEMs.
- Electronics:Conductive pastes and thermal interface materials. Dutch semiconductor packaging facilities drive demand for sub-10 micron spherical grades.
- Chemicals:Feedstock for pigments, pyrotechnics, and solid rocket propellants. Italian fireworks manufacturers source atomized grades through specialized distributors.
Highest procurement contract duration: Aerospace and Automotive Components. Fastest qualification timeline: Chemicals.
Application:
Application selection dictates particle morphology requirements, with spherical grades commanding premium positioning in additive processes versus irregular morphologies in chemical reactions.
- Additives:Functional fillers in plastics and composites. German compounders specify atomized grades for thermal conductivity enhancement in LED housings.
- Coatings:Protective and decorative surface finishes. Automotive basecoat formulators in Spain are reducing metal content as interference pigments displace decorative flake.
- Explosives:Aluminized compositions for mining and defense. Polish industrial explosives producers favor paste formulations for handling safety.
- Metal Injection Molding:Near-net-shape component fabrication. Sweden's captive atomization capacity serves precision MIM feedstock demand across Nordic markets.
Widest specification tolerance: Coatings. Tightest purity thresholds: Metal Injection Molding.
Distribution Channel:
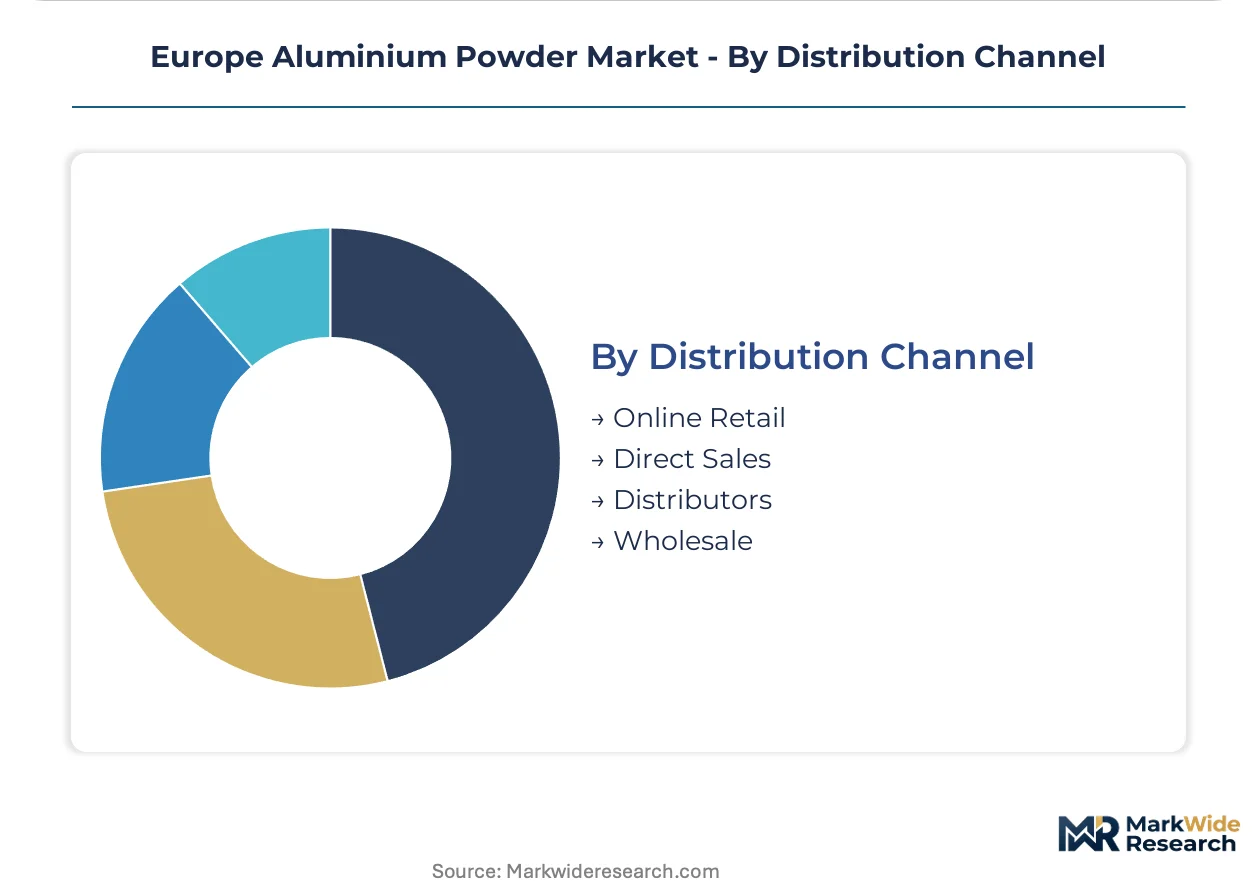
Channel selection reflects buyer scale and technical service requirements, with large automotive consumers bypassing intermediaries while smaller chemical processors rely on distributor technical support.
- Direct Sales:Long-term contracts with volume commitments and technical collaboration. GKN Powder Metallurgy and Höganäs AB serve German Tier-1 suppliers through dedicated account teams.
- Distributors:Technical representation for mid-tier processors. ECKA Granules leverages specialized distributors for coatings paste formulations across Southern Europe.
- Wholesale:Bulk transactions for standardized grades. Secondary aluminium traders in Italy supply wholesale channels for commodity atomized powder.
- Online Retail:Small-lot procurement for R&D and specialty applications. Limited penetration due to hazardous material shipping restrictions under ADR regulations.
Dominant channel by volume: Direct Sales. Fastest digital adoption: Distributors adding e-commerce portals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates Europe's aluminium powder demand through Germany's automotive powder metallurgy cluster, where Tier-1 suppliers qualify atomized feedstock for lightweight drivetrain components.
Germany
Metal injection molding capacity expands across Baden-Württemberg and Bavaria for transmission gears and valve seats. The Federal Environment Agency enforces REACH compliance for powder metallurgy suppliers serving domestic OEMs. Stuttgart's automotive engineering cluster drives qualification of new atomized powder grades under tightening lightweighting mandates.
France
Aerospace additive manufacturers in Toulouse and Bordeaux specify PREP-processed spherical powder for laser powder bed fusion of structural brackets. ANSES coordinates national enforcement of ECHA substance evaluation protocols for high-purity grades. The Île-de-France region hosts specialized distributors serving explosives formulators converting to paste delivery systems.
Sweden
Captive atomization capacity in Höganäs anchors precision MIM feedstock supply across Nordic markets. The Swedish Chemicals Agency implements REACH registration tiering deadlines that push non-compliant producers out of the market. Sandviken's materials technology corridor concentrates plasma rotating electrode process development for aerospace-grade spherical powder.
Italy
Fireworks manufacturers in Naples and Brescia source atomized grades through specialized distributors for pyrotechnic applications. Secondary aluminium supply chains concentrate in Southern Europe, creating geographic mismatch with Northern European powder demand. Milan's chemical processing cluster favors granulated aluminium for controlled reactivity applications.
Netherlands
Semiconductor packaging facilities in Eindhoven drive demand for sub-10 micron spherical grades in conductive pastes and thermal interface materials. The Dutch National Institute for Public Health and the Environment monitors ECHA substance evaluations for electronics-grade purity benchmarks. Rotterdam's port logistics hub handles bulk atomized powder shipments for distribution across Benelux chemical processors.
Europe Aluminium Powder Market Key Industry Players
Premium-margin players sit above commodity-margin players across the purity-certification axis, with inert-gas-atomized grades commanding structural premiums over air-atomized feedstock. The vendor base organizes into three tiers: integrated powder metallurgy specialists, standalone atomization houses, and coating-focused paste formulators. Dominant competitive moves include captive backward integration into atomization assets and multi-year offtake contracting with automotive Tier-1 suppliers.
Among Nordic integrated specialists, Höganäs AB exemplifies the captive atomization archetype, while Sandvik AB occupies a position in precision materials engineering. ECKA Granules represents the specialized paste formulation tier, anchoring coating applications through differentiated delivery systems. These three entities illustrate how geographic concentration in Northern Europe aligns with technical specialization across the value chain.
| Leading Market Players |
|---|
| ALTANA AG |
| AMG Advanced Metallurgical Group NV |
| Höganäs AB |
| Carlfors Bruk AB |
| ECKA Granules |
| AMG Alpoco |
| Sandvik AB |
| GKN Powder Metallurgy |
| Rio Tinto Metal Powders |
| Others |
Cost & Logistics Intelligence
Specialized metallurgy engineers concentrated in Sweden's Sandviken corridor command wage premiums that propagate through atomized powder pricing tiers, widening spreads between commodity flake and aerospace-grade spherical feedstock as labor intensity diverges across production methods.
Pricing Analysis
Value-based pricing anchored to sintered component yield rates dominates long-term offtake agreements with German automotive Tier-1 suppliers. Price differentiation rests on REACH registration tier and inert gas atomization certification, with battery-grade specifications commanding structural premiums over technical grades. Cost compression in commodity flake segments intensifies as pearlescent pigments displace decorative metal content. Chemical processors and explosives formulators exhibit highest price sensitivity, while aerospace additive manufacturers prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
Freight cost differentials between Southern European secondary aluminium concentration and Northern European atomization demand erode recycled feedstock competitiveness against primary metal. Supply concentrates in Germany, Sweden, and France, with captive atomization assets anchoring precision feedstock availability. Raw material sourcing draws from primary aluminium smelters, scrap collection networks, and inert gas suppliers. Single-source vulnerability persists for PREP-processed spherical grades serving safety-critical aerospace applications. Distribution runs through direct sales channels for automotive volume, with specialized distributors handling paste formulations and smaller chemical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European aluminium powder supply operates under binding capacity constraints, with inert gas atomization bottlenecks propping pricing power for qualified producers as REACH registration deadlines eliminate marginal competitors.
For Market Incumbents: Cement market position through captive backward integration into atomization assets and multi-year offtake contracting with German transmission component suppliers. Pearlescent pigment substitution threatens decorative flake margins; respond by accelerating paste formulation capacity for explosives and chemical processing segments. Prioritize CSRD disclosure preparation to capture premium procurement contracts from carbon-transparent buyers.
For New Entrants and Emerging Players: REACH registration tiering in Europe opens a window for specialized battery-grade powder production as European cell manufacturing scales. Target ultra-high-purity spherical grades for anode applications where incumbent atomizers lack retrofit flexibility. Enter through toll-processing arrangements with existing facilities to bypass capital-intensive atomization buildout.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated powder metallurgy specialists given automotive lightweighting mandates and additive manufacturing qualification timelines. Long-term viability favors producers with documented Scope 3 transparency and captive Nordic atomization capacity. Monitor PREP technology adoption rates among French aerospace manufacturers as inflection indicator for spherical powder demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Atomization Capacity Expansion | Höganäs AB's Swedish facilities anchor precision MIM feedstock supply across Nordic automotive clusters. |
| Long-term Supply Agreement | German Tier-1 drivetrain suppliers negotiate three-to-five-year offtake contracts with fixed volume tiers. |
| Green Manufacturing Transition | CSRD disclosure preparation qualifies producers for premium procurement from carbon-transparent buyers. |
| Joint Venture | Specialized paste formulators partner with Eastern European explosives handlers converting from dry powder. |
| Backward Integration | Automotive powder metallurgy specialists acquire atomization assets to secure feedstock consistency. |
Research Approach
Independent corroboration across plant managers at atomization facilities, procurement leads at German Tier-1 automotive suppliers, and technical R&D directors at coating formulators underwrites the qualitative findings. Primary interviews with distribution channel partners and explosives formulators across Poland and Italy combined with secondary validation from ECHA substance evaluation databases, EU customs trade data, and SEC filings of listed metallurgical groups. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulate volume estimates.
Rate-of-change decomposition across product type, end-use industry, and regional production hub segments structures the analytical framework over the projection horizon. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Battery-grade specification emergence and PREP technology penetration serve as industry-specific forecast inputs alongside automotive lightweighting mandate compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for plasma rotating electrode process scaling would alter the outlook for spherical powder supply-demand balance. Forecasts reflect assumptions about REACH enforcement intensity and energy cost normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Flat Carbon Steel Market
Metals
Stainless Steel 400 Series Market
Metals
Crude Steel Market
Metals
Liquid Metal Thermal Pad Market
Metals
Europe Aluminium Wire Rod Market
Metals
Global Aluminium Wire Rod Market
Metals
Platinum Compounds Market
Metals
Aluminium Forging Market
Metals
Saudi Arabia Aluminum Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Nickel Sulfate Market
Metals
Tinplate Market
Metals
Global Oxygen-Free Copper Market
Metals
Galvanized Steel Market
Metals
Copper Foil Market
Metals
Global Metal and Metal Manufactured Products Market