
 Arylamide Pigments Market | 2026-2036
Arylamide Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Arylamide Pigments Market Outlook
Aftermarket color-matching services is reshaping margin distribution across the value chain. BASF SE leverages its integrated pigment-dispersion platform to capture downstream value in automotive refinish workflows. Clariant AG anchors its position through specialized surface-modified grades that command premium positioning in high-performance coatings. Heubach GmbH competes through manufacturing scale across European and Asian production assets.
Arylamide pigments constitute a class of synthetic organic colorants derived from acetoacetanilide coupling components, typically offering lightfastness ratings of 6-8 on the Blue Wool Scale and thermal stability exceeding 200°C for plastics processing. These pigments serve primarily as cost-effective alternatives to high-performance pigments in decorative and industrial coloration. Polymeric variants now lead volume growth as manufacturers seek migration-resistant solutions for food-contact plastics and toy applications. Chemical synthesis remains the dominant technology pathway, though surface modification commands superior margins by solving dispersion failures in waterborne coating systems.
REACH registration requirements in Europe and EPA TSCA oversight in the United States compel reformulation away from legacy diarylide chemistries toward arylamide structures with improved toxicological profiles. China's GB standards for toy safety and food packaging migration limits similarly redirect procurement specifications across export-oriented manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to emerging standards elsewhere.
Market Dynamics
Waterborne coating systems are displacing solvent-based formulations across automotive refinishing, forcing pigment manufacturers to reformulate surface chemistries for dispersion stability without volatile organic compounds.
Growth Catalysts
- REACH Registration:European ECHA compliance deadlines are accelerating migration from legacy diarylide pigments toward arylamide structures with superior toxicological profiles in consumer-facing applications.
- Automotive Refinishing:Collision repair networks in North America and Europe require color-matching precision that arylamide pigments deliver at cost points below high-performance alternatives.
- Polymeric Pigment Innovation:Migration-resistant molecular architectures are opening food-contact plastics and toy manufacturing to organic colorants previously excluded by safety standards.
Market Restraints
- Raw Material Concentration:Acetoacetanilide coupling components depend on petrochemical feedstocks concentrated in Gulf Coast and Northeast Asian refining clusters, exposing formulators to price volatility.
- Substitution Pressure:Inorganic pigments and high-performance diketopyrrolopyrrole chemistries capture premium coating segments where thermal stability exceeds 250°C.
- Regulatory Divergence:China's GB standards for toy safety, EPA TSCA oversight in the United States, and REACH in Europe create incompatible compliance requirements that fragment formulation strategies.
Strategic Opportunities
- India Manufacturing:BIS certification requirements and domestic coating capacity expansion create procurement openings for pigment suppliers with localized technical service capabilities.
- Digital Color Matching:Spectrophotometer-integrated dispensing systems in body shops are creating demand for tightly specified pigment grades with batch-to-batch consistency.
- Bio-Based Coupling Components:Renewable acetoacetanilide derivatives from agricultural waste streams align with EU Green Deal procurement criteria for public infrastructure coatings.
Industry Challenges
- Formulation Chemistry Expertise:Surface modification protocols for waterborne compatibility require specialized knowledge scarce among regional distributors serving small and mid-sized coating plants.
- Capital Equipment Refresh:Milling and micronization assets must accommodate tighter particle size distributions demanded by automotive color-matching systems, requiring substantial equipment investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arylamide Pigments Market |
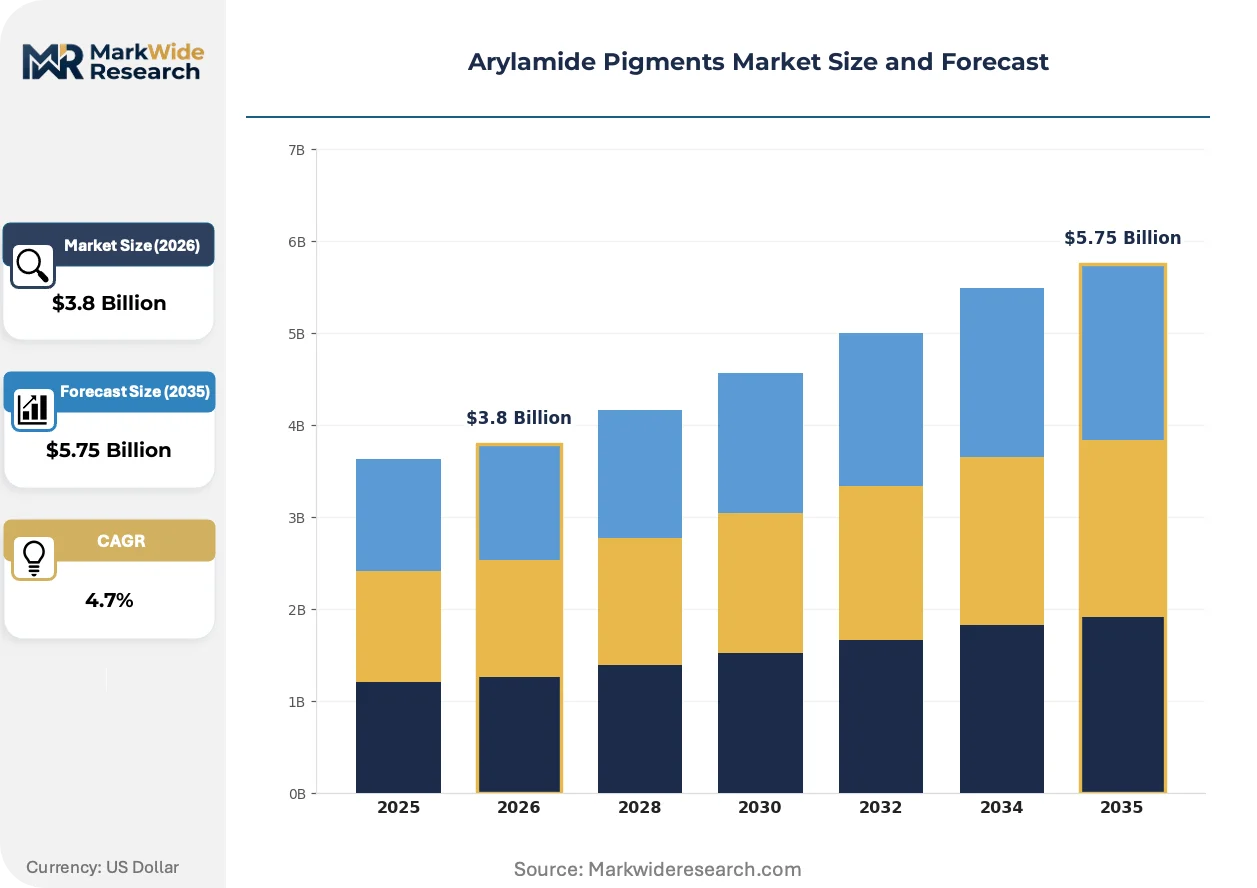
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomeric, Oligomeric, Polymeric, Dye Application: Coatings, Plastics, Inks, Textiles End User: Automotive, Construction, Consumer Goods, Electronics Technology: Chemical Synthesis, Surface Modification, Nanotechnology, Biodegradable |
| Companies Covered | DIC Corporation, Chroma Australia, BASF SE, Hangzhou Aibai Chemical Co., Ltd, Brenntag UK Limited, Clariant AG, Heubach GmbH, Hollindia Internatianak Bv, Sun Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arylamide Pigments Market Strategic Shifts
Computational tools are compressing development cycles for pigment dispersion formulations while regulatory pressure on volatile organic compounds accelerates waterborne system adoption across industrial coating segments.
Surface modification chemistry is digitizing quality control protocols in pigment manufacturing. Advanced particle characterization systems now enable real-time adjustment of surface treatment parameters during production. Coating formulators in automotive OEM and refinish segments are adopting these precision grades to reduce mill-base preparation time. The technology is digitizing specification workflows that previously relied on subjective visual assessment.
EPA TSCA Section 6 restrictions on per- and polyfluoroalkyl substances are forcing reformulation of stain-resistant coatings that historically relied on fluorinated additives. Arylamide pigments with engineered surface properties offer partial functionality replacement in architectural and industrial applications. Coating manufacturers serving the United States market are accelerating qualification programs to maintain product listings with retail and commercial distribution partners.
Specification consolidation among multinational coating houses is compressing supplier qualification timelines. Procurement teams at BASF Coatings, PPG Industries, and AkzoNobel are consolidating pigment approvals to reduce formulation complexity across regional product lines. Technical service capabilities and documented regulatory compliance now outweigh price in vendor selection criteria. This shift is most visible in European automotive refinish supply chains where liability exposure drives conservative sourcing decisions.
Arylamide Pigments Market Segmentation
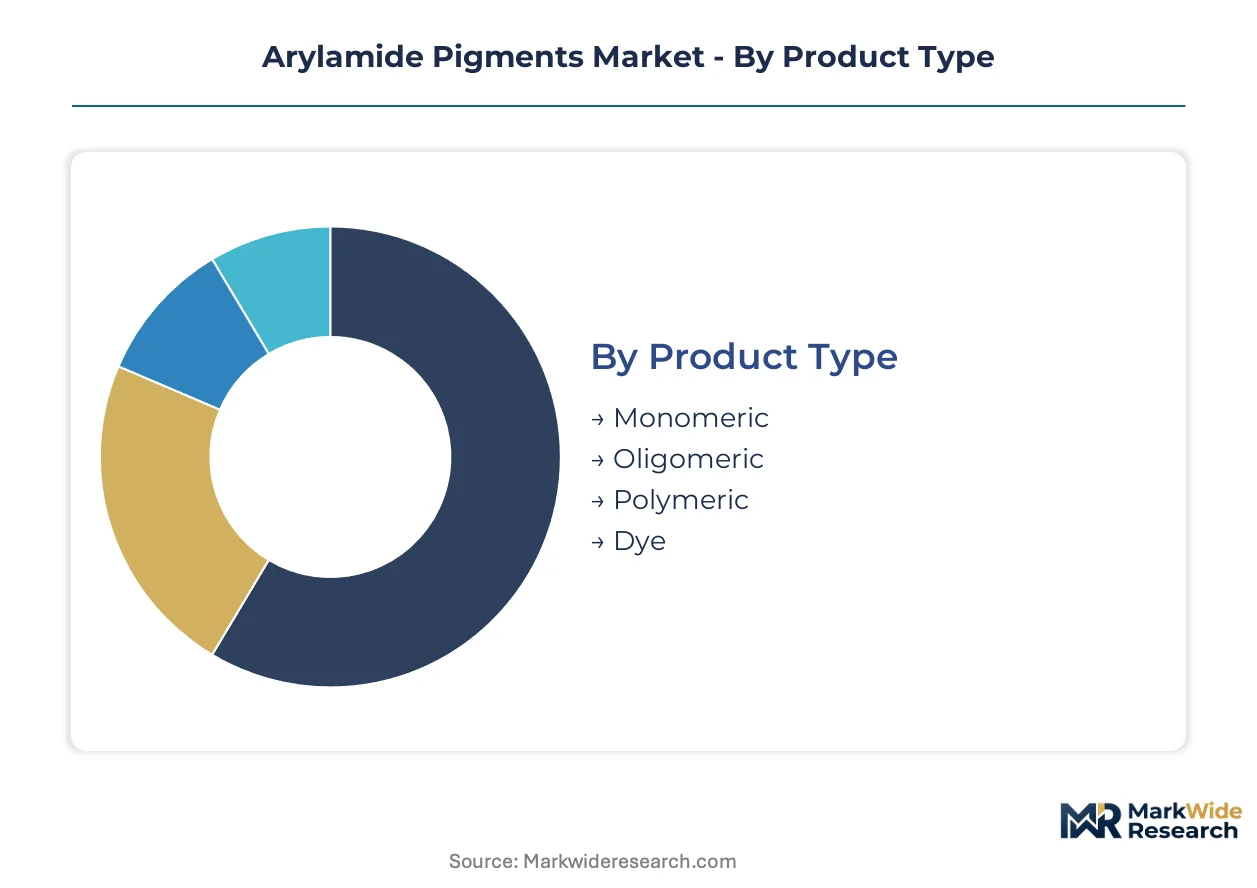
Arylamide pigments serve heterogeneous performance requirements across coating, plastic, and ink formulations. Segmentation reveals how molecular architecture and processing technology align with end-use specifications and regulatory constraints.
Product Type:
Molecular weight distribution separates mature commodity grades from emerging high-performance architectures.
- Monomeric:Low molecular weight structures deliver standard lightfastness ratings for general industrial coatings. Demand concentrates in Chinese export-oriented coating plants serving Southeast Asian construction markets, constrained by REACH migration limits in European-bound goods.
- Polymeric:High molecular weight variants bind pigment molecules into migration-resistant matrices. Food-contact plastics manufacturers in Germany and France specify these grades for compliance with EFSA migration thresholds, driving premium positioning.
- Oligomeric:Intermediate molecular architectures balance cost and performance for mid-tier coating applications.
- Dye:Soluble colorants for specialty inkjet and textile printing systems requiring transparency.
Monomeric grades handle the majority of throughput; polymeric variants are expanding most quickly on share.
Application:
Coating system chemistry determines dispersion stability requirements and surface modification intensity.
- Coatings:Waterborne automotive refinish systems demand surface-treated grades with controlled particle size distributions. Collision repair networks in the United States and Germany require batch-to-batch consistency for spectrophotometer color matching.
- Plastics:Polyolefin and PVC processing exposes pigments to shear heat exceeding 200°C. Toy manufacturers in China source polymeric variants to meet GB standard migration limits for export markets.
- Inks:Offset and flexographic printing applications prioritize transparency and rheological stability.
- Textiles:Fiber dyeing and printing applications favor high tinctorial strength for cotton and polyester substrates.
Coatings command the dominant volume position; plastics is climbing the fastest as food-contact specifications tighten.
End User:
Customer procurement sophistication spans Tier 1 multinationals with consolidated specifications to regional coating plants.
- Automotive:OEM and refinish segments drive the most stringent quality protocols. PPG Industries and BASF Coatings mandate documented REACH compliance and surface modification certificates for European supply chains.
- Consumer Goods:Toy and food packaging manufacturers face converging safety standards across export destinations. Chinese producers navigate GB standards, REACH, and FDA thresholds simultaneously.
- Construction:Architectural coatings for infrastructure and residential applications prioritize cost efficiency over premium performance.
- Electronics:Specialty applications in display and device housings require thermal stability beyond standard arylamide specifications.
Automotive handles the majority of throughput; consumer goods is gaining share fastest on regulatory convergence.
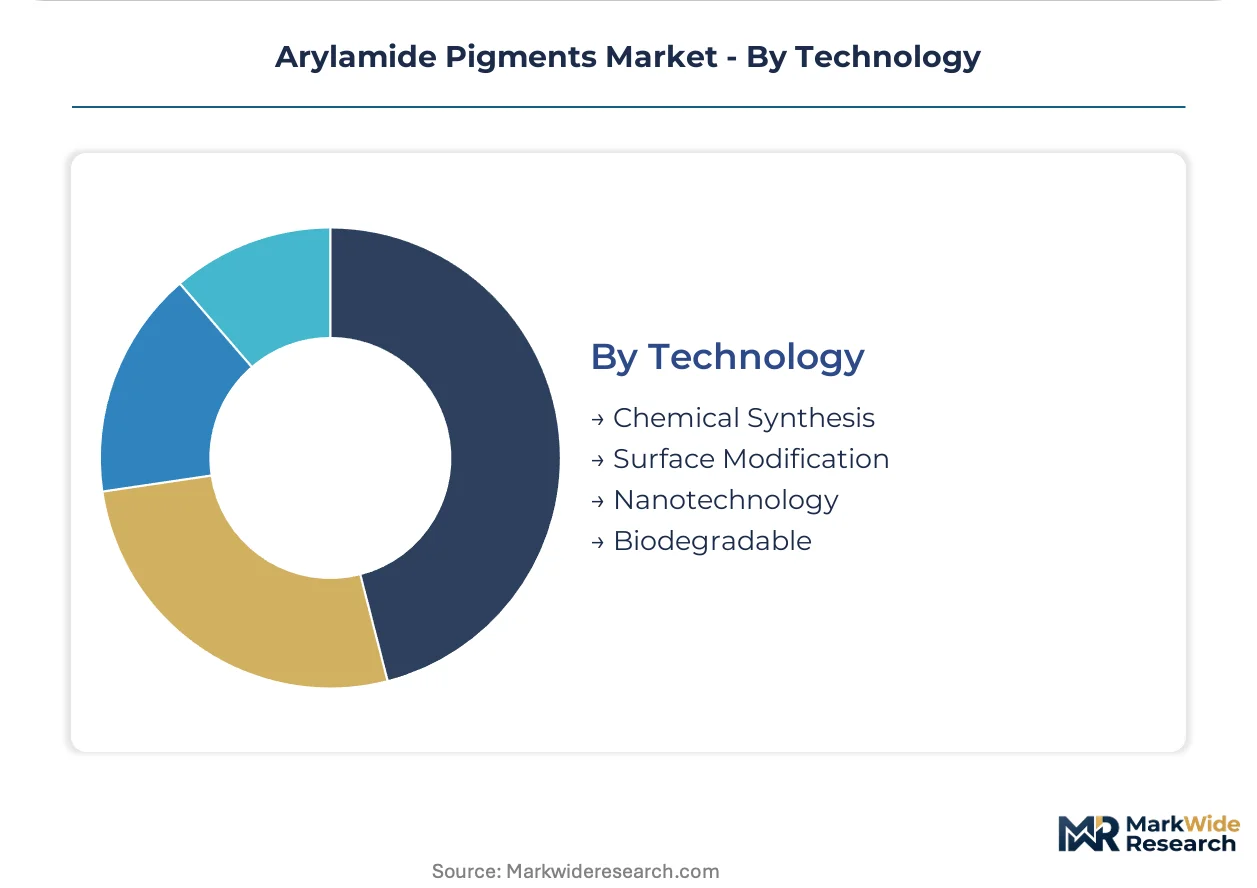
Technology:
Process innovation separates commodity synthesis from value-added surface engineering capabilities.
- Surface Modification:Silane and polymer encapsulation treatments enable waterborne dispersion without volatile organic compounds. Coating formulators in Italy and Spain pay premiums for grades that reduce mill-base preparation time.
- Chemical Synthesis:Conventional diazotization and coupling reactions produce standard grades at scale. Acetoacetanilide feedstock costs from Gulf Coast and Northeast Asian refineries determine margin pressure.
- Nanotechnology:Sub-100nm particle engineering for transparent coatings and high-resolution printing.
- Biodegradable:Emerging bio-based coupling components from agricultural waste streams align with EU Green Deal procurement criteria.
Chemical synthesis handles the majority of throughput; surface modification is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European formulators prioritize REACH-compliant surface-modified grades for waterborne automotive systems, while Chinese producers emphasize cost-optimized monomeric pigments for export-oriented coating plants. Regulatory stringency and end-use sophistication create distinct procurement specifications across major manufacturing clusters.
China
Domestic pigment production serves both local coating plants and export channels to Southeast Asian construction markets. GB standards for toy safety and food packaging migration limits redirect procurement specifications across export-oriented manufacturing clusters in the Yangtze River Delta. Zhejiang and Jiangsu provinces concentrate surface modification capacity for waterborne coating compatibility.
Germany
Automotive refinishing networks in Bavaria and North Rhine-Westphalia drive demand for spectrophotometer-compatible pigment grades with documented REACH compliance. ECHA registration deadlines accelerate migration from legacy diarylide chemistries toward arylamide structures with superior toxicological profiles. The KBA maintains strict oversight of coating formulations for vehicle repair certification.
United States
Collision repair networks require color-matching precision at cost points below high-performance alternatives, concentrating procurement among Tier 1 coating houses. EPA TSCA oversight and evolving Section 6 restrictions on per- and polyfluoroalkyl substances compel reformulation of stain-resistant architectural coatings. Gulf Coast petrochemical feedstock clusters expose acetoacetanilide coupling component costs to price volatility.
India
BIS certification requirements and domestic coating capacity expansion create procurement openings for pigment suppliers with localized technical service capabilities. Maharashtra and Gujarat host expanding automotive OEM and refinish coating plants sourcing migration-resistant polymeric grades. The PLI scheme for chemicals and petrochemicals incentivizes backward integration into coupling component synthesis.
France
Food-contact plastics manufacturers in the Île-de-France and Auvergne-Rhône-Alpes regions specify polymeric arylamide variants for compliance with EFSA migration thresholds. EFSA and ANSM coordinate on safety assessments for colorants in consumer goods applications. Lyon-based coating formulators pay premiums for surface-treated grades that reduce mill-base preparation time in waterborne systems.
Arylamide Pigments Market Competitive Environment
Capability concentration sits with integrated pigment-dispersion platforms; scale advantage sits with manufacturing assets spanning European and Asian production clusters. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with regulatory compliance infrastructure, specialized surface-modification specialists commanding premium positioning, and regional synthesis plants serving cost-sensitive export markets. Dominant competitive moves include portfolio consolidation toward waterborne-compatible grades and geographic expansion into Indian manufacturing with localized technical service capabilities.
Among European-based chemical conglomerates, BASF SE and Clariant AG exemplify the integrated-platform archetype, anchoring positions through documented REACH compliance and surface modification certificates. Heubach GmbH represents the scale-driven manufacturing archetype with production assets across multiple geographies. These three entities collectively illustrate how regulatory compliance infrastructure and technical service capabilities now outweigh price in vendor selection criteria for European automotive refinish supply chains.
| Leading Market Players |
|---|
| DIC Corporation |
| Chroma Australia |
| BASF SE |
| Hangzhou Aibai Chemical Co., Ltd |
| Brenntag UK Limited |
| Clariant AG |
| Heubach GmbH |
| Hollindia Internatianak Bv |
| Sun Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
Acetoacetanilide coupling component production clusters on the US Gulf Coast and in Northeast Asian refining corridors concentrate upstream margin capture, while surface modification specialists in Germany and Zhejiang province extract downstream premiums from waterborne coating formulators seeking dispersion stability.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational coating houses and integrated pigment suppliers, though spot purchasing persists among regional distributors serving small-batch refinishing operations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified surface-modified grades from commodity monomeric pigments and unmodified synthesis outputs. Cost compression in standard grades is intensifying because Chinese export-oriented plants are expanding acetoacetanilide coupling capacity. Tier 1 automotive refinish networks exhibit lowest price sensitivity due to liability exposure, while construction coating distributors remain most responsive to unit cost fluctuations.
Supply Chain Analysis
Export-control regimes on advanced particle characterization equipment limit technology transfer to emerging surface modification facilities, constraining quality parity in regional supply bases. Manufacturing gravity centers on China, Germany, and India, with feedstock dependencies on Gulf Coast petrochemical naphtha, Northeast Asian aniline derivatives, and European silane coupling agents. Single-source vulnerability concentrates in specialized milling equipment for sub-micron particle distributions demanded by spectrophotometer color-matching systems. Distribution runs through authorized technical distributors in European automotive refinish corridors and direct mill relationships in Chinese export manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated multinational coating houses, with BASF Coatings, PPG Industries, and AkzoNobel compressing supplier qualification timelines and mandating documented regulatory compliance that favors incumbents with established certification infrastructure.
For Market Incumbents: Insulate margin position by deepening backward integration into acetoacetanilide coupling component synthesis in Gulf Coast or Northeast Asian feedstock corridors, and accelerate surface modification capacity expansion in India to capture BIS certification-driven procurement shifts. High-performance diketopyrrolopyrrole substitution in thermal-stability-critical segments threatens premium positioning, requiring defensive patent portfolio development around polymeric molecular architectures. For New Entrants and Emerging Players: India's Maharashtra and Gujarat coating manufacturing clusters offer geographic underpenetration for technical service-capable entrants, particularly in polymeric pigment grades serving automotive OEM qualification programs. White-space exists in bio-based coupling component synthesis aligned with EU Green Deal procurement criteria for public infrastructure coatings. A joint-venture route with established Indian distributors bypasses capital-intensive milling asset requirements while building BIS compliance credibility. For Investors and Strategic Acquirers: Capital is best deployed toward surface-modification specialists with documented REACH compliance and existing automotive refinish approvals, as specification consolidation among multinational coating houses renders uncertified synthesis capacity stranded. The 5-10 year viability window favors assets with waterborne dispersion expertise over legacy solvent-compatible operations. The signal to watch is EPA TSCA Section 6 enforcement intensity on fluorinated coating additives, which would accelerate arylamide pigment qualification timelines as partial functionality replacements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coupling Components | Gulf Coast and Northeast Asian feedstock access secures margin control against petrochemical volatility. |
| Surface Modification Capacity Expansion | Waterborne automotive refinish qualification with PPG Industries and BASF Coatings commands premium positioning. |
| India Technical Service Localization | BIS certification requirements and PLI scheme incentives create first-mover procurement advantages in Maharashtra. |
| Bio-Based Coupling Component Development | EU Green Deal public infrastructure procurement criteria open differentiated revenue streams in European architectural coatings. |
| Polymeric Pigment R&D Investment | EFSA migration threshold compliance unlocks food-contact plastics applications in German and French manufacturing. |
Study Parameters
The analysis maps monomeric, polymeric, and surface-modified pigment sub-sectors, each validated through technical R&D directors at coating formulators, procurement leads at automotive refinish networks, plant managers at Chinese synthesis facilities, and distribution channel partners serving regional coating plants. Primary interview intelligence triangulates against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA registration databases. Bottom-up volume modeling from individual production assets reconciles with top-down demand aggregation across end-use applications.
The assumption-set holds REACH compliance deadlines and EPA TSCA oversight trajectories as fixed regulatory boundary conditions, while varying raw material cost scenarios and coating system chemistry transitions across the projection horizon. Segmentation dimensions include molecular architecture grade, application chemistry, end-use industry sophistication, and regional regulatory cluster. CAGRs derive from production capacity utilization trends and substitution elasticity estimates between arylamide and high-performance pigment chemistries. Forecast inputs incorporate automotive collision repair volume patterns and food-contact plastics specification tightening trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese synthesis consortia or accelerated diketopyrrolopyrrole cost reduction would shift volume and margin outcomes substantially. Cross-checking against ECHA registration progression timelines and automotive OEM qualification pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Pharmaceutical Dyes Market