
 Global Oxygen-Free Copper Market | 2026-2036
Global Oxygen-Free Copper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxygen-Free Copper Market Foresight
China is fragmenting the global oxygen-free copper supply base as new smelting capacity comes online in Hunan and Jiangxi provinces. Mitsubishi Materials Corporation leverages its integrated refining-to-rod operations across Japanese industrial corridors. KGHM Polska Miedz SA anchors European supply through its Głogów smelter complex in southwestern Poland. Southwire Company, LLC competes via specialized magnet wire production for North American automotive electrification programs.
Oxygen-free copper refers to electrolytic copper refined to contain less than 5 parts per million of oxygen, typically cast under protective atmospheres to preserve electrical conductivity above 100% IACS for critical signal transmission. Rod and wire categories dominate volume throughput, with C10100 grade commanding premium positioning in semiconductor probe assemblies where trace impurity tolerances approach single-digit ppm thresholds. Aerospace applications sustain the fastest expansion trajectory as satellite constellation builders specify oxygen-free copper for radio frequency components operating across extreme thermal cycles.
FCC emission standards for telecommunications infrastructure and China's GB standards for electrical conductors jointly elevate material purity requirements, while REACH compliance in Europe restricts certain refining additives and reshapes supplier qualification protocols. Japan's METI maintains JIS H 3510 specifications that govern oxygen-free copper acceptance in precision electronics. Stakeholders must weigh the capital intensity of vacuum casting upgrades against the margin compression risk from Asian capacity additions.
Market Dynamics
Semiconductor fabrication facilities in South Korea and Taiwan are pulling oxygen-free copper supply chains toward sub-5 ppm purity thresholds, compressing qualification timelines for incumbent smelters while opening entry points for vacuum-casting specialists.
Growth Catalysts
- China's dual carbon goals:Tightening purity standards for electrical conductors under GB standards are forcing grid infrastructure upgrades toward higher-conductivity materials.
- Satellite constellation deployment:Radio frequency component manufacturers specify oxygen-free copper for thermal cycle resilience across extreme orbital environments.
- Automotive electrification:Magnet wire specifications for traction motors in North American and European EV programs specify C10100 grade for efficiency optimization.
Market Restraints
- Energy cost volatility:Electrolytic refining and vacuum casting operations face margin pressure from electricity input cost swings in European smelting corridors.
- Supply concentration in East Asia:New smelting capacity in Hunan and Jiangxi provinces is fragmenting pricing power and compressing regional margins.
- Silver-copper composite substitution:High-frequency signal transmission applications in certain aerospace subsystems are testing alternative conductor architectures.
Strategic Opportunities
- India's PLI scheme for electronics:Semiconductor packaging incentives under the country's production-linked incentive framework are attracting purity-grade copper investments.
- Subsea cable electrification:Transoceanic data transmission infrastructure projects are specifying oxygen-free copper for repeater housing and power feed applications.
- EU Green Deal alignment:REACH compliance restrictions on certain refining additives are creating qualification advantages for additive-free vacuum casting specialists.
Industry Challenges
- Metallurgical talent scarcity:Vacuum casting process engineering expertise concentrates in aging workforces across Japanese and German industrial corridors.
- Certification timeline compression:Semiconductor probe assembly qualification protocols now demand 18-month purity stability documentation, stretching smaller refiners.
- Legacy furnace reconfiguration:Converting traditional fire-refining assets to protective-atmosphere casting requires capital outlays that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxygen-Free Copper Market |
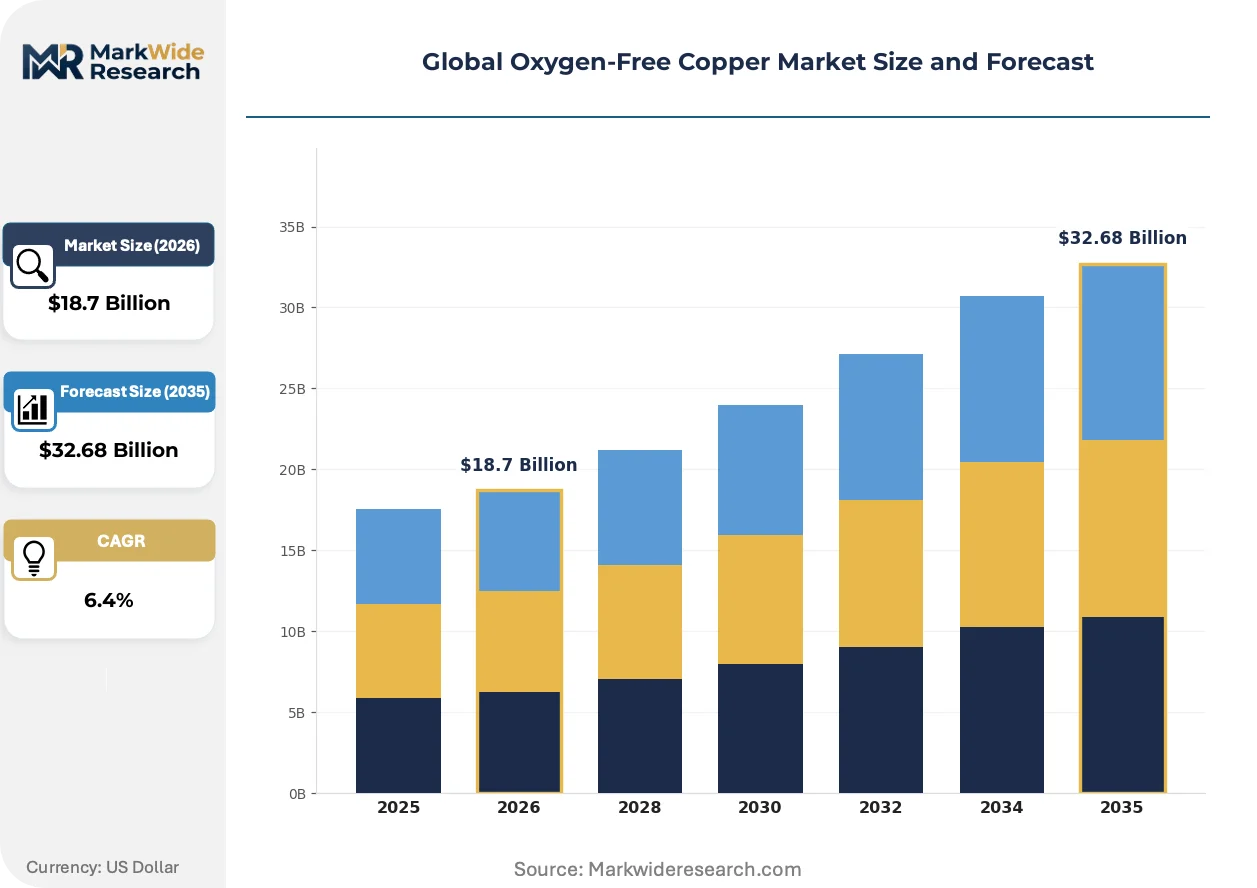
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod, Wire, Tube, Sheet Grade: 1050-O, 1100-H14, C10100, C10200 Application: Electrical Conductors, Audio Equipment, Telecommunications, Aerospace End User: Electronics, Automotive, Power Generation, Industrial |
| Companies Covered | Mitsubishi Materials Corporation, Proterial Metals, Ltd., KGHM Polska Miedz SA, Metrod Holdings Berhad, Aviva Metals, Copper Braid Products, KME Germany GmbH, Sam Dong, Southwire Company, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxygen-Free Copper Market Shifts & Advancements
Protective-atmosphere casting technologies and purity verification protocols are advancing in parallel, with smelters competing on trace impurity detection capabilities rather than commodity scale alone.
Vacuum induction melting is hybridizing with continuous casting architectures to produce C10100 rod with single-digit ppm oxygen consistency. Aerospace cable harness manufacturers in France and Germany are adopting these hybrid-process inputs for satellite payload wiring. The structural consequence is compressing the premium commanded by traditional electrolytic-then-vacuum sequential processing.
REACH compliance in Europe is restricting certain sulfur-bearing refining additives previously common in fire-refined copper production. ECHA substance evaluation protocols are forcing smelters to reformulate flux chemistries or shift entirely to electrolytic-vacuum process routes. Polish and German electrical conductor manufacturers are accelerating supplier audits to lock in additive-free material streams ahead of 2025 evaluation deadlines.
Specification-driven procurement now dominates semiconductor fabrication equipment purchasing, with buyers unbundling material certification from rod supply contracts. South Korean and Taiwanese probe card manufacturers are engaging directly with Japanese vacuum casters for lot-traceable purity documentation, bypassing traditional distributor channels. This disintermediation is most visible in the Pyeongtaek and Hsinchu manufacturing clusters where foundry capital expenditure cycles concentrate demand timing.
Global Oxygen-Free Copper Market Segmentation
Oxygen-free copper markets fragment along purity thresholds and dimensional form factors that dictate processing economics. Grade certification and end-use qualification protocols create distinct commercial tiers with divergent margin structures.
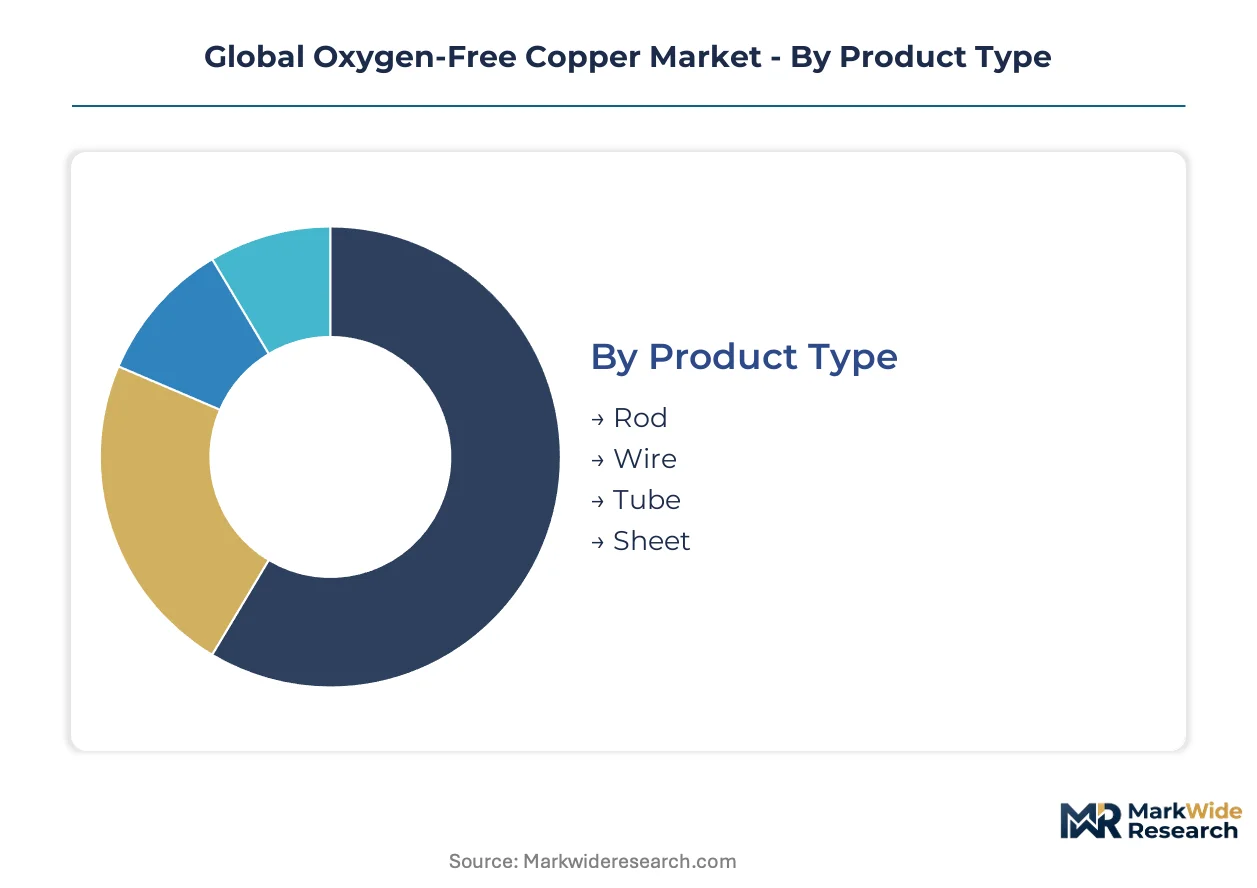
Product Type:
Dimensional form determines casting method, downstream processing steps, and ultimate conductivity preservation.
- Rod:Continuous-cast round stock serves as the feedstock for wire drawing operations. Semiconductor probe card manufacturers in Hsinchu and Pyeongtaek specify vacuum-cast rod with sub-5 ppm oxygen for interconnect etching.
- Wire:Fine-gauge magnet wire dominates automotive traction motor specifications. North American EV programs under NHTSA efficiency mandates require C10100 grade for winding applications to minimize resistive losses.
- Tube:Seamless hollow sections serve cryogenic and heat exchanger applications. BIS certification requirements in India are tightening dimensional tolerances for power generation heat sinks.
- Sheet:Rolled plate forms busbar substrates and RF shielding enclosures. ECHA REACH compliance is restricting sulfur-bearing lubricants used in traditional rolling mill sequences.
Rod commands the established base. The steepest expansion runs through wire.
Grade:
Purity thresholds segment the market into qualification tiers with distinct pricing premiums and customer switching costs.
- C10100:Electrolytic tough pitch copper refined to under 5 ppm oxygen through vacuum induction melting. Aerospace cable harness manufacturers in Germany specify this grade for satellite payload wiring subject to METI JIS H 3510 acceptance protocols.
- C10200:Phosphorus-deoxidized variant with slightly elevated oxygen tolerance. Power generation contractors in Poland deploy this grade for grid infrastructure where GB standard alignment is not mandated.
- 1050-O:Annealed aluminum alloy with oxygen-free copper cladding for weight-critical applications. FAA certification pathways for commercial avionics are driving qualification testing.
- 1100-H14:Strain-hardened pure aluminum substrate with copper metallization. Audio equipment manufacturers in Japan favor this composite for signal path components.
C10200 anchors volume throughput. C10100 captures the premium trajectory.
Application:
Functional use cases impose distinct thermal, mechanical, and signal integrity requirements on material selection.
- Electrical Conductors:Busbar and winding applications prioritize conductivity above 100% IACS. China's dual carbon goals under MEE oversight are forcing grid upgrades toward higher-purity conductors.
- Aerospace:Radio frequency components and cable harnesses for satellite constellations. Extreme thermal cycling across orbital environments demands vacuum-cast material with trace impurity documentation.
- Telecommunications:FCC emission standards for infrastructure equipment are elevating shielding effectiveness requirements. Repeater housings for subsea cable projects specify oxygen-free copper for corrosion resistance.
- Audio Equipment:Signal path components where conductivity stability affects harmonic distortion. Japanese high-end manufacturers source directly from vacuum casters for lot-traceable certification.
Electrical conductors dominate tonnage. Aerospace applications are climbing the fastest.
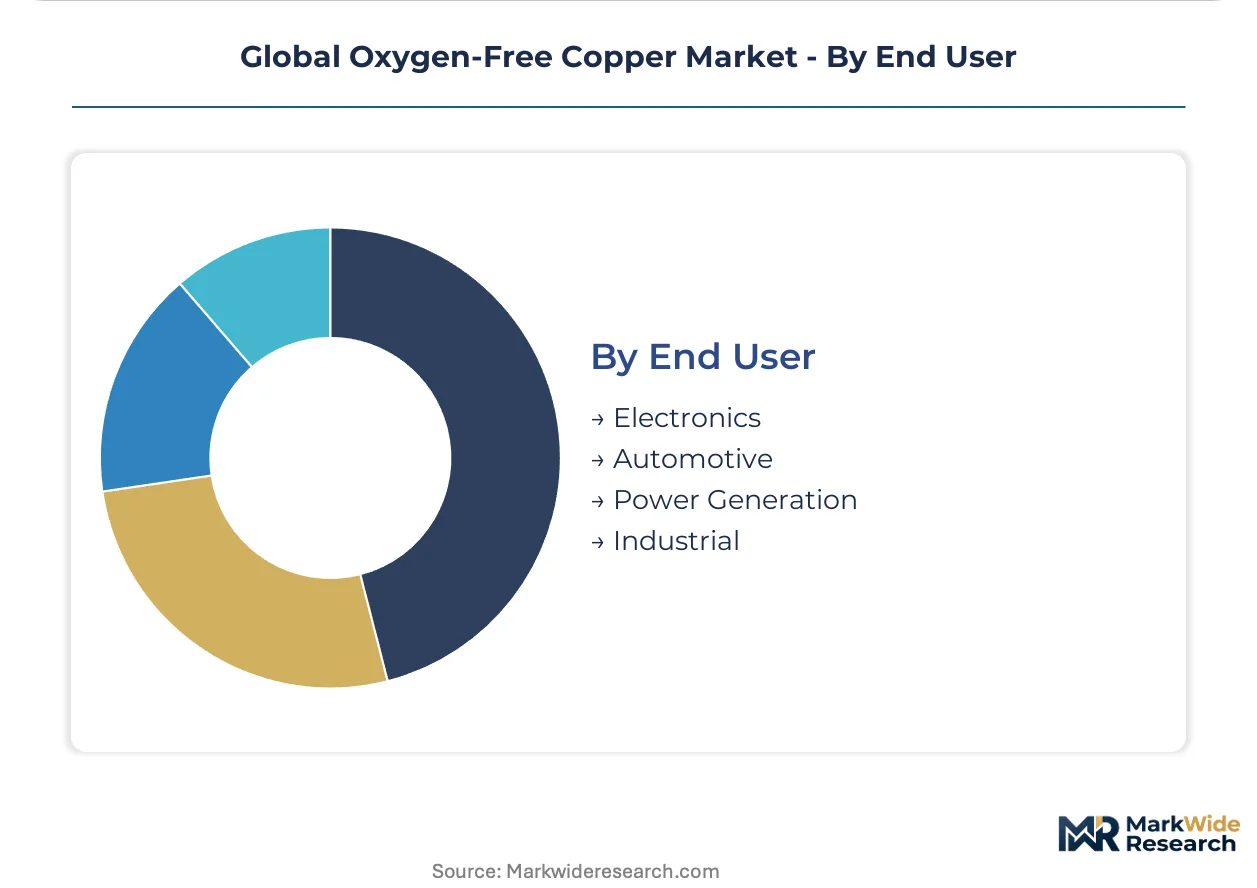
End User:
Customer industry verticals concentrate demand timing and dictate qualification protocol intensity.
- Electronics:Semiconductor packaging and probe assembly operations. South Korean foundry capital expenditure cycles pull supply chains toward 18-month purity stability documentation requirements.
- Automotive:Traction motor magnet wire and battery busbar applications. European EV programs under EU Green Deal alignment are specifying additive-free material streams.
- Power Generation:Transformer windings and generator buswork. India's PLI scheme for electronics is attracting purity-grade copper investments into Gujarat and Tamil Nadu.
- Industrial:Process equipment and instrumentation cabling. REACH compliance deadlines are compressing supplier audit timelines for Polish and German manufacturers.
Electronics commands qualification premiums. Automotive is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE oversight of China's dual carbon goals is reshaping purity standards across East Asian electrical conductor supply chains. GB standard tightening forces grid infrastructure upgrades toward higher-conductivity materials while semiconductor fabrication clusters pull vacuum-casting capacity toward sub-5 ppm thresholds.
China
New smelting capacity in Hunan and Jiangxi provinces fragments pricing power as electrolytic refining expands. GB standards under MEE oversight mandate higher-conductivity conductors for grid infrastructure upgrades. Yangtze River Delta electronics manufacturers specify vacuum-cast rod for semiconductor probe assembly feedstock.
South Korea
Foundry capital expenditure cycles concentrate demand timing for C10100 grade interconnects. MFDS-aligned import protocols govern material acceptance in precision electronics. Pyeongtaek semiconductor clusters specify 18-month purity stability documentation from vacuum casters.
Japan
METI maintains JIS H 3510 specifications governing oxygen-free copper acceptance in precision electronics. Integrated refining-to-rod operations span industrial corridors from Nagoya to Kanto. Audio equipment manufacturers in Tokyo source directly from vacuum casters for lot-traceable certification.
Germany
ECHA REACH compliance restricts sulfur-bearing refining additives, forcing flux chemistry reformulation. Aerospace cable harness manufacturers in Bavaria adopt hybrid-process rod for satellite payload wiring. Frankfurt-area electrical conductor manufacturers accelerate supplier audits ahead of evaluation deadlines.
United States
NHTSA efficiency mandates for EV traction motors specify C10100 grade magnet wire to minimize resistive losses. FCC emission standards elevate shielding effectiveness requirements for telecommunications infrastructure. Southeast automotive electrification programs pull specialized wire capacity from Georgia and Tennessee manufacturing corridors.
Global Oxygen-Free Copper Market Competitive Landscape
Capability concentration sits with vacuum-casting specialists; scale advantage sits with integrated electrolytic refiners. The vendor base stratifies across three tiers: additive-free vacuum casters commanding semiconductor qualification premiums, fire-refined incumbents defending industrial conductor volume, and hybrid-process mid-caps exploiting continuous casting economies. Dominant competitive moves include protective-atmosphere furnace upgrades and direct engagement with probe card manufacturers.
Among Japanese integrated materials groups, Mitsubishi Materials Corporation occupies a position exemplifying captive refining-to-rod control. Polish state-backed miners like KGHM Polska Miedz SA anchor European supply through smelter complex operations. North American wire specialists represented by Southwire Company, LLC sit within the automotive electrification tier, with magnet wire specifications for traction motor programs.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| Proterial Metals, Ltd. |
| KGHM Polska Miedz SA |
| Metrod Holdings Berhad |
| Aviva Metals |
| Copper Braid Products |
| KME Germany GmbH |
| Sam Dong |
| Southwire Company, LLC |
| Others |
Supply & Pricing Matrix
Jiangxi province's electrolytic refining expansion fragments regional pricing power as new smelting capacity compresses margins for vacuum-casting specialists serving semiconductor probe assembly markets. C10100 grade premiums in East Asian electronics clusters now hinge on lot-traceable purity documentation rather than commodity scale alone.
Pricing Analysis
East Asian price spreads between Japanese vacuum-cast rod and Chinese electrolytic output are widening as GB standard tightening elevates certification premiums. Three-tier pricing structure across C10100 premium, C10200 standard, and fire-refined economy grades differentiates by trace impurity thresholds and METI JIS H 3510 compliance. Pricing pressure stems from Hunan capacity additions flooding industrial conductor segments. Power generation contractors in Poland exhibit highest price sensitivity; South Korean foundry procurement teams prioritize qualification stability over unit cost.
Supply Chain Analysis
Semiconductor packaging foundries in Hsinchu and Pyeongtaek concentrate demand timing for sub-5 ppm oxygen rod, pulling vacuum-casting capacity toward probe card feedstock specifications. Raw material flows draw from Chilean cathode, Zambian concentrate, and Japanese scrap recovery streams. Single-source vulnerability concentrates in aging vacuum induction melting expertise across Nagoya and Kanto industrial corridors. Distribution runs through direct mill-to-fab contracts disintermediating traditional metal distributors in East Asian electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum casting process engineering expertise concentrates in aging workforces across Japanese and German industrial corridors, creating acquisition targets for specialist capability. The 18-month purity stability documentation protocols now demanded by South Korean foundries favor incumbents with established qualification archives.
For Market Incumbents: Insulate semiconductor qualification premiums by accelerating protective-atmosphere furnace upgrades ahead of REACH evaluation deadlines. Lock in multi-year direct contracts with Pyeongtaek and Hsinchu probe card manufacturers to defend against Chinese electrolytic refiners pursuing vacuum-casting retrofits. Prioritize metallurgical talent retention in Nagoya and Bavaria corridors where process engineering expertise is thinning. For New Entrants and Emerging Players: Build out additive-free vacuum casting capacity in Gujarat and Tamil Nadu to capture India's PLI scheme for semiconductor packaging incentives. Target automotive magnet wire specifications for European EV programs where EU Green Deal alignment restricts sulfur-bearing refining additives. Establish direct engagement protocols with Japanese audio equipment manufacturers seeking lot-traceable C10100 certification. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because vacuum-casting capability scarcity intensifies as semiconductor purity thresholds tighten. Target mid-tier Japanese and German refiners with established JIS H 3510 qualification archives and aging ownership structures. Watch for inflection when South Korean foundries accelerate 18-month stability documentation requirements beyond current supplier capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Protective-Atmosphere Furnace Upgrade | Preserves C10100 premium positioning against REACH-compliant additive restrictions in European markets. |
| Direct Mill-to-Fab Contracting | Disintermediates distributors in Hsinchu and Pyeongtaek clusters where probe card manufacturers seek lot traceability. |
| Metallurgical Talent Acquisition | Secures vacuum induction melting expertise concentrated in aging Japanese and German engineering workforces. |
| Additive-Free Process Transition | Aligns with ECHA substance evaluation protocols forcing flux chemistry reformulation ahead of deadlines. |
| Hybrid Continuous Casting Deployment | Compresses sequential electrolytic-then-vacuum processing costs for aerospace cable harness specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed copper producers, JIS certification registries, and ECHA substance evaluation protocols. Plant managers at electrolytic refineries, procurement leads at South Korean foundries, vacuum casting process engineers, and distribution channel partners in East Asian electronics clusters provided operational perspective. Bottom-up capacity modeling triangulates against top-down demand aggregation from semiconductor capital expenditure tracking and automotive electrification program announcements.
Forecast inputs span grade tier, dimensional form factor, end-use industry vertical, and regional regulatory cluster across the analysis window. CAGRs derive from segment-level volume buildups validated against smelter capacity expansion announcements and foundry equipment procurement cycles. Hybrid process adoption rates, REACH compliance timeline acceleration, and satellite constellation deployment schedules inform trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by Chinese electrolytic refiners into vacuum casting would shift outcomes beyond modeled ranges. Quarterly review of South Korean foundry qualification protocol changes, ECHA additive restriction enforcement, and Hunan-Jiangxi capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Aluminium Powder Market
Metals
Aluminum Casting Market
Metals
Scandium Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Silver Enamel Market
Metals
Steel Wire Market
Metals
Stainless Steel Sheet Market
Metals
Aluminium Forging Market
Metals
High Purity Aluminium Market
Metals
Lithium Foil Market
Metals
Stainless Steel Foil Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Lightweight Aluminium Pistons Market
Metals
High Purity Lead Market
Metals
Crude Steel Market