
 Liquid Metal Thermal Pad Market | 2026-2036
Liquid Metal Thermal Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Metal Thermal Pad Market Insights
Asset-light leasing models for high-performance thermal testing equipment is narrowing the capital barrier for mid-tier compounders entering the liquid metal thermal pad supply chain. Indium Corporation leverages captive indium refining to control raw material purity across its thermal interface portfolio. Thermal Grizzly differentiates through enthusiast-grade branding and direct-to-consumer channel control in European PC markets. Henkel AG & Co. KGaA sustains automotive qualification pathways that anchor its position in EV battery thermal management systems.
Liquid metal thermal pads are gallium-indium-tin eutectic alloys, often alloyed with trace metals, formulated into compliant sheets or dispensable layers with thermal conductivity exceeding 40 W/mK; they function as phase-stable thermal interfaces between heat-generating dies and metallic heat spreaders where silicone greases thermally degrade. Soft pads dominate consumer electronics retrofit channels due to conformability over non-planar CPU integrated heat spreaders, while custom shapes capture margin pools in aerospace avionics where MIL-STD-810G shock compliance dictates pad geometry. Automated dispensing leads industrial equipment installations where throughput consistency outweighs per-unit material cost.
FDA scrutiny of gallium biocompatibility in wearable medical devices shapes formulation choices for manufacturers exploring adjacent health-tech applications, while REACH restrictions on substance of very high concern classifications constrain indium compound handling protocols across EU-based production lines. China's GB standards for electronic product safety and SAMR market access certification create dual compliance requirements for foreign suppliers targeting domestic OEMs. Stakeholders must monitor evolving halogen-free mandates and carbon border adjustment mechanisms as these frameworks increasingly determine which thermal interface formulations qualify for public procurement and premium consumer segments.
Market Dynamics
Data center operators now mandate liquid metal thermal interfaces for GPU-intensive server racks, creating procurement pull that cascades through semiconductor packaging supply chains and forces compounders to qualify gallium-indium-tin formulations at production scale.
Growth Catalysts
- China's dual carbon goals:Appliance efficiency mandates under SAMR certification accelerate thermal material upgrades in domestic electronics manufacturing.
- EU F-Gas Regulation phase-down:Synthetic refrigerant restrictions intensify passive cooling reliance, expanding thermal pad deployment in commercial HVAC heat exchangers.
- Semiconductor packaging corridors:East Asian foundry concentration in South Korea and Taiwan drives volume procurement of phase-stable interface materials.
Market Restraints
- Gallium price volatility:Byproduct dependency on bauxite/alumina refining creates input cost instability for eutectic alloy formulations.
- Indium supply concentration:Primary refining capacity clusters in Chinese state-controlled smelters, exposing non-domestic compounders to export quota risk.
- REACH SVHC classification:ECHA substance of very high concern protocols constrain indium compound handling across EU-based production lines.
Strategic Opportunities
- EV battery thermal management:Automotive qualification pathways for pouch cell cooling plates open adjacent volume pools beyond computing applications.
- Asset-light testing equipment leasing:Reduced capital barriers enable mid-tier compounders to enter liquid metal thermal pad supply chains without fabrication infrastructure.
- Wearable medical devices:FDA biocompatibility scrutiny of gallium formulations creates first-mover advantage for compliant health-tech suppliers.
Industry Challenges
- MIL-STD-810G shock compliance:Aerospace avionics certification timelines extend 18-24 months for custom pad geometries.
- Automated dispensing integration:Industrial equipment manufacturers face throughput consistency demands that outpace legacy silicone grease application lines.
- Halogen-free mandate alignment:Carbon border adjustment mechanisms in premium consumer segments require dual compliance with GB standards and EU Green Deal frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Metal Thermal Pad Market |
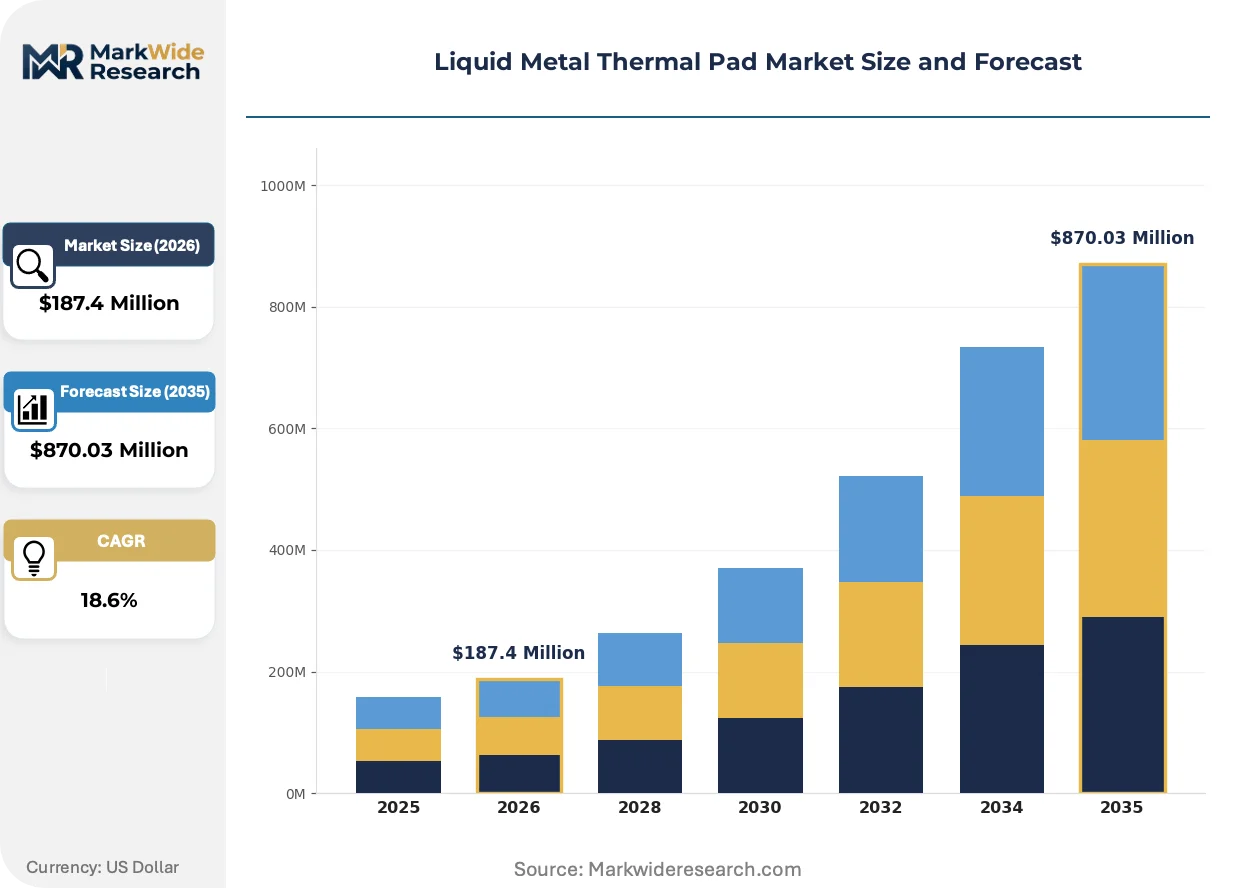
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Pads, Hard Pads, Custom Shapes, Thermal Interface Materials Application: Consumer Electronics, Automotive Cooling, Industrial Equipment, Aerospace End User: OEMs, Aftermarket Providers, Retailers, Industries Installation Method: Manual Application, Automated Dispensing, Surface Mounting, Pre-Applied |
| Companies Covered | Indium Corporation, Thermal Grizzly, Henkel AG & Co. KGaA, Laird Performance Materials, Fujipoly, Shin-Etsu MicroSi, Sino Santech Materials Technology Co., Ltd, Coollaboratory, Innovation Cooling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Metal Thermal Pad Market Trends and Innovations
Formulation chemistry and application methods are converging to address thermal conductivity ceilings that silicone-based materials hit at 15 W/mK, with deployment patterns fragmenting across consumer retrofit, industrial automation, and aerospace qualification tracks.
Alloy engineering is migrating from binary gallium-indium systems toward quaternary formulations with trace silver or zinc additions that suppress supercooling while maintaining electrical isolation. High-performance computing OEMs in Taiwan and South Korea are adopting these variants for chiplet-based GPU architectures. The technology shift is compressing qualification cycles from 36 months to 18 months for thermal interface suppliers.
REACH authorization requirements for indium compounds are tightening substance volume thresholds across EU-based electronics assembly operations. ECHA's 2024 updated guidance on metal alloy classification forces reformulation reviews for thermal pads containing more than 0.1% indium by mass. German automotive suppliers are accelerating alternative qualification programs to maintain CE marking continuity.
Direct procurement from compounders is displacing distributor-mediated purchasing for volumes exceeding 10,000 units annually in data center construction. Colocation operators in Virginia and Frankfurt are negotiating frame contracts that bundle thermal pad supply with installation services. This pattern concentrates supplier relationships with three to five qualified vendors per hyperscale buildout.
Liquid Metal Thermal Pad Market Segmentation
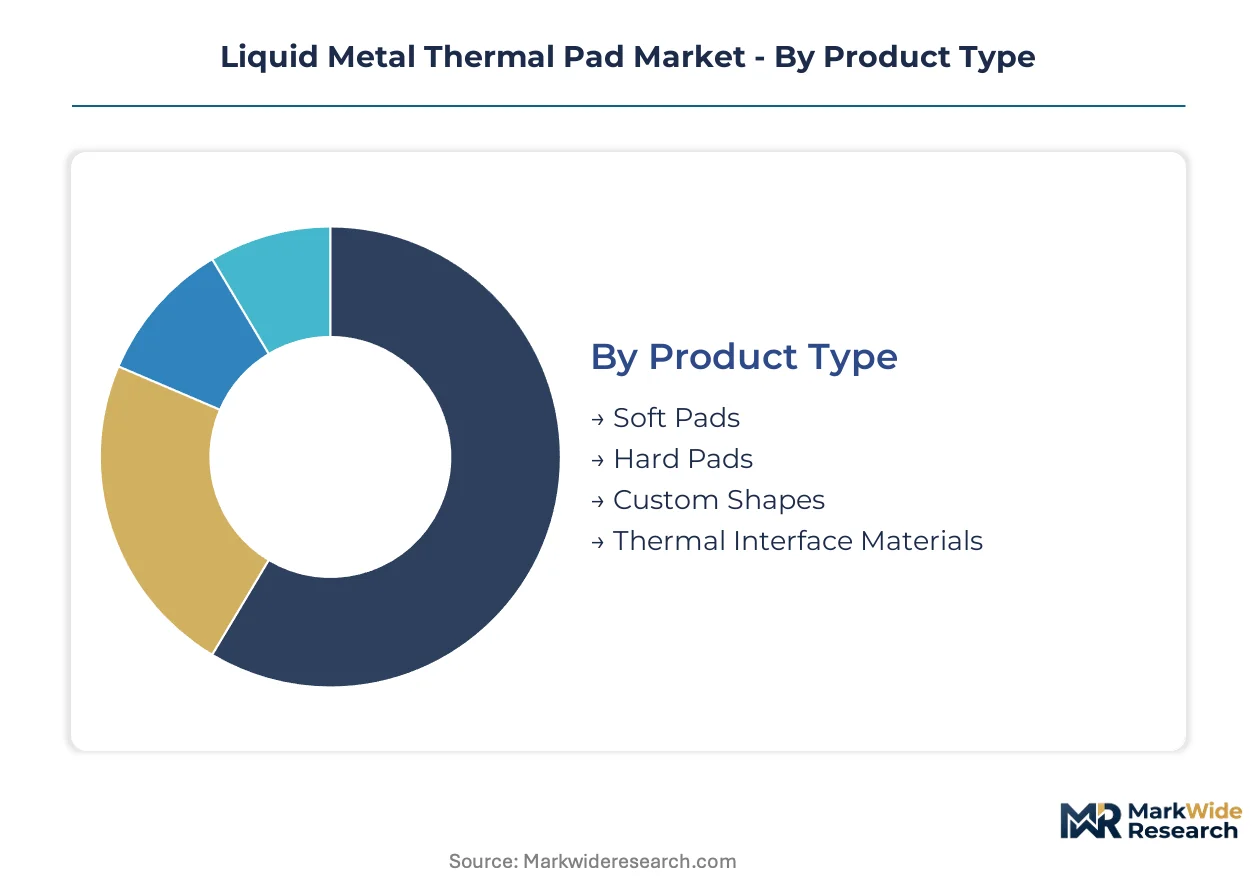
Liquid metal thermal pad segmentation reveals divergent performance requirements across computing, mobility, and industrial thermal loads. Product form factors and installation protocols must align with die geometry, shock tolerance, and line-speed constraints that vary sharply by end-use environment.
Product Type:
Use-case spectrum spans retrofit consumer builds to precision aerospace assemblies, demanding compliant sheets, rigid plates, and engineered geometries with distinct mechanical and thermal specifications.
- Soft Pads:Gallium-indium-tin eutectic alloys in pliable sheet form conform to non-planar CPU integrated heat spreader surfaces without pump-out. Demand concentrates in European and North American PC enthusiast retail channels where Thermal Grizzly and comparable brands control direct-to-consumer distribution.
- Hard Pads:Solidified alloy compositions with higher structural integrity maintain dimensional stability under compression cycling. Data center operators in Virginia and Frankfurt specify these variants for GPU-intensive server racks where long-term interface reliability outweighs initial conformability.
- Custom Shapes:CNC-machined or molded geometries for avionics modules requiring MIL-STD-810G shock compliance.
- Thermal Interface Materials:Dispensable liquid metal compounds for industrial equipment integration lines.
Established volume favors soft pads; emerging adoption favors hard pads.
Application:
Cost tier stratification separates high-volume consumer electronics from qualification-heavy aerospace programs with extended certification timelines.
- Consumer Electronics:Desktop CPU and GPU retrofits drive recurring replacement cycles as enthusiasts upgrade cooling systems. East Asian manufacturing corridors in South Korea and Taiwan anchor procurement volumes for aftermarket thermal pad suppliers serving gaming hardware OEMs.
- Automotive Cooling:Pouch cell and prismatic battery module interfaces in electric vehicles demand phase-stable materials across -40°C to 150°C thermal cycles. Henkel AG sustains automotive qualification pathways that anchor supplier relationships with German and Chinese EV battery pack assemblers.
- Industrial Equipment:Power electronics and motor drive thermal management in factory automation systems.
- Aerospace:Satellite payload and avionics cooling with radiation-hardened interface requirements.
Automotive cooling climbs the fastest as battery thermal management supplants traditional engine cooling in supplier R&D allocation.
End User:
Customer type determines procurement scale, technical support intensity, and margin structure across direct OEM supply, distributor-mediated retail, and industrial procurement channels.
- OEMs:Original equipment manufacturers specify thermal pads at design-in phase for laptops, servers, and automotive battery systems. Taiwan-based high-performance computing OEMs compress qualification cycles from 36 months to 18 months for chiplet-based GPU architectures.
- Aftermarket Providers:Independent service organizations and system integrators source pads for repair and upgrade services. European PC markets sustain enthusiast-grade branding premiums through direct channel control.
- Retailers:E-commerce and specialty electronics stores serving DIY thermal management customers.
- Industries:Direct procurement from compounders for volumes exceeding 10,000 units annually in data center construction.
Direct industrial procurement gains share fastest; retail distribution retains margin premiums in fragmented geographic markets.
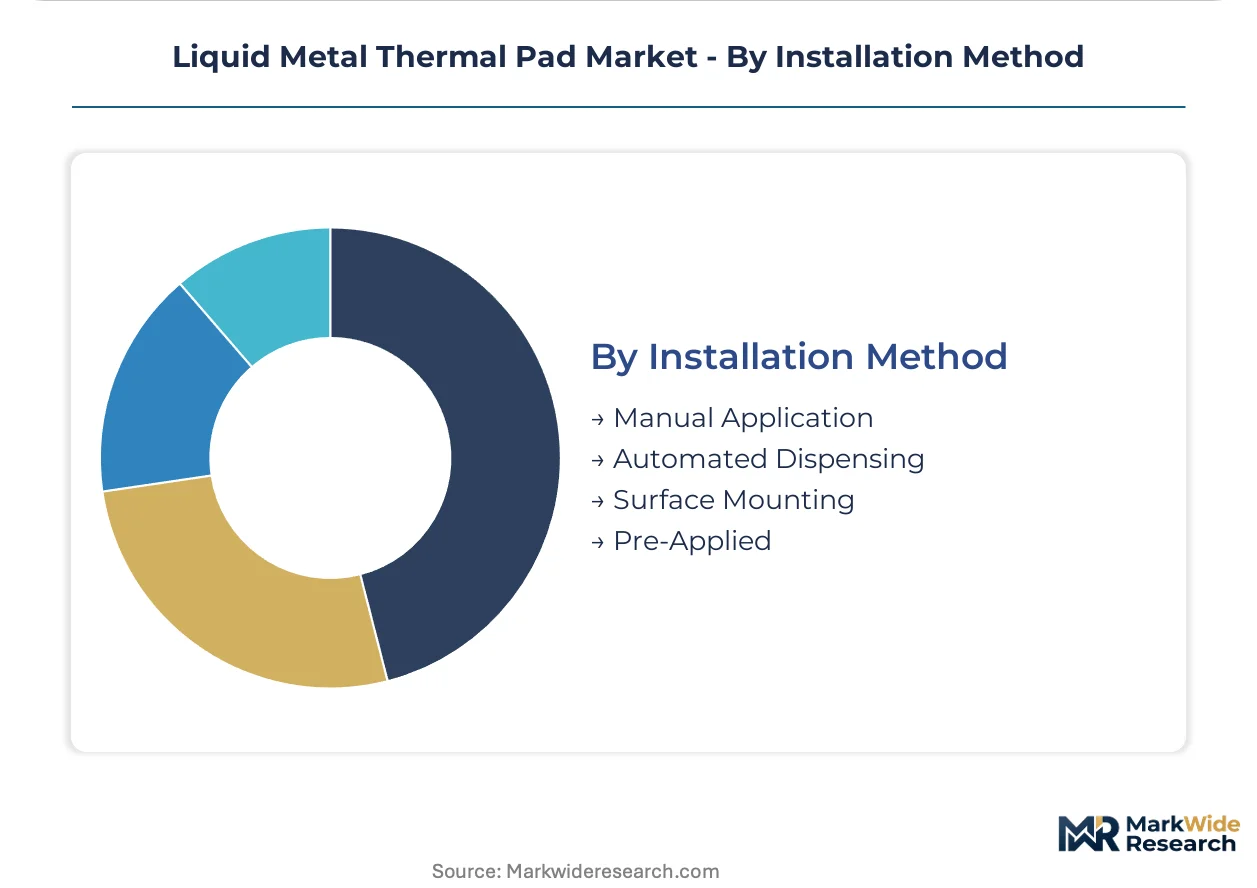
Installation Method:
Volume throughput requirements in electronics assembly lines drive automation adoption, while precision applications retain manual protocols for quality assurance.
- Manual Application:Technician-installed pads in repair environments and low-volume aerospace programs. German automotive suppliers accelerating alternative qualification programs use manual protocols for prototype validation before automated line transfer.
- Automated Dispensing:Robotic liquid metal deposition in semiconductor packaging and battery module assembly. Industrial equipment manufacturers face throughput consistency demands that outpace legacy silicone grease application lines.
- Surface Mounting:Pick-and-place compatible pad formats for SMT assembly integration.
- Pre-Applied:Factory-attached thermal interfaces on heat spreaders and cooling plates from thermal solution suppliers.
Automated dispensing dominates new line installations; manual application defends position in qualification and aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and appliance efficiency mandates under SAMR certification are accelerating thermal material upgrades across domestic electronics manufacturing corridors. South Korea and Taiwan drive volume procurement through concentrated semiconductor packaging lines. The United States and Germany anchor data center demand for GPU-intensive server rack interfaces.
China
Domestic OEM procurement concentrates in Yangtze River Delta electronics manufacturing clusters where GB standards for electronic product safety create dual compliance requirements for foreign suppliers. SAMR certification mandates accelerate thermal material upgrades in appliance and server manufacturing. Shenzhen and Shanghai host the densest concentrations of liquid metal thermal pad compounders serving local OEMs.
South Korea
High-performance computing OEMs in Seoul Capital Area compress qualification cycles from 36 months to 18 months for chiplet-based GPU architectures. MFDS oversight of industrial chemical handling shapes formulation protocols for domestic production lines. Samsung and SK Hynix supply chains in Gyeonggi Province drive volume procurement of phase-stable interface materials.
Taiwan
Semiconductor foundry concentration in Hsinchu Science Park and Tainan Technology Industrial Park generates sustained demand for thermal interface materials in advanced packaging operations. Local environmental regulations governing gallium compound handling constrain formulation choices for foreign suppliers. TSMC supply chain integration pulls thermal pad procurement through dedicated vendor qualification programs.
United States
Hyperscale data center construction in Virginia and Texas creates direct procurement volumes exceeding 10,000 units annually for liquid metal thermal interfaces in GPU-intensive server racks. EPA industrial chemical oversight and OSHA workplace safety protocols shape handling requirements for gallium-indium-tin formulations. Colocation operators in Northern Virginia negotiate frame contracts bundling thermal pad supply with installation services.
Germany
Automotive battery thermal management demand from pouch cell and prismatic module assemblers anchors Henkel AG's supplier relationships in EV manufacturing corridors. ECHA REACH authorization requirements for indium compounds force reformulation reviews for thermal pads exceeding 0.1% indium by mass. Bavaria and Baden-Württemberg host the primary automotive qualification pathways for phase-stable thermal interface materials.
Liquid Metal Thermal Pad Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into captive refiners with upstream material control, enthusiast-grade brands with direct-to-consumer distribution, and automotive-qualified compounders with extended qualification pathways. Three archetypes dominate: raw material integrators securing gallium and indium supply; performance brands commanding retail premiums; and industrial suppliers anchoring OEM design-in relationships. Competitive moves concentrate on backward integration into indium refining and automated dispensing technology licensing.
Among specialty chemical and materials suppliers, Indium Corporation, Thermal Grizzly, and Henkel AG & Co. KGaA occupy distinct positioning vectors. Indium Corporation exemplifies the captive refiner archetype through its namesake metal integration. Thermal Grizzly represents the enthusiast-grade brand model with European PC market channel control. Henkel AG & Co. KGaA anchors the automotive-qualified industrial supplier tier with extended OEM qualification pathways.
| Leading Market Players |
|---|
| Indium Corporation |
| Thermal Grizzly |
| Henkel AG & Co. KGaA |
| Laird Performance Materials |
| Fujipoly |
| Shin-Etsu MicroSi |
| Sino Santech Materials Technology Co., Ltd |
| Coollaboratory |
| Innovation Cooling |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta electronics manufacturing clusters concentrate gallium-indium-tin refining capacity that translates directly into downstream pricing power for domestic compounders serving SAMR-certified appliance OEMs. Foreign suppliers face dual compliance cost burdens against GB standards that compress margin pools in premium segments.
Pricing Analysis
Certification level (CE/FDA-grade for medical wearables, MIL-STD-810G for aerospace) creates the primary spread between commodity thermal pads and qualified interface materials. Three-tier pricing structure across premium qualified, standard industrial, and economy retrofit levels tracks directly to testing documentation depth and batch traceability. Cost compression in the economy tier intensifies because Chinese state-controlled smelters manipulate export quotas on indium feedstock. Data center procurement teams exhibit lowest price sensitivity due to thermal failure cost exposure, while PC enthusiast retailers defend margin through direct channel control.
Supply Chain Analysis
Gallium byproduct recovery from bauxite refining in China, Indonesia, and Guinea anchors upstream feedstock availability for eutectic alloy production. Formulation chemistry draws from indium concentrates, tin ingots, and trace silver or zinc additions for supercooling suppression. Single-source vulnerability clusters in Chinese state-controlled indium smelters exposes non-domestic compounders to export license disruption. Distribution runs through direct frame contracts with hyperscale data center operators for volumes exceeding 10,000 units annually, displacing traditional distributor-mediated purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation service bundling and thermal testing equipment leasing expand faster than hardware margins as data center operators outsource interface qualification and application protocols to compounder-led service teams.
For Market Incumbents: Harden captive indium supply positions through backward integration into refining or long-term offtake agreements with Yangtze River Delta smelters. Accelerate automated dispensing technology licensing to industrial equipment manufacturers facing throughput consistency demands that outpace legacy silicone grease lines. Defend against emerging asset-light compounders by embedding thermal pad supply into multi-year frame contracts with installation service attachments. For New Entrants and Emerging Players: Pursue wearable medical device qualification pathways where FDA biocompatibility scrutiny of gallium formulations has thinned incumbent presence. Target European PC enthusiast retail channels where direct-to-consumer distribution remains fragmented across national markets. Lead with automated dispensing integration services rather than commodity pad supply to bypass capital-intensive fabrication infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science subscription play because thermal interface qualification cycles compress from 36 months to 18 months, accelerating replacement demand and recurring certification revenue. Acquisition target archetype: mid-tier compounders with captive gallium-indium-tin formulation IP and established automotive qualification pathways. Watch indium export quota announcements from Chinese state planning authorities as the signal for feedstock cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Refining | Captive supply secures formulation cost stability against SAMR export quota manipulation. |
| Automated Dispensing Technology Licensing | Industrial equipment manufacturers in Virginia and Frankfurt require throughput consistency for GPU server rack deployment. |
| FDA Biocompatibility Qualification Pathway | Wearable medical device suppliers gain first-mover positioning ahead of REACH SVHC indium restrictions. |
| Installation Service Bundling | Colocation operators in Northern Virginia negotiate frame contracts combining thermal pad supply with application protocols. |
| Automotive Battery Thermal Management Qualification | Henkel AG's pathway anchor with German and Chinese EV assemblers demonstrates high-switching-cost revenue durability. |
Research Methodology
A spread of perspectives from thermal materials R&D directors, data center procurement leads, semiconductor packaging engineers, and automotive battery system architects converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with downstream OEM specification teams and upstream compounder operations managers. Secondary validation drew from ECHA REACH substance classification updates, SAMR certification requirement bulletins, SEC 10-K disclosures from listed materials suppliers, and customs trade data on gallium-indium alloy shipments. Bottom-up segment sizing triangulated against top-down thermal interface material market allocation estimates.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product form factor, installation protocol, end-use thermal load intensity, and regional regulatory compliance cluster. CAGRs derived from installed base replacement cycles in GPU-intensive server racks and EV battery thermal management system penetration curves. Industry-specific forecast inputs included chiplet-based GPU architecture adoption rates from Taiwan-based high-performance computing OEMs and MFDS industrial chemical handling protocol revisions affecting South Korean production lines.
Sensitivities concentrate around gallium price volatility from bauxite refining economics, ECHA SVHC classification threshold adjustments for indium compounds, and Chinese dual carbon policy implementation pace affecting appliance efficiency mandate stringency. Forecasts reflect documented assumptions on qualification cycle compression rates and automated dispensing adoption curves. Material shifts in REACH authorization timelines or SAMR carbon border adjustment mechanisms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Platinum Compounds Market
Metals
Steel Casting Market
Metals
China Copper Market
Metals
US Copper Scrap Market
Metals
Metal Forging Parts Market
Metals
Cold Drawn Wire Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Global Vanadium Market
Metals
Aluminum Welding Market
Metals
Iron and Steel Market
Metals
Carbotanium Market
Metals
Stainless Steel Round Bar Market
Metals
Silver Sulphate Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Nickel Powder Plating Market
Metals
Base Metals Market