
 Global Metal and Metal Manufactured Products Market | 2026-2036
Global Metal and Metal Manufactured Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal and Metal Manufactured Products Market Foresight
Aftermarket service revenue for engineered metal components is reconfiguring profit pools away from commodity tonnage sales. ArcelorMittal leverages its global service center network to capture recurring maintenance contracts. Nucor Corporation anchors its position through electric arc furnace flexibility and regional mill density. China Baowu Steel Group dominates carbon-efficient slab production through hydrogen pilot programs.
Metal and metal manufactured products encompass refined ores, primary metals, alloys, and downstream fabricated components produced through casting, forging, rolling, extrusion, and machining processes, serving structural, thermal, electrical, and mechanical functions across industrial and consumer applications. Ferrous metals and metal fabricated components command the deepest margin pools due to construction and infrastructure pull, while non-ferrous metals and alloys are gaining share from electrification and lightweighting requirements in aerospace and electronics. Casting and rolling technologies sustain the highest throughput volumes, though additive-adjacent machining and precision forging are capturing premium pricing for complex geometries.
The EPA enforces emissions caps on US primary steel and aluminum smelters under the Clean Air Act, while REACH and the EU Green Deal impose carbon border adjustments and embodied carbon disclosure on imported metal goods. China's MEE administers dual carbon targets that mandate scrap-based and hydrogen-reduced iron capacity expansion. Stakeholders must monitor regulatory divergence between carbon-intensive and low-emission production pathways as compliance costs fragment competitive positioning across supply origins.
Market Dynamics
Carbon border adjustments and embodied carbon disclosure mandates are bifurcating supply chains into low-emission and carbon-intensive production corridors, forcing capacity relocation and sourcing recalibration across primary metal producers.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers into the European Union face escalating compliance costs for high-carbon steel and aluminum, accelerating investment in electric arc furnace and hydrogen direct reduction capacity across supplier nations.
- Power generation infrastructure:Utilities in India, Brazil, and Vietnam are expanding transmission networks and renewable generation assets, pulling fabricated structural steel and copper winding alloys into long-term procurement cycles.
- Scrap-based production:China's MEE mandates for dual carbon compliance are expanding induction furnace and electric arc furnace capacity, redirecting ferrous scrap flows toward carbon-efficient slab output.
Market Restraints
- Iron ore and coking coal volatility:Blast furnace operators remain exposed to seaborne raw material price swings from Australian and Brazilian concentrate suppliers, compressing margin predictability.
- Primary aluminum smelter concentration:Over sixty percent of global primary aluminum capacity sits in regions with subsidized power tariffs, creating stranded asset risk as carbon border adjustments phase in.
- Green hydrogen cost premium:Hydrogen direct reduction remains two to three times costlier than conventional blast furnace routes, limiting near-term scale-up outside subsidy-backed demonstration projects.
Strategic Opportunities
- Saudi Arabia and UAE industrial zones:Low-cost renewable electricity and carbon-free hydrogen pilot programs are attracting integrated flat steel and aluminum rolling investments for European and Asian export markets.
- Automotive lightweighting mandates:OEMs in Germany, Japan, and South Korea are expanding aluminum sheet and high-strength steel content per vehicle, opening specification-grade supply contracts.
- Digital twin and predictive maintenance convergence:Service centers are bundling real-time wear monitoring with engineered component supply, shifting revenue from spot tonnage to lifecycle contracts.
Industry Challenges
- Electrical and automation engineering talent:Smelter modernization and furnace electrification require scarce skill sets in power electronics and process control, constraining retrofit timelines.
- Multi-jurisdiction certification complexity:Fabricated structural components for aerospace and nuclear applications face divergent weld qualification and traceability standards across the FAA, EASA, and CAAC.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal and Metal Manufactured Products Market |
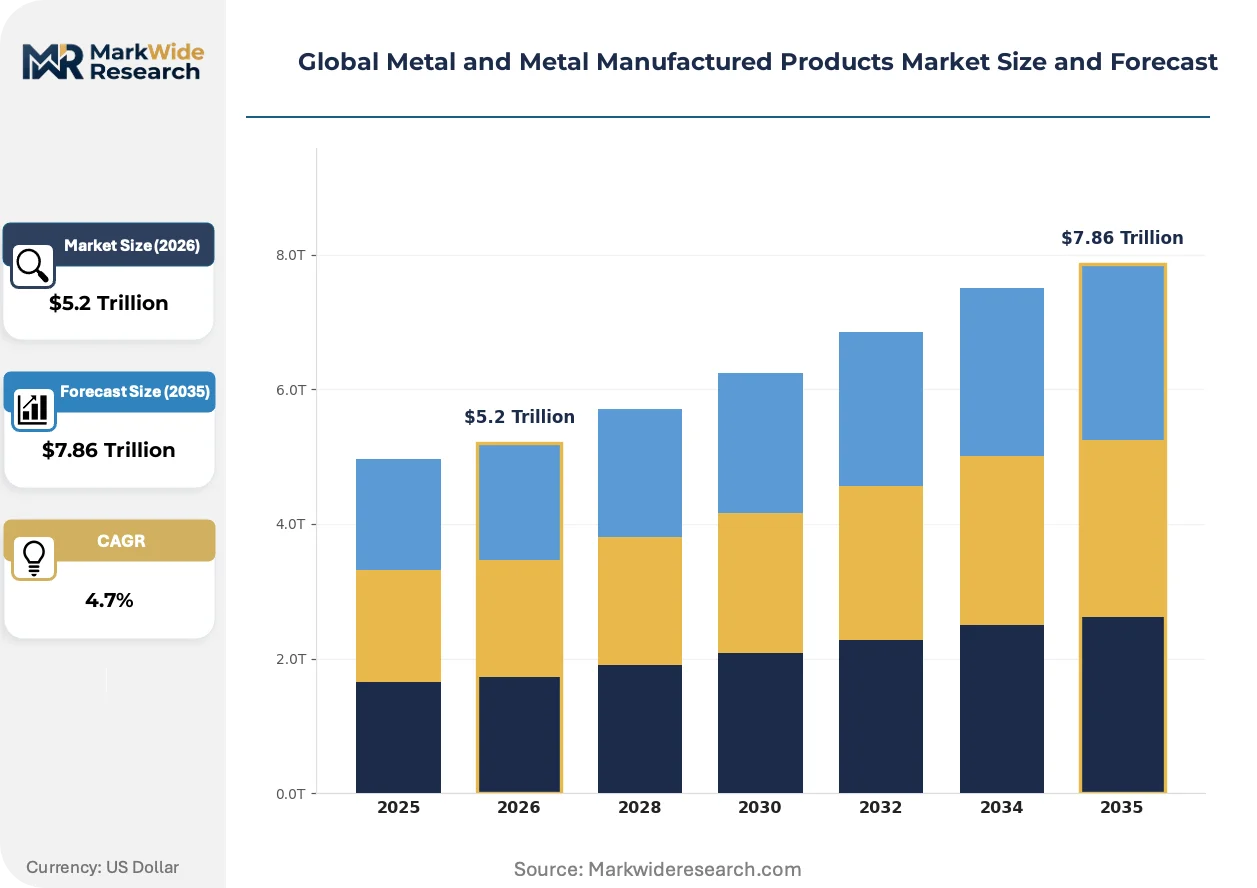
| Market Size in 2026 | $5.2 Trillion |
| Market Size in 2035 | $7.86 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrous Metals, Non-Ferrous Metals, Alloys, Metal Fabricated Components Manufacturing Technology: Casting, Forging, Rolling, Extrusion, Welding, Machining Application: Construction, Aerospace, Energy Equipment, Consumer Goods, Heavy Machinery End User Industry: Infrastructure Development, Aviation Sector, Power Generation, Electronics Industry |
| Companies Covered | ArcelorMittal, China Baowu Steel Group, Nippon Steel Corporation, Nucor Corporation, China Minmetals Corporation, POSCO, JFE Steel Corporation, Tata Steel, China Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal and Metal Manufactured Products Market Shifts & Advancements
Process instrumentation and artificial intelligence are penetrating primary metal production, compressing energy intensity and yield variance while enabling predictive quality control at furnace and rolling mill stages.
Industrial internet-of-things sensor networks are digitizing thermal and chemical process parameters across blast furnaces, electric arc furnaces, and continuous casters. Steelmakers in South Korea and Germany are deploying these systems at commercial scale, reducing specific energy consumption and unplanned downtime through real-time anomaly detection.
The EU Green Deal's carbon border adjustment mechanism and embedded emissions reporting requirements are restructuring trade flows for imported steel and aluminum. MEE-administered dual carbon targets in China are accelerating parallel compliance investments, while the EPA enforces Clean Air Act emissions caps on US smelters. Carbon-intensive producers in Turkey, Russia, and India face margin compression as European buyers demand certified low-emission supply.
Consolidated procurement functions at automotive and construction OEMs are compressing supplier bases and extending contract durations. Tier-one fabricators in Japan and Germany are responding with integrated design-to-delivery offerings that bundle material supply, precision machining, and inventory management. This shift displaces spot market transactions with multi-year framework agreements tied to performance metrics.
Global Metal and Metal Manufactured Products Market Segmentation
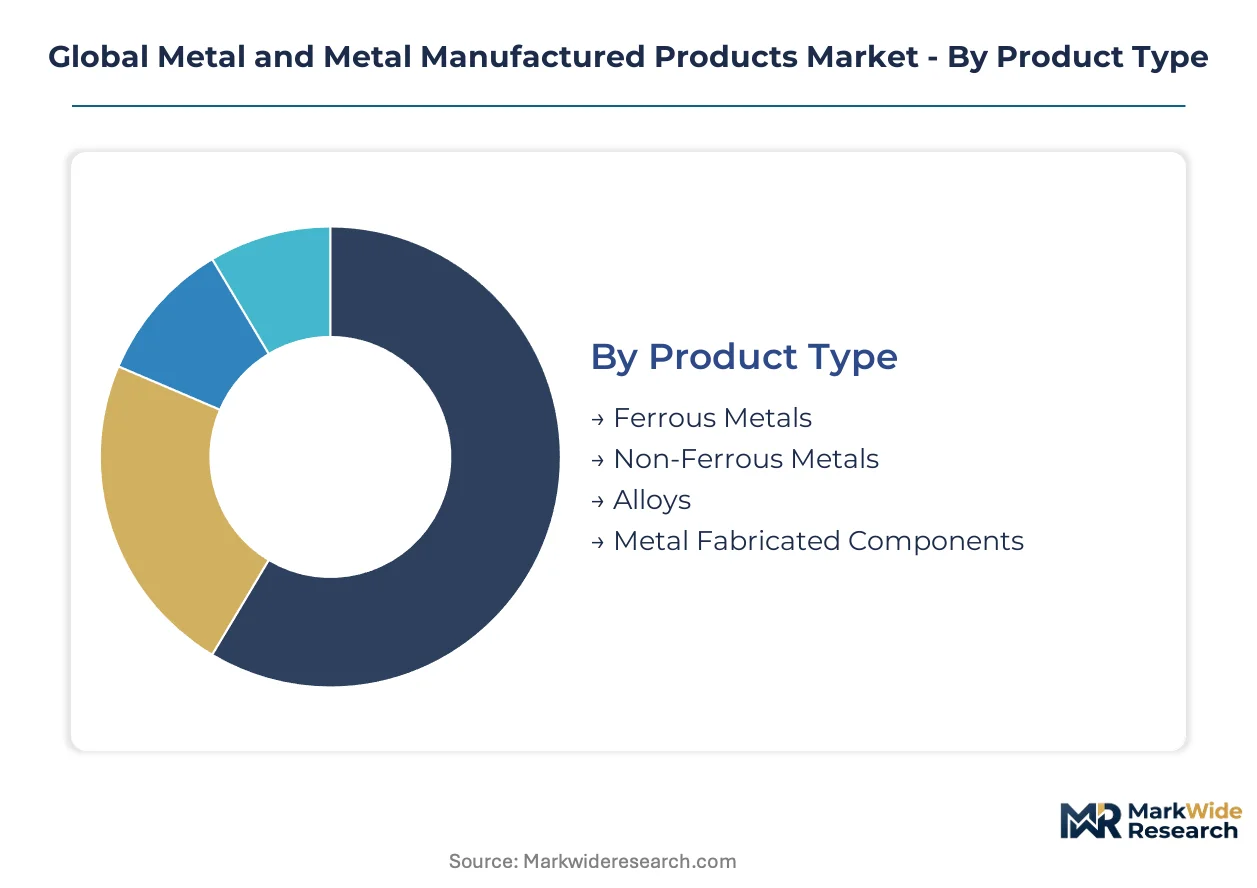
Segmentation in metal markets exposes divergent margin structures and capital intensity across production pathways. Understanding where value concentrates versus where volume flows enables targeted capacity planning and procurement positioning.
Product Type:
Cycle times vary dramatically: ferrous metals turn on construction and infrastructure procurement calendars with 6-18 month visibility, while non-ferrous metals respond to electronics and aerospace spot demand with quarterly volatility.
- Ferrous Metals:Carbon and alloy steels produced through blast furnace and electric arc routes serve structural applications with high tonnage throughput. Demand concentrates in China's property sector and India's industrial corridor builds, though carbon border adjustments are redirecting procurement toward scrap-based and hydrogen-reduced supply.
- Non-Ferrous Metals:Primary aluminum, copper, zinc, and nickel deliver conductivity and corrosion resistance with lower density than ferrous alternatives. Power generation utilities in Vietnam and Brazil are absorbing copper winding alloys for transmission expansion, while automotive OEMs in Germany and Japan specify aluminum sheet for lightweighting mandates.
- Alloys:Engineered combinations of base metals with precise mechanical, thermal, or magnetic properties for specification-critical applications.
- Metal Fabricated Components:Cut, bent, welded, and machined assemblies delivered as finished structural elements or machine subsystems.
Ferrous metals dominate installed base tonnage. Non-ferrous metals are where expansion concentrates for electrification and lightweighting applications.
Manufacturing Technology:
Cost tiers separate high-volume commodity production from precision premium capture: casting and rolling occupy the lowest per-unit processing costs, while machining and precision forging command 3-5x multiples for complex geometries.
- Casting:Molten metal poured into molds produces near-net-shape components with minimal subsequent processing. Sand and investment casting lines in India and Mexico supply automotive and construction OEMs with high-volume structural parts at compressed conversion costs.
- Forging:Compressive deformation under heat generates directional grain structures with superior fatigue resistance. Aerospace tier-one suppliers in Germany and Japan deploy closed-die forging for turbine discs and landing gear components requiring FAA and EASA traceability certification.
- Rolling:Continuous compression between rotating mills reduces slab and billet to sheet, plate, and long products.
- Extrusion:Forced flow through shaped dies creates constant cross-section profiles from aluminum and copper billets.
- Welding:Fusion joining of components enables fabricated assembly construction across infrastructure and machinery applications.
- Machining:Material removal processes achieve tight tolerances for precision-engineered components.
Rolling dominates installed capacity scale. Forging and machining are where margin expansion concentrates.
Application:
Customer type fragmentation splits procurement patterns: construction and heavy machinery buyers negotiate annual framework contracts with volume commitments, while aerospace and electronics specify on a program-by-program basis with embedded quality audits.
- Construction:Structural steel, rebar, and fabricated metalwork for commercial, residential, and civil infrastructure builds. India's National Infrastructure Pipeline and Saudi Arabia's NEOM development are absorbing rising volumes of fabricated structural steel for megaproject delivery.
- Aerospace:Titanium alloys, high-strength aluminum, and superalloys for airframe and propulsion systems. OEMs in France and the United States are qualifying new suppliers against AS9100 and NADCAP standards as they dual-source critical components.
- Energy Equipment:Pressure vessels, turbine components, and transmission infrastructure for power generation and oil and gas extraction.
- Consumer Goods:Appliances, packaging, and durables with moderate performance requirements and high aesthetic finish standards.
- Heavy Machinery:Mining, agricultural, and industrial equipment frames and powertrain components.
Construction dominates current offtake volume. Aerospace is where specification-grade premium capture concentrates.
End User Industry:
Geography drives divergence in growth trajectories: infrastructure and power generation expansion concentrates in emerging economies, while aviation and electronics demand clusters in developed manufacturing hubs with certification density.
- Infrastructure Development:Government-funded transportation, water, and urban construction programs pulling fabricated metal and structural steel. Brazil's Growth Acceleration Program and Indonesia's capital relocation are generating multi-year procurement cycles for integrated steel mills and regional service centers.
- Aviation Sector:Commercial and defense aircraft OEMs and their tiered supply chains specifying material to exacting standards. Boeing and Airbus production rate recoveries are cascading demand through specialty alloy suppliers in the United States and France.
- Power Generation:Utilities and equipment builders procuring copper, steel, and specialty alloys for generation and transmission assets.
- Electronics Industry:Semiconductor packaging, connector, and thermal management applications requiring high-purity copper and specialty alloys.
Infrastructure development dominates current contract volume. Power generation is where electrification-driven expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil demonstrate the highest price elasticity for standard structural grades, while German and Japanese automotive OEMs absorb substantial premiums for certified low-carbon aluminum and high-strength steel specifications.
China
MEE-administered dual carbon mandates are accelerating scrap-based electric arc furnace and hydrogen direct reduction capacity builds. The Yangtze River Delta cluster around Shanghai hosts Baowu's hydrogen pilot programs, while Hebei province's blast furnace concentration faces forced consolidation under emissions intensity targets.
United States
EPA Clean Air Act enforcement is tightening particulate and greenhouse gas caps on primary steel and aluminum smelters. Nucor's electric arc furnace network across the Southeast and Midwest captures margin from carbon-border-exposed import competition, with mini-mill density highest in the Carolinas and Texas.
Germany
EU Carbon Border Adjustment Mechanism compliance costs are redirecting procurement toward certified low-emission supply chains. ThyssenKrupp's Duisburg complex and Salzgitter's SALCOS hydrogen program anchor the Ruhr and Lower Saxony clusters where automotive OEMs specify embodied carbon thresholds.
India
CEA-mandated transmission infrastructure expansion and the National Infrastructure Pipeline are absorbing rising structural steel and copper alloy volumes. JSW Steel and Tata Steel's Odisha and Jharkhand integrated complexes supply fabricated components for industrial corridor builds along the Delhi-Mumbai and Chennai-Bengaluru freight corridors.
Saudi Arabia
NEOM and Red Sea Project megaprojects are generating multi-year procurement cycles for fabricated structural steel. Ma'aden's Ras Al-Khair industrial zone integrates aluminum smelting with low-cost solar power, positioning the Eastern Province as a carbon-efficient export hub for European buyers.
Global Metal and Metal Manufactured Products Market Competitive Landscape
Integrated blast furnace operators and electric arc furnace specialists split the market along carbon intensity lines. The structure concentrates among Asian and European volume leaders, with mid-tier regional mills occupying fragmented construction supply niches. Three archetypes dominate: state-backed Chinese conglomerates with hydrogen pilot scale, North American mini-mill networks with scrap flexibility, and European incumbents with carbon border adjustment compliance infrastructure. Competitive moves center on hydrogen direct reduction partnerships and service center network consolidation.
Among the state-backed Asian conglomerates, China Baowu Steel Group exemplifies the carbon-efficient primary production archetype through its hydrogen program scale. Nucor Corporation anchors the North American mini-mill flexibility position with regional density across the Southeast and Midwest. ArcelorMittal occupies the integrated global network tier, leveraging service center penetration for aftermarket contract capture. These three represent divergent capital intensity and emissions pathway strategies.
| Leading Market Players |
|---|
| ArcelorMittal |
| China Baowu Steel Group |
| Nippon Steel Corporation |
| Nucor Corporation |
| China Minmetals Corporation |
| POSCO |
| JFE Steel Corporation |
| Tata Steel |
| China Steel Corporation |
| Others |
Supply & Pricing Matrix
Iron ore and coking coal volatility from Australian and Brazilian concentrate suppliers determines both margin compression in blast furnace operations and the geographic relocation of capacity toward scrap-based and hydrogen-reduced production corridors. Carbon border adjustment exposure splits pricing tiers between certified low-emission supply and carbon-intensive imports, while procurement managers recalibrate sourcing footprints to manage landed cost variance.
Pricing Analysis
Aftermarket service contracts for engineered components drive lifetime value capture beyond spot tonnage transactions. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade aerospace alloys from construction-grade rebar and commodity sheet. Cost compression in carbon-intensive primary production is intensifying because EU Carbon Border Adjustment Mechanism compliance costs are redirecting procurement toward certified low-emission supply. Construction buyers in India and Brazil demonstrate the highest price elasticity for standard structural grades, while German automotive OEMs absorb substantial premiums for certified low-carbon aluminum specifications.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk as carbon border adjustments phase in and redirect trade flows toward Middle Eastern and Southeast Asian export hubs. Primary production concentrates in China, India, and Russia, while downstream fabrication draws from Mexico, Vietnam, and Poland for regional market access. The supply chain rests on seaborne iron ore from Australia and Brazil, coking coal from Mongolia and Australia, and ferrous scrap flows from North American and European collection networks. Single-source vulnerability in primary aluminum smelting creates stranded asset risk as power tariff subsidies face scrutiny. Distribution runs through integrated mill direct sales for large contract volumes and regional service center networks for fragmented construction and machinery demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in electrical and automation engineering talent constrains smelter modernization timelines and fragments competitive positioning between retrofit-capable incumbents and greenfield entrants with native digital infrastructure.
For Market Incumbents: Pre-empt hydrogen direct reduction partnerships before subsidy-backed demonstration projects lock in regional capacity allocation. Secure backward integration into captive scrap collection networks to defend margin position against carbon border adjustment exposure. Invest in multi-jurisdiction weld qualification certification to capture aerospace and nuclear specification-grade contracts as tier-one fabricators consolidate supplier bases. For New Entrants and Emerging Players: Saudi Arabia's Ras Al-Khair and UAE industrial zones offer underpenetrated access to European export markets seeking carbon-efficient aluminum and flat steel supply. Target automotive lightweighting specification contracts in Germany and Japan where OEMs are expanding aluminum sheet and high-strength steel content per vehicle. Lead with digital twin and predictive maintenance bundling to displace spot market transactions with lifecycle revenue models. For Investors and Strategic Acquirers: The market sits at a capital-reallocation phase that favors electric arc furnace flexibility and hydrogen pilot scale over stranded blast furnace assets. Long-term viability over the next decade hinges on carbon-efficient production pathway positioning and service center network density for aftermarket contract capture. Monitor EU Carbon Border Adjustment Mechanism phase-in schedules and China's MEE dual carbon enforcement intensity as inflection indicators for competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Direct Reduction Partnership | ThyssenKrupp's Duisburg and Salzgitter's SALCOS programs anchor EU low-emission steel supply. |
| Scrap-Based Capacity Expansion | Nucor's Southeast and Midwest mini-mill density captures margin from carbon-border-exposed imports. |
| Service Center Network Consolidation | ArcelorMittal leverages global penetration to shift revenue from spot tonnage to lifecycle contracts. |
| Multi-Jurisdiction Certification Investment | FAA, EASA, and CAAC weld qualification standards enable aerospace tier-one supplier qualification. |
| Digital Twin and Predictive Maintenance Integration | Real-time wear monitoring bundles with engineered component supply displace transactional procurement. |
Research Methodology
A standing panel of plant managers at integrated steel and aluminum smelters, procurement leads at automotive and construction OEMs, aftermarket service heads at regional metal distribution networks, and technical R&D directors at specialty alloy producers provided ongoing calibration across the study period. Primary interview findings were validated against customs and trade data from major exporting authorities, SEC 10-K filings from publicly traded mill operators, industry association reports from the American Iron and Steel Institute and European Steel Association, and national emissions disclosure databases. Bottom-up capacity and production estimates were triangulated with top-down demand modeling from end-use industry procurement cycles.
Scenario bracketing around EU Carbon Border Adjustment Mechanism phase-in schedules, China's MEE dual carbon enforcement intensity, and green hydrogen cost curves structured the projection framework across the analysis window. Segmentation dimensions modeled include product type, manufacturing technology, application, and end-user industry, with regional regulatory clusters and carbon intensity pathways as cross-cutting variables. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated power generation infrastructure buildout timelines in India, Brazil, and Vietnam, plus automotive lightweighting content trajectories from German, Japanese, and South Korean OEM specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese conglomerates or Middle Eastern sovereign wealth-backed greenfield entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Silver Powder and Flakes Market
Metals
Metal Casting Market
Metals
Europe Aluminium Wire Rod Market
Metals
Beryllium Market
Metals
Silver Sulphate Market
Metals
Neodymium Market
Metals
Trivalent Chromium Finishing Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Cerium Market
Metals
Aluminum Tubes Market
Metals
Copper and Copper Alloy Market
Metals
Finished Steel Products Market
Metals
Global Superconducting Wire Market
Metals
Europe Metal Casting Market
Metals
Aluminum Extrusion Market
Metals
North America Aluminum Market