
 Isostatic Pressing Market | 2026-2036
Isostatic Pressing Market Size, Share, and Industry Trends Forecast 2026-2036
Isostatic Pressing Market Intelligence
Preventive maintenance contracts and software-defined pressure profiling is realigning how OEMs monetize isostatic pressing capacity. Kobe Steel leverages its integrated steel and machinery operations to sustain captive demand from Japanese aerospace suppliers. Bodycote anchors its global network through specialized hot isostatic pressing centers in Europe and North America. DORST Technologies GmbH competes via precision cold isostatic pressing systems for ceramic medical implant manufacturers.
Isostatic pressing applies uniform hydrostatic pressure from all directions to compact powders or densify castings, typically operating at pressures from 100 to 400 MPa and temperatures up to 2000°C depending on the process variant. The technique eliminates internal porosity in metals and ceramics, producing components with isotropic mechanical properties critical for rotating machinery and load-bearing implants. Hot isostatic pressing commands the largest value share due to its dominance in aerospace turbine disk repair and additive manufacturing post-processing. Cold isostatic pressing grows fastest in medical ceramics where alumina and zirconia hip socket blanks require near-net-shape forming before final machining. Vacuum isostatic pressing occupies a niche margin pool serving semiconductor-grade sapphire and specialty alloy producers demanding oxygen-controlled environments.
FDA 21 CFR Part 820 quality system regulations and EMA Medical Device Regulation standards shape product liability and traceability requirements for implant manufacturers sourcing isostatically pressed components. Japan's METI industrial standards and Germany's KBA automotive certification frameworks further constrain supplier qualification timelines for safety-critical applications. Stakeholders must monitor evolving EPA and REACH material restrictions on refractory metals and binder chemistries that could alter feedstock sourcing economics and equipment design specifications.
Market Dynamics
Hot isostatic pressing densification protocols for additive manufacturing post-processing are restructuring procurement relationships between aerospace OEMs and specialized service providers, compressing qualification timelines while elevating technical performance thresholds.
Growth Catalysts
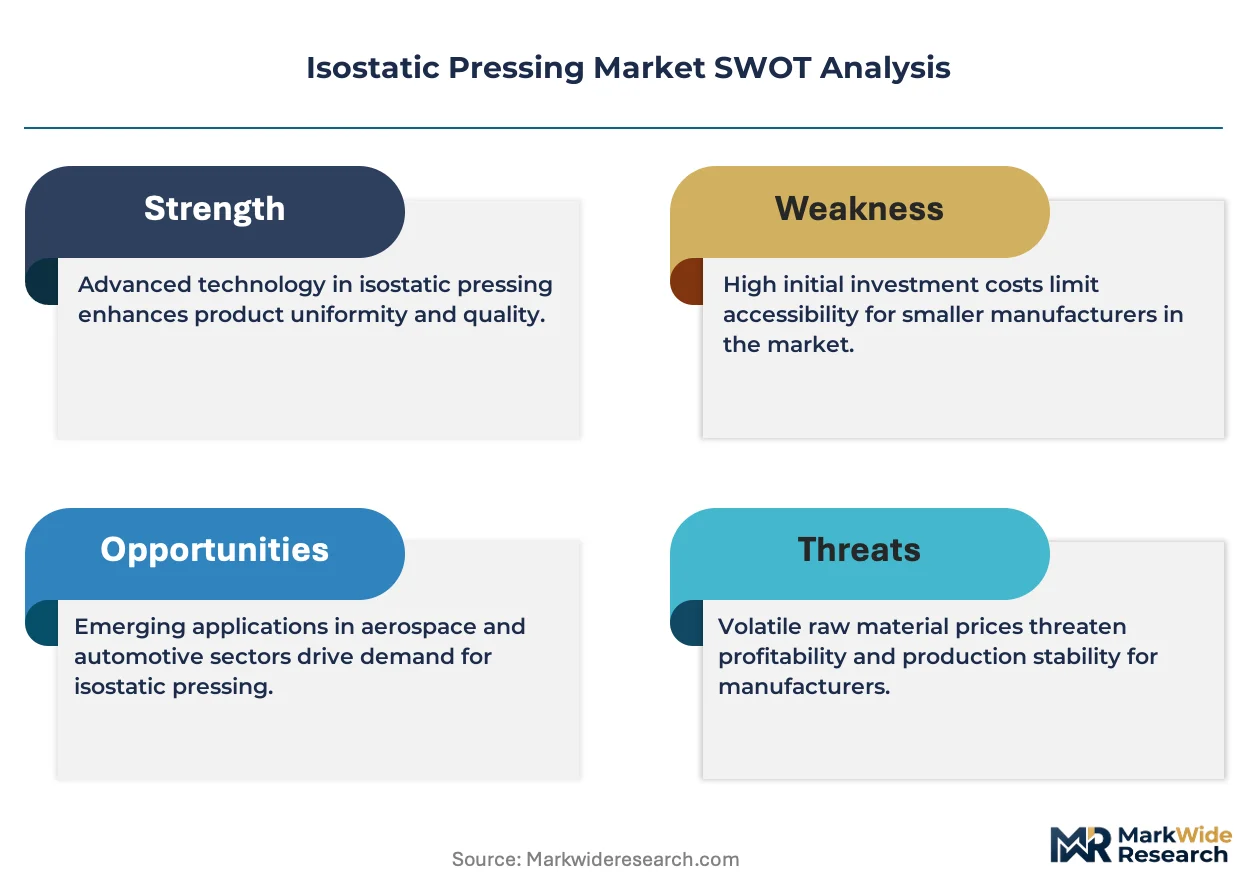
- EMA Medical Device Regulation:Implant-grade component traceability mandates are accelerating certification-driven sourcing from qualified isostatic pressing suppliers across European orthopedic device manufacturers.
- Titanium aluminide turbine blades:Next-generation aerospace engine architectures require hot isostatic pressing densification to achieve fatigue resistance specifications unattainable through conventional casting alone.
- German precision manufacturing clusters:Concentrated defense and energy sector demand around Stuttgart and Munich sustains dedicated hot isostatic pressing capacity investments.
Market Restraints
- Argon gas supply volatility:Inert gas consumption rates of 500-2000 cubic meters per hot isostatic pressing cycle expose operators to commodity price swings and regional supply disruptions.
- Refractory metal sourcing:Tungsten and molybdenum heater element supply concentrates in Chinese processing facilities, creating single-point vulnerability for equipment manufacturers.
- Pressure vessel certification:ASME Boiler and Pressure Vessel Code compliance timelines extend 18-24 months for new facility commissioning, constraining capacity expansion velocity.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting cold isostatic pressing investments for ceramic implant production serving Asian orthopedic markets.
- Semiconductor-grade sapphire growth:Vacuum isostatic pressing for LED substrate manufacturing represents underpenetrated demand vertical with distinct oxygen-controlled processing requirements.
- Digital twin integration:Convergence of finite element modeling with real-time pressure profiling enables predictive densification optimization for complex geometries.
Industry Challenges
- Metallurgical technician scarcity:Specialized expertise in high-temperature alloy behavior and porosity characterization remains concentrated among retiring workforce cohorts in mature manufacturing economies.
- Multi-standard compliance:Simultaneous FDA 21 CFR Part 820, ISO 13485, and customer-specific aerospace quality system audits impose documentation burdens that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isostatic Pressing Market |
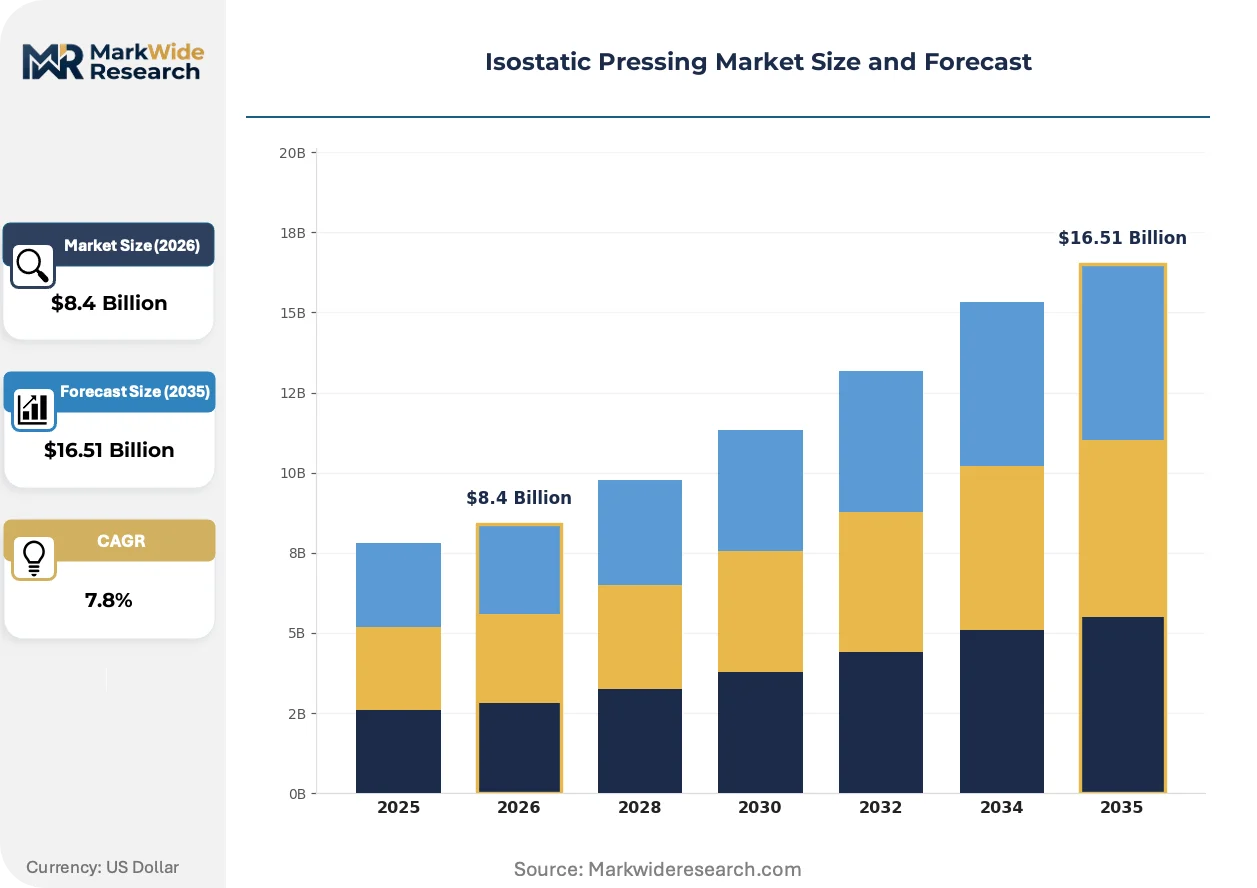
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Isostatic Pressing, Cold Isostatic Pressing, Vacuum Isostatic Pressing, Polymer Isostatic Pressing Material: Metals, Ceramics, Composites, Polymers End User: Aerospace, Automotive, Medical, Electronics Application: Powder Metallurgy, Additive Manufacturing, Tooling, Structural Components |
| Companies Covered | Kobe Steel, Ltd., Bodycote, American Isostatic Presses, Inc., Nikkiso Co., Ltd., DORST Technologies GmbH, Engineered Pressure Systems, Inc., Pressure Technology, Inc., EPSI, Shanxi Golden Kaiyuan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isostatic Pressing Market Strategic Shifts & Innovations
Software-defined process control and distributed manufacturing architectures are displacing centralized high-volume production models, enabling point-of-need densification services that reduce logistics costs and compress lead times for critical components.
Modular hot isostatic pressing units with containerized footprints are decentralizing capacity deployment toward aerospace manufacturing clusters in South Carolina, Bavaria, and Aichi Prefecture. Tier-one suppliers are adopting these systems to perform additive manufacturing post-processing in-house rather than shipping parts to centralized service centers. This proximity model is compressing turnaround times from weeks to days while capturing margin previously allocated to logistics intermediaries.
REACH restrictions on hexavalent chromium surface treatments are forcing equipment manufacturers to redesign protective coatings for pressure vessel internals and furnace furniture. The regulation's sunset dates for specific chemistries are accelerating R&D investment in alumina-based and silicon carbide alternative materials. European hot isostatic pressing operators face compressed timelines to validate new coating systems without degrading process contamination control.
After-sales service unbundling is separating equipment hardware procurement from predictive maintenance subscriptions and process parameter optimization consulting. Original equipment manufacturers are capturing recurring revenue through pressure profile analytics and remote diagnostics while buyers retain flexibility to select third-party maintenance providers. This model is most visible in Japanese and German markets where established supplier relationships support complex contractual structuring.
Isostatic Pressing Market Segmentation
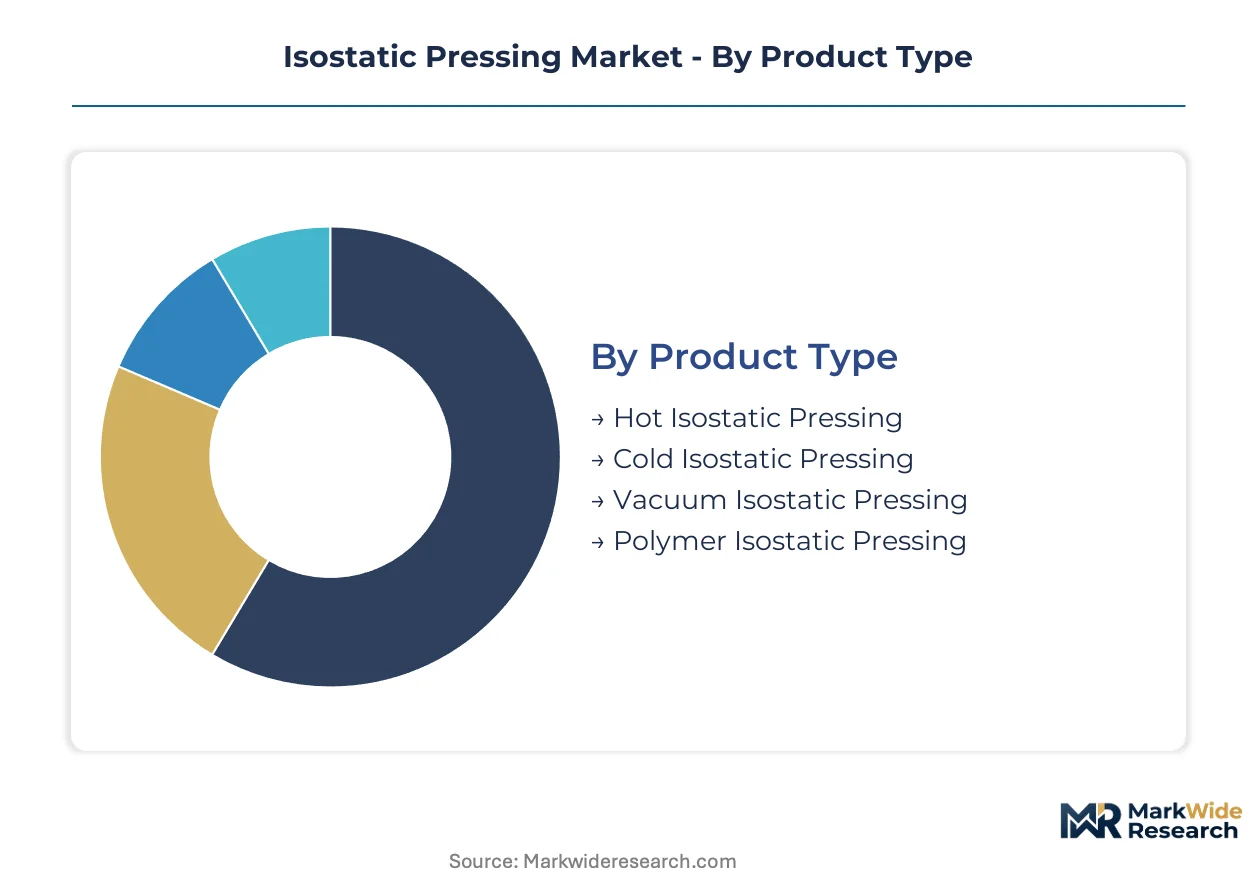
Isostatic pressing equipment and service procurement diverges sharply across process temperatures, material classes, and end-use certification requirements. Each segmentation dimension reflects distinct technical specifications, buyer decision criteria, and supplier qualification barriers that reshape competitive positioning.
Product Type:
Equipment selection hinges on densification temperature requirements and inert atmosphere control, with buyers trading capital intensity against processing flexibility.
- Hot Isostatic Pressing:Operates at 1000-2000°C with argon gas pressures of 100-200 MPa to eliminate internal porosity in cast superalloys and titanium aluminides. Aerospace turbine blade manufacturers in Germany and Japan concentrate procurement here due to fatigue resistance specifications that conventional casting cannot achieve.
- Cold Isostatic Pressing:Applies 100-400 MPa hydrostatic pressure at ambient temperatures using water or oil-based pressure media, forming ceramic and metal powder compacts before sintering. Medical implant manufacturers across the United States and Europe favor this process for alumina and zirconia hip socket blanks requiring near-net-shape precision.
- Vacuum Isostatic Pressing:Oxygen-controlled environments below 10^-5 mbar enable semiconductor-grade sapphire and specialty alloy processing where contamination tolerance approaches parts-per-billion thresholds.
- Polymer Isostatic Pressing:Lower-pressure variants serve PTFE and UHMWPE compression molding for chemical processing equipment linings and bearing applications.
Hot isostatic pressing leads on scale; cold isostatic pressing leads on momentum.
Material:
Feedstock selection determines furnace furniture compatibility, heating element longevity, and post-processing requirements that cascade through total cost of ownership calculations.
- Metals:Nickel-based superalloys, titanium alloys, and tool steels dominate aerospace and defense applications where hot isostatic pressing repairs casting defects and densifies additive-manufactured preforms. Tungsten and molybdenum heater element supply concentration in Chinese processing facilities creates sourcing vulnerability for equipment operators.
- Ceramics:Alumina, zirconia, silicon nitride, and silicon carbide require cold isostatic pressing for medical implants, cutting tools, and armor plates. EMA Medical Device Regulation traceability mandates are accelerating European orthopedic device manufacturer certification requirements for implant-grade ceramic components.
- Composites:Metal-matrix and ceramic-matrix composites for high-temperature structural applications represent emerging demand vertical with specialized pressure-temperature profiling requirements.
- Polymers:Limited to cold pressing applications serving fluoropolymer seals and bearings in chemical processing equipment.
Metals capture the dominant revenue share; ceramics are climbing the fastest.
End User:
Industry-specific quality system requirements and component criticality drive supplier qualification timelines and contract structuring approaches.
- Aerospace:Turbine disk, blade, and structural casting densification commands premium pricing due to FAA and EASA airworthiness certification requirements. Hot isostatic pressing post-processing of additive-manufactured aerospace components is restructuring procurement relationships between OEMs and specialized service providers.
- Automotive:Germany's KBA certification framework constrains supplier qualification for safety-critical powertrain and chassis components, favoring established hot isostatic pressing networks.
- Medical:FDA 21 CFR Part 820 quality system regulations and ISO 13485 standards impose documentation burdens that extend sales cycles for implant-grade component suppliers.
- Electronics:Semiconductor-grade sapphire and specialty alloy demand from LED substrate and advanced packaging applications requires vacuum isostatic pressing with oxygen-controlled environments.
Aerospace leads on scale; medical is gaining share fastest.
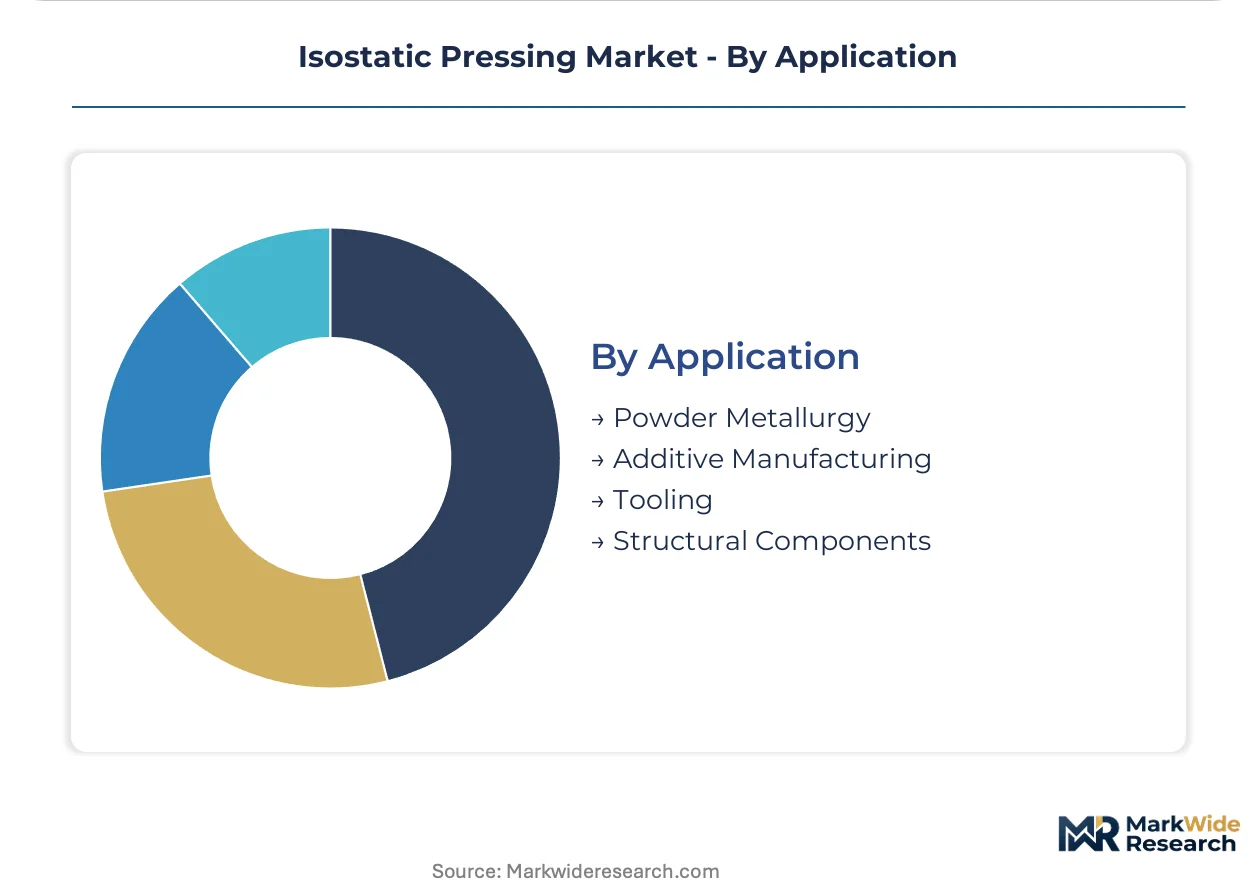
Application:
Process integration depth varies from standalone forming operations to embedded steps within broader manufacturing workflows.
- Powder Metallurgy:Cold isostatic pressing consolidates metal and ceramic powders into green compacts before sintering, serving structural components where net-shape forming reduces machining waste.
- Additive Manufacturing:Hot isostatic pressing densification protocols for 3D-printed metal parts are compressing qualification timelines while elevating technical performance thresholds for aerospace and medical applications.
- Tooling:Cemented carbide and high-speed steel cutting tool blanks require cold isostatic pressing to achieve uniform density and isotropic wear properties.
- Structural Components:Armor plates, nuclear fuel cladding, and chemical processing equipment leverage isostatic pressing for defect elimination in safety-critical applications.
Powder metallurgy leads on scale; additive manufacturing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where isostatic pressing capacity deploys, with cost-of-compliance gaps between jurisdictions driving investment toward markets with streamlined certification pathways for aerospace and medical applications.
United States
FAA airworthiness mandates and FDA 21 CFR Part 820 quality system requirements sustain premium demand for hot isostatic pressing in turbine disk repair and implant-grade component production. South Carolina's aerospace manufacturing corridor anchors modular hot isostatic pressing deployments that compress additive manufacturing post-processing lead times from weeks to days.
Germany
KBA automotive certification frameworks and EMA Medical Device Regulation traceability mandates constrain supplier qualification timelines for safety-critical applications. Stuttgart and Munich precision manufacturing clusters sustain dedicated hot isostatic pressing capacity investments serving defense and energy sector procurement.
Japan
METI industrial standards and aerospace OEM technical specifications drive turbine blade densification requirements that conventional casting cannot satisfy. Aichi Prefecture manufacturing bases integrate captive hot isostatic pressing capacity for titanium aluminide component production.
China
Domestic aerospace engine programs and medical device localization policies are accelerating cold isostatic pressing investments for ceramic implant manufacturing. Tungsten and molybdenum heater element processing concentration creates supply vulnerability for equipment operators dependent on refractory metal sourcing.
India
PLI scheme incentives for medical device domestic manufacturing are attracting cold isostatic pressing capacity for ceramic orthopedic implant production serving Asian markets. Emerging precision manufacturing clusters in Gujarat and Maharashtra are qualifying suppliers under streamlined CDSCO regulatory pathways.
Isostatic Pressing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with equipment OEMs capturing hardware margins while service providers monetize densification throughput. The vendor base organizes around three strategic archetypes: integrated steel-and-machinery conglomerates sustaining captive demand, specialized hot isostatic pressing network operators, and precision cold isostatic pressing system builders. Capacity expansion and strategic partnerships represent the dominant competitive moves, with modular system deployments and additive manufacturing post-processing service agreements reshaping procurement relationships.
Among Japanese and European industrial groups, Kobe Steel, Ltd. and Bodycote occupy positions reflecting distinct strategic orientations toward integrated operations versus specialized service networks. DORST Technologies GmbH exemplifies the precision equipment archetype focused on ceramic medical implant manufacturing segments. These three entities represent the spectrum of competitive positioning from captive supply integration through distributed service capacity to targeted system specialization.
| Leading Market Players |
|---|
| Kobe Steel, Ltd. |
| Bodycote |
| American Isostatic Presses, Inc. |
| Nikkiso Co., Ltd. |
| DORST Technologies GmbH |
| Engineered Pressure Systems, Inc. |
| Pressure Technology, Inc. |
| EPSI |
| Shanxi Golden Kaiyuan Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Software-defined process control and modular containerized units are simultaneously compressing capital deployment costs and fragmenting supply concentration away from centralized high-volume facilities toward aerospace manufacturing clusters in South Carolina, Bavaria, and Aichi Prefecture. This production-method transition redistributes pricing power from legacy service networks to OEMs performing in-house densification, while argon gas consumption rates of 500-2000 cubic meters per cycle tether operating economics to commodity volatility.
Pricing Analysis
Distributor margins for hot isostatic pressing equipment compress 8-15 points when OEMs procure direct for captive installations, while service providers defend throughput pricing via long-term aerospace qualification contracts. Pricing stratifies across FAA-certified turbine repair, ISO 13485 medical implant processing, and standard industrial densification tiers. Cost compression in semiconductor-grade vacuum pressing intensifies because LED substrate manufacturers negotiate volume scale against limited qualified suppliers. Medical device OEMs exhibit highest price sensitivity due to reimbursement pressure, whereas defense contractors accept premium positioning for traceability documentation.
Supply Chain Analysis
ASME Boiler and Pressure Vessel Code certification gates equipment sourcing to qualified fabricators in the United States, Germany, and Japan, constraining vessel supply to 18-24 month lead times. Tungsten and molybdenum heater elements draw from Chinese processing concentration, creating single-source vulnerability for furnace manufacturers. Tariff exposure on refractory metals threatens cost stability for European and North American equipment builders. Distribution runs through specialized industrial distributors serving aerospace OEMs and direct procurement contracts for medical implant manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isostatic pressing market compounds steadily as additive manufacturing post-processing creates durable demand for densification services that conventional casting cannot displace. Aerospace and medical certification requirements erect structural barriers that protect qualified incumbents from commodity competition.
For Market Incumbents: Hedge against modular system disruption by acquiring containerized hot isostatic pressing technology providers in South Carolina and Bavaria aerospace corridors. Captive capacity additions at Tier-1 suppliers threaten service network volumes; defend positioning through exclusive additive manufacturing post-processing partnerships with qualified aerospace OEMs.
For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for cold isostatic pressing investments serving Asian orthopedic markets with streamlined CDSCO regulatory pathways. Target ceramic implant blank production for domestic manufacturers qualifying under EMA Medical Device Regulation traceability mandates. Pursue hospital system partnerships as anchor demand for near-net-shape hip socket manufacturing.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision cold isostatic pressing system builders serving medical ceramics, where EMA certification investments depress near-term margins but create durable competitive moats. Five-to-ten-year viability favors equipment OEMs with software-defined pressure profiling capabilities. Watch for inflection when semiconductor-grade sapphire demand triggers vacuum isostatic pressing capacity shortages.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Capacity Deployment | Containerized hot isostatic pressing units compress additive manufacturing post-processing lead times from weeks to days. |
| Backward Integration into Argon Supply | Long-term inert gas offtake agreements hedge against commodity price volatility and regional supply disruptions. |
| Software-Defined Process Control | Real-time pressure profiling analytics enable predictive densification optimization and recurring revenue capture. |
| Medical Device Certification Investment | FDA 21 CFR Part 820 and ISO 13485 qualification barriers protect implant-grade component pricing from commodity competition. |
| Refractory Metal Sourcing Diversification | Alternative heater element suppliers outside China reduce single-point vulnerability for equipment manufacturers. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market obtained through structured interviews with aerospace procurement directors, medical device quality assurance leads, hot isostatic pressing service center managers, ceramic implant manufacturing engineers, and refractory metal supply specialists. Secondary validation draws from FAA airworthiness directives, FDA 510(k) filings, EMA Medical Device Regulation guidance documents, METI industrial standards publications, and ASME Boiler and Pressure Vessel Code certification records. Bottom-up equipment shipment data triangulates against top-down aerospace and medical device production forecasts.
Segment-level modeling operates at process temperature variant, material class, end-use certification requirement, and geographic manufacturing cluster resolution across the analysis window. CAGRs derive from regression analysis of historical equipment installation rates against aerospace engine production and orthopedic implant procedure growth trajectories. Forecast inputs incorporate additive manufacturing adoption curves for metal powder bed fusion and ceramic injection molding capacity expansion plans.
Revisions become necessary when argon gas supply disruptions, REACH restrictions on refractory metal processing, or ASME certification timeline extensions materially alter capacity expansion economics. Forecasts reflect documented assumptions regarding aerospace OEM in-sourcing decisions and medical device manufacturer qualification timelines. A model refresh is warranted upon material change in FDA or EMA regulatory enforcement intensity for implant-grade component traceability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Wood Protein Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Investment Casting Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Plastic Molds Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Global Friction Products and Materials Market