
 Transparent Polyamides Market | 2026-2036
Transparent Polyamides Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Polyamides Market Outlook
Specialized polymer engineering talent is rotating toward transparent polyamide formulation centers as resin producers compete for high-clarity, high-heat compounds. Evonik Industries AG leverages its PA 12 technology leadership to sustain premium positioning in medical and optical grades. BASF SE anchors European supply through integrated caprolactam-to-polymer operations at Ludwigshafen. Arkema differentiates via specialty amorphous polyamides targeting electronics and consumer aesthetics.
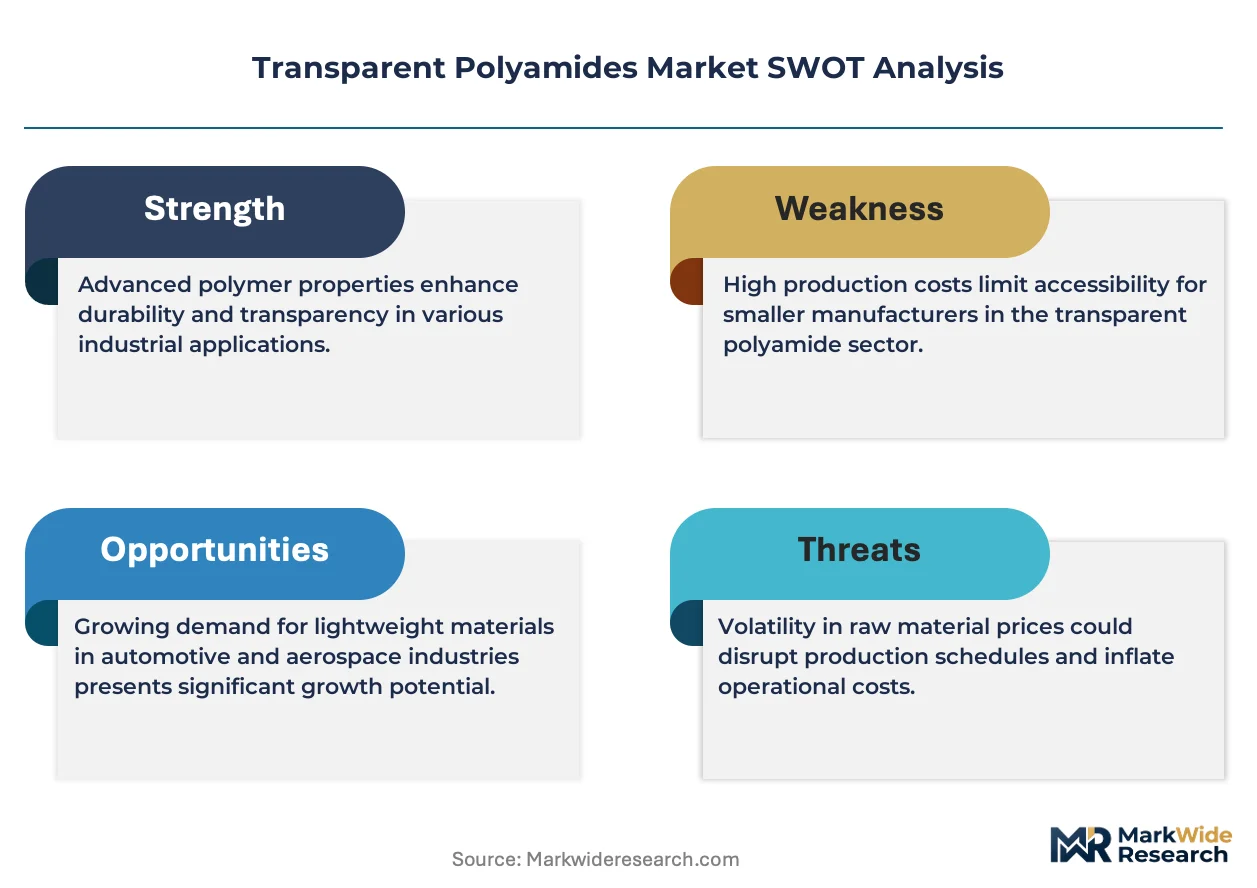
Transparent polyamides are semi-crystalline or amorphous thermoplastic resins combining aliphatic or semi-aromatic repeat units with inherent optical clarity exceeding 85% light transmission in thin sections, manufactured through melt polycondensation or anionic ring-opening polymerization depending on the specific PA backbone. Their primary purpose is to replace glass and conventional opaque engineering plastics in applications requiring simultaneous transparency, mechanical strength, and chemical resistance. PA 12 dominates film and extrusion applications where moisture absorption must remain minimal, while PA 6 and PA 66 occupy cost-sensitive automotive and industrial segments where slight haze tolerance exists. Granule form commands the largest volume share as compounders prefer melt-compounding flexibility, though sheet demand is accelerating in aerospace interior panels.
REACH registration requirements under ECHA govern monomer and additive compositions entering European automotive and electronics supply chains, while FDA food-contact regulations in the United States constrain migration limits for packaging film grades. China's GB standards and MIIT material directives shape domestic qualification protocols for transparent polyamide substitution in display and lighting applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across jurisdictions, as these chemicals appear in some anti-wear and process additive packages. The decisive factor ahead is whether regional recyclability mandates will force reformulation of transparent grades currently optimized for virgin performance rather than closed-loop recovery.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are forcing rapid substitution of glass and metal components with transparent polyamide compounds, compressing qualification timelines from 36 months to 18 months for headlamp and fuel system applications.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for monomer purity are accelerating compounder investment in high-clarity PA 12 production lines serving European automotive supply chains.
- Electronics-grade demand clustering:China's eastern manufacturing corridor is pulling capacity expansion for display and lighting substrate applications requiring moisture-resistant optical polymers.
- Medical device sterilization compatibility:Steam and gamma-stable transparent polyamide grades are penetrating surgical instrument housings and drug delivery components.
Market Restraints
- Laurolactam supply concentration:PA 12 precursor availability depends on a narrow supplier base concentrated in Western Europe, exposing compounders to feedstock disruption risk.
- Per-fluoroalkyl substance restrictions:Evolving EPA and ECHA limits on PFAS-based process additives are forcing reformulation of wear-resistant grades without performance degradation.
- Polycarbonate cost competition:Lower-priced optical-grade PC from Asian producers constrains transparent polyamide penetration in cost-sensitive consumer electronics bezels.
Strategic Opportunities
- Aerospace interior panel certification:FAA flammability-compliant transparent polyamide sheet is displacing thermoset composites in cabin lighting and partition applications.
- Closed-loop recycling mandates:EU Green Deal circularity requirements are creating first-mover advantage for compounders developing chemically recyclable amorphous PA grades.
- Optical fiber buffer coating substitution:Low-haze PA 12 is penetrating telecommunications cable sheathing as legacy materials face hydrolytic degradation limits.
Industry Challenges
- Specialized polymer engineering scarcity:Formulation expertise for high-heat, high-clarity compounds concentrates at legacy European and Japanese resin producers, constraining new entrant scale-up.
- Multi-jurisdiction certification complexity:Simultaneous FDA food-contact, ECHA REACH, and China GB qualification for film grades extends product launch timelines by 12-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Polyamides Market |
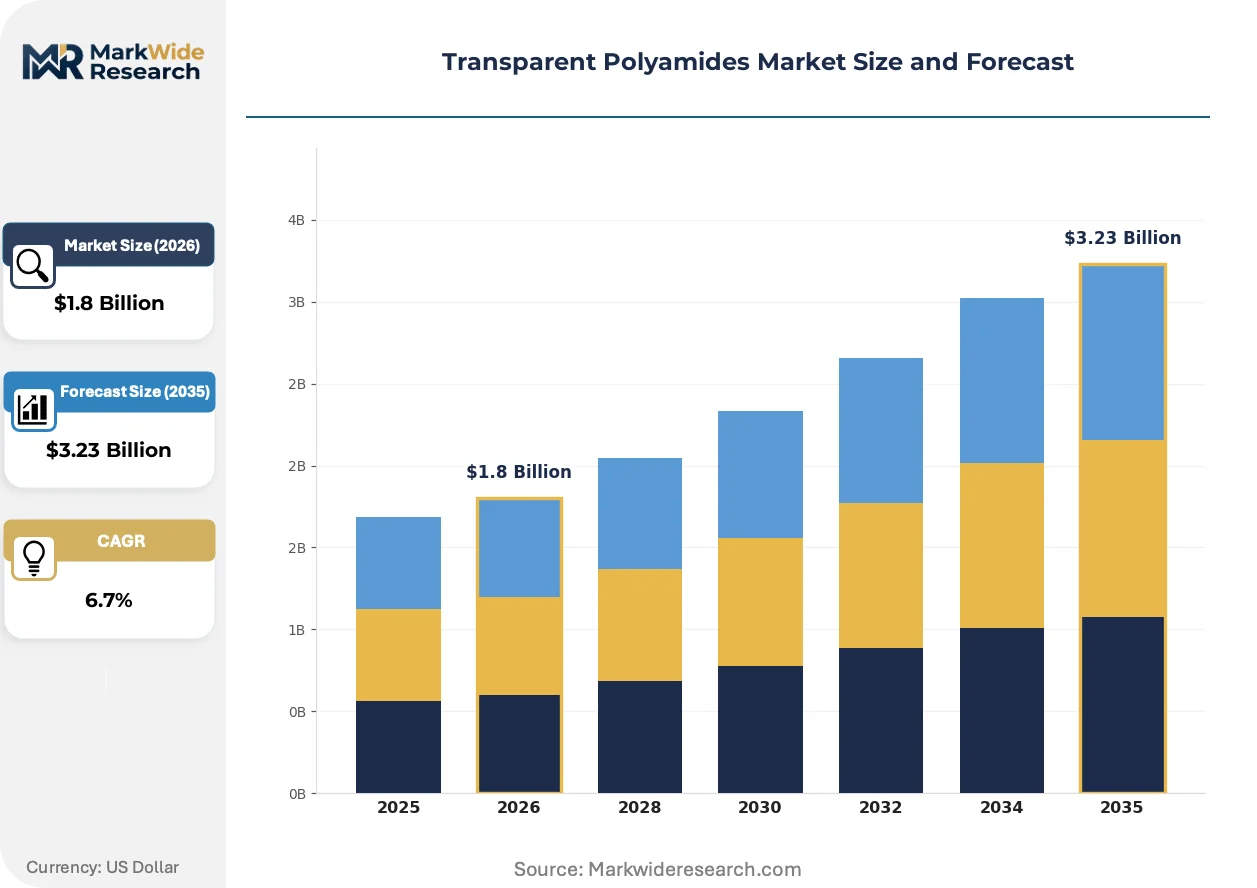
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 12, PA 610 Application: Automotive Components, Packaging Films, Electrical Insulation, Consumer Goods End Use Industry: Automotive, Electronics, Aerospace, Industrial Form: Film, Sheet, Rod, Granule |
| Companies Covered | Evonik Industries AG, BASF SE, Arkema, Domo Chemicals, SYMTAKE CHEMICAL CO. LTD., Dongguan Shengwen New Materials Co., Ltd, Everlight Chemical Industrial Corp., Changyu Holding Group Co., Ltd, Manlon Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Polyamides Market Strategic Shifts
Transparent polyamide technology trajectories center on molecular architecture refinement, regulatory-driven additive substitution, and supply chain proximity realignment as compounders respond to compressed automotive qualification windows.
Amorphous polyamide formulations with cycloaliphatic repeat units are displacing semi-crystalline grades in precision optical applications requiring isotropic shrinkage. German and Japanese automotive Tier-1 suppliers are adopting these materials for complex headlamp lenses with undercut geometries. The shift is compressing tolerance stacks and enabling integrated LED thermal management functions previously requiring metal heat sinks.
ECHA's evolving PFAS restriction proposals are forcing additive package redesigns across European compounding operations. Process aids and anti-wear modifiers containing fluorinated chemistries face phase-out timelines, compelling suppliers to validate bio-based lubricity enhancers. Medical and optical grade producers in Germany and Switzerland are most exposed, with reformulation costs concentrated in high-margin specialty segments.
Compounders are consolidating regional technical service capabilities within 500 kilometers of major automotive assembly clusters. Japanese producers are embedding application development labs in southern Germany to support BMW and Mercedes-Benz lightweighting programs. This proximity model replaces centralized European R&D with distributed formulation support, compressing prototype iteration cycles from six weeks to ten days for fuel system component trials.
Transparent Polyamides Market Segmentation
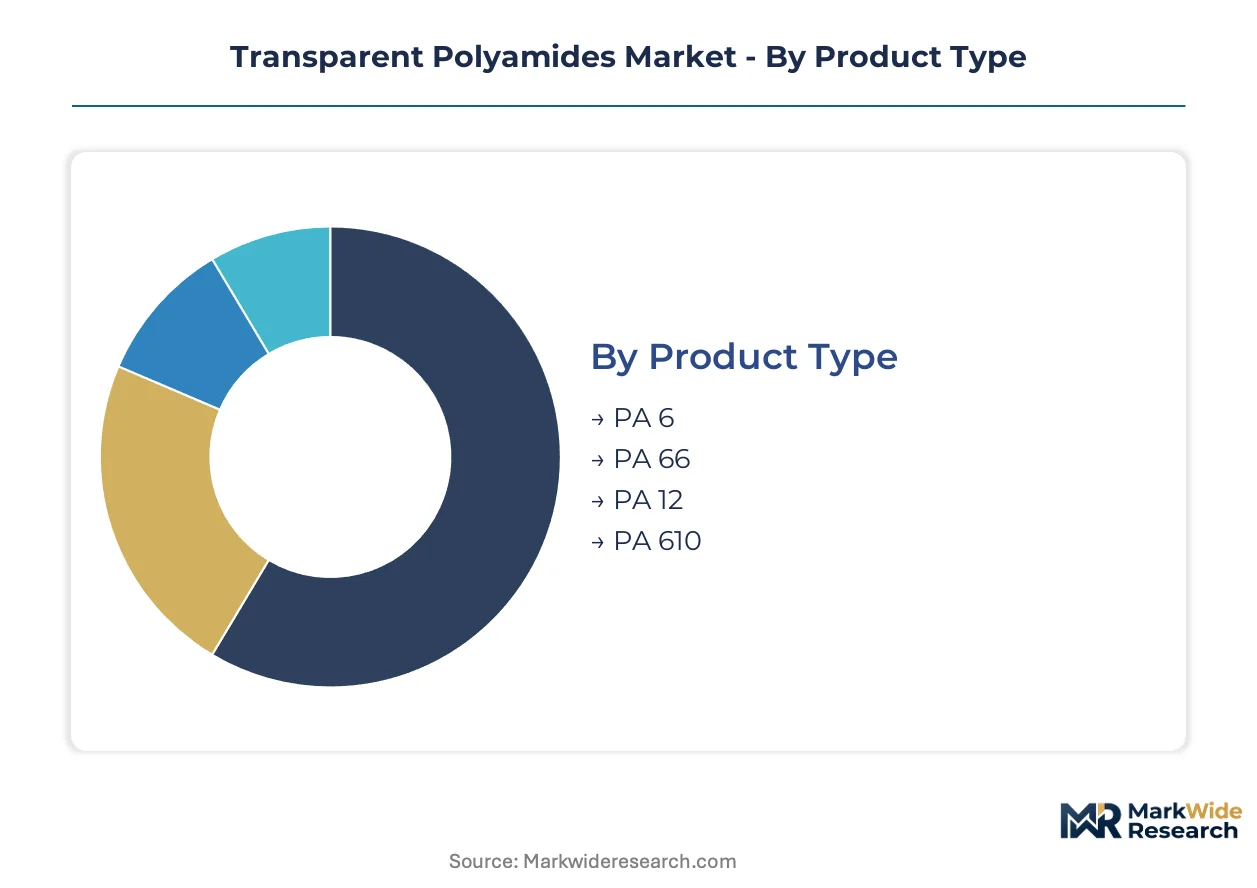
Transparent polyamide segmentation reveals divergent supply chain configurations across polymer chemistry, physical form, and end-use qualification tiers. Compounders route high-purity grades through certified automotive channels while commodity forms flow into packaging and industrial distribution networks.
Product Type:
PA 12 and PA 6 dominate differentiated distribution channels, with medical-grade PA 12 commanding dedicated cold-chain logistics and automotive PA 6 flowing through high-volume toll compounders.
- PA 12:Semi-crystalline aliphatic polyamide with the lowest moisture absorption among commercial grades, manufactured via laurolactam ring-opening polymerization. Demand clusters in German automotive headlamp lenses and Swiss medical device housings where dimensional stability under humid sterilization cycles is mandatory. REACH registration requirements for monomer purity have compressed European supplier qualification timelines.
- PA 6:Caprolactam-based polymer offering cost-positioned optical clarity with moderate moisture sensitivity. Japanese and German fuel system component manufacturers favor this chemistry for cost-sensitive transparent housing applications where slight haze tolerance exists alongside chemical resistance mandates.
- PA 66:Hexamethylenediamine-adipic acid condensation polymer with elevated heat deflection temperature for under-hood optical applications.
- PA 610:Bio-based sebacic acid-derived grade targeting sustainability-certified packaging films and consumer goods.
By volume, PA 6 leads through automotive and industrial scale. By growth pace, PA 12 is expanding most quickly on medical and optical grade premiums.
Application:
Application-driven segmentation separates automotive qualification-intensive components from fast-cycling packaging and electronics insert molding.
- Automotive Components:Headlamp lenses, fuel system sight glasses, and interior trim panels requiring simultaneous optical clarity, chemical resistance to hydrocarbons, and thermal stability for LED-adjacent heat zones. German KBA type-approval and Japanese Ministry of Land, Infrastructure, Transport and Tourism certification compress supplier selection to pre-qualified compounders with established crash-test documentation.
- Packaging Films:Thermoformed trays and lidding films for medical devices and premium food applications where gamma or steam sterilization compatibility replaces polycarbonate and PET. FDA 21 CFR compliance and EU food-contact migration limits constrain additive package selection.
- Electrical Insulation:Transparent wire jacketing and connector housings for high-voltage EV architectures requiring tracking resistance and flame retardancy.
- Consumer Goods:Eyewear frames, watch crystals, and premium cosmetic packaging where aesthetics and scratch resistance command formulation premiums.
Automotive Components generates the largest revenue pool. Packaging Films is gaining share fastest on medical sterilization substitution trends.
End Use Industry:
Industry verticals segment by certification burden and specification stability, with aerospace and medical demanding locked formulations versus automotive's iterative lightweighting cycles.
- Automotive:Dominant volume sink for transparent polyamide compounds, spanning exterior lighting, fuel systems, and interior panels. German and Japanese OEM lightweighting mandates are accelerating PA 12 and amorphous PA adoption in metal-replacement applications.
- Electronics:Display substrates, LED light guides, and connector housings requiring isotropic shrinkage for precision assembly. China's eastern manufacturing corridor concentrates demand for moisture-resistant optical grades in smartphone and tablet applications.
- Aerospace:Cabin interior panels and lighting lenses requiring FAA flammability compliance (FAR 25.853) and smoke density certification. Amorphous polyamide sheet is displacing thermoset composites in partition applications.
- Industrial:Sight glasses, flow indicators, and protective covers for chemical processing equipment where solvent resistance and impact strength outweigh optical perfection requirements.
Automotive absorbs the highest tonnage. Electronics is climbing the fastest on display miniaturization and 5G infrastructure buildout.
Form:
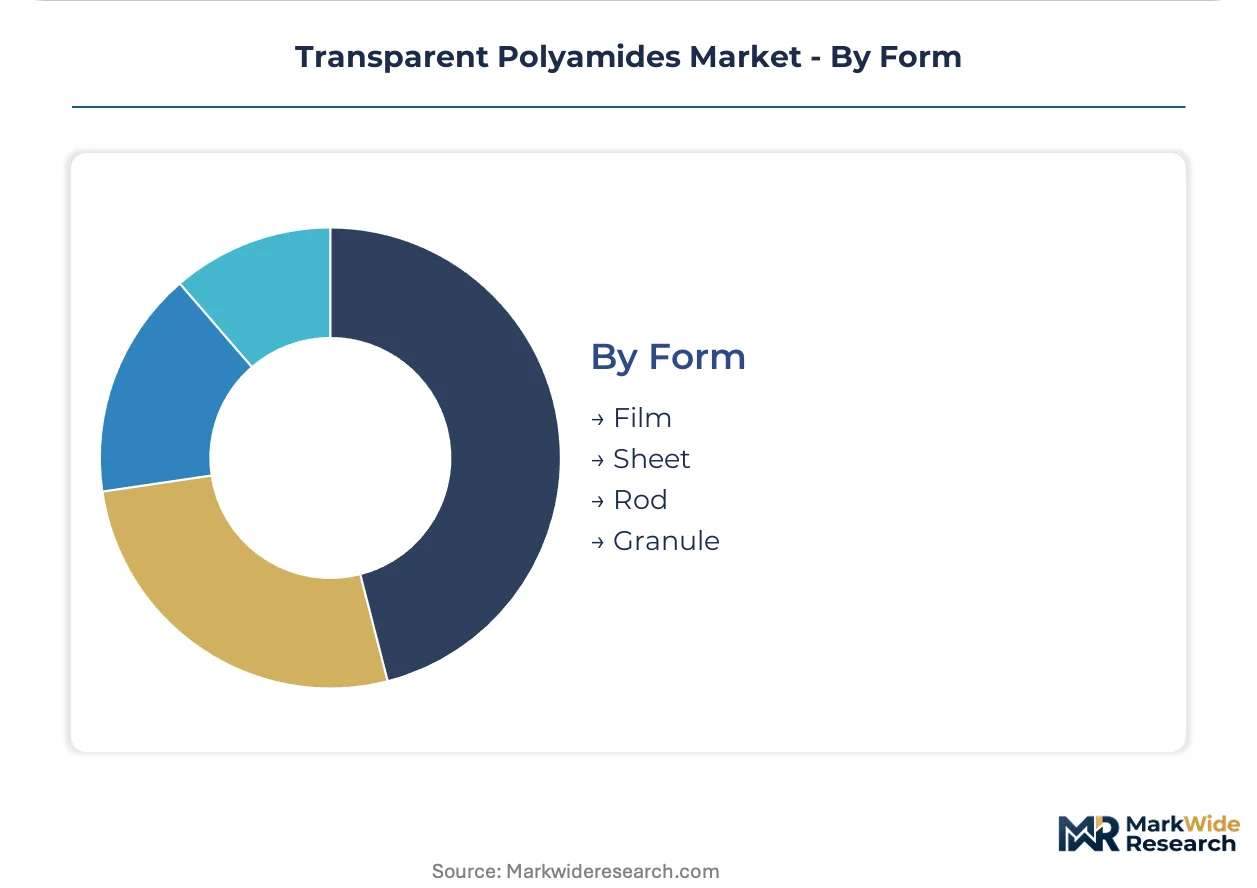
Physical form determines processing route and customer intimacy requirements, with granule commanding compounder relationships and sheet demanding fabrication partnerships.
- Granule:Dominant form factor for melt-compounding flexibility, enabling custom color and additive packages tailored to automotive and electronics specifications. Compounders in Germany, Japan, and China's eastern corridor maintain inventory positions for just-in-time delivery to Tier-1 injection molders.
- Film:Extruded sheet and roll stock for thermoforming and die-cutting operations in medical packaging and consumer goods. PA 12 film grades with controlled crystallinity serve Swiss and German medical device manufacturers requiring deep-draw forming without stress whitening.
- Sheet:Thick-gauge thermoplastic panels for aerospace interior applications and architectural lighting. CNC fabrication and thermoforming partnerships differentiate suppliers beyond resin performance.
- Rod:Machining stock for prototype development and low-volume precision components in industrial and research applications.
Granule leads by volume through automotive and electronics compounding. Sheet is expanding most rapidly on aerospace interior certification wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA registration requirements for monomer purity anchor European demand, while automotive lightweighting mandates in Germany and Japan compress supplier qualification timelines. China's eastern manufacturing corridor concentrates electronics-grade capacity expansion.
Germany
KBA type-approval for headlamp lenses and fuel system components pulls transparent polyamide compounds into BMW and Mercedes-Benz supply chains. REACH compliance deadlines accelerate compounder investment in high-clarity PA 12 production lines. The Ludwigshafen chemical cluster anchors integrated caprolactam-to-polymer operations serving automotive Tier-1 suppliers.
China
MIIT material directives shape domestic qualification protocols for display and lighting substrate applications. GB standards constrain additive package selection for food-contact film grades. The Yangtze River Delta manufacturing corridor concentrates capacity scaling for electronics-grade PA 12 serving smartphone and tablet producers.
Japan
Ministry of Land, Infrastructure, Transport and Tourism certification requirements compress supplier selection for automotive lighting components. METI industrial policy supports lightweighting substitution programs. The Nagoya automotive cluster drives demand for moisture-resistant optical polymers in precision headlamp assemblies.
United States
EPA evolving standards tighten specifications for chemical resistance in fuel system applications. FDA 21 CFR compliance constrains migration limits for medical packaging film grades. The Southeast automotive manufacturing belt concentrates injection molding operations for transparent polyamide fuel system components.
Switzerland
Swissmedic medical device regulations mandate steam and gamma sterilization compatibility for surgical instrument housings. Precision manufacturing standards elevate formulation requirements for optical clarity. The Basel pharmaceutical cluster drives demand for dimensionally stable transparent polyamide grades in drug delivery components.
Transparent Polyamides Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in transparent polyamide supply. European resin producers with captive laurolactam supply anchor the upper tier, while Asian compounders scale regional technical service capabilities. Strategic archetypes include integrated monomer-to-polymer operators, specialty amorphous formulators, and regional toll compounders. Dominant competitive moves encompass distributed application development labs near automotive assembly clusters and reformulation investments addressing PFAS additive restrictions.
Within the integrated chemistry tier, Evonik Industries AG and BASF SE exemplify European leadership through upstream control over critical feedstocks. Arkema occupies a position among specialty amorphous polyamide developers targeting electronics and consumer aesthetics. Among Asia-based specialists, SYMTAKE CHEMICAL CO. LTD. and Dongguan Shengwen New Materials Co., Ltd represent regional compounders scaling capacity for electronics-grade formulations.
| Leading Market Players |
|---|
| Evonik Industries AG |
| BASF SE |
| Arkema |
| Domo Chemicals |
| SYMTAKE CHEMICAL CO. LTD. |
| Dongguan Shengwen New Materials Co., Ltd |
| Everlight Chemical Industrial Corp. |
| Changyu Holding Group Co., Ltd |
| Manlon Polymers |
| Others |
Value Chain & Pricing Dynamics
Scale economies in laurolactam polymerization anchor European producers' cost positions while compressing price floors for Asian compounders lacking captive feedstock. German and Swiss resin producers leverage integrated caprolactam-to-polymer operations to sustain premium positioning against Chinese toll compounders serving electronics-grade spot demand.
Pricing Analysis
Geographic price spreads between Western European medical-grade PA 12 and Chinese electronics-grade compounds exceed transportation-cost differentials alone. Three-tier pricing structure across premium, standard, and economy levels separates Swiss sterilization-certified grades from German automotive-qualified intermediates and Asian commodity film resins. Cost compression in standard-tier PA 6 is intensifying because polycarbonate substitution threats constrain pricing power in consumer electronics bezels. Packaging film buyers exhibit highest price sensitivity due to polycarbonate and PET alternatives, while surgical instrument manufacturers accept premium positioning for dimensional stability under gamma sterilization.
Supply Chain Analysis
Inventory strategy bifurcates between German automotive Tier-1 just-in-time compounding and Chinese electronics distributors holding strategic PA 12 stockpiles against laurolactam disruption. Supply concentrates in Germany, China, and Japan, with European resin producers drawing from captive laurolactam at Ludwigshafen and Asian compounders sourcing from spot markets. Raw material dependencies center on laurolactam monomer, caprolactam feedstock, and cycloaliphatic diamines for amorphous grades. Single-source vulnerability in Western European laurolactam exposes compounders to force majeure disruption. Distribution runs through certified automotive channels for granule compounds and fabrication partnerships for aerospace sheet applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent polyamide incumbents face a substitution defense against polycarbonate cost erosion in consumer electronics and optical applications. Incumbents must navigate polycarbonate price competition while preserving premium positioning in medical and automotive qualification-intensive segments.
For Market Incumbents: Shield medical-grade margin pools through Swissmedic and FDA sterilization certification investments that polycarbonate cannot replicate. Deepen backward integration into laurolactam or secure long-term offtake agreements with European monomer producers to defend against feedstock disruption. Prioritize amorphous polyamide R&D for headlamp lens thermal management functions that commodity polycarbonate fails to deliver.
For New Entrants and Emerging Players: Lead with aerospace interior panel certification as the most penetrable segment, where FAA flammability compliance creates qualification barriers legacy polycarbonate suppliers struggle to clear. Target China's Yangtze River Delta electronics corridor for moisture-resistant optical grade toll compounding partnerships. Establish distributed application development labs within 500 kilometers of BMW and Mercedes-Benz assembly clusters to compress prototype iteration cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated European resin producers with captive laurolactam supply and locked automotive qualification protocols. Long-term viability over the analysis window favors compounders with demonstrated multi-jurisdiction certification track records spanning FDA, ECHA REACH, and China GB standards. Watch for ECHA PFAS restriction implementation as the inflection indicator forcing additive package reformulation investments that favor incumbents with R&D scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laurolactam | Captive monomer supply insulates German producers from feedstock disruption risk. |
| Amorphous Polyamide R&D Expansion | Cycloaliphatic formulations enable complex headlamp geometries with isotropic shrinkage. |
| PFAS Additive Reformulation | ECHA restriction compliance preserves European medical-grade market access. |
| Distributed Application Labs | Proximity to BMW and Mercedes-Benz clusters compresses fuel system prototype cycles. |
| Aerospace Interior Certification | FAA FAR 25.853 compliance displaces thermoset composites in cabin partitions. |
Study Parameters
A standing panel of polymer plant managers, automotive Tier-1 procurement leads, medical device R&D directors, and distribution channel partners provided ongoing calibration across primary fieldwork. Secondary validation drew from ECHA REACH registration databases, FDA 21 CFR food-contact filings, German KBA type-approval records, and customs trade data tracking laurolactam and caprolactam flows. Bottom-up volume builds by grade and application triangulated against top-down demand estimates from automotive production databases and electronics shipment records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled transparent polyamide demand by polymer chemistry, end-use industry vertical, physical form factor, and regional production hub. CAGRs derived from segment-level growth drivers including automotive lightweighting mandates, electronics miniaturization trends, and medical sterilization substitution patterns. Forecast inputs incorporated REACH compliance timelines, PFAS restriction evolution, and aerospace certification pipeline visibility.
Underlying assumptions cover sustained automotive LED headlamp adoption, stable laurolactam supply from Western European producers, and continued polycarbonate price competition in consumer electronics, with deviation risk concentrated in ECHA regulatory acceleration or China MIIT directive shifts. Revision becomes warranted when PFAS restriction implementation timelines accelerate beyond modeled baselines or when aerospace interior certification wins fail to materialize at projected conversion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market