
 Saudi Arabia Aluminum Market | 2026-2036
Saudi Arabia Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Aluminum Market Insights
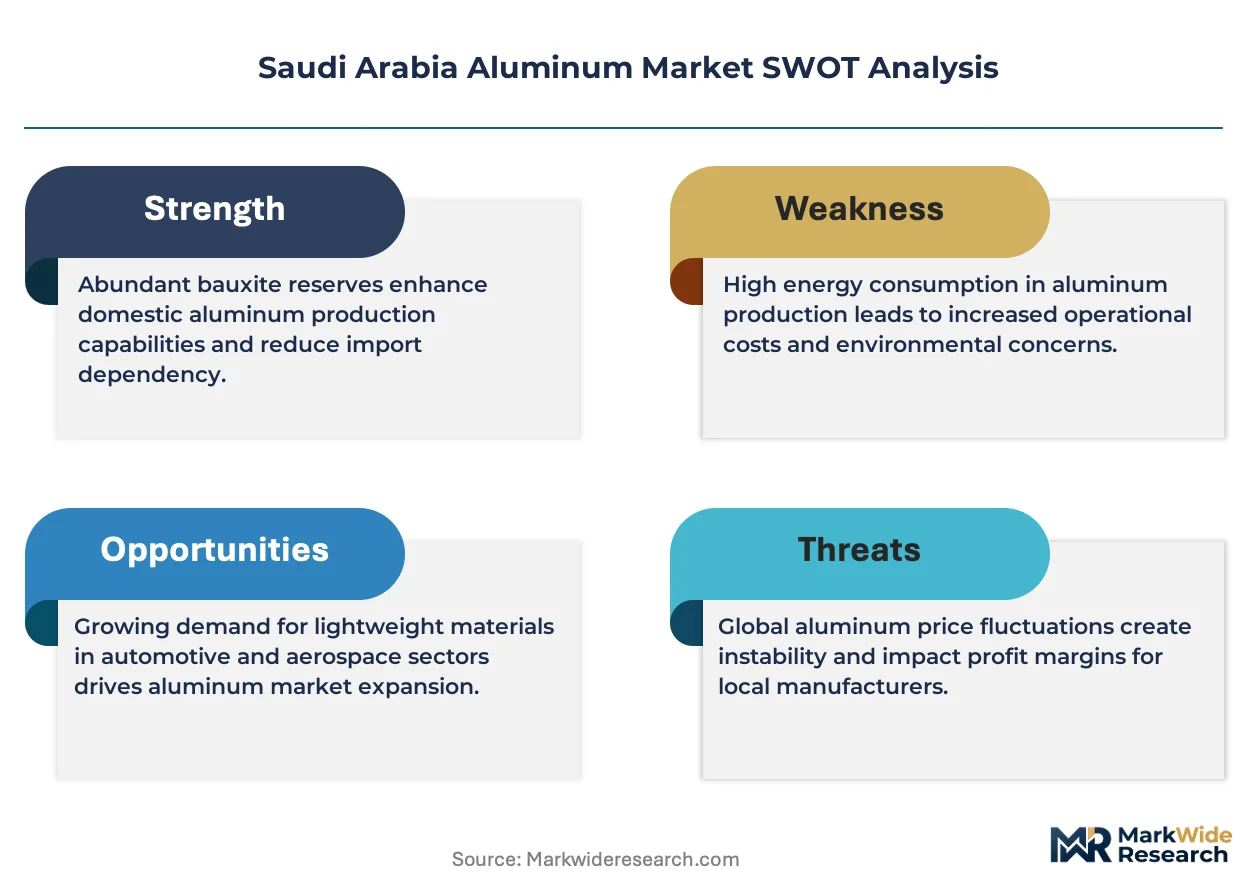
SFDA material certification protocols is shifting the cost-of-entry calculus for new aluminum suppliers entering Saudi downstream markets. Maaden anchors the upstream segment through its Ras Al Khair smelter complex, the largest in the Middle East. Alupco dominates extruded product supply for domestic construction, while Alcoa Corporation extends its technology leadership through long-term offtake partnerships with Saudi industrial developers.
Aluminum is a lightweight, corrosion-resistant metal with density of 2.7 g/cm³, extracted from bauxite through the Bayer process and smelted via Hall-Héroult electrolysis, serving primarily as a structural substitute for steel in weight-critical applications. Flat rolled products occupy the largest volume share, driven by cladding and automotive sheet demand, while extrusions capture premium margins from architectural systems specified in Gulf Cooperation Council building codes. Billets and ingots function as feedstock intermediates, with ingot trade flowing heavily through Jeddah Islamic Port.
SFDA enforces product safety standards for aluminum in food-contact packaging, while the Saudi Standards, Metrology and Quality Organization governs structural alloy grades under SASO building material regulations. The Saudi Building Code mandates specific aluminum alloy series for curtain wall applications, creating compliance-driven specification power for certified mills. Stakeholders must monitor how dual carbon goals and renewable energy mandates reshape smelter power sourcing economics in the Kingdom.
Market Dynamics
Vision 2030 construction megaprojects are compressing procurement cycles for structural aluminum systems, forcing fabricators to pre-certify alloys before tender submission rather than post-award qualification.
Growth Catalysts
- Ras Al Khair smelter capacity expansion:Maaden's upstream investment guarantees domestic ingot supply security, reducing import dependency for downstream extruders serving Riyadh-Jeddah corridor projects.
- Saudi Building Code curtain wall mandates:Specific alloy series requirements for high-rise facades are locking certified mills into multi-year supply agreements with tier-one developers.
- SFDA food-contact certification:Packaging-grade aluminum sheet demand from dairy and beverage processors is accelerating as import substitution policies favor locally certified converters.
Market Restraints
- Smelter power cost volatility:Aluminum production electricity intensity ties margin stability to Saudi Electricity Company industrial tariff adjustments and renewable transition timelines.
- Jeddah Islamic Port ingot concentration:Bulk raw material import dependency through a single maritime gateway creates congestion risk during peak construction seasons.
- Scrap collection infrastructure gaps:Secondary aluminum feedstock availability lags fabrication demand, forcing reliance on primary metal despite circular economy targets.
Strategic Opportunities
- NEOM linear city specifications:The giga-project's modular construction methodology favors prefabricated aluminum facade systems over conventional on-site assembly.
- Electric vehicle battery enclosure demand:Automotive OEM localization under the National Industrial Development Center incentives creates a new extrusion application vertical.
- SASO green building certification:Recycled content thresholds in the Saudi Green Building Forum rating system advantage domestic secondary smelters with verified scrap sourcing.
Industry Challenges
- Welding technician certification bottlenecks:SASO-compliant structural welding qualifications for 6000-series alloys require 18-month training cycles that outpace project staffing needs.
- Dual carbon compliance documentation:Smelters must reconcile Saudi Energy Efficiency Center mandates with buyer Scope 3 reporting requirements, multiplying audit overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Aluminum Market |
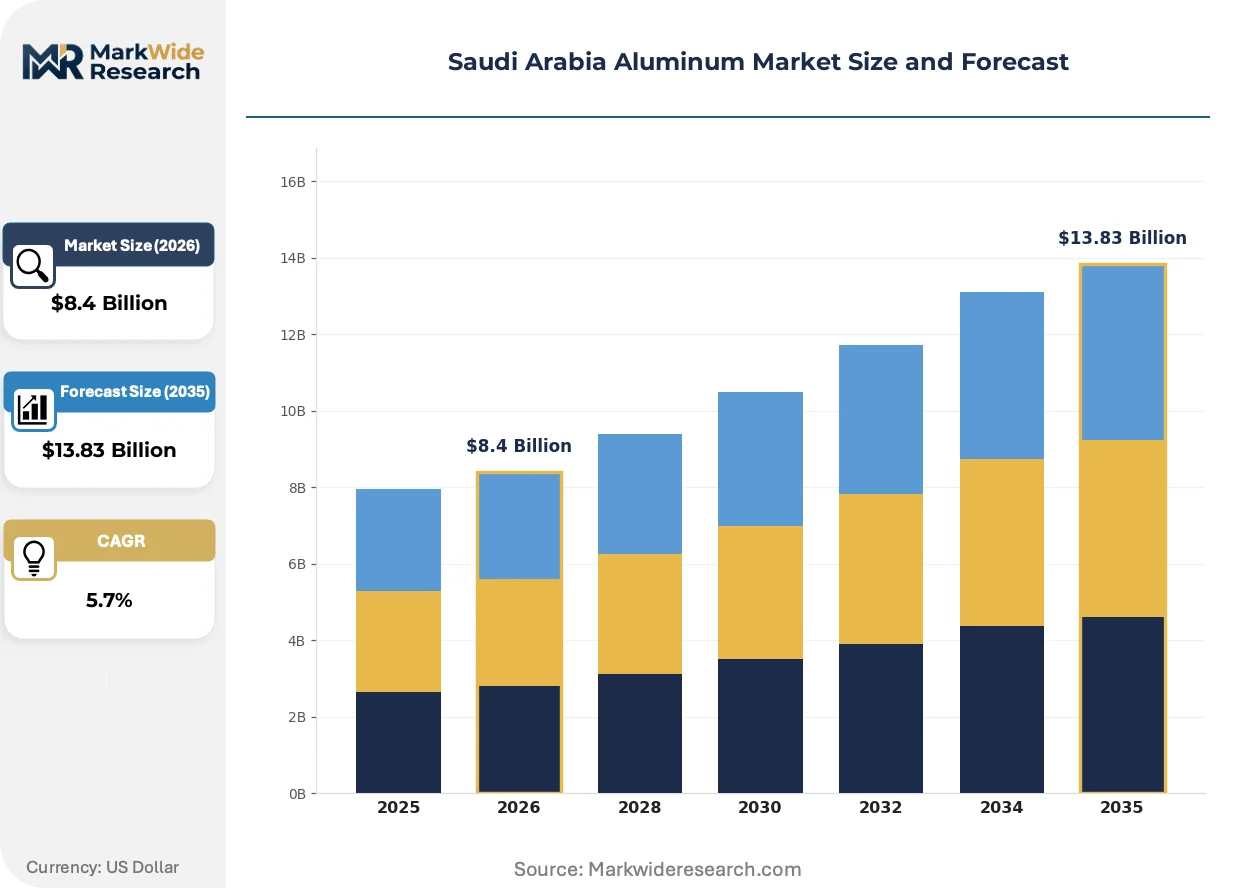
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Rolled, Extrusions, Billets, Ingots Application: Construction, Transportation, Packaging, Aerospace End User: Manufacturing, Automotive, Utilities, Building Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Al Taiseer Group (TALCO), Al-Jazirah Aluminium (Alumjaz), Maaden (Saudi Arabian Mining Company), Nesma Recycling Co. Ltd., Al-Esra Aluminium, Aluminium Products Company (Alupco), ALINCO (Aluminium International Co.), Eastern Aluminum Extrusion Factory, Alcoa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Aluminum Market Trends and Innovations
Digital alloy traceability and low-carbon smelting technologies are restructuring how Saudi fabricators qualify for premium project tiers, separating certified suppliers from commodity traders.
Pre-engineered building envelope systems are modularizing facade procurement for Vision 2030 giga-projects. Developers are specifying unitized curtain wall modules rather than stick-built alternatives, compressing on-site installation schedules by 60 percent. This shift is modularizing the traditional split between aluminum extruders and glazing subcontractors into integrated envelope specialists.
SFDA has tightened migration testing protocols for aluminum food-contact surfaces, requiring third-party laboratory certification for every alloy batch. The Saudi Food and Drug Authority's updated technical regulations are disqualifying uncertified Asian suppliers from institutional catering contracts. Dairy processors in Al Kharj and Qassim regions are now demanding mill-test certificates with full chemical composition traceability.
Buyers are consolidating specification authority at the developer level rather than delegating to general contractors. Large-scale project owners in Riyadh are pre-approving aluminum alloy grades and finishe suppliers before main contract award, compressing downstream substitution flexibility. This concentration is most visible in the Red Sea coastal tourism developments where envelope performance guarantees now sit with asset operators rather than construction managers.
Saudi Arabia Aluminum Market Segmentation
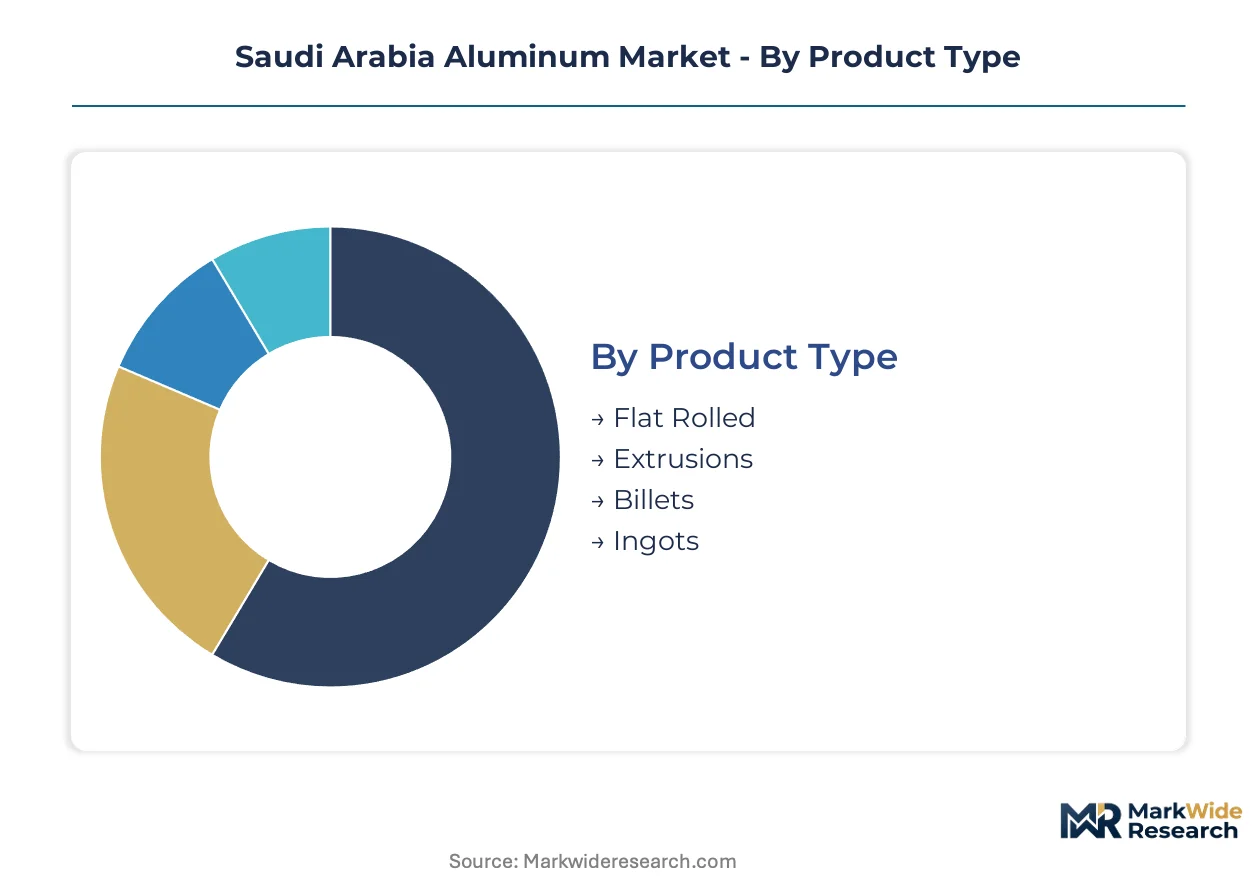
Structural aluminum procurement in the Kingdom diverges sharply across product forms and end-use specifications. SFDA certification requirements and Saudi Building Code mandates create non-interchangeable demand pools that reshape how suppliers configure their alloy portfolios.
Product Type:
Maaden's Ras Al Khair complex anchors supply concentration for primary forms, while downstream fabrication clusters in Riyadh and Jeddah determine conversion economics for finished products.
- Flat Rolled:Continuous cast and hot-rolled sheet products serve cladding, automotive body panels, and food-contact packaging applications. Demand concentrates in Jeddah's industrial corridor where dairy processors and beverage canners operate under SFDA migration testing protocols that disqualify uncertified imports.
- Extrusions:Pressed 6000-series profiles deliver structural geometries for curtain walls, window systems, and transportation framing. Riyadh's giga-project developments lock certified extruders into pre-approval frameworks before tender submission, compressing substitution flexibility.
- Billets:Cast cylindrical feedstock for downstream extrusion presses.
- Ingots:Primary metal pigs flowing through Jeddah Islamic Port for remelt operations.
Flat rolled absorbs the bulk of installed capacity; extrusions is expanding most quickly.
Application:
Vision 2030 construction timelines compress procurement cycles differently across end-use verticals, with envelope systems facing the most severe pre-certification deadlines.
- Construction:Structural systems, curtain walls, roofing, and interior fit-out applications dominate volume consumption. NEOM and Red Sea Project specifications favor unitized facade modules over stick-built alternatives, consolidating demand with integrated envelope specialists.
- Transportation:Weight-critical chassis, rail rolling stock, and emerging electric vehicle battery enclosures. The National Industrial Development Center's automotive localization incentives are pulling extrusion capacity toward EV-specific alloy development.
- Packaging:Beverage cans, foil laminates, and institutional food containers.
- Aerospace:High-strength 7000-series and 2000-series alloys for airframe components.
Construction commands the dominant share of qualified supplier relationships; transportation is climbing the fastest as OEM localization accelerates.
End User:
Specification authority consolidation at the developer level fragments traditional channel structures, with asset operators now controlling alloy pre-approval rather than general contractors.
- Building:Commercial developers, hospitality operators, and residential project owners in Riyadh and Jeddah. Pre-approval frameworks mandate mill-test certificates with full chemical traceability before main contract award.
- Automotive:Assembling OEMs and tier-one component suppliers localizing under industrial incentive programs. Battery enclosure specifications create new demand for crash-worthy extrusion profiles.
- Manufacturing:Industrial equipment fabricators and consumer goods producers.
- Utilities:Power transmission infrastructure and renewable energy mounting systems.
Building sector procurement absorbs the deepest certification overhead; automotive is gaining share fastest as EV supply chains localize.
Distribution Channel:
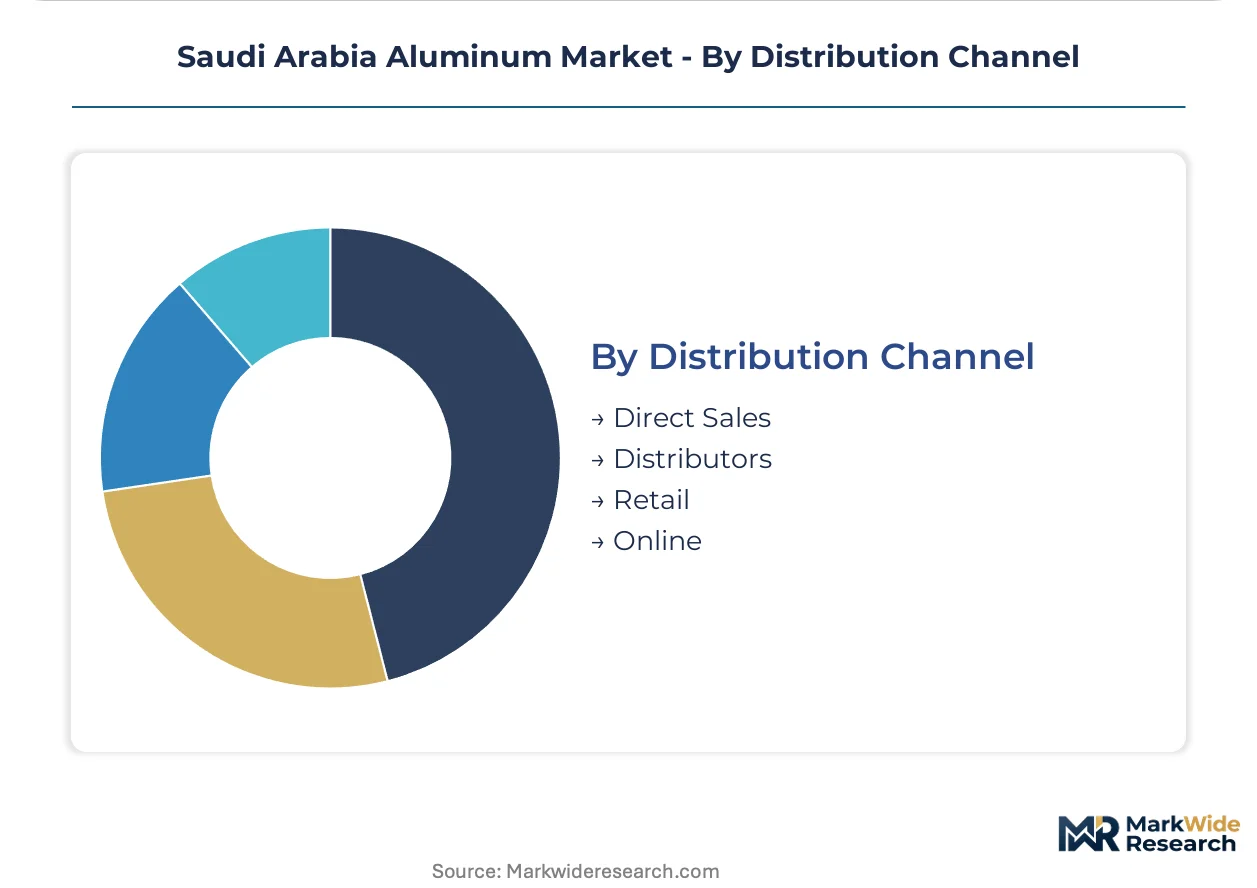
Project scale and certification complexity drive channel bifurcation, with giga-projects bypassing traditional distributors entirely while smaller fabricators remain dependent on stocked intermediaries.
- Direct Sales:Mill-direct contracts for tier-one developers and industrial accounts. Maaden and major extruders maintain dedicated commercial teams for NEOM, Red Sea Project, and Qiddiya developments.
- Distributors:Stocking intermediaries serving uncertified fabricators and maintenance-repair operations. Jeddah-based metal service centers hold imported ingot and standard extrusion inventories.
- Retail:Small-volume sales to independent workshops and residential contractors.
- Online:Digital quotation platforms for standard alloy grades and catalog extrusions.
Direct sales captures the highest-value project flows; distributor relationships face margin compression as pre-approval requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction megaprojects under Vision 2030 concentrate aluminum procurement in the Riyadh-Jeddah corridor, where smelter capacity and fabrication clusters overlap. The Kingdom's regional demand patterns diverge sharply across four economic zones.
Riyadh
Qiddiya and Diriyah giga-projects absorb high-performance extrusion profiles for entertainment and heritage developments. The Saudi Building Code mandates 6000-series alloy certification for all curtain wall applications above four stories. Riyadh-based fabricators maintain pre-approval frameworks with tier-one developers before tender submission.
Eastern Province
Ras Al Khair anchors the Kingdom's primary aluminum production through Maaden's smelter complex, the largest in the Middle East. Industrial demand from Jubail's petrochemical sector drives specialty alloy consumption for corrosion-resistant equipment. The Energy Efficiency Center mandates dual carbon compliance documentation for smelter power sourcing.
Western Region
Jeddah Islamic Port handles bulk ingot imports for remelt operations serving Makkah construction and Red Sea coastal tourism. SFDA food-contact certification requirements disqualify uncertified Asian suppliers from dairy and beverage packaging contracts. Jeddah-based metal service centers hold standard extrusion inventories for uncertified fabricators.
NEOM Northwest
The linear city's modular construction methodology favors prefabricated aluminum facade systems over conventional on-site assembly. Developer-level specification authority consolidates alloy pre-approval before main contract award. NEOM's envelope performance guarantees sit with asset operators rather than construction managers.
Saudi Arabia Aluminum Market Competitive Landscape
Saudi producers anchor the upstream tier; international specialists hold technology and offtake positions. The market structures around Maaden's smelter dominance and a fragmented downstream fabrication base. Three archetypes define competitive positioning: integrated mining-smelting operators, certified extrusion specialists, and trading intermediaries serving uncertified demand. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Within the integrated operator tier, Maaden anchors primary metal supply security for the Kingdom's downstream extruders. Among certified fabrication specialists, Alupco occupies a position exemplifying pre-approved supplier frameworks for giga-project developers. Alcoa Corporation sits within the technology-licensing tier, extending process expertise through long-term offtake arrangements with Saudi industrial developers.
| Leading Market Players |
|---|
| Al Taiseer Group (TALCO) |
| Al-Jazirah Aluminium (Alumjaz) |
| Maaden (Saudi Arabian Mining Company) |
| Nesma Recycling Co. Ltd. |
| Al-Esra Aluminium |
| Aluminium Products Company (Alupco) |
| ALINCO (Aluminium International Co.) |
| Eastern Aluminum Extrusion Factory |
| Alcoa Corporation |
| Others |
Pricing and Supply Chain Analysis
Pre-approval frameworks mandated by Riyadh's tier-one developers are compressing substitution flexibility and forcing supply-side certification investments that widen price spreads between certified and uncertified aluminum tiers. The Kingdom's downstream fabricators must absorb these qualification costs or exit high-value project flows entirely.
Pricing Analysis
High-volume ingot transactions run on thin margins anchored to LME benchmarks, while certified extrusion profiles for giga-project envelopes capture substantial premiums tied to SASO compliance documentation. Pricing stratifies across three tiers: mill-direct contracts for pre-approved suppliers, distributor-stocked standard grades, and spot-market imports lacking SFDA certification. Cost compression in the spot tier is intensifying because Jeddah port congestion extends working capital cycles for uncertified traders. General contractors serving smaller developments exhibit the greatest price sensitivity; asset operators at NEOM and Red Sea Project developments prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Maaden's Ras Al Khair complex, which feeds the majority of domestic primary metal requirements. The Kingdom's smelter output draws from Australian bauxite and imported alumina, with caustic soda and carbon anodes as critical process inputs. Tariff exposure on Chinese semi-finished products creates procurement uncertainty for downstream extruders lacking long-term offtake coverage. Distribution runs through mill-direct contracts for certified tier-one projects and Jeddah-based metal service centers for uncertified maintenance-repair operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics prevail as smelter capacity expansion lags giga-project absorption rates, propping pricing power for qualified suppliers. The certification bottleneck functions as the primary capacity gatekeeper.
For Market Incumbents: To counter emerging secondary smelters with verified scrap sourcing, deepen backward integration into bauxite refining and secure long-term power purchase agreements with renewable developers. Lock tier-one developers into multi-year envelope performance contracts before new entrants complete SASO qualification cycles. Prioritize welding technician training partnerships with technical institutes to resolve certification bottlenecks faster than project staffing demands. For New Entrants and Emerging Players: Capture the secondary aluminum feedstock gap by building scrap collection infrastructure in the Eastern Province industrial corridor, where fabrication demand outruns circular economy supply. Target EV battery enclosure specifications as the most penetrable automotive vertical, leveraging National Industrial Development Center incentives for localized extrusion capacity. Lead with alloy development partnerships rather than commodity ingot trading to bypass pre-approval barriers at major developments. For Investors and Strategic Acquirers: The window for entry favors integrated envelope specialists with certified facade system capabilities and established developer relationships. Long-term viability hinges on positioning for post-2030 maintenance-repair cycles when giga-project construction peaks subside. Watch for Saudi Electricity Company industrial tariff restructuring as the signal for smelter margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Smelter Power Purchase Agreement | Long-term renewable sourcing insulates Maaden from SEC tariff volatility and dual carbon compliance costs. |
| SASO Certification Investment | Third-party alloy validation unlocks pre-approval frameworks at Qiddiya and Diriyah developments. |
| Scrap Collection Infrastructure Buildout | Domestic secondary feedstock sourcing satisfies Saudi Green Building Forum recycled content thresholds. |
| EV Extrusion Alloy Development | Crash-worthy profile specifications for battery enclosures capture National Industrial Development Center incentives. |
| Unitized Facade System Integration | Modular envelope manufacturing compresses on-site installation schedules for NEOM linear city specifications. |
Research Methodology
Document review covered customs trade records, SEC filings from listed aluminum producers, and SFDA technical regulations, complemented by interviews with Maaden procurement executives, Alupco fabrication managers, and Jeddah port logistics operators. Secondary validation drew from SASO building material standards, Saudi Building Code amendments, and Saudi Electricity Company tariff disclosures. Bottom-up demand modeling triangulated against top-down smelter capacity assessments.
Value projections across the analysis window reflect segment-level absorption rates for construction, transportation, and packaging applications, with alloy grade and certification tier as cross-cutting dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating Vision 2030 project timelines and industrial localization incentives. Key inputs include smelter power cost trajectories and SFDA migration testing protocol adoption rates among food-contact converters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to renewable energy transition timelines and scrap collection infrastructure buildout pace. Forecasts reflect documented assumptions about giga-project execution schedules and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Brass Rods Market
Metals
Russia Metal Fabrication Market
Metals
Metallurgical Coal Market
Metals
Smelting Chemicals Market
Metals
Stainless Steel Round Bar Market
Metals
Global Electrolytic Copper Foil Market
Metals
Reconditioned Steel Drums Market
Metals
HSLA Steel Plate Market
Metals
Palladium Market
Metals
Copper Powder Market
Metals
Bismuth Market
Metals
Cold Drawn Wire Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Aluminum Welding Market
Metals
Nickel Powder Plating Market
Metals
TMCP Steel Market