
 Nickel Sulfate Market | 2026-2036
Nickel Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Sulfate Market Outlook
Market Context
Long-term offtake contracting is decoupling nickel sulfate pricing from traditional LME nickel benchmarks, creating a separate commercial layer for battery-grade material. GEM leverages captive cobalt-nickel recycling streams to secure feedstock outside conventional mining channels. Umicore sustains European precursor leadership through certified sustainable sourcing programs that trace material to mine origin. Sumitomo Metal Mining anchors Japanese cathode supply chains with integrated nickel refining and sulfate production at its Harima complex.
Technical Definition and Segment Structure
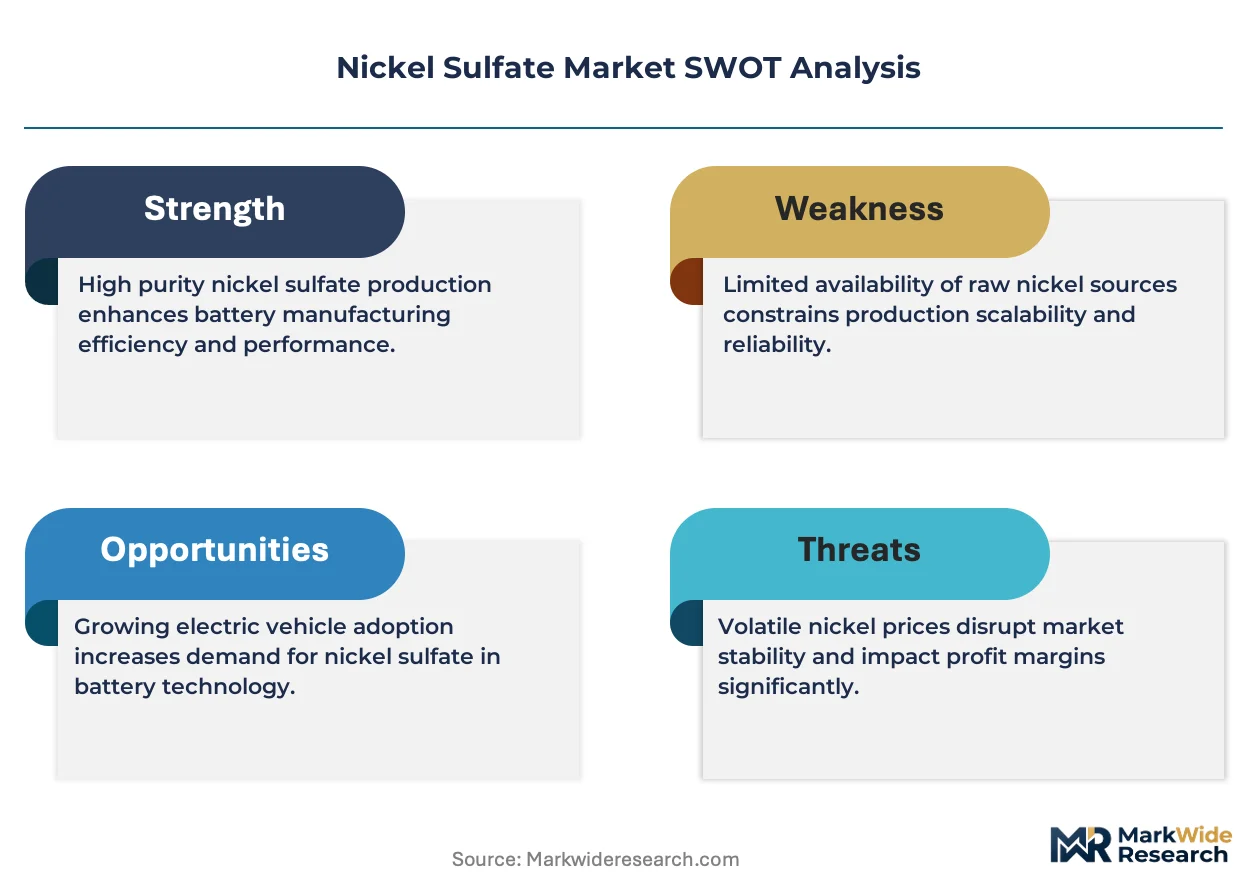
Nickel sulfate is a nickel(II) salt compound typically produced as hexahydrate crystals or concentrated aqueous solution, with battery-grade specifications requiring cobalt and copper impurities below 10 ppm for cathode precursor synthesis. The compound serves primarily as a precursor input for nickel-cobalt-manganese and nickel-cobalt-aluminum cathode active materials used in electric vehicle batteries. Electrolytic nickel sulfate commands premium positioning over crude variants due to stringent metal impurity thresholds demanded by cathode manufacturers. Powder and crystal forms dominate physical delivery, while liquid sulfate solution gains traction in vertically integrated precursor plants seeking to eliminate redissolution steps. Battery applications absorb the majority of high-purity output, with plating and electronics segments relegated to lower-specification material pools.
Regulatory Framework and Outlook
Indonesia's Ministry of Energy and Mineral Resources governs nickel ore export bans and downstream processing incentives that have redirected global sulfate supply chains toward domestic HPAL facilities. China's SAMR enforces GB standards for battery material purity, while the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that will reshape import qualification criteria. Stakeholders must monitor how Indonesia's evolving downstream rules interact with European due diligence requirements to assess which integrated producers can maintain dual-market access without parallel certification burdens.
Market Dynamics
Long-term offtake contracting is decoupling nickel sulfate pricing from traditional LME nickel benchmarks, creating a separate commercial layer for battery-grade material. This structural shift concentrates negotiating power among integrated HPAL operators and cathode manufacturers with multi-year supply agreements.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint disclosure and recycled content thresholds are accelerating qualification of certified sustainable sulfate supply chains for European cathode producers.
- High-nickel cathode chemistry:NCM 811 and NCA formulations are electrifying demand for battery-grade material with sub-10 ppm cobalt and copper impurity specifications.
- Indonesia's downstream processing corridor:Integrated HPAL-to-sulfate operations are scaling capacity to capture value-added refining within the country's nickel ore export ban framework.
Market Restraints
- Feedstock cost volatility:MHP and mixed hydroxide precipitate pricing fluctuates with Indonesian nickel ore availability and Chinese stainless steel demand cycles.
- HPAL technical complexity:High-pressure acid leach operations require precise temperature and pressure control, with ramp-up timelines extending 18-24 months for nameplate capacity achievement.
- Water and energy intensity:Sulfate crystallization and purification stages consume substantial electricity and process water, constraining site selection to regions with abundant low-cost power.
Strategic Opportunities
- Battery recycling feedstock:Black mass processing and hydrometallurgical recovery are creating circular sulfate supply outside conventional mining channels.
- Solid-state battery precursors:Sulfide-based solid electrolytes require ultra-high-purity nickel compounds with stricter impurity thresholds than current cathode specifications.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting precursor investments to Gujarat and Tamil Nadu industrial corridors.
Industry Challenges
- HPAL engineering talent scarcity:Specialized metallurgists and process engineers with high-pressure autoclave experience command premium compensation and limited geographic mobility.
- Dual certification burden:Producers must simultaneously satisfy China's GB standards and EU Battery Regulation traceability requirements, duplicating audit and documentation costs.
- Legacy plating customer erosion:Traditional electroplating sulfate buyers face displacement as battery-grade capacity absorbs available high-purity output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Sulfate Market |
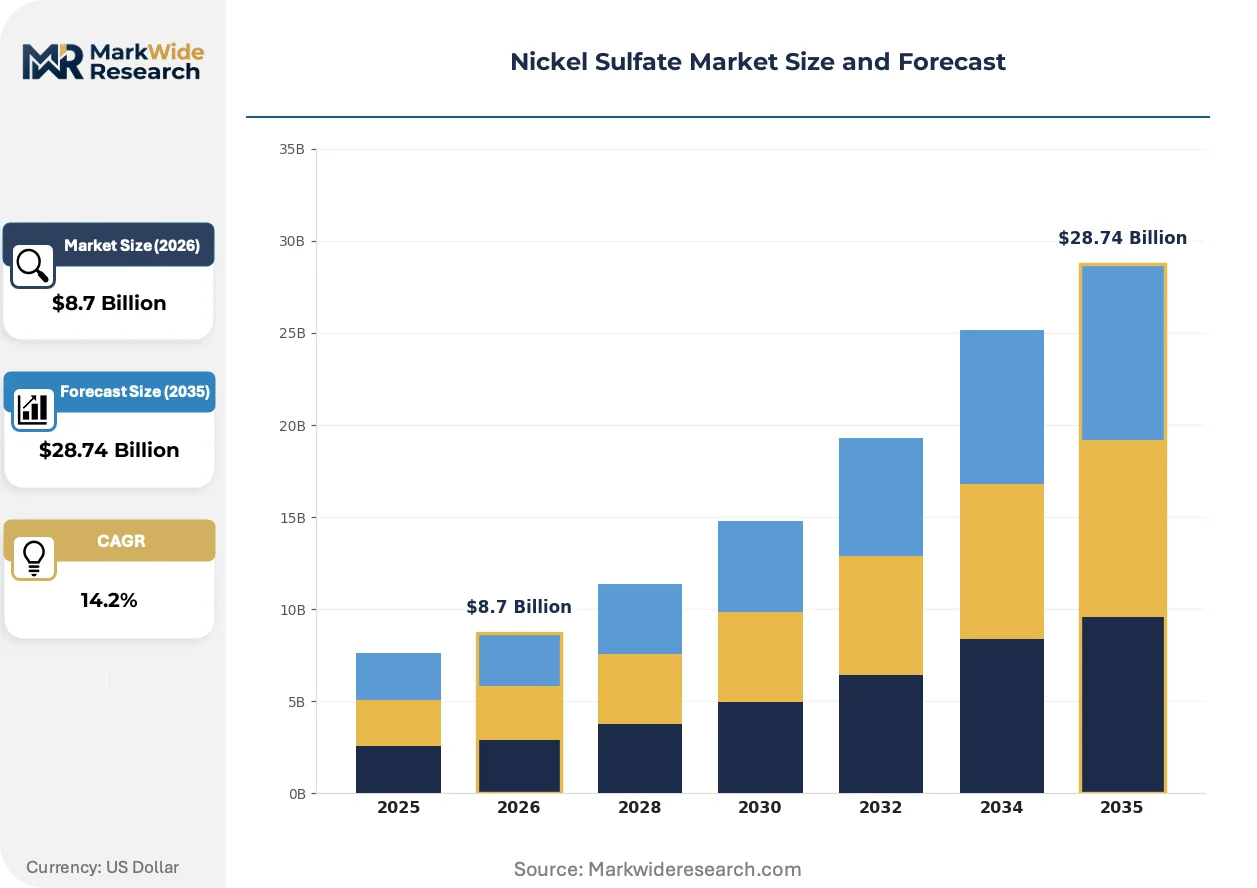
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Nickel Sulfate, Crude Nickel Sulfate, Pure Nickel Sulfate, Nickel Sulfate Solution Application: Batteries, Electronics, Plating, Catalysts Form: Granular, Powder, Liquid, Crystal End User: Aerospace, Automotive OEMs, Electronics Manufacturers, Chemical Industry |
| Companies Covered | GEM (China), Umicore, Jinchuan Group International Resources, Tsingshan Holding Group, Guangxi Yinyi, Sumitomo Metal Mining, Nickel Industries, Jindal Stainless, Norilsk Nickel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Sulfate Market Strategic Shifts
Direct solvent extraction and crystallization advances are compressing impurity removal steps while continuous flow processing is displacing batch operations in precursor manufacturing. These technical trajectories are reshaping capital deployment and operational scale requirements across the value chain.
Direct solvent extraction with synergistic extractant systems is electrifying impurity separation efficiency in integrated HPAL facilities. Cathode precursor manufacturers in South Korea and Japan are adopting these circuits to reduce reagent consumption and wastewater generation. The technology is compressing the traditional leach-precipitate-redissolve sequence into single-unit operations.
China's SAMR enforcement of revised GB/T 26008 standards for battery-grade nickel sulfate is tightening cobalt, copper, and zinc impurity ceilings. Domestic precursor producers must recertify supply chains or face exclusion from subsidized electric vehicle battery procurement programs. Indonesian integrated operators are responding by installing additional purification stages to maintain dual-market access.
Buyers are consolidating procurement through multi-year offtake agreements with integrated producers rather than spot market purchases. Cathode manufacturers in Japan and Europe are displacing merchant sulfate traders with direct equity stakes in Indonesian HPAL projects. This pattern concentrates supply relationships among vertically integrated chemical conglomerates with captive refining assets.
Nickel Sulfate Market Segmentation
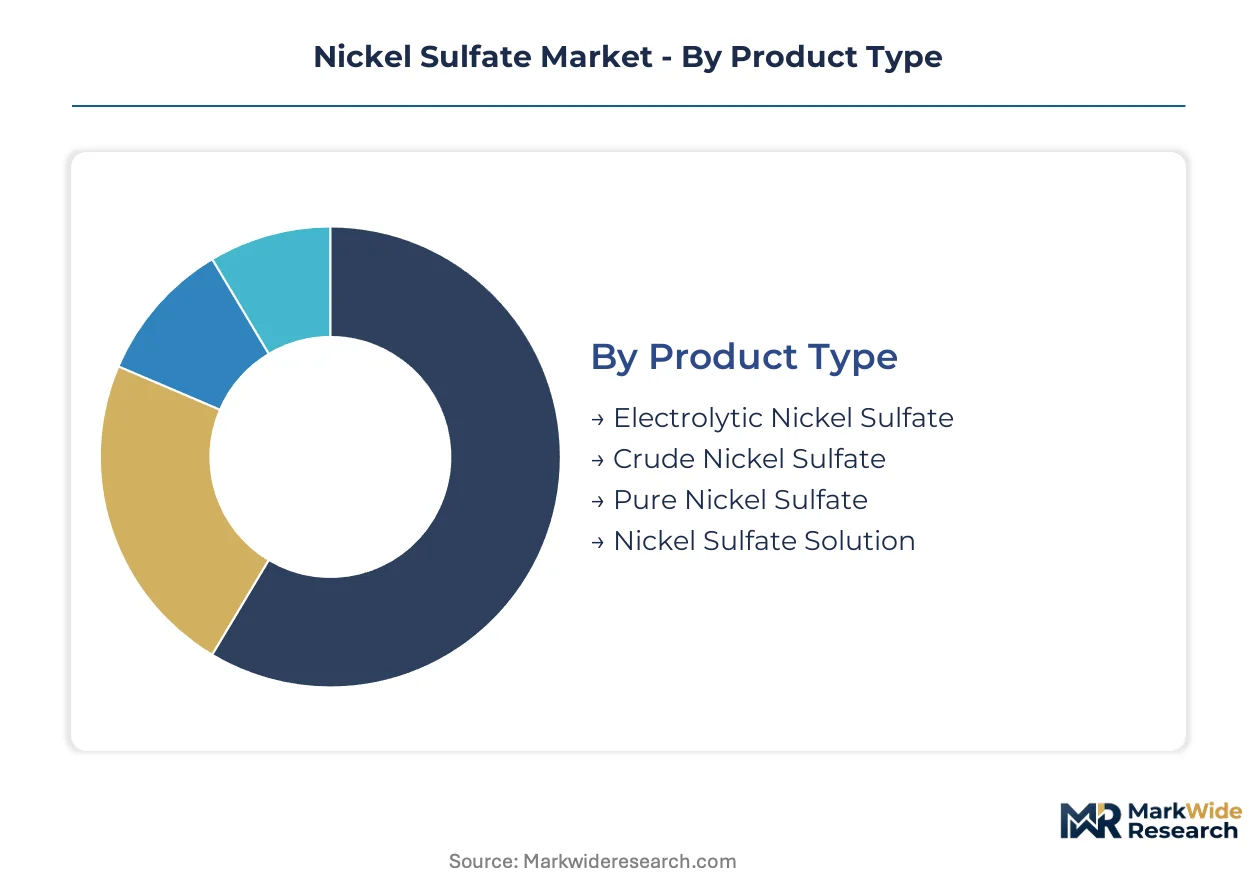
Nickel sulfate segmentation reflects divergent purity standards and physical specifications across battery precursor, plating, and specialty chemical channels. Cathode manufacturers impose sub-10 ppm impurity ceilings that partition the market into premium battery-grade streams versus commoditized industrial grades.
Product Type:
Electrochemical performance specifications differentiate material value tiers, with impurity thresholds determining qualification for cathode precursor synthesis.
- Electrolytic Nickel Sulfate:Produced through electrowinning circuits with cobalt and copper content below 10 ppm, commanding premium positioning in NCM 811 and NCA cathode supply chains. Korean and Japanese precursor manufacturers concentrate procurement through multi-year offtake agreements with Indonesian HPAL operators to secure certified volumes.
- Crude Nickel Sulfate:Intermediate product from atmospheric leaching with elevated iron and magnesium content, serving as feedstock for further refining or lower-specification plating applications. Chinese stainless steel producers absorb volumes for internal nickel recovery circuits.
- Pure Nickel Sulfate:Crystalline material meeting technical-grade specifications for electronics and specialty chemical synthesis, bridging battery-grade purity and industrial utility.
- Nickel Sulfate Solution:Concentrated aqueous delivery eliminating redissolution steps in vertically integrated precursor plants, gaining traction at Indonesian corridor facilities.
Electrolytic nickel sulfate leads on scale; nickel sulfate solution leads on momentum.
Application:
End-use concentration patterns reveal battery chemistry evolution as the dominant demand shaper, displacing legacy industrial absorption.
- Batteries:Cathode active material precursor for lithium-ion cells, with high-nickel NCM formulations electrifying volume requirements. European OEM qualification programs under EU Battery Regulation carbon disclosure mandates are accelerating certified supply chain development.
- Electronics:Printed circuit board plating and semiconductor manufacturing with moderate purity tolerances, facing feedstock competition from battery-grade capacity expansion.
- Plating:Decorative and functional coating applications in automotive components and consumer goods, experiencing supply squeeze as refiners prioritize higher-margin battery streams.
- Catalysts:Petrochemical hydrogenation processes and specialty chemical synthesis, absorbing technical-grade material outside battery qualification pathways.
Batteries absorb the dominant revenue share; catalysts retain the most stable demand baseline.
Form:
Physical delivery specifications align with downstream processing economics, with liquid and crystal forms commanding distinct logistics and handling premiums.
- Crystal:Hexahydrate crystalline product with defined particle size distribution for precise precursor batching, preferred by Japanese and Korean cathode manufacturers with established dissolution protocols.
- Liquid:Aqueous solution at standardized concentration for direct injection into continuous flow precursor synthesis, eliminating solid handling and redissolution capital at integrated HPAL-to-precursor facilities.
- Powder:Dried fine particulate for specialty chemical and catalyst applications with modified dissolution kinetics.
- Granular:Coarse crystalline agglomerate for industrial plating baths and bulk chemical processing with reduced dust generation.
Crystal form dominates established precursor supply chains; liquid form is climbing the fastest in greenfield integrated projects.
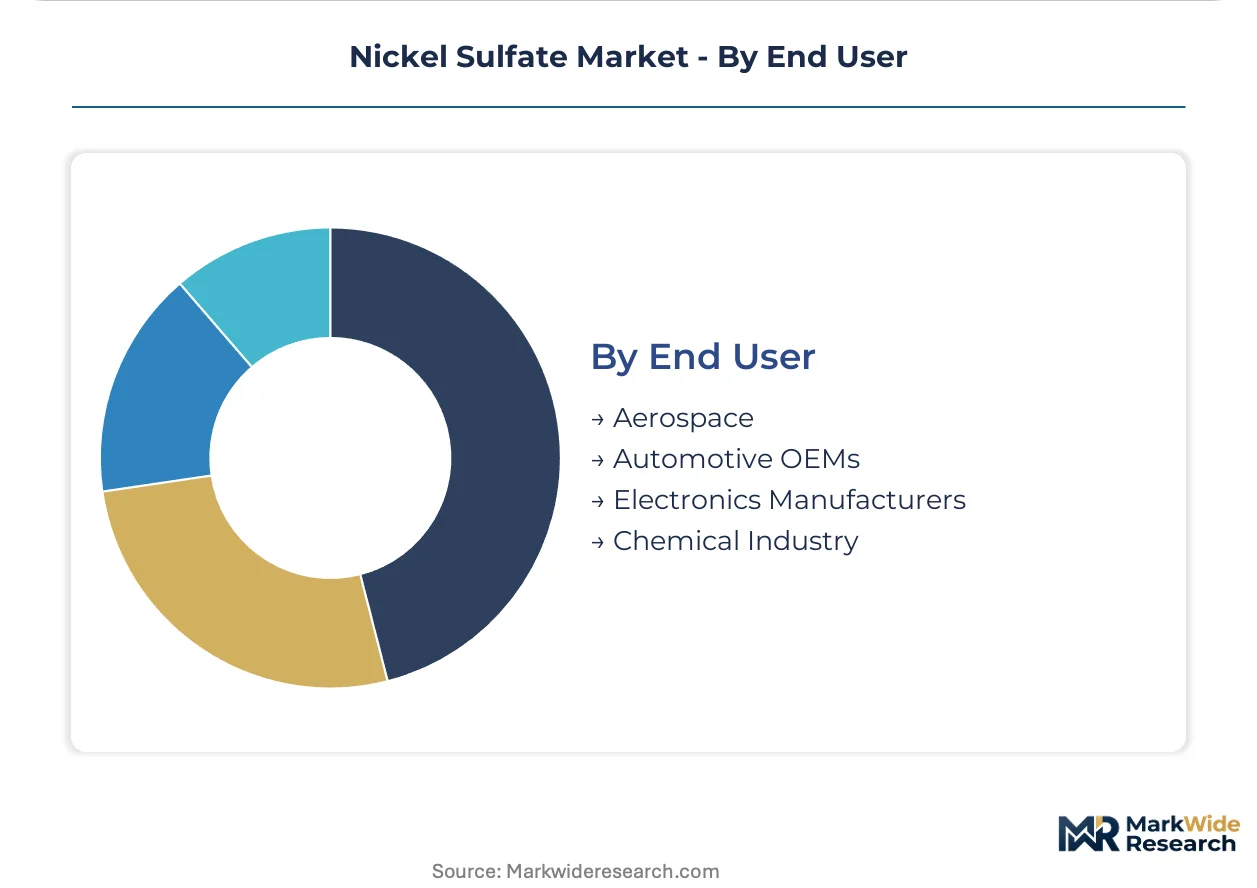
End User:
Customer concentration patterns reflect the battery value chain's vertical integration imperatives, with automotive OEMs and electronics manufacturers exerting divergent procurement pressures.
- Automotive OEMs:Direct offtake contracting with integrated nickel sulfate producers for captive cathode material supply, particularly European and Japanese manufacturers securing Indonesian HPAL equity stakes.
- Electronics Manufacturers:PCB fabricators and semiconductor material suppliers with moderate volume requirements and technical-grade purity specifications, facing price pressure from battery-grade demand diversion.
- Chemical Industry:Diversified specialty chemical and catalyst producers absorbing technical-grade material pools outside battery qualification pathways.
- Aerospace:Limited-volume applications in superalloy and specialty coating segments with stringent traceability requirements.
Automotive OEMs concentrate the largest procurement volumes; electronics manufacturers face the steepest supply access constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's HPAL corridor commands processing scale that China cannot match domestically, while European qualification protocols create divergent certification burdens across supply chains.
Indonesia
Morowali Industrial Park and Weda Bay cluster HPAL-to-sulfate operations serving Korean and Japanese cathode producers. The Ministry of Energy and Mineral Resources enforces nickel ore export bans that redirect feedstock toward domestic refining. Integrated facilities at Halmahera are scaling crystallization capacity to meet battery-grade purity specifications.
China
Jiangsu and Zhejiang precursor manufacturers absorb sulfate volumes for NCM cathode production. SAMR enforces revised GB/T 26008 standards tightening cobalt and copper impurity ceilings below 10 ppm. GEM leverages captive recycling streams in Xiangtan to secure feedstock outside conventional mining channels.
South Korea
Posco Chemical and LG Chem precursor plants concentrate demand in Gyeongsang provinces. The MFDS coordinates with trade ministries on battery material import qualification protocols. Ulsan industrial complexes are installing direct solvent extraction circuits to reduce reagent consumption in sulfate purification.
Japan
Sumitomo Metal Mining anchors cathode supply chains through integrated refining at its Harima complex. METI administers subsidies for domestic precursor manufacturing and critical mineral stockpiling. Kansai region facilities are certifying supply chains under EU Battery Regulation traceability requirements.
Germany
Umicore sustains European precursor leadership through certified sustainable sourcing programs tracing material to mine origin. The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that reshape import qualification criteria. Saxony-Anhalt facilities are qualifying Indonesian HPAL sulfate for automotive OEM offtake contracts.
Nickel Sulfate Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated HPAL operators commanding premium positioning in battery-grade supply chains. The vendor base concentrates among vertically integrated mining-chemical conglomerates and specialized precursor manufacturers with captive refining assets. Two strategic archetypes dominate: Indonesian integrated producers with ore-to-sulfate control, and European-Japanese specialists with certified sustainable sourcing programs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as cathode manufacturers secure equity stakes in upstream processing to lock in qualified volumes.
Among Chinese integrated operators, GEM and Tsingshan Holding Group exemplify the ore-to-sulfate archetype with captive feedstock control over HPAL processing corridors. Umicore represents the certification-specialist tier, anchoring European precursor supply chains through traceability programs that satisfy EU Battery Regulation mandates. Sumitomo Metal Mining occupies a position bridging both archetypes, combining Japanese refining expertise with Indonesian upstream integration through equity partnerships.
| Leading Market Players |
|---|
| GEM (China) |
| Umicore |
| Jinchuan Group International Resources |
| Tsingshan Holding Group |
| Guangxi Yinyi |
| Sumitomo Metal Mining |
| Nickel Industries |
| Jindal Stainless |
| Norilsk Nickel |
| Others |
Value Chain & Pricing Dynamics
Captive ore-to-sulfate integration across Indonesia's HPAL corridor anchors both supply security and pricing power for battery-grade material, concentrating negotiating leverage among operators with direct feedstock control under the country's export ban framework.
Pricing Analysis
Capacity additions in Indonesia are reshaping price floors for battery-grade nickel sulfate as long-term offtake contracting displaces spot market reference. Contract-based long-term offtake dominates, with price differentiation driven by certification grade under EU Battery Regulation mandates and volume scale in multi-year agreements. Cost compression in crude sulfate tiers is intensifying because stainless steel demand cycles pull MHP feedstock toward competing channels. Merchant traders face steepest price sensitivity; integrated producers with captive HPAL assets exhibit least.
Supply Chain Analysis
Black mass collection and hydrometallurgical recovery flows are creating circular sulfate supply outside conventional mining channels, reducing virgin feedstock dependence. Geographic supply concentrates in Indonesia, China, and Australia. Raw material dependencies rest on MHP, mixed hydroxide precipitate, and laterite ore. Single-source vulnerability around Indonesian HPAL engineering talent constrains capacity ramp velocity. Distribution runs through direct equity stakes by Korean and Japanese cathode manufacturers in upstream processing assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-grade nickel sulfate represents a margin-expansion story as high-nickel cathode chemistry shifts premium-tier demand toward sub-10 ppm impurity specifications with associated certification premiums.
For Market Incumbents: Deploy certification investment as the primary lever to defend positioning. Incumbents should deepen backward integration into Indonesian HPAL corridors to lock in qualified feedstock under tightening EU Battery Regulation traceability mandates. Channel control through direct precursor plant equity stakes in South Korea and Japan secures volume commitment against emerging merchant traders. For New Entrants and Emerging Players: E-commerce platform routes for black mass procurement offer lowest-friction market entry. White-space targets include India's PLI-supported precursor corridor in Gujarat and Tamil Nadu, plus solid-state battery electrolyte feedstock with stricter purity thresholds than current cathode specs. Partner with established HPAL operators for tolling arrangements rather than greenfield construction. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale HPAL operators with proven ramp records because engineering talent scarcity prevents rapid organic replication. Five-to-ten year viability favors integrated producers with dual China-EU certification pathways. Monitor Indonesian Ministry of Energy and Mineral Resources downstream rule evolution as inflection indicator for feedstock access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Capacity Expansion | Indonesian integrated operators scale crystallization to meet battery-grade purity under ore export bans. |
| Backward Integration into Recycling | GEM leverages captive black mass streams in Xiangtan to bypass conventional mining feedstock constraints. |
| EU Battery Regulation Certification | Umicore traces material to mine origin to satisfy carbon disclosure and recycled content mandates. |
| Long-term Supply Agreement | Posco Chemical and LG Chem lock in Indonesian sulfate volumes through direct equity stakes. |
| Joint Venture | Sumitomo Metal Mining partners across Harima refining and Indonesian upstream to bridge certification and scale. |
Study Parameters
Multiple input streams — HPAL plant managers, cathode manufacturer procurement leads, nickel ore trading desks, and battery recycling operators — were reconciled against customs data, Indonesian Ministry of Energy and Mineral Resources filings, and SAMR GB standard enforcement records. Primary interviews with downstream precursor technical directors and upstream metallurgical engineers informed capacity ramp timelines and impurity specification evolution. Bottom-up sulfate demand modeling and top-down nickel flow analysis triangulated volume estimates.
Cross-referencing historical capacity achievement rates against expert panel input shaped the projection framework across the analysis window. Segmentation dimensions included product grade tier, cathode chemistry formulation, physical delivery form, and regional regulatory cluster. CAGRs derived from fitted adoption curves for high-nickel NCM penetration and HPAL capacity commissioning schedules. Forecast inputs incorporated EU Battery Regulation implementation pacing and Indonesian downstream investment incentive durability.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery sulfide electrolytes would alter the outlook toward ultra-high-purity compound demand. Forecasts reflect assumptions around HPAL engineering talent availability and China-EU regulatory alignment. Practitioners should monitor Indonesian ore export ban enforcement shifts and EU carbon border adjustment mechanism scope expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Nickel Powder Plating Market
Metals
Silver Enamel Market
Metals
Russia Metal Fabrication Market
Metals
Industrial Metal Strips Market
Metals
Lightweight Aluminium Pistons Market
Metals
Global Bronze Market
Metals
Aluminium Powder Market
Metals
Clutch Spring Wires Market
Metals
Global Copper Cathode Market
Metals
Metal Forging Parts Market
Metals
Metallic Rope Cords Market
Metals
Global Welding Powder Market
Metals
Metal Powder Market
Metals
Beryllium Copper Plate Market
Metals
High Purity Aluminium Market
Metals
Zinc Plating Market