
 Aluminium Forging Market | 2026-2036
Aluminium Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Forging Market Outlook
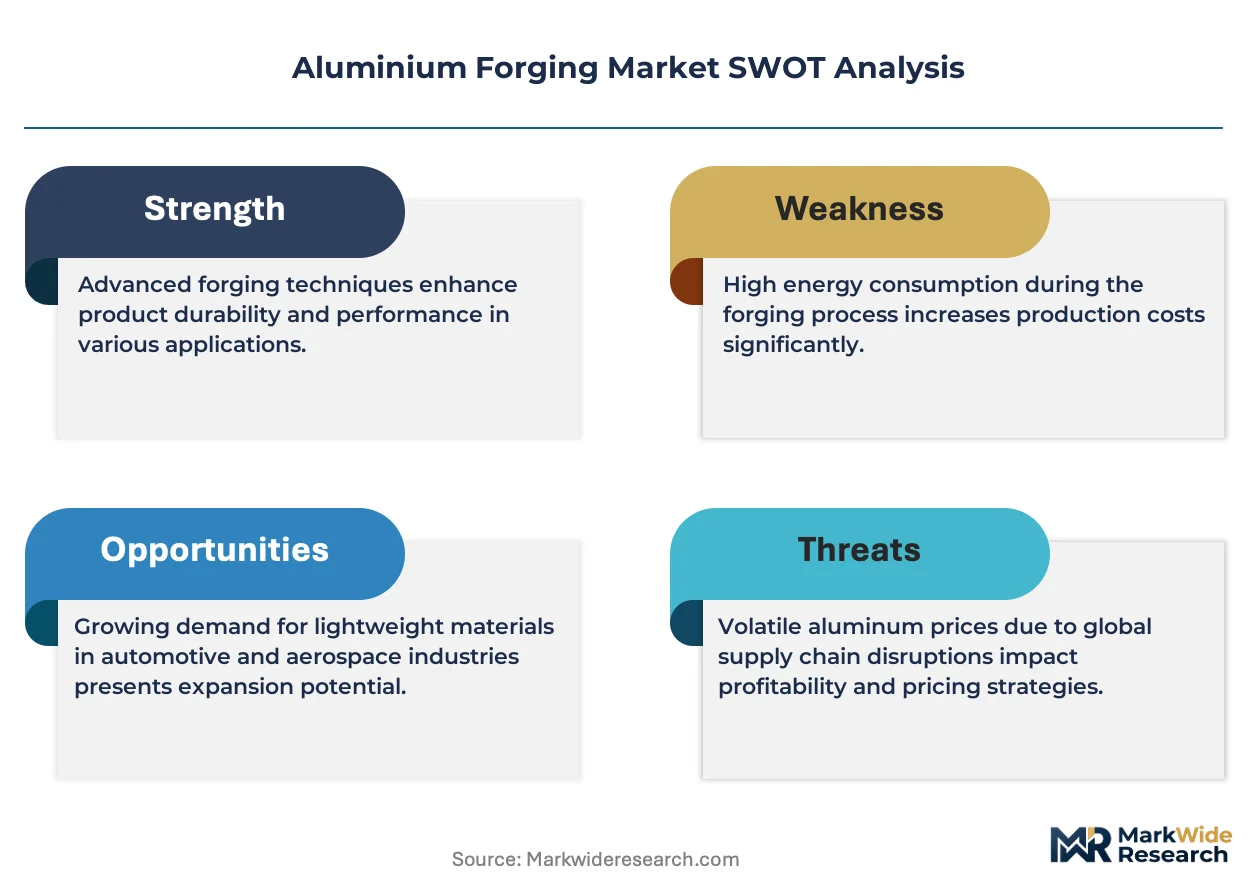
Lightweighting architectures in commercial aviation is fragmenting the traditional titanium-dominant supply base, opening procurement lanes for high-strength aluminium forgings. Howmet Aerospace leverages its aerospace-grade forging capacity across multiple Tier-1 supply chains. Bharat Forge anchors its position through backward integration into aluminium billet sourcing and heat-treatment infrastructure. Alcoa Corporation differentiates via captive smelter-to-forge metallurgical control.
Aluminium forging is a solid-state deformation process where aluminium alloy billets are shaped under compressive force at temperatures typically between 350°C and 500°C, producing grain-aligned components with fatigue resistance superior to cast equivalents. Closed die forging commands the largest value share due to its precision in producing complex aerospace and automotive structural members with minimal machining allowance. Rolled ring forging is accelerating fastest, driven by demand for seamless cylindrical components in jet engine casings and wind turbine hubs where weld elimination is critical.
The US FAA airworthiness directives and EPA emissions standards for forging furnaces jointly elevate compliance costs while favoring capital-rich operators with environmental control investments. Europe's ECHA REACH restrictions on process chemicals and the EU Green Deal carbon border adjustments are reshaping sourcing decisions for imported aluminium forgings. China's MEE enforcement of dual carbon goals is forcing capacity consolidation among smaller forging shops. Stakeholders must monitor regulatory divergence between jurisdictions as a determinant of competitive cost structures.
Market Dynamics
Aerospace OEMs are fragmenting the traditional titanium-dominant supply base, opening procurement lanes for high-strength aluminium forgings as next-generation airframes prioritize weight reduction and fuel efficiency targets.
Growth Catalysts
- Commercial Aviation Lightweighting:Boeing and Airbus are expanding forged aluminium content in wing ribs, bulkheads, and landing gear components to meet ICAO emissions standards.
- China's Dual Carbon Enforcement:The MEE is consolidating energy-intensive forging capacity, favoring capital-rich operators with environmental control investments and captive renewable power.
- Automotive EV Structural Demand:Battery enclosure manufacturers in Germany's supplier belt around Stuttgart are specifying closed-die aluminium forgings for crashworthiness and thermal management.
Market Restraints
- Primary Aluminium Price Volatility:LME aluminium price swings compress forging margins, particularly for toll processors without captive smelter supply.
- China Supply Concentration Risk:Domestic forging capacity consolidation under NMPA emissions benchmarks is reducing export availability and tightening global billet supply.
- Carbon Fiber Substitution Threat:Automated fiber placement advances in aerospace primary structures are displacing forged aluminium in non-load-bearing applications.
Strategic Opportunities
- India Automotive Supplier Base:PLI scheme incentives for advanced manufacturing are attracting forging investments for domestic OEMs and export to Middle Eastern markets.
- Offshore Wind Hub Manufacturing:Rolled ring forging demand for 15MW+ turbine main bearings is creating new capacity requirements in coastal industrial zones.
- EU Green Deal Carbon Border Adjustment:CBAM implementation is rewarding European forging operations with verified low-carbon metallurgy against imported competition.
Industry Challenges
- Heat Treatment Technician Shortage:Specialized furnace operators and metallurgists with aerospace certification credentials are in critically short supply across mature manufacturing regions.
- FAA Airworthiness Certification Timelines:New alloy qualification for flight-critical components requires 18-36 month testing cycles, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Forging Market |
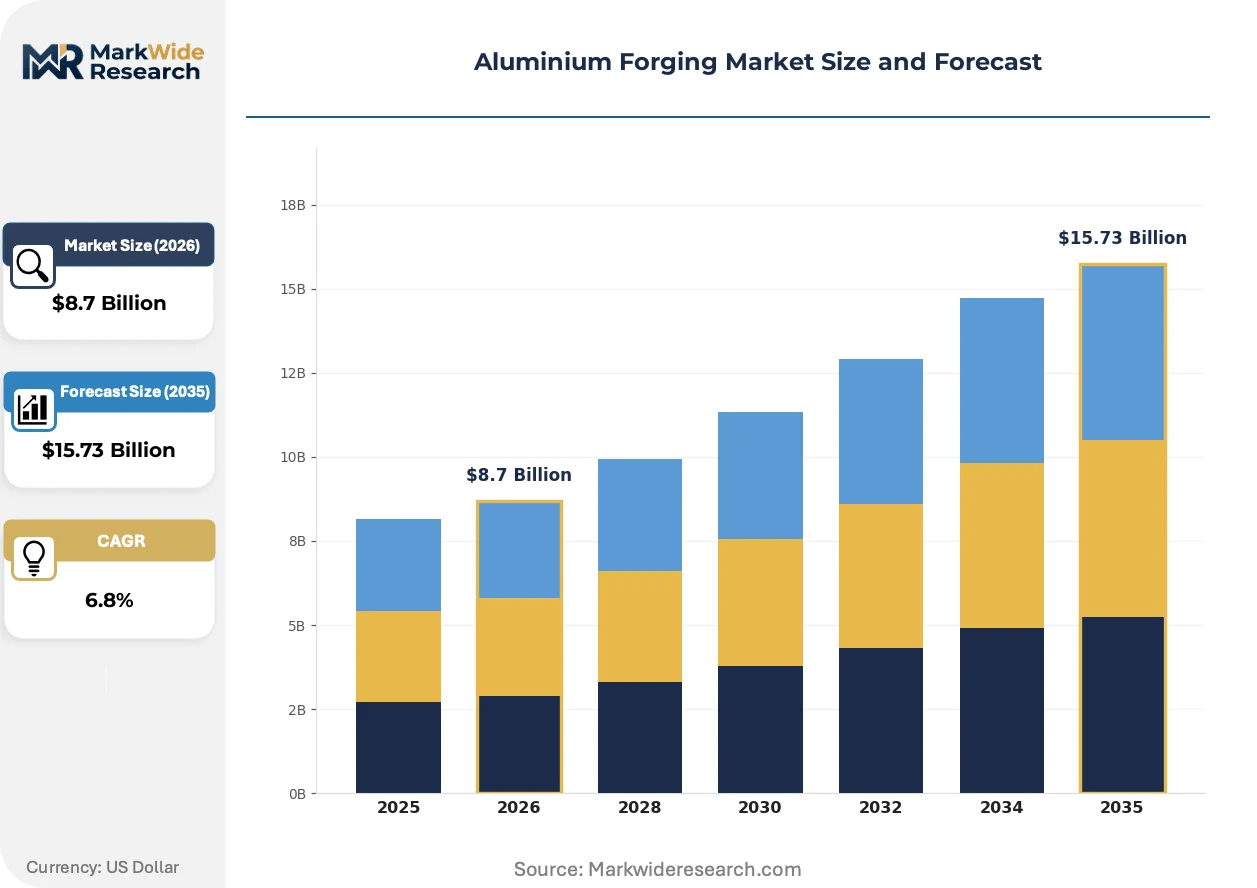
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Die, Open Die, Rolled Ring, Others Application: Aerospace, Automotive, Construction, Industrial Machinery End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Technology: Hot Forging, Cold Forging, Isothermal Forging, Hybrid Forging |
| Companies Covered | Howmet Aerospace, Bharat Forge, Alcoa Corporation, Arconic, ATI, Aluminum Precision Products, Farinia Group, Scot Forge, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Forging Market Strategic Shifts
Digital thread integration across forging operations is compressing design-to-production cycles, while regulatory pressure on embodied carbon is reshaping metallurgical sourcing decisions and heat treatment energy profiles.
Isothermal forging is migrating from niche aerospace applications toward automotive powertrain components. Tier-1 suppliers in Germany and Japan are installing servo-hydraulic presses with precision temperature control to produce net-shape gears and connecting rods. The process is migrating from high-cost titanium workhorses toward volume aluminium production, enabling thinner walls and reduced machining allowances that cut material waste by half.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent alternatives or laser surface modification across European forging operations. ECHA enforcement has accelerated capital deployment in closed-loop chemical recovery systems. Aerospace fastener and landing gear manufacturers face the steepest compliance costs, with some relocating heat treatment steps to non-EU jurisdictions to maintain process economics.
Consolidated procurement platforms are displacing traditional distributor networks for standard-grade aluminium forgings. Tier-2 automotive suppliers in Michigan and Bavaria are contracting directly with integrated mills for scheduled billet-to-forge deliveries, bypassing intermediate stockists. This pattern is most pronounced in high-volume chassis components where specification standardization has reduced the value of technical distributor services.
Aluminium Forging Market Segmentation
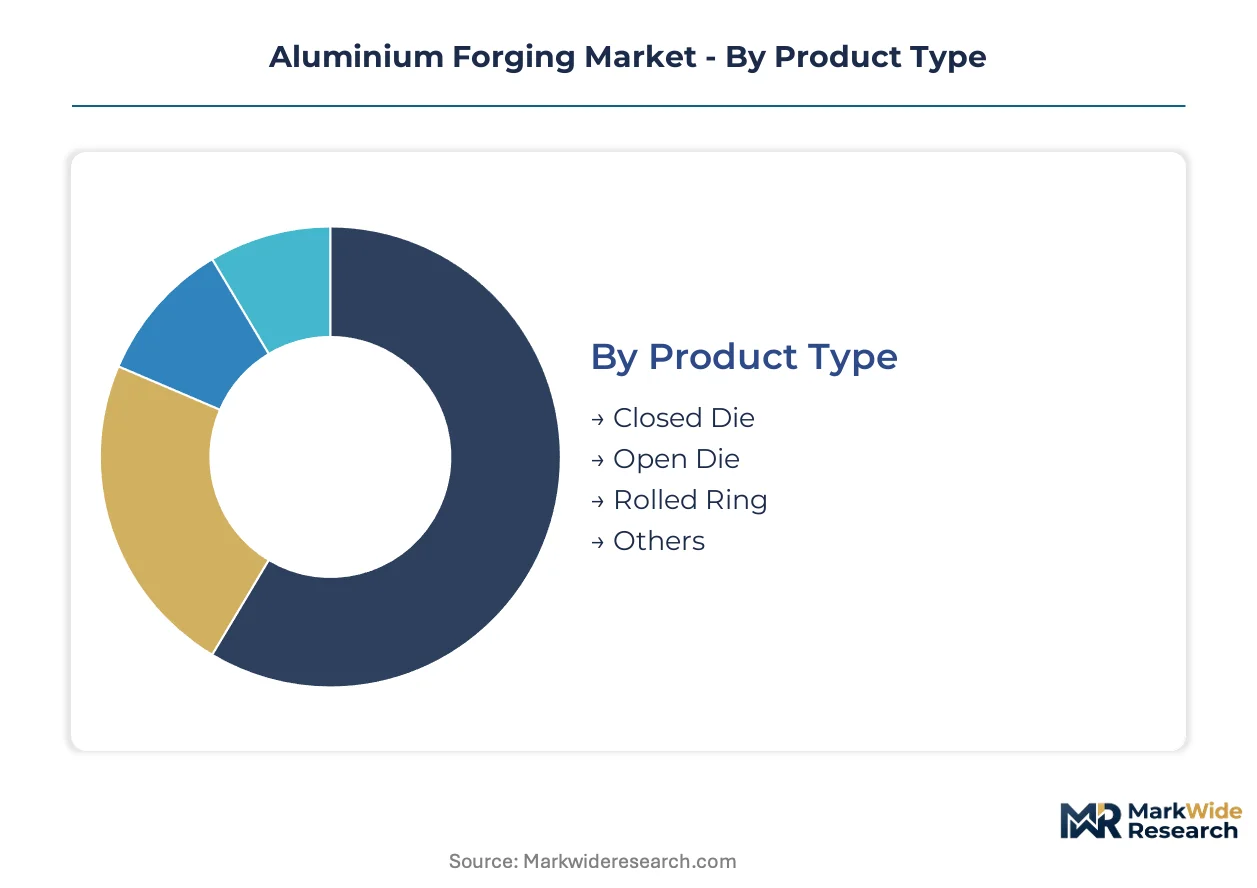
Segmentation in aluminium forging reveals divergent margin profiles and capital intensity across process technologies. Procurement cycles vary dramatically between aerospace qualification timelines and automotive volume contracts.
Product Type:
Cycle times compress from months for aerospace-grade closed die work to weeks for standard industrial open die production. Rolled ring forging occupies the middle ground with batch-dependent scheduling.
- Closed Die:Precision die cavities shape complex geometries with minimal machining allowance. Demand concentrates in Boeing and Airbus wing rib programs where fatigue resistance specifications exceed cast alternatives. Boeing's 787 and Airbus A350 programs anchor procurement volumes.
- Rolled Ring:Seamless cylindrical components eliminate weld zones in critical rotating assemblies. Offshore wind turbine main bearing demand in Germany's North Sea ports and jet engine casing orders from GE Aerospace and Rolls-Royce drive capacity expansion.
- Open Die:Simple hammer or press forging for large structural sections with lower tooling investment.
- Others:Specialized processes including seamless hollow forging and precision upsetting for niche applications.
Closed die forging anchors the volume base while rolled ring forging gains share at the steepest rate.
Application:
Margin tiers separate flight-critical aerospace work from construction commodity forgings by a factor of three to five. Customer technical requirements dictate metallurgical control investments.
- Aerospace:Wing ribs, bulkheads, and landing gear components require 18-36 month alloy qualification cycles under FAA airworthiness directives. Howmet Aerospace and PCC Structurals dominate Tier-1 supply chains for next-generation airframes prioritizing weight reduction.
- Automotive:EV battery enclosures and crash management systems specify closed-die aluminium forgings for specific energy absorption. Germany's supplier belt around Stuttgart and Munich concentrates demand from Mercedes-Benz and BMW electric platforms.
- Construction:Structural connectors and facade support hardware serve commercial building projects with standardized specifications.
- Industrial Machinery:Hydraulic cylinder ends, valve bodies, and pump housings serve capital equipment replacement cycles.
Aerospace applications command premium pricing while automotive demand expands most quickly.
End User:
Procurement authority is consolidating toward OEMs and Tier-1 suppliers as specification complexity rises. Distributor margins compress where technical differentiation erodes.
- OEMs:Boeing, Airbus, and automotive manufacturers specify forging requirements directly for proprietary designs. Airbus's Hamburg and Toulouse engineering centers source qualified suppliers through consolidated procurement platforms.
- Tier-1 Suppliers:Howmet Aerospace, GKN Aerospace, and automotive chassis specialists manage sub-tier forging capacity under long-term agreements.
- Aftermarket Providers:Replacement components for mature aircraft fleets and industrial equipment serve maintenance cycles.
- Distributors:Standard-grade billet and forging stock for job shops face disintermediation from mill-direct contracting.
Tier-1 suppliers anchor the volume base while OEM direct procurement gains share fastest.
Technology:
Energy intensity and tooling costs create distinct competitive moats. Process selection locks in capital deployment for decades.
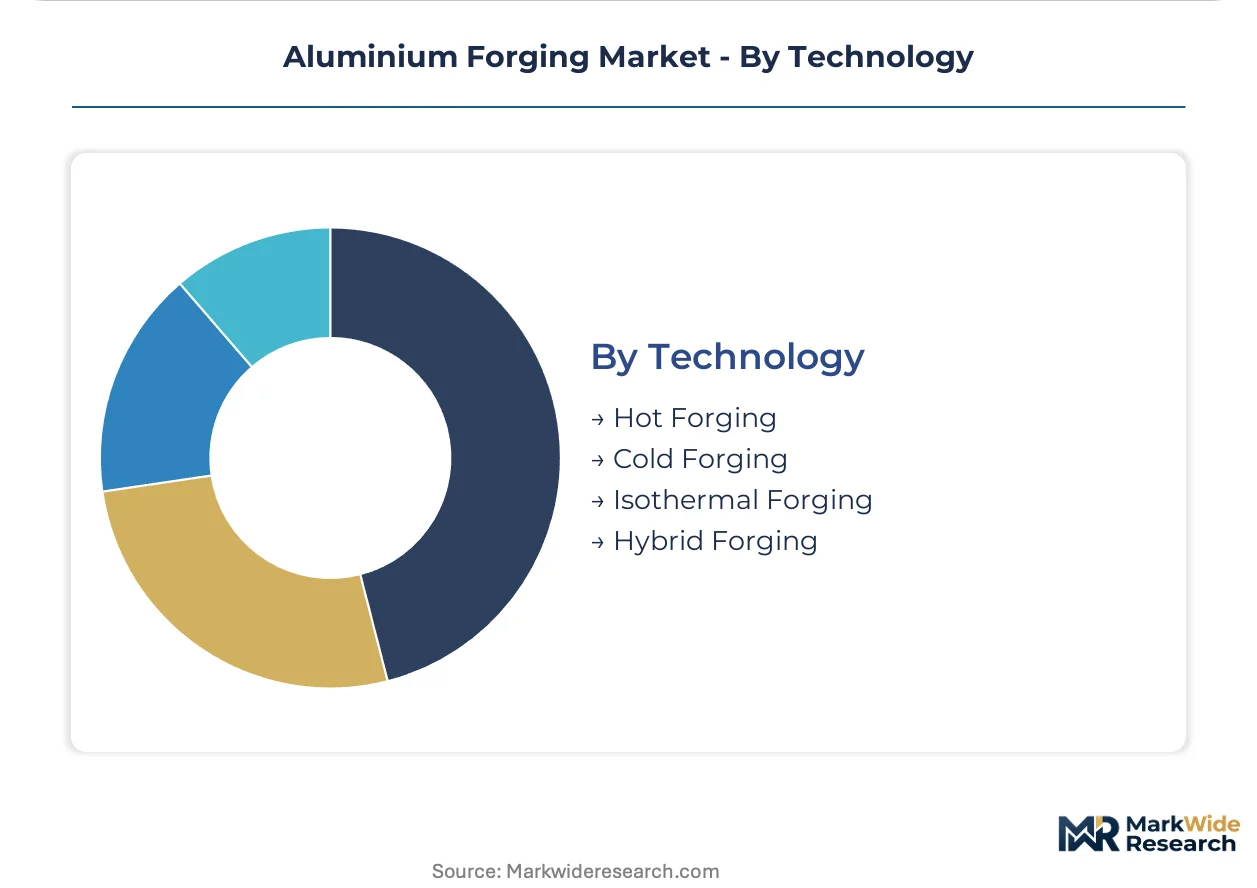
- Hot Forging:Conventional deformation between 350°C and 500°C serves high-volume automotive and industrial applications with established equipment bases.
- Cold Forging:Near-net-shape production at ambient temperatures delivers surface finish and dimensional precision for fastener and small component manufacturing.
- Isothermal Forging:Precision temperature control enables thinner walls and reduced machining waste. Germany's Schuler and Japan's Komatsu supply servo-hydraulic presses migrating from titanium workhorses toward volume aluminium production.
- Hybrid Forging:Combined thermal and mechanical processing routes optimize grain structure for demanding applications.
Hot forging anchors the volume base while isothermal forging climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace OEM procurement offices cluster around Hamburg, Toulouse, and Seattle, while automotive forging demand concentrates in Germany's supplier belt and China's Yangtze industrial corridor. Buyers prioritize proximity to qualified heat-treatment facilities and regulatory-compliant metallurgical certification.
United States
Defense aerospace programs and commercial aviation OEMs in Washington state and the Gulf Coast drive demand for closed-die wing rib forgings. The FAA enforces 18-36 month alloy qualification timelines under airworthiness directives. Howmet Aerospace operates forging capacity in Cleveland and Whitehall to serve Boeing's 787 and Airbus A350 supply chains.
Germany
Mercedes-Benz and BMW electric platforms specify aluminium forgings for battery enclosures and crash management systems. The KBA enforces EU Green Deal carbon border adjustments that reward verified low-carbon metallurgy. Stuttgart and Munich anchor the automotive supplier belt where Tier-1 chassis specialists contract directly with integrated mills.
China
Domestic aviation programs and wind turbine hub manufacturing absorb rolled ring forging capacity along the Yangtze River Delta. The MEE consolidates energy-intensive forging shops under dual carbon enforcement, favoring operators with captive renewable power. Jiangsu and Zhejiang provinces host the surviving large-scale forging complexes after NMPA-mandated capacity closures.
India
PLI scheme incentives attract forging investments for domestic automotive OEMs and export to Middle Eastern markets. The BIS certifies aluminium alloy grades for aerospace and defense applications. Pune and Chennai industrial corridors concentrate new press installations serving Mahindra and Tata Motors electric vehicle programs.
Japan
Isothermal forging press deployments for automotive powertrain components migrate from titanium workhorses toward volume aluminium production. METI supports precision manufacturing investments through technology licensing programs. Aichi and Osaka prefectures host servo-hydraulic press installations producing net-shape gears with reduced machining waste.
Aluminium Forging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply chains. Integrated mills with captive smelter supply negotiate long-term billet-to-forge contracts directly with automotive OEMs, while toll processors without upstream metal sourcing face margin compression from LME price volatility. Three archetypes dominate: aerospace-grade specialists with FAA-qualified heat treatment infrastructure, automotive volume producers with isothermal forging capability, and diversified metals conglomerates with backward integration into primary aluminium. Competitive moves center on M&A to secure heat treatment technician talent and capacity expansion in coastal industrial zones serving offshore wind hub demand.
Among aerospace-anchored fabricators, Howmet Aerospace and ATI exemplify the premium-tier archetype with multi-program qualification across Boeing and Airbus supply chains. Bharat Forge represents the diversified industrial conglomerate model with upstream control over billet sourcing and metallurgical infrastructure. Thyssenkrupp AG occupies a position bridging automotive volume production and specialized aerospace work within European regulatory frameworks.
| Leading Market Players |
|---|
| Howmet Aerospace |
| Bharat Forge |
| Alcoa Corporation |
| Arconic |
| ATI |
| Aluminum Precision Products |
| Farinia Group |
| Scot Forge |
| Thyssenkrupp AG |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Zhejiang provinces along China's Yangtze River Delta concentrate surviving large-scale forging capacity after NMPA-mandated emissions closures, concentrating billet supply power among operators with captive renewable power and elevating pricing leverage over downstream automotive and aerospace buyers in Germany and the United States.
Pricing Analysis
Cost-plus contracts indexed to LME aluminium spot prices dominate long-term offtake agreements between integrated mills and automotive OEMs, with aerospace-grade closed-die forgings commanding substantial premiums over standard industrial grades due to FAA certification requirements and 18-36 month alloy qualification timelines. Three-tier pricing structure across aerospace-certified, automotive-volume, and industrial-commodity levels separates margin tiers by a factor of three to five. Cost compression in automotive chassis components is intensifying because Tier-1 suppliers are contracting directly with integrated mills, bypassing distributor markups. EV battery enclosure manufacturers in Germany's supplier belt exhibit the highest price sensitivity, while flight-critical aerospace programs show minimal elasticity due to sole-source qualification constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with Howmet Aerospace, Bharat Forge, and Thyssenkrupp AG, which operate qualified heat-treatment infrastructure across multiple jurisdictions. Primary supply anchors in China, Germany, and the United States feed downstream fabrication, with billet sourcing drawing from captive smelter operations in Canada and Australia. Supply chain risk centers on single-source vulnerability for aerospace-grade alloy qualification, where FAA-certified heat treatment technicians are in critically short supply. Distribution runs through consolidated procurement platforms displacing traditional distributor networks, with Tier-2 automotive suppliers in Michigan and Bavaria contracting mill-direct for scheduled billet-to-forge deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminium forging market rewards operators possessing scarce FAA-certified metallurgical talent and captive renewable energy access, with capability gaps in heat treatment infrastructure and alloy qualification timelines creating defensive moats for incumbents while constraining expansion velocity for challengers.
For Market Incumbents: Insulate aerospace-grade margin tiers by accelerating heat treatment technician apprenticeship pipelines and securing captive renewable power purchase agreements ahead of EU Green Deal carbon border adjustments. Carbon fiber substitution in non-load-bearing aerospace structures and China's MEE capacity consolidation represent dual threats requiring preemptive positioning in rolled ring forging for offshore wind turbine hubs. For New Entrants and Emerging Players: India's PLI scheme corridors around Pune and Chennai offer underpenetrated white-space for automotive EV structural forgings serving Mahindra and Tata Motors platforms, with export pathways to Middle Eastern markets providing volume ramp before aerospace qualification investments. Target isothermal forging capability for net-shape powertrain components as the most penetrable technology tier, leveraging servo-hydraulic press deployments migrating from titanium toward volume aluminium production. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified industrial conglomerates with backward integration into primary aluminium and qualified aerospace heat treatment infrastructure. Long-term viability hinges on exposure to dual-use defense-commercial aerospace programs and automotive EV structural demand rather than commodity industrial forgings. Acquisition targets should demonstrate verified low-carbon metallurgy credentials and coastal proximity to offshore wind hub manufacturing zones. Watch FAA airworthiness directive acceleration and ECHA REACH enforcement stringency as inflection indicators for competitive cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive smelter access insulates margins from LME volatility and secures alloy traceability for aerospace certification. |
| Isothermal Forging Capacity Expansion | Servo-hydraulic press installations enable thinner-wall net-shape production, cutting material waste by half for automotive powertrain components. |
| Heat Treatment Technician Pipeline Development | FAA-certified metallurgist scarcity across mature manufacturing regions threatens capacity utilization without proactive workforce investment. |
| Coastal Industrial Zone Positioning | Proximity to North Sea and Yangtze Delta offshore wind assembly hubs captures rolled ring forging demand for 15MW+ turbine main bearings. |
| Verified Low-Carbon Metallurgy Certification | EU Green Deal carbon border adjustments reward European operations with documented renewable power and recycled content against imported competition. |
Study Parameters
A spread of perspectives from aerospace procurement directors at Boeing and Airbus, Tier-1 forging operations managers, heat treatment technicians with FAA credentials, automotive platform engineers at Mercedes-Benz and BMW, and primary aluminium traders converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings of listed forging operators, FAA airworthiness directive databases, and ECHA REACH enforcement records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers produced convergent volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning process technology, application tier, end-user procurement authority, and regional regulatory cluster. CAGRs emerged from curve-fitting historical production data against announced capacity expansions and OEM platform launch timelines. Industry-specific forecast inputs incorporated Boeing and Airbus order backlogs, China's MEE capacity closure schedules, and Germany's KBA carbon border adjustment implementation trajectory.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-sponsored Chinese forging conglomerates or carbon fiber composite manufacturers would shift outcomes beyond modeled ranges. Quarterly review of FAA airworthiness directive issuance rates, LME aluminium price volatility bands, and ECHA enforcement actions against hexavalent chromium surface treatments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
India Steel Market
Metals
Copper Azoles Market
Metals
Global Flat Steel Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Ferro Aluminum Market
Metals
Bismuth Oxide Market
Metals
Global Stretch Spring Wire Market
Metals
Silver-Platinum Paste Market
Metals
Industrial Silver Market
Metals
India Metal Fabrication Market
Metals
Global Tin Market
Metals
Powder Metallurgy Market
Metals
Global Vanadium Market
Metals
Europe Aluminium Wire Rod Market
Metals
North America Iron Casting Market
Metals
Huntite Market