
 Crude Steel Market | 2026-2036
Crude Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Steel Market Analysis
Multi-source procurement of iron ore and metallurgical coal is pivoting toward captive mining and long-term offtake contracts as price volatility reshapes mill economics. China Baowu Group leverages its integrated Australian and Brazilian ore positions to sustain margin stability across volatile cycles. ArcelorMittal competes through a diversified Atlantic basin footprint that anchors supply security for European and North American flat steel customers. Nippon Steel Corporation differentiates via premium automotive-grade sheet specialization that commands tighter tolerances than commodity offerings.
Crude steel is an intermediate metallic product derived from iron ore reduction, typically containing 0.02% to 2.14% carbon by weight, with molten output cast into slabs, blooms, or billets for downstream rolling and forming. Its primary purpose is to serve as the foundational feedstock for structural shapes, vehicle bodies, machinery housings, and energy transmission equipment. Flat steel occupies the largest value pool due to automotive and appliance lamination requirements, while electric arc furnace output is the fastest-growing production channel as scrap recycling economics improve against virgin ore-based routes. Long steel and reinforcing bars retain mature, volume-driven profiles tied to construction cycles with thinner margin structures.
The US EPA enforces greenhouse gas reporting and emissions limits under the Clean Air Act that affect integrated mill operations, while China's MEE implements dual carbon targets requiring provincial steel output caps and carbon intensity benchmarks. India's CEA mandates energy consumption norms for designated consumers including integrated steel plants, tightening compliance costs for blast furnace operators. Stakeholders must monitor how carbon border adjustment mechanisms and scrap availability reshape the optimal production technology mix across major producing regions.
Market Dynamics
China's MEE provincial output caps and carbon intensity benchmarks are forcing blast furnace operators to accelerate electric arc furnace retrofits, compressing the technology mix across Asia's largest production base.
Growth Catalysts
- India's PLI scheme for specialty steel:The production-linked incentive framework is channeling capital toward high-grade automotive and coated sheet capacity, aligning mill expansion with downstream manufacturing clusters.
- Construction vertical demand:Infrastructure budgets across emerging economies are sustaining long steel and rebar offtake as urbanization drives structural fabrication needs.
- Scrap recycling economics:Improving collection infrastructure and sorting technology are lowering electric arc furnace feedstock costs relative to virgin ore-based routes.
Market Restraints
- Metallurgical coal price volatility:Seaborne premium hard coking coal fluctuations are eroding blast furnace operator margins and complicating long-term contract negotiations.
- Chinese supply concentration:Over half of global crude steel output originates from mills subject to MEE provincial caps, creating volume uncertainty for international buyers.
- Direct reduced iron technical limitations:Hydrogen-based reduction remains energy-intensive at scale, constraining near-term adoption outside pilot installations.
Strategic Opportunities
- Vietnam's underpenetrated flat steel market:Domestic appliance and electronics manufacturing growth is outpacing local cold-rolling capacity, creating import substitution potential.
- EU Carbon Border Adjustment Mechanism:The phased implementation is creating competitive advantage for mills with verified low-carbon intensity production, rewarding early EAF adopters.
- Automotive-grade sheet specification convergence:Tighter tolerance requirements for electric vehicle body-in-white applications are compressing supplier qualification timelines and favoring integrated producers.
Industry Challenges
- Electric arc furnace transformer engineering talent:The specialized skill set for large-scale furnace electrical systems is concentrated among a shrinking cohort of experienced designers and commissioning engineers.
- Blast furnace relining capex cycles:Major rebuilds require extended outage periods and capital commitments that strain balance sheets during margin compression phases.
- ISO 14064 carbon verification complexity:Scope 3 emissions accounting across ore, coal, and scrap supply chains is creating audit bottlenecks and certification delays for export-bound mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Steel Market |
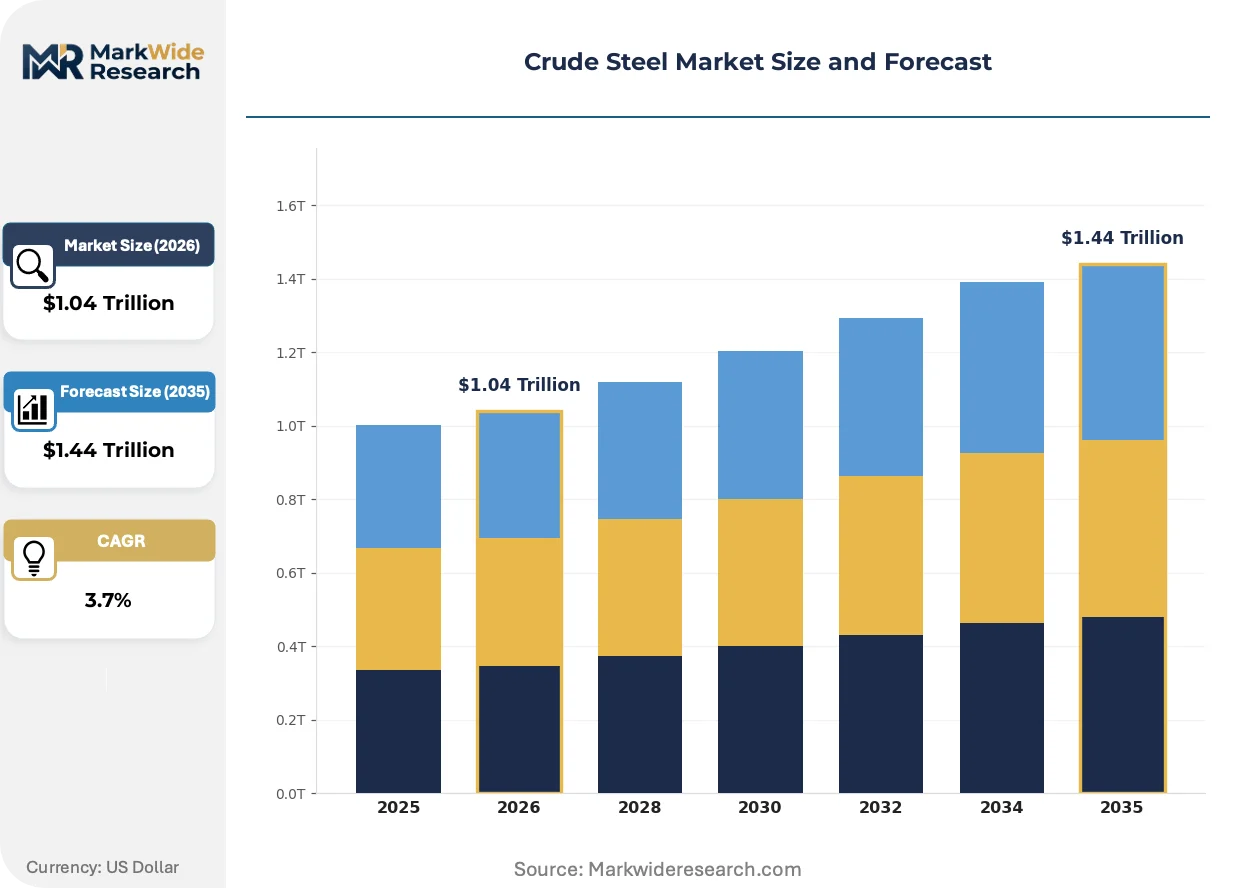
| Market Size in 2026 | $1.04 Trillion |
| Market Size in 2035 | $1.44 Trillion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Steel, Long Steel, Reinforcing Bars, Stainless Steel Production Process: Basic Oxygen Furnace, Electric Arc Furnace, Blast Furnace, Open Hearth Furnace End User: Construction, Automotive, Appliances, Manufacturing Application: Infrastructure, Machinery, Transportation, Energy |
| Companies Covered | POSCO, Ansteel Group, China Baowu Group, JSW Steel, Tata Steel Group, ArcelorMittal, HBIS Group, NLMK, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Steel Market Emerging Trajectories
Production technology trajectories are diverging sharply between regions with abundant scrap access and those locked into ore-based infrastructure, reshaping competitive positioning across flat and long steel categories.
Hydrogen direct reduction technology is converging with carbon capture utilization and storage systems in European pilot installations. Automotive OEMs in Germany and Sweden are contracting for near-zero-emission steel volumes under ten-year offtake agreements. This convergence is compressing the timeline for commercial-scale fossil-free production and forcing integrated mills to accelerate greenfield DRI-HBI investments.
China's MEE dual carbon targets are mandating provincial steel output caps and carbon intensity benchmarks that tighten annually through 2030. Blast furnace operators in Hebei and Jiangsu provinces are facing forced capacity swaps that require EAF replacement ratios. Flat steel producers serving export markets are prioritizing carbon verification to preempt EU CBAM border charges.
Automotive OEM procurement teams are unbundling steel supply contracts from legacy mill-direct relationships. Tier-1 stampers in North America and Europe are consolidating volume through steel service centers that offer just-in-time slitting and blanking. This channel shift is most visible in battery enclosure and motor lamination steel, where precision tolerances and inventory velocity outweigh traditional volume discount structures.
Crude Steel Market Segmentation
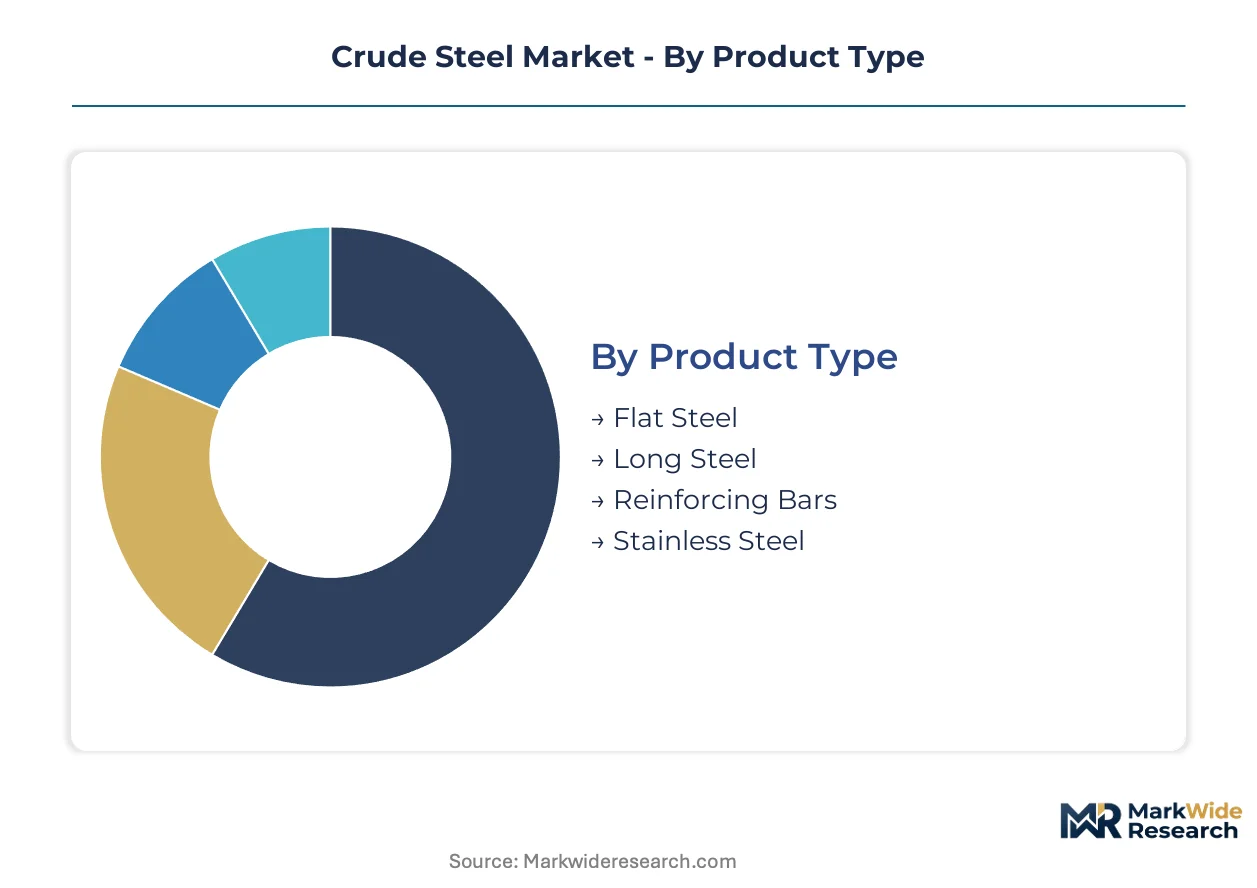
Crude steel segmentation reveals how production technology, product form, and end-use requirements create distinct margin pools and capital intensity profiles across the value chain. Understanding these divisions helps stakeholders align capacity investments with evolving demand patterns in construction, automotive, and energy infrastructure.
Product Type:
Buyers prioritize dimensional tolerance and surface finish specifications that determine downstream processing yields.
- Flat Steel:Hot-rolled and cold-rolled sheet products serve automotive body panels and appliance enclosures where thickness uniformity below 0.1mm deviation commands premium pricing. Demand concentrates in Germany and Japan as electric vehicle manufacturers tighten body-in-white specifications for battery platform integration.
- Long Steel:Structural sections, rails, and merchant bars carry higher carbon tolerance and lower surface quality requirements than flat products. Indian infrastructure projects in Maharashtra and Gujarat are absorbing merchant bar volumes as metro rail and highway expansion accelerates.
- Reinforcing Bars:Deformed bar products for concrete reinforcement feature ribbed profiles engineered for tensile bond strength with cement matrices.
- Stainless Steel:Chromium-nickel alloy grades resist corrosion in chemical processing and medical equipment applications requiring passivation surface treatments.
Volume sits with reinforcing bars; growth tilts toward flat steel.
Production Process:
Feedstock access and electricity pricing determine route economics more than equipment vintage.
- Electric Arc Furnace:Scrap-fed melting using graphite electrodes achieves 85% lower carbon intensity than ore-based routes when powered by renewable electricity. US Gulf Coast mills leverage abundant domestic scrap and low natural gas prices to undercut imported billet on rebar and wire rod.
- Basic Oxygen Furnace:Molten pig iron refinement with oxygen injection produces high-purity grades for automotive exposed panels and tinplate. Chinese BOF operators in Jiangsu province face MEE carbon intensity benchmarks forcing partial EAF hybridization.
- Blast Furnace:Coke-fueled iron ore reduction remains the dominant mass production route for virgin steel output.
- Open Hearth Furnace:Obsolete regenerative melting technology persists only in legacy installations awaiting capital replacement.
Blast furnace output dominates volume; EAF expansion is climbing the fastest.
End User:
Specification stringency and contract duration vary sharply across buyer categories.
- Construction:Rebar and structural steel buyers prioritize delivery reliability and mill proximity over metallurgical refinement. Indian contractors in Delhi-Mumbai Industrial Corridor projects are locking three-year offtake contracts with JSW and Tata to secure volume amid capacity constraints.
- Automotive:OEM stamping operations demand interstitial-free grades with ultra-low carbon content for complex draw forming. German manufacturers are qualifying Swedish hydrogen-reduced steel for hood and door applications under Scope 3 emissions accounting rules.
- Appliances:Cold-rolled and coated sheet buyers balance corrosion resistance against deep-draw formability for refrigerator and washing machine panels.
- Manufacturing:General machinery and equipment producers source standard grades through distributors with limited specification customization.
Construction commands the largest volume share; automotive specifications are gaining share fastest.
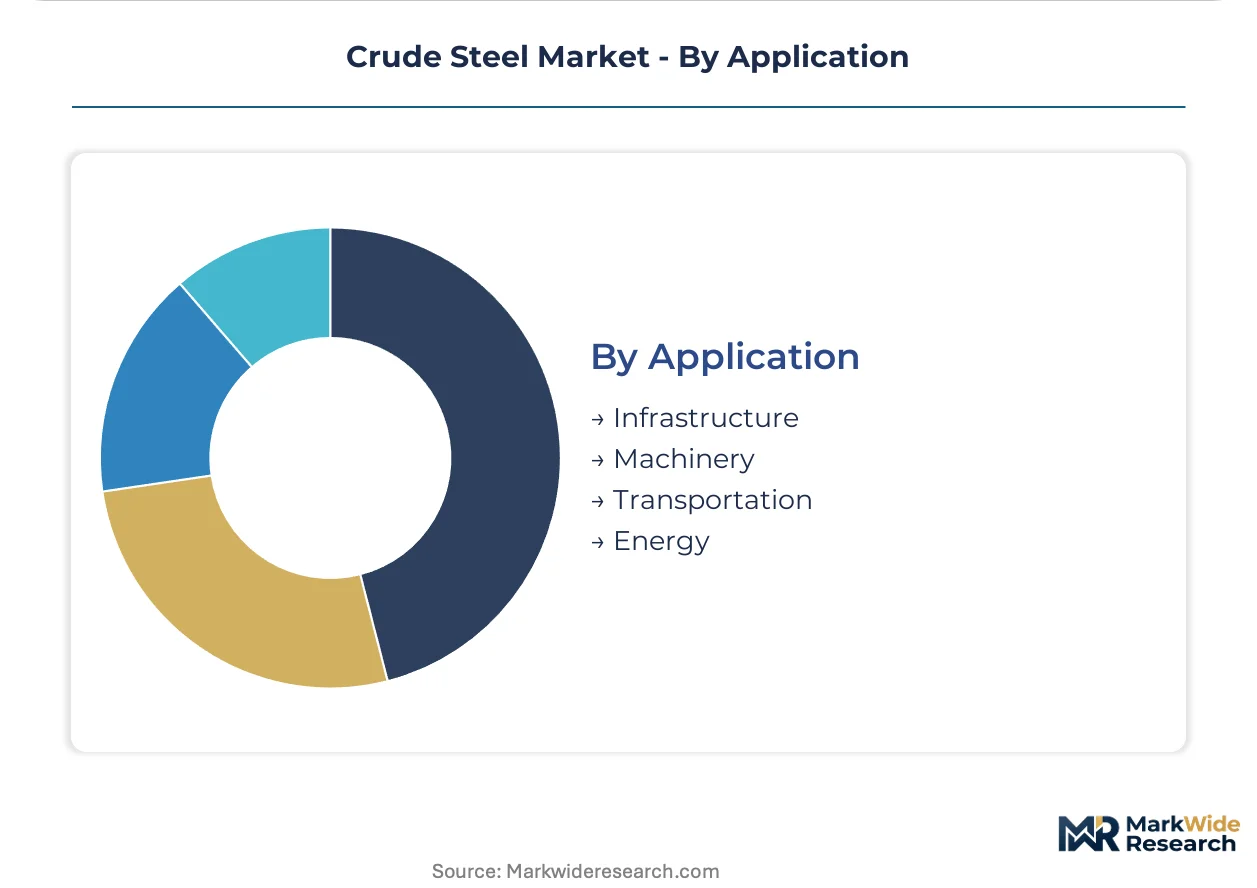
Application:
Performance requirements and regulatory exposure shape grade selection across use cases.
- Infrastructure:Bridge decks, tunnels, and water treatment facilities demand high-strength low-alloy grades with atmospheric corrosion resistance. Brazilian federal procurement under PAC infrastructure programs is specifying quenched and tempered plate for suspension bridge cable anchors.
- Machinery:Forgings, castings, and engineered components require controlled sulfur and phosphorus levels for fatigue resistance. Japanese machine tool builders in Aichi prefecture are sourcing vacuum-degassed billet for precision spindle applications.
- Transportation:Rail, shipbuilding, and aerospace structures utilize specialized grades with fracture toughness certification.
- Energy:Pipeline, wind tower, and pressure vessel applications require sour gas resistance and low-temperature impact properties.
Infrastructure absorbs the heaviest tonnage; energy sector specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara region and coking coal seams in Queensland anchor Asia-Pacific supply chains. Brazilian Carajás ore feeds Atlantic basin mills. Scrap collection networks in the US Great Lakes and Rhine-Ruhr corridor determine electric arc furnace economics.
China
Hebei and Jiangsu provinces host the densest blast furnace clusters serving domestic construction and automotive stamping. MEE provincial output caps force capacity swaps requiring EAF replacement ratios. Tangshan steelmakers retrofitting with hydrogen-ready direct reduction units face compressed commissioning timelines.
India
Maharashtra and Gujarat absorb merchant bar volumes as metro rail and highway expansion accelerates. CEA energy consumption norms tighten compliance costs for designated consumers including integrated steel plants. JSW Steel and Tata Steel Group add greenfield capacity in Odisha to serve Delhi-Mumbai Industrial Corridor projects.
United States
Gulf Coast mills leverage abundant domestic scrap and low natural gas prices to undercut imported billet on rebar and wire rod. EPA Clean Air Act emissions limits affect integrated mill operations in the Great Lakes region. Nucor and Steel Dynamics expand EAF sheet capacity in Texas to capture appliance and automotive demand.
Germany
ThyssenKrupp and Salzgitter pilot hydrogen-reduced steel for automotive body-in-white applications under Scope 3 emissions accounting rules. EU Carbon Border Adjustment Mechanism implementation rewards early EAF adopters with verified low-carbon intensity production. Duisburg-Ruhrort remains Europe's largest inland steel port handling slab and coil transshipment.
Japan
Kansai and Chubu prefectures concentrate specialty sheet production for precision automotive and machinery applications. METI supports hydrogen direct reduction pilot installations converging with carbon capture utilization systems. Nippon Steel Corporation commands premium pricing for interstitial-free grades with ultra-low carbon content.
Crude Steel Market Vendor Landscape
Capacity expansion dominates the current landscape as mills race to capture greenfield opportunities before policy windows close. The vendor base clusters around three tiers: state-backed Chinese producers with captive ore access, diversified Atlantic basin operators serving automotive OEMs, and scrap-fed regional specialists in deregulated electricity markets. Strategic archetypes include integrated blast furnace operators defending flat steel positions, electric arc furnace pure-plays exploiting scrap arbitrage, and hydrogen reduction pioneers securing automotive offtake contracts. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among state-backed Asian producers, China Baowu Group exemplifies the integrated archetype with Australian and Brazilian ore positions. ArcelorMittal anchors the diversified Atlantic footprint serving European and North American flat steel customers. Nippon Steel Corporation occupies the premium automotive-grade specialization tier. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| POSCO |
| Ansteel Group |
| China Baowu Group |
| JSW Steel |
| Tata Steel Group |
| ArcelorMittal |
| HBIS Group |
| NLMK |
| Nippon Steel Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers with captive mining positions anchor supply discipline through long-term offtake contracts that insulate pricing from spot volatility. This ownership pattern concentrates pricing power among integrated operators while fragmenting procurement leverage for merchant buyers dependent on seaborne markets.
Pricing Analysis
Service bundling separates contract structures in crude steel procurement. Long-term offtake agreements dominate volume transactions, embedding technical support and logistics coordination within base pricing. Automotive-grade sheet commands premium positioning through ISO 14064 carbon verification and tighter dimensional tolerances. Price differentiation rests on certification tier and volume scale, with construction rebar buyers exhibiting highest sensitivity to delivered cost fluctuations. Cost compression in commodity flat products is intensifying as Chinese MEE output caps redirect surplus tonnage toward export markets.
Supply Chain Analysis
Skilled commissioning engineers for large-scale electric arc furnace transformers concentrate in Germany, Japan, and the US Great Lakes corridor. Raw material flows draw from Australian Pilbara iron ore, Queensland coking coal, and US domestic scrap collection networks. Single-source vulnerability persists in premium hard coking coal sourcing from concentrated seaborne suppliers. Distribution runs through integrated mill-direct channels for automotive OEMs and steel service centers serving construction and appliance fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Carbon Border Adjustment Mechanism compliance costs erect a barrier-to-entry moat favoring mills with verified low-carbon production, forcing capital-heavy certification investments that disadvantage marginal operators.
For Market Incumbents: Acquire hydrogen direct reduction pilot installations to secure automotive offtake positioning before qualification timelines compress. Backward integration into captive iron ore mining in Australia or Brazil defends margin stability against metallurgical coal price volatility. Prioritize EAF transformer engineering talent retention as the specialist cohort shrinks.
For New Entrants and Emerging Players: Steel service centers offer channel access for precision slitting and blanking capabilities targeting battery enclosure and motor lamination specifications. Vietnam's underpenetrated flat steel market presents white-space opportunity as domestic appliance manufacturing outpaces local cold-rolling capacity. Pursue automotive tier-1 stamper partnerships rather than direct OEM qualification.
For Investors and Strategic Acquirers: Distressed-cycle entries favor scrap-fed regional specialists in deregulated US electricity markets with renewable power purchase agreements. Five-to-ten year viability hinges on carbon intensity verification capabilities for EU export eligibility. Monitor hydrogen-based reduction cost curves as inflection indicator for technology substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Australian and Brazilian ore positions insulate China Baowu Group from seaborne price volatility cycles. |
| Hydrogen Direct Reduction Scale-Up | ThyssenKrupp pilot installations secure ten-year automotive offtake contracts under German Scope 3 rules. |
| EAF Capacity Expansion | Nucor and Steel Dynamics Texas sheet mills capture appliance demand using Gulf Coast scrap and gas economics. |
| Carbon Verification Investment | ISO 14064 certification preempts EU CBAM border charges for Hebei province flat steel exporters. |
| Steel Service Center Consolidation | Tier-1 stamper volume aggregation through just-in-time slitting displaces legacy mill-direct relationships. |
Methodological Framework
Document review covered customs trade databases, SEC filings from integrated producers, and IEA steel sector outlooks, complemented by interviews with blast furnace operations managers, electric arc furnace procurement leads, automotive OEM stamping engineers, and steel service center distribution heads. Secondary validation drew from China MEE provincial output filings, EU ETS transaction registries, and India CEA energy consumption reports. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-level projections across production technology, product form, and end-use application fed aggregate market sizing over the projection horizon. CAGRs derived from regression against historical capacity utilization, policy implementation schedules, and scrap-to-virgin price spreads. Modeled inputs included MEE provincial cap enforcement trajectories, PLI scheme disbursement pacing, and hydrogen reduction cost learning curves.
Several conditions sit outside the modeled scope, including unannounced blast furnace relining outages, abrupt scrap export restriction policies, and breakthrough DRI-HBI technology cost reductions. Forecasts assume documented policy implementation timelines and commodity price band stability. Material deviation in Chinese MEE enforcement intensity or EU CBAM phase-in acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Electrolytic Iron Market
Metals
Palladium Market
Metals
Galvanized Steel Coil Market
Metals
Ore Metals Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Aluminum Scrap Recycling Market
Metals
Bismuth Market
Metals
Steel Casting Market
Metals
Wear Steel Plate Market
Metals
Global Flat Steel Market
Metals
India Steel Market
Metals
Aluminium Conductors Market
Metals
Ferrochrome Market
Metals
Europe Aluminium Powder Market
Metals
GCC Metal Forging Market
Metals
Copper Azoles Market