
 Global Flat Carbon Steel Market | 2026-2036
Global Flat Carbon Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flat Carbon Steel Market Foresight
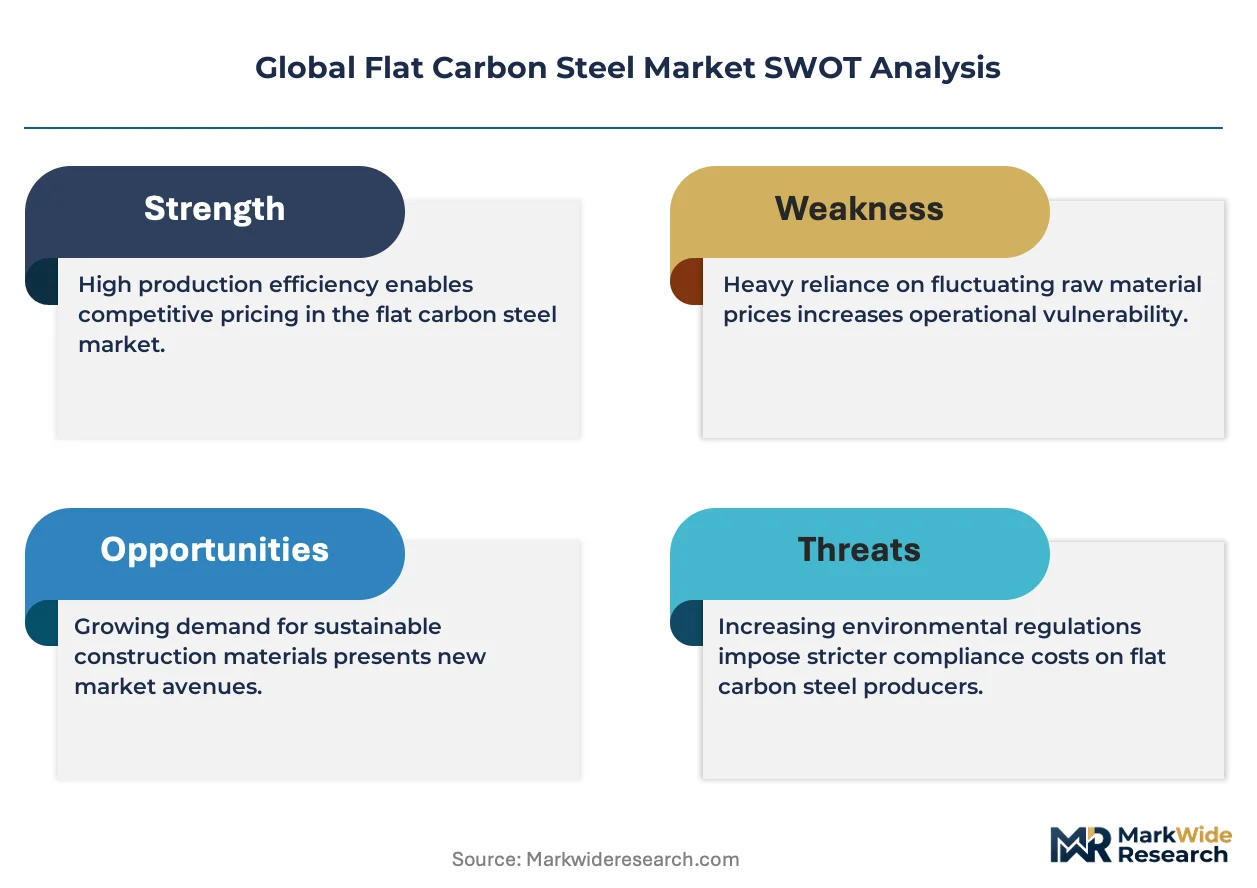
Modular coil-to-sheet processing is hardening as the dominant procurement configuration, letting buyers split large-tonnage orders across multiple downstream fabricators. ArcelorMittal leverages its integrated European network to supply pre-cut blanks directly to automotive stamping plants. Tata Steel anchors South Asian demand through its captive port facilities and slab-to-coil continuity. Nippon Steel Corporation differentiates via ultra-low-carbon sheet grades engineered for hydrogen-ready pipeline applications.
Flat carbon steel comprises rolled products under 6 mm thickness, containing 0.05% to 2.0% carbon by weight, produced through continuous hot or cold reduction of cast slabs for structural and forming applications. Hot rolled steel dominates tonnage flows into construction and shipbuilding, where yield strength and weldability govern specification. Cold rolled steel commands premium positioning in electrical appliances and precision manufacturing, where tighter dimensional tolerances justify higher unit economics. Galvanized steel is gaining share in infrastructure and consumer goods, as zinc coating extends service life in corrosive environments.
China's MEE enforces dual carbon goals that cap emissions intensity per tonne of crude steel output, while the EU's CBAM imposes embodied-carbon tariffs on imported flat products from 2026. India's BIS mandates IS 2062 compliance for structural steel used in public infrastructure, creating a certification barrier for uncertified foreign mills. Stakeholders must monitor how divergent carbon-accounting rules across Beijing, Brussels, and New Delhi reshape sourcing arbitrage and capital allocation for new rolling capacity.
Market Dynamics
Carbon border tariffs are rewiring sourcing decisions for flat carbon steel buyers, forcing mills to reconfigure supply chains around embodied-carbon accounting rather than pure unit cost.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers into the European Union must now document emissions intensity per tonne, creating certified-low-carbon premium tiers that reward integrated mills with blast furnace gas capture.
- Automotive lightweighting mandates:OEMs in Germany and South Korea are specifying advanced high-strength grades for electric vehicle platforms, pulling demand toward thinner-gauge, higher-yield products.
- India's western industrial corridor:Infrastructure firms and machinery producers in Gujarat and Maharashtra are scaling sheet and coil consumption for port, road, and renewable energy fabrication.
Market Restraints
- Iron ore and coking coal volatility:Input cost swings compress rolling margins unpredictably, especially for non-integrated mills dependent on spot seaborne raw materials.
- Supply concentration in coastal China:Over half of global flat steel capacity sits within three provinces, exposing buyers to concentrated logistics disruption and policy shock risk.
- Scrap-based electric arc furnace limitations:EAF output cannot yet match integrated mill quality for certain automotive exposed-panel grades, constraining decarbonization pathways.
Strategic Opportunities
- Vietnam and Indonesia fabrication demand:Shipbuilding and appliance manufacturing clusters in Haiphong and Batam are absorbing cold-rolled and galvanized tonnage as regional import substitution accelerates.
- Hydrogen-ready pipeline specifications:Transmission operators in the Netherlands and the United Kingdom are pre-qualifying ultra-low-carbon sheet grades for retrofitted natural gas infrastructure.
- Modular coil-to-sheet processing:Buyers are splitting large-tonnage orders across multiple downstream fabricators, creating service-center consolidation opportunities for logistics-integrated distributors.
Industry Challenges
- Carbon-accounting talent scarcity:Mills lack sufficient lifecycle assessment specialists to meet divergent Beijing, Brussels, and New Delhi disclosure requirements simultaneously.
- Legacy blast furnace asset stranding:Multi-billion dollar basic oxygen furnace complexes face accelerated depreciation risk as hydrogen-direct-reduction pilot plants reach industrial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flat Carbon Steel Market |
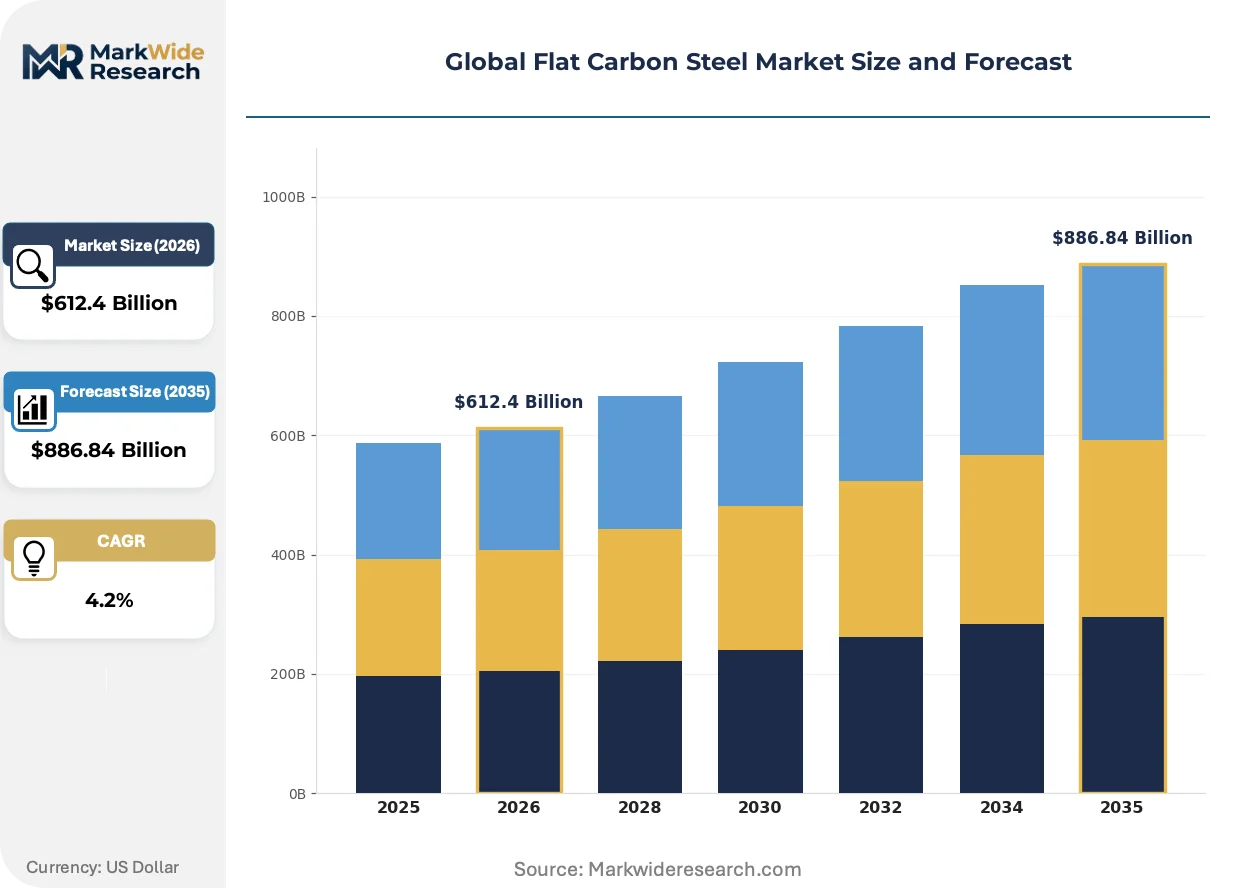
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $886.84 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Steel, Cold Rolled Steel, Galvanized Steel, Electro-galvanized Steel, Tinplate Application: Construction, Shipbuilding, Manufacturing, Electrical Appliances, Packaging End User Industry: Infrastructure Firms, Maritime Fabricators, Machinery Producers, Electronics Manufacturers, Consumer Goods Makers Form: Sheets, Coils, Plates, Strips |
| Companies Covered | China Baowu Steel Group, ArcelorMittal, Nippon Steel Corporation, Tata Steel, POSCO, ThyssenKrupp, JFE Steel Corporation, HBIS Group, Voestalpine Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flat Carbon Steel Market Shifts & Advancements
Digital process control and low-carbon metallurgy are converging to redefine quality premiums and supplier qualification criteria across end-use verticals.
Direct reduced iron-electric arc furnace (DRI-EAF) production is overtaking conventional blast furnace-basic oxygen furnace routes for new capacity investments. European automotive stamping plants are qualifying DRI-EAF sheet for exposed body panels at accelerated timelines. This shift is compressing the cost premium between low-carbon and conventional grades faster than most procurement forecasts anticipated.
China's Ministry of Ecology and Environment enforces dual carbon goals that cap emissions intensity per tonne of crude steel output. The regulation forces provincial governments to ration production permits during peak demand periods. Export-oriented mills in Jiangsu and Shandong are responding by installing waste heat recovery and coke dry quenching systems to maintain volume allocations.
Buyers are consolidating vendor lists around mills that can deliver pre-cut blanks directly to stamping plants, bypassing traditional service center intermediation. Automotive OEMs in Germany and South Korea are driving this consolidation through just-in-sequence contracts that penalize dimensional variance. The tightest supplier qualification windows are now operating in the Stuttgart manufacturing cluster and the Ulsan shipbuilding complex.
Global Flat Carbon Steel Market Segmentation
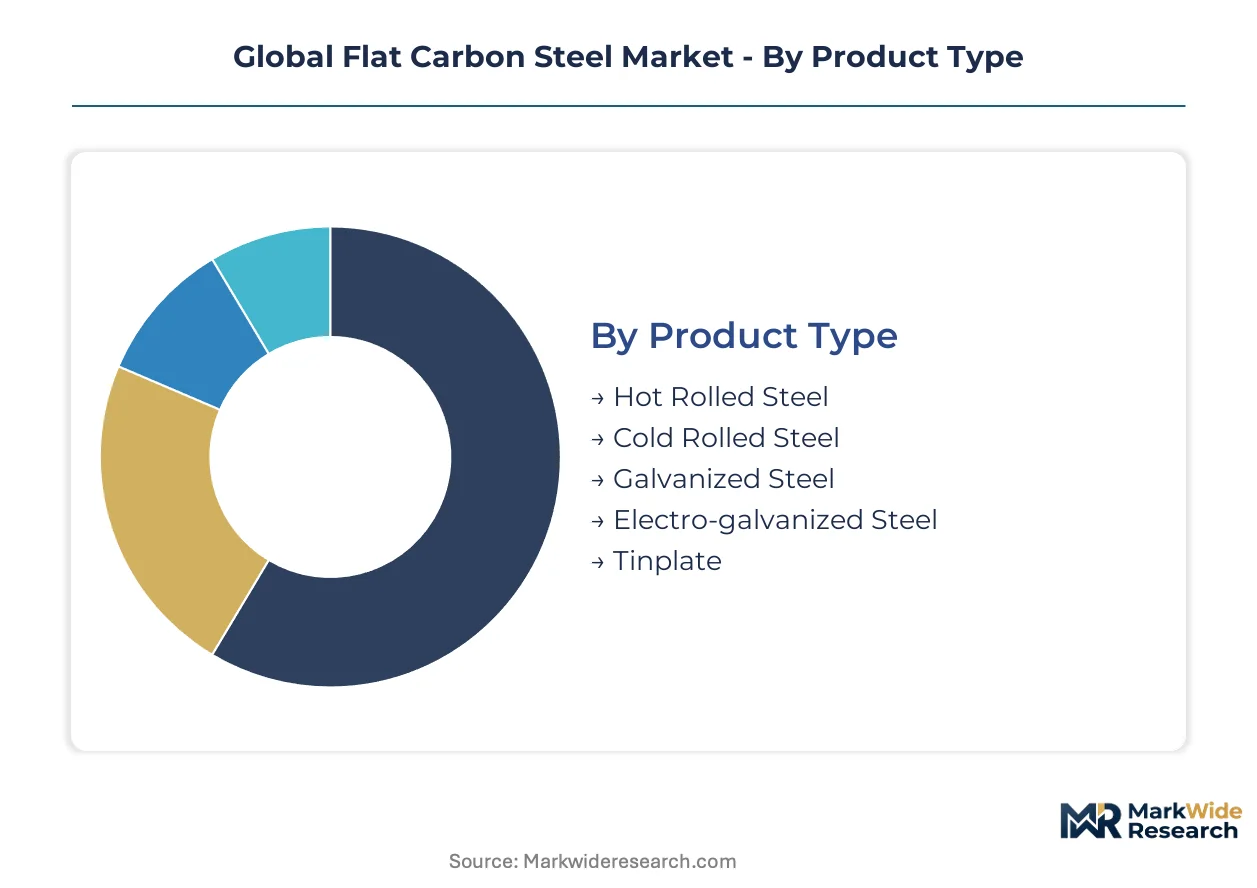
Procurement patterns in flat carbon steel diverge sharply across product grades and end-use specifications. Buyers optimize around yield strength requirements, corrosion resistance, and forming tolerances rather than commodity pricing alone.
Product Type:
Cost tier determines supplier qualification depth and contract structure across the five product categories.
- Hot Rolled Steel:Produced through continuous casting and hot reduction above recrystallization temperature, yielding 235-355 MPa tensile strength with oxide scale surface finish. Construction firms in India's western corridor and shipyards in South Korea absorb bulk tonnage for structural framing and hull assembly, driven by weldability mandates and speed-to-fabrication requirements.
- Cold Rolled Steel:Annealed and temper-rolled below transformation temperature to achieve tighter dimensional tolerances and superior surface quality. Automotive stamping plants in Germany specify advanced high-strength cold-rolled grades for electric vehicle body-in-white components, pulled by lightweighting targets and crash-performance standards.
- Galvanized Steel:Zinc-coated through hot-dip or continuous galvanizing lines to extend service life in corrosive environments. Infrastructure contractors in the Netherlands specify galvanized sheet for hydrogen-ready pipeline retrofits, responding to transmission operator pre-qualification protocols.
- Electro-galvanized Steel:Thin zinc deposition via electrolytic process for precision-coated applications requiring uniform thickness control. Electronics manufacturers in Japan favor electro-galvanized substrate for appliance enclosures and precision hardware.
- Tinplate:Thin low-carbon sheet with tin coating for food and beverage packaging applications. Canning facilities in Vietnam and Indonesia scale tinplate procurement as regional consumer goods manufacturing expands.
Volume sits with hot rolled grades; growth tilts toward cold-rolled and galvanized specifications.
Application:
Application scope dictates metallurgical complexity and certification burden rather than pure tonnage economics.
- Construction:Structural framing, roofing, and reinforcement applications consuming standard-grade hot-rolled sections. India's BIS mandates IS 2062 compliance for public infrastructure projects, creating certification barriers for uncertified foreign mills.
- Shipbuilding:Hull plate, deck structures, and marine-grade sections requiring high toughness at low temperatures. Maritime fabricators in South Korea and Vietnam drive specification toward thermomechanically processed grades with through-thickness ductility.
- Manufacturing:General industrial fabrication spanning machinery bases, material handling equipment, and process vessels. Machinery producers in Gujarat and Maharashtra scale sheet and coil consumption for port and renewable energy fabrication.
- Electrical Appliances:Motor laminations, transformer cores, and appliance enclosures demanding precise magnetic properties or cosmetic surfaces. Cold-rolled non-oriented electrical steel commands premium positioning in this segment.
- Packaging:Food cans, aerosol containers, and industrial closures requiring corrosion resistance and formability. Regional import substitution in Southeast Asia accelerates tinplate and TFS (tin-free steel) absorption.
Construction commands absolute tonnage; manufacturing and electrical appliances are expanding most quickly.
End User Industry:
Customer type shapes service-level requirements from mill-direct delivery to modular coil-to-sheet distribution.
- Infrastructure Firms:Large-scale contractors procuring certified structural grades for bridges, ports, and energy installations. These buyers consolidate vendor lists around mills with captive port facilities and slab-to-coil continuity.
- Maritime Fabricators:Shipyards and offshore constructors requiring mill test certificates and traceability documentation. Classification society approvals from Lloyd's Register and DNV govern supplier qualification.
- Machinery Producers:Capital equipment manufacturers sourcing pre-cut blanks and precision-rolled sections. German automotive OEMs drive just-in-sequence contracts that penalize dimensional variance.
- Electronics Manufacturers:Appliance and component makers specifying surface-critical cold-rolled and coated grades. These buyers prioritize coil-to-coil consistency over absolute yield strength.
- Consumer Goods Makers:Packaging converters and durable goods producers absorbing tinplate and light-gauge coated products. Regional fabrication clusters in Batam and Haiphong anchor demand growth.
Infrastructure firms dominate procurement scale; machinery producers and electronics manufacturers are gaining share fastest.
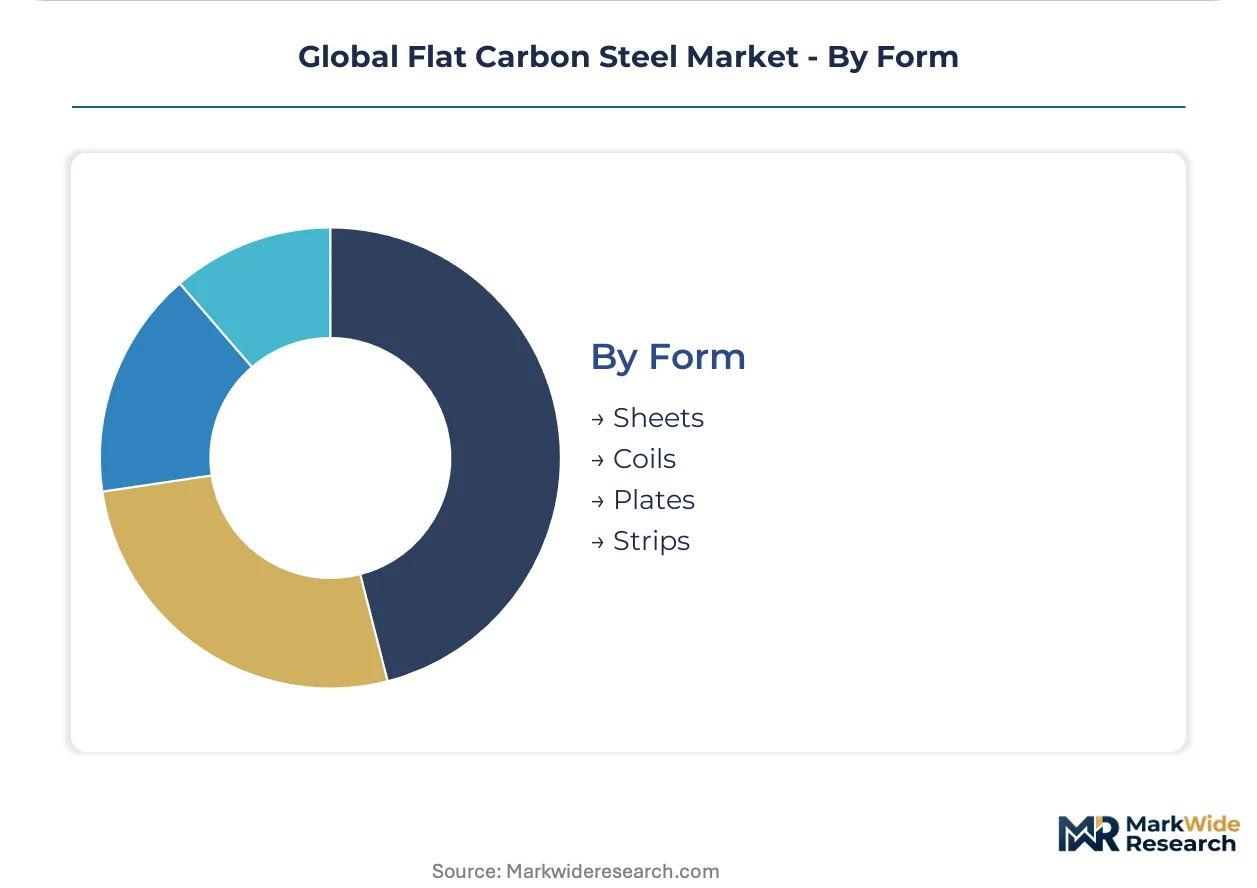
Form:
Physical configuration determines logistics economics and downstream processing requirements.
- Sheets:Flat-rolled product cut to rectangular dimensions for stamping, bending, and fabrication. Automotive stamping plants in Stuttgart and Ulsan qualify sheet suppliers through tightest dimensional variance windows.
- Coils:Continuous wound strip enabling efficient transport and automated feed into processing lines. Coil form supports modular coil-to-sheet processing configurations that split large orders across multiple fabricators.
- Plates:Thicker flat product above 6mm threshold, technically outside flat carbon steel definition but overlapping in heavy-gauge applications. Shipyards specify normalized or thermomechanically rolled plate for hull structures.
- Strips:Narrow-width coil product slit from master coils for specific width requirements. Precision strip serves electronics and small-appliance manufacturing with minimal edge trim waste.
Coils dominate transport efficiency; sheets command premium positioning in precision end-uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces roughly half of global flat carbon steel output yet consumes the majority domestically, while Germany and India import specialized grades their domestic mills cannot economically roll. This production-consumption mismatch shapes cross-border trade flows and investment location decisions.
China
Jiangsu and Shandong provinces host export-oriented mills supplying Southeast Asian fabrication clusters. The Ministry of Ecology and Environment enforces dual carbon goals that cap emissions intensity per tonne of crude steel output, forcing provincial governments to ration production permits during peak demand periods. Mills in these coastal provinces respond by installing waste heat recovery systems to maintain volume allocations.
Germany
Automotive OEMs in the Stuttgart manufacturing cluster specify advanced high-strength cold-rolled grades for electric vehicle body-in-white components. The EU's Carbon Border Adjustment Mechanism imposes embodied-carbon tariffs on imported flat products from 2026, rewarding integrated mills with blast furnace gas capture. ThyssenKrupp anchors the Ruhr industrial basin with direct reduction pilot plants targeting hydrogen-ready steel output.
India
Infrastructure firms and machinery producers in Gujarat and Maharashtra scale sheet and coil consumption for port, road, and renewable energy fabrication. The Bureau of Indian Standards mandates IS 2062 compliance for structural steel used in public infrastructure, creating certification barriers for uncertified foreign mills. Tata Steel leverages captive port facilities at Jamshedpur and Kalinganagar to maintain slab-to-coil continuity.
South Korea
Shipyards in the Ulsan shipbuilding complex drive specification toward thermomechanically processed grades with through-thickness ductility. The Ministry of Trade, Industry and Energy supports domestic mill modernization through low-carbon steel R&D programs. POSCO supplies the Busan-Ulsan maritime corridor with mill test certificates meeting Lloyd's Register and DNV classification society approvals.
Vietnam
Shipbuilding and appliance manufacturing clusters in Haiphong absorb cold-rolled and galvanized tonnage as regional import substitution accelerates. The country's national industrial regulator implements steel quality standards aligned with ASEAN harmonization protocols. Fabricators in northern industrial zones process imported Chinese coils into finished components for re-export to European consumer goods markets.
Global Flat Carbon Steel Market Competitive Landscape
The competitive structure tilts toward integrated multinational producers with captive raw material access and coastal logistics infrastructure. Tier-one positions concentrate around blast furnace-basic oxygen furnace complexes with downstream cold rolling and coating lines. Three archetypes dominate: state-backed Chinese champions with domestic volume scale, European-Japanese quality specialists serving automotive exposed-panel grades, and Indian-Korean integrated players with port-adjacent slab capacity. Dominant competitive moves include hydrogen-direct-reduction pilot investments and just-in-sequence contract structures that bypass traditional service center intermediation.
Within the state-backed champion archetype, China Baowu Steel Group and HBIS Group represent production scale positions anchored in coastal province industrial clusters. Among quality-specialist integrated producers, ArcelorMittal occupies a position exemplifying European network coordination for pre-cut blank delivery to automotive stamping plants. Nippon Steel Corporation sits within the ultra-low-carbon grade segment, representing hydrogen-ready pipeline qualification capabilities developed for Netherlands and United Kingdom transmission operator protocols.
| Leading Market Players |
|---|
| China Baowu Steel Group |
| ArcelorMittal |
| Nippon Steel Corporation |
| Tata Steel |
| POSCO |
| ThyssenKrupp |
| JFE Steel Corporation |
| HBIS Group |
| Voestalpine Group |
| Others |
Supply & Pricing Matrix
The EU's Carbon Border Adjustment Mechanism gates qualified supply and premium-tier pricing access for flat carbon steel buyers, as mills lacking blast furnace gas capture face tariff exposure while certified-low-carbon producers command contract premiums from automotive OEMs and infrastructure firms.
Pricing Analysis
Margin tightening in premium-grade cold-rolled sheet reflects iron ore and coking coal volatility compressing rolling margins for non-integrated mills. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with German automotive OEMs showing least price sensitivity for just-in-sequence contracts while Indian infrastructure contractors drive hardest bargain on hot-rolled structural grades.
Supply Chain Analysis
Direct-to-automotive channels handle hyperscale OEM demand through mill-direct pre-cut blank delivery, bypassing traditional service center intermediation. Supply concentrates in China, India, and South Korea, with raw material flows drawing from Australian iron ore, Mongolian coking coal, and Indonesian nickel for specialized grades. Single-source vulnerability in coastal Chinese provinces exposes buyers to concentrated logistics disruption risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat carbon steel markets are becoming a vertical-integration race, with blast furnace gas capture and hydrogen-direct-reduction pilot investments emerging as the decisive upstream levers separating premium-tier suppliers from margin-compressed commodity players.
For Market Incumbents: Acquire hydrogen-direct-reduction pilot assets and waste heat recovery systems to defend against carbon-border tariff exposure and scrap-based EAF substitution threats. Consolidate around captive port facilities and slab-to-coil continuity to lock in infrastructure and maritime fabricator contracts. For New Entrants and Emerging Players: Launch via modular coil-to-sheet processing partnerships targeting Vietnam and Indonesia fabrication clusters, where shipbuilding and appliance manufacturing absorb cold-rolled and galvanized tonnage. Penetrate through regional import substitution acceleration and logistics-integrated distributor consolidation. For Investors and Strategic Acquirers: ThyssenKrupp's direct reduction pilot reaching industrial scale is the leading indicator that hydrogen-ready steel output will separate viable acquisition targets from stranded blast furnace assets. Target integrated mills with coastal logistics infrastructure and automotive qualification timelines over pure volume scale positions.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Furnace Gas Capture Installation | Enables EU CBAM compliance and premium-tier contract access for German automotive OEMs. |
| Hydrogen-Direct-Reduction Pilot Investment | Positions mills for Netherlands and United Kingdom hydrogen-ready pipeline specifications. |
| Captive Port Facility Development | Secures slab-to-coil continuity for Tata Steel and POSCO in Indian and Korean markets. |
| Just-in-Sequence Contract Structure | Bypasses service center intermediation for Stuttgart and Ulsan automotive stamping plants. |
| Modular Coil-to-Sheet Processing Partnership | Captures service-center consolidation opportunities in Vietnam and Indonesia fabrication clusters. |
Research Methodology
Document review covered trade customs data, SEC filings from listed steel producers, and BIS certification registries, complemented by interviews with procurement directors at German automotive OEMs, plant managers at Indian integrated mills, and classification society surveyors at Lloyd's Register and DNV. Primary fieldwork with downstream fabricators in Gujarat and Maharashtra was triangulated against secondary sources including IEA steel sector reports and EIA industrial energy consumption data.
Cross-referencing historical production capacity expansions against panel input from platform engineering and procurement specialists established the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, and regional regulatory cluster, with CAGRs derived from capacity utilization trends and embodied-carbon accounting rule divergence between Beijing, Brussels, and New Delhi.
The model assumes a particular technology adoption path for hydrogen-direct-reduction; alternative pathways for scrap-based EAF quality advancement would alter the outlook for automotive exposed-panel grade supply. Forecasts reflect assumptions around carbon-border tariff implementation timing and provincial production permit rationing enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Electrodeposited Copper Foil Market
Metals
Aluminum Extrusion Market
Metals
Steel Sheet for Home Appliances Market
Metals
Seamless Stainless Steel Products Market
Metals
Copper Chromium Black Market
Metals
United States Metal Casting Market
Metals
Rubidium Market
Metals
Silver Powder and Flakes Market
Metals
Rolled Steel Motor Market
Metals
Global Copper Sputtering Target Market
Metals
Stainless Steel Foil Market
Metals
316 Stainless Steel Container Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Global Aluminum Extruded Products Market
Metals
Europe Welding Consumables Market
Metals
Steel Long Products Market