
 Aluminium Powder Market | 2026-2036
Aluminium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Powder Market Analysis
Buyer concentration in the aerospace and automotive sectors is shifting as tier-one suppliers consolidate qualified powder vendors into narrower approved-source lists. Alcoa leverages captive bauxite-to-powder integration to secure supply certainty for additive manufacturing clients. Kymera International anchors its position through specialized atomization capabilities serving defense and space alloy programs. Toyal Group differentiates via flake powder expertise for coatings and chemical applications across Asia-Pacific industrial clusters.
Aluminium powder consists of finely divided metallic aluminium particles produced through atomization or milling, typically ranging from 1 to 200 microns in diameter, with atomized grades offering spherical morphology optimized for sintering and thermal spray processes. Its primary commercial purpose centers on providing reactive metal feedstock for solid rocket propellants, powder metallurgy parts, and surface coating systems requiring thermal reflectivity or corrosion resistance. Atomized aluminium powder leads volume due to additive manufacturing qualification momentum, while flake aluminium powder commands margin concentration in automotive and industrial coating formulations. Gas atomization technology captures investment focus as producers seek tighter particle size distribution for aerospace specification compliance.
EPA particulate matter standards and OSHA combustible dust regulations constrain US production facility siting and operational permitting, elevating capital costs for domestic atomization capacity. REACH registration requirements and the EU Green Deal embodied-carbon tracking framework shape European import sourcing decisions toward low-carbon primary aluminium feedstock. China's GB standards and dual carbon goals from MEE pressure local producers to transition energy-intensive milling operations toward renewable-powered atomization systems. Stakeholders must monitor evolving aerospace material qualification protocols and carbon border adjustment mechanisms to align capacity investments with forthcoming specification and trade compliance requirements.
Market Dynamics
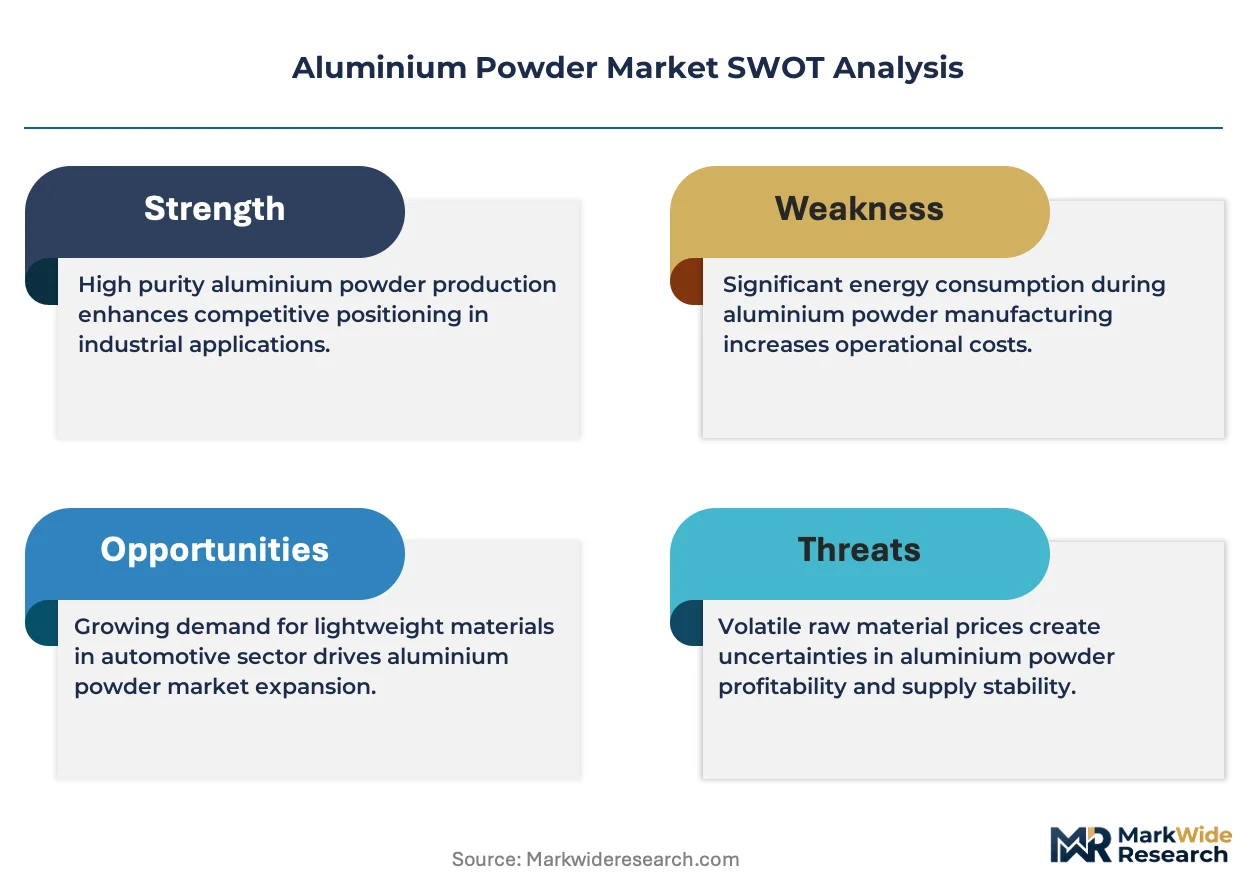
Gas atomization capacity expansion is concentrating supplier power among producers capable of meeting aerospace particle size distribution specifications, while REACH and EPA particulate standards simultaneously elevate purity barriers for cross-border trade.
Growth Catalysts
- Additive manufacturing feedstock qualification:Aerospace OEMs are mandating atomized spherical powders for laser powder bed fusion processes, pulling capacity toward certified suppliers.
- REACH compliance deadlines:ECHA registration requirements for aluminium powder imports are filtering out uncertified traders and consolidating volume with registered producers.
- China's dual carbon transition:MEE pressure on energy-intensive milling operations is accelerating gas atomization adoption in Shandong and Henan provinces.
Market Restraints
- Primary aluminium price volatility:LME aluminium fluctuations transmit directly to powder production economics, compressing margins for non-integrated atomizers.
- China supply concentration:Over sixty percent of global flake powder milling capacity sits in Chinese industrial clusters, creating single-source exposure for coating formulators.
- Combustible dust liability:OSHA enforcement of NFPA 652 standards is constraining US greenfield atomization facility permitting and extending commissioning timelines.
Strategic Opportunities
- India defense aerospace expansion:DRDO solid propellant programs and ISRO launch vehicle production are creating qualified-supplier vacancies for spherical atomized grades.
- EU carbon border adjustment mechanism:CBAM implementation is incentivizing low-carbon primary aluminium feedstock sourcing for European powder producers.
- Digital alloy qualification platforms:Convergence of computational thermodynamics with in-situ process monitoring is compressing aerospace material certification cycles.
Industry Challenges
- Atomization metallurgist scarcity:Deep expertise in gas flow dynamics and powder morphology control is concentrated among retiring specialists at legacy defense contractors.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of AMS, ASTM, and GB standards for aerospace and automotive qualification is extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Powder Market |
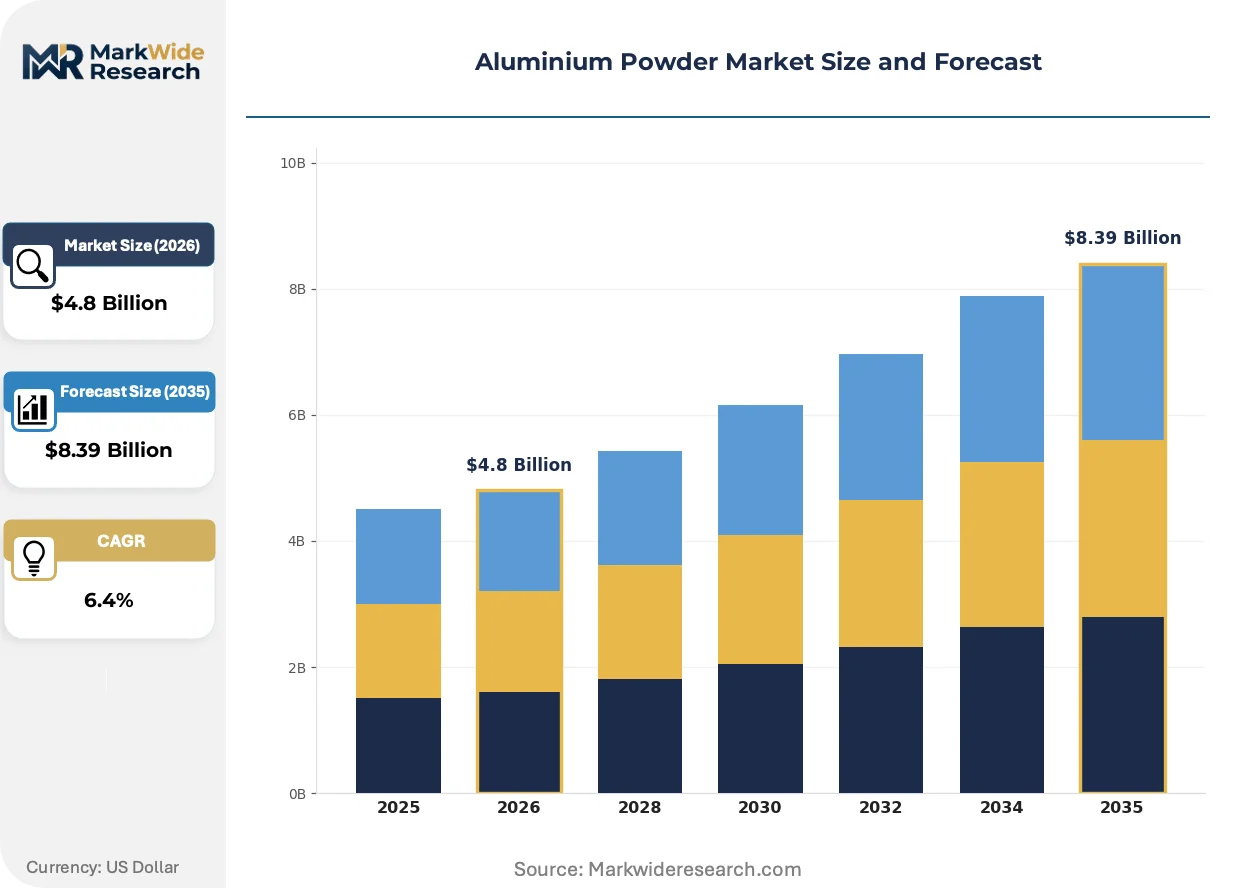
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Aluminium Powder, Flake Aluminium Powder, Granulated Aluminium Powder, Aluminium Powder Coating Application: Aerospace, Automotive, Electrical, Building & Construction Technology: Mechanical Milling, Chemical Vapor Deposition, Electrochemical Deposition, Gas Atomization End User: Manufacturers, Distributors, Research Institutions, Alloy Producers |
| Companies Covered | Alcoa, Kymera International, Toyal Group, Valimet, Metal Powder Company, Zhangqiu Metallic Pigment, AMG Advanced Metallurgical Group, Hoganas AB, Henan Yuanyang Powder Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Powder Market Emerging Trajectories
Plasma spheroidization and closed-loop atomization systems are reshaping powder morphology control, while regulatory carbon tracking and buyer consolidation are restructuring supplier qualification protocols across end-use verticals.
Ultrasonic atomization is expanding into high-purity aluminium powder production for electronics packaging and thermal interface materials. Semiconductor fabricators in Taiwan and South Korea are qualifying these grades for flip-chip bonding applications at accelerated sampling rates. The technology is expanding into markets previously served by air-atomized powders by delivering tighter oxygen content control.
REACH Annex XVII restrictions on aluminium powder classification are compelling European importers to document particle size distribution and surface oxide thickness for every shipment. ECHA enforcement actions against non-compliant traders have redirected sourcing toward registered producers with full substance data sets. Coating formulators in Germany and Italy are absorbing compliance costs through qualified-supplier premiums.
Consolidated procurement through approved-source lists is compressing vendor counts at tier-one aerospace and automotive suppliers. Buyers are unbundling technical service from powder supply and contracting directly with atomization specialists for alloy development. This pattern is most pronounced in Germany's automotive supply chain, where coating divisions now maintain single-source relationships with qualified flake powder mills.
Aluminium Powder Market Segmentation
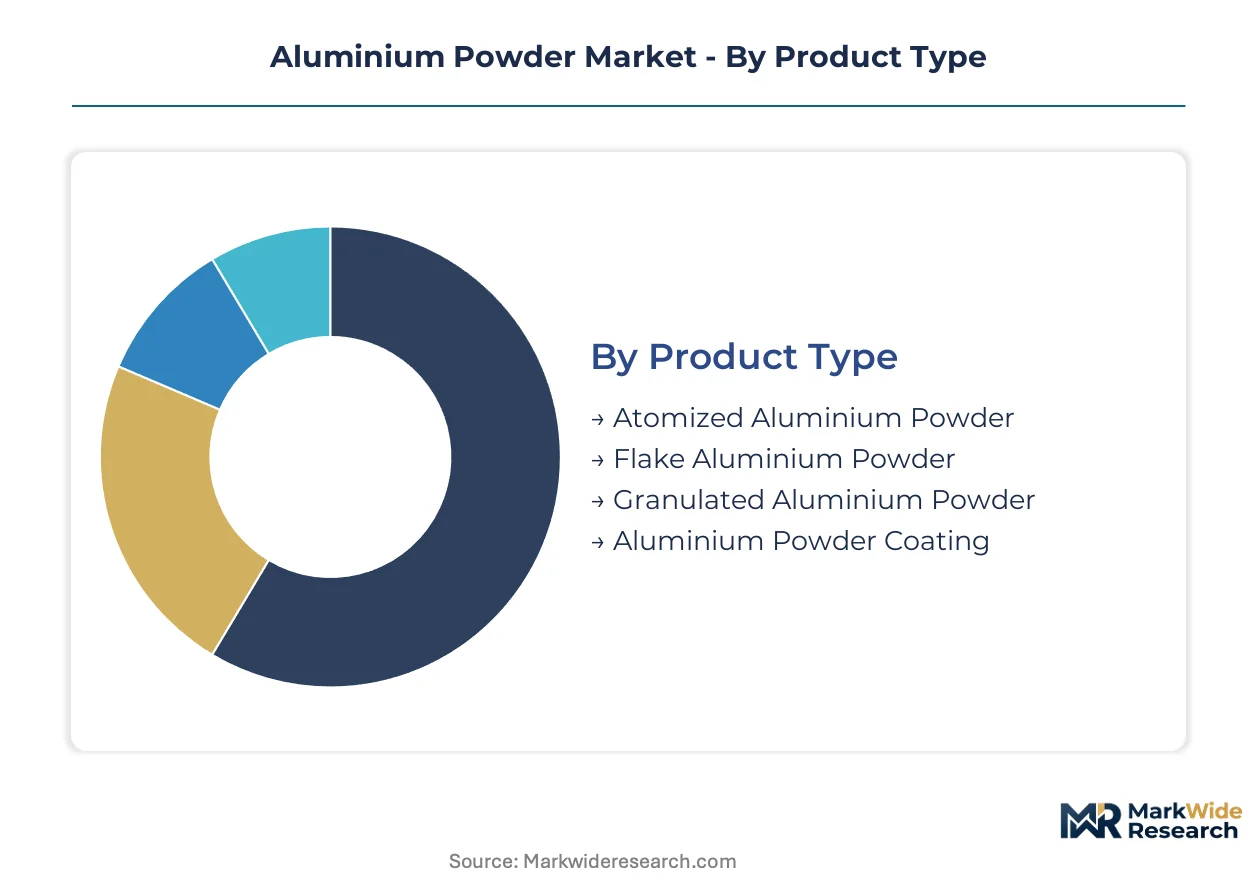
Aluminium powder segmentation reveals how capital deployment and technical specifications diverge across production methods and customer requirements. Each dimension carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Capital intensity varies sharply across production methods, with atomization requiring specialized inert gas infrastructure and flake milling demanding energy-intensive classification systems.
- Atomized Aluminium Powder:Spherical particles produced through inert gas atomization deliver consistent flowability for laser powder bed fusion. Aerospace OEMs in Germany and the United States are consolidating purchases around qualified atomizers capable of meeting AMS 5662 oxygen content specifications.
- Flake Aluminium Powder:Lamellar particles manufactured through ball milling and stamping provide high surface area for coating reflectivity and chemical reactivity. Automotive coating formulators in Japan and South Korea are narrowing approved-source lists to mills with automated particle thickness control.
- Granulated Aluminium Powder:Agglomerated fines serve pyrotechnic and metallurgical applications requiring controlled burn rates.
- Aluminium Powder Coating:Pre-formulated thermoset and thermoplastic blends target architectural and appliance finishing segments.
Most installed capacity flows through atomized grades serving aerospace qualification programs. Expansion is steepest in flake powder for automotive coating consolidation.
Application:
Customer concentration and specification stringency create divergent margin tiers across end-use verticals.
- Aerospace:Laser powder bed fusion and thermal spray applications demand spherical morphology with tight particle size distribution. Tier-one suppliers in Toulouse, Hamburg, and Seattle are unbundling alloy development from powder supply, contracting directly with atomization specialists.
- Automotive:Coatings, brake linings, and powder metallurgy components consume flake and atomized grades at volume scale. German OEM coating divisions are absorbing qualified-supplier premiums to secure REACH-compliant flake supply.
- Electrical:Conductive pastes and thermal interface materials utilize high-purity atomized fractions.
- Building & Construction:Protective coatings and concrete admixtures represent price-sensitive volume demand.
Aerospace commands the highest qualified-supplier premiums. Automotive generates the largest absolute volume throughput.
Technology:
Process selection determines particle morphology, purity ceilings, and regulatory compliance pathways.
- Gas Atomization:Inert gas impingement of molten aluminium produces spherical powders with controlled oxygen content. Investment is concentrating in closed-loop systems capable of meeting EPA particulate and ECHA registration requirements simultaneously.
- Mechanical Milling:Ball milling and stamping reduce ingot or foil to flake morphology. China's Shandong and Henan provinces host the majority of global milling capacity, though MEE dual carbon pressure is accelerating atomization transitions.
- Chemical Vapor Deposition:Vapor-phase reduction enables ultra-high purity for electronics packaging.
- Electrochemical Deposition:Electrolytic methods produce dendritic powders for specific chemical applications.
Gas atomization captures the majority of new capital deployment. Mechanical milling retains cost advantages in coating-grade flake production.
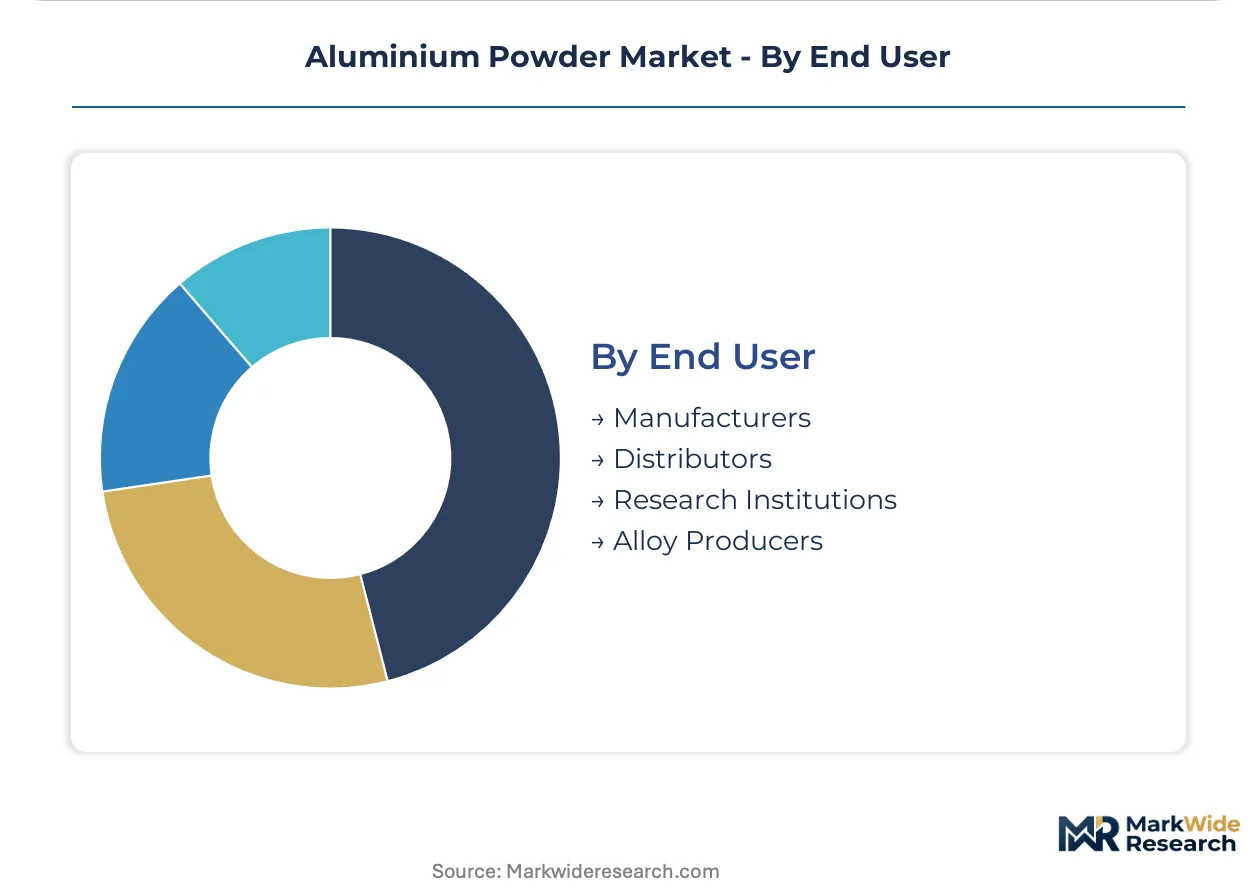
End User:
Procurement sophistication and technical service requirements segment the customer base.
- Alloy Producers:Master alloy and additive manufacturing feedstock manufacturers specify tight chemistry windows. Indian defense programs through DRDO and ISRO are creating qualified-supplier vacancies for spherical atomized grades.
- Manufacturers:Powder metallurgy parts producers and coating applicators prioritize lot-to-lot consistency and logistics reliability.
- Distributors:Regional traders face ECHA registration and EPA compliance barriers that favor registered producers with full substance data sets.
- Research Institutions:Universities and national laboratories sample developmental alloys at smaller batch scales.
Alloy producers drive the most demanding specification evolution. Distributors are consolidating around compliant registered suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgists specializing in gas flow dynamics and powder morphology control concentrate in legacy defense contractor hubs and emerging industrial clusters across four continents. Their expertise distribution shapes where atomization capacity expands and where qualification bottlenecks persist.
United States
Aerospace OEMs in Seattle and Los Angeles mandate spherical atomized powders for laser powder bed fusion, consolidating purchases around qualified suppliers. EPA particulate standards and OSHA combustible dust enforcement constrain greenfield atomization permitting in Texas and Ohio. Houston-area facilities navigate extended commissioning timelines as regulators apply NFPA 652 standards.
Germany
Automotive coating divisions in Stuttgart and Munich absorb qualified-supplier premiums to secure REACH-compliant flake supply from registered producers. ECHA enforcement actions against non-compliant traders redirect sourcing toward full substance data set holders. Hamburg hosts tier-one aerospace suppliers unbundling alloy development from powder supply contracts.
China
Domestic gas atomization capacity in Shandong and Henan provinces serves both alloy producers and regional coating formulators. MEE dual carbon pressure accelerates transitions from energy-intensive milling toward renewable-powered atomization systems. Qingdao industrial clusters concentrate flake powder milling capacity serving Asia-Pacific coating demand.
India
DRDO solid propellant programs and ISRO launch vehicle production create qualified-supplier vacancies for spherical atomized grades. BIS standards and defense procurement protocols filter vendor qualification toward registered producers with aerospace certification. Bengaluru and Hyderabad host emerging atomization capacity targeting import substitution.
Japan
Automotive coating formulators in Nagoya and Osaka narrow approved-source lists to mills with automated particle thickness control. METI industrial standards and JIS specifications shape import sourcing toward low-oxide flake grades. Yokohama-based distributors consolidate around compliant registered suppliers facing ECHA-equivalent substance documentation requirements.
Aluminium Powder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across atomization technology tiers, creating a bifurcated structure where scale advantages clash with customization agility. The vendor base organizes around three strategic archetypes: integrated primary aluminium producers, specialized atomization houses, and regional milling specialists. Consolidation pressures favor M&A activity among mid-cap atomizers seeking aerospace qualification scale. Capacity expansion concentrates in closed-loop gas atomization systems capable of simultaneous EPA and ECHA compliance.
Within the integrated producer tier, Alcoa exemplifies upstream control over bauxite-to-powder supply chains. Kymera International and Toyal Group occupy distinct specialization positions—one anchored in defense and space alloy programs, the other in flake powder expertise for coatings. These three names represent how competitive positioning fragments across feedstock integration, atomization technology, and end-use vertical focus rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Alcoa |
| Kymera International |
| Toyal Group |
| Valimet |
| Metal Powder Company |
| Zhangqiu Metallic Pigment |
| AMG Advanced Metallurgical Group |
| Hoganas AB |
| Henan Yuanyang Powder Technology |
| Others |
Supply Flow & Price Mechanics
LME aluminium ingot costs transmit directly through atomization facility economics, compressing margins for non-integrated producers while integrated suppliers capture downstream pricing power through captive bauxite-to-powder supply chains. This input-cost pathway stratifies the market into three distinct pricing tiers: aerospace-qualified spherical grades commanding certification premiums, automotive coating flakes absorbing REACH compliance costs, and industrial commodity powders trading on spot metal indices.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across buyer segments. Tier-one aerospace OEMs unbundle technical alloy development from powder supply, contracting atomization specialists directly and paying separate service fees for particle size distribution customization. Automotive coating formulators absorb qualified-supplier premiums for REACH-registered flake supply from registered producers with full substance data sets. Price differentiation hinges on certification grade and volume scale, with AMS-qualified spherical grades separating from industrial commodity tiers. Pricing pressure stems from primary aluminium volatility transmitting through non-integrated atomizers, compressing margins at the standard grade tier. Building and construction segments exhibit highest price sensitivity, while defense and space alloy programs demonstrate lowest sensitivity due to specification stringency and sole-source qualification protocols.
Supply Chain Analysis
Dual-sourcing requirements from tier-one aerospace and automotive buyers mandate multi-supplier qualification, forcing coating formulators to maintain approved-source relationships across at least two registered mills. Geographic supply concentration centers on China, Germany, and the United States, with Shandong and Henan provinces hosting over sixty percent of global flake powder milling capacity. Raw material dependencies draw from primary aluminium smelters, inert gas suppliers, and specialty alloy feedstock providers. Single-source vulnerability concentrates in Chinese industrial clusters where MEE dual carbon pressure accelerates energy-intensive milling transitions. Distribution runs through qualified direct contracts for aerospace grades and regional distributor networks for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminium powder market functions as a stable compounder, with additive manufacturing feedstock qualification pulling sustained capacity investment toward certified atomizers. Aerospace specification evolution and regulatory carbon tracking create durable barriers that protect qualified supplier returns.
For Market Incumbents: To counter margin compression from primary aluminium volatility, deepen backward integration into captive bauxite or long-term smelter offtake agreements. Alcoa's integrated supply chain exemplifies this defensive positioning. Counter emerging atomization specialists by accelerating closed-loop gas atomization capacity additions in EPA-compliant US jurisdictions and ECHA-registered European hubs, compressing commissioning timelines through pre-permitted brownfield expansions. For New Entrants and Emerging Players: Capture qualified-supplier vacancies in Indian defense aerospace through DRDO solid propellant and ISRO launch vehicle programs, where BIS standards and defense procurement protocols filter toward registered producers with aerospace certification. The most penetrable white-space sits in spherical atomized grades for alloy producers serving import substitution mandates. Establish go-to-market presence through metallurgist hiring from legacy defense contractor retirement pipelines, securing gas flow dynamics expertise that accelerates qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap atomizers with aerospace qualification scale because buyer consolidation into approved-source lists concentrates volume with registered producers possessing full substance data sets. The viable acquisition target archetype combines closed-loop gas atomization assets with existing AMS or ASTM certification. Watch the EU carbon border adjustment mechanism implementation signal as the inflection indicator for low-carbon primary aluminium feedstock sourcing premiums reshaping European powder producer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Gas Atomization Capacity Expansion | EPA particulate and ECHA registration compliance enables simultaneous US and European market access. |
| Backward Integration into Primary Aluminium | Captive bauxite-to-powder supply chains insulate margin compression from LME volatility transmission. |
| REACH Registration Investment | Full substance data sets filter non-compliant traders and consolidate volume with registered producers. |
| Defense Aerospace Qualification Pursuit | DRDO and ISRO programs create import substitution vacancies for spherical atomized grade suppliers. |
| Digital Alloy Qualification Platform Deployment | Computational thermodynamics convergence compresses aerospace material certification cycles for qualified atomizers. |
Methodological Framework
Multiple input streams — primary interviews with atomization facility managers, aerospace procurement leads, and coating formulator technical directors; secondary validation through customs trade data, SEC filings from integrated primary aluminium producers, and ECHA registration databases; plus patent and technical literature review — were reconciled through bottom-up capacity modeling and top-down demand triangulation. Plant manager interviews captured utilization rates and qualification pipeline status. Aerospace procurement leads detailed approved-source list consolidation patterns. Coating formulator technical directors explained REACH compliance cost absorption mechanisms.
Historical capacity expansion patterns were cross-referenced against panel input from metallurgists specializing in gas flow dynamics to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include production method, end-use vertical, particle morphology specification, and geographic regulatory cluster. CAGRs were derived from reconciling supply-side capacity buildout schedules with demand-pull indicators from additive manufacturing qualification momentum and defense aerospace procurement pipelines. Forecast inputs incorporated MEE dual carbon transition timelines and EPA permitting velocity for greenfield atomization facilities.
Primary aluminium price volatility, REACH enforcement intensity against non-compliant traders, and aerospace OEM qualification protocol evolution are the dominant revision risks to modeled outcomes. Deviation in LME aluminium sustained price bands would shift margin compression timelines and integrated producer competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Carbon Steel Market
Metals
Armour Steel Plate Market
Metals
Copper Azoles Market
Metals
High Purity Aluminium Market
Metals
Global Wire Rods Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Global Chromium Market
Metals
Refined Nickel Market
Metals
Metal Powder Market
Metals
Crude Steel Market
Metals
Vietnam Aluminum Market
Metals
Global Oxygen-Free Copper Market
Metals
Rhodium Market
Metals
Osmium Market
Metals
Nickel Market
Metals
India Special Steel Market