
 Tinplate Market | 2026-2036
Tinplate Market Size, Share, and Industry Trends Forecast 2026-2036
Tinplate Market Outlook
Electrolytic deposition precision is narrowing the acceptable tolerance band for tin coating weights across premium packaging grades. Thyssenkrupp AG leverages its continuous annealing expertise to supply automotive and packaging clients with gauge-optimized coil. Tata Steel anchors South Asian supply through integrated cold-rolling and tinning lines at its Jamshedpur complex. ArcelorMittal competes on scale, operating multiple European tinplate finishing facilities that feed continental canning demand.
Tinplate denotes a thin cold-rolled steel sheet carrying an electrodeposited tin layer typically ranging from 0.4 to 11.2 grams per square meter per side, engineered to provide solderability, corrosion resistance, and a neutral interaction with food contents. The material serves primarily as a substrate for two-piece and three-piece food and beverage cans, aerosol containers, and closure systems where hermetic sealing and extended shelf stability are mandatory. Electrolytic tinplate retains the dominant share of value generation owing to established canning line compatibility and deep supplier infrastructure, while tin free steel commands expanding share in crown cork and general-line applications where cost reduction outweighs solderability requirements. Thin gauge material leads volume throughput in beverage can ends, though thick gauge coil carries superior margin pools in chemical drum and industrial pail segments where mechanical rigidity specifications are stringent.
EPA effluent guidelines govern wastewater discharge from steel finishing operations in the United States, while REACH restricts certain chromium-based passivation chemistries in European tinplate surface treatments. FDA food-contact notifications shape coating compliance for tinplate destined for acid food applications, creating a multi-jurisdictional compliance burden for exporters. India's BIS certification mandates mechanical testing and coating adherence benchmarks for domestic tinplate commerce. Stakeholders must monitor regulatory divergence between food-contact regimes and emerging restrictions on per- and polyfluoroalkyl substances that could displace incumbent organic coating systems.
Market Dynamics
Electrolytic tinning precision and REACH-mandated coating chemistry shifts are compressing supplier margins while consolidating procurement toward integrated steel-tinning operations in India and Europe.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for metal packaging feedstock is accelerating domestic cold-rolling and tinning capacity additions at Jamshedpur and emerging mill clusters.
- FDA food-contact notifications:Acid food applications in the United States require coating compliance certifications that favor established tinplate suppliers with validated organic coating systems.
- Aerosol container demand:Personal care and household chemical brands are expanding tinplate procurement for corrosion-resistant valve cups and domed can bodies.
Market Restraints
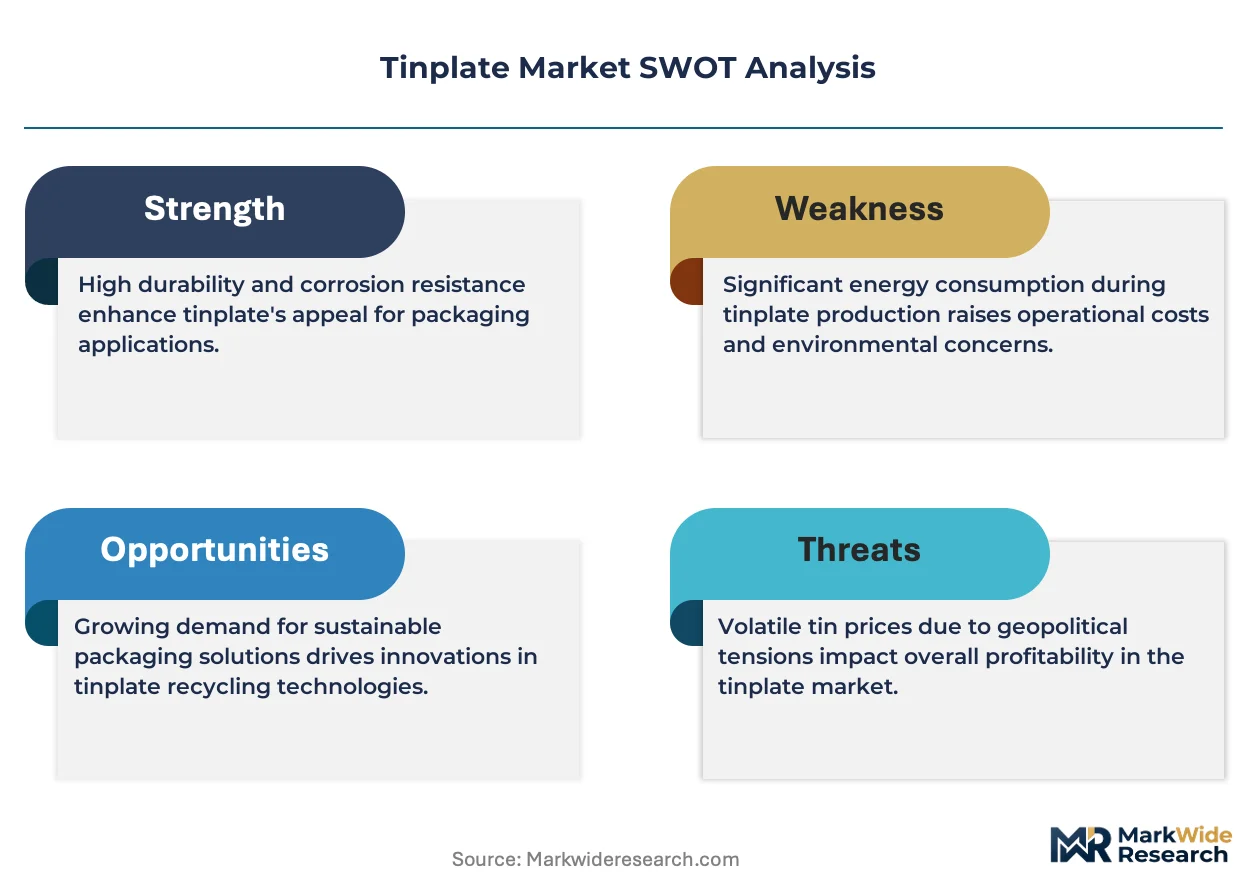
- Tin price volatility:London Metal Exchange tin pricing swings directly compress tinning line margins and destabilize coating weight optimization programs.
- Chinese supply concentration:Integrated steel-tinning complexes in Hebei and Shandong provinces control disproportionate export volumes, creating freight cost and tariff exposure for distant buyers.
- Tin free steel substitution:Chromium-coated steel alternatives are capturing crown cork and general-line applications where solderability is non-critical.
Strategic Opportunities
- BIS certification pathways:Domestic mechanical testing and coating adherence benchmarks create protected market space for India-registered producers against unvalidated imports.
- Thin gauge beverage ends:Two-piece aluminum can conversion slowdowns are preserving tinplate demand for steel can ends in specialty beverage categories.
- EU Green Deal alignment:Circular packaging mandates and recycled content thresholds favor tinplate's established scrap recovery infrastructure over competing substrates.
Industry Challenges
- Passivation chemistry reformulation:REACH restrictions on hexavalent chromium surface treatments force accelerated R&D timelines for compliant organic-inorganic hybrid coatings.
- Continuous annealing line retrofit costs:Gauge-flexible tinning capacity requires capital-intensive furnace upgrades that strain mid-scale coil processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinplate Market |
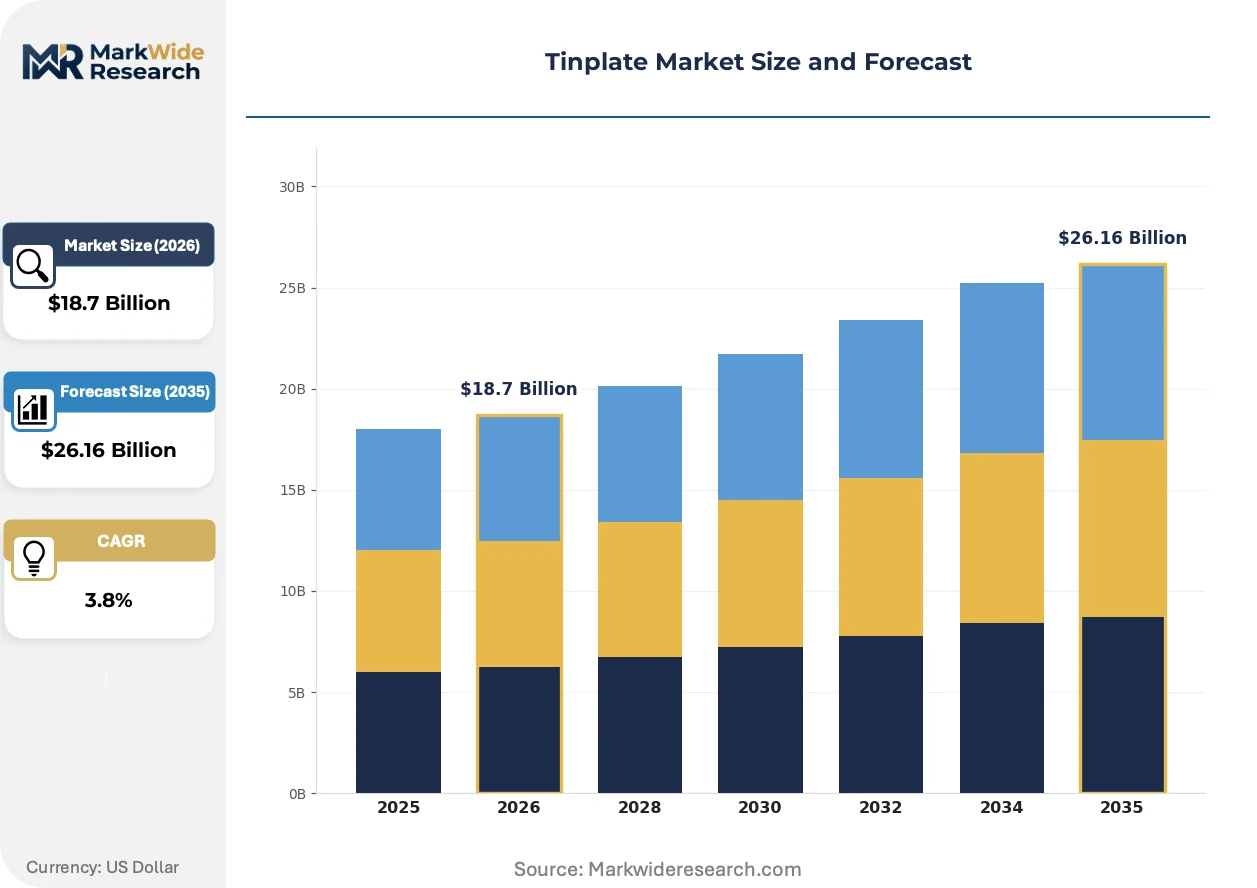
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Tinplate, Tin Free Steel, Composite Tinplate, Coated Tinplate End Use Industry: Food & Beverage Packaging, Chemical Containers, Electrical Equipment, Automotive Components Thickness: Thin Gauge, Medium Gauge, Thick Gauge, Extra Thick Gauge Coating Type: Organic Coatings, Inorganic Coatings, Epoxy Coatings, Aqueous Coatings |
| Companies Covered | Thyssenkrupp AG, Tata Steel, ArcelorMittal, Tinplate Company of India Ltd., JSW Steel Ltd., Nippon Steel Corp., United States Steel Corp., Toyo Kohan Co., Ltd., JFE Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinplate Market Strategic Shifts
Laser surface texturing and chromium-free passivation chemistries are compressing traditional coating tolerances while procurement consolidation favors suppliers with integrated metallurgical laboratories.
Laser-etched micro-cavities on tinplate surfaces are improving lacquer adhesion for aggressive food chemistries. Premium seafood and tomato paste canners in Portugal and Thailand are qualifying these coils for reduced pinhole rates. Conventional grit-blast surface preparation is rendering obsolete for high-acid applications demanding sub-micron coating uniformity.
REACH Annex XVII restrictions on chromium VI compounds are forcing European tinplate finishers to migrate toward zirconium-based and titanium-based passivation layers. Surface treatment houses in Germany and the Netherlands are scaling pilot lines for these chemistries ahead of sunset dates. Acid food exporters to the European Union face multi-jurisdictional coating recertification burdens that favor suppliers with in-house analytical validation.
Consolidated beverage can makers are compressing supplier panels and mandating coil-to-can traceability systems. Regional tinning operations in India and Brazil are investing in QR-coded coil tagging and cloud-based metallurgical databases to retain tier-one supplier status. This behavioral shift is most visible in procurement contracts linking coating weight certificates directly to downstream canning line efficiency guarantees.
Tinplate Market Segmentation
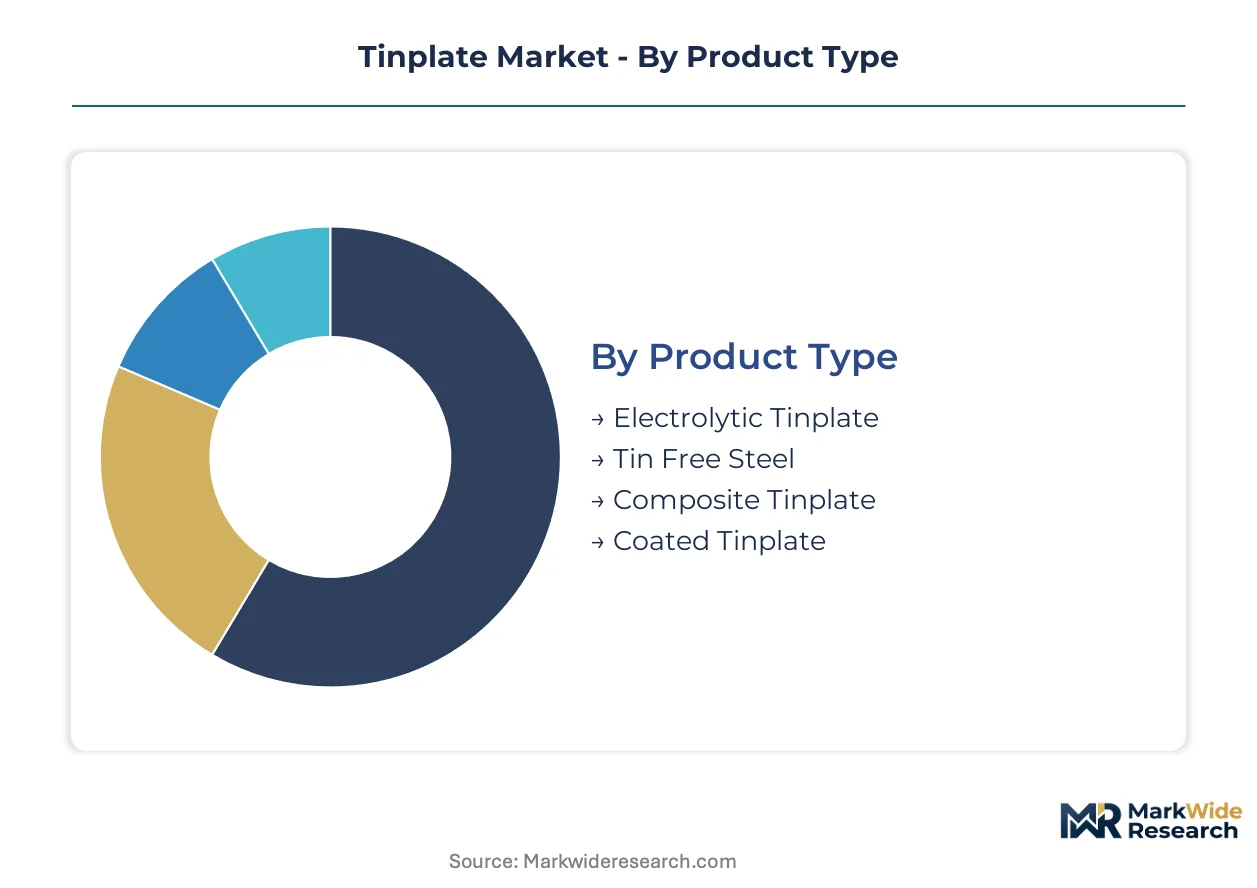
Tinplate procurement decisions hinge on coating chemistry compatibility with specific food-contact regulations and canning line mechanical requirements. Each segmentation dimension carries distinct compliance burdens and margin profiles that reshape supplier-customer relationships across the value chain.
Product Type:
After-sales service intensity varies sharply across product categories, with electrolytic tinplate demanding metallurgical support for coating weight disputes and tin free steel requiring minimal technical intervention.
- Electrolytic Tinplate:Cold-rolled steel substrate carries electrodeposited tin layers from 0.4 to 11.2 grams per square meter per side, engineered for solderability and hermetic sealing in three-piece food cans. European canners in Portugal and Germany concentrate procurement here due to established lacquer adhesion protocols and REACH-compliant passivation availability.
- Tin Free Steel:Chromium-coated steel alternative eliminates tin entirely, trading solderability for cost reduction in crown cork and general-line applications. Indian beverage closure manufacturers are expanding procurement of these coils under PLI scheme incentives that reward domestic feedstock substitution.
- Composite Tinplate:Multi-layer substrates combine tin with polymer interlayers for aggressive chemical resistance.
- Coated Tinplate:Pre-applied organic systems reduce downstream lacquering steps for high-volume canners.
By volume, electrolytic tinplate leads. By growth pace, tin free steel is expanding most quickly.
End Use Industry:
Application-specific certification requirements create divergent margin pools, with food-contact segments commanding premium pricing for validated coating systems.
- Food & Beverage Packaging:Two-piece and three-piece cans, aerosol containers, and closure systems require hermetic sealing and neutral food interaction. FDA food-contact notifications for acid foods in the United States and evolving BIS certification in India are concentrating procurement toward suppliers with in-house analytical validation laboratories.
- Chemical Containers:Industrial pails and drums demand thick gauge mechanical rigidity for hazardous material containment. German chemical drum manufacturers specify stringent gauge tolerances that favor integrated steel-tinning operations with continuous annealing expertise.
- Electrical Equipment:Solderable substrates for electronic component housings.
- Automotive Components:Fuel filter housings and brake line reservoirs requiring corrosion resistance.
Food & beverage packaging generates dominant revenue share. Chemical containers yield the highest per-ton margins.
Thickness:
Cost tier stratification separates commodity beverage ends from premium industrial pail specifications.
- Thin Gauge:Sub-0.20mm coils optimize material yield for beverage can ends and shallow-drawn containers. Thai seafood canners are qualifying these specifications for reduced pinhole rates in aggressive food chemistries.
- Medium Gauge:General-purpose food cans balance material cost with structural integrity.
- Thick Gauge:Chemical drum and industrial pail segments where mechanical rigidity specifications are stringent carry superior margin pools.
- Extra Thick Gauge:Heavy-duty applications including large-capacity industrial containers.
Thin gauge dominates unit volume. Extra thick gauge commands steepest expansion trajectory in specialty chemical logistics.
Coating Type:
Regulatory chemistry mandates are forcing rapid formulation shifts across all coating categories.
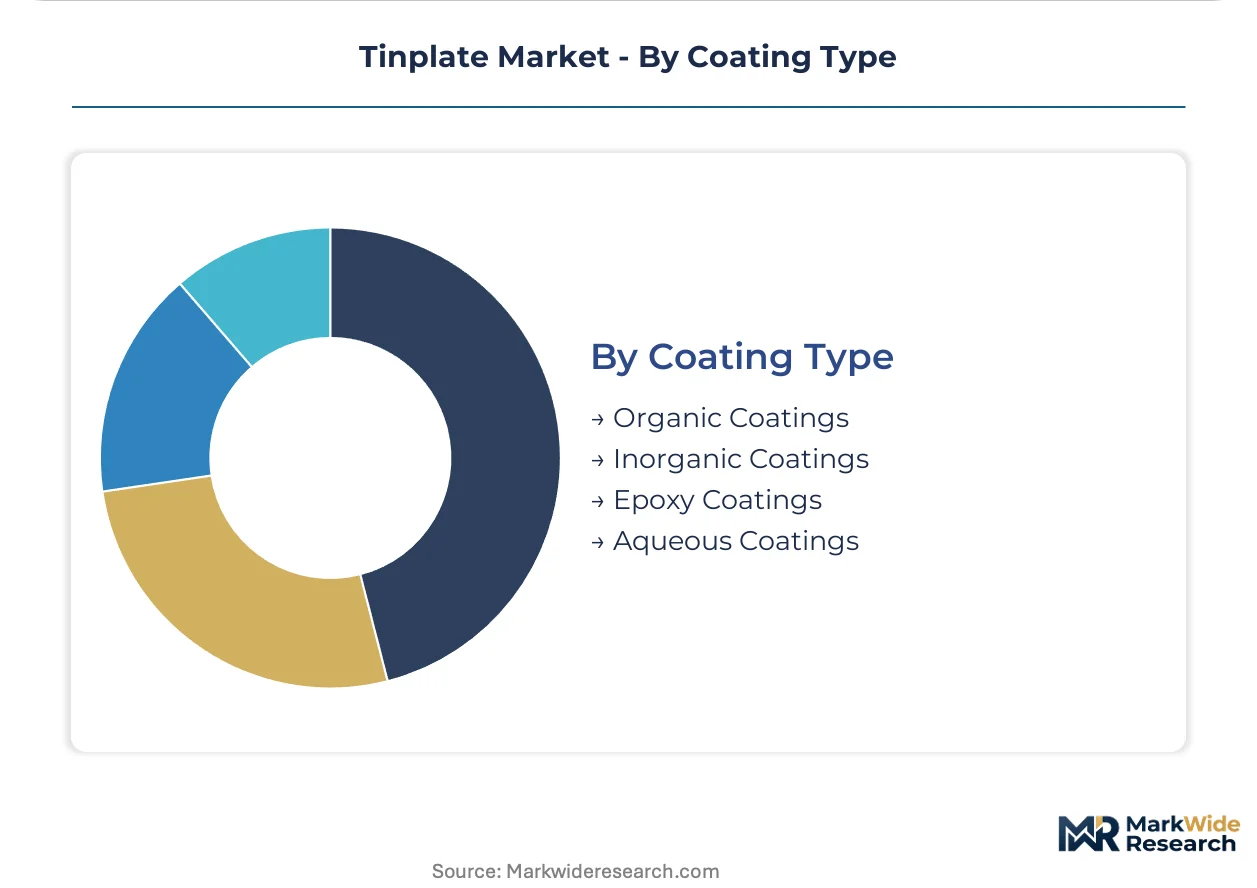
- Organic Coatings:Epoxy-phenolic and polyester systems provide barrier protection against acid foods. REACH restrictions on per- and polyfluoroalkyl substances are displacing incumbent organic systems in European export supply chains.
- Inorganic Coatings:Zirconium-based and titanium-based passivation layers replace hexavalent chromium under Annex XVII sunset dates. German surface treatment houses are scaling pilot lines ahead of compliance deadlines.
- Epoxy Coatings:High-performance barrier systems for aggressive food chemistries.
- Aqueous Coatings:Water-based systems reducing volatile organic compound emissions in canning operations.
Organic coatings retain installed base dominance. Inorganic systems are gaining share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese tinplate exports flow predominantly into Southeast Asian canning operations, while European mills redirect supply toward domestic food-contact packaging under tightening REACH compliance deadlines.
China
Hebei and Shandong provinces host integrated steel-tinning complexes supplying corrosion-resistant coil for regional aerosol and food can manufacturers. GB standards govern coating weight tolerances and surface finish specifications for domestic commerce. Tianjin port clusters handle bulk export consolidation toward Vietnam and Indonesia, where downstream canning lines are expanding capacity for processed seafood and tomato paste.
India
Jamshedpur anchors South Asian supply through Tata Steel's integrated cold-rolling and tinning complex serving domestic food and beverage packaging demand. BIS certification mandates mechanical testing and coating adherence benchmarks that protect registered producers against unvalidated imports. PLI scheme incentives are accelerating capacity additions at emerging mill clusters in Gujarat and Maharashtra, drawing investment from multinational can makers seeking localized feedstock security.
Germany
Ruhr Valley finishing facilities supply gauge-optimized coil to continental chemical drum manufacturers and premium food canners. REACH Annex XVII restrictions on hexavalent chromium passivation chemistries are forcing surface treatment houses toward zirconium-based and titanium-based alternatives ahead of sunset dates. Dortmund and Duisburg industrial corridors concentrate continuous annealing expertise for automotive and packaging clients demanding sub-micron coating uniformity.
United States
Great Lakes steel corridors maintain tinplate finishing capacity for domestic three-piece food can and aerosol container demand. EPA effluent guidelines govern wastewater discharge from steel finishing operations, while FDA food-contact notifications shape coating compliance for acid food applications. Pittsburgh and Cleveland mill complexes face import competition from Asian supply but retain advantage in validated organic coating systems for high-acid tomato and citrus applications.
Japan
Kansai and Chubu industrial regions host precision tinning operations supplying solderable substrates for electronic component housings and specialty food packaging. METI oversees industrial standards coordination with downstream canning equipment manufacturers. Osaka-based surface treatment specialists are qualifying laser-etched micro-cavity coils for reduced pinhole rates in aggressive food chemistries, serving premium seafood exporters to European Union markets.
Tinplate Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where integrated steel-tinning operations command procurement preference from consolidated beverage can makers. The vendor base separates into three strategic archetypes: multinational steel majors with continuous annealing expertise, regional mills leveraging domestic certification barriers, and specialized surface treatment houses focused on passivation chemistry innovation. Dominant competitive moves include backward integration into captive cold-rolling capacity and accelerated R&D timelines for REACH-compliant coating systems.
Among European steel majors, Thyssenkrupp AG and ArcelorMittal exemplify the scale-driven archetype, occupying positions within integrated metallurgical supply chains that span multiple continental finishing facilities. Tata Steel anchors the regional mill category through its Jamshedpur complex, representing the protected-market strategy enabled by India's BIS certification pathways and PLI scheme incentives. These three entities collectively illustrate how geographic coverage and regulatory alignment determine supplier tier status in procurement panels.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| Tata Steel |
| ArcelorMittal |
| Tinplate Company of India Ltd. |
| JSW Steel Ltd. |
| Nippon Steel Corp. |
| United States Steel Corp. |
| Toyo Kohan Co., Ltd. |
| JFE Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Hebei and Shandong integrated steel-tinning complexes anchor global coil supply and concentrate margin pools in REACH-compliant European finishing and BIS-certified Indian operations. London Metal Exchange tin price swings transmit directly through coating weight programs, compressing tinning line profitability and amplifying procurement consolidation toward captive cold-rolling capacity.
Pricing Analysis
Electrolytic tinplate versus tin free steel versus next-generation chromium-free passivated coil defines the three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on coating weight certification precision and FDA food-contact notification validation for acid food applications. Cost compression in standard-grade electrolytic tinplate is intensifying because Chinese export volumes destabilize regional spot markets. Beverage can end manufacturers exhibit highest price sensitivity, while German chemical drum producers demonstrate lowest sensitivity due to stringent mechanical rigidity specifications.
Supply Chain Analysis
Extended payment terms from Hebei and Shandong mills to Southeast Asian canning operations strain working capital and favor supply-chain finance facilities at Singapore trading houses. Geographic concentration centers on China, India, and Germany as dominant coil sources. Raw material dependencies rest on tin ingot from Indonesian smelters, cold-rolled steel substrate from integrated blast furnaces, and chromium compounds for passivation chemistries. Tariff exposure on Chinese exports creates structural supply chain risk. Distribution runs through Tianjin port consolidation for Asian buyers and Rotterdam- Antwerp corridors for European canners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tinplate incumbents face sustained substitution pressure from aluminum two-piece cans and chromium-coated steel crown cork applications. Defense of position requires navigating coating chemistry reformulation mandates while securing feedstock integration.
For Market Incumbents: Harden coating chemistry R&D pipelines against REACH Annex XVII sunset dates for hexavalent chromium passivation. Secure backward integration into captive cold-rolling capacity at Jamshedpur or comparable integrated complexes to insulate margins from tin price volatility. Tin free steel substitution in crown cork segments demands accelerated qualification of zirconium-based passivation alternatives. For New Entrants and Emerging Players: Mid-scale BIS-certified tinning operations in Gujarat and Maharashtra represent the most penetrable entry point for domestic Indian food packaging procurement. PLI scheme incentives reduce capital intensity for greenfield continuous annealing investments. Target aerosol valve cup specifications where corrosion resistance requirements exclude aluminum substitution and established suppliers lack regional presence. For Investors and Strategic Acquirers: Capital is best deployed toward surface treatment houses with in-house analytical validation laboratories and REACH-compliant organic-inorganic hybrid coating pipelines. Long-term viability across the projection horizon depends on regulatory chemistry alignment rather than scale alone. Watch for FDA food-contact notification backlog clearance as inflection signal for validated supplier tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Rolling Capacity | Tata Steel's Jamshedpur complex demonstrates margin protection against substrate cost volatility. |
| REACH-Compliant Passivation R&D Scale-Up | German surface treatment houses in Dortmund industrial corridors secure European canner procurement preference. |
| BIS Certification Pathway Investment | Domestic mechanical testing benchmarks create protected market space against unvalidated Chinese imports. |
| Coil-to-Can Traceability System Deployment | QR-coded tagging and cloud-based metallurgical databases retain tier-one supplier status with consolidated beverage makers. |
| Thin Gauge Beverage End Qualification | Thai seafood canner adoption of laser-etched micro-cavity coils preserves tinplate demand amid aluminum conversion slowdowns. |
Study Parameters
A spread of perspectives from tinning line operations managers, can maker procurement directors, surface treatment R&D leads, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of integrated steel majors, BIS certification registries, ECHA REACH restriction updates, and FDA food-contact notification databases. Bottom-up coil shipment analysis and top-down packaging demand modeling provided triangulation.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation by product type, end-use industry, thickness grade, and coating chemistry. CAGRs derived from normalized historical shipment trajectories and projected capacity additions. Key forecast inputs included London Metal Exchange tin price bands and PLI scheme disbursement timelines for Indian domestic capacity.
Macroeconomic conditions sit as an overlay; deviation in industrial steel demand cycles or Indonesian tin smelter output would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance deadlines and coating substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Copper Alloy Market
Metals
Galvanized Steel Market
Metals
Rolled Steel Motor Market
Metals
Bismuth Market
Metals
Stainless Steel Round Bar Market
Metals
Metallurgical Silicon Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
US Metal Fabrication Market
Metals
Trivalent Chromium Finishing Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Iron and Steel Market
Metals
Crude Steel Market
Metals
Clutch Spring Wires Market
Metals
Motor Lamination Material Market
Metals
Europe Aluminium Cans Market
Metals
GCC Aluminium Powder Market