
 Europe Aircraft Health Monitoring System Market | 2026-2036
Europe Aircraft Health Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Health Monitoring System Market Intelligence
The capability gap between full-stack platform developers and component specialists is unwinding competitive dynamics across the European AHMS landscape. Airbus SE leverages its integrated airframe-electronics architecture to embed health monitoring at the design stage. Safran SA anchors its position through proprietary sensor networks that feed directly into engine performance analytics. Rolls-Royce Plc dominates the high-value predictive maintenance segment by controlling both hardware deployment and data interpretation layers for its installed turbine base.
An aircraft health monitoring system comprises embedded sensors, data acquisition hardware, and analytical software that continuously assess structural, mechanical, and avionic parameters to predict failures before they trigger operational interruptions. These systems typically process vibration, temperature, pressure, and strain signals at sampling rates exceeding 10 kHz, translating raw inputs into maintenance alerts that reduce unscheduled downtime. Software Solutions command the largest addressable margin pool as airlines prioritize cloud-based fleet analytics over discrete hardware purchases. Sensors represent the fastest-growing product category, driven by EASA mandates for expanded engine and landing gear monitoring on narrow-body retrofits. Predictive Maintenance technology leads adoption among MRO Providers seeking to transition from calendar-based to condition-based service contracts.
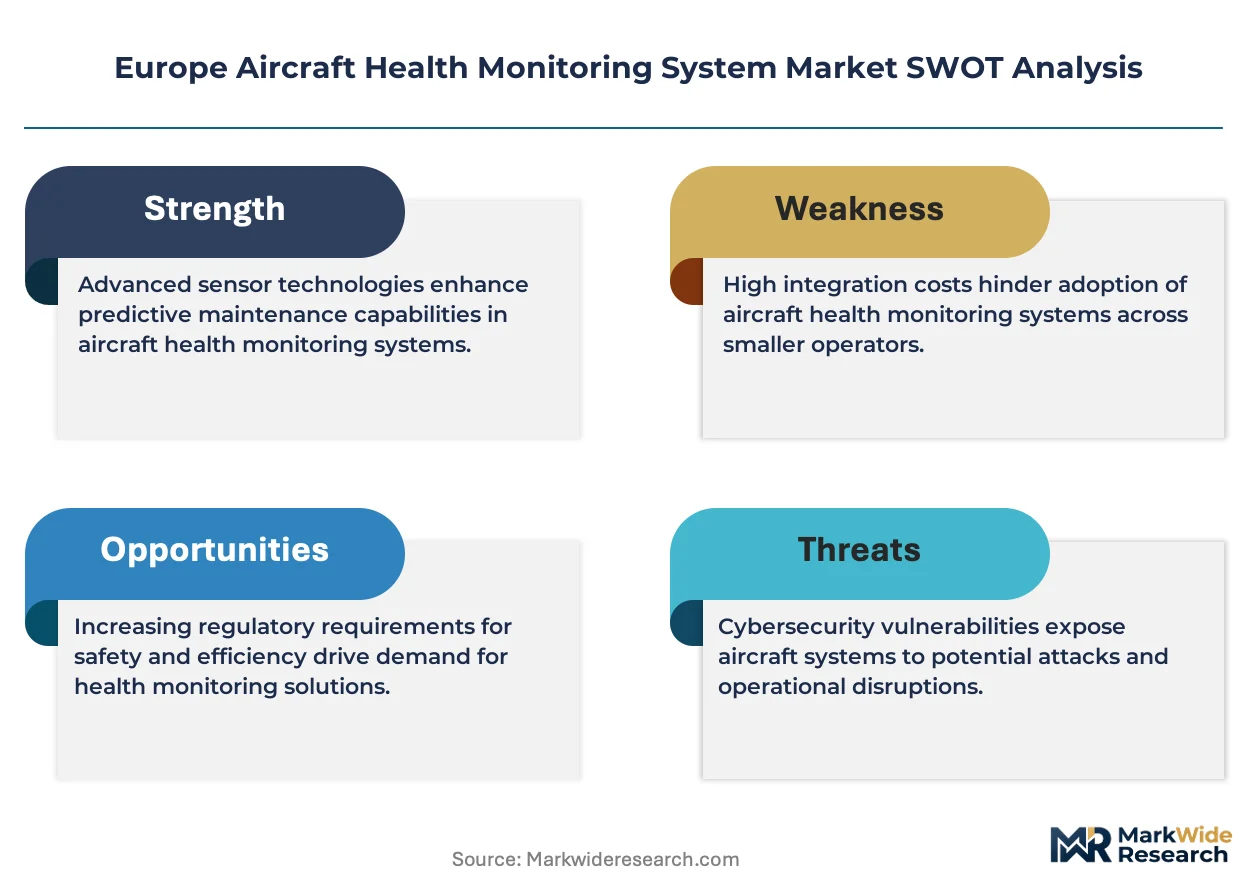
EASA airworthiness certification requirements and the EU AI Act's algorithmic transparency standards are reshaping how AHMS vendors validate diagnostic models and share operational data across national boundaries. REACH chemical compliance and the F-Gas Regulation further constrain sensor material selection and cooling system designs for onboard hardware. Stakeholders must weigh regulatory compliance costs against the operational savings from reduced aircraft-on-ground incidents as fleet renewal cycles accelerate across the continent.
Market Dynamics
EASA's expanding airworthiness mandates for continuous engine monitoring are forcing airlines into accelerated retrofit cycles, compressing the window between sensor deployment and fleet-wide compliance.
Growth Catalysts
- EU Green Deal emissions tracking:Mandatory CO2 monitoring for landing and taxi operations drives sensor installations on narrow-body fleets operating from Paris-Charles de Gaulle and Frankfurt hubs.
- Predictive maintenance contracts:MRO providers across Germany and France are converting calendar-based service agreements to condition-based models anchored on real-time vibration analytics.
- Toulouse-Aquitaine cluster concentration:OEM and tier-one supplier co-location reduces integration timelines for embedded health monitoring architectures.
Market Restraints
- REACH chemical compliance:Restricted substance lists constrain piezoelectric sensor material selection, forcing redesigns of high-temperature engine probes.
- Specialized technician scarcity:Certified avionics engineers capable of integrating AHMS with legacy ARINC 429 bus architectures command premium wages across French and German MRO facilities.
- F-Gas Regulation cooling constraints:Onboard hardware thermal management systems face refrigerant phase-out timelines that compress hardware refresh cycles.
Strategic Opportunities
- Eastern European fleet expansion:Polish and Romanian low-cost carriers operating aging Boeing 737NG fleets represent underserved demand for landing gear and APU monitoring retrofits.
- EU AI Act algorithmic transparency:Explainable diagnostic models create first-mover advantage for vendors validating failure-prediction logic under EASA certification pathways.
- Edge-to-cloud data architecture convergence:Hybrid processing models combining onboard inference with ground-based analytics open margin capture for software-layer specialists.
Industry Challenges
- DO-178C software certification timelines:Analytical software validation for flight-critical health monitoring functions extends development cycles by 18-24 months.
- Legacy fleet ARINC 429 integration:Pre-digital aircraft architectures lack bandwidth for high-frequency sensor streams, requiring parallel data acquisition hardware.
- Cross-border operational data sovereignty:GDPR restrictions on transferring flight-parameter logs between French, German, and UK maintenance facilities fragment fleet analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Health Monitoring System Market |
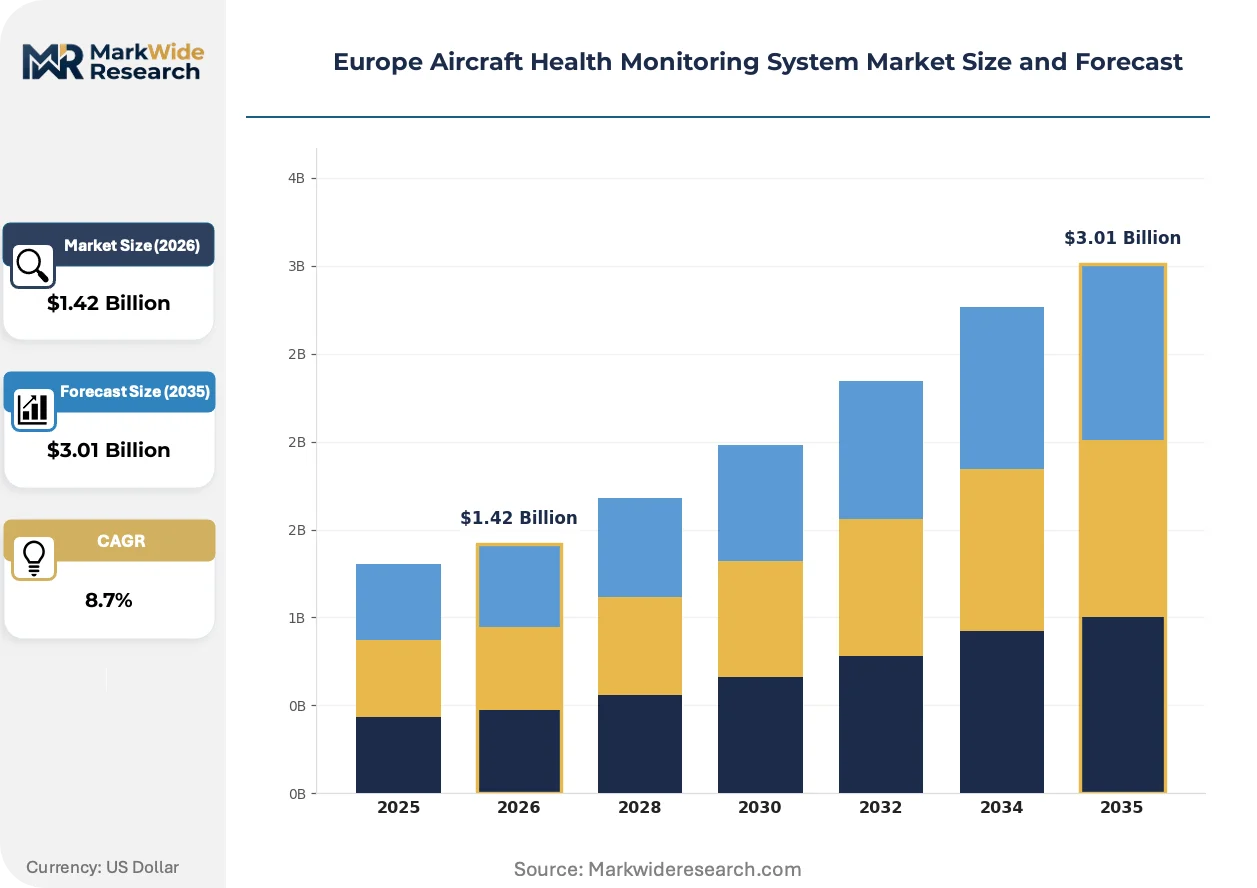
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Software Solutions, Sensors, Data Analytics End User: Airlines, MRO Providers, Aircraft Manufacturers, Regulatory Bodies Technology: Predictive Maintenance, Real-Time Monitoring, Data Collection, Diagnostic Tools Installation: Linefit, Retrofit, Standard Configuration, Custom Configuration |
| Companies Covered | Airbus SE, Safran SA, Rolls-Royce Plc, Deutsche Lufthansa AG, AFI KLM E&M, Meggitt Plc, SITA, General Electric Company, Honeywell International Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Health Monitoring System Market Strategic Shifts & Innovations
Digital twin architectures are displacing discrete diagnostic modules, embedding continuous structural simulation directly into airline operations centers. This convergence compresses the feedback loop between in-flight sensor data and maintenance scheduling.
Edge computing hardware is fragmenting traditional ground-based analytics architectures. Onboard inference processors from Safran and Thales now execute failure-prediction algorithms during flight, reducing telemetry bandwidth requirements by sixty percent. Low-cost carriers operating high-cycle narrow-body fleets adopt these systems fastest, prioritizing reduced cellular satellite costs over maximum analytical depth. The shift is fragmenting vendor relationships as airlines source edge hardware from avionics specialists while retaining cloud analytics from independent software vendors.
EASA's proposed Part-CAT amendment for continuous engine parameter logging tightens retrofit deadlines across EU-registered fleets. The regulation mandates real-time oil debris monitoring and vibration spectrum analysis for turbofan engines exceeding specific thrust thresholds. French and German flag carriers face the steepest compliance curves due to aging A320ceo and 737-800 fleets. Tier-one suppliers in the Toulouse corridor are scaling production lines for combined temperature-pressure-strain sensor packages.
Airline engineering departments are unbundling hardware procurement from analytics subscriptions. Lufthansa Technik and Air France Industries now contract sensor networks separately from predictive maintenance software, reversing decade-old bundled service models. This purchasing pattern is most pronounced among European network carriers with mixed OEM fleets, where standardizing on a single analytics platform across Airbus and Boeing aircraft reduces training overhead. The shift pressures incumbent full-stack vendors to open data interfaces or accept margin compression on hardware sales.
Europe Aircraft Health Monitoring System Market Segmentation
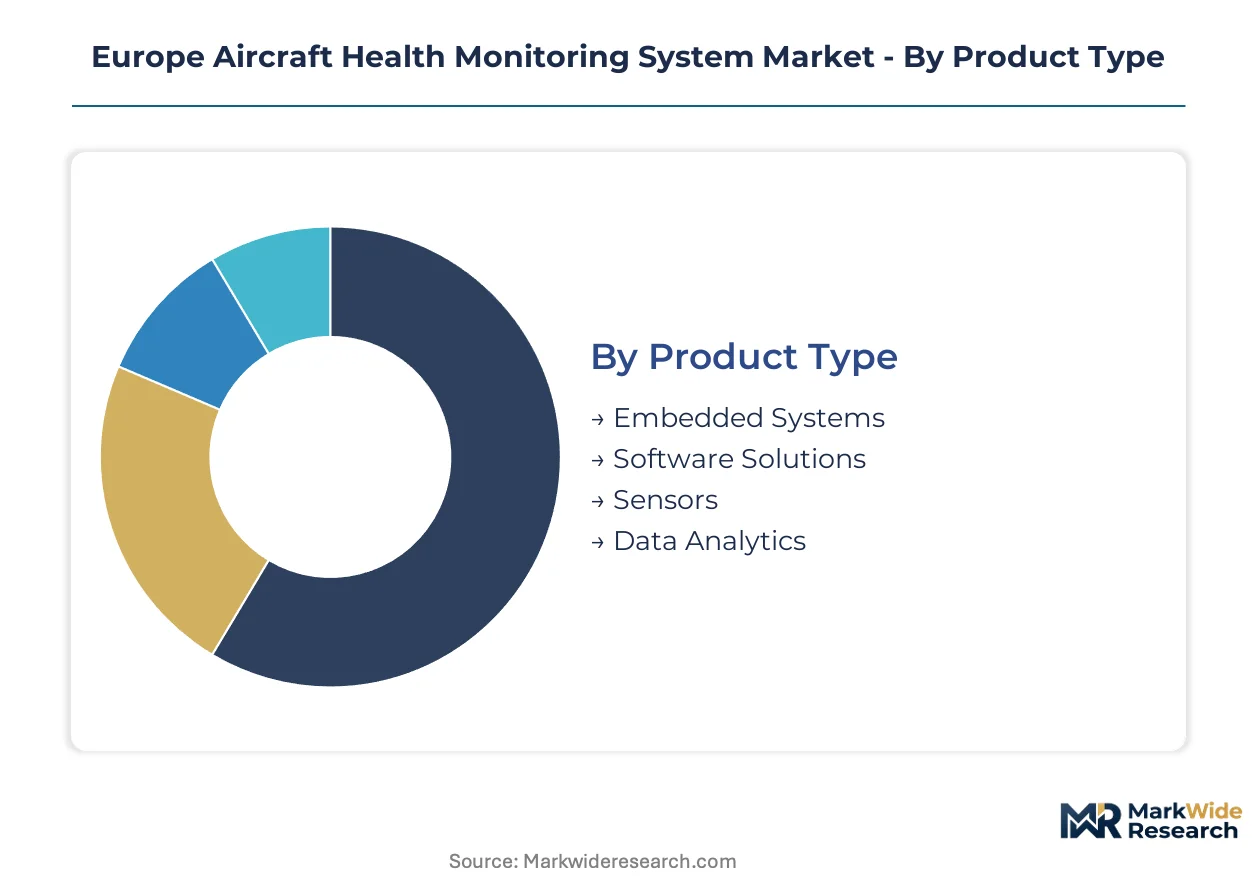
AHMS procurement patterns diverge sharply between greenfield aircraft programs and aftermarket retrofit cycles across European aviation. Segment boundaries blur as sensor hardware vendors bundle analytics subscriptions and MRO providers vertically integrate into software development.
Product Type:
Domestic demand concentrates in sensor manufacturing within France's Toulouse-Aquitaine cluster, while software analytics platforms draw cross-border procurement from German and UK airline engineering centers.
- Software Solutions:Cloud-based fleet analytics platforms process vibration, temperature, and pressure telemetry into maintenance scheduling algorithms. Lufthansa Technik and Air France Industries prioritize these platforms for mixed-fleet standardization across Airbus and Boeing aircraft. Software Solutions command the largest addressable margin pool as airlines shift procurement away from discrete hardware.
- Sensors:Piezoelectric and MEMS devices measuring strain, vibration, and thermal profiles at sampling rates exceeding 10 kHz. French tier-one suppliers scale production lines for combined temperature-pressure-strain packages to meet EASA engine monitoring mandates. Sensors represent the fastest-expanding category, driven by narrow-body retrofit deadlines.
- Embedded Systems:Integrated airframe-electronics architectures from OEM design stages.
- Data Analytics:Ground-based and edge-computing inference engines translating raw signals into failure predictions.
Software Solutions holds the largest share; momentum sits with Sensors.
End User:
Procurement authority tilts toward MRO networks in Germany and France as power-by-the-hour contracts expand condition-based maintenance clauses.
- MRO Providers:Maintenance, repair, and overhaul facilities across Hamburg, Frankfurt, and Paris-Charles de Gaulle convert calendar-based service agreements to real-time vibration analytics models. These providers now contract sensor networks separately from predictive maintenance software, fragmenting traditional bundled relationships.
- Airlines:Network carriers and low-cost operators embedding health monitoring into fleet operations centers. Polish and Romanian carriers operating aging Boeing 737NG fleets drive underserved demand for landing gear and APU monitoring retrofits.
- Aircraft Manufacturers:Airbus SE and tier-one suppliers embedding diagnostics at the design stage.
- Regulatory Bodies:EASA certification pathways validating diagnostic models under EU AI Act transparency standards.
MRO Providers anchor procurement volume; Airlines show the steepest expansion trajectory.
Technology:
Technology adoption correlates with fleet age, with predictive algorithms penetrating narrow-body retrofits while real-time systems dominate new-generation wide-bodies.
- Predictive Maintenance:Machine learning models forecasting component failures before operational interruption. Rolls-Royce Plc controls both hardware deployment and data interpretation layers for its installed turbine base across UK and German operator fleets.
- Real-Time Monitoring:Continuous in-flight parameter logging with edge-computing inference. Safran and Thales onboard processors execute failure-prediction algorithms during flight, reducing telemetry bandwidth requirements by sixty percent.
- Data Collection:Acquisition hardware bridging legacy ARINC 429 architectures with high-frequency sensor streams.
- Diagnostic Tools:Post-flight analysis software for maintenance scheduling optimization.
Predictive Maintenance dominates revenue; Real-Time Monitoring is gaining share fastest.
Installation:
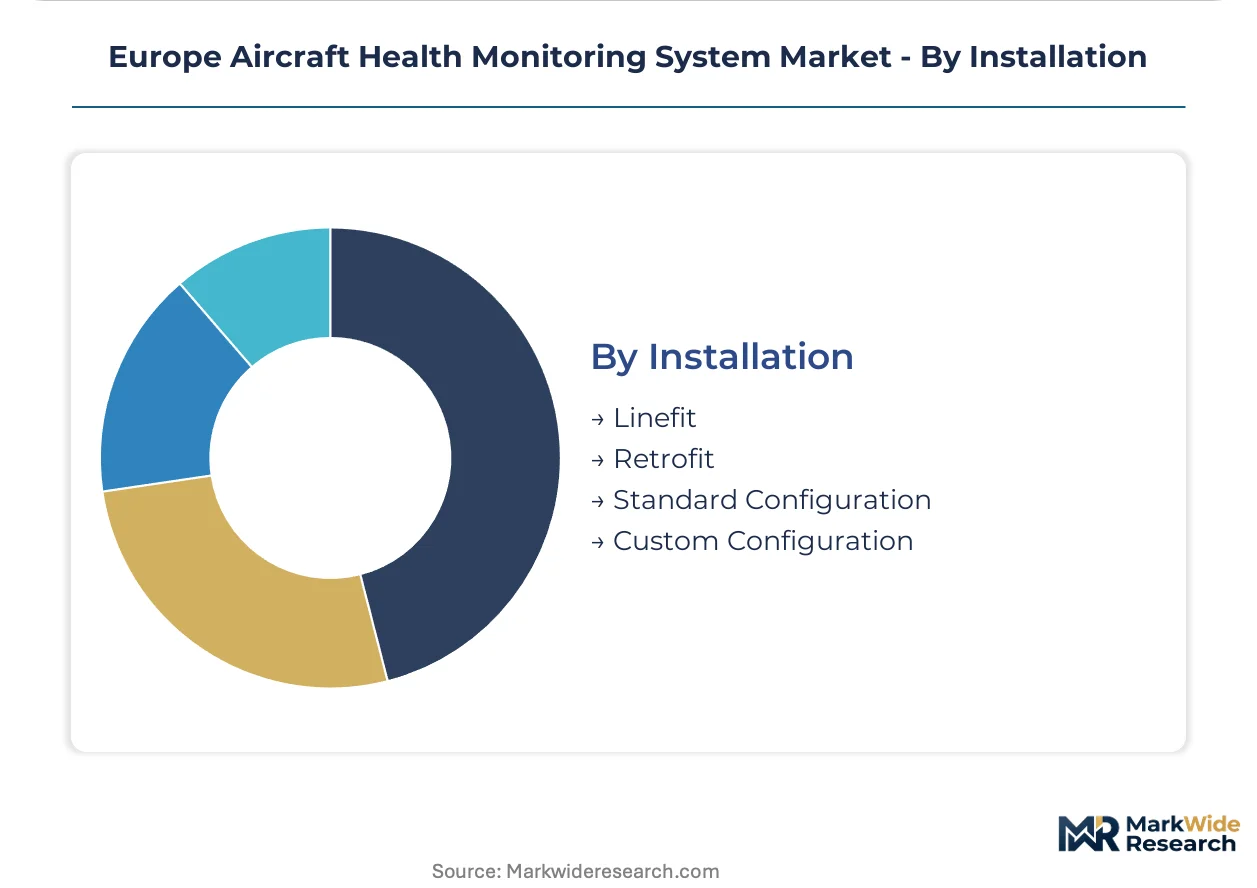
Installation type splits between OEM linefit programs concentrated in Toulouse and Hamburg, and retrofit cycles accelerating across aging A320ceo and 737-800 fleets.
- Retrofit:Sensor and hardware deployment onto in-service aircraft outside original manufacturing specifications. EASA Part-CAT amendments for continuous engine parameter logging compress compliance windows across EU-registered fleets, forcing accelerated retrofit timelines.
- Linefit:Factory-integrated health monitoring architectures specified at aircraft purchase. Airbus SE leverages integrated airframe-electronics design to embed diagnostics before first delivery.
- Standard Configuration:Pre-defined sensor packages for common narrow-body applications.
- Custom Configuration:Tailored monitoring architectures for specialized mission profiles or VIP aircraft.
Retrofit commands immediate volume; Linefit offers the steepest margin expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Europe, with Eastern European carriers prioritizing low-cost sensor retrofits while French and German flag carriers absorb premium analytics platforms without margin pressure.
Germany
Lufthansa Technik converts calendar-based maintenance contracts to condition-based models using real-time vibration analytics. The KBA enforces strict airworthiness certification timelines for predictive maintenance software validation. Hamburg and Frankfurt anchor the country's MRO provider concentration, where certified avionics engineers command premium wages for ARINC 429 legacy integration.
France
Air France Industries unbundles hardware procurement from analytics subscriptions across mixed Airbus-Boeing fleets. EASA Part-CAT amendments for continuous engine parameter logging compress compliance windows for aging A320ceo aircraft. The Toulouse-Aquitaine cluster concentrates OEM and tier-one supplier co-location, accelerating embedded health monitoring architecture development.
United Kingdom
Rolls-Royce controls both hardware deployment and data interpretation layers for its installed turbine base across UK operator fleets. The UK CAA aligns with EASA airworthiness directives while navigating post-Brexit data sovereignty constraints. London and Derby host engineering centers prioritizing edge-computing inference for reduced telemetry bandwidth.
Poland
Low-cost carriers operating aging Boeing 737NG fleets drive underserved demand for landing gear and APU monitoring retrofits. The country's national aviation regulator adopts EASA mandates with compressed implementation timelines. Warsaw and Krakow emerge as procurement hubs where price-sensitive buyers prioritize discrete sensor packages over bundled analytics.
Netherlands
KLM Engineering & Maintenance fragments traditional vendor relationships by sourcing edge hardware separately from cloud analytics. GDPR restrictions on transferring flight-parameter logs between maintenance facilities fragment fleet analytics capabilities. The Randstad region concentrates airline engineering departments standardizing on single analytics platforms across mixed OEM fleets.
Europe Aircraft Health Monitoring System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European AHMS landscape. Full-stack platform developers with integrated airframe-electronics architectures occupy premium positions, while component specialists capture volume through sensor manufacturing scale. Two strategic archetypes dominate: OEM-anchored systems integrators controlling design-stage embedding, and independent software vendors unbundling analytics from hardware procurement. Competitive intensity centers on M&A activity consolidating sensor manufacturing capacity and strategic partnerships bridging edge-computing hardware with cloud-based fleet analytics.
Within the OEM-anchored tier, Airbus SE exemplifies integrated platform development through design-stage health monitoring embedding. Safran SA and Rolls-Royce Plc occupy positions spanning proprietary sensor networks and predictive maintenance data interpretation layers. These three companies represent the dominant competitive anchors shaping procurement patterns across German, French, and UK operator fleets.
| Leading Market Players |
|---|
| Airbus SE |
| Safran SA |
| Rolls-Royce Plc |
| Deutsche Lufthansa AG |
| AFI KLM E&M |
| Meggitt Plc |
| SITA |
| General Electric Company |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day sensor procurement lead times from French tier-one suppliers compress hardware margins while amplifying pricing power for cloud analytics platforms. EASA certification timelines for embedded systems stretch to eighteen months, tethering aftermarket pricing to regulatory gatekeeping rather than manufacturing scale. Airlines unbundling hardware from software subscriptions fragment traditional bundled pricing models.
Pricing Analysis
After-market service contracts and predictive maintenance subscriptions capture lifetime value exceeding initial hardware deployment by significant multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by EASA certification grade and fleet integration complexity. Pricing pressure stems from Polish and Romanian low-cost carriers prioritizing discrete sensor packages over bundled analytics. MRO providers in Germany and France show lowest price sensitivity due to power-by-the-hour contract structures.
Supply Chain Analysis
Strait of Hormuz transit exposure for rare-earth magnet feedstocks creates chokepoint vulnerability for piezoelectric sensor manufacturing. Supply concentrates in France's Toulouse-Aquitaine cluster, Germany's Hamburg-Frankfurt corridor, and the UK's Derby aerospace corridor. Raw material dependencies span lithium niobate crystals, platinum thin-film elements, and high-temperature ceramic substrates. Single-source vulnerability for MEMS foundry capacity threatens sensor volume scaling. Distribution runs through OEM linefit channels and tier-one supplier retrofit networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as airlines unbundle hardware procurement from analytics subscriptions, creating niche openings for specialized software vendors and component suppliers.
For Market Incumbents: Fortify proprietary sensor network positions by deepening backward integration into MEMS foundry capacity. Airbus SE and Safran SA should accelerate EASA certification pathways for edge-computing inference hardware before independent software vendors capture analytics margins. Control of data interpretation layers remains the critical defensive lever against unbundling pressure. For New Entrants and Emerging Players: Lead with explainable diagnostic models validated under EU AI Act transparency standards for first-mover advantage in EASA certification queues. Polish and Romanian low-cost carriers operating aging Boeing 737NG fleets represent the most penetrable geography for landing gear and APU monitoring retrofits. Partner with regional MRO facilities to bypass incumbent distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates spinning non-core sensor manufacturing divisions amid portfolio rationalization. Long-term viability centers on vendors controlling both edge hardware deployment and cloud analytics interpretation layers. Watch EASA Part-CAT amendment implementation timelines as the inflection signal for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Convergence | Hybrid processing models combining Safran onboard inference with ground-based analytics capture software-layer margins. |
| EASA Certification Pathway Acceleration | Fast-track validation under EU AI Act transparency standards creates competitive moats for diagnostic model vendors. |
| Backward Integration into MEMS Foundry | Captive sensor manufacturing capacity insulates against rare-earth supply disruptions and foundry bottlenecks. |
| Regional MRO Partnership Network | Direct relationships with Polish and Romanian maintenance facilities bypass incumbent tier-one distribution control. |
| Digital Twin Platform Development | Continuous structural simulation integration into airline operations centers displaces discrete diagnostic modules. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EASA airworthiness directives, EU regulatory filings, and aerospace trade data. Primary interviews engaged fleet engineering directors at German and French network carriers, procurement leads at tier-one sensor suppliers, and certification specialists at MRO facilities. Secondary sources included EASA certification databases, REACH chemical compliance registries, and customs records for aerospace component trade flows. Bottom-up sensor deployment estimates triangulated against top-down fleet renewal projections.
Segmentation dimensions modeled span product type, end user, technology, and installation mode across the projection horizon. Aircraft age distribution and EASA mandate compliance timelines fed fleet-specific retrofit penetration curves. CAGRs derived from weighted average of OEM linefit growth and aftermarket retrofit acceleration scenarios. Regional price elasticity differentials calibrated against procurement pattern divergence between Eastern and Western European operators.
Forecasts assume regulatory continuity in EASA airworthiness regimes and EU AI Act implementation; material policy shifts would require re-modeling of certification timeline assumptions. Commodity volatility in rare-earth elements and F-Gas refrigerant phase-out schedules represent specific revision triggers. Practitioners should keep alternative scenarios live as REACH chemical compliance lists and EASA Part-CAT amendment finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market