
 Commercial Aircraft Health Monitoring Systems Market | 2026-2036
Commercial Aircraft Health Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Health Monitoring Systems Market Analysis
Carbon fiber composites replacing aluminum in next-generation airframes is realigning sensor placement strategies and calibration protocols for health monitoring systems. Safran leverages its integrated avionics portfolio to embed structural sensors directly into composite layups during manufacturing. RTX Corporation sustains competitive positioning through dual-use technology pipelines that serve both commercial aviation and defense health monitoring requirements. Meggitt specializes in high-temperature engine monitoring solutions that withstand the thermal loads of advanced turbofan architectures.
Commercial Aircraft Health Monitoring Systems encompass integrated sensor networks, data acquisition hardware, and analytical software platforms designed to continuously assess airframe integrity, propulsion performance, and cabin environmental parameters with sampling frequencies exceeding 1,000 Hz for critical structural nodes. Their primary purpose is to transition aviation maintenance from interval-based overhauls to condition-driven interventions, reducing aircraft-on-ground duration and extending component life cycles. Engine Condition Monitoring commands the largest installed base due to regulatory mandates on turbine performance tracking, while Machine Learning Algorithms represent the fastest-expanding technology segment as airlines deploy predictive models trained on historical failure patterns. Wireless Sensor Networks retain mature status in narrow-body applications but face margin compression from commoditized hardware.
The FAA mandates continuous airworthiness monitoring under 14 CFR Part 25, while EASA enforces comparable requirements through CS-25 certification standards, and China's CAAC aligns with dual carbon goals by promoting fuel efficiency gains through optimized maintenance scheduling. These regulatory frameworks directly shape product roadmaps by specifying minimum detectable crack lengths, response latency thresholds, and data retention periods for flight-critical systems. Stakeholders must monitor evolving certification timelines for AI-driven diagnostic tools as regulators develop qualification protocols for autonomous fault classification algorithms.
Market Dynamics
The transition from aluminum to carbon fiber composite airframes is restructuring sensor placement methodologies and recalibrating health monitoring architectures across the aviation sector. This materials shift demands entirely new integration protocols for structural sensing networks.
Growth Catalysts
- FAA Airworthiness Directives:Updated mandates under 14 CFR Part 25 on continuous structural monitoring are compressing OEM integration timelines and mandating fleet-wide sensor deployment for narrow-body and wide-body platforms.
- Machine Learning Algorithms:Airlines are deploying predictive models trained on historical failure patterns to transition maintenance from interval-based overhauls to condition-driven interventions.
- Full-Service Carriers:Major airlines in the United States are retrofitting existing fleets with predictive analytics platforms to reduce unscheduled maintenance events and aircraft-on-ground duration.
Market Restraints
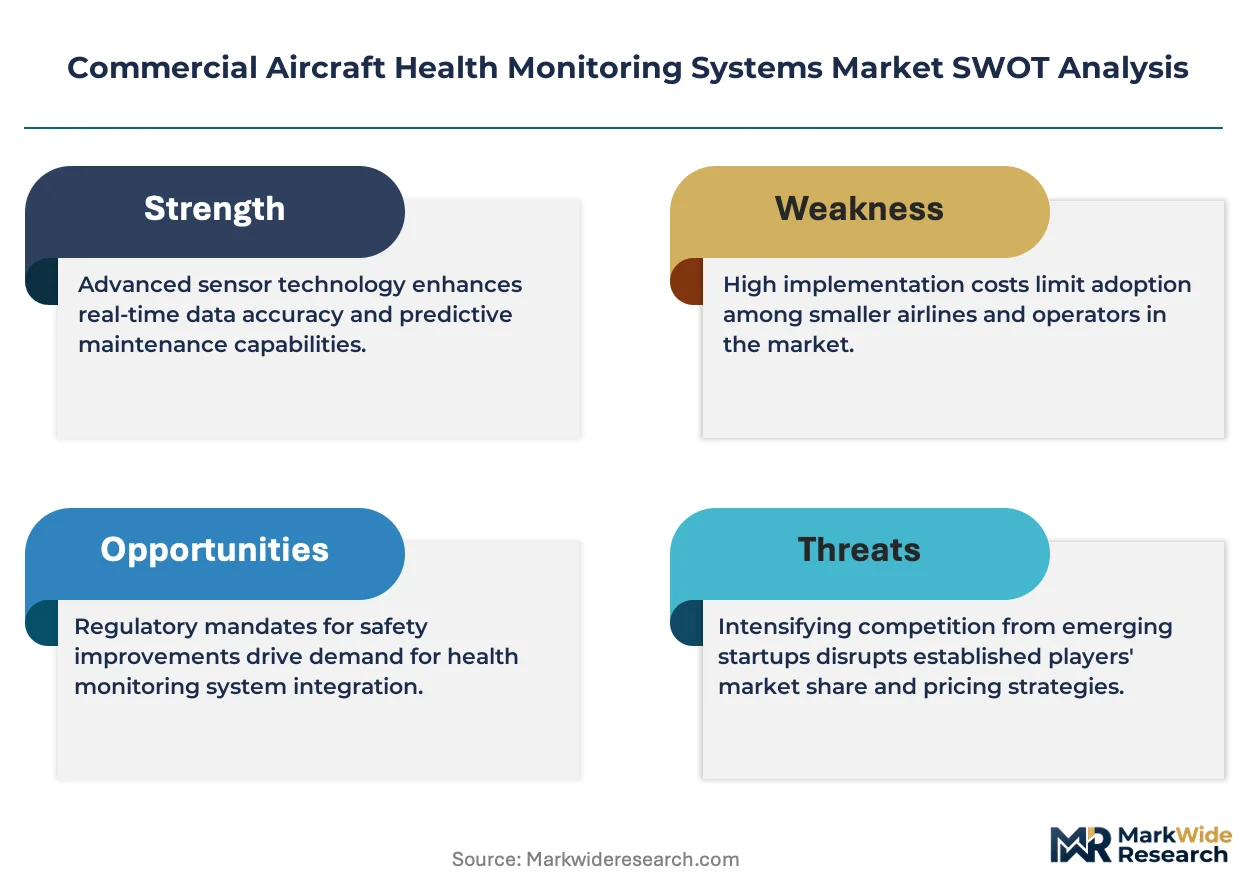
- Specialized Sensor Costs:High-temperature engine monitoring solutions capable of withstanding advanced turbofan thermal loads command premium pricing that limits retrofit penetration in aging fleets.
- Wireless Hardware Commoditization:Mature wireless sensor networks in narrow-body applications face margin compression as standardized hardware proliferates through non-specialized suppliers.
- Certification Latency:Evolving FAA and EASA protocols for AI-driven diagnostic tools create extended qualification timelines for autonomous fault classification algorithms.
Strategic Opportunities
- Composite Manufacturing Integration:Embedding structural sensors directly into carbon fiber layups during airframe production eliminates retrofit complexity and creates captive supplier relationships.
- Dual-Use Technology Pipelines:Defense health monitoring requirements for military aviation platforms provide development cost absorption and technology transfer pathways for commercial applications.
- China CAAC Alignment:The regulator's dual carbon goals promote fuel efficiency gains through optimized maintenance scheduling, creating policy tailwinds for predictive system adoption.
Industry Challenges
- Data Acquisition Hardware Integration:Sampling frequencies exceeding 1,000 Hz for critical structural nodes generate massive data volumes that strain legacy aircraft computing architectures and storage systems.
- Cross-Regulatory Harmonization:Divergent EASA CS-25 certification standards and FAA 14 CFR Part 25 requirements force redundant testing protocols for global platform certifications.
- Specialized Engineering Talent:The intersection of aerospace structures, sensor physics, and machine learning creates acute shortages in qualified diagnostic algorithm developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Health Monitoring Systems Market |
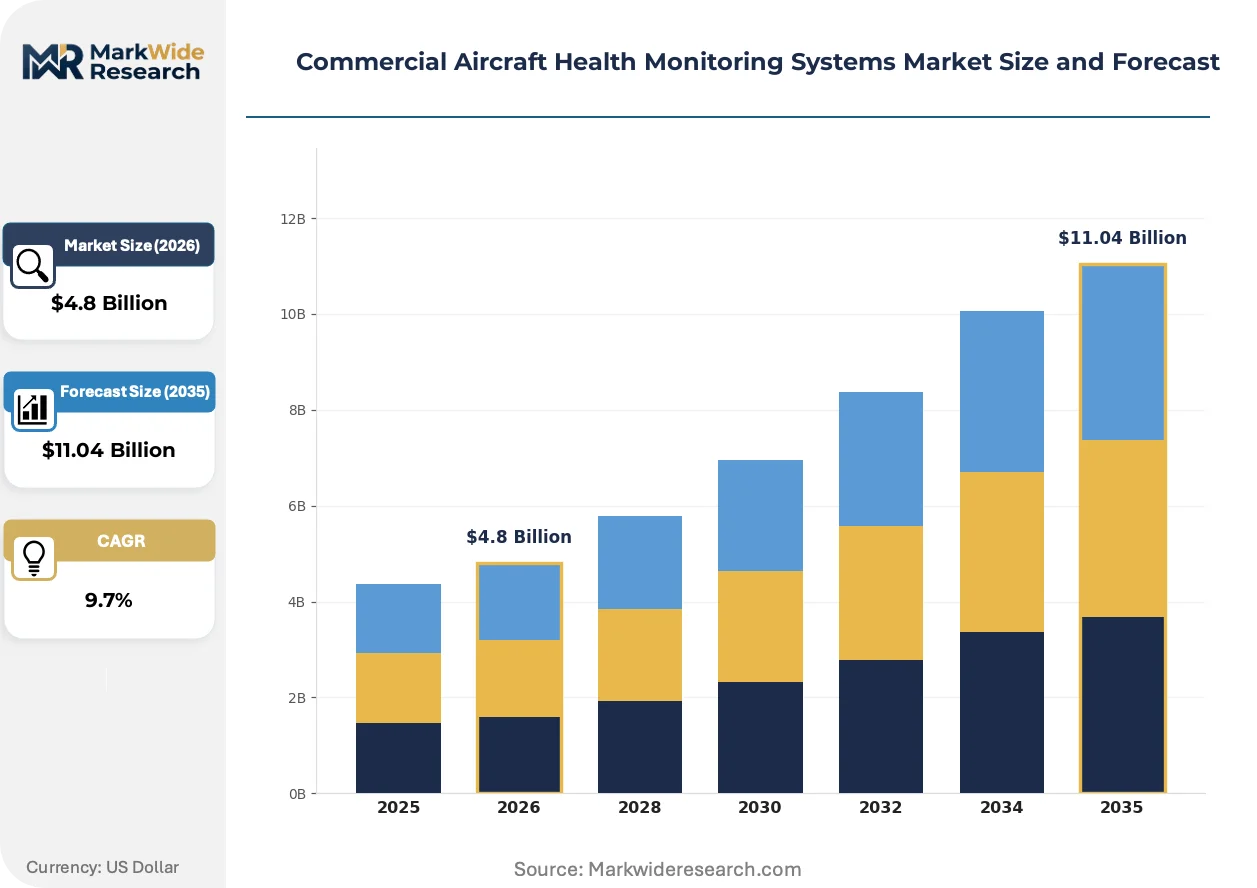
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Health Monitoring, Engine Condition Monitoring, Cabin Environment Monitoring, Power Management Systems Technology: Wireless Sensor Networks, Machine Learning Algorithms, Internet of Things, Cloud Computing End User: Commercial Airlines, Maintenance Repair Overhaul (MRO) Providers, Original Equipment Manufacturers (OEMs), Defense Contractors Application: Flight Safety Management, Predictive Maintenance, Operational Efficiency, Regulatory Compliance |
| Companies Covered | Safran, RTX Corporation, Airbus, Thales Group, Meggitt, Boeing, Honeywell International, RSL Electronics, GE Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Health Monitoring Systems Market Emerging Trajectories
Aviation maintenance economics are compressing intervention cycles from scheduled overhauls toward real-time condition assessment, reshaping how sensor networks, data infrastructure, and analytical platforms converge across fleet operations.
Edge computing architectures for aircraft health monitoring is decentralizing data processing from ground-based servers to onboard systems. Full-service carriers deploying narrow-body retrofits are adopting distributed processing nodes to reduce satellite bandwidth costs and enable real-time anomaly detection during flight. This topology is decentralizing the traditional hub-and-spoke data model that concentrated analytics in airline operations centers.
EASA's evolving CS-25 certification standards for autonomous fault classification are tightening response latency thresholds for flight-critical systems. The framework mandates specific minimum detectable crack lengths and data retention periods that force hardware redesigns in legacy platform upgrades. Engine condition monitoring systems face the steepest compliance curves given existing turbine performance tracking mandates.
Airline procurement of health monitoring capabilities is fragmenting from bundled OEM contracts toward unbundled component sourcing. Maintenance divisions now separately acquire sensor hardware, data platforms, and analytical services from specialized vendors rather than accepting integrated packages. This pattern is most visible in United States-based carriers retrofitting mid-life narrow-body fleets with best-of-breed predictive systems.
Commercial Aircraft Health Monitoring Systems Market Segmentation
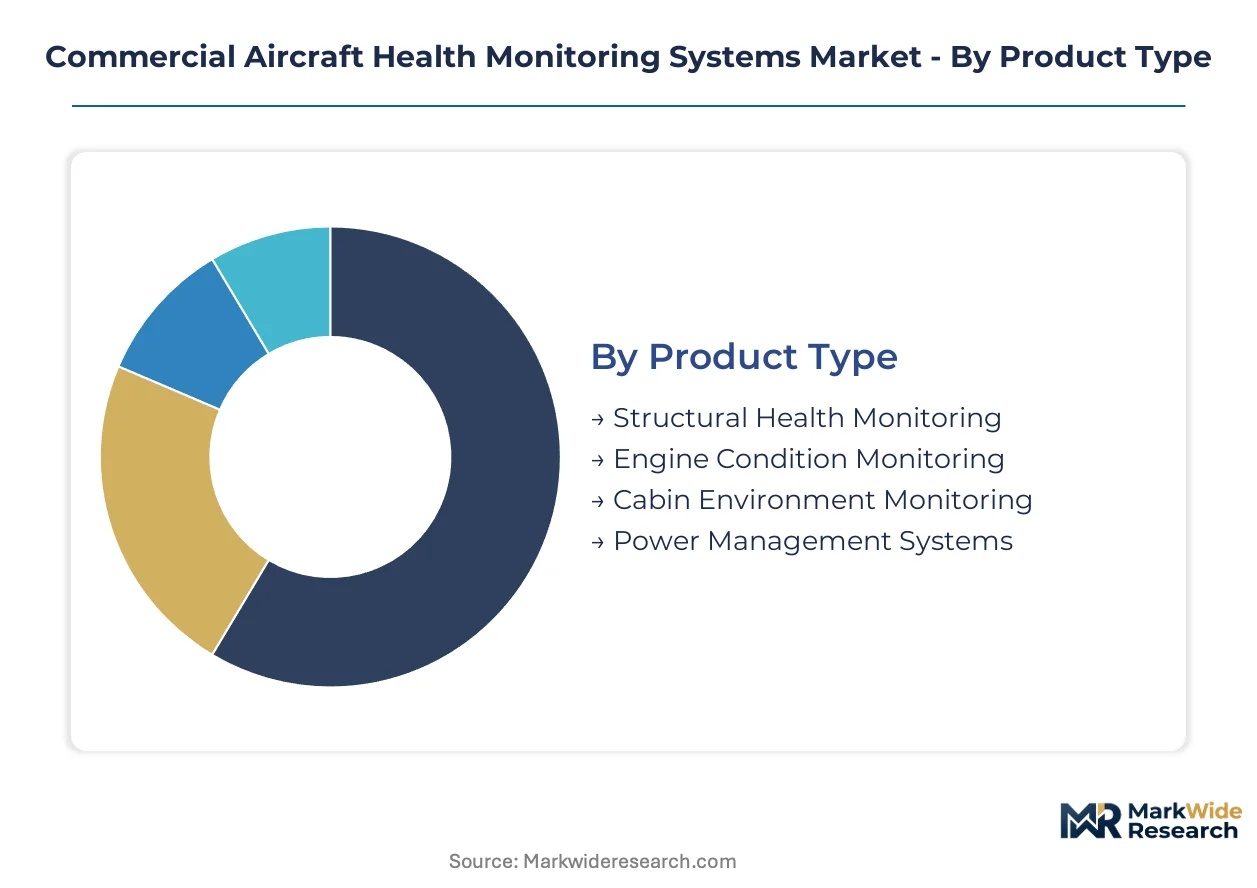
Segmentation in commercial aircraft health monitoring systems reveals how procurement decisions split between integrated OEM packages and unbundled specialist sourcing. Airlines now separately acquire sensor hardware, analytical platforms, and data services rather than accepting bundled offerings. This fragmentation creates distinct competitive arenas where technical specifications, certification timelines, and lifecycle costs drive supplier selection.
Product Type:
Standardization dominates structural and engine monitoring due to FAA airworthiness mandates, while cabin and power systems retain customization flexibility for airline-specific configurations.
- Structural Health Monitoring:Fiber optic and piezoelectric sensor networks embedded in composite airframes detect strain, delamination, and crack propagation with micro-precision. United States-based full-service carriers retrofitting narrow-body fleets drive retrofit demand as FAA 14 CFR Part 25 mandates compress integration timelines.
- Engine Condition Monitoring:High-temperature thermocouples, vibration sensors, and oil debris monitors track turbine performance parameters exceeding 1,000 Hz sampling rates. Regulatory mandates on turbine performance tracking create the largest installed base across commercial aviation platforms.
- Cabin Environment Monitoring:Pressure, temperature, and air quality sensors maintain passenger safety thresholds.
- Power Management Systems:Electrical load monitoring and battery health diagnostics for increasingly electrified aircraft architectures.
Most installed capacity flows through Engine Condition Monitoring. Expansion is steepest in Structural Health Monitoring.
Technology:
Cost tiers separate mature wireless hardware facing commoditization pressure from premium analytics platforms commanding sustained margins through proprietary algorithms.
- Wireless Sensor Networks:Standardized radio frequency and Bluetooth Low Energy modules transmit structural and engine data to onboard acquisition units. Narrow-body applications in aging fleets face margin compression as non-specialized suppliers proliferate standardized hardware.
- Machine Learning Algorithms:Predictive models trained on historical failure patterns enable autonomous fault classification and maintenance scheduling optimization. Airlines in the United States deploy these platforms to transition from interval-based overhauls to condition-driven interventions.
- Internet of Things:Connected device ecosystems integrating multiple sensor types into unified data streams.
- Cloud Computing:Scalable storage and processing infrastructure for fleet-wide analytics and long-term trend analysis.
Wireless Sensor Networks carry the heaviest installed base. Machine Learning Algorithms are gaining share fastest.
End User:
Volume concentrates with commercial airlines operating large fleets, while margin accrues to MRO providers selling analytical services and OEMs capturing embedded sensor contracts.
- Commercial Airlines:Fleet operators deploying health monitoring across narrow-body and wide-body platforms to minimize aircraft-on-ground duration. United States majors lead retrofit investments as unscheduled maintenance reduction becomes a competitive priority.
- Maintenance Repair Overhaul (MRO) Providers:Independent service specialists offering predictive analytics and diagnostic services to airlines without in-house capabilities.
- Original Equipment Manufacturers (OEMs):Airframe and engine producers embedding sensors during manufacturing and capturing long-term service contracts.
- Defense Contractors:Military aviation platforms with dual-use technology transfer pathways to commercial applications.
Commercial Airlines account for the dominant share of deployed systems. Defense Contractors show the steepest expansion trajectory.
Application:
Maturity varies from mandatory regulatory compliance with standardized requirements to discretionary operational efficiency investments with variable returns.
- Flight Safety Management:Real-time structural integrity assessment and emergency alert systems for critical failure scenarios.
- Predictive Maintenance:Algorithm-driven component replacement scheduling that extends life cycles and reduces unscheduled events. United States airlines prioritize this application to compress maintenance intervention cycles.
- Operational Efficiency:Fuel burn optimization and route planning through continuous performance monitoring.
- Regulatory Compliance:Automated data logging and reporting to satisfy FAA 14 CFR Part 25 and EASA CS-25 certification requirements.
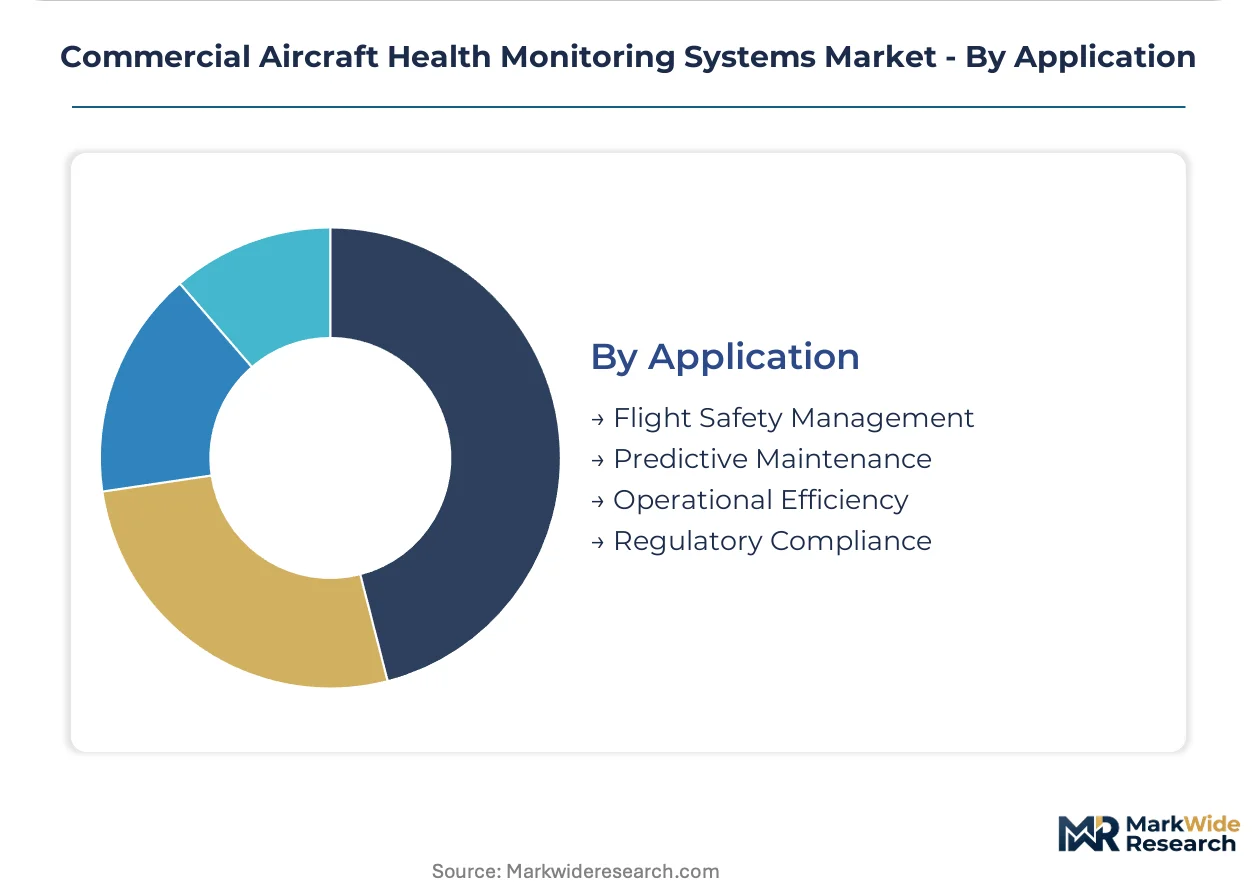
Regulatory Compliance absorbs the most sensor deployments. Predictive Maintenance shows the fastest climb in new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle-Tacoma-Bellevue anchors global demand for commercial aircraft health monitoring systems, hosting Boeing's integrated manufacturing and sensor development operations alongside a dense supplier ecosystem.
United States
Full-service carriers in Dallas-Fort Worth and Chicago are retrofitting narrow-body fleets with predictive analytics platforms to compress maintenance intervention cycles. FAA airworthiness directives under 14 CFR Part 25 mandate continuous structural monitoring, accelerating OEM integration timelines. The Pacific Northwest cluster concentrates embedded sensor manufacturing for next-generation composite airframes.
France
Airframe producers near Toulouse embed fiber optic networks directly into carbon fiber layups during manufacturing, eliminating retrofit complexity. EASA CS-25 certification standards for autonomous fault classification tighten response latency thresholds for flight-critical systems. The Occitanie aerospace corridor specializes in high-temperature engine monitoring thermocouples for advanced turbofan architectures.
Germany
Hamburg-based maintenance divisions separately acquire sensor hardware and analytical services from specialized vendors rather than accepting bundled OEM packages. The country's national aviation regulator enforces data retention periods for structural health monitoring that exceed FAA minimums. Bavarian industrial clusters develop edge computing architectures that decentralize processing from ground servers to onboard distributed nodes.
China
CAAC alignment with dual carbon goals promotes fuel efficiency gains through optimized maintenance scheduling, creating policy tailwinds for predictive system adoption. The regulator's certification protocols for AI-driven diagnostic tools are evolving alongside domestic machine learning platform deployment. Yangtze River Delta manufacturing centers produce standardized wireless sensor modules for narrow-body retrofit applications.
United Kingdom
Derby-based engine specialists capture long-term service contracts through turbine performance tracking mandates that create the largest installed base across commercial aviation. The Civil Aviation Authority coordinates with EASA on cross-regulatory harmonization for crack detection minimums. Farnborough-area defense contractors maintain dual-use technology pipelines that transfer military health monitoring capabilities to commercial platforms.
Commercial Aircraft Health Monitoring Systems Market Vendor Landscape
Global majors compete with regional champions across certification timelines and composite integration depth. The vendor base splits between airframe-embedded specialists and aftermarket retrofit providers, with tiered pricing separating premium-tier integrated systems from commoditized wireless hardware. Three archetypes dominate: vertically integrated aerospace conglomerates with captive sensor manufacturing, independent component specialists selling unbundled hardware, and predictive analytics software vendors licensing algorithm platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as airlines fragment procurement across supplier categories.
Within the integrated systems tier, Safran and RTX Corporation exemplify archetypes combining avionics portfolios with manufacturing-stage sensor embedding. Meggitt occupies a position among high-temperature specialists serving engine monitoring applications where thermal load tolerance commands sustained margins. These three anchors illustrate how competitive positioning depends on whether suppliers capture value at the manufacturing stage through embedded contracts or at the aftermarket stage through retrofit hardware and software licensing.
| Leading Market Players |
|---|
| Safran |
| RTX Corporation |
| Airbus |
| Thales Group |
| Meggitt |
| Boeing |
| Honeywell International |
| RSL Electronics |
| GE Aviation |
| Others |
Supply Flow & Price Mechanics
Carbon fiber composite manufacturing integration is simultaneously compressing retrofit hardware margins and concentrating sensor procurement decisions at the airframe production stage. This materials transition forces suppliers to capture value through embedded manufacturing contracts rather than aftermarket hardware sales, reshaping both cost structures and buyer-supplier power dynamics.
Pricing Analysis
Input-cost pass-through from high-temperature thermocouples and fiber optic strain sensors drives pricing stratification across certification tiers. Premium pricing accrues to EASA CS-25 and FAA 14 CFR Part 25 certified systems with guaranteed response latencies, while commoditized wireless modules face cost compression from standardized Bluetooth Low Energy hardware. Price differentiation hinges on thermal load tolerance and autonomous fault classification capabilities. Margins are tightening in narrow-body wireless retrofit segments as Yangtze River Delta producers flood standardized sensor modules. Commercial airlines with aging aluminum fleets exhibit highest price sensitivity, whereas OEMs embedding sensors during composite layup accept premium pricing for manufacturing-stage integration.
Supply Chain Analysis
Single-source vulnerability sits with specialized high-temperature thermocouple foundries in France and Germany that serve advanced turbofan architectures. Geographic supply concentration centers on the United States for edge computing hardware, France for fiber optic embedding equipment, and China for standardized wireless modules. Raw material dependencies include rare-earth elements for piezoelectric sensors, high-purity silica for fiber optics, and nickel-based alloys for engine thermocouples. Tariff exposure on Chinese wireless components creates supply chain risk for narrow-body retrofit programs. Distribution runs through OEM direct contracts for embedded systems and MRO channel partners for aftermarket analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EASA's tightening CS-25 latency thresholds and CAAC's dual carbon policy tailwinds, with regulatory compliance costs in Europe funding technology transfer opportunities to Asia-Pacific maintenance optimization demand.
For Market Incumbents: Deploy manufacturing-stage embedding contracts to lock out retrofit competitors. Safran and RTX Corporation exemplify this lever through composite layup integration that eliminates aftermarket hardware penetration. Incumbents must absorb R&D costs for AI-driven diagnostic certification while defending against unbundled software vendors licensing predictive analytics separately from sensor hardware. Capacity addition in Toulouse and Hamburg secures proximity to Airbus and Lufthansa Technik maintenance clusters. For New Entrants and Emerging Players: MRO analytics service providers represent the most penetrable channel partner type for algorithm-only vendors lacking manufacturing capabilities. White-space targets include predictive maintenance platforms for mid-life narrow-body fleets operated by United States regional carriers and edge computing nodes for satellite bandwidth cost reduction. New entrants should pursue unbundled procurement patterns among German maintenance divisions that separately acquire sensor hardware and analytical services. For Investors and Strategic Acquirers: Roll-up economics work for specialized high-temperature sensor manufacturers because thermal load tolerance expertise commands sustained margins immune to wireless hardware commoditization. Platform consolidation across fiber optic embedding, engine thermocouples, and predictive software creates cross-selling opportunities to OEM embedded contracts and MRO service agreements. Long-term viability hinges on regulatory ratification timelines for autonomous fault classification algorithms. The signal to watch is FAA qualification protocol publication for AI-driven diagnostic tools, which would de-risk algorithm-heavy acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Integration | Embedding sensors during carbon fiber layup eliminates retrofit complexity and creates captive supplier relationships with Airbus and Boeing. |
| Dual-Use Technology Pipeline Development | Defense health monitoring requirements for military aviation absorb R&D costs that transfer to commercial applications through RTX Corporation's integrated portfolio. |
| Predictive Analytics Platform Licensing | Machine learning algorithms trained on historical failure patterns enable United States airlines to transition from interval-based overhauls to condition-driven interventions. |
| Edge Computing Architecture Deployment | Distributed processing nodes reduce satellite bandwidth costs for full-service carriers retrofitting narrow-body fleets with real-time anomaly detection. |
| CAAC Certification Alignment | Dual carbon policy compliance creates policy tailwinds for predictive system adoption through fuel efficiency gains from optimized maintenance scheduling. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline fleet managers, MRO procurement directors, OEM sensor integration engineers, and FAA certification specialists with secondary validation against EASA CS-25 amendment filings, FAA airworthiness directive databases, and customs records for wireless sensor module trade flows. Bottom-up triangulation across installed base estimates and top-down validation through aerospace OEM revenue disclosures anchored market sizing.
Segment-weighting approaches distributed value across product type, technology, end user, and application dimensions, with additional modeling for regional regulatory cluster adoption patterns. CAGRs were derived from regression analysis of historical fleet retrofit penetration rates and projected OEM embedded sensor contract awards. Forecast inputs included narrow-body fleet age distributions, composite airframe production ramp schedules, and evolving qualification timelines for autonomous fault classification algorithms across the analysis window.
Revisions become necessary when FAA or EASA publication of AI-driven diagnostic qualification protocols accelerates or delays, when composite airframe production rates shift, or when defense-to-commercial technology transfer pathways constrict. Forecasts reflect documented assumptions about regulatory harmonization progress and airline unbundled procurement persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market