
 Helicopter Aeronautical Software Market | 2026-2036
Helicopter Aeronautical Software Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Aeronautical Software Market Intelligence
EU Green Deal aviation targets is broadening the addressable market for fuel-optimization flight management modules across European rotorcraft fleets. L3Harris Technologies leverages its embedded systems heritage to dominate military mission-computing contracts. Kongsberg anchors Nordic offshore helicopter segments with terrain-awareness navigation suites. Collins Aerospace sustains aftermarket leverage through proprietary maintenance software protocols locked to its avionics hardware.
Helicopter aeronautical software encompasses embedded and cloud-deployed applications governing flight path computation, engine performance monitoring, communication relay management, and predictive maintenance algorithms, typically operating under DO-178C safety assurance standards for airborne systems. The software serves to reduce pilot workload, optimize fuel burn, and extend component life cycles in both civilian and military rotary-wing operations. Flight Management and Navigation product categories command the deepest installed base, though Cloud-Based deployment is expanding fastest as fleet operators seek centralized data analytics. Civil Aviation end users generate the largest revenue pool, while Surveillance applications for law enforcement and border patrol exhibit the steepest growth trajectory.
FAA NextGen mandates and EASA rotorcraft certification standards shape product roadmaps by requiring continuous software updates for airspace interoperability. Military procurement across NATO frameworks imposes additional security hardening requirements that filter into civilian product tiers. Stakeholders must weigh the capital intensity of embedded hardware refresh cycles against the operational flexibility offered by hybrid cloud architectures as fleet connectivity standards crystallize.
Market Dynamics
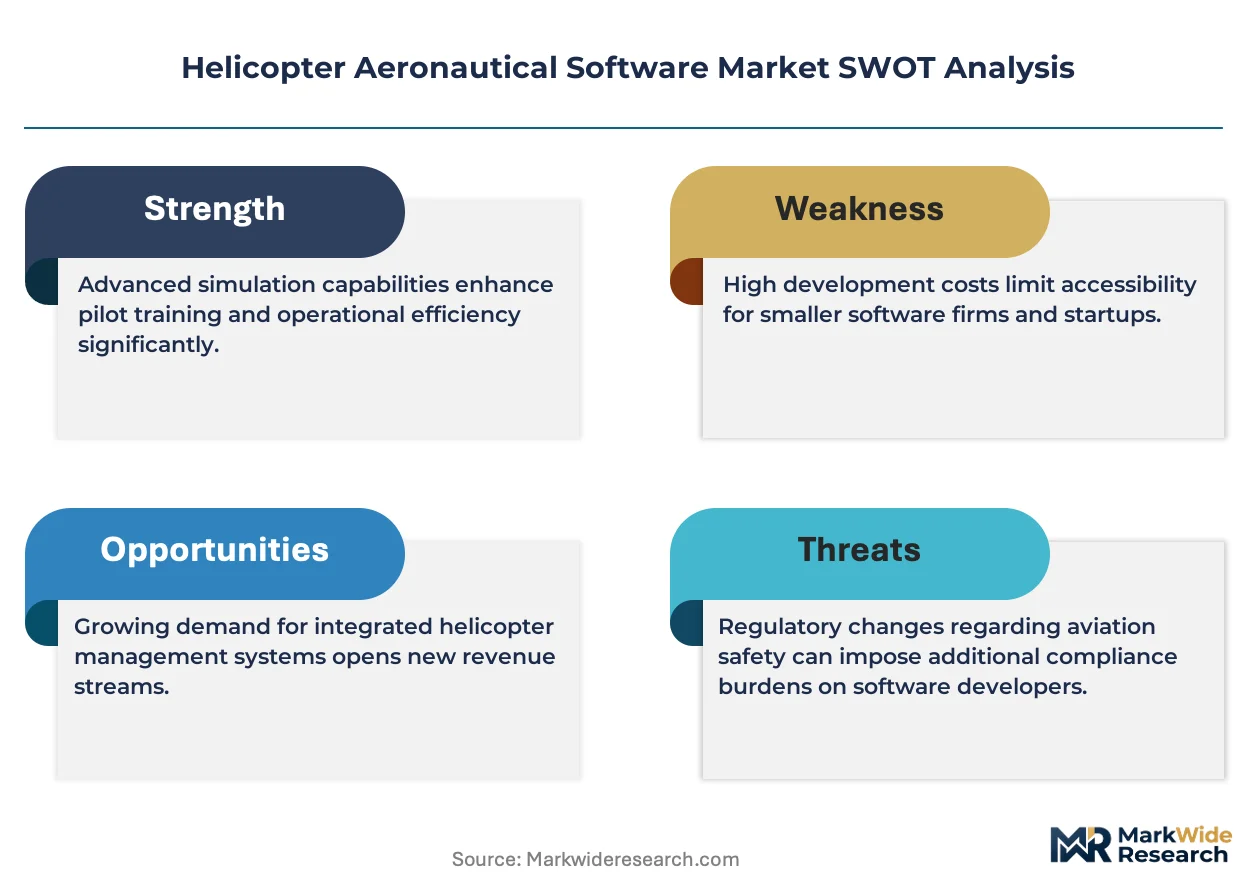
DO-178C safety assurance standards are tightening development cycles as avionics suppliers absorb escalating certification costs for airborne software systems.
Growth Catalysts
- FAA NextGen Mandates:United States military operators are accelerating procurement of mission-critical avionics suites to satisfy airspace interoperability requirements for helicopter integration.
- EU Green Deal Aviation Targets:Fuel-optimization flight management modules are broadening their addressable market across European rotorcraft fleets as carbon reduction deadlines approach.
- German Fleet Modernization:Bundespolizei and ADAC air rescue programs are driving concentrated demand for predictive maintenance algorithms and terrain-awareness navigation systems.
Market Restraints
- Embedded Hardware Refresh Cycles:Capital intensity of replacing legacy mission-computing hardware constrains software upgrade velocity for mid-size fleet operators.
- Supply Concentration in Nordic Offshore:Kongsberg's dominance in terrain-awareness navigation creates dependency risk for North Sea helicopter operators seeking alternative suppliers.
- NATO Security Hardening Requirements:Additional cryptographic and anti-tamper specifications for military procurement filter into civilian tiers, elongating development timelines.
Strategic Opportunities
- Cloud-Based Deployment Architecture:Fleet operators are migrating toward centralized data analytics platforms that enable remote engine performance monitoring across distributed rotorcraft networks.
- Surveillance Application Expansion:Law enforcement and border patrol segments exhibit steep growth trajectories for communication relay management software.
- Hybrid Cloud Architectures:Operational flexibility gains from combining embedded edge computing with cloud analytics are attracting civil aviation end users seeking lifecycle cost reduction.
Industry Challenges
- DO-178C Certification Timeline Compression:Continuous software update requirements for airspace interoperability strain verification and validation resource allocation.
- Proprietary Maintenance Protocol Lock-In:Collins Aerospace's hardware-tied software ecosystems create switching friction for aftermarket service competition.
- Legacy Avionics Integration Complexity:Hybrid architectures must bridge decades-old embedded systems with modern connectivity standards without compromising safety integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Aeronautical Software Market |
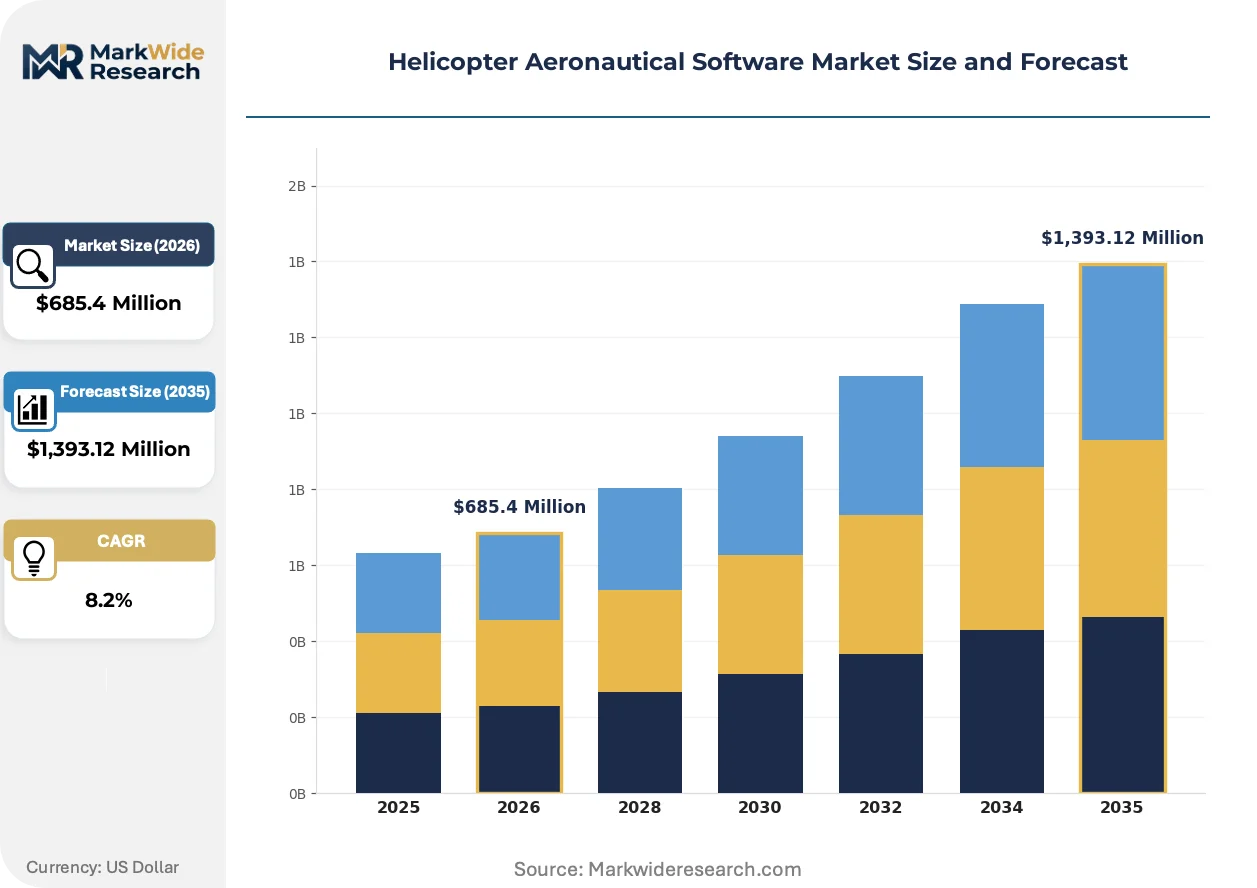
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
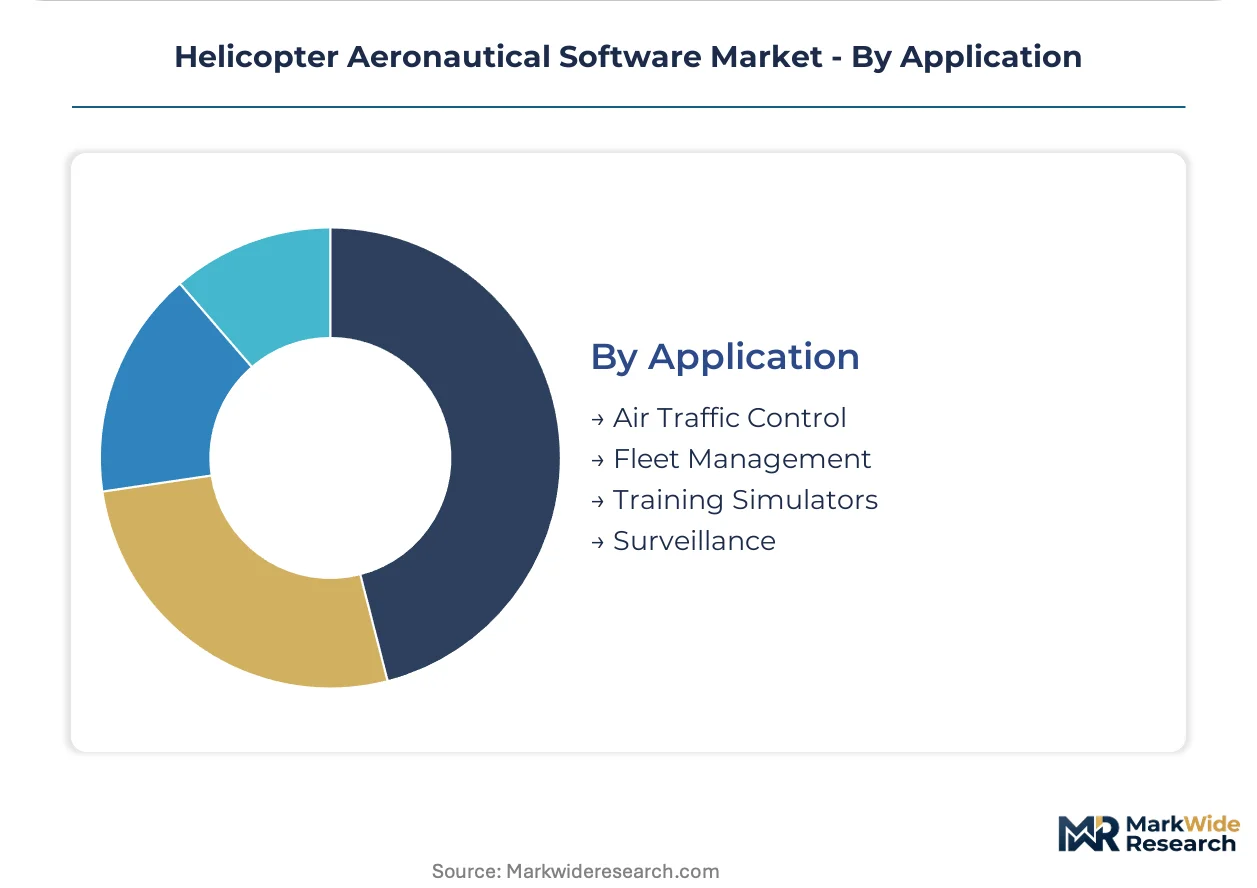
| Segmentation | Product Type: Flight Management, Navigation, Communication, Maintenance End User: Civil Aviation, Military, OEMs, Charter Services Deployment: On-Premises, Cloud-Based, Hybrid, Embedded Application: Air Traffic Control, Fleet Management, Training Simulators, Surveillance |
| Companies Covered | Abaco Systems, Fugro, L3Harris Technologies, FreeFlight Systems, Kongsberg, Aspen Avionics, Dassault Systèmes, Ramco Systems, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Aeronautical Software Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is redefining real-time decision architectures for rotary-wing platforms, compressing latency thresholds for critical flight functions.
Machine learning-based predictive maintenance is expanding into engine health monitoring and component lifecycle forecasting for offshore oil-and-gas transport fleets. North Sea operators are deploying these systems across multi-aircraft networks to reduce unscheduled downtime. The technology is expanding into adjacent applications including vibration analysis and gearbox wear prediction.
EASA rotorcraft certification standards are mandating enhanced flight data recording and transmission capabilities for new type certificates. Manufacturers must embed continuous monitoring protocols that stream operational parameters to ground-based analytics platforms. Civil aviation operators in Germany and France are responding by consolidating vendor relationships to simplify compliance documentation.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete software subscription tiers. Fleet managers are separating predictive analytics licenses from hardware support packages to match expenditure with actual utilization. This pattern is most visible among United States-based air medical operators managing mixed-vendor rotorcraft portfolios.
Helicopter Aeronautical Software Market Segmentation
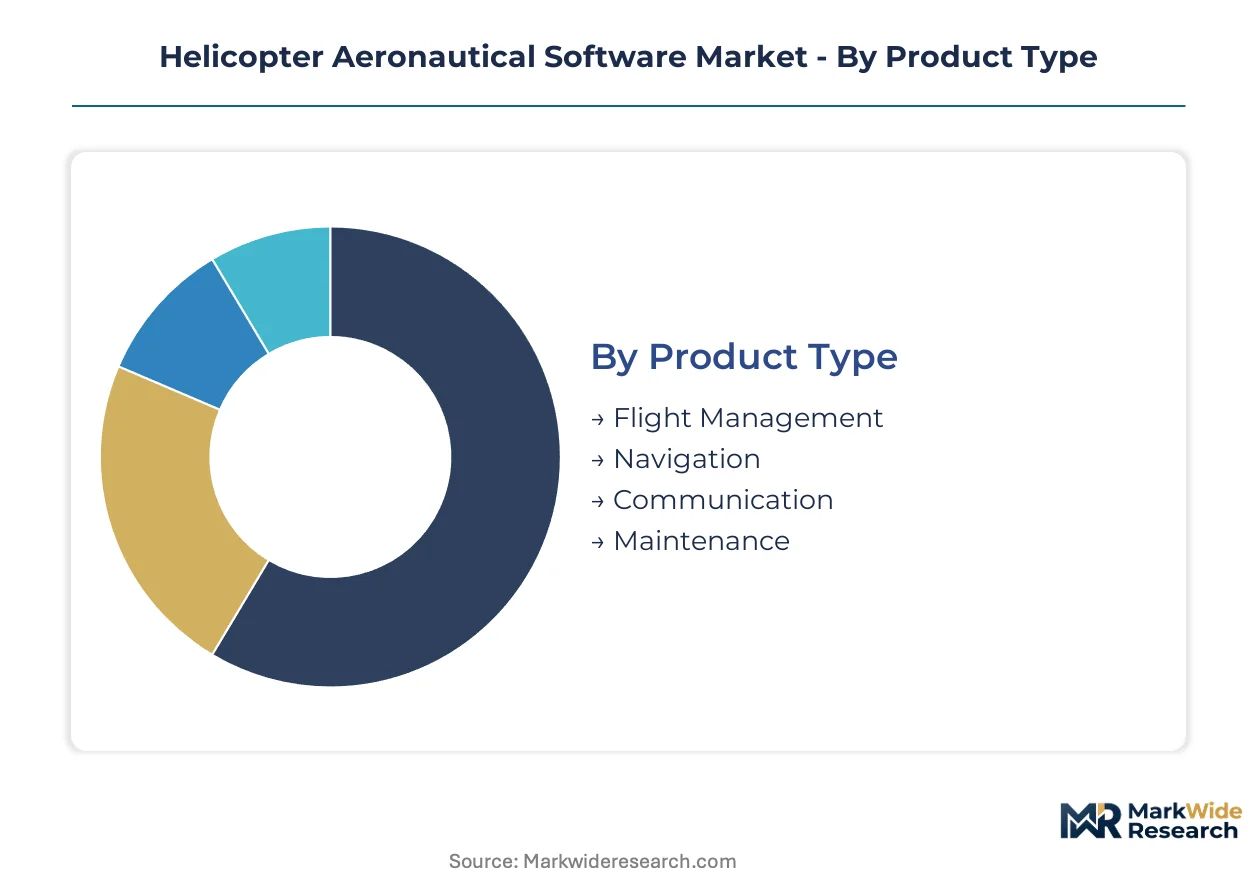
Segmentation in helicopter aeronautical software reveals how safety certification requirements, fleet connectivity architectures, and procurement authority structures fragment demand across distinct technology tiers. Each axis shapes vendor product roadmaps and customer acquisition economics differently.
Product Type:
Technical specification depth determines certification burden and aftermarket revenue durability across software modules.
- Flight Management:Core algorithms governing flight path computation, fuel burn optimization, and waypoint sequencing operate under DO-178C safety assurance standards. Demand concentrates in German air rescue fleets where Bundespolizei modernization mandates drive replacement of legacy mission-computing suites.
- Navigation:Terrain-awareness and GPS/INS integration modules require continuous updates for airspace interoperability under FAA NextGen timelines. Offshore helicopter operators in the North Sea anchor procurement volume as they retrofit aging rotorcraft for instrument flight rule expansion.
- Communication:Relay management software enabling pilot-controller data link and satellite connectivity.
- Maintenance:Predictive algorithms for engine performance monitoring and component lifecycle forecasting.
Mature deployment sits with Flight Management. Newer deployment is concentrated in Maintenance.
End User:
Procurement authority and budget cycle predictability create divergent vendor engagement models across customer categories.
- Civil Aviation:Fleet operators managing mixed-vendor rotorcraft portfolios prioritize operational flexibility and lifecycle cost reduction. United States air medical services drive subscription unbundling trends as they separate predictive analytics licenses from hardware support packages.
- Military:NATO framework procurement imposes cryptographic hardening and anti-tamper specifications that elongate development timelines. Mission-critical avionics suite procurement accelerates as United States operators satisfy airspace interoperability mandates.
- OEMs:Helicopter manufacturers embedding software at production for type certification compliance.
- Charter Services:On-demand operators seeking modular software tiers matched to utilization patterns.
Revenue concentration favors Civil Aviation. Steepest expansion trajectory belongs to Military.
Deployment:
Architecture choice trades capital intensity against operational agility as fleet connectivity standards crystallize.
- Cloud-Based:Centralized data analytics platforms enable remote engine performance monitoring across distributed rotorcraft networks. European operators respond to EASA enhanced flight data recording mandates by consolidating vendor relationships for ground-based analytics integration.
- Embedded:Edge-resident software operating within hardened mission-computing hardware maintains deterministic latency for safety-critical functions. Capital intensity of hardware refresh cycles constrains upgrade velocity for mid-size fleet operators.
- On-Premises:Local server installations for operators with restricted data sovereignty requirements.
- Hybrid:Combinations of embedded edge computing with cloud analytics gaining traction among cost-sensitive civil aviation end users.
Installed base dominance rests with Embedded. Cloud-Based deployment is expanding most quickly.
Application:
Functional use case determines integration complexity and regulatory exposure for software vendors.
- Surveillance:Communication relay management and sensor fusion software for law enforcement and border patrol missions. German Bundespolizei fleet modernization programs concentrate demand for multi-spectral imaging integration and real-time data transmission.
- Fleet Management:Network-level scheduling, maintenance coordination, and asset tracking across multi-aircraft operations. Offshore oil-and-gas transport operators in the North Sea deploy these systems to reduce unscheduled downtime across helicopter networks.
- Air Traffic Control:Ground-based separation assurance and flow management systems interfacing with rotorcraft avionics.
- Training Simulators:Synthetic environment software for pilot qualification and procedure rehearsal.
Established penetration characterizes Fleet Management. Surveillance exhibits the fastest share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fort Worth anchors North American rotorcraft software engineering, with military mission-computing suppliers clustered along the Interstate 35 corridor between Texas and Oklahoma.
United States
FAA NextGen mandates for helicopter airspace interoperability drive software refresh cycles across military and civil fleets. United States operators accelerate procurement of mission-critical avionics suites to satisfy these regulatory timelines. The Dallas-Fort Worth metroplex concentrates embedded systems engineering talent serving both defense and commercial rotorcraft markets.
Germany
Bundespolizei and ADAC air rescue programs generate concentrated demand for predictive maintenance algorithms and terrain-awareness navigation. EASA rotorcraft certification standards mandate enhanced flight data recording capabilities that reshape vendor selection criteria. Bavaria hosts specialized avionics integration facilities supporting fleet modernization across federal police and emergency medical services.
United Kingdom
North Sea offshore helicopter operators retrofit aging rotorcraft for instrument flight rule expansion, anchoring demand for GPS/INS integration modules. The country's national aviation regulator aligns with EASA timelines for continuous monitoring protocol implementation. Aberdeen maintains its position as the primary cluster for oil-and-gas transport fleet management software deployment.
France
Civil aviation operators consolidate vendor relationships to simplify compliance documentation for EASA enhanced flight data transmission mandates. The country's national aerospace regulator enforces strict type certification requirements for new helicopter software integrations. Toulouse hosts engineering centers developing synthetic environment software for pilot qualification systems.
Norway
Offshore oil-and-gas transport fleets deploy machine learning-based predictive maintenance across multi-aircraft networks to reduce unscheduled downtime. Kongsberg anchors terrain-awareness navigation supply for North Sea helicopter operators. Stavanger concentrates rotorcraft fleet management software engineering serving North Sea energy sector logistics.
Helicopter Aeronautical Software Market Key Industry Players
The competitive structure tilts toward defense-heritage systems integrators with embedded avionics certification expertise. Tier-one suppliers leverage DO-178C safety assurance capabilities to capture military mission-computing contracts, while specialized navigation vendors dominate offshore helicopter segments. Three archetypes define the field: aerospace conglomerates with proprietary hardware-software ecosystems, standalone avionics specialists, and emerging cloud-native platform providers. Consolidation through strategic acquisitions and technology licensing agreements reshapes vendor positioning as fleet operators seek unified compliance solutions.
Within the defense-integrated tier, L3Harris Technologies and Collins Aerospace exemplify the hardware-software bundling model that creates aftermarket switching friction. Kongsberg occupies a position as the terrain-awareness navigation anchor for Nordic offshore segments. These three represent contrasting strategic postures: bundled ecosystem lock-in versus specialized geographic segment dominance.
| Leading Market Players |
|---|
| Abaco Systems |
| Fugro |
| L3Harris Technologies |
| FreeFlight Systems |
| Kongsberg |
| Aspen Avionics |
| Dassault Systèmes |
| Ramco Systems |
| Collins Aerospace |
| Others |
Cost & Logistics Intelligence
DO-178C certification labor costs cascade through three pricing tiers as embedded software suppliers pass verification and validation overhead downstream to military procurement officers and civil fleet operators.
Pricing Analysis
Uptime guarantees anchor value-based pricing for predictive maintenance modules, with subscription tiers scaling by fleet size and data throughput volume. Three-tier pricing structure across premium, standard, and economy levels separates DO-178C certified mission-critical suites from uncertified analytics tools and open-source navigation alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because cloud-native entrants are undercutting legacy hardware-software bundles. Mid-size civil fleet operators exhibit highest price sensitivity; NATO military procurement shows lowest.
Supply Chain Analysis
DO-178C qualification gates concentrate qualified engineering talent in the United States, Germany, and France, where regulatory proximity accelerates certification timelines. Embedded mission-computing hardware draws from semiconductor fabs in Taiwan, specialized avionics foundries in the United States, and precision sensor manufacturers in Germany. Single-source vulnerability sits with terrain-awareness navigation chipsets sourced through Kongsberg's Nordic supply base. Distribution runs through direct OEM integration for new rotorcraft and aftermarket avionics dealers for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DO-178C compliance costs erect a barrier-to-entry moat that rewards incumbent certification infrastructure while filtering out undercapitalized software entrants.
For Market Incumbents: Extend proprietary maintenance protocol ecosystems to deepen switching friction against cloud-native challengers. Consolidate German and United States engineering centers to compress DO-178C validation timelines as EASA and FAA update interoperability mandates. Vertical integration into edge-computing hardware secures deterministic latency performance for safety-critical flight functions.
For New Entrants and Emerging Players: Cloud-native SaaS platforms offer the lowest-friction entry path for mid-size civil operators unbundling predictive analytics from legacy hardware support. White-space concentrates in North Sea offshore fleet management and United States air medical subscription tiers. Partner with established avionics dealers for regulatory credibility rather than pursuing direct OEM certification.
For Investors and Strategic Acquirers: German Bundespolizei fleet modernization contract awards are the leading indicator that surveillance application software is approaching inflection velocity. Long-term viability favors acquirers of DO-178C-certified embedded specialists with NATO security clearances. Watch for EASA enhanced flight data recording mandate enforcement as the signal triggering consolidation among compliance-capable vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Certification Investment | Unlocks NATO military procurement and EASA civil type certificates for mission-critical modules. |
| Hybrid Cloud Architecture Launch | Combines embedded edge computing with centralized analytics to capture cost-sensitive civil operators. |
| Surveillance Software Partnership | Integrates multi-spectral imaging with communication relay for German Bundespolizei modernization. |
| Predictive Maintenance Acquisition | Adds machine learning engine health monitoring to existing flight management installed base. |
| North Sea Fleet Management Expansion | Deploys network-level scheduling across offshore oil-and-gas transport rotorcraft in Norway and United Kingdom. |
Research Approach
FAA certification databases, EASA type certificate records, and NATO procurement disclosure filings formed the secondary backbone for market sizing and regulatory timeline validation. Primary interviews with avionics engineering directors, fleet procurement managers at offshore operators, military program officers, and predictive maintenance software product heads combined with secondary triangulation. Bottom-up segmentation by product type, deployment architecture, and end-user category was cross-validated against top-down helicopter production forecasts and fleet modernization budget disclosures.
Bottom-up modeling aggregated segment-level assumptions across flight management, navigation, communication, and maintenance software categories, with deployment mode and application use case as cross-cutting dimensions. CAGRs were derived from regression analysis against regulatory mandate enforcement schedules and fleet refresh cycle patterns. Forecast inputs incorporated DO-178C certification queue lengths, EASA enhanced flight data recording compliance deadlines, and cloud infrastructure capex trajectories at major fleet operators.
The model holds under steady regulatory enforcement timelines; deviation in FAA NextGen mandate delays or NATO security classification changes would shift vendor revenue recognition patterns. Forecasts reflect assumptions about certification resource availability and cloud connectivity standard crystallization. A model refresh is warranted upon material change in EASA rotorcraft certification standard implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market