
 Flight Data Recorder (FDR) Market | 2026-2036
Flight Data Recorder (FDR) Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Data Recorder (FDR) Market Foresight
Solid-state memory architecture is rewriting how flight data recorders store, protect, and transmit critical telemetry. Safran SA leverages its European avionics heritage to sustain leadership in crash-protected memory engineering. RTX Corporation anchors North American defense contracts through hardened recorder systems purpose-built for military platforms.
A flight data recorder captures parametric aircraft performance data across hundreds of channels using crash-survivable solid-state memory arrays rated for extreme thermal and impact conditions; its primary purpose is to preserve forensic evidence for accident investigation and operational safety analysis. Solid-state recorders now dominate installed bases as magnetic tape formats approach obsolescence, while digital signal processing architectures command premium positioning due to real-time data compression and redundancy protocols. Defense aviation applications generate concentrated margin pools given classified encryption requirements and extended operational lifecycles.
The FAA mandates 25-hour cockpit voice recording and secondary power independence under updated Part 121 operating rules, while EASA enforces equivalent standards through its Air OPS regulation framework and CE marking for avionics equipment. China's CAAC and its GB standards for civil aviation equipment add a third compliance layer for manufacturers seeking access to COMAC supply chains. Stakeholders must monitor evolving cybersecurity mandates for data-at-rest protection as regulators integrate network resilience into airworthiness criteria.
Market Dynamics
Solid-state memory architectures are compressing product lifecycles while FAA and EASA mandates for 25-hour cockpit voice recording and secondary power independence force wholesale fleet retrofit programs across commercial aviation.
Growth Catalysts
- FAA Part 121 Mandates:Updated operating rules now require extended-duration recording capabilities and independent secondary power systems, compelling airlines to accelerate FDR replacement schedules across narrow-body and wide-body fleets.
- COMAC Supply Chain Integration:China's civil aviation regulator enforces GB standards for avionics equipment, creating captive demand for crash-protected memory systems certified to CAAC airworthiness criteria.
- Solid-State Array Penetration:Magnetic tape formats approach functional obsolescence as digital signal processing architectures with real-time compression and redundancy protocols capture premium positioning in new aircraft deliveries.
Market Restraints
- Crash-Survivable Memory Cost Structure:Specialized solid-state arrays rated for extreme thermal and impact conditions require rare-earth materials and precision manufacturing, constraining margin flexibility for tier-two suppliers.
- Defense Procurement Concentration:Classified encryption requirements and extended military operational lifecycles limit addressable market participation to vendors with established security clearances and hardened platform experience.
- Certification Timeline Friction:EASA Air OPS regulation framework and CE marking processes for avionics equipment impose multi-year validation periods that delay revenue recognition on new product introductions.
Strategic Opportunities
- Urban Air Mobility Integration:Emerging eVTOL and advanced air mobility platforms require lightweight, miniaturized recording systems, opening design-win competitions for next-generation form factors outside traditional airframe specifications.
- Cybersecurity Data-at-Rest Mandates:Regulators are integrating network resilience into airworthiness criteria, creating specification gaps that encryption-capable vendors can exploit before standards fully crystallize.
- Aftermarket Service Unbundling:Airlines are separating FDR maintenance from original equipment contracts, enabling independent MRO providers to capture recurring revenue streams through predictive health monitoring and rapid replacement logistics.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:The intersection of avionics software certification, real-time operating systems, and crash-survivable hardware design concentrates qualified personnel at a handful of defense contractors and Tier-1 suppliers.
- Legacy Fleet Integration Complexity:Retrofitting 25-hour voice recording capabilities into existing analog cockpit architectures demands custom interface engineering that fragments engineering resources and extends program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Data Recorder (FDR) Market |
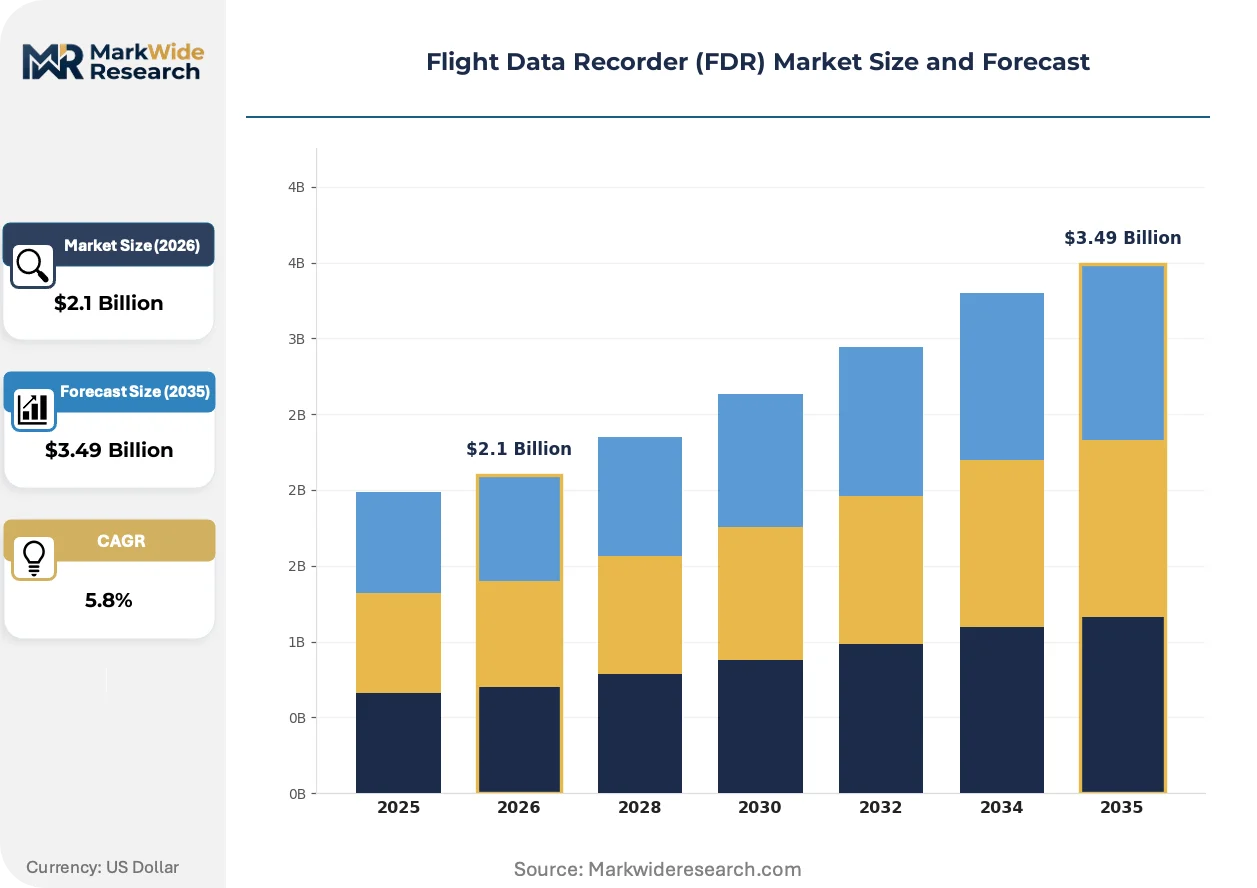
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Recorders, Magnetic Tape Recorders, Hybrid Recorders, Crash-Protected Memory Units Technology: Fiber Optic Sensors, Microelectromechanical Systems, Piezoelectric Sensors, Digital Signal Processing Application: Commercial Aviation, Defense Aviation, General Aviation, Unmanned Aerial Vehicles End User: Airlines, Aerospace Manufacturers, Military Forces, Aircraft Maintenance Organizations |
| Companies Covered | Safran SA, RTX Corporation, Honeywell International Inc., Teledyne Technologies Incorporated, Universal Avionics Systems Corporation, L3Harris Technologies Inc., Leonardo S.p.A., AstroNova Inc., Curtiss-Wright Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Data Recorder (FDR) Market Shifts & Advancements
Real-time telemetry transmission and edge computing architectures are redefining how flight data moves from aircraft to ground infrastructure, compressing the window between incident occurrence and investigative access.
Solid-state flight data recorder technology is hybridizing crash-protected memory engineering with live data streaming capabilities. Commercial airlines operating long-haul routes are adopting these hybrid architectures fastest, driven by insurer pressure for immediate incident response. The technology is hybridizing traditional forensic preservation with operational intelligence, enabling predictive maintenance algorithms that compress unscheduled downtime.
EASA's updated Air OPS regulation framework now mandates tamper-evident recording chains and extended underwater locator beacon durations. This policy shift forces manufacturers to redesign thermal protection enclosures and acoustic pinger systems. Wide-body operators with transoceanic route structures face the steepest compliance costs and are responding through pooled procurement consortia to secure volume pricing on retrofit kits.
Airline technical procurement departments are consolidating FDR vendor relationships from multi-source to dual-source strategies, prioritizing suppliers with integrated crash-protected memory and quick-access recorder capabilities. The channel being disrupted is fragmented regional distributor networks, replaced by direct OEM-to-airline contracting with embedded long-term service agreements. This concentration is most visible in Germany and France, where Lufthansa Group and Air France-KLM leverage fleet scale to dictate specification roadmaps and captive maintenance terms.
Flight Data Recorder (FDR) Market Segmentation
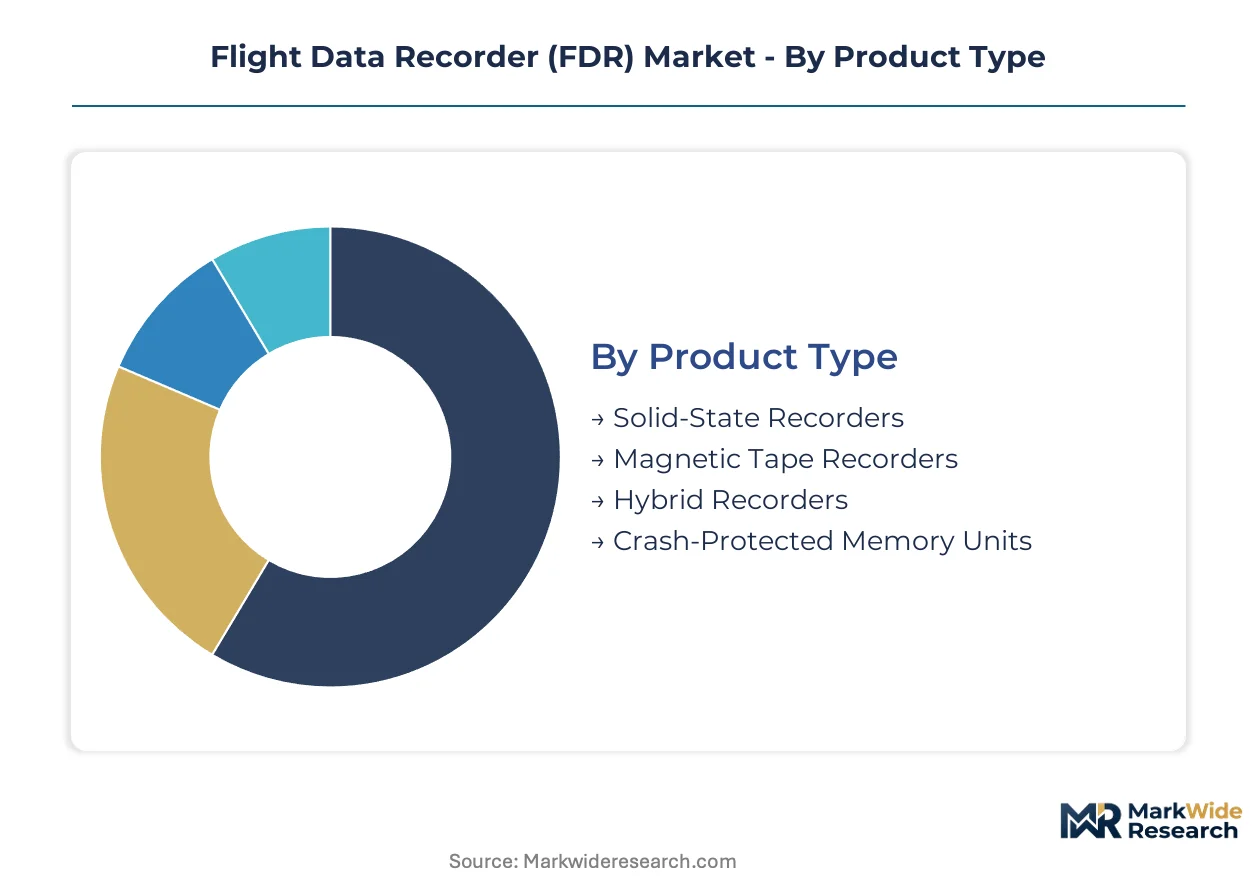
Flight data recorder segmentation reveals how technical architecture, operational environment, and procurement authority shape specification requirements and margin structures. Manufacturers configure product portfolios across four distinct dimensions, each carrying unique certification burdens and customer concentration profiles.
Product Type:
Cost tier differentiation separates legacy replacement demand from next-generation platform specifications, with memory architecture as the primary price determinant.
- Solid-State Recorders:Non-volatile flash memory arrays rated for 3,400 G impact and 1,100°C thermal exposure dominate new aircraft deliveries. Commercial airlines in the United States and China specify these units for 25-hour cockpit voice recording compliance under FAA Part 121 and CAAC GB standards.
- Magnetic Tape Recorders:Analog sequential recording formats using helical scan tape mechanisms persist in aging narrow-body fleets awaiting retirement. Demand concentrates among regional carriers in Germany operating extended-life Boeing 737 Classic and Airbus A320ceo aircraft under EASA Air OPS transition timelines.
- Hybrid Recorders:Dual-architecture systems bridging solid-state primary storage with tape backup for redundancy protocols.
- Crash-Protected Memory Units:Stand-alone hardened memory enclosures without integrated recording electronics, deployed in military platforms requiring classified encryption modules.
Solid-State Recorders hold installed capacity. Hybrid Recorders are rotating up the share rankings.
Technology:
Application-specific sensing modalities determine signal fidelity, environmental tolerance, and integration complexity with airframe data buses.
- Digital Signal Processing:Real-time compression algorithms and redundant encoding protocols enable 25-hour continuous recording within constrained memory footprints. Defense aviation programs in the United States specify DSP architectures for encrypted telemetry streams on strategic airlift and surveillance platforms.
- Fiber Optic Sensors:Immune to electromagnetic interference and rated for extreme thermal cycling, these sensors capture structural health data in composite airframes. Demand clusters in next-generation commercial programs where Boeing and Airbus integrate distributed sensing for predictive maintenance.
- Microelectromechanical Systems:Silicon-based accelerometers and gyroscopes measuring attitude and vibration parameters.
- Piezoelectric Sensors:Crystal-based transducers converting mechanical strain into electrical signals for high-frequency vibration monitoring.
Digital Signal Processing commands margin premiums. Fiber Optic Sensors are climbing the fastest on new platform specifications.
Application:
Operational environment dictates crash-survivability requirements, recording duration mandates, and cybersecurity protocols.
- Commercial Aviation:Scheduled passenger and cargo operations subject to FAA, EASA, and CAAC recording duration mandates. Fleet renewal programs at Lufthansa Group and Air France-KLM in Germany and France drive concentrated demand for 25-hour voice recording retrofit kits.
- Defense Aviation:Classified missions requiring tamper-evident chains and encrypted data-at-rest protection. Extended operational lifecycles and security clearance requirements limit vendor participation to established defense contractors.
- General Aviation:Private and business aircraft operating under less stringent recording requirements, with voluntary adoption of lightweight solid-state units.
- Unmanned Aerial Vehicles:Remotely piloted systems requiring miniaturized recording formats for incident reconstruction and regulatory compliance.
Commercial Aviation holds installed capacity. Defense Aviation is rotating up the share rankings.
End User:
Procurement authority and technical integration responsibility determine contract structure, service attachment rates, and specification influence.
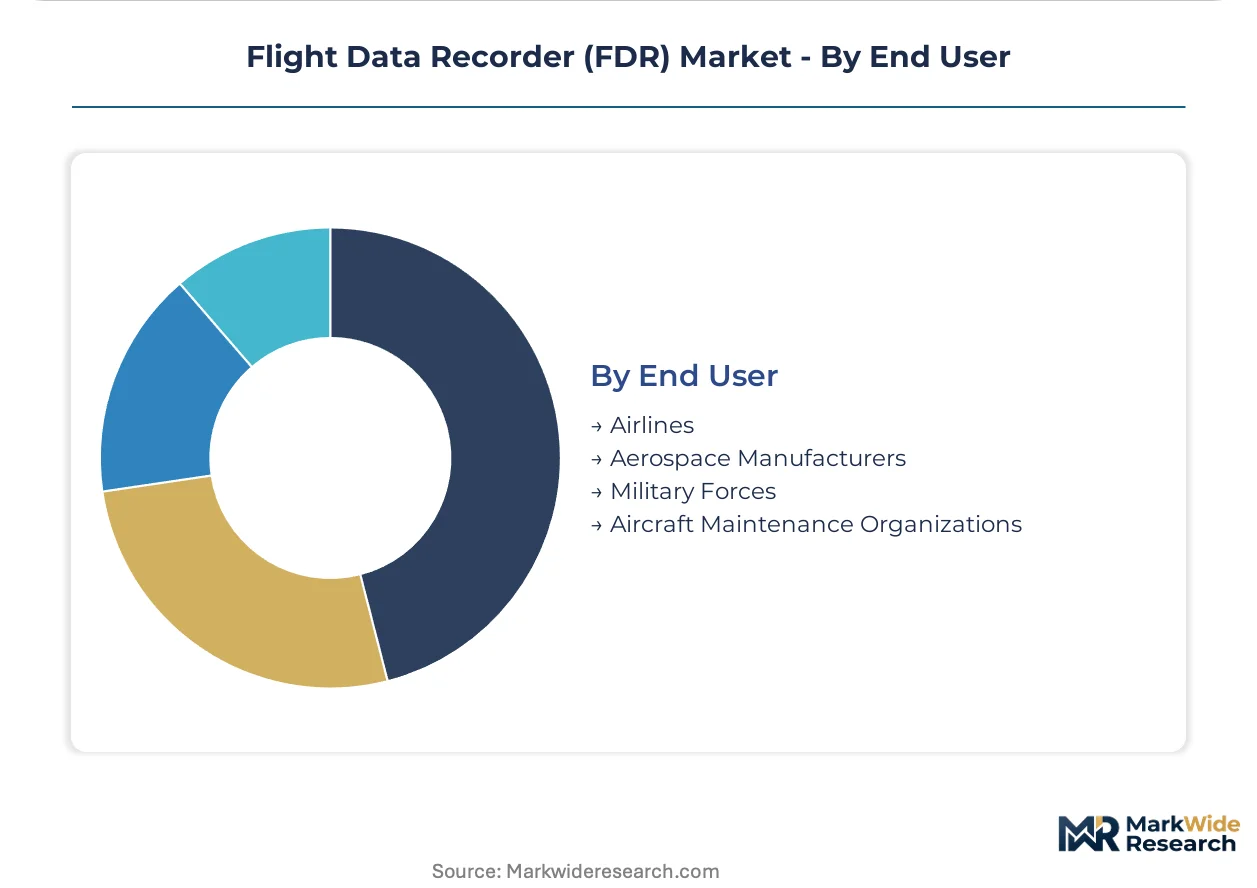
- Airlines:Operating carriers with direct regulatory compliance obligations and fleet-wide retrofit accountability. United States-based network carriers leverage scale to dictate quick-access recorder integration and long-term service agreements.
- Aerospace Manufacturers:Airframe OEMs specifying FDR systems at platform design phase for line-fit installation. Boeing in the United States and COMAC in China control supplier selection through airworthiness certification partnerships.
- Military Forces:Defense procurement agencies with classified requirements and extended support timelines.
- Aircraft Maintenance Organizations:Independent MRO providers capturing aftermarket retrofit and replacement demand as airlines unbundle maintenance contracts.
Airlines hold installed capacity. Aircraft Maintenance Organizations are expanding most quickly as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports FDR retrofit kits to Lufthansa Group's Central European fleet operations. The United States ships line-fit systems to Boeing's final assembly lines. China supplies crash-protected memory units to COMAC's expanding domestic production.
United States
Network carriers at Dallas-Fort Worth and Atlanta hubs drive concentrated demand for 25-hour voice recording compliance. FAA Part 121 mandates force accelerated replacement schedules across aging narrow-body fleets. Boeing's Seattle-area engineering centers specify quick-access recorder integration for 737 MAX and 777X platforms.
China
COMAC's Shanghai final assembly lines generate captive demand for CAAC-certified avionics equipment. GB standards for civil aviation equipment create regulatory barriers favoring domestic suppliers. The Yangtze River Delta cluster hosts precision manufacturing facilities producing solid-state memory arrays for C919 and ARJ21 programs.
Germany
Lufthansa Group's Frankfurt and Munich hubs anchor European retrofit demand under EASA Air OPS transition timelines. CE marking processes for avionics equipment impose multi-year validation periods that delay new product introductions. Hamburg's aerospace corridor concentrates MRO providers capturing unbundled maintenance contracts from flag carriers.
France
Air France-KLM's Paris-Charles de Gaulle operations leverage fleet scale to dictate specification roadmaps for quick-access recorder capabilities. EASA tamper-evident recording chain mandates force thermal protection enclosure redesigns. Toulouse's aviation cluster integrates FDR systems into Airbus A350 and A320neo final assembly.
Japan
ANA and JAL's Tokyo-Narita hubs specify lightweight solid-state units for domestic route optimization. METI's industrial standards for avionics equipment align with JIS certification requirements. Nagoya's aerospace manufacturing corridor supplies precision components for regional jet programs requiring miniaturized recording formats.
Flight Data Recorder (FDR) Market Competitive Landscape
On the supply side, the industry is consolidated around defense contractors with security clearances and European avionics heritage firms. Tier-one suppliers control crash-protected memory engineering through rare-earth material access and precision manufacturing capabilities. Three archetypes dominate: aerospace conglomerates with integrated avionics portfolios, defense specialists with classified encryption expertise, and regional component fabricators serving aftermarket retrofit demand. Competitive moves center on strategic partnerships for CAAC certification access and technology licensing for solid-state array miniaturization.
Within the defense-specialist tier, L3Harris Technologies Inc. and Curtiss-Wright Corporation exemplify vendors with established security clearances and hardened platform experience. Safran SA represents the European heritage archetype, anchoring crash-protected memory engineering through continental avionics supply relationships. RTX Corporation occupies a position bridging commercial airline procurement and military platform specifications, reflecting the dual-use nature of modern flight data recording architectures.
| Leading Market Players |
|---|
| Safran SA |
| RTX Corporation |
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| Universal Avionics Systems Corporation |
| L3Harris Technologies Inc. |
| Leonardo S.p.A. |
| AstroNova Inc. |
| Curtiss-Wright Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in legacy magnetic tape recorder manufacturing across Germany is forcing tier-two suppliers into aggressive price competition while solid-state array foundries in the United States and China command premium positioning through capacity discipline. This utilization divergence shapes procurement negotiations, with airlines extracting volume concessions on retrofit kits while accepting premium pricing for line-fit installations on new aircraft programs.
Pricing Analysis
The technology-generation pricing gap separates obsolete magnetic tape formats from solid-state primary storage and emerging hybrid architectures with live-streaming capabilities. Three-tier pricing structure across crash-protected memory certification grades, volume scale commitments, and aftermarket service bundling dominates contract structures. Price differentiation rests on FAA Part 121 and EASA Air OPS compliance tiers, with full 25-hour voice recording certification commanding substantial premiums over transitional configurations. Cost compression in magnetic tape retrofit supply is intensifying because regional carriers delay fleet retirement timelines. Low-cost carriers operating aging narrow-body fleets exhibit highest price sensitivity, while network carriers with transoceanic route structures prioritize reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for solid-state memory arrays sits with specialized aerospace electronics manufacturers in the United States, Germany, and Japan possessing rare-earth material access and precision machining capabilities. Geographic supply concentration clusters in the United States for DSP architecture design, China for COMAC-certified production lines, and Germany for EASA-compliant thermal protection enclosures. Raw material dependencies include rare-earth elements for high-temperature memory substrates, precision-machined titanium for crash-survivable housings, and specialized ceramic compounds for thermal insulation. Single-source vulnerability around qualified solid-state array suppliers certified to FAA TSO-C124 standards creates structural risk. Distribution runs through direct OEM-to-airline contracting with embedded long-term service agreements, displacing fragmented regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel capable of integrating avionics software certification, real-time operating systems, and crash-survivable hardware engineering concentrate at a handful of defense contractors and tier-one suppliers, creating persistent capability scarcity that constrains market entry and sustains incumbent pricing power.
For Market Incumbents: Entrench market position through backward integration into rare-earth material supply chains and captive production of precision-machined thermal protection enclosures. Accelerate certification investment for CAAC GB standards compliance before COMAC supply chains fully crystallize, locking out competitors lacking established airworthiness partnerships. Vertical integration into quick-access recorder capabilities addresses airline procurement consolidation toward dual-source strategies with embedded service agreements. For New Entrants and Emerging Players: Build out specialized capabilities in cybersecurity data-at-rest protection before regulatory standards fully crystallize, exploiting specification gaps in emerging EASA network resilience mandates. Urban air mobility platforms requiring miniaturized solid-state recording systems represent the most penetrable segment, with eVTOL manufacturers lacking established avionics supplier relationships. Go-to-market execution should prioritize direct engineering partnerships with advanced air mobility startups over traditional airframe OEM channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent MRO providers capturing unbundled FDR maintenance contracts from airlines separating service from original equipment procurement. Long-term viability over the coming decade rests on positioning within aftermarket predictive health monitoring and rapid replacement logistics. Acquisition focus should target component fabricators with established EASA CE marking capabilities and rare-earth material access. The signal to monitor is CAAC certification timeline acceleration for domestic suppliers, which would compress foreign vendor margins in China's expanding commercial aviation market.| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Certification Investment | Unlocks access to COMAC C919 and ARJ21 supply chains before domestic suppliers consolidate positions. |
| Cybersecurity Capability Buildout | Captures specification premiums as EASA integrates network resilience into airworthiness criteria. |
| Urban Air Mobility Partnership | Secures design wins on eVTOL platforms outside traditional Boeing and Airbus specifications. |
| Aftermarket Service Unbundling | Enables recurring revenue capture as airlines separate FDR maintenance from equipment contracts. |
| Rare-Earth Supply Integration | Reduces cost exposure and secures qualified material access for crash-protected memory production. |
Research Methodology
Desk research of FAA regulatory filings, EASA Air OPS amendments, CAAC GB standards documentation, and commercial aviation fleet databases preceded structured interviews with avionics engineering directors, airline technical procurement managers, MRO operations executives, and defense platform program managers. Primary fieldwork combined telephone and video interviews with industry stakeholders across the United States, China, Germany, and France with secondary validation through airworthiness certification records and OEM supplier qualification documents. Bottom-up triangulation across installed base estimates and top-down reconciliation against fleet renewal program announcements anchored volume and value outputs.
Assumptions held regulatory mandates at currently published FAA Part 121 and EASA Air OPS requirements while varying fleet retirement timelines and COMAC production ramp scenarios across sensitivity bands. The analytical framework modeled segmentation dimensions including memory architecture generation, application environment, and procurement authority structure throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles projected against mandated compliance deadlines. Industry-specific forecast inputs included CAAC certification timeline probabilities and urban air mobility platform introduction schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated cybersecurity mandate implementation would shift outcomes substantially. Forecasts reflect assumptions regarding regulatory timeline adherence and rare-earth material supply continuity. Quarterly review of CAAC certification issuance rates, COMAC monthly delivery figures, and EASA tamper-evident recording chain enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Air Data Systems Market