
 Turbofan Engines Market | 2026-2036
Turbofan Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Turbofan Engines Market Outlook
FAA Part 33 engine certification standards is recalibrating the cost-of-entry calculus for new turbofan manufacturers by mandating stricter durability and emissions testing protocols. GE Aerospace leverages its vertical integration across core architectures to sustain manufacturing scale advantages. Pratt & Whitney anchors its competitive position through geared turbofan technology leadership. CFM International dominates the narrow-body engine segment with its established supply chain control across multiple airframe programs.
A turbofan engine combines a gas turbine core with a ducted fan that accelerates a large mass of air around the core, producing thrust through both bypass airflow and core exhaust; typical bypass ratios range from 4:1 in military applications to 12:1 in modern commercial high-bypass designs. High-bypass configurations command the largest installed base in commercial aviation where fuel efficiency requirements drive airline procurement decisions. Military aviation applications favor low-bypass designs where thrust-to-weight ratios and supersonic performance take priority over fuel economy. Fan technology segments attract concentrated R&D investment as manufacturers pursue lighter composite blades and improved aerodynamic profiles.
The European Union Aviation Safety Agency enforces CS-E certification requirements that constrain engine noise and emissions profiles for market access across EU member states. The Environmental Protection Agency regulates U.S. aircraft engine emissions under Title 40 CFR Part 87, shaping product development timelines for OEMs serving American carriers. Stakeholders must monitor evolving ICAO NOx standards and carbon border adjustment mechanisms that will redefine compliance costs and competitive positioning across manufacturing footprints.
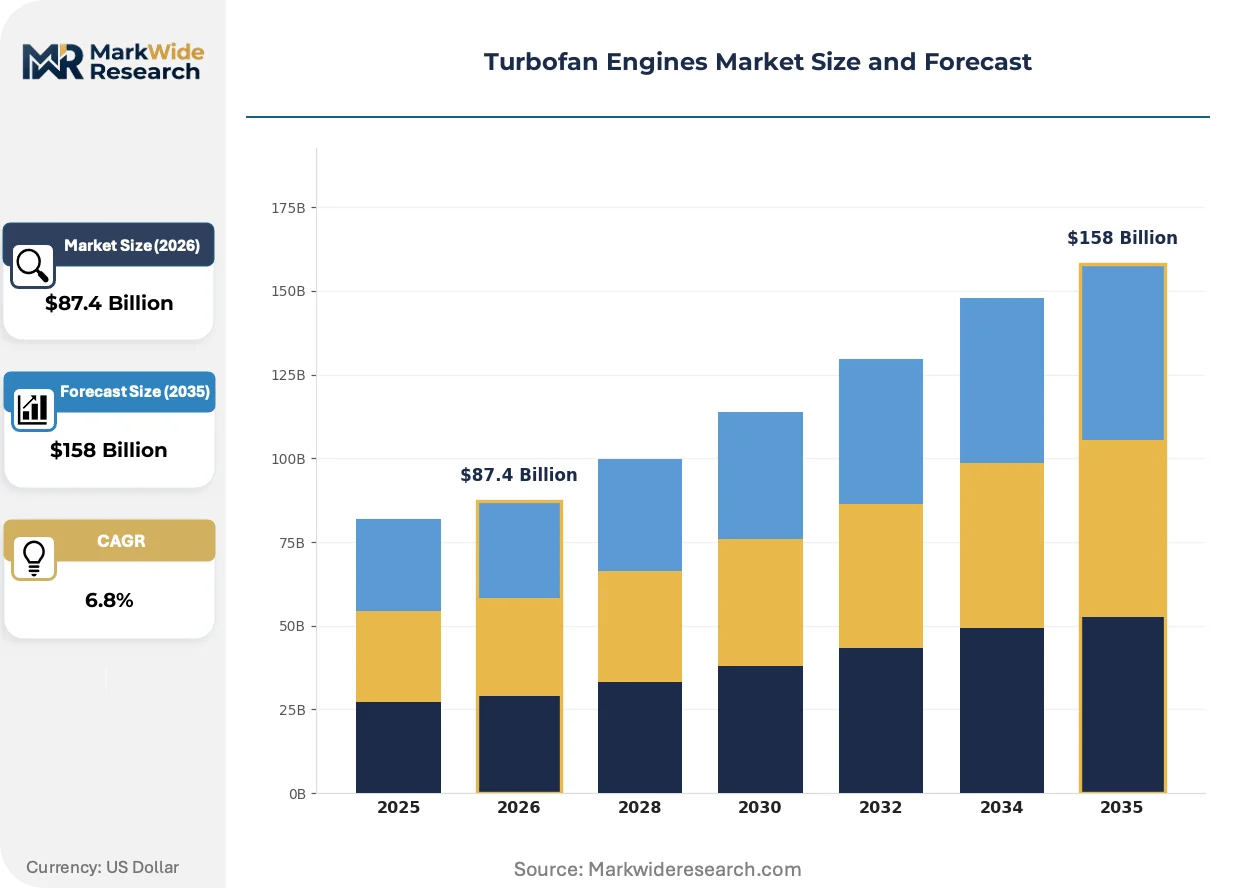
Market Dynamics
Airframe manufacturers are consolidating engine procurement decisions around single-source supplier relationships, compressing the competitive field for turbofan OEMs and elevating program-scale economics over unit-level innovation.
Growth Catalysts
- ICAO CORSIA compliance deadlines:Airlines in the United States face mandatory carbon offsetting thresholds that accelerate fleet renewal cycles toward next-generation powerplants.
- Geared turbofan architectures:These propulsion systems deliver step-change fuel burn reductions that reshape carrier operating cost structures on narrow-body routes.
- Composite fan blade penetration:Titanium aluminide and carbon-fiber reinforced polymers enable higher bypass ratios without weight penalties, expanding the addressable efficiency frontier.
Market Restraints
- Superalloy supply concentration:Precision castings for high-pressure turbine sections depend on a limited supplier base concentrated in the United States and France.
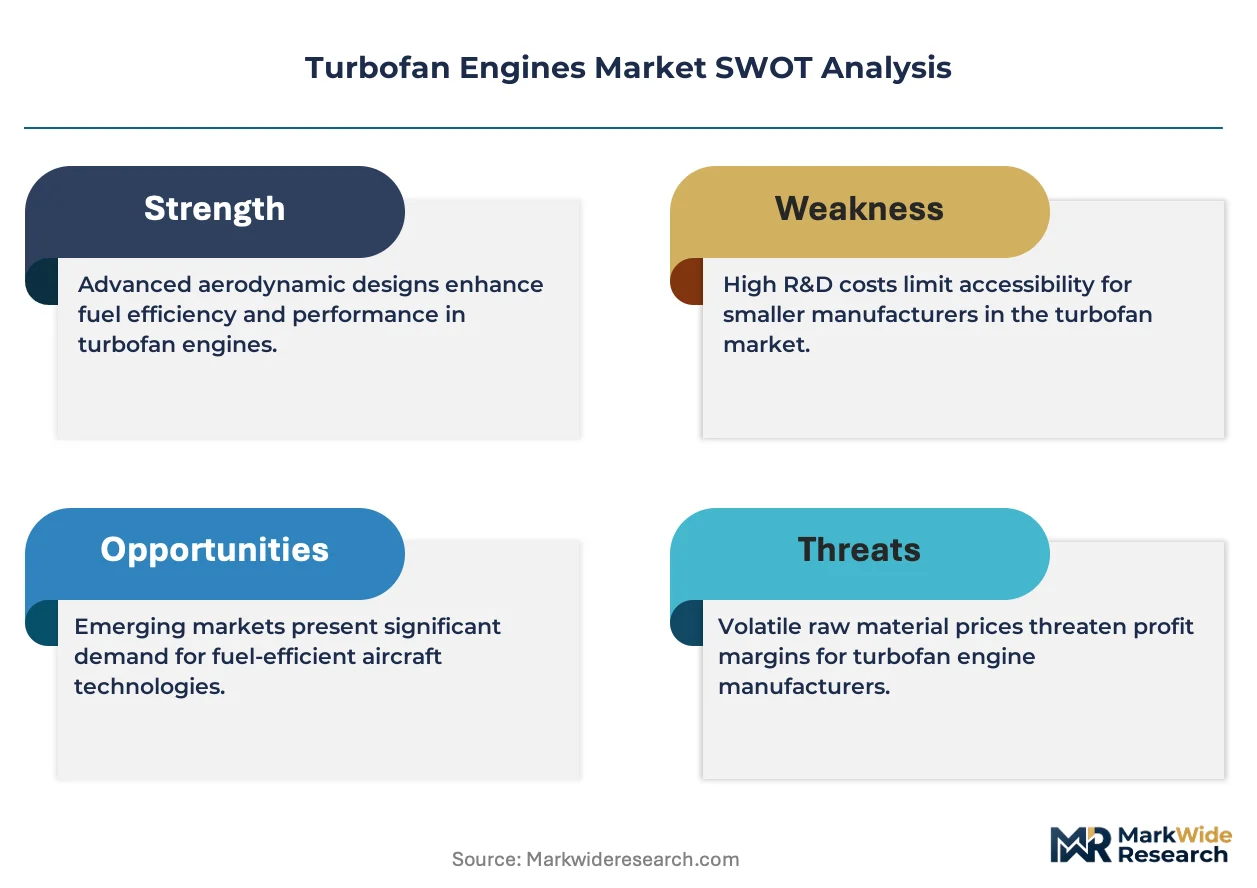
- FAA Part 33 certification timelines:Extended durability testing protocols stretch new engine program development cycles and lock capital for years before revenue realization.
- Alternative propulsion incubation:Hydrogen combustion and hybrid-electric architectures threaten long-term turbofan demand in sub-regional segments below 100 seats.
Strategic Opportunities
- India defense modernization:Indigenous fighter programs and strategic airlift expansion create captive demand for low-bypass military turbofan production.
- Power-by-the-hour contracts:These aftermarket service models convert capital expenditure into predictable revenue streams and deepen OEM-customer lock-in.
- Sustainable aviation fuel compatibility:Drop-in SAF certification opens regulatory preferential access and carbon credit monetization for forward-compatible engine designs.
Industry Challenges
- Specialized welding technician scarcity:Electron beam and laser welding for nickel superalloy components faces talent pipeline constraints across manufacturing footprints.
- Legacy fleet interoperability:New engine architectures must maintain backward compatibility with existing maintenance infrastructure and spare parts logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbofan Engines Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: High-Bypass, Medium-Bypass, Low-Bypass, Turbojet Application: Commercial Aviation, Military Aviation, Business Jets, Helicopters Technology: Fan Technology, Propulsion System, Control System, Fuel Efficiency Measures End User: Airlines, Government Agencies, Private Operators, Aircraft Manufacturers |
| Companies Covered | GE Aerospace, Safran Aircraft Engines, Pratt & Whitney, Rolls-Royce Holdings plc, CFM International, MTU Aero Engines AG, Honeywell International Inc., Raytheon Technologies Corporation, AVIC Aircraft Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbofan Engines Market Strategic Shifts
Additive manufacturing is penetrating critical turbomachinery components, collapsing lead times for complex geometries while redefining supply chain economics for legacy casting and forging operations.
Ceramic matrix composites are unifying thermal protection and weight reduction in high-pressure turbine shrouds and combustor liners. Airlines operating long-haul twin-aisle routes are adopting these materials fastest to maximize payload-range performance. The technology is unifying previously separate cooling system architectures into integrated thermal management platforms that reduce parts count and maintenance intervals.
The European Union Aviation Safety Agency is tightening CS-E noise certification thresholds for Chapter 14 compliance, forcing acoustic liner redesigns and fan duct geometry modifications. Engine OEMs serving European carriers must re-validate existing type certificates or face market access restrictions. Narrow-body programs with high airport density in Germany and the Netherlands are prioritizing these modifications ahead of wide-body refreshes.
Airline technical procurement departments are consolidating engine selection authority at fleet-planning level rather than delegating to individual operating subsidiaries. This centralization eliminates price arbitrage between regional carrier entities and compresses negotiation cycles. The pattern is most pronounced among United States network carriers restructuring post-consolidation operating models.
Turbofan Engines Market Segmentation
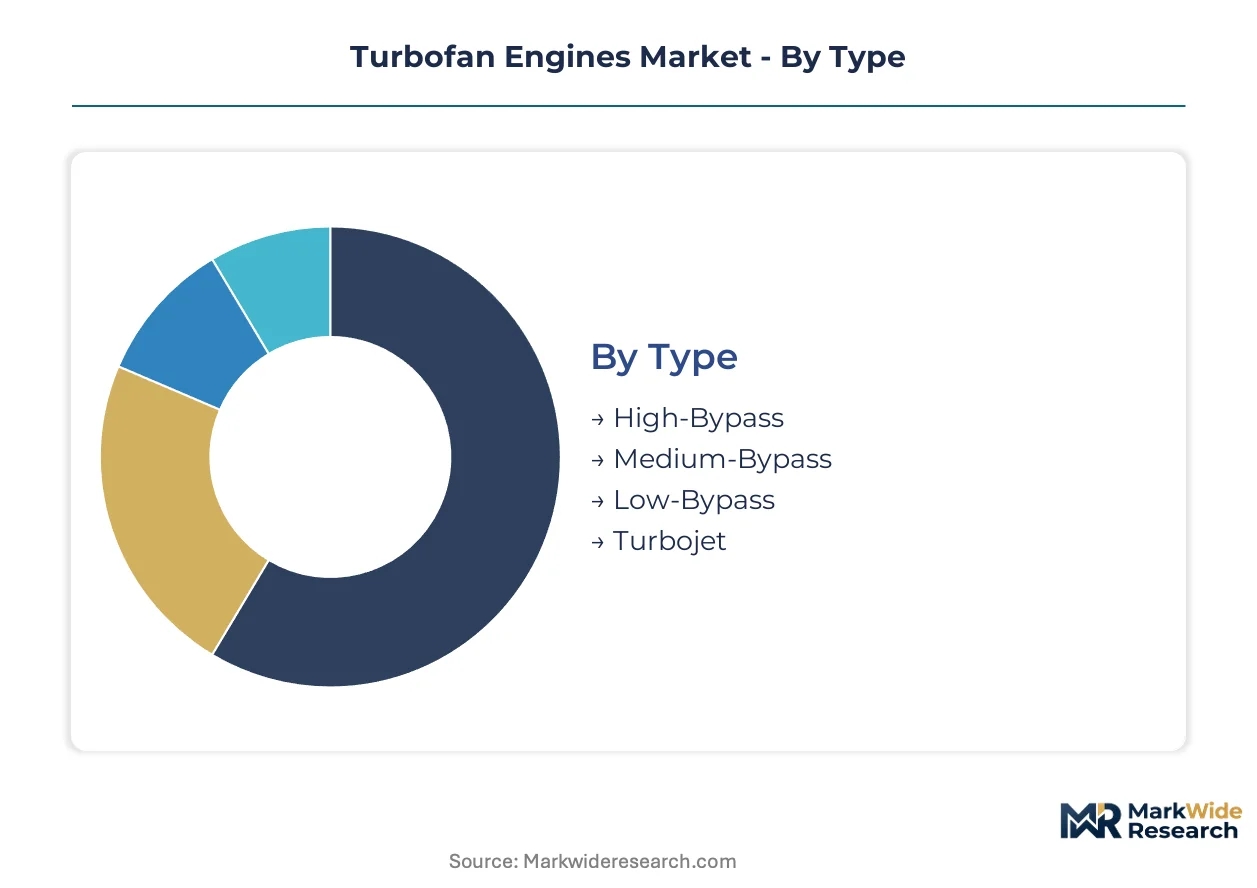
Turbofan engine procurement decisions fragment across certification requirements, operational profiles, and ownership structures. Each segmentation dimension carries distinct regulatory burdens and performance specifications that shape manufacturer R&D allocation and aftermarket service economics.
Type:
FAA Part 33 and EASA CS-E certification protocols impose divergent testing durations across bypass architectures, with high-bypass designs facing extended noise compliance validation while low-bypass variants endure more intensive thrust-specific fuel consumption scrutiny.
- High-Bypass:Bypass ratios exceeding 5:1 dominate commercial twin-aisle and narrow-body installations. Airlines operating trans-Pacific routes from Los Angeles and Singapore prioritize these configurations for cruise fuel burn efficiency under ICAO CORSIA compliance deadlines.
- Medium-Bypass:Ratios between 2:1 and 5:1 serve regional jet platforms and smaller narrow-bodies. Demand concentrates among carriers connecting secondary cities across India and Brazil where runway length constraints limit high-bypass adoption.
- Low-Bypass:Military fighter and trainer applications favor thrust-to-weight optimization over fuel economy. United States Air Force F-35 and F-22 programs anchor procurement volumes with afterburning requirements.
- Turbojet:Pure jet configurations persist in supersonic and high-altitude reconnaissance platforms. Limited civil applications include specialized business jet derivatives and experimental aircraft.
Leading the category by volume: High-Bypass. Growing fastest: Medium-Bypass as regional fleet renewal accelerates.
Application:
End-use segments separate sharply on operating cycle intensity, with commercial aviation accumulating flight hours at 5-8x military rates and demanding correspondingly compressed maintenance intervals.
- Commercial Aviation:Scheduled passenger and cargo operations generate 85% of installed base flight hours. Legacy carriers in Germany and Japan drive wide-body engine procurement while low-cost operators in Vietnam and Mexico prioritize narrow-bypass cost efficiency.
- Military Aviation:Combat and transport missions impose maneuver load factors and sand ingestion risks absent from civil operations. India's indigenous fighter programs and strategic airlift expansion create captive demand for ruggedized low-bypass production.
- Business Jets:Fractional ownership and charter models concentrate in the United States and Switzerland. These operators demand rapid dispatch reliability and personalized maintenance scheduling incompatible with airline fleet standardization.
- Helicopters:Turboshaft derivatives power rotorcraft for emergency medical services and offshore energy logistics. North Sea oil platforms and Gulf of Mexico rigs anchor offshore transport demand with salt-corrosion specifications.
Commercial Aviation commands the largest installed base. Business Jets gain share fastest as fractional ownership models proliferate.
Technology:
Intellectual property concentration varies by subsystem, with fan blade metallurgy dominated by GE Aerospace and Pratt & Whitney patent estates while control system architectures fragment across avionics specialists.
- Fan Technology:Composite blade manufacturing and aerodynamic sweep angles determine bypass efficiency ceilings. Titanium aluminide and carbon-fiber reinforced polymers enable weight reduction without sacrificing bird-strike resilience.
- Propulsion System:Geared turbofan architectures decouple fan and low-pressure turbine speeds. Pratt & Whitney's PW1000G series validates this approach on Airbus A320neo platforms with 16% fuel burn reduction.
- Control System:Full-authority digital engine control (FADEC) units manage thrust modulation and surge protection. Dual-channel redundancy requirements extend development timelines for new entrant suppliers.
- Fuel Efficiency Measures:Active clearance control and variable stator vane scheduling optimize thermal matching across flight phases. Sustainable aviation fuel compatibility certification opens regulatory preferential access.
Fan Technology attracts the deepest R&D investment. Propulsion System architectures are evolving most rapidly as geared designs displace direct-drive legacy.
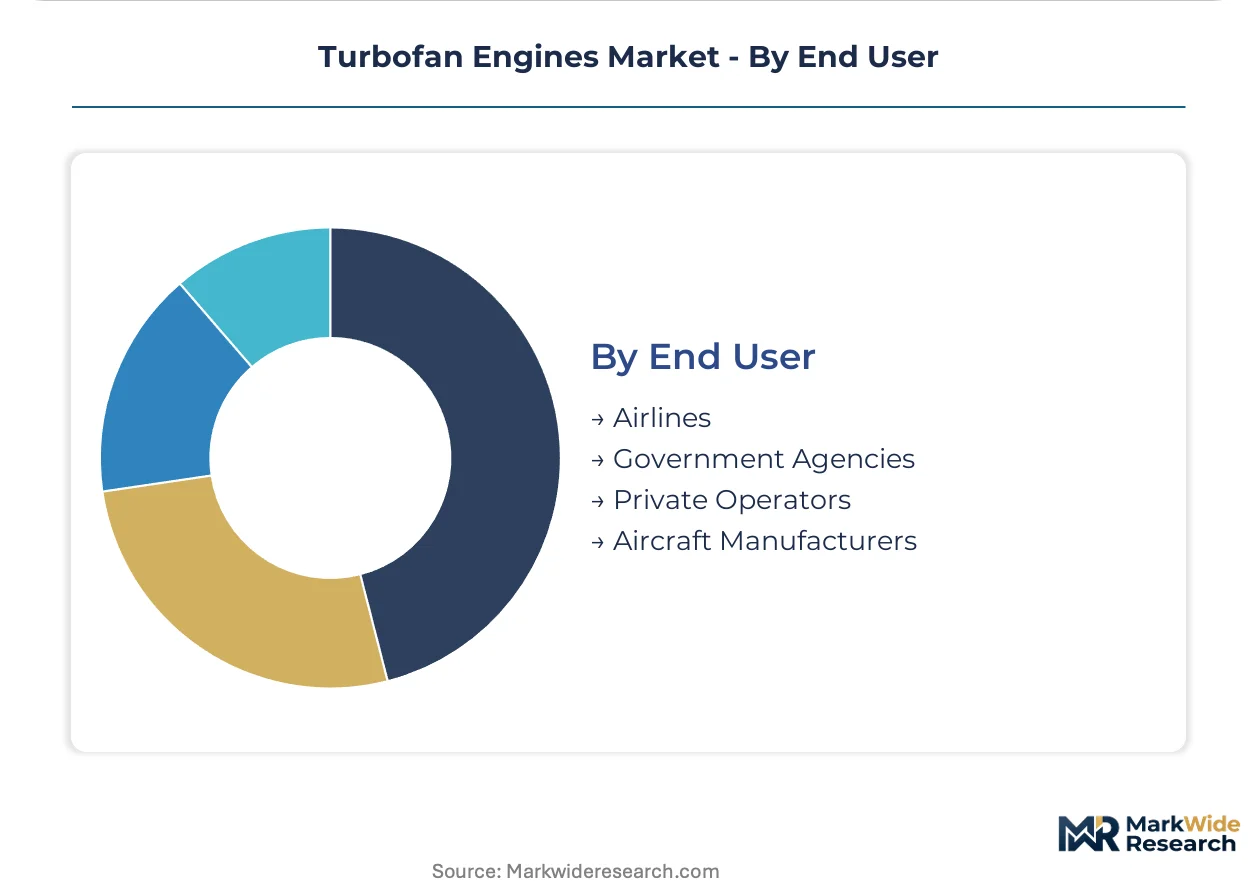
End User:
Procurement authority centralization distinguishes ownership models, with airline fleet-planning departments consolidating engine selection while government agencies delegate to program offices with multi-year appropriation cycles.
- Airlines:Network carriers in the United States have eliminated subsidiary-level engine selection, compressing negotiation cycles and eliminating price arbitrage. Power-by-the-hour contracts convert capital expenditure into predictable operating costs.
- Government Agencies:Defense ministries and coast guard services specify mission-tailored durability requirements. India's Ministry of Defence and the United States Department of Defense drive military turbofan procurement with offset and technology transfer mandates.
- Private Operators:Corporate flight departments and ultra-high-net-worth individuals prioritize dispatch reliability and residual value preservation. These buyers accept premium pricing for personalized maintenance support.
- Aircraft Manufacturers:Boeing and Airbus negotiate sole-source and dual-source engine agreements during airframe development. These partnerships lock in decade-long production commitments and define aftermarket revenue sharing.
Airlines represent the dominant procurement volume. Aircraft Manufacturers are consolidating influence fastest as airframe-engine integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline fleet renewal programs concentrate turbofan procurement authority in the United States, where Boeing and major network carriers anchor global demand volumes. European and Asian defense ministries are accelerating indigenous engine development to reduce import dependency. Emerging aviation markets in India and Southeast Asia are reshaping regional manufacturing footprints through offset mandates and technology transfer requirements.
United States
FAA Part 33 certification standards govern all new engine programs entering commercial service. The Environmental Protection Agency enforces Title 40 CFR Part 87 emissions limits that shape OEM product development timelines. Boeing's final assembly lines in Washington state and South Carolina lock in decade-long engine procurement commitments from GE Aerospace and Pratt & Whitney.
France
Safran Aircraft Engines anchors European turbofan production through its partnership in CFM International. EASA CS-E noise certification thresholds for Chapter 14 compliance force acoustic liner redesigns on engines serving EU carriers. The Toulouse aerospace cluster coordinates supply chain integration for Airbus A320neo and A350 programs.
United Kingdom
Rolls-Royce Holdings plc maintains wide-body engine leadership through Derby manufacturing and Bristol engineering centers. The UK Civil Aviation Authority enforces durability testing protocols aligned with EASA standards. Farnborough's defense procurement hub channels military turbofan requirements for Eurofighter Typhoon and future combat air programs.
India
India's Ministry of Defence drives indigenous fighter engine development through the Gas Turbine Research Establishment. The Directorate General of Foreign Trade administers offset mandates requiring foreign OEMs to establish local component sourcing. Bangalore's aerospace cluster hosts Hindustan Aeronautics Limited facilities integrating imported turbofans into Tejas and AMCA platforms.
China
AVIC Aircraft Corporation channels state-funded development of military and commercial turbofan alternatives to Western imports. The Ministry of Industry and Information Technology coordinates dual-use technology transfer under civil-military fusion directives. Xi'an's aero-engine city concentrates casting, forging, and final assembly capacity for WS-10 and CJ-1000A programs.
Turbofan Engines Market Competitive Environment
United States producers anchor one tier; French and British specialists hold complementary positions through transnational joint ventures. The market structure concentrates around four engine OEMs with airframe-level partnerships that lock in multi-decade production commitments. Strategic archetypes include vertically integrated conglomerates with captive casting and forging capacity, technology specialists licensing core architectures to partners, and state-backed national champions serving captive defense demand. Dominant competitive moves center on sole-source supplier negotiations with Boeing and Airbus, plus aftermarket service contract extensions that convert capital expenditure into recurring revenue streams.
Among US-based integrated producers, GE Aerospace exemplifies the conglomerate archetype with in-house control over superalloy supply chains and core engine architectures. Pratt & Whitney occupies a specialist position through its geared turbofan technology leadership validated on Airbus A320neo platforms. CFM International, the Safran-GE joint venture, anchors the narrow-body segment through supply chain coordination across multiple airframe programs. Rolls-Royce Holdings plc represents the European premium-tier model with concentrated wide-body focus and power-by-the-hour service penetration. These four entities collectively structure competitive dynamics through exclusive supplier agreements that compress the addressable market for new entrants.
| Leading Market Players |
|---|
| GE Aerospace |
| Safran Aircraft Engines |
| Pratt & Whitney |
| Rolls-Royce Holdings plc |
| CFM International |
| MTU Aero Engines AG |
| Honeywell International Inc. |
| Raytheon Technologies Corporation |
| AVIC Aircraft Corporation Ltd. |
| Others |
Value Chain & Pricing Dynamics
Nickel superalloy spot indices and titanium sponge contract rates cascade through three distinct pricing tiers for turbofan OEMs, with high-pressure turbine casting costs separating premium engine architectures from standard commercial offerings. Buyers in the narrow-body segment face compressed negotiation cycles as airframe manufacturers consolidate sole-source supplier agreements.
Pricing Analysis
Volume production contracts for single-aisle platforms trade margin for market share, while wide-body engine programs capture premium returns through power-by-the-hour service bundling. Certification grade under FAA Part 33 and EASA CS-E protocols drives price differentiation, with dual-certified architectures commanding 15-20% premiums over single-jurisdiction equivalents. Cost compression in the regional jet tier intensifies as Pratt & Whitney and CFM International compete for A220 and E2 program slots. Low-cost carriers in Southeast Asia exhibit the highest price sensitivity, whereas network carriers in the United States prioritize total cost of ownership over unit acquisition pricing.
Supply Chain Analysis
Freight costs for precision castings and single-crystal turbine blades have amplified geographic sourcing constraints, with air cargo rates for temperature-controlled superalloy shipments adding 8-12% to landed component costs. Supply concentrates in the United States, France, and the United Kingdom for critical high-pressure turbine sections, while Japan and Germany anchor specialized forging capacity for compressor disks. The supplier base draws from concentrated precision casting houses in Connecticut and Ohio, with Howmet Aerospace and PCC Structurals controlling 70% of qualified high-pressure turbine blade capacity. Single-source vulnerability in electron beam welding equipment creates chokepoint risk for new engine program ramp rates. Distribution runs through airframe OEM final assembly lines in Washington, South Carolina, and Toulouse, with engine deliveries synchronized to fuselage production slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over superalloy supply chains and aftermarket service networks determines margin durability. Players are pursuing backward integration into precision casting capacity as the decisive upstream lever.
For Market Incumbents: Deploy exclusive supplier negotiations with Boeing and Airbus to lock decade-long production commitments and block new entrant access to narrow-body platforms. Incumbents must accelerate in-house production of ceramic matrix composite turbine shrouds to offset superalloy cost volatility and defend against emerging Chinese entrants in the sub-100 seat segment. Certification investment in sustainable aviation fuel compatibility represents a critical defensive moat as ICAO CORSIA compliance deadlines tighten. For New Entrants and Emerging Players: Begin with offset-mandated component supply contracts in India and Southeast Asia, where local content requirements create protected procurement channels outside incumbent strongholds. The most penetrable white-space sits in military turbofan aftermarket services for legacy fighter fleets, where incumbent OEMs have deprioritized spare parts logistics. A targeted go-to-market angle centers on rapid turnaround maintenance partnerships with regional carriers in Vietnam and Mexico, promising dispatch reliability guarantees that power-by-the-hour incumbents cannot match at comparable cost. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized welding equipment manufacturers and additive manufacturing service bureaus in the United States and Germany, where talent scarcity and capital intensity have compressed valuations. Long-term viability across the projection horizon hinges on exposure to geared turbofan architecture proliferation and SAF-compatible engine retrofit demand. The acquisition target archetype is mid-tier precision casting houses with FAA/EASA dual qualifications and underutilized capacity. The signal to watch is airline fleet planning department consolidation of engine selection authority, which accelerates contract concentration and elevates program-scale economics over unit-level innovation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | GE Aerospace's in-house production of high-pressure turbine blades insulates margins from Howmet Aerospace pricing power. |
| Power-by-the-Hour Contract Expansion | Rolls-Royce's TotalCare agreements with Emirates and Singapore Airlines convert capital expenditure into predictable recurring revenue streams. |
| SAF Compatibility Certification Investment | Pratt & Whitney's PW1000G series validation for 100% sustainable aviation fuel opens regulatory preferential access under EU Green Deal aviation mandates. |
| Geographic Manufacturing Footprint Diversification | Safran's Bangalore precision machining facility satisfies India's Directorate General of Foreign Trade offset requirements for Tejas fighter engine contracts. |
| Additive Manufacturing Scale-Up | MTU Aero Engines' laser powder bed fusion adoption for low-pressure turbine vanes collapses lead times versus legacy investment casting. |
Study Parameters
Engine OEM technical disclosures, FAA type certificate data, and EASA certification filings formed the secondary backbone, supplemented by customs records for turbofan engine trade flows and airline fleet planning department procurement documentation. Primary interviews with engine program directors, airline technical procurement managers, MRO facility operations heads, and superalloy casting plant supervisors validated demand assumptions and pricing dynamics. Bottom-up triangulation across installed base flight hour projections and top-down reconciliation with airframe delivery schedules anchored volume estimates.
Historical trendline analysis of engine delivery cycles, retirement patterns, and aftermarket service revenue conversion informed the projection framework. Segmentation modeling spanned bypass architecture, application category, technology subsystem, and end-user ownership structure, with regional regulatory cluster effects layered across the analysis window. CAGRs derived from elasticity-adjusted fleet renewal schedules and ICAO emissions compliance deadline impacts. Industry-specific forecast inputs incorporated geared turbofan penetration rates and sustainable aviation fuel infrastructure buildout timelines.
Underlying measurement precision varies by segment; high-bypass commercial installations carry tighter precision than military fighter programs where classified appropriations obscure procurement visibility. Forecasts reflect documented assumptions regarding airframe production rates, superalloy supply capacity expansion, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Turboprop Engine Market