
 Air Data Calibrators Market | 2026-2036
Air Data Calibrators Market Size, Share, and Industry Trends Forecast 2026-2036
Air Data Calibrators Market Insights
Modular bundling of pitot-static test sets with wireless data acquisition modules is pivoting buyer preference toward integrated field-deployable kits. Laversab leverages its military channel dominance to sustain long-term service contracts with defense agencies across multiple continents. Druck anchors its position through in-house pressure sensor production that controls component quality and reduces lead times for aerospace OEMs.
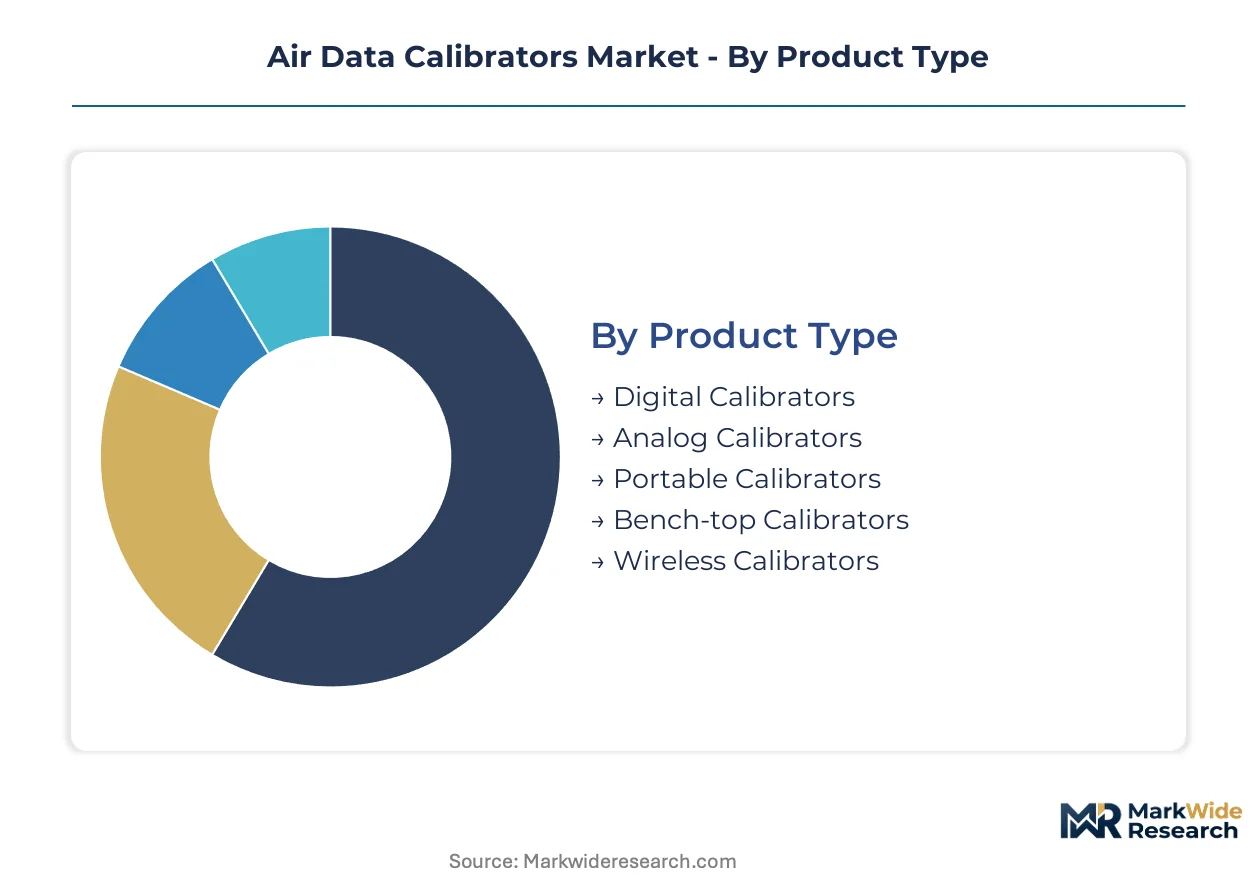
Air data calibrators are precision instruments that generate and measure pressure, temperature, and airflow variables to verify aircraft pitot-static systems, altimeters, airspeed indicators, and vertical speed indicators against certified reference standards, typically achieving accuracy within ±0.005% of full scale for pressure functions. Digital calibrators now lead product category revenue as flight line crews demand automated test sequences and digital logging that eliminates manual transcription errors. Portable calibrators represent the fastest-expanding configuration segment, driven by military operators and maintenance repair organizations that require depot-level accuracy in forward operating environments without bench-top infrastructure.
FAA Technical Standard Order requirements and EASA CS-25 airworthiness codes mandate periodic calibration intervals for all pitot-static test equipment used in certified aircraft maintenance, directly shaping replacement cycles and traceability documentation burdens for end users. Military operators face additional compliance layers from MIL-STD-1553 data bus integration standards and country-specific defense procurement regulations that specify calibration laboratory accreditation. Stakeholders must monitor evolving UAV type certification pathways in the United States, Europe, and China, as these will determine whether existing air data calibrator specifications satisfy unmanned platform testing or demand entirely new performance envelopes.
Market Dynamics
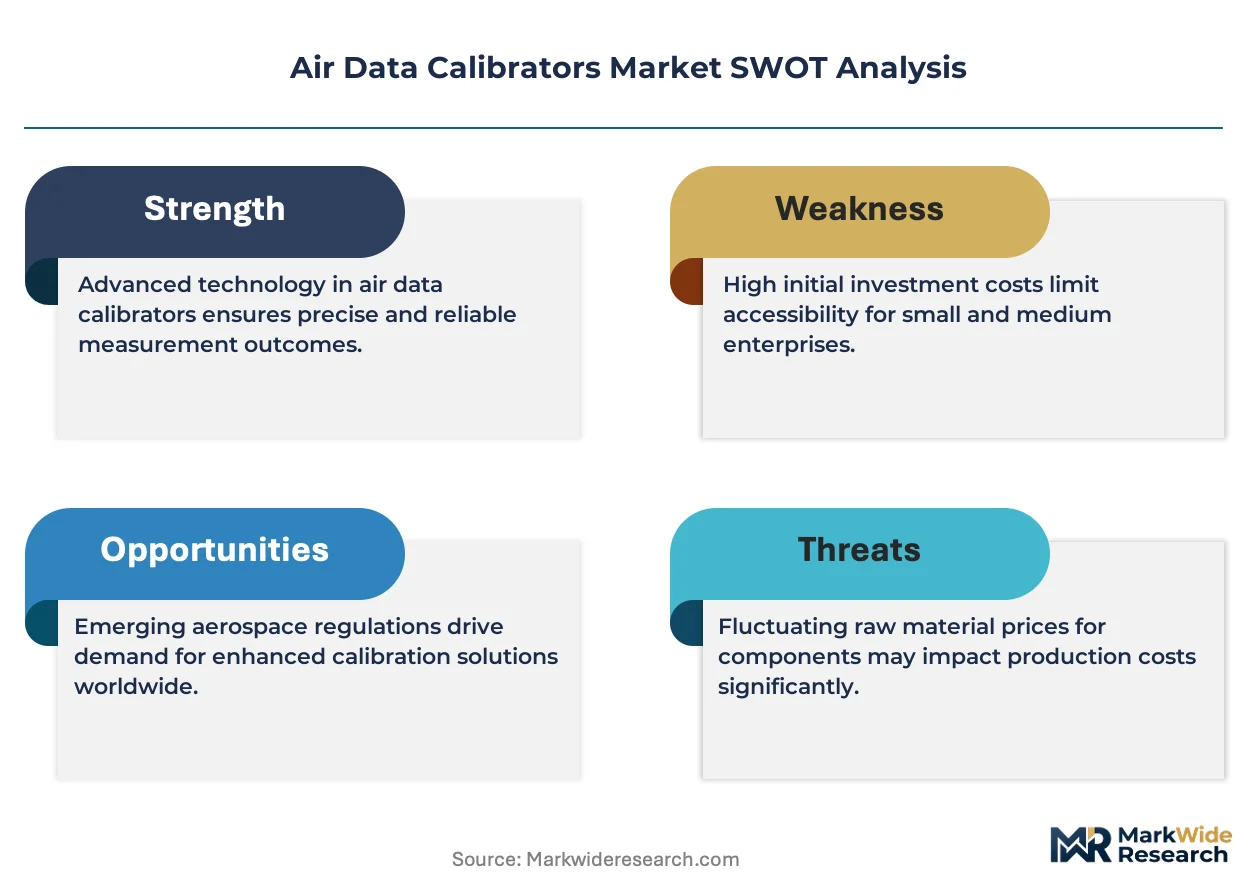
Defense procurement cycles and civilian aviation maintenance mandates are tightening calibration intervals, compressing equipment replacement timelines and forcing suppliers to hold larger certified inventory pools near military bases and MRO clusters.
Growth Catalysts
- FAA Technical Standard Order mandates:Periodic recertification requirements for pitot-static test equipment create predictable replacement demand across US commercial aviation maintenance networks.
- Wireless data acquisition modules:Flight line crews now expect automated test sequences with digital logging, eliminating manual transcription errors and accelerating turnaround times.
- China's military aviation expansion:The country's investment in next-generation fighter and transport fleets drives procurement of depot-level portable calibration systems for forward operating environments.
Market Restraints
- Precision pressure sensor supply concentration:Component sourcing depends on a limited number of qualified suppliers, creating lead time vulnerability for aerospace OEMs.
- Traceability documentation burdens:EASA CS-25 airworthiness codes impose extensive calibration record-keeping requirements that increase administrative overhead for smaller MRO operators.
- Bench-top infrastructure dependency:Fixed calibration laboratories face displacement risk as portable systems achieve equivalent accuracy without facility investment.
Strategic Opportunities
- UAV type certification pathways:Emerging unmanned platform standards in the United States, Europe, and China may require entirely new air data calibrator performance envelopes.
- Integrated field-deployable kits:Modular bundling of pitot-static test sets with wireless modules is pivoting buyer preference toward complete portable solutions.
- MIL-STD-1553 data bus integration:Defense procurement regulations specifying laboratory accreditation create service contract opportunities for certified calibration providers.
Industry Challenges
- Metrology technician scarcity:Specialized skills for pressure standard maintenance and uncertainty analysis are concentrating in defense contractor and national laboratory channels.
- Multi-standard compliance complexity:Manufacturers must simultaneously satisfy FAA, EASA, and country-specific military specifications, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Data Calibrators Market |
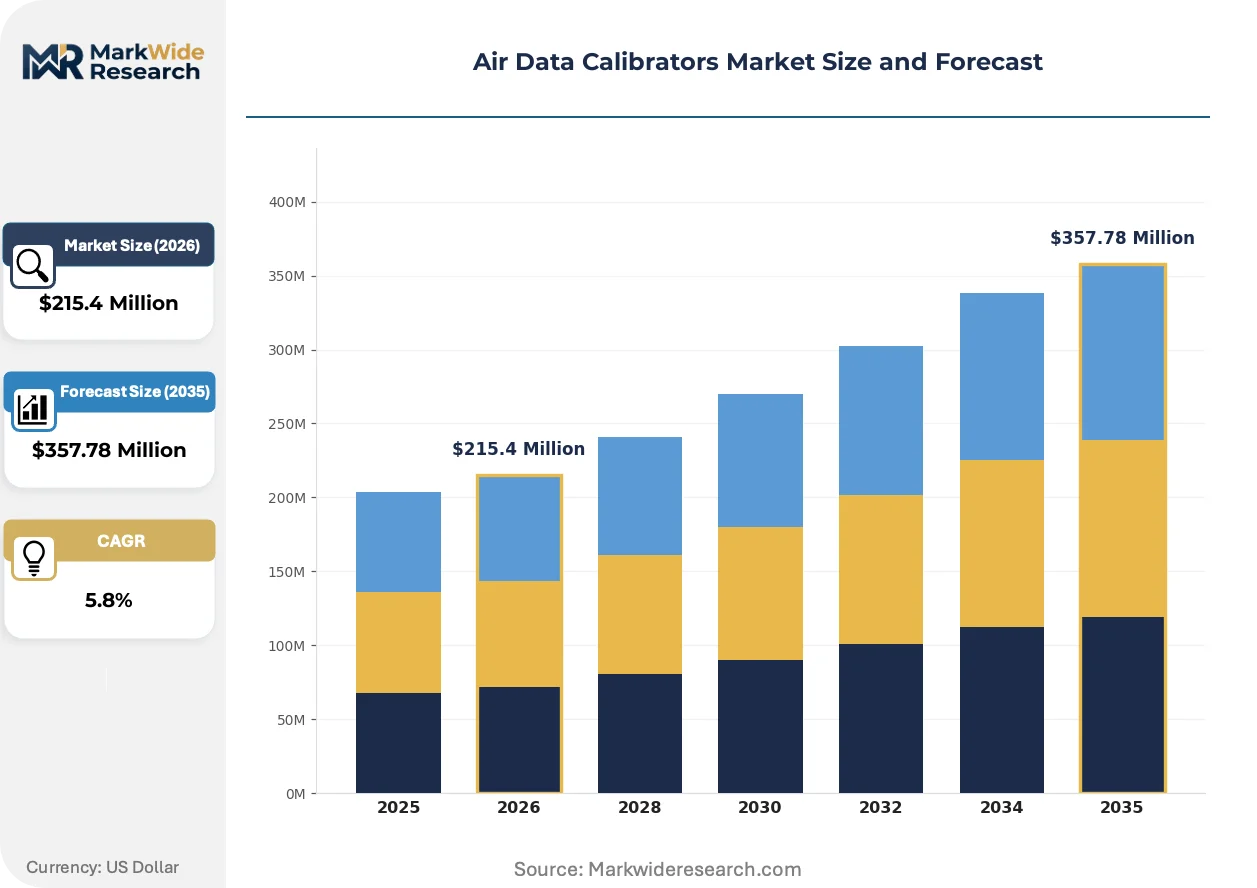
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Calibrators, Analog Calibrators, Portable Calibrators, Bench-top Calibrators, Wireless Calibrators Technology: Pitot Static Systems, Pressure Measurement, Temperature Sensors, Airflow Sensors, Data Acquisition Application: Aircraft Testing, UAV Calibration, Aerospace Engineering, Simulator Training, Wind Tunnel Testing End User: Aircraft Manufacturers, Maintenance Repair Organizations, Flight Schools, Military Operators, Calibration Laboratories |
| Companies Covered | Laversab, Raptor Scientific (TestVonics), Druck (Baker Hughes), Mensor, Barfield, ATEQ Aviation, D.Marchiori (DMA), King Nutronics Corporation, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Data Calibrators Market Trends and Innovations
Digital automation and portable precision are restructuring how calibration services are delivered, with field-deployable accuracy now matching laboratory-grade performance and compressing the traditional infrastructure hierarchy.
Automated test sequence software is converging with cloud-based calibration management platforms. Military operators and commercial MROs are adopting these systems to maintain continuous traceability chains across distributed maintenance sites. This convergence is collapsing the distinction between field and laboratory calibration workflows, enabling remote audit readiness without physical document transport.
EASA's evolving CS-25 airworthiness interpretations are tightening uncertainty budgets for altimeter verification procedures. Aircraft manufacturers must now demonstrate tighter pressure measurement confidence intervals during type certification. European calibration service providers are responding by upgrading primary standard capabilities and pursuing expanded ISO 17025 scopes.
Maintenance organizations are unbundling after-sales service contracts from equipment procurement. Buyers now prefer separate calibration service agreements with defined turnaround guarantees over bundled multi-year packages. This pattern is most visible in Germany's commercial aviation sector, where independent calibration laboratories are capturing service volume from OEM-affiliated providers.
Air Data Calibrators Market Segmentation
Air data calibrator procurement varies sharply by operational environment, with military flight lines demanding portable precision while commercial MROs favor automated bench systems. Equipment specification directly determines compliance pathway, traceability burden, and total cost of ownership across these divergent use cases.
Product Type:
Capital intensity clusters in bench-top infrastructure and wireless integration layers, while portable configurations minimize facility investment at the cost of per-unit precision engineering.
- Digital Calibrators:Microprocessor-controlled units execute automated test sequences with digital logging capabilities, eliminating manual transcription errors during pitot-static verification. Flight line crews at US military bases and German commercial MROs now specify these as standard equipment, driven by FAA Technical Standard Order documentation requirements and EASA CS-25 traceability mandates.
- Portable Calibrators:Battery-powered systems achieve depot-level accuracy without fixed laboratory infrastructure, enabling forward deployment in expeditionary maintenance environments. China's military aviation expansion drives procurement concentration here, as next-generation fighter and transport fleets require calibration capability at dispersed operating locations.
- Analog Calibrators:Mechanical pressure standards with manual readouts persist in legacy fleet support and training applications where digital complexity introduces failure modes.
- Bench-top Calibrators:Fixed installations with primary standard traceability serve national calibration laboratories and aircraft type certification programs requiring lowest uncertainty budgets.
- Wireless Calibrators:Bluetooth-enabled modules transmit measurement data directly to cloud-based calibration management platforms, collapsing field-to-laboratory workflow distinctions.
Digital calibrators absorb the bulk of installed capacity; portable calibrators are expanding most quickly.
Technology:
Component sophistication determines supply chain vulnerability, with precision pressure sensors concentrating among qualified aerospace suppliers and data acquisition modules facing shorter innovation cycles.
- Pitot Static Systems:Integrated test sets simulate altitude, airspeed, and vertical speed conditions through precision pressure generation and measurement. Military procurement specifications from the US Department of Defense and China's defense agencies mandate MIL-STD-1553 data bus integration for these systems.
- Pressure Measurement:Quartz resonant and capacitive pressure transducers achieve ±0.005% full-scale accuracy required for altimeter verification during aircraft type certification. EASA's tightening CS-25 uncertainty interpretations are forcing upgrades to primary standard capabilities among European calibration service providers.
- Temperature Sensors:Platinum resistance thermometers and thermocouple interfaces correct pressure measurements for thermal drift in flight line conditions.
- Airflow Sensors:Laminar flow elements and hot-wire anemometers verify total pressure probe performance in wind tunnel and simulator environments.
- Data Acquisition:Multi-channel sampling systems with automated uncertainty calculation software compress calibration interval documentation burdens for MRO operators.
Pressure measurement commands the highest component investment; data acquisition is climbing the fastest as cloud integration becomes standard.
Application:
Regulatory stringency varies dramatically across application contexts, with certified aircraft maintenance imposing full FAA and EASA compliance burdens while simulator training operates under relaxed traceability requirements.
- Aircraft Testing:Type certification programs for new commercial and military airframes require exhaustive pitot-static system validation against certified reference standards. Boeing and Airbus supplier networks in the United States, Germany, and China concentrate demand here, with calibration intervals tied directly to production line throughput.
- UAV Calibration:Emerging unmanned platform certification pathways in the United States, Europe, and China may demand entirely new air data calibrator performance envelopes as type standards solidify. Military drone operators currently adapt existing portable systems, but dedicated UAV calibration protocols are under development.
- Aerospace Engineering:Research and development applications prioritize measurement flexibility over strict traceability, enabling use of modular sensor configurations.
- Simulator Training:Flight training devices require periodic air data channel verification, though with relaxed uncertainty budgets compared to airworthy aircraft.
- Wind Tunnel Testing:Aerodynamic research facilities employ high-channel-count pressure scanning systems for model surface pressure mapping.
Aircraft testing dominates current procurement volume; UAV calibration is gaining share fastest as regulatory frameworks mature.
End User:
Buying power and technical sophistication diverge sharply, with military operators leveraging multi-year service contracts while independent calibration laboratories compete on turnaround guarantees.
- Military Operators:Defense agencies across multiple continents specify depot-level portable systems with integrated logistics support, sustaining long-term service relationships. US Air Force and Navy procurement cycles, combined with China's military aviation investment, create predictable replacement demand for precision calibration equipment.
- Maintenance Repair Organizations:Commercial aviation MROs face compressed calibration intervals from tightening FAA and EASA mandates, forcing equipment refresh timelines. Germany's independent calibration laboratories are capturing service volume from OEM-affiliated providers through unbundled service agreements with defined turnaround guarantees.
- Aircraft Manufacturers:Production line integration demands automated test sequences with direct quality system interface.
- Flight Schools:Training fleet maintenance operates with reduced regulatory burden, prioritizing cost-effective portable solutions.
- Calibration Laboratories:ISO 17025-accredited facilities maintain primary standards traceable to national metrology institutes.
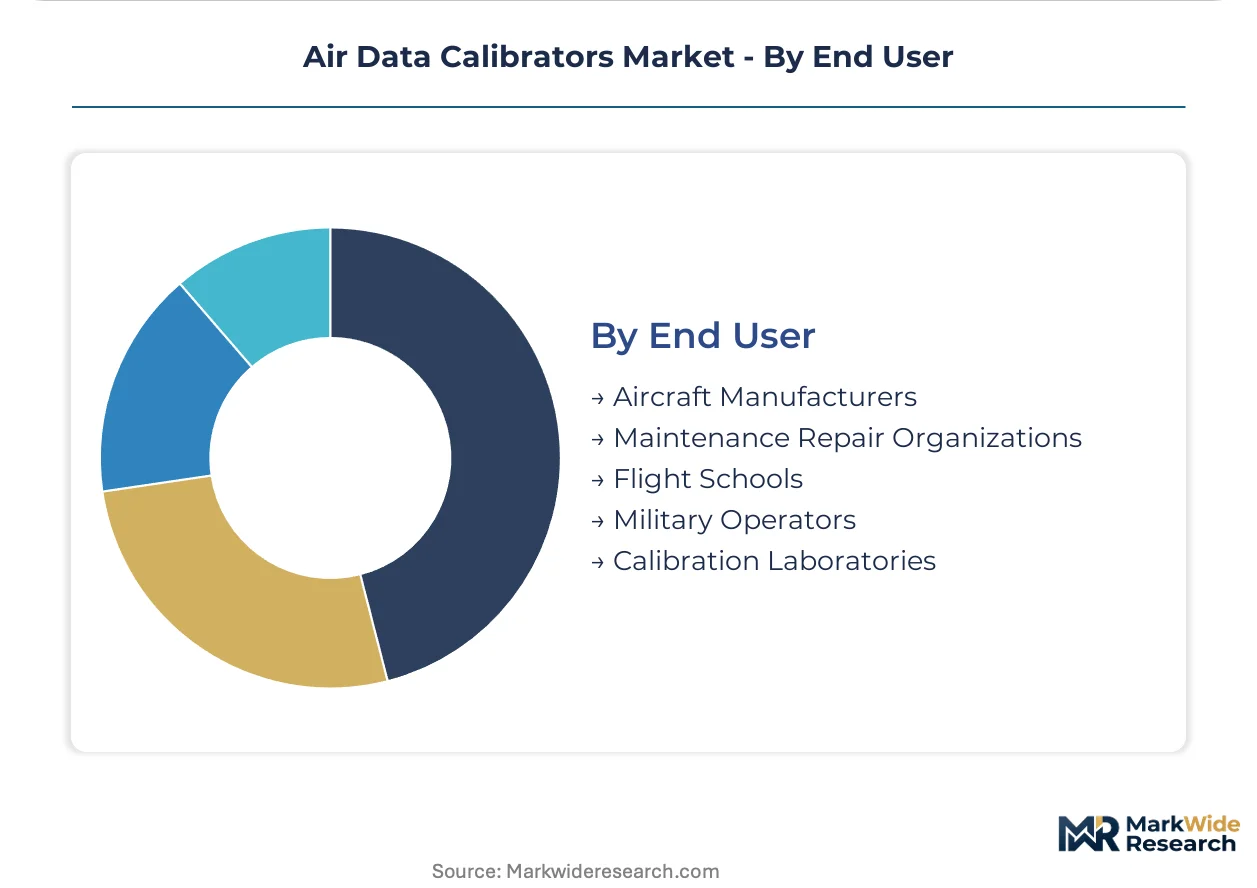
Military operators and MROs together absorb the bulk of installed capacity; calibration laboratories are expanding most quickly as third-party service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Germany and the United States contrasts with consumption expansion in China's military aviation sector. Defense procurement cycles and commercial MRO density determine regional equipment deployment patterns. Calibration service networks cluster near major air force bases and aircraft production facilities.
United States
FAA Technical Standard Order mandates drive predictable replacement demand across commercial aviation maintenance networks. Military procurement from the Department of Defense specifies MIL-STD-1553 data bus integration for pitot-static test systems. Oklahoma City and San Antonio host concentrated calibration service operations supporting Air Force and Navy fleet maintenance.
Germany
EASA CS-25 airworthiness codes impose extensive traceability documentation requirements that shape equipment specifications. Independent calibration laboratories in Hamburg and Munich capture service volume from OEM-affiliated providers through unbundled agreements. Production integration demands from Airbus supplier networks concentrate demand for automated test sequences.
China
Investment in next-generation fighter and transport fleets drives procurement of depot-level portable calibration systems. The country's military aviation expansion requires calibration capability at dispersed operating locations beyond fixed laboratory infrastructure. Xi'an and Chengdu aerospace clusters host expanding maintenance bases for indigenous aircraft programs.
United Kingdom
Royal Air Force procurement cycles sustain demand for integrated field-deployable kits with logistics support contracts. EASA regulatory alignment maintains pressure measurement uncertainty standards for commercial MRO operations. Bristol and Broughton aerospace corridors concentrate calibration service providers supporting Airbus wing production and military fleet maintenance.
France
Dassault Aviation and Safran supplier networks generate demand for precision pressure standards during aircraft type certification. EASA tightening of CS-25 uncertainty interpretations forces upgrades to primary standard capabilities among Paris-region calibration laboratories. Toulouse and Bordeaux clusters integrate calibration services into commercial and military production workflows.
Air Data Calibrators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base separates into defense contractors with long-term service relationships, precision sensor manufacturers with captive component supply, and calibration service providers with ISO 17025 accreditation. Three archetypes dominate: integrated system houses controlling full production chains, modular equipment specialists emphasizing field portability, and third-party service laboratories competing on turnaround guarantees. Consolidation pressures concentrate among component suppliers while equipment vendors pursue geographic expansion through military channel partnerships.
Within the integrated system tier, Laversab and Druck exemplify contrasting strategic positions. Laversab occupies a defense-focused archetype through sustained service contracts with military agencies. Druck anchors the precision sensor manufacturing vector through in-house pressure transducer production. Raptor Scientific represents the modular specialist position, with TestVonics-branded equipment targeting portable deployment requirements. These three patterns—service-integrated, component-captive, and field-specialized—structure competitive differentiation across procurement channels.
| Leading Market Players |
|---|
| Laversab |
| Raptor Scientific (TestVonics) |
| Druck (Baker Hughes) |
| Mensor |
| Barfield |
| ATEQ Aviation |
| D.Marchiori (DMA) |
| King Nutronics Corporation |
| Fluke Corporation |
| Others |
Pricing and Supply Chain Analysis
Quartz resonant pressure sensor pricing indices cascade through aerospace calibration equipment tiers, compressing margins in standard-grade portable units while premium bench-top systems with captive sensor production retain pricing power against military procurement budgets.
Pricing Analysis
Margin tightening in portable calibrator tiers reflects quartz pressure transducer supply concentration among qualified aerospace suppliers. Three-tier pricing structure across primary-standard, field-certified, and training-grade levels separates calibration laboratories from flight line operators. ISO 17025 accreditation commands substantial premiums over uncertified equipment. Cost-down pressure on analog legacy systems accelerates as digital automation becomes mandatory for FAA documentation compliance. Independent MROs exhibit highest price sensitivity; defense agencies with multi-year service contracts demonstrate lowest.
Supply Chain Analysis
Metrology technician scarcity in Germany and the United States constrains precision pressure standard manufacturing capacity. Component sourcing draws from quartz crystal suppliers in Switzerland, capacitive sensor foundries in Japan, and data acquisition module producers in Taiwan. Single-source vulnerability concentrates in resonant pressure transducers qualified to MIL-STD-1553 integration standards. Distribution runs through defense contractor channels for military procurement and independent calibration service networks for commercial aviation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around component-captive integrated system houses as precision pressure sensor supply concentration eliminates pure-play assemblers without backward integration into transducer manufacturing.
For Market Incumbents: To counter portable system entrants achieving laboratory-grade accuracy, deepen captive sensor production through acquisition of quartz resonant transducer specialists in Switzerland or Japan. Anchor defense service contracts with MIL-STD-1553 integrated logistics support packages that extend beyond equipment replacement cycles. For New Entrants and Emerging Players: Launch via cloud-based calibration management platform partnerships targeting Germany's independent MRO laboratories unbundling from OEM-affiliated service providers. White-space concentration sits in UAV-specific calibration protocols as type certification pathways solidify in the United States and China. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision sensor manufacturers with ISO 17025 laboratory accreditation in France and the United Kingdom as EASA uncertainty budget tightening forces capability upgrades. Signal to watch: defense procurement cycle announcements from the US Department of Defense and China's military aviation investment authorities indicating replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Transducer Manufacturing | Captive quartz resonant sensor production secures supply against qualified supplier concentration in Switzerland and Japan. |
| MIL-STD-1553 Data Bus Certification Investment | Defense procurement specifications from the US Department of Defense mandate this integration for pitot-static test system eligibility. |
| Cloud-Based Calibration Management Platform Launch | Remote audit readiness collapses field-to-laboratory workflow distinctions for distributed military maintenance sites. |
| UAV-Specific Protocol Development | Emerging unmanned platform type certification in the United States and China demands dedicated performance envelopes. |
| ISO 17025 Accreditation Expansion | EASA CS-25 tightening uncertainty budgets forces European calibration service providers to upgrade primary standard capabilities. |
Research Methodology
FAA Technical Standard Order documentation, EASA CS-25 airworthiness interpretation records, and defense procurement contract filings formed the secondary backbone. Primary interviews with military calibration program managers, commercial MRO technical directors, aerospace OEM quality engineers, and ISO 17025 laboratory accreditation officers combined with bottom-up equipment shipment analysis and top-down defense budget allocation triangulation.
Historical trendline analysis of pitot-static test equipment replacement cycles, pressure sensor qualification timelines, and calibration interval compression patterns informed the projection framework. Segmentation dimensions spanned product configuration, pressure measurement technology, application context from aircraft testing through UAV calibration, and end-user archetype. CAGRs derived from equipment procurement elasticity to regulatory mandate timing and military fleet modernization schedules.
The model assumes a particular technology adoption path; alternative pathways for wireless data acquisition module integration would alter the outlook. Forecasts reflect assumptions regarding EASA uncertainty budget evolution, FAA mandate enforcement intensity, and China's military aviation procurement continuity. Material deviation in defense budget authorization triggers or commercial aviation maintenance cycle recovery warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market