
 Aircraft Control Software Market | 2026-2036
Aircraft Control Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Control Software Market Insights
European avionics engineering is consolidating as tier-one suppliers absorb embedded software competencies from fragmented middleware vendors. Honeywell International Inc. leverages its integrated flight-deck architecture to dominate commercial retrofits. RTX Corporation sustains military-grade control systems through captive semiconductor sourcing. Safran SA anchors European narrowbody programs with fly-by-wire platforms certified to DO-178C.
Aircraft control software comprises real-time operating systems, sensor fusion algorithms, and actuator command modules that process flight-critical data within deterministic latency bounds, typically sub-50 milliseconds, to maintain stability and trajectory authority. Flight Management System deployments generate the largest revenue pool among solution offerings due to mandatory retrofit cycles on aging narrowbody fleets. Autopilot modules represent the fastest-expanding segment as single-pilot and reduced-crew operations advance toward regulatory acceptance. Safety Monitoring solutions command premium pricing where airlines face escalating insurance mandates from the EU Aviation Safety Agency.
FAA certification under DO-178C and EASA equivalent ED-12C impose exhaustive verification rigor that extends development timelines and elevates barriers for new entrants. The EU AI Act introduces additional algorithmic transparency obligations for adaptive flight control systems operating in European airspace. Stakeholders must monitor divergence between FAA and EASA interpretive guidance on machine-learning-based control loops to avoid dual-certification cost inflation.
Market Dynamics
DO-178C certification requirements from the FAA and EASA are compressing development timelines while elevating verification costs, forcing suppliers to restructure engineering workflows around formal methods and model-based design.
Growth Catalysts
- Autonomous flight mandates:Commercial airlines retrofit narrowbody fleets with single-pilot-capable autopilot modules to reduce crew costs. EASA regulatory pathways for reduced-crew operations accelerate procurement cycles.
- EU AI Act transparency obligations:Algorithmic explainability requirements for adaptive control systems create replacement demand for legacy black-box architectures in European airspace.
- Defense procurement concentration:Pentagon programs for next-generation combat aircraft drive classified development contracts toward vendors with captive semiconductor fabrication.
Market Restraints
- Verification cost inflation:DO-178C Level A certification demands exhaustive testing that consumes 60-70% of program budgets for flight-critical software modules.
- Semiconductor supply concentration:Radiation-hardened processors for space and military applications depend on a single foundry in New Mexico, creating single-point vulnerability.
- Formal methods talent scarcity:Engineers proficient in Coq, Isabelle, and SPARK verification languages command premium compensation that smaller vendors cannot match.
Strategic Opportunities
- Urban air mobility underpenetration:eVTOL manufacturers in Germany and France seek certifiable control stacks for passenger drone operations before 2030 EASA deadlines.
- Digital twin convergence:Real-time hardware-in-the-loop simulation combined with AI-driven failure prediction enables predictive maintenance contracts for airline fleets.
- India defense localization:Indigenization mandates under the country's aerospace procurement rules create openings for joint ventures with HAL and DRDO laboratories.
Industry Challenges
- Legacy system integration friction:ARINC 429 and MIL-STD-1553 bus architectures in aging Boeing 737 and Airbus A320 fleets resist seamless upgrade to Ethernet-based deterministic networking.
- Machine learning certification ambiguity:FAA interpretive guidance on neural network verification for adaptive control loops remains unpublished, stalling development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Control Software Market |
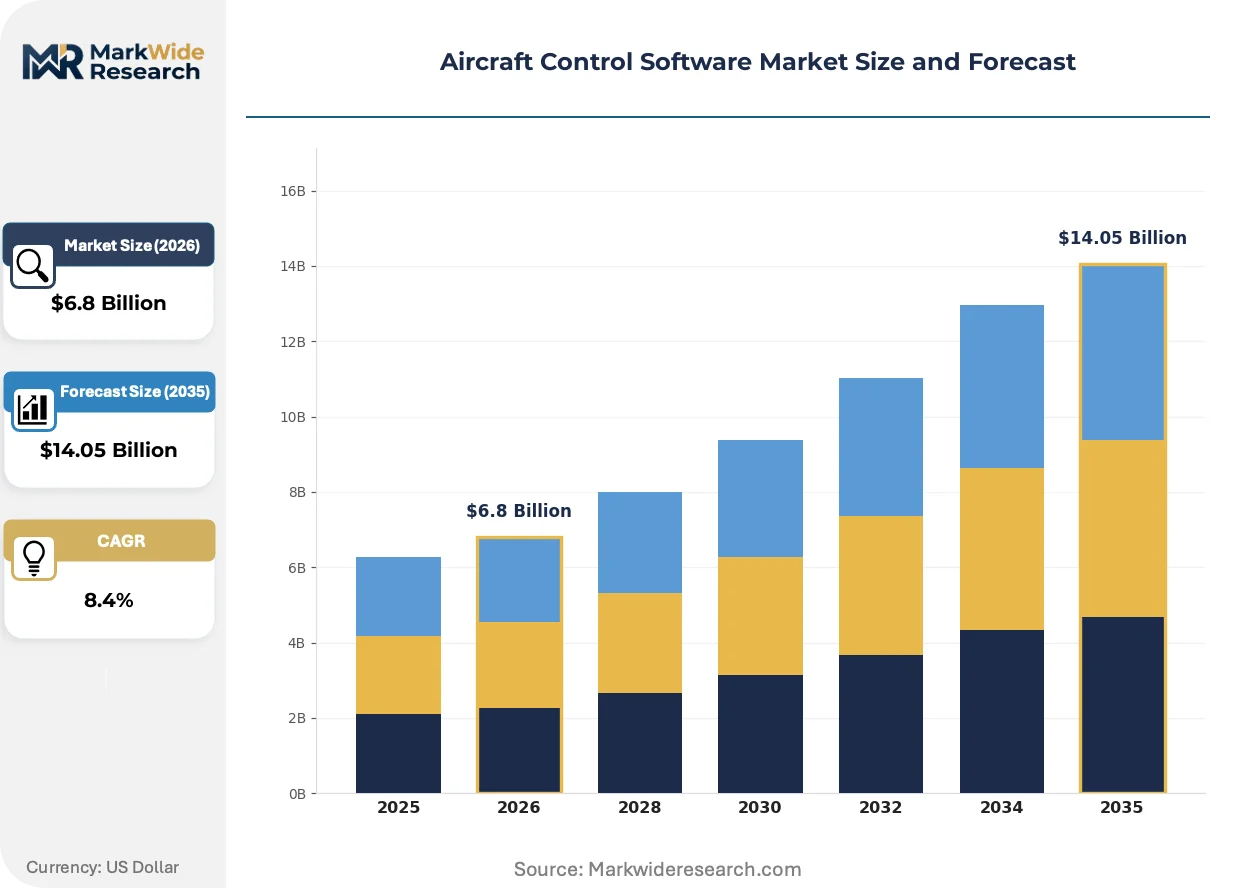
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Onboard, Ground-Based, Cloud-Based, Hybrid Solution Offering: Flight Management System, Navigation Control, Autopilot, Safety Monitoring, Communication Interface Use Case: Airline Operations, Military Missions, Cargo Transport, Flight Training, Air Traffic Control Customer Role: Aircraft Manufacturers, Aviation Operators, Defense Agencies, Flight Schools |
| Companies Covered | Honeywell International Inc., RTX Corporation, Safran SA, Moog Inc., Parker Hannifin Corporation, Collins Aerospace, BAE Systems, Thales Group, Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Control Software Market Trends and Innovations
Deterministic Ethernet architectures are displacing legacy avionics databuses, while formal verification methods and AI-driven development tools compress the path to certification compliance.
Time-Triggered Ethernet (TTEthernet) is overtaking ARINC 664 and AFDX as the backbone protocol for integrated modular avionics. Airbus and Boeing next-generation programs mandate TTEthernet for its guaranteed latency and bandwidth partitioning. The protocol is overtaking legacy alternatives in fly-by-wire retrofits by eliminating the need for separate critical and non-critical networks.
EASA's ED-12C/DO-178C interpretive guidance on machine learning is tightening verification requirements for adaptive flight control systems. Developers must now demonstrate bounded behavior for neural network inference layers under all foreseeable operational conditions. European narrowbody programs face schedule compression as engineering teams restructure AI modules to satisfy deterministic execution proofs.
Airlines now unbundle software maintenance from hardware support contracts, procuring control system updates through subscription models tied to flight-hour metrics. Tier-one suppliers respond with continuous integration pipelines that deploy certified patches without aircraft downtime. This consumption-pattern shift concentrates procurement leverage with Lufthansa, Delta, and Air France-KLM fleet engineering departments.
Aircraft Control Software Market Segmentation
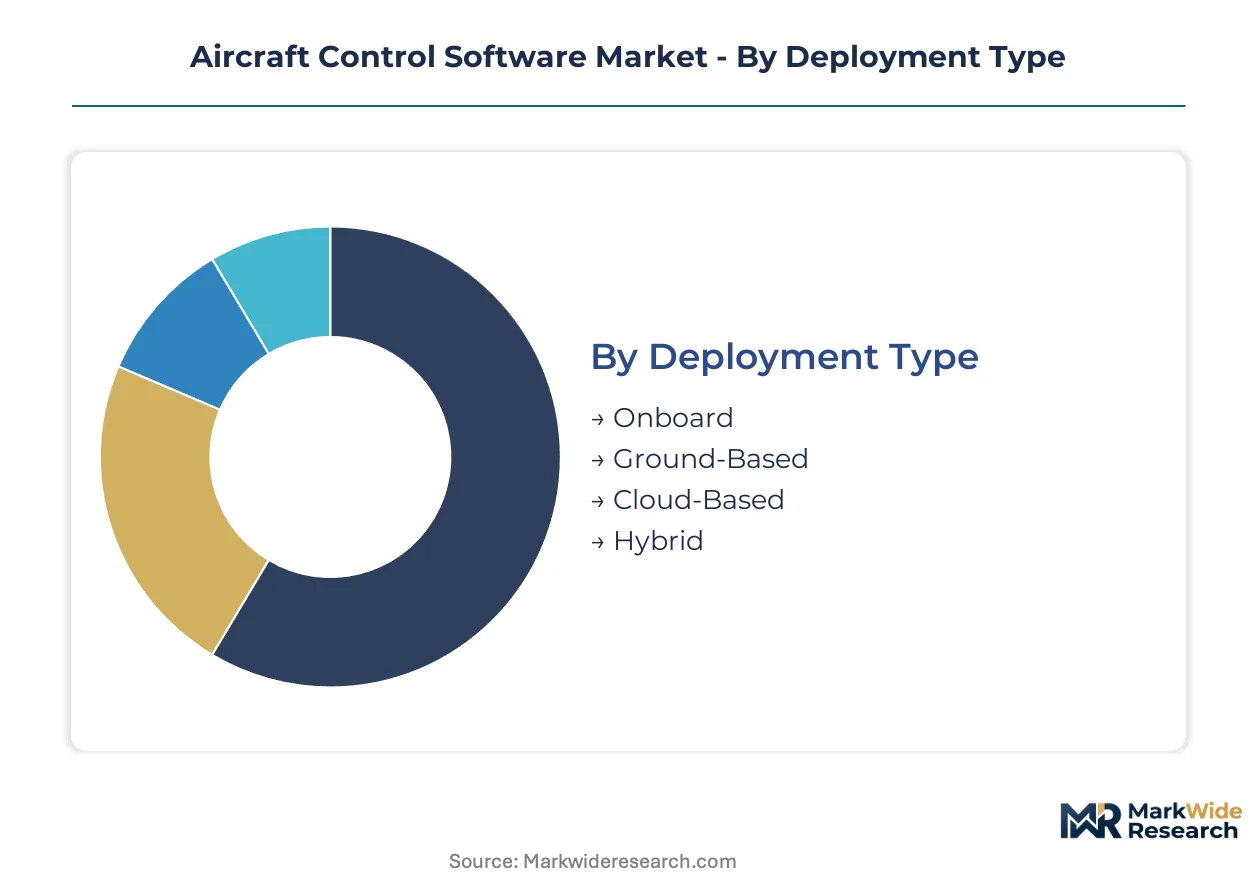
Aircraft control software segmentation reveals how capital allocation, regulatory burden, and operational criticality fragment procurement patterns across the aviation value chain. Each dimension captures distinct buyer priorities, from DO-178C certification intensity to integration complexity with legacy avionics architectures.
Deployment Type:
Capital intensity peaks where hardware-software integration demands radiation-hardened processors and deterministic latency guarantees. Ground and cloud deployments spread costs across multiple aircraft, while onboard systems concentrate investment per unit.
- Onboard:Embedded real-time operating systems execute sensor fusion and actuator commands within sub-50 millisecond deterministic bounds. Flight-critical modules in Boeing and Airbus narrowbodies absorb 60-70% of program budgets for DO-178C Level A verification. Airlines retrofit aging 737 and A320 fleets with upgraded flight management computers to satisfy EASA mandates for reduced-crew operations.
- Ground-Based:Remote piloting stations and fleet monitoring centers process telemetry through redundant server architectures. Military drone programs in the United States and Germany drive procurement for beyond-line-of-sight control infrastructure. Defense agencies prioritize hardened facilities with captive semiconductor supply chains to mitigate single-foundry vulnerability.
- Cloud-Based:Predictive maintenance algorithms and flight data analytics deploy through airline subscription models. Lufthansa and Delta fleet engineering departments procure software updates tied to flight-hour metrics without aircraft downtime.
- Hybrid:Partitioned architectures split critical control loops onboard while offloading diagnostics and optimization to ground servers. Urban air mobility developers in Germany and France seek certifiable hybrid stacks for passenger drone operations.
Most installed capacity flows through Onboard systems. Expansion is steepest in Hybrid configurations.
Solution Offering:
Revenue concentration tracks mandatory retrofit cycles and insurance-driven procurement rather than discretionary technology adoption. Premium pricing attaches to modules where failure consequences trigger regulatory grounding or liability exposure.
- Flight Management System:Integrated navigation, performance optimization, and trajectory management software certified to DO-178C standards. Aging narrowbody fleets in the United States and Europe drive mandatory replacement demand as legacy architectures reach end-of-life. Airlines face compressed procurement timelines to satisfy EASA deadlines for single-pilot-capable operations.
- Autopilot:Reduced-crew and single-pilot modules represent the steepest expansion trajectory as EASA regulatory pathways advance toward operational approval. Honeywell and Safran anchor development for European narrowbody programs with fly-by-wire platforms requiring exhaustive neural network verification.
- Navigation Control:Sensor fusion algorithms integrate GPS, inertial reference, and ground-based augmentation systems. Military missions demand anti-jam capabilities with classified performance specifications.
- Safety Monitoring:Real-time exceedance detection and predictive failure alerting command premium pricing where EU Aviation Safety Agency insurance mandates escalate carrier liability exposure.
- Communication Interface:ARINC 429, MIL-STD-1553, and Ethernet protocol stacks bridge legacy databuses with modern integrated modular avionics. Integration friction with aging Boeing and Airbus fleets resists seamless upgrade to deterministic networking.
Procurement volume concentrates in Flight Management System replacements. Technology leadership is shifting toward Autopilot modules.
Use Case:
End-use segmentation separates mission-critical defense procurement from commercial aviation's cost-driven retrofit cycles. Each vertical imposes distinct certification timelines and supplier qualification requirements.
- Airline Operations:Commercial carriers modernize fleets with autonomous flight capabilities to reduce crew costs. United States-based operators anchor demand as Boeing delivery schedules and FAA certification pathways set industry pacing.
- Military Missions:Pentagon next-generation combat aircraft programs drive classified development contracts toward vendors with captive semiconductor fabrication in New Mexico. RTX Corporation sustains military-grade control systems through upstream supply control.
- Cargo Transport:Dedicated freighter operators retrofit converted narrowbodies with updated flight management systems. EASA regulatory pressure on European cargo carriers accelerates replacement timelines.
- Flight Training:Simulator manufacturers procure certifiable control stacks for pilot qualification devices. Flight schools in India seek joint venture partnerships under indigenization mandates.
- Air Traffic Control:Ground-based separation management and trajectory coordination systems deploy across national air navigation service providers. FAA and EASA interoperability standards shape procurement specifications.
Revenue concentration sits with Airline Operations. Procurement momentum is building fastest in Military Missions.
Customer Role:
Buyer concentration determines contract structure, from long-term platform development partnerships to discrete retrofit purchases. Direct relationships with fleet engineering departments increasingly displace traditional hardware-software bundled procurement.
- Aircraft Manufacturers:Boeing and Airbus integrate control software into original equipment fly-by-wire architectures. DO-178C certification costs and development timeline compression force restructuring around formal methods and model-based design.
- Aviation Operators:Lufthansa, Delta, and Air France-KLM fleet engineering departments now unbundle software maintenance from hardware support contracts. Continuous integration pipelines deploy certified patches through subscription models tied to flight-hour consumption.
- Defense Agencies:Pentagon programs concentrate procurement with vendors possessing classified facility clearances and radiation-hardened processor supply chains. Indian defense localization mandates under HAL and DRDO indigenization rules create joint venture openings.
- Flight Schools:Training device manufacturers procure certifiable control stacks for pilot qualification simulators. Procurement scale remains constrained against commercial and military verticals.
Contract value concentrates with Aircraft Manufacturers. Procurement autonomy is shifting fastest toward Aviation Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping engineering center placement as DO-178C compliance costs diverge between jurisdictions. Vendors migrate development to regions with lower formal-methods talent costs while maintaining certification proximity to FAA and EASA oversight hubs.
United States
Boeing's narrowbody delivery schedules and Pentagon next-generation combat aircraft programs concentrate demand. FAA DO-178C interpretive guidance on machine learning verification remains unpublished, stalling adaptive control development. Seattle and Wichita engineering clusters absorb the bulk of flight-critical software procurement.
France
Airbus narrowbody programs and Safran's fly-by-wire platforms anchor European demand. EASA's ED-12C guidance on neural network bounded behavior tightens verification timelines for adaptive systems. Toulouse and Paris-Saclay engineering corridors host the continent's densest concentration of DO-178C certification specialists.
Germany
Lufthansa's fleet engineering department unbundles software maintenance contracts, shifting procurement leverage toward operators. EU AI Act algorithmic transparency obligations create replacement demand for legacy black-box architectures. Munich and Hamburg urban air mobility developers seek certifiable control stacks for 2030 EASA deadlines.
India
Defense indigenization mandates under HAL and DRDO procurement rules drive joint venture formation. Flight training device manufacturers procure certifiable control stacks for pilot qualification simulators. Bangalore and Hyderabad aerospace clusters attract tier-one supplier engineering offshoring for model-based design workflows.
United Kingdom
BAE Systems sustains military-grade development through classified facility clearances and radiation-hardened processor supply relationships. CAA convergence with EASA standards shapes certification pathway planning for dual-market products. Bristol and Broughton engineering centers specialize in formal verification toolchains for safety-critical modules.
Aircraft Control Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue urban air mobility and reduced-crew autopilot specializations. The vendor base concentrates around tier-one avionics integrators with captive semiconductor sourcing and formal-methods capabilities. Three archetypes dominate: integrated flight-deck architects, military-grade control specialists with upstream supply control, and fly-by-wire platform anchors for narrowbody programs. Competitive moves center on absorbing embedded software competencies from fragmented middleware vendors and restructuring engineering workflows around model-based design.
Among North American-integrated conglomerates, Honeywell International Inc. and RTX Corporation exemplify contrasting supply-chain strategies. Honeywell leverages integrated flight-deck architecture dominance for commercial retrofit markets. RTX sustains military-grade positioning through captive semiconductor fabrication in New Mexico. Safran SA occupies a comparable anchor position in European narrowbody programs, representing the continent's fly-by-wire platform concentration. Moog Inc. and Parker Hannifin Corporation sit within the actuator command module specialization tier, serving both commercial and defense verticals through deterministic control hardware integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| Safran SA |
| Moog Inc. |
| Parker Hannifin Corporation |
| Collins Aerospace |
| BAE Systems |
| Thales Group |
| Boeing Company |
| Others |
Pricing and Supply Chain Analysis
Defense contractor consolidation through private-equity rollups has concentrated pricing power among tier-one avionics integrators with captive semiconductor sourcing, while formal-methods talent scarcity inflates engineering costs that pass through to airline procurement budgets.
Pricing Analysis
Direct-to-OEM channel structures dominate procurement, with Boeing and Airbus extracting volume discounts that compress margins for flight-critical software modules. Three-tier pricing structure across DO-178C Level A certified, Level B verified, and non-critical diagnostic tiers separates premium safety monitoring from standard autopilot functions. Pricing pressure stems from EASA's accelerating retrofit deadlines for reduced-crew operations, which compress supplier negotiation timelines. Cargo carriers and regional airlines exhibit highest price sensitivity, while defense agencies absorb premium pricing for radiation-hardened processor integration.
Supply Chain Analysis
India's defense procurement localization mandates under HAL indigenization rules are reshaping sourcing patterns, forcing joint ventures with domestic engineering clusters in Bangalore and Hyderabad. Radiation-hardened semiconductor fabrication concentrates in the United States, Taiwan, and South Korea, with single-foundry dependency in New Mexico creating structural vulnerability for military-grade control systems. Supply chain risk centers on tariff exposure for European narrowbody programs sourcing TTEthernet components from Asian foundries. Distribution runs through tier-one avionics integrators directly to aircraft manufacturers and airline fleet engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EASA's ED-12C interpretive guidance on neural network bounded behavior creates replacement demand cycles that outpace organic growth.
For Market Incumbents: Anchor certification proximity by embedding formal-methods teams within Toulouse and Seattle engineering corridors, absorbing fragmented middleware vendors before emerging urban air mobility specialists consolidate embedded software competencies. Vertical integration into radiation-hardened processor supply chains defends against single-foundry vulnerability while DO-178C Level A verification investment creates margin protection from talent scarcity inflation. For New Entrants and Emerging Players: Urban air mobility developers in Germany and France represent the most penetrable buyer archetype, seeking certifiable hybrid control stacks before EASA's 2030 passenger drone deadlines. White-space concentration sits in predictive maintenance algorithms for airline subscription models and flight training device control stacks under India's indigenization mandates. A formal-methods-as-a-service go-to-market angle bypasses captive talent costs that burden tier-one integrators. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap middleware vendors with DO-178C certification track records but fragmented customer concentration. Long-term viability favors targets with model-based design toolchains and EASA regulatory relationships that transfer across urban air mobility and reduced-crew autopilot applications. Watch FAA interpretive guidance publication on machine learning verification as the signal triggering adaptive control system procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Formal Methods Capability Acquisition | Absorbing Coq and Isabelle verification specialists compresses DO-178C compliance timelines for EASA deadlines. |
| Radiation-Hardened Supply Securement | Captive semiconductor fabrication in New Mexico insulates Pentagon programs from single-foundry concentration risk. |
| Urban Air Mobility Stack Certification | Hybrid onboard-ground architectures for German eVTOL developers open subscription revenue before 2030 EASA mandates. |
| Predictive Maintenance Platform Launch | Flight-hour-linked software subscriptions with Lufthansa and Delta concentrate recurring revenue outside hardware cycles. |
| India Defense Joint Venture Formation | HAL and DRDO partnerships satisfy localization rules while accessing Bangalore engineering cost advantages. |
Research Methodology
Bottom-up airline fleet retrofit modeling reconciled against top-down defense procurement tracking forms the analytical core, combining primary interviews with avionics engineering directors, EASA certification specialists, airline fleet procurement managers, and urban air mobility CTOs with secondary validation from FAA certification databases, EASA ED-12C guidance publications, Pentagon budget justification documents, and customs records for radiation-hardened semiconductor trade flows.
Historical trendline analysis of DO-178C program timelines and flight management system replacement cycles informs projection frameworks across deployment type, solution offering, and customer role segmentation dimensions, with CAGRs derived from regression against narrowbody delivery schedules and regulatory deadline compression effects.
Underlying measurement precision varies by segment; Flight Management System and Autopilot modules carry tighter precision than Safety Monitoring and Communication Interface categories due to mandatory retrofit reporting requirements. Forecasts reflect assumptions on EASA regulatory pathway timing and FAA machine learning guidance publication. A small set of regulatory trigger events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market