
 Global Aircraft Health Monitoring Market | 2026-2036
Global Aircraft Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Health Monitoring Market Intelligence
The scarcity of qualified data scientists with aerospace domain expertise is unwinding traditional maintenance workflows, forcing a shift toward automated analytics platforms. Safran Group leverages its deep engine manufacturing knowledge to integrate health monitoring at the design stage. Honeywell International Inc. specializes in avionics and software, offering comprehensive system packages. RTX Corporation competes on the strength of its Collins Aerospace and Pratt & Whitney divisions, providing integrated propulsion and airframe solutions.
Aircraft health monitoring comprises systems that use onboard sensors and data analytics to continuously assess the condition of critical components. These systems collect high-frequency data, such as vibration and thermal signatures, from engines and airframes. Condition monitoring software represents a high-margin segment, while predictive maintenance is the primary application driving technology adoption. Within technology, wireless sensor networks are gaining traction over traditional wired systems due to lower installation weight and complexity.
Regulatory bodies including the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) mandate stringent safety and maintenance protocols that necessitate advanced monitoring. These regulations define the required data logging and reporting standards, directly shaping system design and market access. Future competitive advantage will be determined by a vendor's ability to navigate complex data ownership agreements and address rising cybersecurity threats.
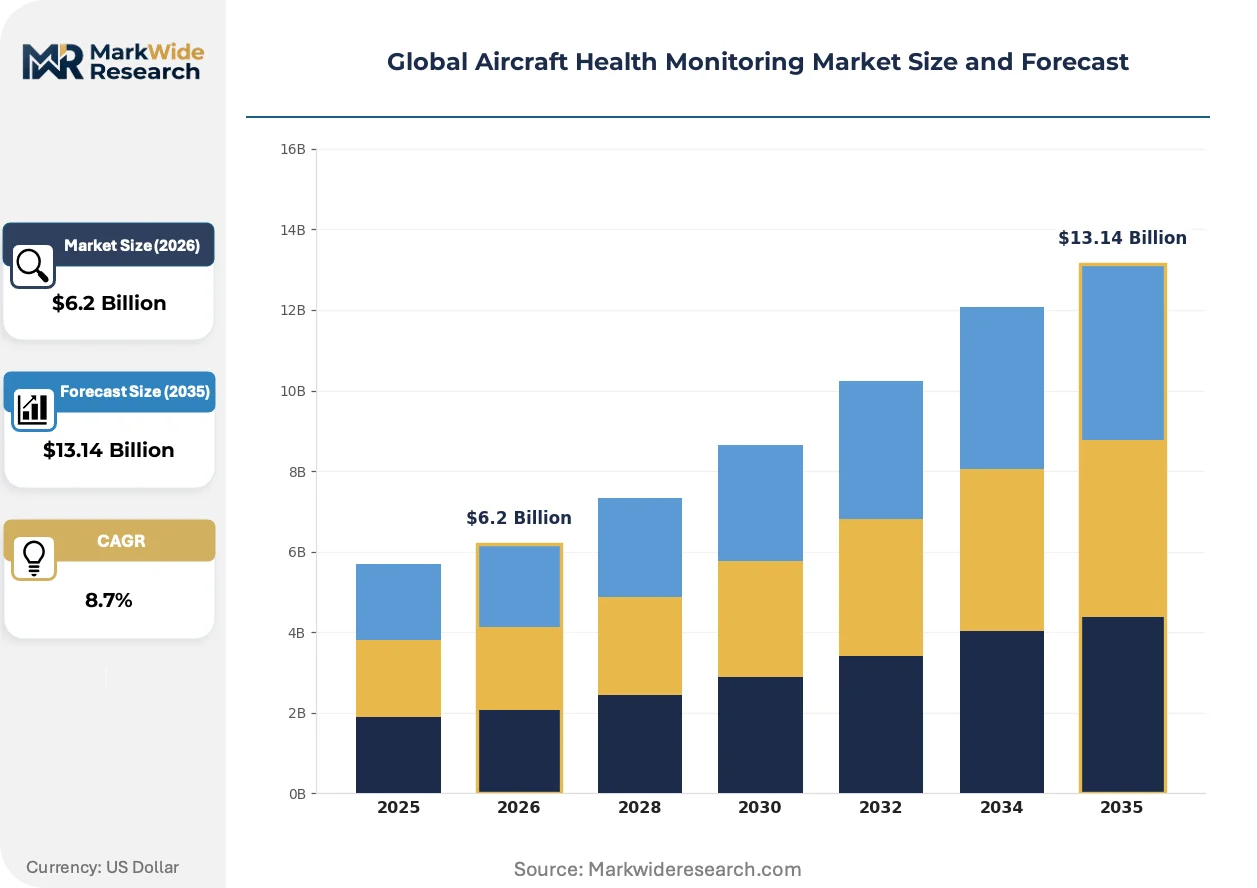
Market Dynamics
The aircraft health monitoring market is shaped by the transition from scheduled, time-based maintenance to condition-based and predictive upkeep. This structural shift is driven by regulatory pressure from bodies like the FAA and EASA for enhanced safety and operational efficiency.
Growth Catalysts
- Predictive Maintenance Mandates:New regulations from authorities including the US Federal Aviation Administration are compelling commercial airlines to adopt predictive technologies, directly stimulating demand for advanced monitoring systems to ensure compliance and improve safety.
- Wireless Sensor Networks:The adoption of wireless sensor technology is accelerating due to its lower installation weight and reduced complexity compared to traditional wired systems, making it an attractive option for both new aircraft and retrofits.
- Operational Efficiency Demands:Commercial airlines and cargo carriers are increasingly focused on maximizing aircraft utilization and minimizing unscheduled downtime, creating strong demand for health monitoring systems that enable proactive maintenance and optimized flight schedules.
Market Restraints
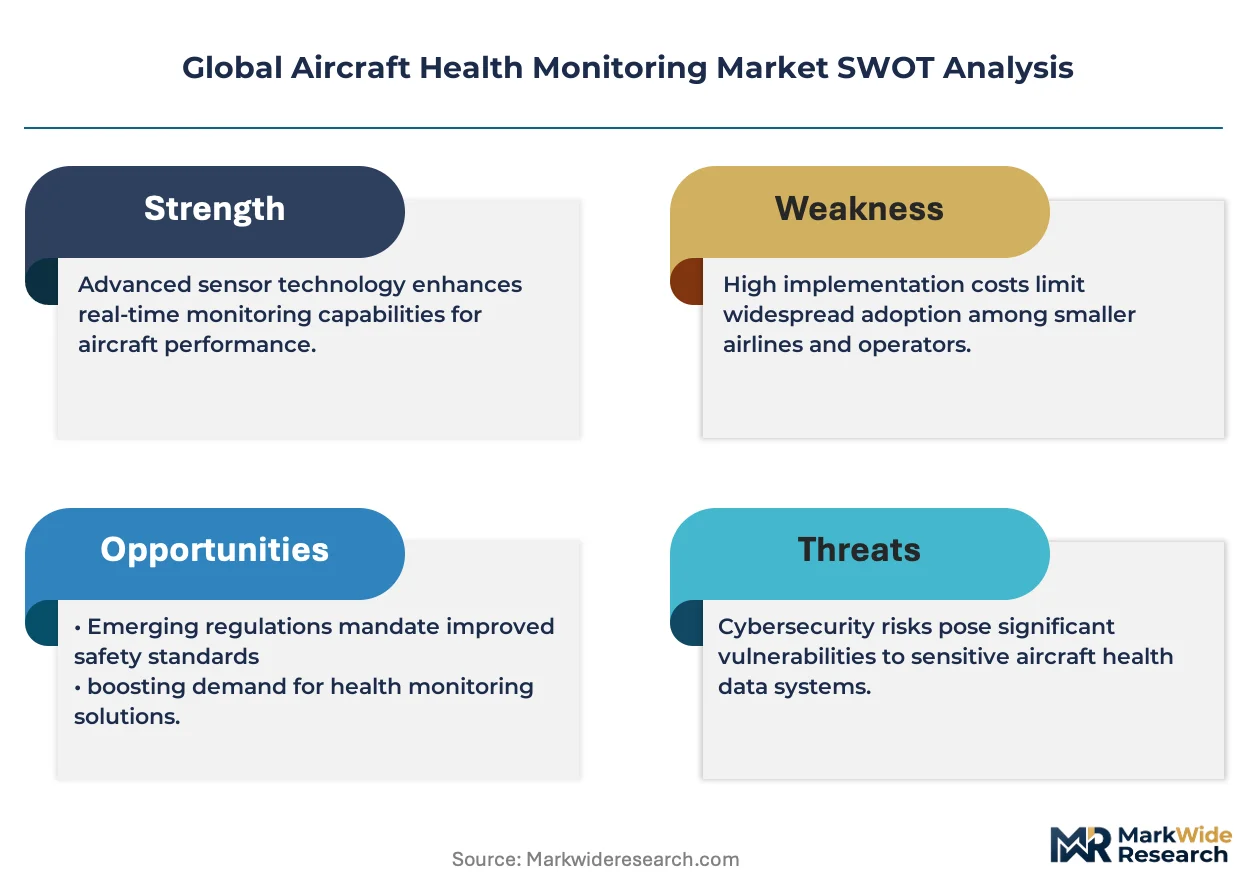
- High Retrofit Costs:The substantial capital investment required to retrofit older aircraft fleets with modern, integrated health monitoring systems presents a significant financial barrier, particularly for smaller airlines and operators in emerging markets.
- Data Ownership Complexity:Ambiguous and contested data ownership agreements between aircraft manufacturers, airlines, and MROs create legal and operational friction, limiting the ability to share and analyze fleet-wide data for maximum insight.
- Legacy System Integration:Integrating new sensor and software platforms with a diverse array of legacy avionics and ground-based IT systems on older aircraft is technically challenging, often leading to costly and prolonged implementation projects.
Strategic Opportunities
- Digital Twin Integration:The convergence of AHM data with digital twin technology creates an opportunity to build high-fidelity virtual models of specific aircraft, enabling more accurate failure prediction and maintenance simulation before physical work begins.
- Expansion into Secondary Systems:Extending monitoring capabilities beyond primary engines and airframes to ancillary systems such as landing gear, hydraulics, and environmental controls represents a significant area for market expansion and value creation.
- MRO Service Bundling in Asia:Maintenance Repair Organizations in rapidly growing aviation hubs like Singapore and Dubai can bundle advanced AHM analytics with their traditional repair services, offering a complete asset management solution to regional airlines.
Industry Challenges
- Aerospace Data Scientist Scarcity:A critical shortage of data scientists possessing the specialized domain expertise in aerospace engineering and flight dynamics constrains the development of sophisticated analytical models and limits the interpretation of monitoring data.
- Cybersecurity Vulnerabilities:The increased connectivity of modern aircraft for data transmission exposes AHM systems to growing cybersecurity threats, necessitating robust security protocols to protect critical flight and maintenance data from unauthorized access or manipulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Health Monitoring Market |
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $13.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Sensors, Data Acquisition Systems, Condition Monitoring Software, Diagnostic Tools, Communication Modules Technology: Wireless Sensor Networks, Vibration Analysis, Acoustic Emission, Infrared Thermography, Ultrasonic Testing Application: Flight Safety Management, Predictive Maintenance, Fuel Efficiency Optimization, Structural Health Monitoring, Engine Performance Assessment End User: Commercial Airlines, Aircraft Manufacturers, Maintenance Repair Organizations, Government Aviation Authorities, Private Jet Operators |
| Companies Covered | Airbus SE, Safran Group, Honeywell International Inc., Thales Group, Rolls-Royce Holdings PLC, The Boeing Company, General Electric Company, Meggitt PLC, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Health Monitoring Market Strategic Shifts & Innovations
The automation of analytics is a defining theme, as the scarcity of specialized data scientists pushes vendors toward developing platforms that can autonomously process sensor data. This trend is complemented by the integration of health monitoring capabilities earlier in the aircraft design lifecycle.
Wireless sensor networks provide a lightweight method for collecting high-frequency data, such as thermal signatures and vibration patterns, from critical airframe and engine components. Commercial airlines and MROs are adopting these systems for both line-fit on new aircraft and retrofits on existing fleets. The proliferation of these modular sensor systems is fragmenting the previously monolithic data acquisition architecture into a more distributed and flexible ecosystem.
European Union Aviation Safety Agency (EASA) rules are becoming more stringent, requiring more detailed data logging for predictive maintenance programs. This regulatory push forces air carriers to invest in AHM platforms capable of continuous condition analysis and secure data reporting. The commercial airline segment is most affected, now prioritizing vendors whose systems are pre-validated against evolving EASA and FAA standards for easier certification.
Airlines are increasingly procuring integrated health management services tied directly to operational outcomes like fleet availability rather than buying standalone hardware. This model disrupts traditional transactional sales, favoring vendors that offer subscription-based analytics and performance guarantees. This shift is most prominent among large fleet operators in North America and Europe who seek to align maintenance costs with operational performance.
Global Aircraft Health Monitoring Market Segmentation
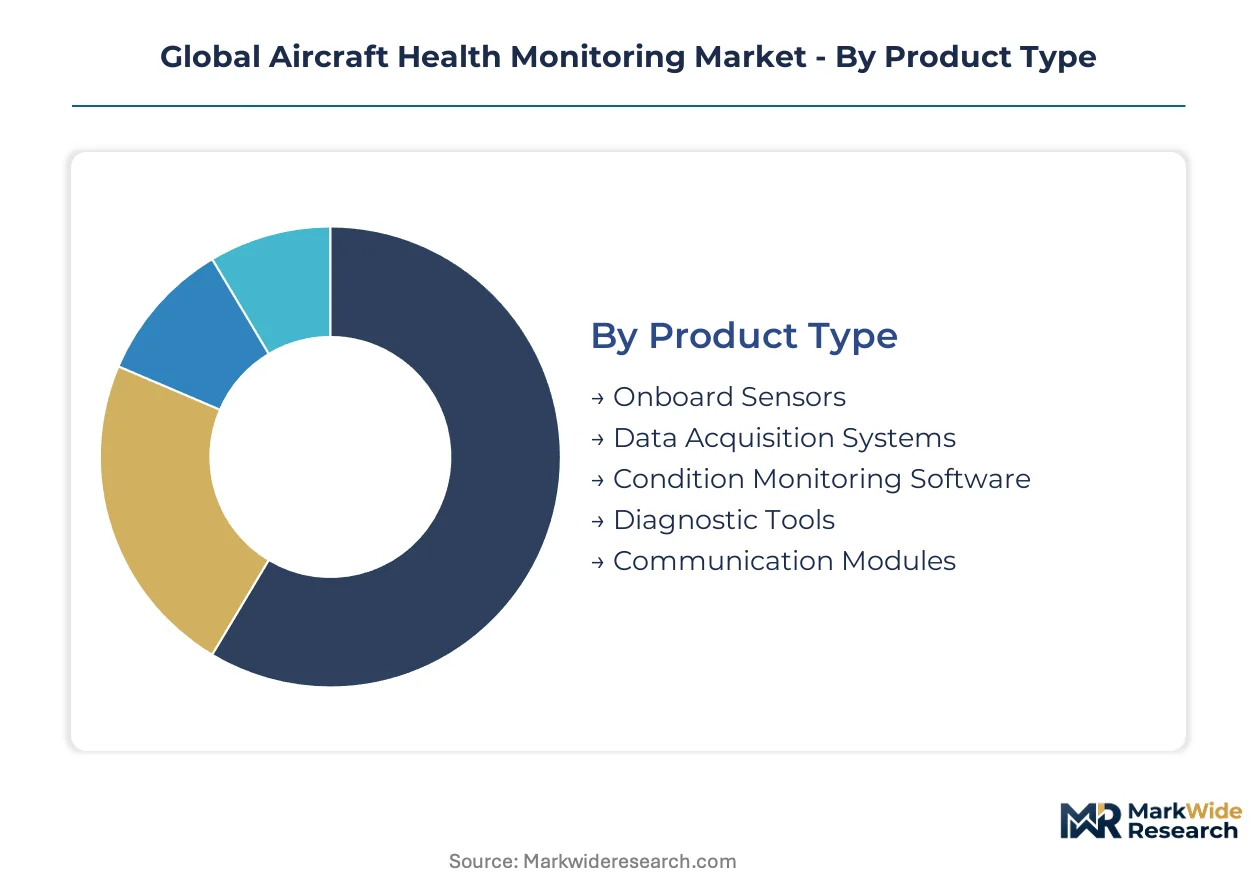
The aircraft health monitoring market is segmented to reveal distinct value propositions and demand patterns across its diverse ecosystem. Understanding these segments helps stakeholders identify areas of concentrated growth and strategic investment within the global aviation industry.
Product Type:
The product type segmentation highlights how different components contribute to the overall monitoring solution, with certain categories seeing stronger adoption in export-oriented markets due to integrated system requirements.
- Condition Monitoring Software:This segment includes advanced analytical platforms that process sensor data to assess component health, predict failures, and optimize maintenance schedules. Demand for these high-margin software solutions is concentrating in major aviation hubs like Singapore and Dubai, driven by complex fleet management needs.
- Onboard Sensors:These devices are integrated directly into aircraft components, collecting real-time data such as vibration, temperature, and pressure signatures. Commercial airlines globally are adopting these sensors for continuous data capture, enabling proactive maintenance and improved operational safety.
- Data Acquisition Systems:These systems gather, digitize, and transmit raw data from various onboard sensors to processing units.
- Diagnostic Tools:Specialized equipment and software used for in-depth analysis of identified anomalies and component failures.
- Communication Modules:Hardware and software components facilitating the secure and efficient transmission of monitoring data to ground-based systems.
Condition Monitoring Software holds the largest share; momentum sits with Onboard Sensors.
Technology:
Technology choices within aircraft health monitoring systems often reflect the specific application requirements, with some approaches better suited for airframe integrity while others focus on propulsion systems.
- Wireless Sensor Networks:These systems utilize interconnected, lightweight sensors that transmit data wirelessly, reducing installation complexity and weight compared to wired alternatives. Commercial airlines are increasingly deploying wireless networks for both new aircraft and retrofits, particularly for hard-to-reach airframe sections.
- Vibration Analysis:This technique monitors the vibrational patterns of rotating components like engines and gearboxes to detect imbalances, wear, or impending failures. Maintenance Repair Organizations in North America and Europe rely heavily on vibration analysis for engine health assessment and predictive maintenance.
- Acoustic Emission:This technology detects stress waves generated by material deformation or crack propagation, particularly useful for structural integrity monitoring.
- Infrared Thermography:Utilizes thermal imaging to identify hot spots or abnormal temperature distributions, indicating potential component overheating or electrical faults.
- Ultrasonic Testing:Employs high-frequency sound waves to detect internal flaws, cracks, or corrosion within materials without disassembly.
Wireless Sensor Networks exhibit the steepest expansion trajectory; Vibration Analysis maintains a substantial market presence.
Application:
The various applications of aircraft health monitoring directly address different operational priorities, with some focused on safety compliance and others on cost reduction for large fleet operators.
- Predictive Maintenance:This application leverages data analytics to forecast component failures and schedule maintenance proactively, minimizing unscheduled downtime and optimizing resource allocation. Commercial airlines globally prioritize predictive maintenance to meet stringent regulatory mandates from authorities like the FAA and EASA.
- Structural Health Monitoring:These systems continuously assess the integrity of the airframe, detecting fatigue, corrosion, or damage before they become critical. Aircraft manufacturers integrate structural health monitoring during the design phase to enhance aircraft safety and extend operational life.
- Flight Safety Management:Integrates AHM data to provide real-time insights into aircraft condition, supporting pilots and ground crews in ensuring safe operations.
- Fuel Efficiency Optimization:Analyzes engine and airframe performance data to suggest operational adjustments that reduce fuel consumption.
- Engine Performance Assessment:Monitors key engine parameters to evaluate operational efficiency, identify deviations, and optimize maintenance intervals.
Predictive Maintenance commands the largest segment revenue; Structural Health Monitoring is rapidly gaining share.
End User:
The end-user landscape for aircraft health monitoring reflects varied needs, with established players driving demand for comprehensive solutions while newer entrants focus on specialized applications.
- Commercial Airlines:These operators utilize AHM systems to enhance operational efficiency, reduce maintenance costs, and comply with regulatory requirements for their large fleets. Airlines in Europe and North America are increasingly procuring integrated health management services tied to operational outcomes.
- Maintenance Repair Organizations:MROs integrate AHM data and analytics into their service offerings, providing comprehensive asset management solutions to their clients. Demand is concentrating among MROs in major aviation centers such as Atlanta and Dubai.
- Aircraft Manufacturers:OEMs integrate health monitoring capabilities at the design stage, offering built-in systems for new aircraft.
- Government Aviation Authorities:These bodies use AHM data for regulatory oversight, accident investigation, and defining safety and maintenance protocols.
- Private Jet Operators:Smaller fleets utilize AHM to ensure reliability and minimize downtime for high-value private aircraft.
Commercial Airlines account for the majority of demand; Maintenance Repair Organizations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Federal Aviation Administration (FAA) anchors global demand for aircraft health monitoring, driving compliance and technological adoption. Its stringent safety mandates compel commercial airlines to invest in advanced predictive maintenance systems. This regulatory influence extends beyond US borders, shaping international aviation standards and market requirements.
United States
Demand for AHM systems in the United States stems from commercial airlines seeking operational efficiency and compliance with FAA mandates. The FAA's push for predictive maintenance drives investment in advanced monitoring technologies. Major aviation clusters in Atlanta and Seattle concentrate MRO activities and OEM development.
France
European Union Aviation Safety Agency (EASA) regulations significantly influence the French aircraft health monitoring market, particularly for Airbus and its supply chain. EASA's detailed data logging requirements necessitate sophisticated AHM platforms for continuous condition analysis. Toulouse serves as a major aerospace hub, fostering innovation in integrated health management solutions.
Singapore
Singapore's strategic position as an aviation hub drives strong demand for AHM, particularly from Maintenance Repair Organizations. The Civil Aviation Authority of Singapore (CAAS) supports advanced MRO capabilities through various initiatives. Changi Airport's ecosystem facilitates extensive AHM analytics and service bundling for regional airlines.
United Arab Emirates
Commercial airlines in the United Arab Emirates are adopting AHM to maximize fleet utilization and minimize unscheduled downtime. The General Civil Aviation Authority (GCAA) implements strict safety and maintenance protocols, stimulating AHM system integration. Dubai's expanding aviation sector, including major MRO facilities, attracts significant investment in health monitoring technologies.
Germany
German aerospace manufacturers and airlines prioritize AHM for enhanced safety and compliance with EASA standards. The German Federal Aviation Office (LBA) oversees aviation safety, promoting the integration of advanced monitoring systems. Hamburg's strong aerospace industry, particularly in aircraft manufacturing and maintenance, fosters AHM system development.
Global Aircraft Health Monitoring Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the aircraft health monitoring market, creating a dynamic competitive environment. The market exhibits a tiered structure, with established aerospace giants competing alongside specialized software and sensor providers. Three strategic archetypes include integrated system providers offering comprehensive solutions, component specialists focusing on specific hardware innovation, and pure-play data analytics platforms. Strategic partnerships for technology co-development and portfolio diversification into new monitoring areas are dominant competitive moves among these diverse players.
Integrated system providers such as Honeywell International Inc. exemplify comprehensive avionics and software offerings, catering to broad market needs. Safran Group, with its deep engine manufacturing knowledge, represents a component specialist integrating health monitoring at the design stage, particularly for propulsion systems. RTX Corporation, through its Collins Aerospace and Pratt & Whitney divisions, occupies a position as a major provider of integrated propulsion and airframe solutions, anchoring a significant portion of the market. These entities leverage their extensive aerospace expertise to deliver advanced monitoring capabilities.
| Leading Market Players |
|---|
| Airbus SE |
| Safran Group |
| Honeywell International Inc. |
| Thales Group |
| Rolls-Royce Holdings PLC |
| The Boeing Company |
| General Electric Company |
| Meggitt PLC |
| RTX Corporation |
Cost & Logistics Intelligence
Extended lead times for highly specialized onboard sensors and condition monitoring software shape pricing power for integrated system providers. This reflects a supply chain concentrated in technologically advanced manufacturing hubs.
Pricing Analysis
Geographic pricing variations exist, with higher costs in regions like Europe and North America reflecting stringent certification requirements. The dominant pricing model is subscription-based analytics for software and project-based for system integration. Customization level and after-sales service drive price differentiation. Pricing softness stems from increased competition among software providers; commercial airlines are highly price-sensitive, while aircraft manufacturers prioritize integrated system performance.
Supply Chain Analysis
The United States and Germany concentrate the production of advanced avionics and sensor components for aircraft health monitoring. Raw material dependencies include specialized semiconductors and high-performance alloys for sensor manufacturing. Single-source vulnerability for proprietary software algorithms presents a structural risk. Distribution runs through direct sales channels to aircraft manufacturers and MROs, with third-party integrators serving retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft health monitoring market functions as a defensive-moat story. High switching costs, driven by deep integration with critical aircraft systems and stringent regulatory validation, protect established providers from disruptive entry.
For Market Incumbents:Shield core market share by deepening vertical integration into data analytics platforms. This counters the threat from specialized software providers and leverages existing customer relationships. Invest in advanced cybersecurity protocols to protect sensitive flight data, a key lever against emerging vulnerabilities. Expand certification investments to meet evolving EASA and FAA standards.
For New Entrants and Emerging Players:Unserved demand for real-time monitoring of secondary aircraft systems, such as landing gear and hydraulics, offers a clear market entry point. Target Maintenance Repair Organizations in rapidly expanding Asian aviation hubs like Singapore. Develop AI-driven predictive models for specific component failures, providing a focused go-to-market angle. Offer flexible, outcome-based subscription models to attract smaller fleet operators.
For Investors and Strategic Acquirers:Long-term, this sits as a mission-critical infrastructure play because of aviation's non-negotiable safety requirements and continuous operational efficiency demands. Seek out data analytics specialists with deep aerospace domain expertise as acquisition targets. The signal to watch is the increasing share of condition monitoring software revenue tied to performance-based contracts, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI/ML for Anomaly Detection | This enhances predictive maintenance accuracy for commercial airlines, reducing unscheduled downtime. |
| Expand Cybersecurity for Data Platforms | Robust security protocols protect critical flight data from manipulation, addressing regulatory concerns. |
| Develop Wireless Sensor Miniaturization | Smaller, lighter sensors enable broader deployment across airframe sections, reducing installation complexity. |
| Form Partnerships with MROs in Asia | Collaborations with Maintenance Repair Organizations in Dubai expand service bundling capabilities for regional fleets. |
| Invest in Digital Twin Technology | High-fidelity virtual models improve failure prediction and maintenance simulation for aircraft manufacturers. |
Research Approach
Operator-level perspectives from MRO directors, airline fleet managers, OEM design engineers, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with validation against secondary sources like FAA advisories, EASA reports, and company SEC filings. This approach ensured robust bottom-up and top-down triangulation of market dynamics and forecasts.
Sensitivity analysis informed the development of the quantitative forecast model across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected adoption rates. Key forecast inputs included aircraft fleet expansion plans and predictive maintenance mandate timelines.
Forecasts assume regulatory continuity in FAA and EASA regimes; material policy shifts would require re-modeling. Geopolitical events affecting air travel or significant technological breakthroughs represent risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market