
 Aviation Test Equipment Market | 2026-2036
Aviation Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Test Equipment Market Intelligence
The divergence in R&D investment between integrated systems providers and niche component specialists is redrawing the competitive landscape. Large players like Honeywell International leverage their extensive portfolio to serve major airlines and defense contractors. In contrast, Keysight Technologies specializes in high-frequency test systems for advanced communications. Rohde & Schwarz differentiates with its electromagnetic compatibility (EMC) testing solutions for new aircraft platforms.
Aviation test equipment includes specialized hardware and software used to verify the performance and safety of aircraft components and systems. These tools perform functions like digital signal processing to validate modern avionics and ensure airworthiness. Avionics Test Systems and Engine Diagnostic Tools are critical product segments, with demand driven by Maintenance Repair Organizations. The application of this equipment in maintenance diagnostics and system integration ensures operational readiness.
Regulatory frameworks established by the Federal Aviation Administration (FAA) in the United States and the European Union Aviation Safety Agency (EASA) mandate rigorous testing protocols. These regulations directly influence equipment design, calibration standards under ISO/IEC 17025, and market access for new testing technologies. Vendors must now decide whether to specialize in testing for sustainable aviation fuels and electric propulsion or focus on legacy fleet support.
Market Dynamics
The proliferation of next-generation aircraft platforms and stringent airworthiness directives from the FAA and EASA are the central forces shaping the market. This dual pressure necessitates a complete refresh cycle, rendering much of the legacy test equipment obsolete for modern avionics and propulsion systems.
Growth Catalysts
- Next-Generation Avionics:The transition to integrated modular avionics in new aircraft platforms from manufacturers in the United States and France requires test equipment with advanced digital signal processing capabilities.
- Airworthiness Directives:New FAA and EASA regulations targeting the verification of flight-critical software and hardware systems are forcing Maintenance Repair Organizations to upgrade their test benches and calibration protocols.
- MRO Expansion in Asia:The rapid growth of commercial airline fleets in China and India is creating a surge in demand for engine diagnostic tools and avionics test systems to support new MRO facilities.
Market Restraints
- High Capital Investment:The significant upfront cost of acquiring and calibrating test equipment to meet stringent standards like ISO/IEC 17025 acts as a major barrier for smaller MROs and new market entrants.
- Long Development Cycles:The extensive time required for designing, validating, and certifying new test equipment for novel aircraft platforms, such as those with electric propulsion, slows market responsiveness to new technologies.
- Proprietary System Interfaces:Aircraft manufacturers often use proprietary data buses and software protocols, forcing test equipment vendors to engage in costly and complex reverse-engineering or licensing agreements to ensure compatibility.
Strategic Opportunities
- Electric and Hybrid Propulsion:The aviation industry's shift towards electric aircraft creates a new market for specialized test equipment designed to validate battery management systems, high-voltage power electronics, and electric motor performance.
- Sustainable Aviation Fuels (SAF):Testing and certification of engine performance and material compatibility with various SAF blends present an opportunity for vendors to develop new analytical and diagnostic tools for fuel systems.
- Digital Twin Integration:There is a significant opportunity to develop test equipment that integrates with aircraft digital twins, enabling predictive maintenance, virtual testing, and lifecycle simulation for MROs and OEMs.
Industry Challenges
- Skilled Workforce Scarcity:A critical shortage of technicians and engineers proficient in both RF engineering and complex software for modern avionics test systems constrains the ability of MROs to deploy new equipment effectively.
- Legacy System Interoperability:Ensuring that new test equipment is backward-compatible with the diverse and aging aircraft fleets still in service presents a significant and costly engineering challenge for equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Test Equipment Market |
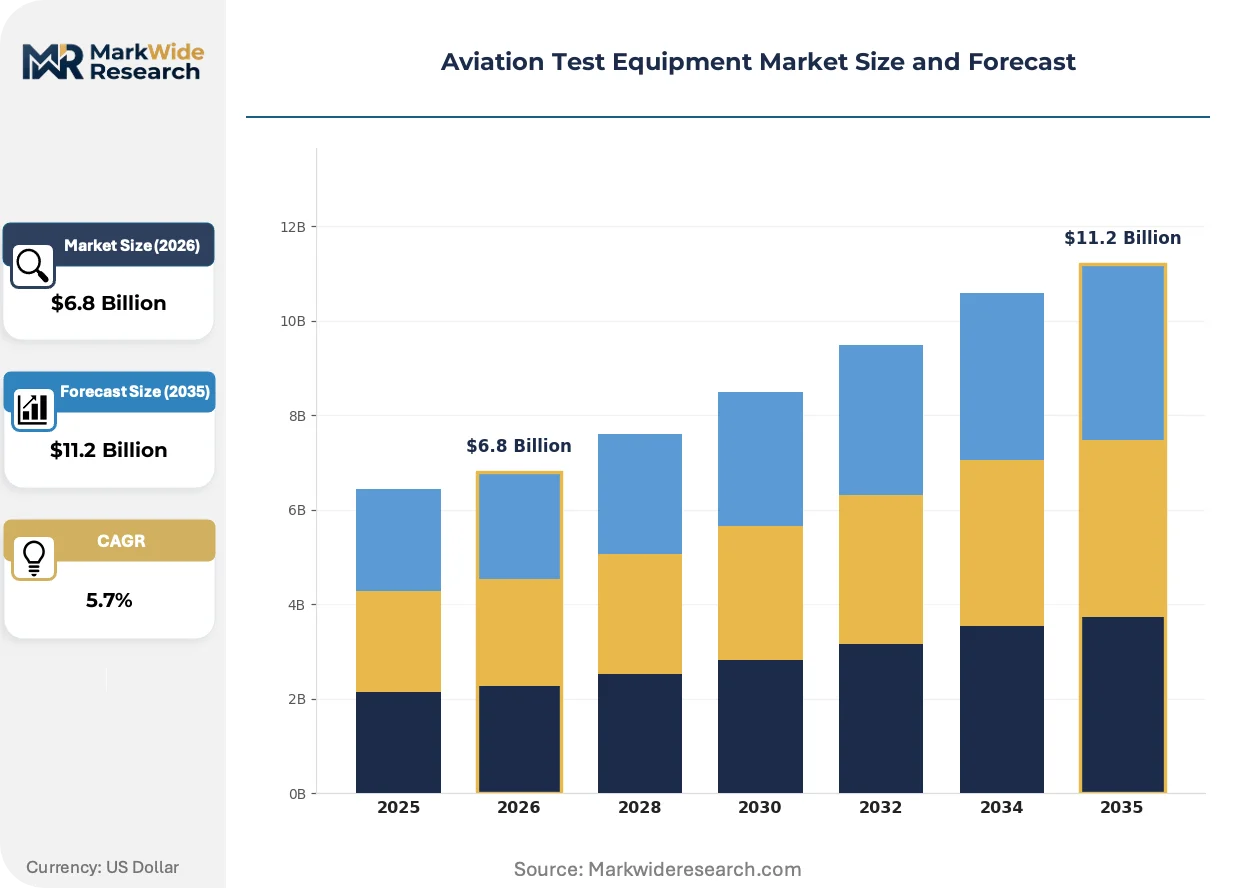
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Support Equipment, Avionics Test Systems, Engine Diagnostic Tools, Structural Integrity Analyzers, Flight Control Testers Technology: Wireless Communication, Optical Inspection, Digital Signal Processing, Vibration Analysis, Electromagnetic Compatibility Application: Component Testing, System Integration, Maintenance Diagnostics, Quality Assurance, Calibration Services End User: Aircraft Manufacturers, Maintenance Repair Organizations, Certification Bodies, Airlines, Defense Contractors |
| Companies Covered | Honeywell International, ATEQ Aviation, Keysight Technologies, Laversab, Tel-Instrument Electronics Corp., Rohde & Schwarz, Teradyne, Moog, VIAVI Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Test Equipment Market Strategic Shifts & Innovations
A fundamental shift from fixed-function, hardware-centric test equipment to software-defined, modular platforms is reconfiguring the market. This evolution prioritizes adaptability and future-proofing to manage the rapid pace of avionics and propulsion system innovation.
Portable test instruments built on field-programmable gate array (FPGA) technology provide reconfigurable hardware for real-time signal analysis. MRO line maintenance crews and field service engineers are the primary adopters, seeking to reduce aircraft-on-ground time. This technology is miniaturizing the traditional test bench, moving complex diagnostic capabilities directly to the flight line.
Cybersecurity mandates from the FAA and EASA for connected aircraft systems are now a primary design driver. These regulations compel the development of test equipment capable of simulating cyber threats and validating the security of avionics data buses. Avionics manufacturers and MROs are most affected, now required to integrate penetration testing and vulnerability analysis into their certification workflows.
Buyers are increasingly shifting from capital expenditure to operational expenditure models for test equipment procurement. This preference for leasing or subscription-based access disrupts the traditional outright purchase model, forcing vendors to develop service-oriented offerings. The trend is most pronounced in North America and Europe, where large MROs use it to manage technology obsolescence.
Aviation Test Equipment Market Segmentation
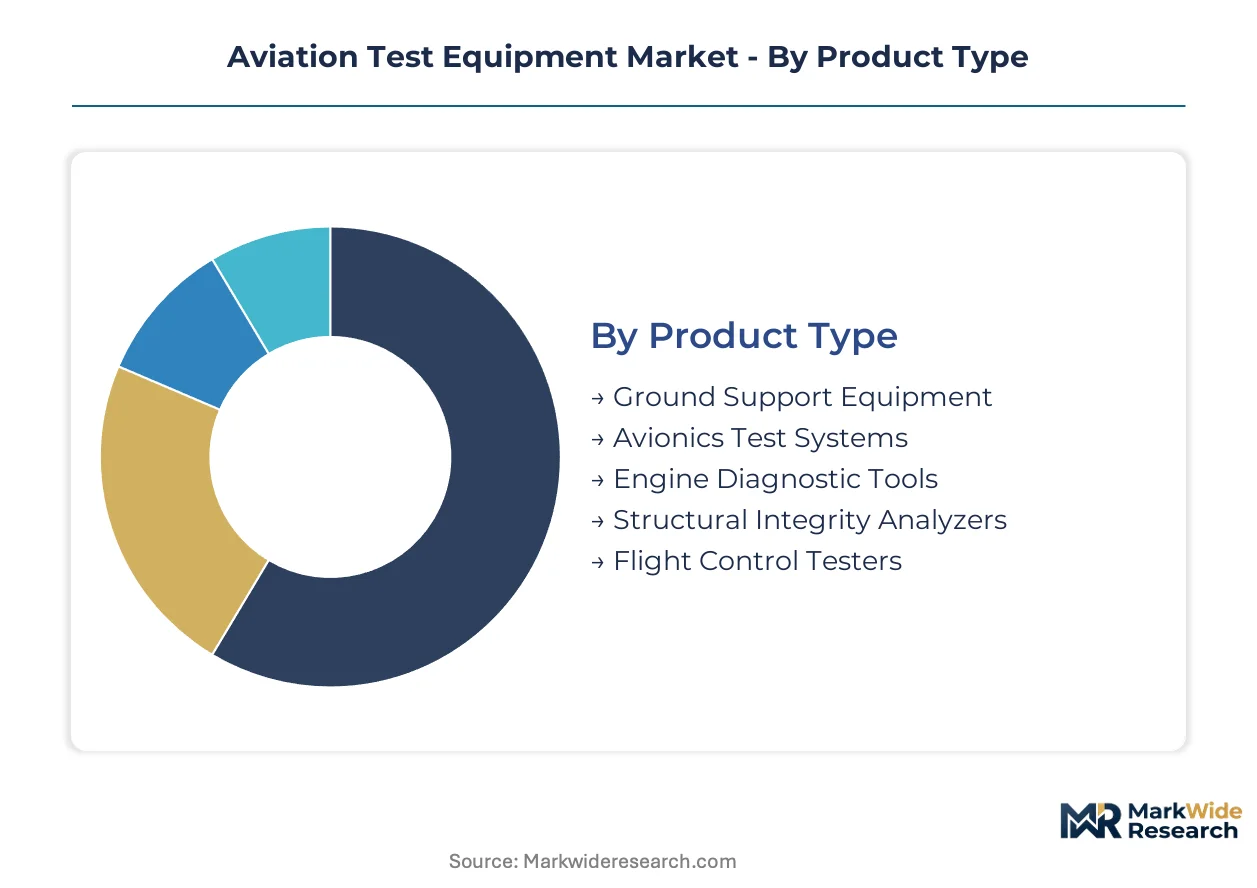
Segmentation within the aviation test equipment market provides a granular view of specialized needs across the aerospace ecosystem. Understanding these distinct segments helps manufacturers align product development with precise operational requirements, ensuring compliance with stringent airworthiness standards.
Product Type:
The distribution channels for aviation test equipment vary significantly by product type, reflecting specialized procurement paths and deployment strategies for different operational needs.
- Avionics Test Systems:These systems perform digital signal processing and software validation for integrated modular avionics. Demand concentrates in established aerospace manufacturing hubs like the United States and France, driven by FAA and EASA directives for next-generation aircraft.
- Engine Diagnostic Tools:Equipment in this segment analyzes engine performance, material compatibility with new fuels, and overall health. Rapid expansion of commercial airline fleets in China and India creates surge demand for these tools in new MRO facilities.
- Ground Support Equipment:This category includes a range of tools for pre-flight checks, routine maintenance, and aircraft movement on the ground.
- Structural Integrity Analyzers:These specialized instruments detect fatigue, corrosion, and other material defects in airframe components.
- Flight Control Testers:This equipment verifies the functionality and responsiveness of an aircraft's primary and secondary flight control surfaces.
Ground Support Equipment dominates the installed base for routine operations. Engine Diagnostic Tools is where expansion concentrates with new propulsion systems.
Technology:
The technological underpinnings of aviation test equipment directly influence its application scope across the maintenance and manufacturing lifecycle, from design validation to in-service diagnostics.
- Digital Signal Processing:This technology analyzes complex electronic signals to validate the performance of modern avionics and flight-critical software. It is crucial for next-generation integrated modular avionics systems, mandated by FAA and EASA regulations.
- Electromagnetic Compatibility:EMC testing solutions ensure aircraft systems operate without interference, validating platform resilience to external electromagnetic environments. New aircraft platforms require rigorous EMC testing, driven by increasing connectivity and cybersecurity mandates from EASA and the FAA.
- Wireless Communication:This technology facilitates data transfer and remote control for test equipment, enhancing flexibility for line maintenance crews.
- Optical Inspection:Optical tools provide high-resolution visual analysis for internal components and surface integrity, particularly in engine and airframe structures.
- Vibration Analysis:This technology identifies imbalances and wear in rotating components like engines and propellers, preventing mechanical failures.
Digital Signal Processing capabilities are fundamental to modern test benches. Electromagnetic Compatibility solutions are gaining share fastest for new aircraft certification.
Application:
The cost structure for aviation test equipment varies by application, reflecting the complexity and criticality of the testing function required for airworthiness and operational safety.
- Maintenance Diagnostics:This application involves troubleshooting, fault isolation, and performance verification during routine and unscheduled maintenance events. MROs and airlines heavily invest in these tools to reduce aircraft-on-ground time and implement predictive maintenance strategies.
- System Integration:This application verifies the compatibility and holistic performance of multiple aircraft systems working together. Aircraft manufacturers and defense contractors rely on system integration testing for complex new platforms and digital twin validation.
- Component Testing:This involves individual verification of parts like sensors, actuators, and circuit boards before assembly or during repair.
- Quality Assurance:This application ensures that manufacturing processes and repaired components meet design specifications and regulatory standards.
- Calibration Services:These services maintain the accuracy and reliability of test equipment itself, ensuring compliance with ISO/IEC 17025 standards.
Maintenance Diagnostics represents the largest volume of daily test operations. System Integration is critical for the introduction of new aircraft models.
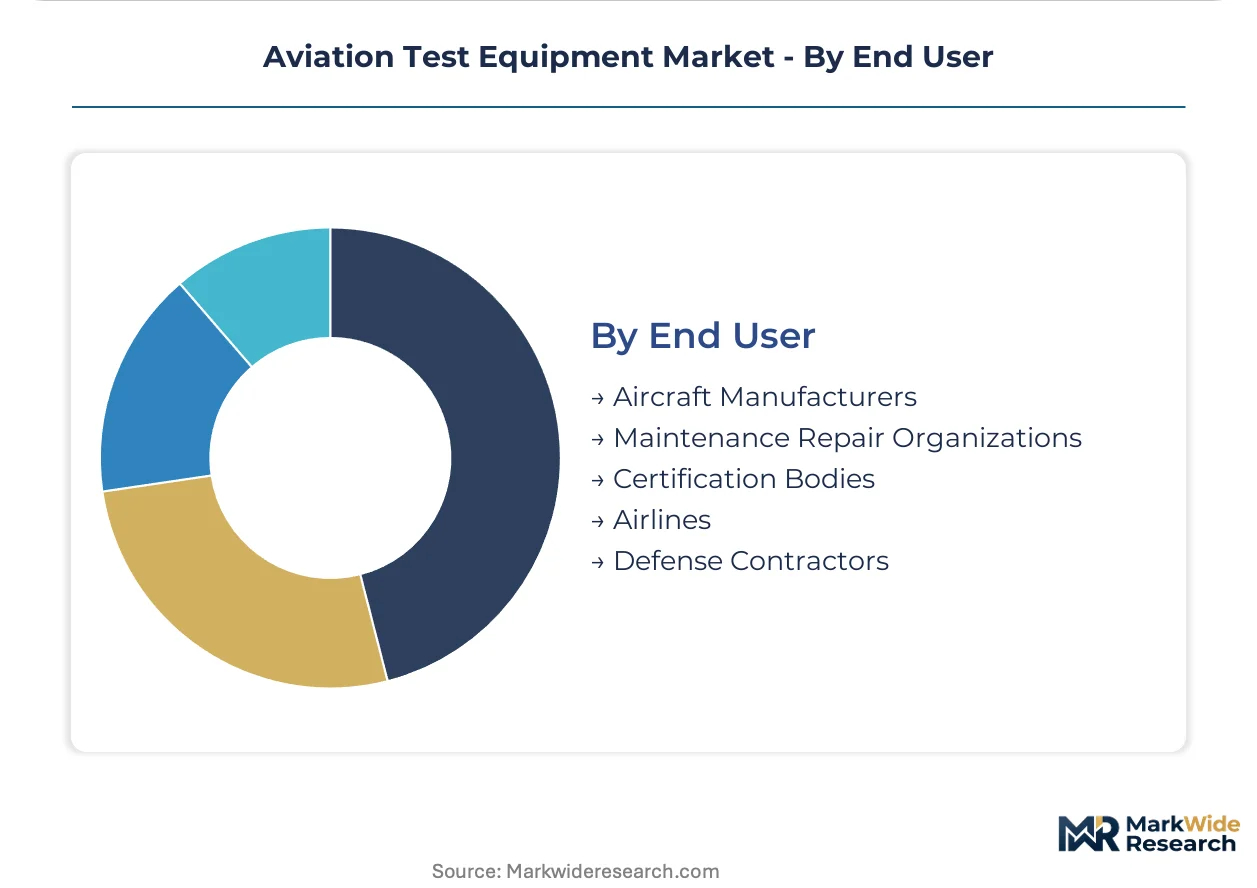
End User:
The volume of aviation test equipment procurement is heavily influenced by the specific needs and operational scale of each end-user segment within the aerospace industry.
- Maintenance Repair Organizations:MROs require a broad range of test equipment to ensure the airworthiness and operational readiness of commercial and defense aircraft fleets. Expanding MRO facilities in Asia, driven by FAA and EASA airworthiness directives, significantly contribute to demand.
- Aircraft Manufacturers:These entities use test equipment for validating new aircraft designs, certifying components, and ensuring compliance with regulatory bodies like the FAA. Long development cycles and proprietary system interfaces pose unique challenges for these users.
- Certification Bodies:These organizations utilize specialized equipment to verify compliance with aviation regulations and safety standards for new aircraft and components.
- Airlines:Airlines rely on test equipment for line maintenance and ensuring the safety and operational efficiency of their active fleets.
- Defense Contractors:These users require highly specialized and often custom test solutions for military aircraft, drones, and advanced aerospace systems.
Maintenance Repair Organizations drive the largest segment of recurring equipment demand. Defense Contractors require highly specialized and secure testing solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced aviation test equipment remains concentrated in established markets like the United States, while emerging regions such as China are driving volume-based procurement. This dynamic reflects differing investment priorities and regulatory landscapes across continents. Established aerospace manufacturing hubs continue to lead in innovation for next-generation systems.
United States
The United States market experiences strong demand for next-generation avionics test equipment. FAA directives mandate rigorous verification of flight-critical software and hardware systems. Aerospace manufacturing hubs in cities like Seattle and Wichita continuously integrate advanced testing capabilities.
France
French aerospace manufacturers require sophisticated test solutions for integrated modular avionics. EASA regulations drive compliance for new aircraft platforms and component certification. Toulouse, a major aerospace center, focuses on validating cutting-edge propulsion systems.
China
China's expanding commercial airline fleets generate significant demand for engine diagnostic tools. The Civil Aviation Administration of China (CAAC) supports the development of new MRO facilities. Major aviation hubs such as Shanghai and Beijing are rapidly expanding their testing infrastructure.
India
India's burgeoning MRO sector requires substantial investments in avionics test systems. The Directorate General of Civil Aviation (DGCA) enforces airworthiness directives for modern aircraft. Hyderabad and Bengaluru serve as key centers for new maintenance and testing operations.
Germany
Germany exhibits robust demand for electromagnetic compatibility (EMC) testing solutions. EASA mandates stringent EMC validation for new aircraft platforms. Munich and Hamburg are central to advanced aerospace research and specialized test equipment development.
Aviation Test Equipment Market Key Industry Players
Concentration sits with integrated systems providers offering broad portfolios for major airlines and defense contractors. The competitive landscape features a blend of these large, diversified players and specialized niche component vendors. These integrated providers often leverage extensive R&D investments to maintain their market position. Companies engage in strategic partnerships and portfolio diversification to serve evolving customer needs across the aerospace ecosystem.
Within the integrated systems provider archetype, Honeywell International offers extensive portfolios, serving as a comprehensive solutions provider for major airlines and defense contractors globally. Keysight Technologies, a US-based company, represents specialists in high-frequency test systems, anchoring advanced communications validation for complex avionics architectures. This positioning addresses the intricate demands of modern aircraft systems. Rohde & Schwarz GmbH, a German entity, exemplifies differentiation with its electromagnetic compatibility (EMC) testing solutions, crucial for certifying new aircraft platforms against stringent interference mandates from regulators like EASA.
| Leading Market Players |
|---|
| Honeywell International |
| ATEQ Aviation |
| Keysight Technologies |
| Laversab |
| Tel-Instrument Electronics Corp. |
| Rohde & Schwarz |
| Teradyne |
| Moog |
| VIAVI Solutions |
| Others |
Cost & Logistics Intelligence
The transition from fixed-function hardware to software-defined modular platforms is reshaping both the supply geography and pricing economics of aviation test equipment. This shift moves production from traditional component manufacturing to specialized software development, enabling operational expenditure models.
Pricing Analysis
Configured-to-order pricing for specialized avionics test systems commands a premium over standardized ground support equipment. The dominant pricing structure blends project-based contracts for complex system integration with subscription-based access for software-defined platforms. Price differentiation stems from certification levels, such as ISO/IEC 17025 compliance, and the degree of customization for proprietary aircraft interfaces. Pricing softness reflects the increasing buyer preference for operational expenditure models, with smaller MROs exhibiting higher price sensitivity than major aircraft manufacturers.
Supply Chain Analysis
The United States produces advanced avionics test systems and specialized digital signal processing hardware, while Germany supplies electromagnetic compatibility components. Raw material dependencies include high-frequency semiconductor components and embedded software modules. Single-source vulnerability for proprietary aircraft interfaces poses a structural risk for equipment manufacturers. Distribution runs through direct sales channels to aircraft manufacturers and major MROs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aviation test equipment market now exhibits a shift in buyer power, driven by the rapid expansion and consolidation of Maintenance Repair Organizations in Asia. These large MRO facilities influence procurement terms for new avionics and engine diagnostic tools.
For Market Incumbents:Secure long-term service contracts for software-defined test platforms to counter obsolescence risks from new technologies. Invest heavily in R&D for sustainable aviation fuels and electric propulsion testing solutions, leveraging existing customer relationships. This proactive approach mitigates the threat of specialized component vendors capturing emerging market segments. Expanding calibration service capabilities under ISO/IEC 17025 acts as a crucial lever for customer retention.
For New Entrants and Emerging Players:Anchor in underserved niches such as portable FPGA-based test instruments for line maintenance or dedicated cybersecurity testing solutions. The most penetrable segment remains smaller MROs seeking cost-effective, adaptable equipment for modern avionics. Focus on offering subscription-based access models for specialized diagnostic software. This go-to-market angle reduces capital expenditure barriers for new market participants.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with private equity-backed niche component specialists possessing unique software IP or advanced calibration capabilities. The long-term viability of this market remains strong, driven by continuous airworthiness directives and aircraft fleet expansion. Target acquisition archetypes include firms specializing in digital twin integration or high-frequency test systems. Increased operational expenditure spending by MROs on software licenses serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Development | This initiative future-proofs equipment against rapid avionics innovation for major aircraft manufacturers. |
| Electric Propulsion Test System R&D | Developing these tools addresses the emerging market for validating battery management systems in new aircraft. |
| Cybersecurity Testing Integration | This move aligns with new FAA and EASA mandates for connected aircraft system security validation. |
| Subscription Service Model Expansion | Offering OpEx-based access meets evolving procurement preferences from large MROs in Europe. |
| ISO/IEC 17025 Calibration Network Growth | Expanding calibration services ensures compliance and reliability for critical avionics test systems. |
Research Approach
A standing panel of avionics engineers, MRO procurement managers, and regulatory compliance officers provided ongoing calibration for market assumptions. Primary interviews with these industry stakeholders combined with secondary validation from FAA directives, EASA regulations, and aerospace industry reports. This approach utilized both bottom-up market sizing and top-down industry trend analysis.
Outputs were rigorously validated against external benchmarks, including published aerospace forecasts and MRO investment trends across the analysis window. The analytical framework integrated quantitative modeling across product type, technology, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected technological adoption. Aircraft fleet growth rates and MRO facility expansion plans served as key inputs.
Decision-makers should treat outputs as directional under current regulatory trajectories and technological development roadmaps; material deviation would warrant model refresh. Forecasts reflect assumptions regarding geopolitical stability and MRO investment patterns, with unexpected shifts in airworthiness directives representing specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market