
 Flight Data Monitoring Market | 2026-2036
Flight Data Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Data Monitoring Market Intelligence
Subscription-based software platforms for data analysis are expanding the addressable market beyond simple hardware sales. Safran SA leverages its deep aerospace integration to offer bundled hardware and analytics solutions. Honeywell International Inc. competes on the strength of its comprehensive avionics and connectivity portfolio. Meanwhile, Collins Aerospace differentiates through its advanced data link and ground support systems, securing its position with major airframers and airlines.
Flight data monitoring involves the routine collection and analysis of digital flight data to enhance operational safety. These systems process information from sources like Quick Access Recorders (QARs), capturing hundreds of parameters per flight second. The primary purpose is to identify operational risks, improve pilot training, and optimize aircraft performance. While flight safety applications remain the foundational driver, demand for predictive maintenance solutions represents the fastest-growing segment. Airlines constitute the largest end-user base, but military aviation is adopting these systems for fleet readiness and mission analysis.
Regulatory frameworks from the FAA in the United States and EASA across Europe mandate Flight Operations Quality Assurance (FOQA) programs for commercial carriers. International Civil Aviation Organization (ICAO) standards further harmonize global requirements for safety management systems, directly influencing system adoption. Vendor selection increasingly depends on the ability to integrate disparate data sources and deliver actionable insights for both safety and operational efficiency.
Market Dynamics
The convergence of regulatory safety mandates and the pursuit of operational efficiency defines the market's core dynamic. Airlines are compelled by authorities like the FAA and EASA to implement safety programs, while simultaneously using the resulting data to optimize fuel consumption and maintenance schedules.
Growth Catalysts
- Regulatory Mandates:The enforcement of Safety Management Systems (SMS) by the International Civil Aviation Organization (ICAO) and national bodies like the US Federal Aviation Administration compels commercial operators to adopt formal Flight Operations Quality Assurance (FOQA) programs.
- Predictive Maintenance:The adoption of advanced analytics by commercial airlines to forecast component failures before they occur reduces unscheduled downtime and maintenance costs, creating strong demand for data-rich monitoring systems.
- Military Fleet Modernization:Defense organizations, particularly in the United States, are integrating flight data monitoring to improve fleet readiness, optimize pilot training, and support mission analysis for advanced combat and transport aircraft.
Market Restraints
- High Implementation Costs:The initial capital outlay for certified hardware, including Quick Access Recorders and ground support systems, presents a significant financial barrier for smaller airlines and general aviation operators.
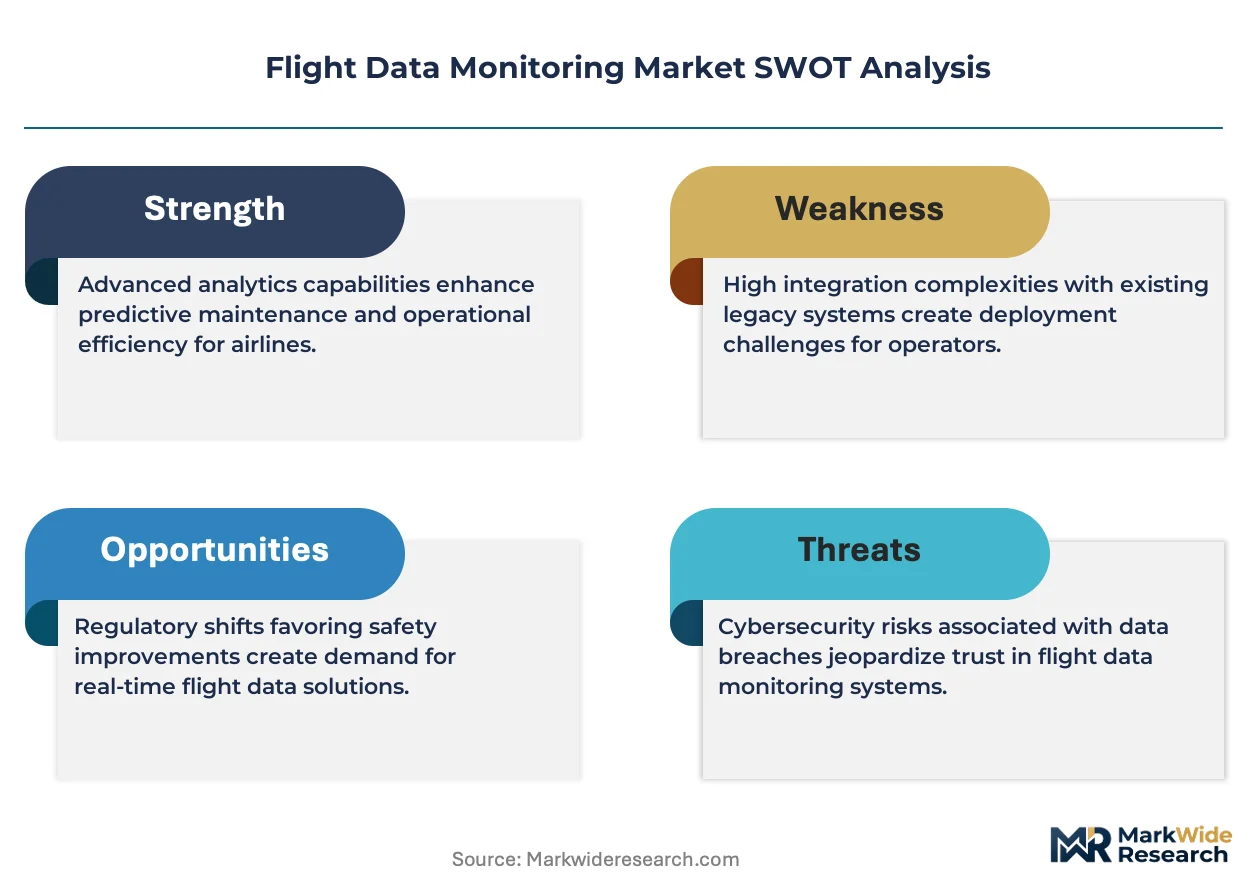
- Legacy System Integration:Integrating modern FDM software with a diverse and often aging array of avionics systems across mixed aircraft fleets creates significant technical complexity and implementation delays for operators.
- Data Transmission Bottlenecks:While data collection is robust, limitations in aircraft-to-ground connectivity bandwidth can delay the transmission of large data files, hindering real-time analysis and immediate post-flight review.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging UAM and advanced air mobility sectors will require certified flight data monitoring systems from their inception to ensure operational safety and gain regulatory and public acceptance.
- Expansion in Regional Aviation:Targeting underpenetrated regional and low-cost carriers in high-growth aviation markets, such as those in Southeast Asia and India, with scalable, cost-effective FDM solutions represents a key growth vector.
- Analytics for Sustainability:Developing analytics modules specifically focused on optimizing flight profiles for reduced fuel burn and carbon emissions provides a new value proposition aligned with airline sustainability goals under frameworks like CORSIA.
Industry Challenges
- Cybersecurity Vulnerabilities:The increasing connectivity of aircraft and ground systems creates new attack surfaces, demanding sophisticated cybersecurity measures to protect sensitive flight operational data from unauthorized access or manipulation.
- Specialized Talent Scarcity:A shortage of data analysts with the dual expertise in aviation operations and advanced data science hinders the ability of airlines to extract maximum value from their FDM programs.
- Data Standardization Gaps:The lack of a universal data format standard across different aircraft manufacturers and avionics vendors complicates the process of aggregating and analyzing data for operators with multi-type fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Data Monitoring Market |
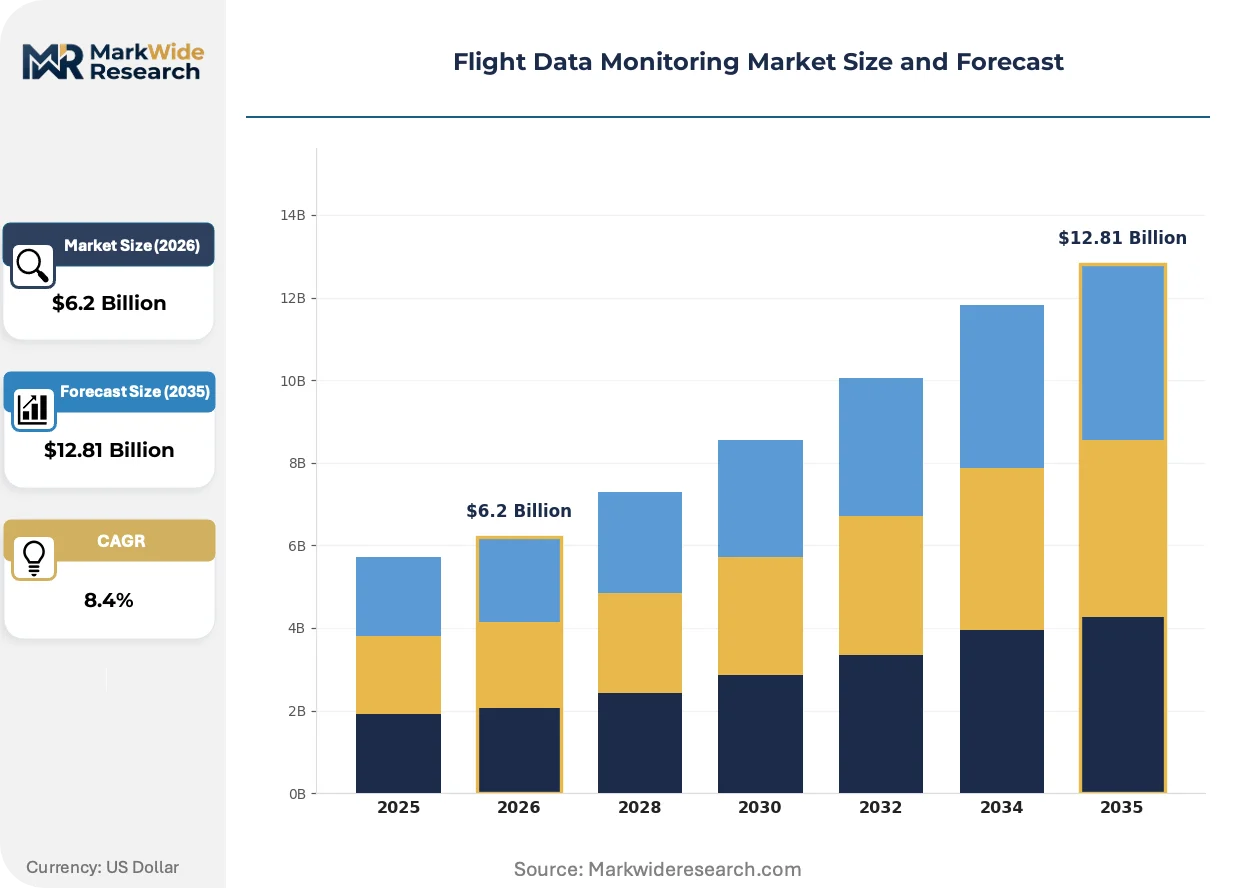
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Data Analyse Systems, Aircraft Health Monitoring, Flight Data Acquisition, Software Platforms, Hardware Sensors Technology: Wireless Transmission, Sensor Fusion, Big Data Analytics, Cloud Computing, Machine Learning Application: Flight Safety, Predictive Maintenance, Operational Efficiency, Regulatory Compliance, Risk Management End User: Airlines, Maintenance Repair Organizations, Regulatory Authorities, Flight Training Schools, Military Aviation |
| Companies Covered | Teledyne Technologies Incorporated, Curtiss-Wright Corporation, Safran SA, L3Harris Technologies, Inc., FLYHT Aerospace Solutions Ltd., Honeywell International Inc., Guardian Mobility, Scaled Analytics Inc., Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Data Monitoring Market Strategic Shifts & Innovations
The market's evolution is defined by the shift from retrospective safety analysis to proactive, data-driven operational management. Analytics platforms are becoming central to managing the entire asset lifecycle, influencing everything from maintenance planning to in-flight decision-making for fuel efficiency.
Advanced machine learning algorithms form the core of modern FDM platforms, enabling the automatic detection of subtle anomalies and precursor events within vast datasets. Commercial airlines are the leading adopters, transitioning from simple event-trigger analysis to sophisticated predictive modeling. This analytical power is expanding into real-time operational support, providing flight crews and ground control with data to optimize fuel consumption and flight paths dynamically.
Global standards from the International Civil Aviation Organization (ICAO), particularly Annex 19, are institutionalizing Safety Management Systems (SMS). This framework requires operators to use proactive and predictive methods for risk identification, directly driving the need for FDM and Flight Operations Quality Assurance programs. National regulators, including Europe's EASA, are aligning their own rules with these ICAO standards, solidifying FDM as a fundamental component of airline compliance.
A significant behavioral shift involves airlines moving away from capital-intensive hardware acquisition toward subscription-based software and analytics services. This Software-as-a-Service (SaaS) model provides access to powerful analytical tools and vendor expertise without a large upfront investment. The trend is particularly prominent among budget carriers and regional operators who can now deploy advanced FDM capabilities previously accessible only to large, flag-carrier airlines.
Flight Data Monitoring Market Segmentation
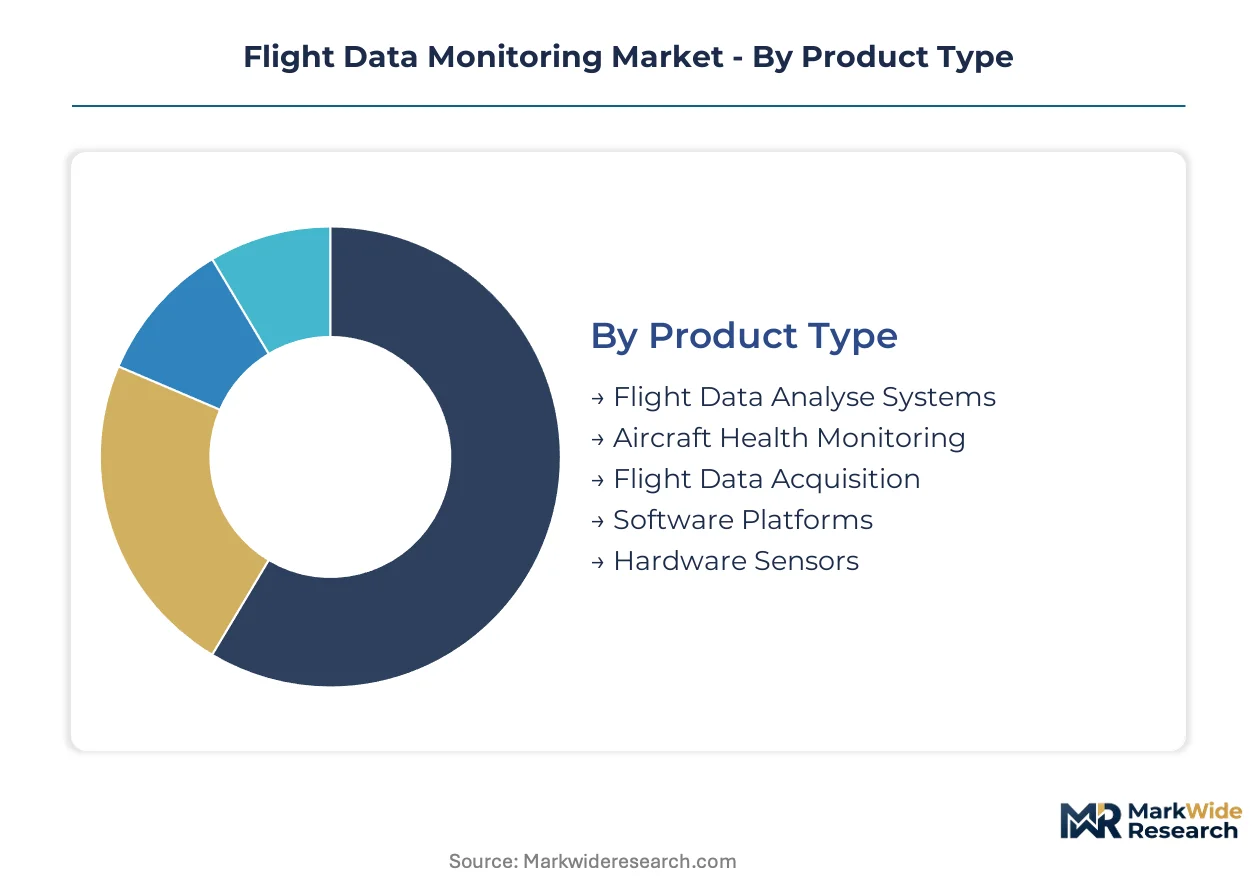
The Flight Data Monitoring market segments highlight the diverse technological requirements and varied end-user applications driving its expansion. Understanding these distinctions clarifies investment priorities and strategic positioning for vendors. Each segment addresses specific operational challenges or regulatory mandates within the aviation ecosystem.
Product Type:
Product type segmentation reflects the varying certification burdens and integration complexities for operators.
- Software Platforms:These subscription-based analytical tools process vast flight data, offering features like trend monitoring, event detection, and reporting. Commercial airlines increasingly adopt these platforms for their scalability and reduced upfront capital expenditure.
- Flight Data Analyse Systems:Dedicated systems provide in-depth analysis of collected flight parameters, identifying deviations from standard operating procedures and potential safety risks. Regulatory bodies like the FAA mandate the use of such systems for Flight Operations Quality Assurance (FOQA) programs, particularly for commercial air transport.
- Aircraft Health Monitoring:This segment focuses on real-time and post-flight analysis of aircraft system performance to predict component failures and optimize maintenance schedules.
- Flight Data Acquisition:Hardware components, such as Quick Access Recorders (QARs), capture digital flight information from various aircraft systems for subsequent download and analysis.
- Hardware Sensors:These devices collect specific operational parameters, feeding data into acquisition systems for comprehensive flight monitoring.
Leading the category by volume: Software Platforms. Growing fastest: Flight Data Analyse Systems.
Technology:
Technology advancements are enabling more sophisticated data processing and real-time insights across the market.
- Machine Learning:Algorithms automatically detect subtle anomalies and precursor events within vast datasets, moving FDM beyond simple threshold exceedance. Predictive maintenance applications for commercial airlines heavily leverage machine learning models.
- Big Data Analytics:This technology processes and interprets large volumes of disparate flight data from multiple sources, transforming raw information into actionable insights. Airlines utilize big data analytics to optimize fuel consumption and improve operational efficiency.
- Cloud Computing:Cloud platforms provide scalable infrastructure for storing, processing, and analyzing flight data, reducing the need for on-premise IT resources.
- Sensor Fusion:This involves combining data from multiple sensors to provide a more comprehensive and accurate picture of aircraft state and performance.
- Wireless Transmission:Enables efficient and often automated transfer of flight data from aircraft to ground systems, supporting quicker post-flight review.
Technology advancements in Machine Learning are driving innovation, while Big Data Analytics provides foundational capabilities.
Application:
Applications within FDM address both mandatory safety requirements and voluntary operational enhancements.
- Predictive Maintenance:This application utilizes flight data to forecast component failures and schedule maintenance proactively, minimizing unscheduled downtime. Airlines are rapidly adopting predictive maintenance solutions to reduce operational costs and enhance fleet reliability.
- Flight Safety:The foundational application of FDM involves identifying operational risks, improving pilot training, and enhancing overall flight safety through routine data analysis. Regulatory frameworks from ICAO and EASA compel commercial operators to implement robust flight safety programs.
- Operational Efficiency:Analyzing flight data helps optimize flight profiles, reduce fuel burn, and streamline ground operations for cost savings.
- Regulatory Compliance:FDM systems provide the necessary data and reporting capabilities to meet mandates from aviation authorities like the FAA and EASA.
- Risk Management:By identifying potential hazards and deviations, FDM supports proactive risk mitigation strategies within aviation operations.
Demand for Predictive Maintenance applications is expanding rapidly, complemented by established requirements for Flight Safety.
End User:
The end-user base for FDM solutions spans various sectors within the aviation industry, each with distinct needs.
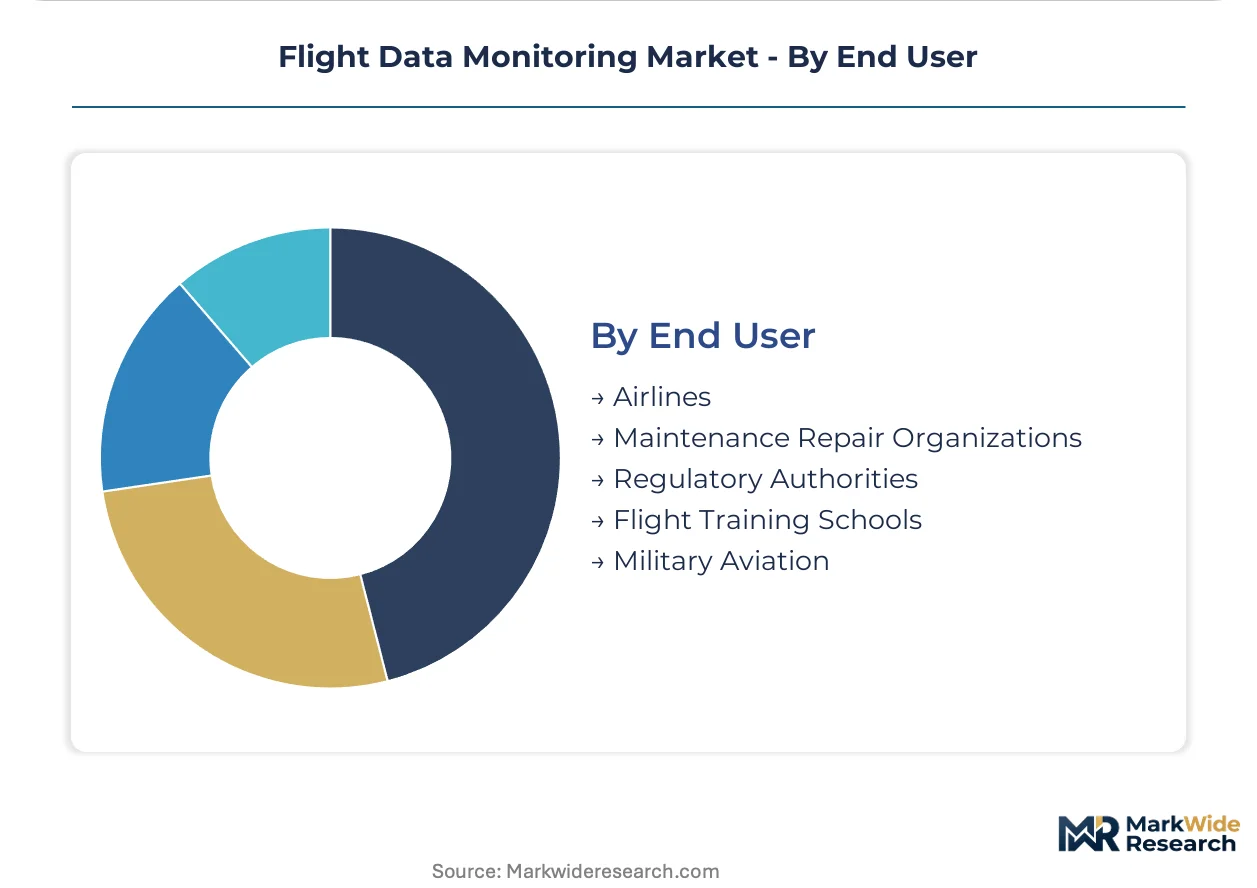
- Airlines:Commercial and cargo carriers represent the largest end-user segment, driven by regulatory compliance, safety improvements, and the pursuit of operational efficiency. Large airlines often require integrated solutions that support extensive fleets and complex operational structures.
- Military Aviation:Defense organizations utilize FDM for fleet readiness, optimizing pilot training, and mission analysis for advanced combat and transport aircraft. The United States military is a significant adopter, integrating these systems for enhanced operational effectiveness.
- Maintenance Repair Organizations:MROs leverage flight data to diagnose issues, perform targeted maintenance, and verify repair effectiveness.
- Regulatory Authorities:These bodies use FDM data for oversight, accident investigation, and to ensure compliance with aviation safety standards.
- Flight Training Schools:FDM provides valuable insights into trainee performance, enhancing instructional effectiveness and safety protocols.
The largest consumer base resides with Airlines, with significant expansion observed in Military Aviation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Flight Data Monitoring market exhibits a clear divide between technology development and end-user consumption. Leading aerospace nations drive innovation in FDM systems, while a broader range of countries actively implement these solutions for safety and efficiency. This dynamic shapes regional investment and deployment patterns for flight data analysis.
United States
Demand for flight data monitoring systems in the United States stems from its extensive commercial and military aviation fleets. The US Federal Aviation Administration (FAA) mandates Flight Operations Quality Assurance (FOQA) programs for commercial carriers. Major aerospace hubs like Seattle and Wichita are central to the development and integration of advanced FDM technologies.
France
France drives innovation in flight data monitoring through its strong aerospace manufacturing sector and airline operations. The European Union Aviation Safety Agency (EASA) regulations compel French operators to implement robust safety management systems. Toulouse, a European aerospace center, houses significant research and development for FDM analytics.
Germany
German airlines and defense organizations seek flight data monitoring for operational efficiency and predictive maintenance. EASA frameworks influence the adoption of FDM solutions across the German aviation industry. Munich and Hamburg host key aerospace clusters developing sophisticated data analysis tools for aircraft performance.
Japan
Japanese airlines and military services prioritize flight data monitoring for enhancing safety and optimizing fleet readiness. The Japan Civil Aviation Bureau (JCAB) oversees compliance with ICAO safety management system standards. Tokyo and Nagoya are centers for avionics manufacturing and FDM software integration within the region.
India
India's rapidly expanding aviation sector generates significant demand for scalable flight data monitoring solutions. The Directorate General of Civil Aviation (DGCA) enforces safety regulations requiring FDM implementation for commercial fleets. Major aviation hubs like Delhi and Mumbai are focal points for FDM system deployment and data analysis.
Flight Data Monitoring Market Key Industry Players
Top-tier vendors anchor the integrated hardware and software solutions segment, while specialized analytics providers address niche demands for data interpretation. The market structure features a mix of established aerospace giants and agile software firms. Strategic partnerships between avionics manufacturers and data science companies are common. Companies often focus on portfolio diversification to offer comprehensive FDM packages.
Within the integrated solutions archetype, US-based L3Harris Technologies, Inc. and Safran SA, a French aerospace company, exemplify providers offering extensive avionics and data analysis capabilities. These firms leverage their deep industry presence to deliver bundled hardware and analytics. Curtiss-Wright Corporation, another US-based entity, represents a significant player in the data acquisition hardware and ground support systems segment. These companies anchor the market through their comprehensive offerings and long-standing relationships with major airframers and airlines.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| Curtiss-Wright Corporation |
| Safran SA |
| L3Harris Technologies, Inc. |
| FLYHT Aerospace Solutions Ltd. |
| Honeywell International Inc. |
| Guardian Mobility |
| Scaled Analytics Inc. |
| Collins Aerospace |
| Others |
Cost & Logistics Intelligence
Specialized data analysts and aviation software engineers in aerospace hubs like Toulouse and Seattle drive premium pricing for integrated FDM solutions, creating distinct pricing-tier spreads compared to subscription-based services leveraging broader talent pools.
Pricing Analysis
Cost-down pressure on regional and low-cost carriers accelerates due to tight operating margins and intense competition, influencing FDM solution procurement. The dominant pricing structure combines subscription-based SaaS platforms with transactional hardware sales for Quick Access Recorders. Price differentiation stems from the level of regulatory certification required and the depth of integrated analytics support. Large commercial airlines demonstrate lower price sensitivity for comprehensive, integrated FDM systems, while smaller operators prioritize cost-effective, scalable solutions.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the aftermarket supply chain for FDM hardware, ensuring timely delivery of certified components. Supply concentration for advanced avionics components and specialized sensors resides primarily in the United States, France, and Germany. The industry relies on high-tech inputs like secure data storage and robust processing units. Single-source vulnerability for specific certified hardware components presents a structural supply chain risk, while distribution largely runs through direct sales channels from major aerospace manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Flight Data Monitoring market is poised for consolidation, driven by the significant upfront implementation costs that challenge smaller, specialized providers. This environment favors established players capable of offering comprehensive, integrated solutions across the aviation ecosystem.
For Market Incumbents:
Hedge against the threat of data standardization gaps by investing heavily in open architecture platforms and API development. Acquire smaller, specialized analytics firms to integrate advanced machine learning capabilities and expand their software-as-a-service offerings. Deepen vertical integration into data acquisition hardware while enhancing R&D in AI and machine learning to maintain a competitive edge. Focus on expanding certified solutions to meet evolving regulatory mandates from bodies like EASA and FAA.
For New Entrants and Emerging Players:
A significant price-point gap exists between premium, integrated FDM solutions and the budget constraints of regional carriers. Target underpenetrated regional aviation markets in Southeast Asia and India with scalable, cost-effective SaaS solutions. Focus on developing cloud-native analytics platforms that offer rapid deployment and minimal upfront capital expenditure. Urban Air Mobility represents a white-space opportunity for certified FDM systems, leveraging flexible, subscription-based models.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized AI/ML analytics providers given the accelerating demand for predictive maintenance solutions. Long-term viability in the FDM market remains strong, driven by persistent regulatory mandates and the shift towards data-driven operational efficiency. Target acquisition profiles should include niche software firms with proprietary algorithms or hardware manufacturers holding key certifications. The signal to watch is the rapid adoption of certified FDM systems within the nascent Urban Air Mobility sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI/ML Algorithms | Enhances predictive maintenance capabilities for airlines, optimizing fleet performance and reducing operational costs. |
| Develop Cloud-Native SaaS Platforms | Lowers entry barriers for regional carriers, expanding market reach and enabling scalable data analysis. |
| Expand into Urban Air Mobility (UAM) | Positions providers at the forefront of emerging aviation, securing early market share in a high-growth segment. |
| Pursue Global Regulatory Certifications | Ensures compliance with ICAO and EASA standards, facilitating market access across diverse geographies for FDM systems. |
| Strategic Partnerships with Avionics OEMs | Integrates FDM solutions directly into new aircraft platforms, streamlining adoption for commercial and military aviation. |
Research Approach
Multi-period observation of FDM adoption rates and technology advancements anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with aviation safety officers, airline maintenance directors, FDM software engineers, and regulatory compliance managers. This was validated against secondary sources including ICAO reports, FAA advisory circulars, EASA regulations, and aerospace industry financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market sizing.
An input-output matrix framework facilitated the quantitative modeling of market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Key industry-specific forecast inputs included aircraft delivery schedules and the implementation timelines for new regulatory mandates.
Inputs from publicly available aviation safety databases and company reports were available through the study window; gaps in real-time operational data introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory enforcement and technological evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market