
 Aircraft Health Monitoring System (AHMS) Market | 2026-2036
Aircraft Health Monitoring System (AHMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Health Monitoring System (AHMS) Market Analytics
DO-178C software certification is redrawing competitive boundaries for avionics suppliers entering the AHMS space. Honeywell International leverages its embedded systems heritage to sustain platform-agnostic architectures across Boeing and Airbus programs. Rolls-Royce anchors its position through proprietary engine sensor networks that feed real-time data into fleet analytics portals. Safran competes via integrated landing gear and nacelle monitoring systems that extend MRO contract value.
An Aircraft Health Monitoring System comprises networked sensors, data acquisition units, and diagnostic algorithms that measure vibration, temperature, pressure, and strain across airframe and propulsion components to predict failures before they trigger operational disruptions. The system relies on ARINC 429 and MIL-STD-1553 data buses to aggregate multi-source inputs at sampling rates exceeding 1 kHz for critical rotating machinery. Hardware and sensor segments dominate installed base value, while predictive analytics and machine learning layers capture expanding software recurring revenue as airlines prioritize fleet-wide prognostics over reactive maintenance scheduling. MRO Providers represent a fast-growing end user category as third-party overhaul shops invest in vendor-agnostic diagnostic platforms to win airline outsourcing contracts.
FAA airworthiness directives and EASA CS-25 certification standards mandate continuous structural and engine monitoring for extended-range twin-engine operations, directly shaping sensor density requirements and software validation protocols. The EU AI Act introduces algorithmic transparency obligations for predictive maintenance models deployed on European-registered aircraft, adding compliance layers for machine learning-based AHMS offerings. Stakeholders must weigh regulatory divergence between FAA performance-based standards and EU prescriptive AI governance when architecting next-generation platforms for multinational fleets.
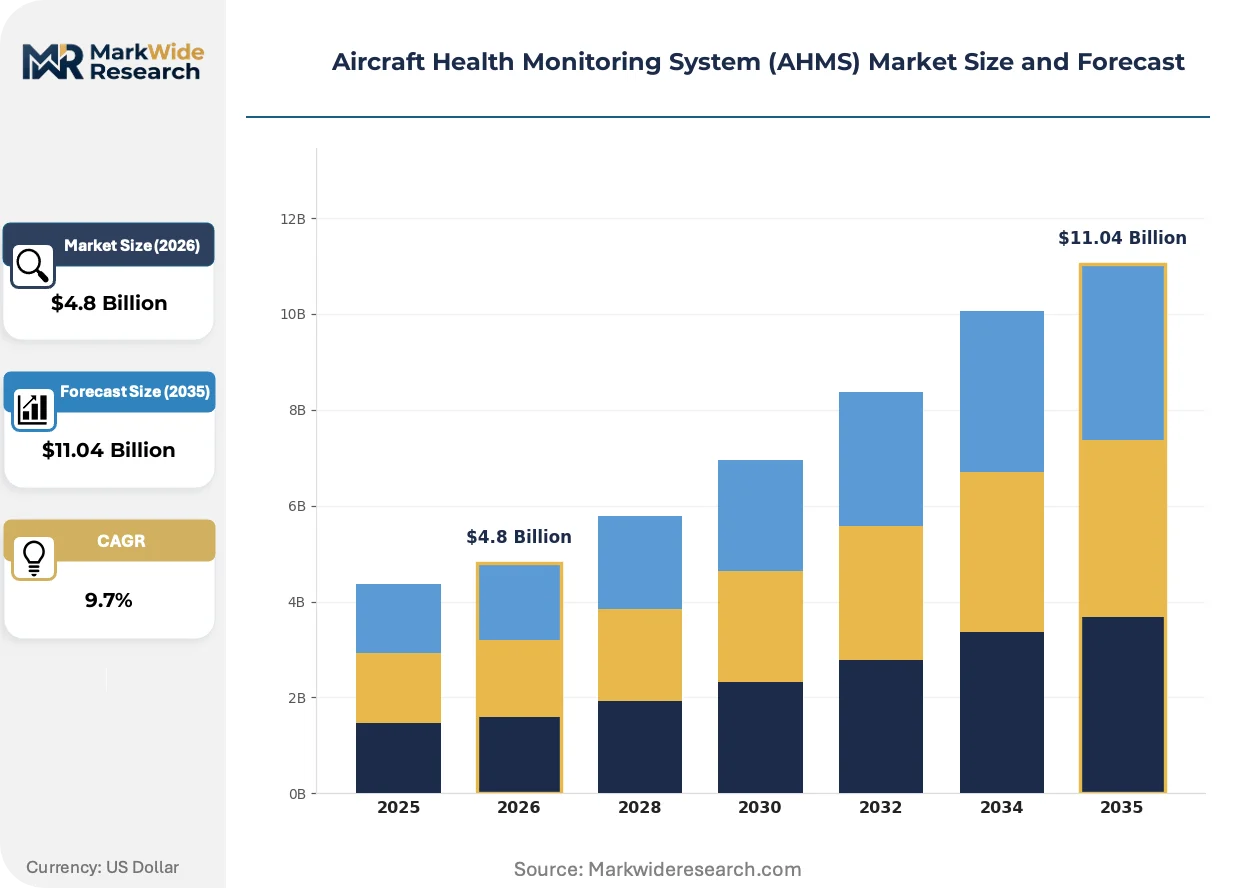
Market Dynamics
The AHMS market is experiencing structural compression as predictive maintenance contracts displace traditional time-based overhaul schedules, forcing suppliers to reconfigure revenue models around data services rather than hardware shipments.
Growth Catalysts
- FAA Extended-range Operations Mandates:Airworthiness directives for continuous engine monitoring on twin-engine aircraft are mandating sensor retrofits across aging fleets, expanding installed base requirements.
- Machine Learning Inference at the Edge:Onboard diagnostic algorithms now process vibration spectra locally, reducing latency for critical failure predictions without ground-link dependency.
- Commercial Fleet Expansion in Southeast Asia:Low-cost carriers in Vietnam, Indonesia, and the Philippines are ordering narrow-body aircraft with factory-installed AHMS architectures.
Market Restraints
- Sensor Hardware Cost Concentration:Piezoelectric accelerometers and fiber-optic strain gauges rely on specialized ceramics supply chains concentrated in Japan and Germany.
- DO-178C Certification Burden:Software validation for Level A criticality systems requires 50-70% of development budgets, creating barrier-to-entry friction for new diagnostic platform vendors.
- Legacy Aircraft Interoperability Gaps:ARINC 429 data buses on pre-2000 airframes lack bandwidth for high-frequency sampling, limiting retrofit economics.
Strategic Opportunities
- EU AI Act Algorithmic Transparency Requirements:European-registered operators need explainable predictive models, creating demand for interpretable machine learning architectures.
- MRO Provider Channel Expansion:Third-party overhaul shops in Poland, Singapore, and Mexico are building vendor-agnostic diagnostic platforms to capture airline outsourcing contracts.
- Digital Twin Convergence:Integration of AHMS sensor streams with physics-based simulation models enables remaining-useful-life predictions for structural components.
Industry Challenges
- Embedded Systems Talent Scarcity:DO-178C qualified software engineers command premium compensation, constraining development velocity for mid-tier suppliers.
- Multi-Platform Integration Complexity:Airlines operating mixed Boeing-Airbus fleets face data normalization challenges across proprietary OEM diagnostic protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Health Monitoring System (AHMS) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Sensor, Integration Services Technology: Real-time Monitoring, Predictive Analytics, Machine Learning, Data Fusion End User: Commercial Aviation, Military Aviation, Cargo Airlines, MRO Providers Application: Engine Monitoring, Structural Health, Performance Optimization, Maintenance Management |
| Companies Covered | Airbus, Boeing, Honeywell International, Raytheon Technologies, General Electric, Safran, Rolls-Royce, Meggitt, FLYHT Aerospace Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Health Monitoring System (AHMS) Market Evolving Landscape
Wireless sensor networks are displacing wired harness architectures across new aircraft programs, compressing installation weight and enabling retrofit applications previously uneconomical.
Edge computing architectures are fragmenting the traditional centralized flight data recorder model. Distributed processing units now run diagnostic algorithms on wing-mounted sensor nodes, reducing cable runs by 40-60% on clean-sheet designs. MRO providers are adopting these modular systems for line-replaceable unit strategies that minimize hangar downtime.
EASA CS-25 certification standards for structural health monitoring are tightening sensor density requirements for composite airframes. European manufacturers must demonstrate damage detection capabilities below critical crack lengths for primary load-bearing structures. This regulatory pressure is accelerating qualification programs for ultrasonic and thermographic inspection systems integrated into production lines.
Airline procurement teams are unbundling predictive analytics subscriptions from hardware purchase agreements. Carriers now negotiate software renewals separately from sensor warranties, with Middle Eastern and Asian operators leading this contractual separation. This shift compresses vendor lock-in duration and intensifies competition on algorithm performance metrics rather than installed base protection.
Aircraft Health Monitoring System (AHMS) Market Segmentation
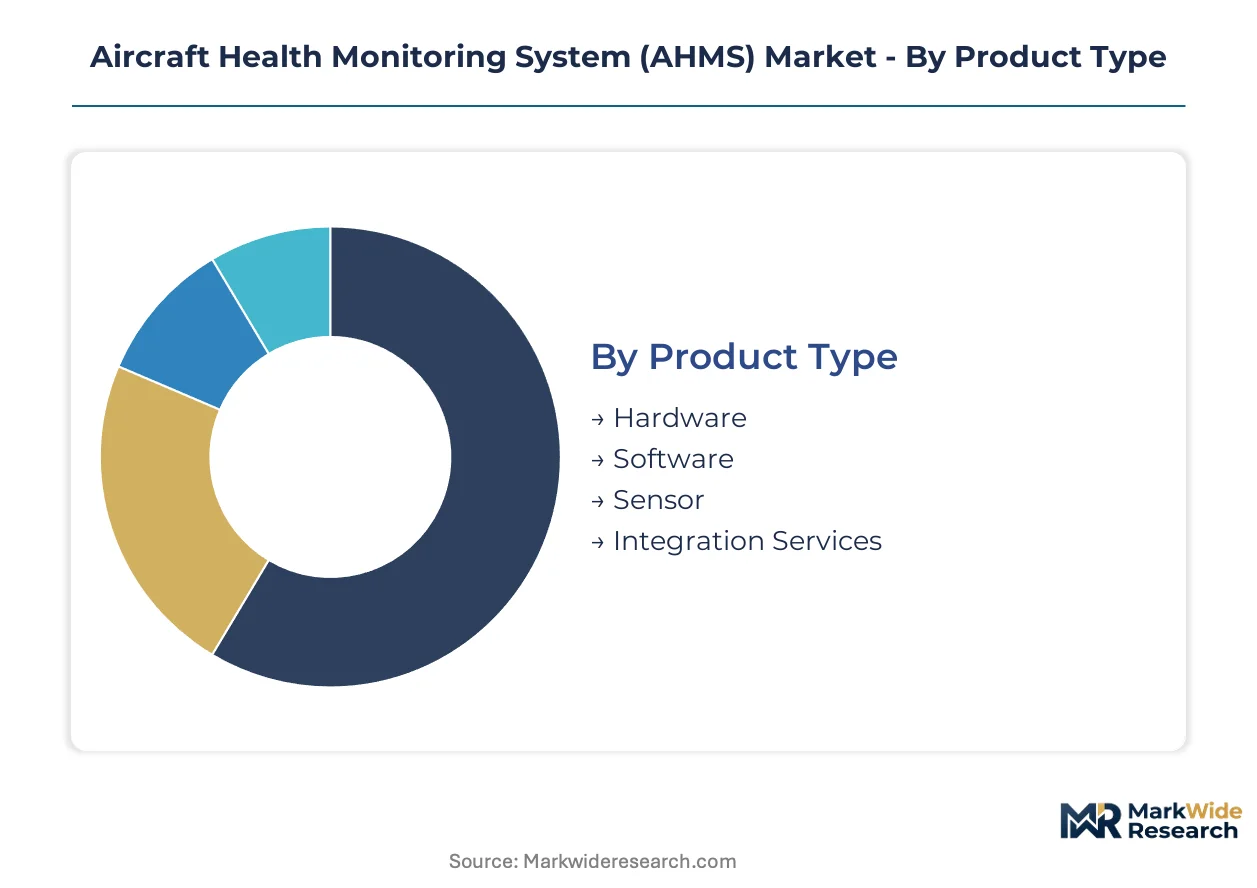
Segmentation in the AHMS market reveals how value migrates from hardware installations toward recurring software and analytics revenue. Suppliers must calibrate portfolio depth across product tiers while navigating divergent certification requirements between commercial and military end users.
Product Type:
Margin pools concentrate in sensor hardware and integration services, where long-term MRO contracts and retrofit programs sustain pricing power.
- Hardware:Data acquisition units, processing modules, and communication gateways form the physical backbone of AHMS installations. Demand clusters around Boeing 737 MAX and Airbus A320neo production lines in the United States and France, driven by factory-fit mandates for extended-range operations.
- Sensor:Piezoelectric accelerometers, fiber-optic strain gauges, and thermocouples capture vibration, temperature, and structural load data at sampling rates exceeding 1 kHz. Commercial aviation fleets in Germany and Japan are retrofitting aging narrow-bodies with wireless sensor nodes to bypass ARINC 429 bandwidth constraints.
- Software:Diagnostic algorithms and fleet analytics platforms process sensor streams into actionable maintenance alerts. Airlines in the United Arab Emirates and Singapore are unbundling software subscriptions from hardware purchases.
- Integration Services:System architecture design, certification support, and fleet-wide deployment project management. Third-party MRO providers in Poland and Mexico are building vendor-agnostic integration capabilities to capture airline outsourcing.
The dominant share belongs to Hardware, while Sensor is closing the gap fastest as wireless retrofit programs accelerate.
Technology:
Application intensity varies sharply between real-time operational alerts and predictive models requiring ground-based computation.
- Real-time Monitoring:Continuous data streams from engine and airframe sensors trigger immediate crew alerts for exceedance conditions. FAA airworthiness directives for twin-engine extended operations mandate these capabilities across United States-registered fleets.
- Predictive Analytics:Statistical models forecast component remaining useful life based on degradation trends. European operators face EU AI Act transparency requirements that favor interpretable regression approaches over black-box neural networks.
- Machine Learning:Deep learning architectures process high-dimensional vibration spectra for anomaly detection. Edge deployment on wing-mounted nodes is expanding most quickly in Southeast Asian low-cost carrier fleets.
- Data Fusion:Multi-source integration combining sensor feeds with flight operational data and maintenance history. Military aviation programs in the United Kingdom and Australia prioritize this layer for platform-agnostic fleet management.
Real-time Monitoring retains the largest installed base, though Machine Learning is gaining share fastest as edge computing architectures mature.
End User:
Procurement sophistication diverges between price-sensitive cargo operators and military buyers with captive sustainment budgets.
- Commercial Aviation:Full-service and low-cost carriers operating scheduled passenger services. Vietnam, Indonesia, and Philippines carriers are factory-installing AHMS on new narrow-body orders to minimize unplanned downtime.
- MRO Providers:Third-party overhaul shops building diagnostic capabilities to win airline outsourcing contracts. Singapore and Poland have emerged as regional hubs for vendor-agnostic platform development.
- Cargo Airlines:Dedicated freighter operators with high aircraft utilization driving preventive maintenance investment. United States-based integrators lead adoption of engine monitoring for aging wide-body conversions.
- Military Aviation:Defense agencies with platform-specific requirements and classified data handling protocols. United Kingdom and Australian programs emphasize interoperability across mixed fleets.
Commercial Aviation commands the deepest penetration, while MRO Providers are expanding most quickly as airlines outsource diagnostic capabilities.
Application:
Sensor density and algorithm complexity scale with the criticality of failure modes in each operational domain.
- Engine Monitoring:Vibration, temperature, and oil debris analysis for turbofan health assessment. EASA certification standards for extended-range twin-engine operations are tightening sensor coverage requirements across European-registered aircraft.
- Structural Health:Strain gauging and ultrasonic inspection for composite airframe damage detection. Boeing and Airbus production lines in the United States and France are qualifying thermographic systems for primary structure monitoring.
- Performance Optimization:Aerodynamic efficiency tracking and fuel burn analysis. Cargo operators in Germany and the Netherlands prioritize this application for long-haul freighter economics.
- Maintenance Management:Workscope planning and spare parts forecasting based on prognostic outputs. Middle Eastern carriers in the United Arab Emirates and Qatar are separating these software renewals from hardware warranties.
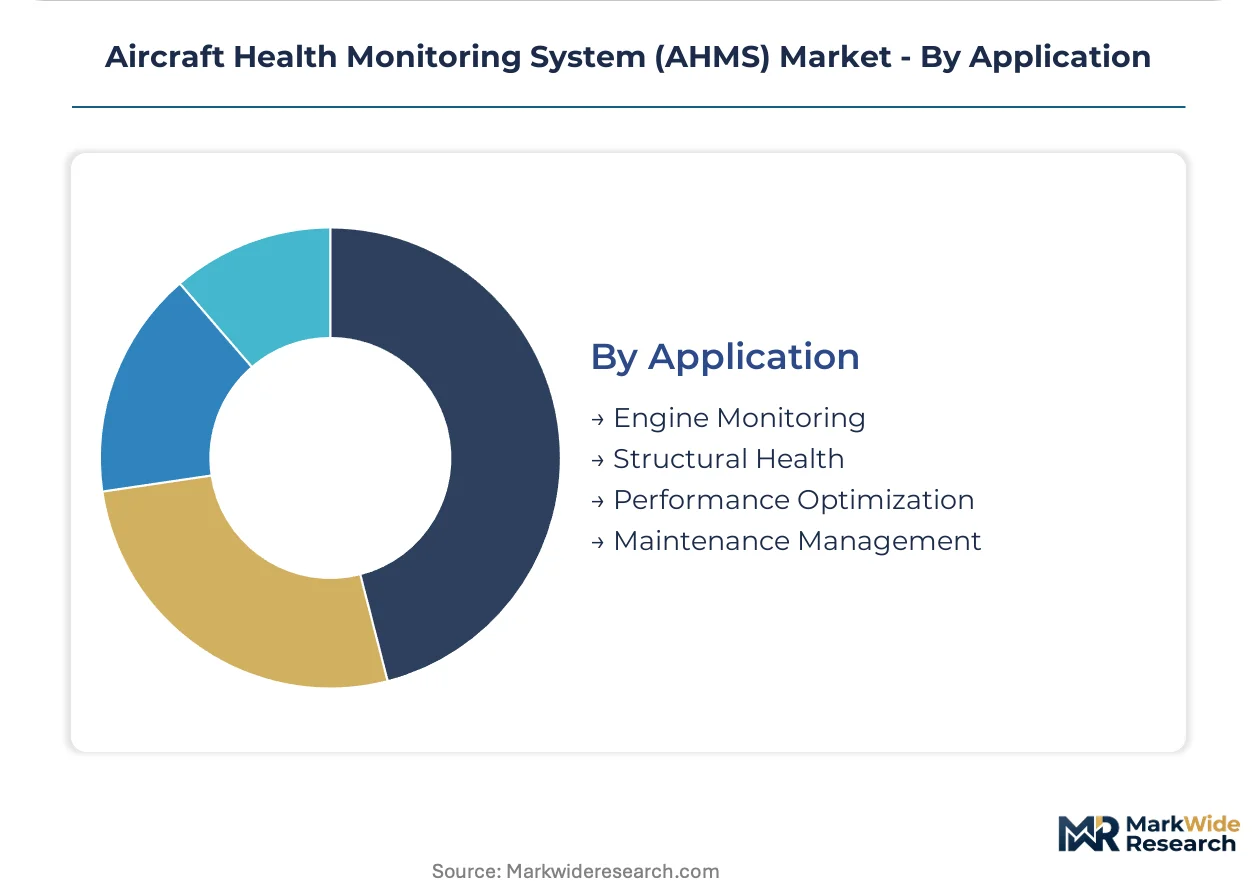
Engine Monitoring holds the largest revenue share, though Structural Health is climbing the fastest as composite airframe certification standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airlines in the United States, Germany, and Singapore are driving AHMS procurement through extended-range operations mandates and fleet modernization programs. Defense agencies in the United Kingdom and Japan are expanding platform-agnostic monitoring architectures for mixed military fleets. Factory-fit installations concentrate in France and the United States where Boeing and Airbus final assembly lines operate.
United States
FAA airworthiness directives for continuous engine monitoring on twin-engine aircraft are mandating sensor retrofits across aging narrow-body and wide-body fleets. The FAA's performance-based certification standards for predictive maintenance software are shaping validation protocols for machine learning-based diagnostic platforms. Seattle and Wichita anchor development clusters where tier-one suppliers integrate AHMS architectures into Boeing 737 MAX and 787 production lines.
Germany
Lufthansa Technik and cargo operators are investing in engine monitoring systems for aging wide-body conversions to minimize unplanned downtime on high-utilization routes. EASA CS-25 certification standards for structural health monitoring are tightening sensor density requirements for composite airframes registered in European Union member states. Hamburg and Munich host MRO provider clusters building vendor-agnostic diagnostic platforms to capture airline outsourcing contracts from Middle Eastern and Asian carriers.
United Kingdom
Ministry of Defence programs are prioritizing interoperability across mixed Boeing-Airbus military fleets, driving demand for platform-agnostic data fusion architectures. The UK Civil Aviation Authority aligns with EASA standards for extended-range twin-engine operations, mandating continuous monitoring capabilities for British-registered commercial aircraft. Bristol and Derby concentrate engine health monitoring development where Rolls-Rance anchors proprietary sensor networks feeding fleet analytics portals.
Singapore
Third-party MRO providers are building vendor-agnostic diagnostic platforms to win airline outsourcing contracts from Southeast Asian low-cost carriers. The Civil Aviation Authority of Singapore enforces ICAO-aligned airworthiness standards that mandate predictive maintenance capabilities for extended-range operations. Seletar Aerospace Park clusters integration specialists delivering AHMS retrofit programs for regional cargo and passenger operators.
Japan
ANA and JAL are retrofitting pre-2000 narrow-body aircraft with wireless sensor nodes to bypass ARINC 429 bandwidth constraints on aging data buses. METI industrial policy supports domestic aerospace supply chain development, including piezoelectric accelerometer manufacturing for structural health applications. Nagoya and Tokyo concentrate sensor hardware production where specialized ceramics supply chains serve both commercial aviation and defense programs.
Aircraft Health Monitoring System (AHMS) Market Competitive Landscape
Player mix skews toward diversified aerospace conglomerates with embedded systems heritage and engine OEMs with proprietary sensor networks. Market structure concentrates around tier-one suppliers capable of DO-178C Level A software certification and platform-agnostic hardware architectures. Two strategic archetypes dominate: avionics specialists leveraging flight control software expertise and propulsion manufacturers monetizing engine-specific data streams. Competitive moves center on unbundling software subscriptions from hardware warranties and building MRO channel partnerships to capture aftermarket diagnostic revenue.
Among diversified aerospace conglomerates, Honeywell International and Raytheon Technologies exemplify the avionics-centric archetype through platform-agnostic system architectures. Rolls-Royce and General Electric occupy positions as propulsion-anchored competitors leveraging proprietary engine sensor networks for fleet analytics. Safran sits within the integrated systems tier, extending MRO contract value through landing gear and nacelle monitoring capabilities. These three archetypes—avionics specialists, engine OEMs, and integrated systems providers—define competitive positioning as airlines unbundle predictive analytics from hardware procurement.
| Leading Market Players |
|---|
| Airbus |
| Boeing |
| Honeywell International |
| Raytheon Technologies |
| General Electric |
| Safran |
| Rolls-Royce |
| Meggitt |
| FLYHT Aerospace Solutions |
| Others |
Value Network & Pricing Analysis
Long-term predictive maintenance contracts with inflation-linked indexation clauses lock in multi-year revenue visibility for AHMS suppliers while insulating airlines from sensor hardware cost volatility. These agreements tie software subscription renewals to fleet utilization metrics, creating pricing transparency that favors carriers with high aircraft deployment rates.
Pricing Analysis
Cost-plus contracts with aerospace-grade ceramics indexation dominate sensor procurement, embedding Japan-sourced piezoelectric material costs into final hardware pricing. Price differentiation hinges on DO-178C certification tier and aftermarket service bundling, with Level A systems commanding substantial premiums over diagnostic-only offerings. Pricing pressure intensifies as airlines unbundle software subscriptions from hardware warranties, compressing vendor lock-in duration. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while Middle Eastern full-service operators prioritize algorithm performance over unit economics.
Supply Chain Analysis
Extended lead times for specialized ceramics have forced tier-one suppliers to hold 6-9 months of piezoelectric accelerometer inventory, straining working capital across the value chain. Manufacturing concentrates in Japan, Germany, and the United States, with Nagoya and Munich anchoring precision sensor production. Raw material dependencies include barium titanate ceramics, fiber-optic strain gauge substrates, and high-temperature thermocouple alloys. Single-source vulnerability in Japanese ceramics supply creates exposure to seismic disruption and export licensing delays. Distribution runs through Boeing and Airbus final assembly lines for factory-fit installations, with third-party MRO channels expanding for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AHMS market represents a high-growth disruption as edge computing architectures fragment centralized flight data models and EU AI Act transparency mandates reshape algorithmic competition. FAA extended-range operations directives and EASA CS-25 certification tightening create regulatory tailwinds that entrench incumbent positions while opening white-space for interpretable machine learning specialists.
For Market Incumbents: Fortify platform-agnostic architectures through backward integration into wireless sensor node production, reducing dependency on Japanese ceramics suppliers. Deepen DO-178C certification moats by investing in automated validation toolchains that compress Level A software development cycles. Defend against unbundling pressure by embedding predictive analytics into flight operations software suites that carriers cannot easily replace. For New Entrants and Emerging Players: Differentiate on explainable AI architectures that satisfy EU AI Act algorithmic transparency requirements for European-registered fleets. Target third-party MRO providers in Poland and Mexico with vendor-agnostic diagnostic platforms that normalize data across Boeing-Airbus mixed fleets. Pursue line-replaceable unit strategies that minimize hangar downtime and accelerate adoption among cost-sensitive cargo operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric diagnostic platforms with fleet analytics subscriptions separated from hardware warranties. Long-term viability favors suppliers with embedded systems heritage capable of spanning commercial aviation and defense applications. Acquisition candidates should demonstrate DO-178C qualified engineering teams and established channel partnerships with tier-one MRO providers. Monitor EASA structural health monitoring certification timeline acceleration as the signal for composite airframe sensor density inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Deployment | Onboard diagnostic processing reduces ground-link dependency for Southeast Asian low-cost carriers. |
| EU AI Act Compliance Investment | Interpretable machine learning architectures unlock European-registered fleet contracts requiring algorithmic transparency. |
| MRO Channel Partnership Expansion | Third-party overhaul shops in Singapore and Poland capture airline outsourcing with vendor-agnostic platforms. |
| Wireless Sensor Network Qualification | Retrofit applications bypass ARINC 429 bandwidth constraints on pre-2000 airframes. |
| Digital Twin Integration Development | Physics-based simulation models enable remaining-useful-life predictions for structural components. |
Research Methodology
A spread of perspectives from fleet maintenance directors, avionics procurement officers, MRO operations managers, and regulatory compliance leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA airworthiness directive filings, EASA certification documentation, airline fleet planning disclosures, and aerospace supplier SEC filings. Bottom-up sensor shipment estimates and top-down fleet expansion projections were triangulated to anchor market sizing.
Segmentation dimensions modeled include hardware versus software versus services revenue split, real-time monitoring versus predictive analytics technology tier, commercial aviation versus MRO provider versus military end-user category, and engine versus structural health versus performance optimization application area. CAGRs were derived from installed base expansion rates and recurring revenue attach ratios across the projection horizon. Forecast inputs incorporated extended-range operations mandate compliance deadlines and composite airframe production ramp schedules.
The analysis sits within stated boundaries; outcomes outside sustained FAA-EASA regulatory alignment or accelerated wireless sensor qualification timelines would require recalibration. Forecasts reflect assumptions regarding fleet modernization rates and MRO outsourcing propensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aircraft Control Software Market