
 Aircraft Flight Recorder Market | 2026-2036
Aircraft Flight Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
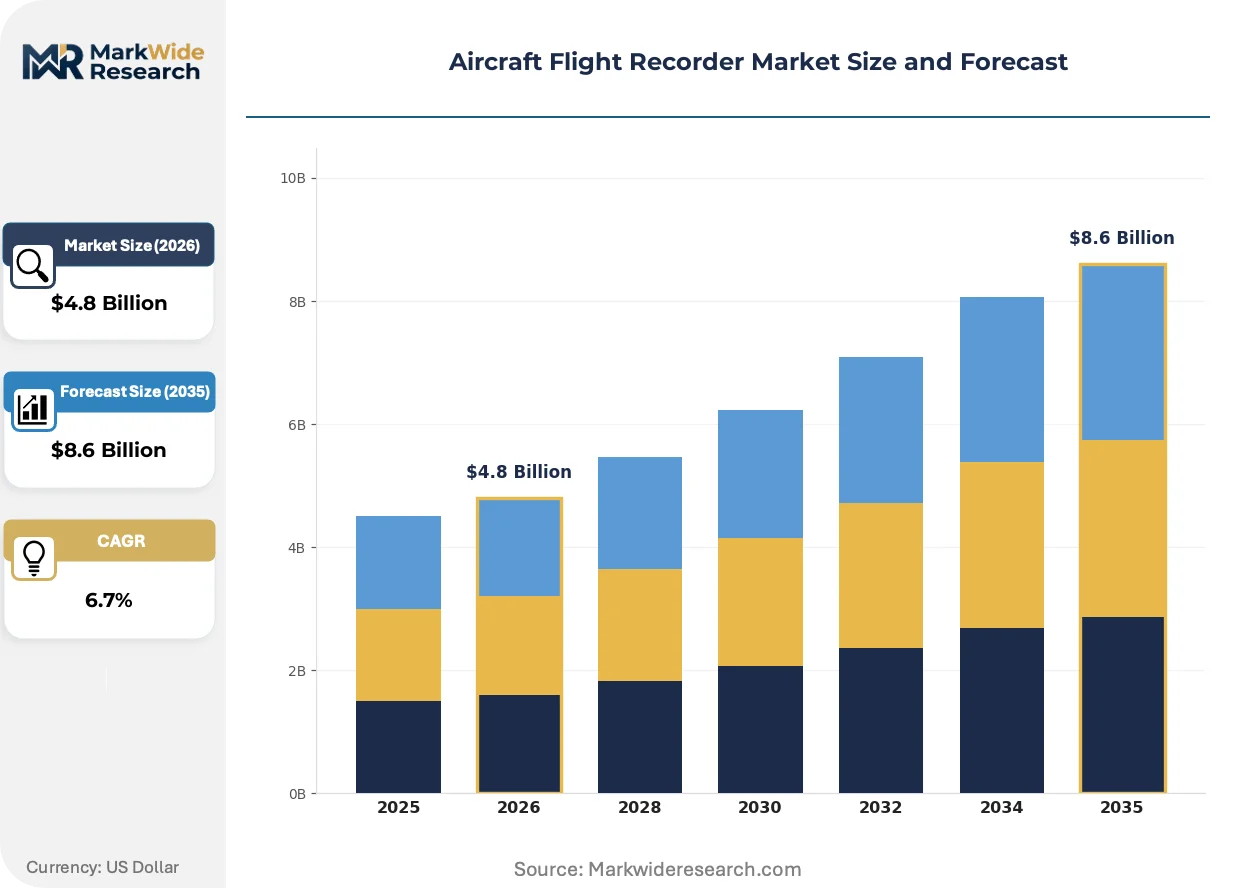
Aircraft Flight Recorder Market Outlook
Modular recorder packaging is consolidating buyer choice around integrated black-box systems that combine cockpit voice, flight data, and emergency locator functions in single line-replaceable units. Honeywell International Inc. leverages its avionics integration heritage to anchor positions on Boeing and Airbus platforms. L3Harris Technologies Inc. sustains defense-sector dominance through ruggedized designs purpose-built for military airframes. Curtiss-Wright Corporation specializes in crash-survivable memory modules that differentiate its offerings for helicopter and unmanned system applications.
Aircraft flight recorders are hardened electronic devices engineered to withstand impact forces exceeding 3,400 G, deep-sea pressure, and post-crash fire exposure while preserving at least 25 hours of flight parameter data and two hours of cockpit audio for accident investigation. Solid-state technology leads the technology segment due to superior shock resistance and data density versus legacy magnetic tape architectures, though hybrid systems retain niche roles in certain retrofit contexts. Combined voice and data recorder configurations command attention in the type segment as regulators mandate streamlined installations that reduce unit count and wiring complexity across commercial aviation end users.
The Federal Aviation Administration mandates 25-hour cockpit voice recording duration under updated Technical Standard Orders, while the European Union Aviation Safety Agency enforces ED-112A compliance for next-generation recorder survivability. ICAO's Global Aeronautical Distress and Safety System timeline pressures operators to accelerate replacement cycles regardless of equipment age. Stakeholders must weigh captive versus outsourced solid-state memory sourcing as supply chain constraints and evolving crashworthiness specifications reshape procurement economics.
Market Dynamics
ICAO's 25-hour cockpit voice recording mandate is compressing replacement cycles fleet-wide, forcing operators to retire serviceable tape-based units before technical end-of-life and reshaping procurement priorities toward crash-survivable solid-state architectures.
Growth Catalysts
- ED-112A Survivability Standards:EUROCAE's updated environmental testing protocols mandate deeper crush resistance and fire immunity, compelling European carriers to accelerate fleet-wide recorder upgrades.
- Unmanned Aerial System Expansion:Military drone procurement programs require lightweight, hardened data recorders for flight test documentation and incident reconstruction, opening parallel demand channels beyond manned aviation.
- Extended Underwater Locator Beacon Duration:ICAO's 90-day minimum battery life specification for submerged aircraft recovery is rendering pre-2015 beacon designs obsolete across international commercial fleets.
Market Restraints
- Semiconductor Supply Concentration:Solid-state memory controller fabrication concentrates in East Asian foundries, exposing recorder manufacturers to single-source disruption risks for radiation-hardened components.
- Titanium Casing Cost Volatility:Crash-survivable housing production depends on aerospace-grade titanium sponge, whose price fluctuation directly compresses margin on low-volume military contracts.
- Magnetic Tape Archive Compatibility:Accident investigation agencies retain legacy tape reading infrastructure, creating friction against full solid-state adoption in certain national aviation authorities.
Strategic Opportunities
- India Narrowbody Production:Airbus and Boeing final assembly line expansion near Bangalore creates localized demand for line-fit recorder systems on A320 and 737 family aircraft.
- Cloud-Based Telemetry Pre-Positioning:Real-time flight data streaming to ground servers is enabling reduced-capacity onboard recorders for certain commercial applications, converging satellite communications with traditional black-box functions.
- Helicopter Offshore Oil Segment:North Sea and Gulf of Mexico rotary-wing operators face distinct crash-survivability requirements, rewarding specialized recorder packaging for autorotation-impact scenarios.
Industry Challenges
- DO-178C Software Certification:Solid-state recorder embedded systems require airborne software assurance at Level A, stretching engineering timelines and talent pools for formal methods verification.
- Retrofit Wiring Integration:Aging commercial aircraft harness architectures lack bandwidth for combined voice-data recorder installations, demanding costly airframe modifications.
- Deep-Sea Recovery Protocol Standardization:Variation in national investigator equipment and training for 6,000-meter retrieval operations complicates unified beacon signal formatting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Flight Recorder Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cockpit Voice Recorder, Flight Data Recorder, Combined Voice and Data Recorder, Underwater Locator Beacon Technology: Solid State, Magnetic Tape, Optical Disk, Hybrid Systems End User: Commercial Aviation, Military Aviation, General Aviation, Business Jets Configuration: Fixed Installations, Portable Devices, Integrated Systems, Remote Monitoring |
| Companies Covered | Safran SA, RUAG Group, Honeywell International Inc., Thales Group, Elbit Systems Ltd., L3Harris Technologies Inc., Leonardo S.p.A, Universal Avionics Systems Corporation, Curtiss-Wright Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Flight Recorder Market Strategic Shifts
Flight recorder architecture is converging around multi-function line-replaceable units that collapse discrete hardware into unified survivable enclosures, compressing installation footprint while expanding data capture scope.
Solid-state memory arrays with ferroelectric RAM buffering are modularizing crash-survivable storage design, enabling manufacturers to separate high-speed data acquisition modules from impact-protected vaults without signal degradation. Commercial narrowbody operators are adopting these split-architecture systems to simplify line maintenance access while preserving deep-sea recovery integrity. The physical separation of volatile and non-volatile storage is modularizing supplier ecosystems, allowing specialized memory vendors to enter without full airframe integration capabilities.
EASA's ED-112A environmental standard is mandating 3,400 G mechanical shock survival and 1,100°C fire exposure duration, eliminating marginal tape-based designs from European-registered aircraft. The regulation's test-sequence rigor is redirecting R&D investment toward ceramic encapsulation and phase-change thermal protection. Rotary-wing and unmanned segments face disproportionate compliance burden due to weight-constrained packaging limits.
Airline technical procurement departments are consolidating recorder sourcing under airframe OEM line-fit agreements, displacing post-delivery aftermarket selection. This channel compression favors integrated avionics suppliers with existing Boeing and Airbus supplier status. The shift is most pronounced among low-cost carriers in Southeast Asia, where fleet standardization overrides best-of-component technical preferences.
Aircraft Flight Recorder Market Segmentation
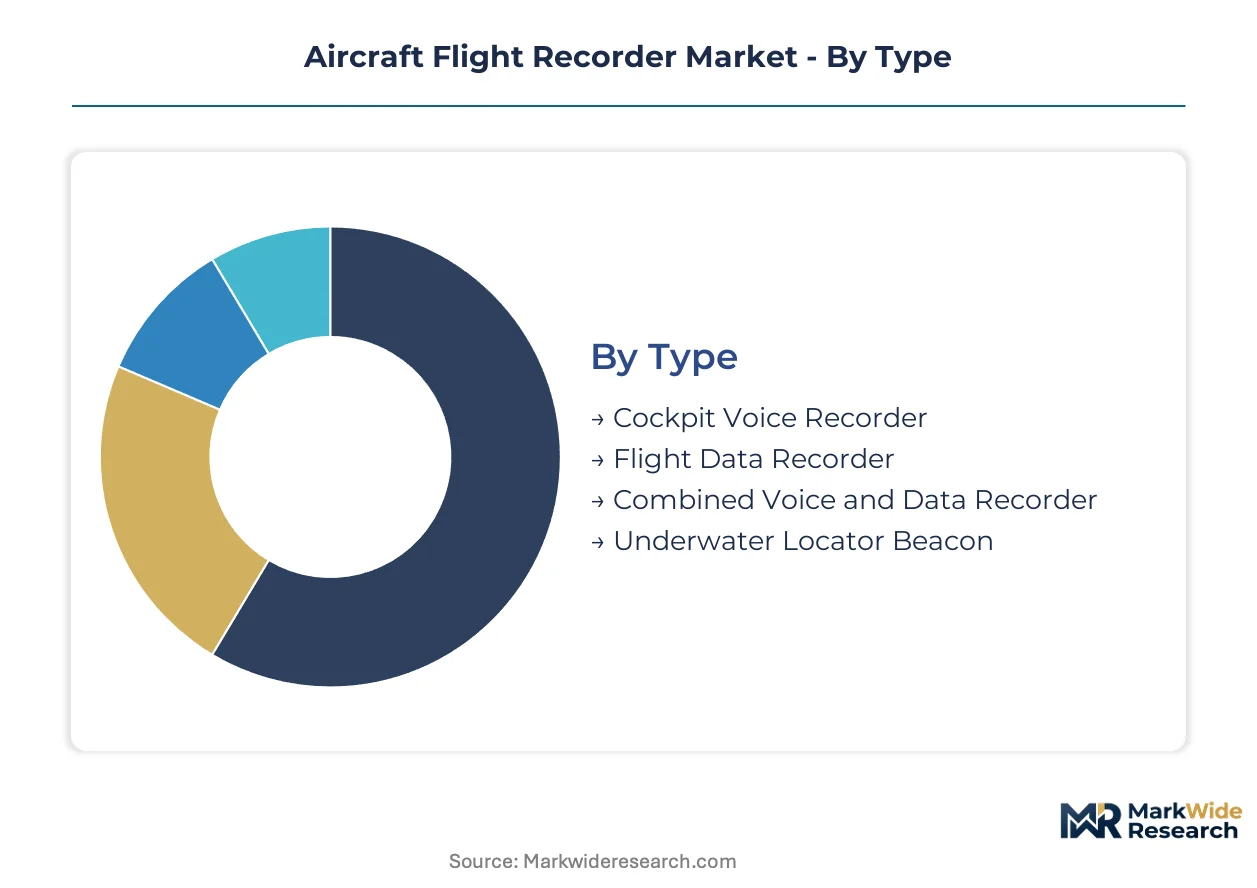
Flight recorder procurement patterns diverge sharply across installation contexts, with regulatory mandates and airframe integration requirements reshaping how buyers evaluate technical specifications. Understanding these segment boundaries clarifies where capital concentrates and which technologies face displacement pressure.
Type:
Volume installations favor single-function units on legacy fleets, while premium configurations command new-production narrowbody and widebody programs.
- Combined Voice and Data Recorder:Unified architectures consolidate cockpit audio and flight parameter capture within single crash-survivable enclosures. Airlines operating Airbus A320neo and Boeing 737 MAX families specify these units to reduce wiring complexity and maintenance access points, driven by EASA and FAA streamlining mandates for new-type certifications.
- Flight Data Recorder:Discrete parameter-logging systems retain substantial installed base across aging commercial fleets where retrofit economics prohibit full system replacement. Demand concentrates in Asia-Pacific cargo operators extending service life of converted freighter aircraft, constrained by airframe modification costs and downtime scheduling.
- Cockpit Voice Recorder:Standalone audio capture units dominate military trainer and helicopter applications where space and weight limits preclude integrated packaging.
- Underwater Locator Beacon:Separate beacon modules persist in retrofit markets and as line-replaceable spares for operators phasing toward integrated designs.
Today's leader: Combined Voice and Data Recorder. Tomorrow's challenger: Cockpit Voice Recorder in specialized rotary-wing configurations.
Technology:
Cost tiers separate crash-survivable solid-state architectures from legacy media requiring specialized readout infrastructure.
- Solid State:Non-volatile flash memory arrays with ferroelectric RAM buffering dominate new-production installations across commercial and military platforms. Shock resistance exceeding 3,400 G and data density advantages drive specification by Boeing and Airbus for line-fit deliveries, with procurement accelerating as ICAO extended-duration mandates render tape systems non-compliant.
- Magnetic Tape:Sequential recording media retains niche presence in certain national aviation authority fleets where accident investigation infrastructure maintains legacy readout capability. Operators in jurisdictions with slower regulatory adoption cycles continue scheduled maintenance of these units, though replacement part availability tightens as manufacturers consolidate production.
- Hybrid Systems:Transitional architectures pairing solid-state acquisition with tape-based archival bridge retrofit timelines for cost-constrained operators.
- Optical Disk:Write-once optical storage occupies minimal remaining share in specific test-flight documentation applications.
Solid State commands current procurement volumes. Hybrid Systems offer the steepest expansion trajectory as retrofit demand peaks ahead of regulatory deadlines.
End User:
Customer type determines survivability specifications, with military programs accepting weight penalties for enhanced hardening.
- Commercial Aviation:Scheduled air carriers and cargo operators constitute the dominant procurement channel, driven by fleet renewal cycles and regulatory compliance timelines. Narrowbody production rates at Airbus and Boeing facilities sustain line-fit demand, while retrofit programs accelerate as 25-hour voice recording mandates compress replacement schedules.
- Military Aviation:Defense procurement programs specify ruggedized designs with enhanced electromagnetic pulse resistance and extended temperature operating ranges. Fighter and transport platforms require specialized packaging, with unmanned system expansion creating parallel demand for miniaturized recorders.
- Business Jets:Corporate and fractional ownership fleets balance certification requirements with cabin space constraints.
- General Aviation:Light aircraft and rotorcraft operators face cost barriers to full recorder installation, with regulatory exemptions limiting addressable market.
Commercial Aviation anchors present revenue. Military Aviation is gaining share fastest as drone procurement scales.
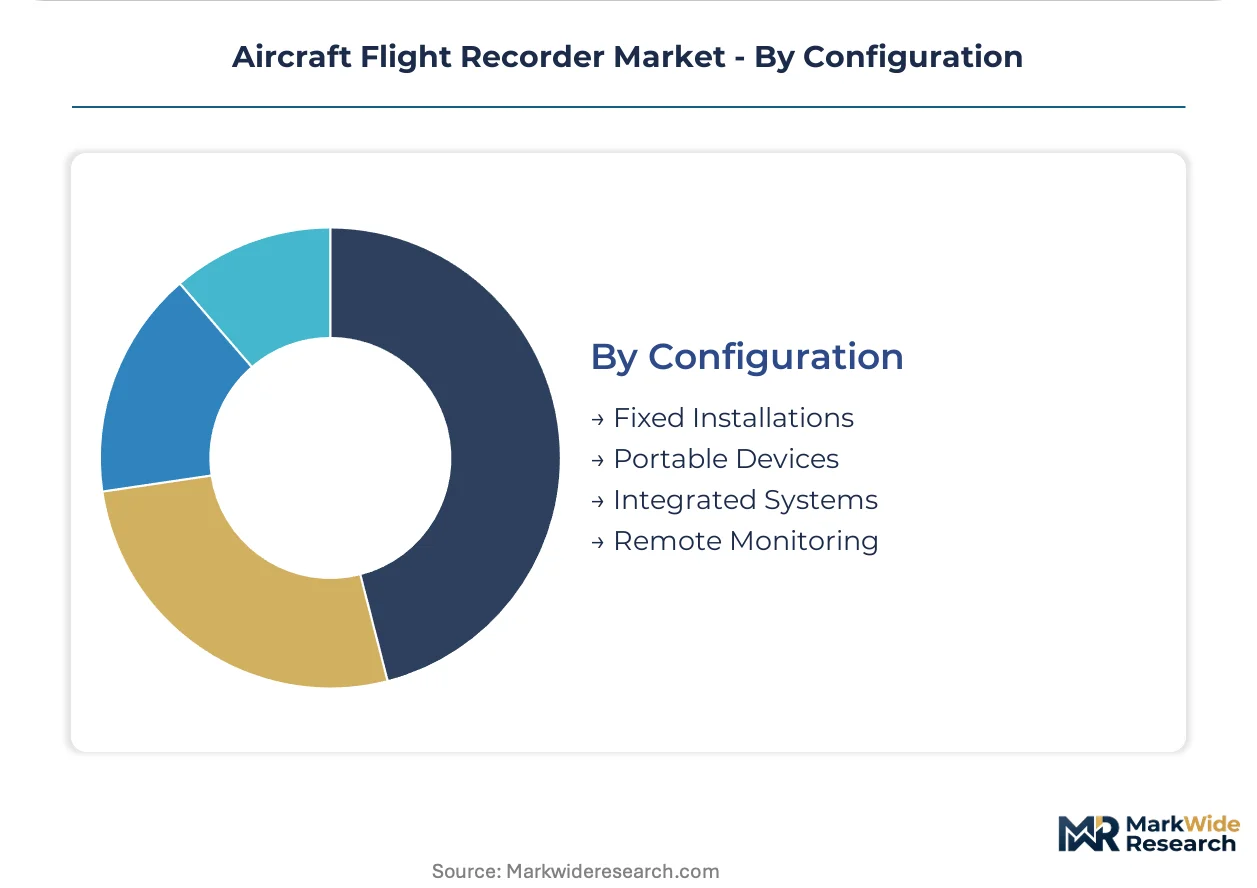
Configuration:
Margin profiles separate integrated OEM line-fit agreements from aftermarket portable and remote alternatives.
- Integrated Systems:Multi-function line-replaceable units combining voice, data, and locator functions within unified enclosures command premium positioning. Airframe OEM supplier status determines competitive access, with Honeywell and L3Harris anchoring positions through existing avionics integration relationships.
- Fixed Installations:Permanent-mount recorder configurations dominate commercial transport category aircraft, with crash-survivable memory vaults installed in tail sections per historical survivability analysis.
- Remote Monitoring:Satellite-linked telemetry systems enabling real-time data streaming to ground infrastructure represent emerging architecture, potentially reducing onboard storage requirements for certain operational profiles.
- Portable Devices:Removable recorders serve flight-test and experimental aircraft applications requiring rapid data retrieval.
Integrated Systems define current procurement economics. Remote Monitoring presents the most significant structural challenge to traditional black-box architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian engineer David Warren invented the first flight data recorder prototype in 1957, establishing the technical lineage that concentrated manufacturing expertise in Anglo-American aerospace clusters before diffusing to European and Asian production centers.
United States
FAA Technical Standard Order mandates for 25-hour cockpit voice recording duration drive fleet-wide replacement cycles at American carriers. The Federal Aviation Administration enforces updated survivability specifications through airworthiness directives that compress procurement timelines. Seattle and Wichita aerospace corridors host integration facilities where Boeing platforms receive line-fit recorder systems.
China
Commercial Aircraft Corporation of China narrowbody production lines generate sustained demand for crash-survivable memory systems on indigenous C919 platforms. The Civil Aviation Administration of China aligns certification requirements with ICAO extended-duration voice recording standards. Shanghai Pudong and Tianjin aviation industrial zones concentrate avionics assembly operations serving domestic fleet expansion.
Germany
EUROCAE ED-112A compliance deadlines pressure Lufthansa Group and Air Berlin successor carriers into accelerated retrofit programs. The Luftfahrt-Bundesamt enforces European Union Aviation Safety Agency environmental testing protocols for mechanical shock and fire immunity. Hamburg and Munich maintenance hubs specialize in combined voice-data recorder installations for Airbus A320 family aircraft.
France
Airbus final assembly lines at Toulouse-Blagnac anchor European demand for integrated black-box systems on A350 and A320neo programs. The Direction Générale de l'Aviation Civile mandates ED-112A certification for all newly registered commercial aircraft. Grenoble aerospace electronics cluster hosts specialized facilities for underwater locator beacon battery system manufacturing.
India
Airbus and Boeing final assembly expansion near Bangalore creates localized procurement channels for line-fit recorder installations on export-bound narrowbodies. The Directorate General of Civil Aviation implements ICAO Global Aeronautical Distress and Safety System timelines for extended beacon duration. Hyderabad and Bengaluru defense-aerospace corridors develop indigenous recorder capabilities for military unmanned aerial system programs.
Aircraft Flight Recorder Market Competitive Environment
The competitive structure tilts toward integrated avionics conglomerates with established airframe OEM supplier status. Consolidation around multi-function line-replaceable units favors players with existing Boeing and Airbus certification relationships. Three archetypes dominate: diversified aerospace-electronics conglomerates, defense-specialized ruggedization experts, and crash-survivable memory module specialists. Competitive moves center on strategic partnerships for satellite telemetry integration and portfolio diversification into unmanned system applications.
Among diversified conglomerates, Safran SA and Thales Group exemplify the integrated avionics archetype with French aerospace heritage. Honeywell International Inc. occupies a position bridging commercial and defense procurement channels. L3Harris Technologies Inc. represents the defense-specialized tier, while Curtiss-Wright Corporation anchors the crash-survivable memory specialist segment. These three named entities collectively illustrate how supplier positioning stratifies across airframe integration depth and end-use ruggedization requirements.
| Leading Market Players |
|---|
| Safran SA |
| RUAG Group |
| Honeywell International Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| L3Harris Technologies Inc. |
| Leonardo S.p.A |
| Universal Avionics Systems Corporation |
| Curtiss-Wright Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ED-112A-compliant crash-survivable systems and legacy tape-based architectures manifests in divergent pricing power and sourcing complexity. Premium-tier solid-state recorders command substantial markups through Boeing and Airbus line-fit channels, while commodity retrofit segments face margin compression from semiconductor supply constraints and titanium casing cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates airframe OEM line-fit agreements from aftermarket retrofit installations and military ruggedized specifications. Price differentiation hinges on EUROCAE certification tier and volume scale, with narrowbody production contracts securing favorable unit economics against one-off helicopter or business jet orders. Cost compression in the retrofit tier is intensifying because magnetic tape component availability tightens as manufacturers consolidate production. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while defense procurement programs demonstrate lowest elasticity due to survivability mandates.
Supply Chain Analysis
Domestic-content mandates in China and India are reshaping sourcing patterns for crash-survivable memory modules and underwater locator beacon assemblies. Geographic supply concentration centers on the United States, China, and Germany for final integration, with South Korea and Taiwan anchoring solid-state memory controller fabrication. Raw material dependencies draw from aerospace-grade titanium sponge, radiation-hardened semiconductor wafers, and high-temperature ceramic encapsulants. Single-source vulnerability in East Asian foundries for radiation-hardened components presents structural supply chain risk. Distribution runs through airframe OEM supplier networks and defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through solid-state technology substitution and regulatory-mandated replacement cycles that compress buyer negotiation leverage.
For Market Incumbents: Deepen backward integration into solid-state memory module production to offset semiconductor supply concentration risks. Anchor certification investment in ED-112A and FAA Technical Standard Order compliance to defend against emerging modular suppliers entering without full airframe integration capabilities. Prioritize channel control through Boeing and Airbus supplier status renewals. For New Entrants and Emerging Players: Enter via specialized underwater locator beacon battery systems and helicopter autorotation-impact recorder packaging where incumbent coverage remains thin. Target North Sea and Gulf of Mexico offshore oil rotary-wing operators as the most penetrable segment. Pursue go-to-market angles through MRO channel partnerships rather than direct OEM line-fit competition. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented crash-survivable memory specialists lack airframe integration depth and face DO-178C software certification talent scarcity. Long-term viability favors vertically integrated avionics conglomerates with defense and commercial dual-channel presence. Acquisition target archetypes include modular memory vendors with ferroelectric RAM buffering capabilities. Watch satellite-linked telemetry adoption rates as inflection indicator for traditional black-box architecture displacement.| Strategic Initiative | Industry Significance |
|---|---|
| ED-112A Certification Investment | Secures European market access as EASA enforces environmental testing protocols. |
| Solid-State Memory Backward Integration | Reduces single-source dependency on East Asian radiation-hardened component foundries. |
| Helicopter Specialization Development | Captures North Sea offshore oil segment with autorotation-impact survivable packaging. |
| Satellite Telemetry Partnership | Positions for cloud-based pre-positioning convergence with traditional black-box functions. |
| India Narrowbody Line-Fit Expansion | Localizes procurement for Airbus and Boeing Bangalore final assembly operations. |
Study Parameters
Direct dialogue with avionics procurement directors, flight test engineers, MRO maintenance planners, and regulatory certification specialists grounded qualitative assessment, supplemented by FAA airworthiness directive filings, EUROCAE ED-112A documentation, ICAO GADSS implementation timelines, and customs trade data for aerospace electronics. Secondary validation drew from SEC 10-K disclosures of listed avionics suppliers and narrowbody production rate announcements from Airbus and Boeing. Bottom-up and top-down triangulation cross-checked segment-level demand against fleet renewal projections.
Installed base replacement schedules and new-production line-fit ratios across the projection horizon fed quantitative segmentation by recorder type, technology tier, end-user category, and configuration format. CAGRs were derived from regression analysis against regulatory deadline compression and fleet age distribution curves. Industry-specific forecast inputs incorporated 25-hour cockpit voice recording mandate adoption curves and unmanned aerial system procurement scaling assumptions.
Inputs from airframe OEM production planners and defense procurement officers were available through the study window; gaps in classified military program timelines introduce uncertainty bands around the unmanned segment trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and semiconductor supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market