
 Wireless in-Flight Entertainment Market | 2026-2036
Wireless in-Flight Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless in-Flight Entertainment Market Intelligence
Seatback-to-streaming unbundling is consolidating buyer choice around modular hardware packages that airlines can phase in without full cabin overhauls. Panasonic Avionics Corporation leverages its satellite antenna manufacturing to sustain end-to-end system control from content delivery to airborne hardware. Thales Group anchors European carrier relationships through avionics integration expertise that spans flight management and passenger-facing systems. Gogo LLC competes aggressively in the North American narrowbody retrofit segment where bandwidth economics favor its air-to-ground network architecture.
Wireless in-flight entertainment comprises cabin-area networks that distribute cached or live-streamed media to passenger devices through onboard servers, access points, and satellite or terrestrial data links operating at frequencies typically between 2.4 GHz and 5.9 GHz depending on protocol. The primary commercial purpose centers on monetizing passenger dwell time through tiered connectivity sales, advertising inventory, and operational data collection that feeds airline loyalty programs. Streaming Services and Personal Devices together capture the fastest expansion as hardware-light deployment models reduce per-seat installation costs and accelerate fleet-wide rollout timelines. Wi-Fi 6 technology leads technology segmentation for new installations given its higher spectral efficiency in dense cabin environments, while Satellite Data Links retain critical importance for transoceanic routes beyond terrestrial coverage footprints.
FAA certification requirements for airborne connectivity equipment govern hardware approval timelines in the United States, while EASA's continuing airworthiness regulations shape European retrofit standards and interoperability mandates. The EU AI Act and GDPR frameworks increasingly influence how passenger viewing data and behavioral analytics may be collected, stored, and monetized across European-registered aircraft. Stakeholders must monitor spectrum reallocation proceedings at national regulators and satellite operator merger activity that could reshape bandwidth pricing and availability for airborne services.
Market Dynamics
Airlines are dismantling seatback hardware architectures in favor of bring-your-own-device streaming models, compressing installation timelines from years to months and redistributing capital from fixed cabin assets to bandwidth procurement.
Growth Catalysts
- Wi-Fi 6 spectral efficiency:Dense cabin environments demand higher throughput per access point. Wi-Fi 6 protocols reduce interference between passenger devices during peak boarding and deplaning windows.
- FAA portable electronic device guidance:Evolving FAA guidelines accelerate certification timelines for airborne connectivity hardware, shortening deployment cycles for retrofit fleets.
- Advertising inventory monetization:Airlines capture passenger dwell time through targeted pre-roll and sponsored content placements, creating ancillary revenue streams independent of ticket pricing.
Market Restraints
- Satellite bandwidth cost volatility:Transoceanic routes depend on geostationary and LEO satellite capacity where operator consolidation threatens pricing stability for airborne data links.
- Terrestrial network coverage gaps:Air-to-ground architectures face physical limitations over water and remote terrain, fragmenting service consistency across route networks.
- GDPR passenger data constraints:European-registered aircraft face strict limits on behavioral analytics collection, constraining personalization algorithms that drive advertising yield.
Strategic Opportunities
- Indian aviation expansion:Domestic carriers operate growing narrowbody fleets with minimal legacy seatback infrastructure, enabling greenfield wireless deployment without retrofit complexity.
- 5G-ATG spectrum convergence:Terrestrial 5G networks and airborne terminals are converging, promising latency reductions for real-time gaming and video conferencing applications.
- PLI scheme manufacturing incentives:India's production-linked incentive schemes for electronics manufacturing attract cabin hardware assembly, reducing import dependency for regional carriers.
Industry Challenges
- Airworthiness certification bottlenecks:STC approvals for modified cabin configurations consume 12-18 months, delaying fleet-wide rollouts and compressing revenue realization windows.
- Legacy IFE integration complexity:Hybrid fleets mixing seatback and streaming systems require redundant content licensing and maintenance training, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless in-Flight Entertainment Market |
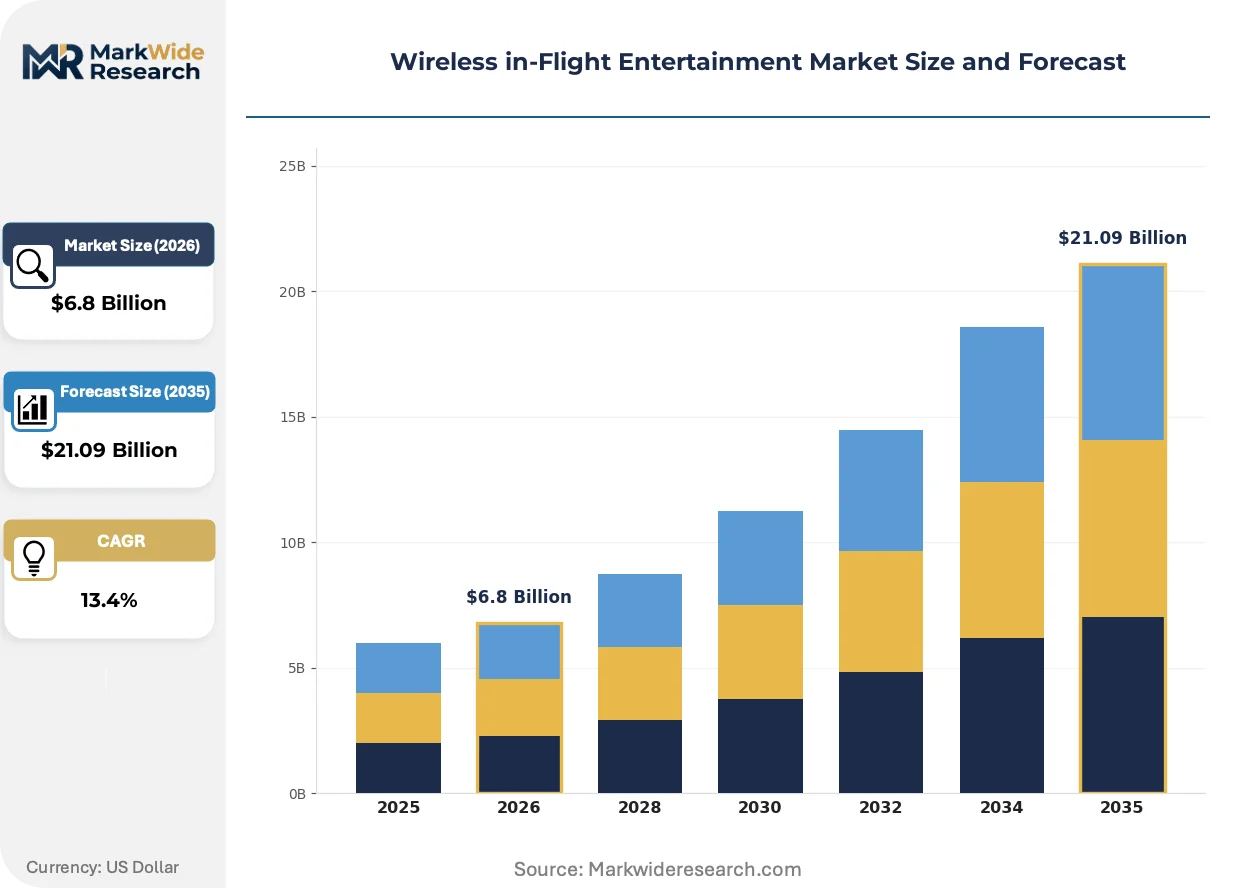
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Seatback Screens, Personal Devices, Connectivity Modules, Media Servers Technology: Wi-Fi 6, Satellite Data Links, Bluetooth, Near Field Communication, LTE Application: Passenger Entertainment, Flight Information Display, Advertising Services, Cabin Crew Communication, On-Demand Content End User: Commercial Airlines, Private Charter Operators, Military Aviation, Corporate Flight Departments, Aero Maintenance Providers |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Gogo LLC, Collins Aerospace, Anuvu, Astronics Corporation, Burrana Pty Ltd, Lufthansa Systems GmbH, Bluebox Avionics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless in-Flight Entertainment Market Strategic Shifts & Innovations
Streaming architectures are collapsing the traditional hardware-software boundary in cabin entertainment, forcing suppliers to restructure around bandwidth provisioning rather than physical media distribution.
LEO satellite constellations are expanding into aviation connectivity, delivering lower-latency links than geostationary alternatives. Low-cost carriers in Southeast Asia adopt these terminals aggressively to avoid seatback installation costs. The technology is expanding into long-haul narrowbody routes previously considered uneconomical for satellite service.
EASA continuing airworthiness regulations now mandate interoperability testing between European-registered aircraft and multi-orbit satellite networks. This forces hardware vendors to certify dual-band terminals capable of switching between LEO and GEO constellations mid-flight. Widebody operators on transatlantic routes face the steepest compliance timelines.
Passenger willingness-to-pay patterns are fragmenting across demographic and route-type lines. Business travelers on transcontinental routes purchase premium connectivity tiers at rates three times higher than leisure passengers on short-haul segments. Airlines respond with dynamic pricing algorithms that adjust bandwidth tier pricing based on departure time and destination type, with North American carriers leading deployment of these systems.
Wireless in-Flight Entertainment Market Segmentation
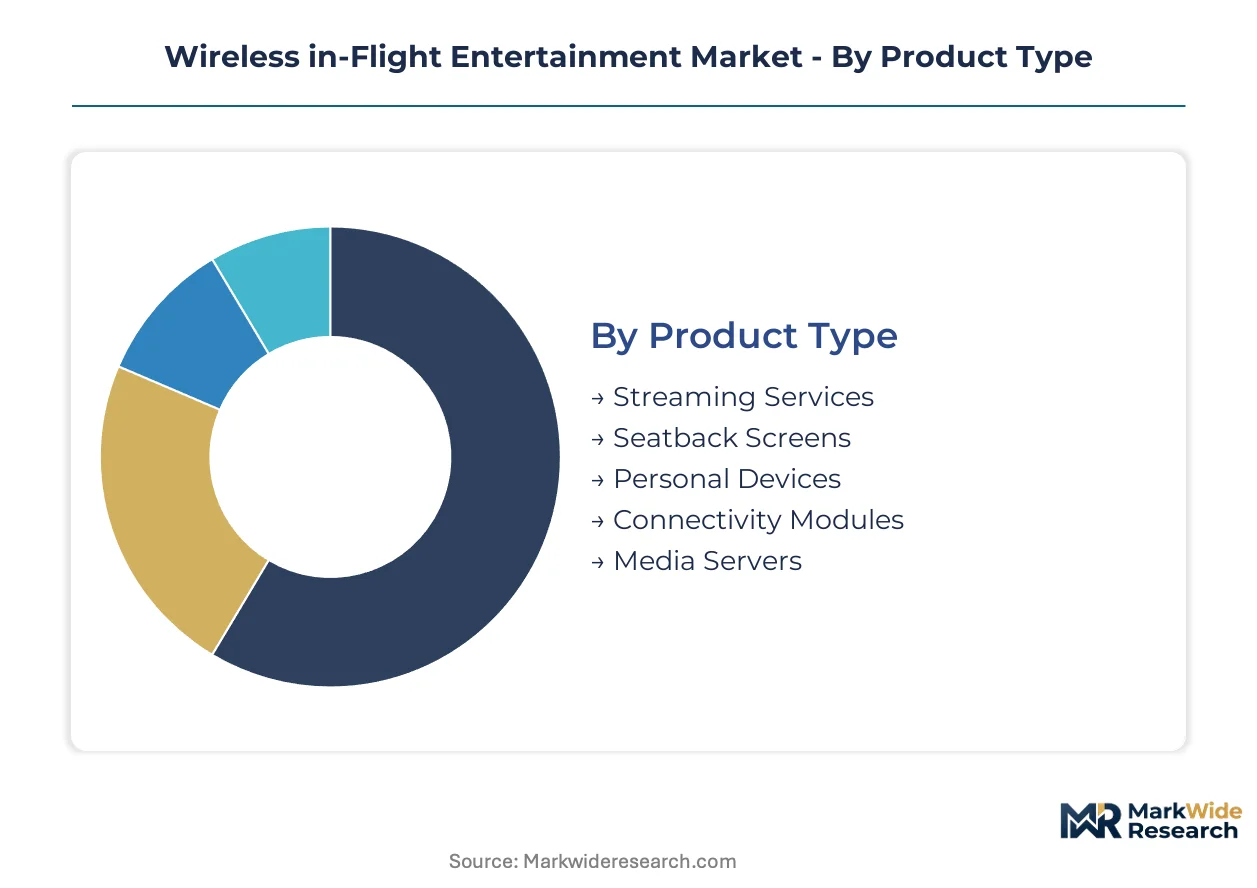
Wireless in-flight entertainment segmentation reveals how airlines balance passenger experience investment against fleet retrofit complexity and route-specific connectivity economics. Each category exposes different pressure points between hardware durability, bandwidth procurement costs, and regulatory certification timelines.
Product Type:
Customization intensity varies sharply across this category, from standardized streaming software deployments to bespoke seatback integration requiring airframe-specific STC approvals.
- Streaming Services:Cloud-hosted content platforms deliver cached media libraries and live channels to passenger devices without dedicated cabin hardware. Demand concentrates among North American low-cost carriers retrofitting narrowbody fleets where minimizing downtime drives procurement decisions.
- Personal Devices:BYOD frameworks leverage passenger smartphones and tablets as display endpoints, reducing per-seat capital expenditure. Airlines in India favor this model for greenfield narrowbody deployments where legacy seatback infrastructure never existed.
- Seatback Screens:Integrated displays with embedded processors and storage for offline content playback.
- Connectivity Modules:Compact satellite or ATG transceivers mounting on aircraft exterior structures.
- Media Servers:Onboard storage and distribution hardware caching licensed content for local streaming.
Leading the category by volume: Personal Devices. Growing fastest: Streaming Services.
Technology:
Spectral efficiency and coverage footprint trade-offs divide this category between terrestrial architectures with lower latency and satellite systems reaching transoceanic routes.
- Wi-Fi 6:IEEE 802.11ax protocols deliver higher throughput density in crowded cabin environments through orthogonal frequency-division multiple access. New installations across United States domestic fleets favor this standard for its interference resilience during peak boarding windows.
- Satellite Data Links:Ku-band and Ka-band terminals connect to geostationary or LEO constellations for beyond-territorial-water coverage. EASA interoperability mandates now require dual-band terminals capable of switching between LEO and GEO networks mid-flight.
- Bluetooth:Short-range wireless pairing passenger headphones to seatback or streaming interfaces.
- Near Field Communication:Contactless protocols enabling quick device pairing and payment authentication.
- LTE:Cellular-derived air-to-ground links operating in licensed aviation spectrum bands.
Dominant by deployment share: Wi-Fi 6. Expanding most quickly: Satellite Data Links.
Application:
Revenue model differentiation separates this category between direct passenger monetization and indirect value capture through advertising or operational efficiency.
- Passenger Entertainment:Movie, television, and audio streaming services form the core revenue-generating application. Premium tier purchases on transcontinental routes generate three times the attachment rates versus short-haul leisure segments.
- Advertising Services:Targeted pre-roll placements and sponsored content insertion create ancillary revenue independent of connectivity subscription sales. GDPR constraints on European-registered aircraft limit behavioral targeting precision.
- Flight Information Display:Real-time route mapping, arrival estimates, and connection updates pushed to passenger screens.
- Cabin Crew Communication:Internal messaging and service coordination tools replacing intercom-dependent workflows.
- On-Demand Content:Transactional premium titles and destination-specific programming outside base subscription libraries.
Highest revenue concentration: Passenger Entertainment. Steepest expansion trajectory: Advertising Services.
End User:
Fleet scale and procurement sophistication create divergent requirements across this category, from standardized narrowbody retrofits to highly customized VIP cabin installations.
- Commercial Airlines:Scheduled passenger carriers operating fleet-wide connectivity programs with standardized hardware configurations. Major United States network carriers drive volume through large retrofit orders spanning hundreds of aircraft.
- Private Charter Operators:On-demand aviation services configuring cabin systems around individual client preferences. These operators prioritize seamless streaming integration with personal device ecosystems over fixed hardware investments.
- Military Aviation:Defense transport and command aircraft with hardened connectivity requirements and classified network isolation.
- Corporate Flight Departments:Company-owned aircraft serving executive travel with premium bandwidth provisioning.
- Aero Maintenance Providers:Third-party MRO facilities installing and certifying connectivity hardware during scheduled heavy checks.
Commanding procurement volume: Commercial Airlines. Gaining share fastest: Private Charter Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for electronics manufacturing in Southeast Asia and the Indian subcontinent are accelerating wireless cabin system assembly, while established aerospace clusters in France and the United States retain design and certification authority.
United States
Domestic carriers operate the world's largest narrowbody retrofit programs, driving demand for modular streaming hardware that minimizes aircraft downtime. FAA certification timelines for supplemental type certificates shape deployment schedules, with recent guidance compressing portable electronic device approval windows. Seattle-Tacoma aerospace corridor hosts concentrated avionics engineering talent supporting connectivity system integration.
India
Greenfield narrowbody fleets from IndiGo and Akasa Air adopt bring-your-own-device frameworks without legacy seatback infrastructure to dismantle. PLI scheme incentives for electronics manufacturing attract cabin hardware assembly to Karnataka and Tamil Nadu, reducing import dependency for regional carriers. Bangalore's aviation technology cluster is expanding software development for streaming content platforms.
Germany
Lufthansa Group's fleet standardization requirements sustain demand for integrated connectivity-entertainment systems across mixed narrowbody and widebody operations. EASA continuing airworthiness regulations mandate interoperability testing with multi-orbit satellite networks, forcing hardware recertification for dual-band terminals. Hamburg's aircraft interiors cluster specializes in retrofit engineering for European carrier fleets.
France
Airbus delivery schedules for long-haul widebodies embed factory-installed connectivity modules, creating bundled procurement channels for satellite terminal manufacturers. EU AI Act and GDPR frameworks constrain passenger behavioral data collection, limiting advertising yield optimization algorithms. Toulouse aerospace corridor concentrates satellite antenna engineering for aviation applications.
United Kingdom
British Airways and Virgin Atlantic transatlantic routes require seamless LEO-GEO satellite handoff capabilities under EASA mandates, driving premium terminal specifications. CAA alignment with EASA certification standards streamlines hardware approval for European-registered aircraft operating UK bases. London Gatwick aviation services cluster supports connectivity system maintenance for low-cost carrier fleets.
Wireless in-Flight Entertainment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software platforms, and bandwidth provisioning. Tier-one suppliers consolidate around end-to-end system integration, while regional specialists capture narrowbody retrofit niches. Strategic archetypes include satellite antenna manufacturers extending into cabin distribution, avionics integrators leveraging flight management expertise, and air-to-ground network operators optimizing terrestrial bandwidth economics. Dominant competitive moves center on airworthiness certification partnerships and spectrum acquisition positioning.
Within the diversified technology tier, Panasonic Avionics Corporation and Thales Group exemplify vertically integrated suppliers controlling hardware manufacturing through content delivery. Gogo LLC occupies a distinct position as a connectivity-focused specialist with concentrated North American narrowbody presence. Among European system integrators, Lufthansa Systems GmbH and Bluebox Avionics Ltd represent regional specialists serving carrier-specific requirements.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Gogo LLC |
| Collins Aerospace |
| Anuvu |
| Astronics Corporation |
| Burrana Pty Ltd |
| Lufthansa Systems GmbH |
| Bluebox Avionics Ltd |
| Others |
Cost & Logistics Intelligence
EASA continuing airworthiness regulations for multi-orbit satellite interoperability gate qualified supply of dual-band terminals and reserve premium-tier pricing access for vendors with completed STC certifications. Airlines face compressed procurement timelines as these mandates accelerate hardware refresh cycles while bandwidth procurement costs reshape total cost of ownership calculations across fleet deployment programs.
Pricing Analysis
Margin tightening in connectivity hardware reflects satellite operator consolidation and the shift from seatback capital expenditure to recurring bandwidth subscriptions. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling, with EASA STC completion commanding substantial premiums. Cost-down pressure on ATG terminal installations accelerates as Gogo LLC and Anuvu compete for narrowbody retrofit contracts. Low-cost carriers exhibit highest price sensitivity, while corporate flight departments prioritize performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale commercial airline demand, while specialized distributors serve private charter and corporate flight departments with customized configurations. Manufacturing concentrates in the United States, France, and India, with Bangalore and Toulouse aerospace corridors anchoring software development and antenna engineering respectively. Component sourcing draws from Taiwan for semiconductor content, Japan for precision RF components, and domestic suppliers for mechanical assemblies. Single-source vulnerability in LEO satellite terminal chipsets poses structural risk given concentrated foundry capacity. Distribution runs through airframe OEM integration lines for factory-fit installations and MRO networks for retrofit deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Streaming architectures are displacing legacy seatback hardware as the dominant cabin entertainment paradigm, compressing installation timelines and redirecting capital toward bandwidth procurement rather than fixed physical assets.
For Market Incumbents: Extend certification partnerships with EASA and FAA to accelerate STC timelines for dual-band satellite terminals before interoperability mandates harden compliance requirements. Deepen backward integration into antenna manufacturing to defend margin position against LEO constellation operators entering direct terminal sales. Prioritize software platform stickiness through loyalty program data integration that survives hardware refresh cycles.
For New Entrants and Emerging Players: Cloud-native content delivery platforms offer a technology-first wedge into the Indian narrowbody greenfield segment where legacy seatback infrastructure never existed. Target domestic carriers operating PLI scheme-supported fleets with modular BYOD frameworks that minimize certification burden. Pursue white-label partnerships with regional MRO providers lacking in-house streaming platform development capability.
For Investors and Strategic Acquirers: FAA guidance publication accelerating portable electronic device approval windows is the leading indicator that certification velocity will differentiate vendor market share capture over the projection horizon. Acquisition target archetypes include specialized software platforms with airline content licensing relationships and ATG network operators with concentrated narrowbody footprints. Monitor satellite operator merger announcements as inflection signals for bandwidth pricing volatility that reshapes hardware vendor profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Band Terminal Certification | EASA interoperability mandates force hardware recertification investments that consolidate vendor positioning. |
| LEO Constellation Partnership | Lower-latency satellite links enable real-time applications that differentiate premium connectivity tiers. |
| BYOD Platform Licensing | Software-only deployments reduce airline capital burden while capturing recurring content distribution revenue. |
| PLI Manufacturing Localization | Indian electronics incentives attract assembly capacity that reduces import dependency for regional carriers. |
| Advertising Yield Optimization | Passenger behavioral analytics integration creates ancillary revenue streams independent of subscription sales. |
Research Approach
Document review covered FAA certification filings, EASA continuing airworthiness directives, satellite operator spectrum allocation proceedings, and airline fleet deployment announcements, complemented by interviews with avionics engineering directors, airline procurement executives, MRO facility managers, and connectivity platform product leads. Secondary validation drew from customs trade data for cabin hardware imports, SEC filings of publicly traded satellite operators, and aviation regulatory dockets. Bottom-up triangulation across installation unit economics and top-down validation against carrier fleet size data ensured cross-verified market sizing.
Segment-level outputs across the modeling period reflect product type disaggregation between streaming services and personal device frameworks, technology segmentation spanning Wi-Fi 6 and satellite data link architectures, application splits between passenger entertainment and advertising services, and end-user differentiation across commercial airlines and private charter operators. CAGRs were derived from logistic diffusion curves fitted to fleet retrofit completion rates and greenfield deployment schedules. Industry-specific forecast inputs incorporated EASA STC approval timeline distributions and LEO constellation launch cadence projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated satellite operator consolidation or extended FAA certification delays for multi-orbit terminal designs. Forecasts reflect assumptions regarding passenger willingness-to-pay elasticity and airline capital allocation priorities between hardware and bandwidth expenditure. Periodic stress-testing of base assumptions is recommended against regulatory timeline shifts and spectrum reallocation proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Towbars Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Hangar Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Airship Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Aircraft Radome Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Aircraft Leasing Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Active Air Deflector Market