
 Flight Data Monitoring and Analysis (FDMA) Market | 2026-2036
Flight Data Monitoring and Analysis (FDMA) Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Data Monitoring and Analysis (FDMA) Market Insights
Modular component unbundling is decoupling hardware acquisition from software subscription tiers, giving fleet operators granular procurement control. Teledyne Controls leverages its embedded data acquisition heritage to anchor long-term service contracts with legacy aircraft operators. GE Aerospace competes through vertical integration into engine health monitoring, bundling FDMA outputs with predictive maintenance workflows. Safran Electronics & Defense specializes in military-grade secure data links, occupying a defensible niche in defense aviation procurement cycles.
Flight Data Monitoring and Analysis encompasses the systematic capture, transmission, and interpretation of aircraft sensor outputs—typically sampling parameters at rates exceeding 64 words per second per flight recorder—to enable operational safety oversight and performance diagnostics. The primary commercial purpose centers on transforming raw flight parameter streams into actionable intelligence for risk mitigation and operational efficiency. Real-time monitoring systems command premium positioning due to latency-critical safety applications, while predictive analytics platforms represent the fastest-expanding segment as carriers pursue condition-based maintenance transitions. Post-flight analysis software retains mature, stable demand among smaller operators with limited real-time infrastructure budgets.
The FAA mandates flight operational quality assurance programs under 14 CFR Part 121, compelling scheduled carriers to maintain continuous monitoring capabilities as a condition of operating authority. EASA implements parallel requirements through its EU-OPS framework, with additional CSRD disclosure obligations pressing European operators toward auditable data governance architectures. Stakeholders must monitor evolving cybersecurity certification standards for connected aircraft systems, as regulatory bodies on both sides of the Atlantic harden data integrity requirements for cloud-connected flight recorders.
Market Dynamics
Predictive analytics platforms are compressing maintenance cycles across commercial aviation, forcing legacy post-flight analysis vendors to rearchitect subscription models or cede market position to real-time monitoring specialists.
Growth Catalysts
- 14 CFR Part 121 FOQA Mandates:FAA flight operational quality assurance requirements compel scheduled US carriers to maintain continuous monitoring infrastructure, creating baseline demand for certified recording systems.
- Engine Health Telemetry Convergence:Turbofan sensor data streams now integrate with airframe parameter logs, enabling unified fleet diagnostics that reduce unscheduled engine removals.
- Condition-Based Maintenance Transition:Commercial airlines in the United States are retiring calendar-based overhaul schedules in favor of usage-indexed interventions, driving predictive platform procurement.
Market Restraints
- Semiconductor Supply Concentration:Specialized flight recorder processors depend on Taiwanese foundry capacity, exposing lead times to geopolitical disruption risks.
- CSRD Disclosure Compliance Burden:European operators face auditable data governance architecture requirements that extend procurement cycles and inflate systems integration costs.
- Legacy Analog Fleet Persistence:Thousands of regional turboprops lack digital quick access recorders, fragmenting addressable market for unified software platforms.
Strategic Opportunities
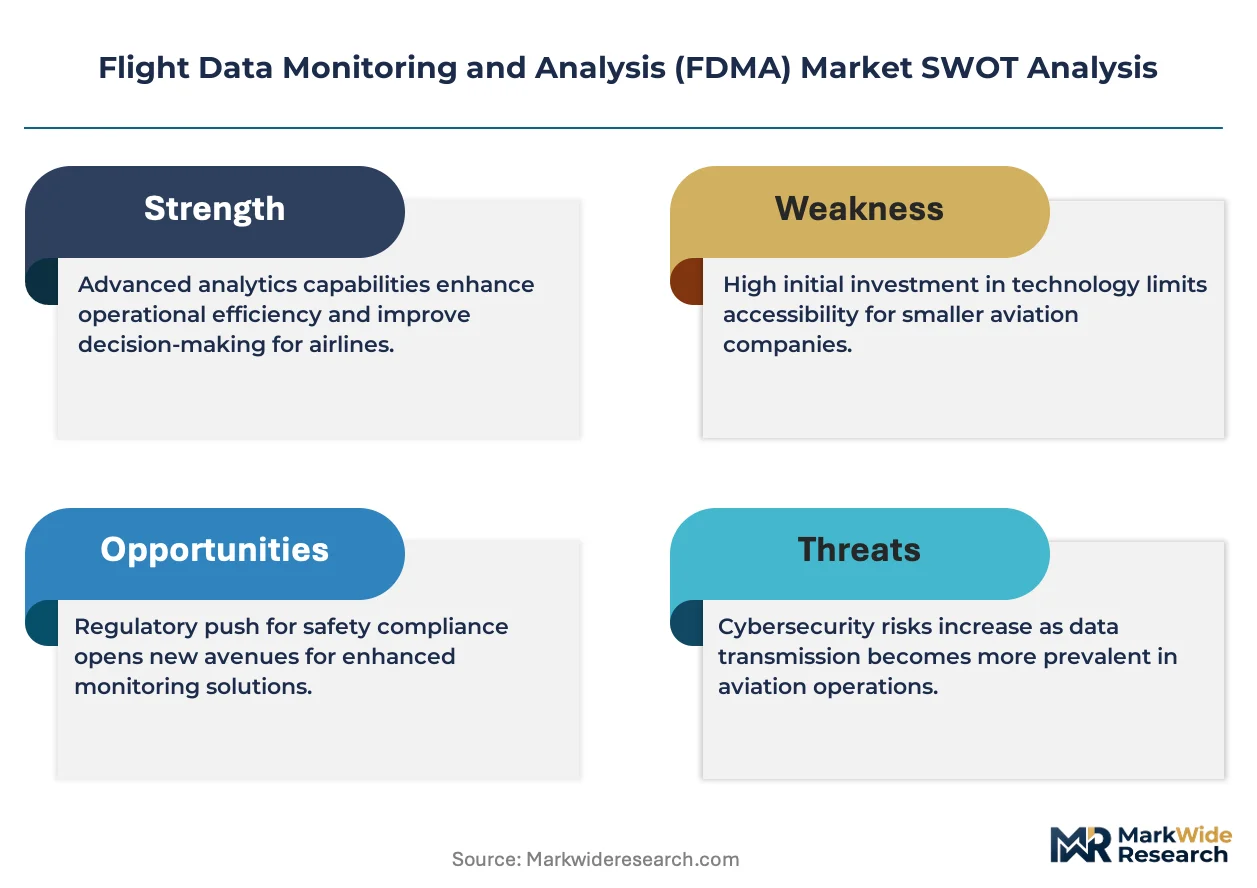
- EU-OPS Cybersecurity Certification Gap:EASA's pending connected aircraft data integrity standards create first-mover advantage for vendors with pre-certified cloud transmission architectures.
- Urban Air Mobility Sensor Fusion:eVTOL platforms require novel lightweight parameter logging systems, opening design-win competitions absent entrenched incumbents.
- Performance-Based Navigation Analytics:RNP-AR approach data exploitation remains underdeveloped, offering monetizable fuel efficiency insights for network carriers.
Industry Challenges
- Flight Data Analyst Talent Scarcity:Operators struggle to recruit personnel combining aviation domain knowledge with Python-based statistical modeling competencies.
- Multi-Generational Fleet Integration:Mixed fleets spanning ARINC 573, 717, and 664 networks force expensive middleware development for unified monitoring dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Data Monitoring and Analysis (FDMA) Market |
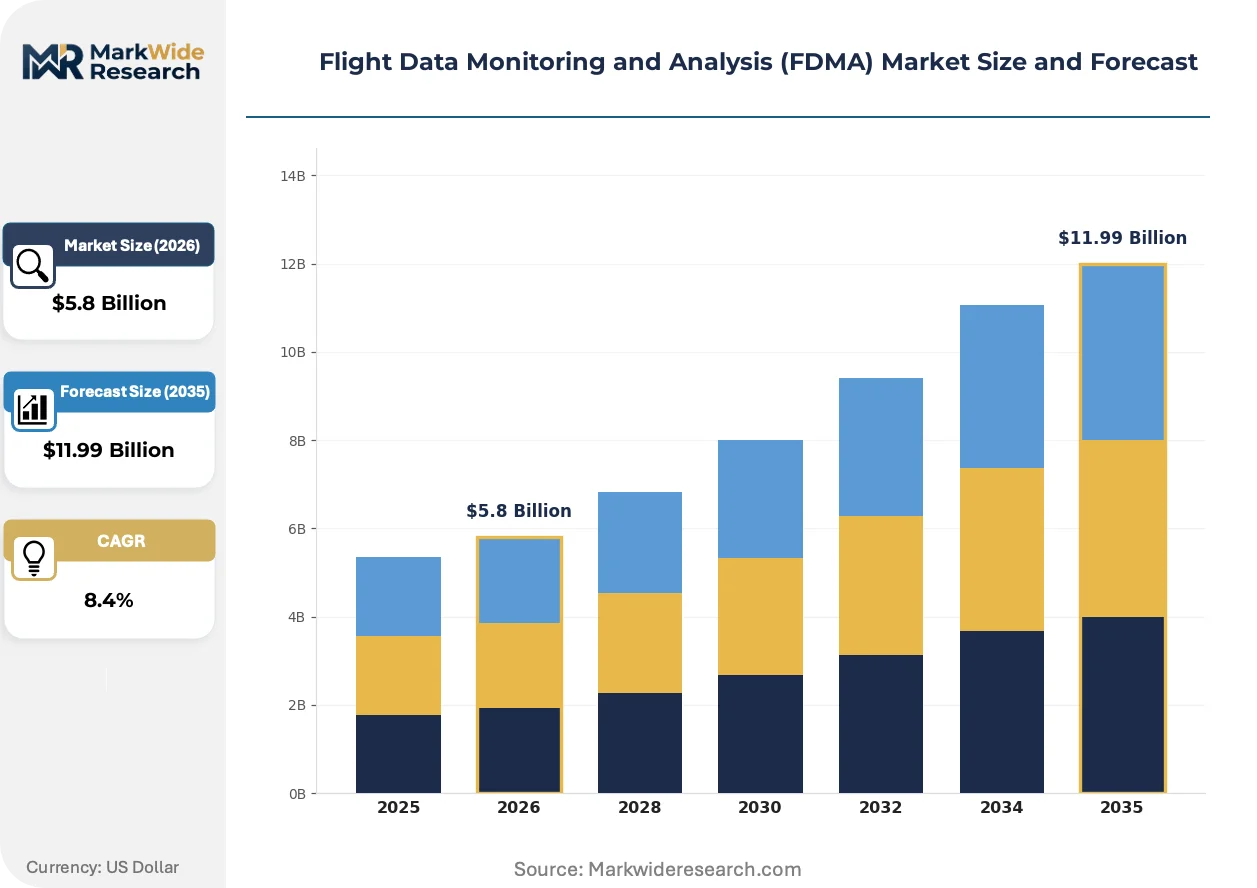
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Monitoring Systems, Post-Flight Analysis Software, Automated Reporting Tools, Predictive Analytics Platforms Application: Safety Compliance, Flight Performance Optimization, Maintenance Prediction, Pilot Training Support End User Industry Vertical: Commercial Airlines, Cargo Operators, Airport Authorities, Flight Schools Deployment: Onboard Systems, Cloud-Based Platforms, Hybrid Solutions, Ground-Based Analysis Centers |
| Companies Covered | Teledyne Controls, GE Aerospace, Honeywell International Inc, Leonardo S.p.A, Collins Aerospace, Safran Electronics & Defense, Curtiss-Wright Corporation, Flight Data Services Ltd, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Data Monitoring and Analysis (FDMA) Market Trends and Innovations
Edge computing architectures are redistributing analytical workloads from ground servers to airborne processors, compressing latency for safety-critical event detection while complicating certification pathways.
Machine learning inference engines are expanding into flight data recorders, enabling real-time exceedance detection without ground station dependency. Regional carriers with limited IT infrastructure adopt these embedded systems fastest, bypassing expensive terrestrial network builds. The technology is expanding into predictive turbulence alerting, compressing reactive flight planning cycles.
EASA's EU-OPS framework amendments are hardening data integrity requirements for cloud-connected recorders, mandating end-to-end encryption and audit trail preservation. European operators must revalidate existing supplier contracts against emerging certification baselines. Military-grade secure data link specialists capture disproportionate share of defense aviation procurement as dual-use standards converge.
After-sales service unbundling is fragmenting traditional hardware-software bundles, with fleet operators procuring quick access recorder hardware separately from analytics subscriptions. Tier-two carriers leverage this flexibility to pilot multiple software vendors before enterprise commitments. The pattern is most visible among US fractional ownership fleets managing heterogeneous aircraft types.
Flight Data Monitoring and Analysis (FDMA) Market Segmentation
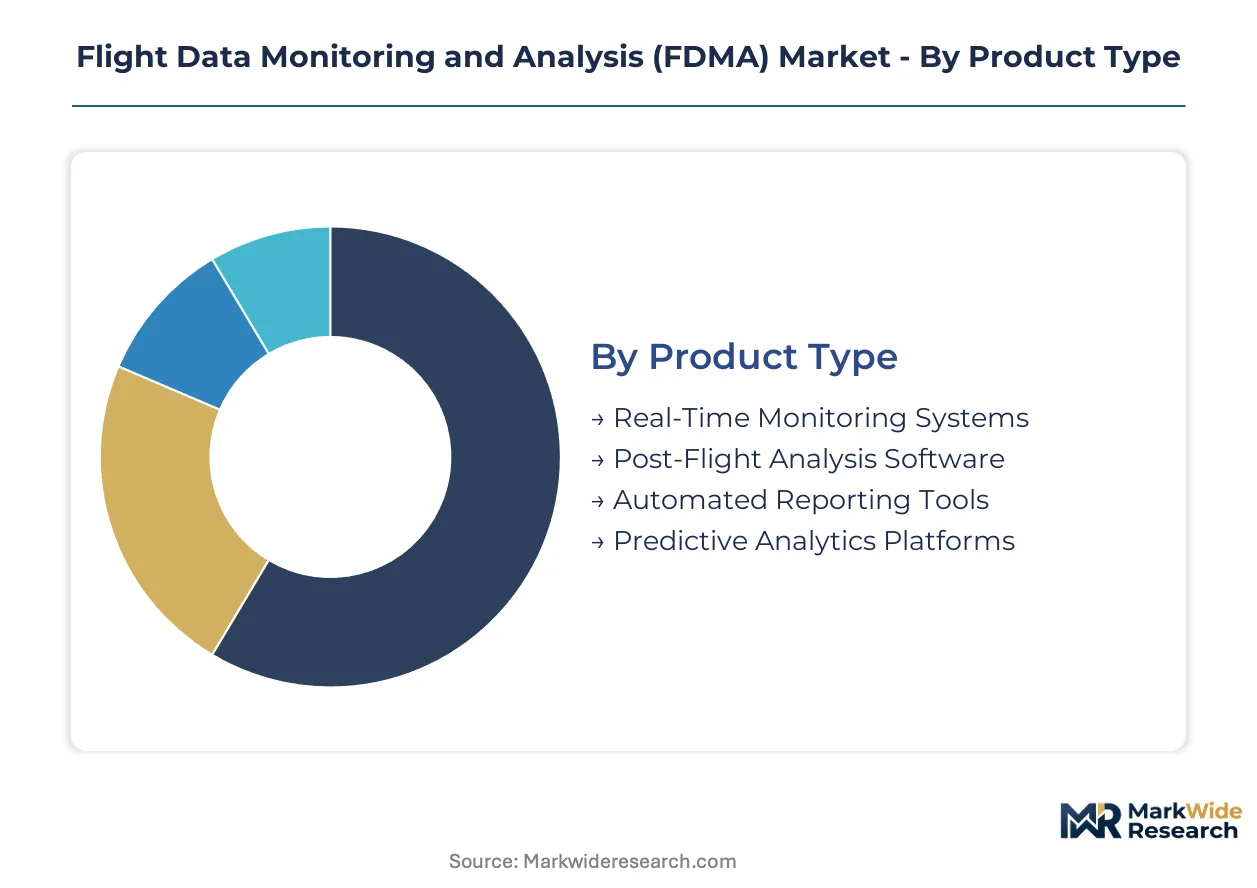
Segmentation in flight data monitoring reveals how procurement priorities diverge between latency-critical safety applications and efficiency-driven predictive maintenance. Carrier fleet composition, regulatory jurisdiction, and IT infrastructure maturity determine which product configurations capture budget allocation.
Product Type:
Supply concentration for flight data processors and specialized avionics components shapes competitive dynamics across product tiers, with real-time systems commanding premium positioning due to hardware-software integration complexity.
- Real-Time Monitoring Systems:Embedded airborne architectures process parameter streams exceeding 64 words per second for immediate exceedance alerting. Demand concentrates among United States network carriers subject to FAA 14 CFR Part 121 continuous monitoring mandates, where latency tolerance approaches zero for safety-critical event detection.
- Predictive Analytics Platforms:Machine learning inference engines transform historical flight parameter repositories into maintenance intervention forecasts. United States commercial airlines expanding condition-based maintenance programs represent the steepest expansion trajectory, displacing calendar-based overhaul schedules with usage-indexed workflows.
- Post-Flight Analysis Software:Ground-based batch processing tools dominate smaller operator budgets with limited real-time infrastructure.
- Automated Reporting Tools:Regulatory submission automation reduces manual analyst workload for FOQA compliance documentation.
Today's leader: Real-Time Monitoring Systems. Tomorrow's challenger: Predictive Analytics Platforms.
Application:
Cost tier differentiation separates mission-critical safety compliance from discretionary performance optimization investments, with regulatory mandates anchoring baseline demand regardless of carrier profitability cycles.
- Safety Compliance:Mandatory FOQA and EU-OPS program infrastructure satisfies regulatory operating authority conditions. United States scheduled carriers under FAA jurisdiction maintain this as non-negotiable baseline expenditure.
- Maintenance Prediction:Condition-based intervention scheduling reduces unscheduled engine removals and airframe component replacements. United States commercial airlines with integrated fleet health telemetry networks capture measurable operating cost reductions.
- Flight Performance Optimization:Fuel efficiency analytics from RNP-AR approach data exploitation remains underpenetrated among network carriers.
- Pilot Training Support:Exceedance replay and trend debriefing tools enhance flight school curriculum delivery.
Safety Compliance absorbs the largest absolute spend. Maintenance Prediction offers the steepest expansion trajectory.
End User Industry Vertical:
Customer type concentration determines pricing power, with commercial airlines leveraging fleet scale for enterprise negotiations while fragmented flight schools accept standard subscription tiers.
- Commercial Airlines:Integrated fleet-wide monitoring networks spanning hundreds of aircraft drive volume procurement of unified software platforms. United States major carriers negotiate multi-year service contracts with predictive maintenance bundling.
- Cargo Operators:High-utilization schedules intensify maintenance prediction ROI, accelerating predictive platform adoption among express freight carriers.
- Airport Authorities:Ground infrastructure monitoring for apron safety and noise compliance represents emerging adjacent demand.
- Flight Schools:Limited IT infrastructure budgets constrain adoption to post-flight analysis software with minimal real-time capabilities.
Commercial Airlines dominate current revenue. Cargo Operators present the steepest expansion trajectory.
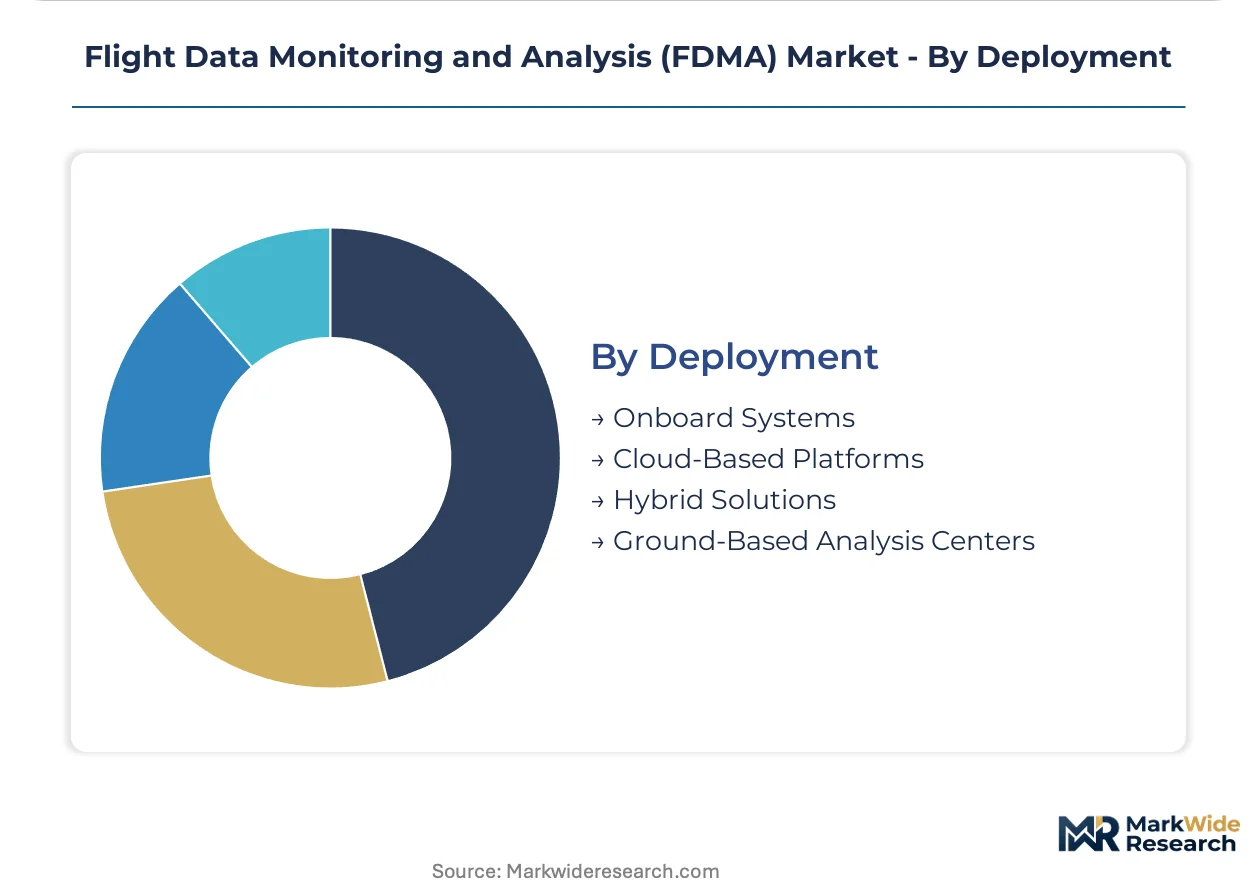
Deployment:
Infrastructure maturity across carrier IT departments determines deployment model selection, with cloud migration accelerating where cybersecurity certification pathways clarify.
- Onboard Systems:Embedded processors with edge computing architectures compress latency for safety-critical detection without ground station dependency. Regional carriers with limited terrestrial network infrastructure adopt these fastest.
- Cloud-Based Platforms:Scalable analytics storage and collaborative dashboard access require EASA-aligned data integrity certification for European operator adoption.
- Hybrid Solutions:Split processing between airborne edge detection and ground-based deep analytics balances latency and computational depth.
- Ground-Based Analysis Centers:Legacy centralized processing persists where fleet-wide connectivity investments remain pending.
Hybrid Solutions capture current procurement preference. Cloud-Based Platforms face steepest expansion trajectory pending certification clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flight data monitoring systems first achieved commercial scale in the United States during the 1990s, when FAA regulatory mandates institutionalized operational quality assurance programs. Today, procurement patterns reflect divergent regulatory timelines and fleet modernization cycles across major aviation markets.
United States
Network carriers under FAA 14 CFR Part 121 jurisdiction maintain the world's densest installed base of continuous monitoring infrastructure. The FAA's flight operational quality assurance mandates create non-negotiable baseline demand regardless of carrier profitability cycles. Seattle and Wichita clusters host avionics integration facilities serving both commercial and defense programs.
Germany
Lufthansa Group's integrated fleet health telemetry network drives predictive platform procurement across the country's full-service carrier segment. EASA's EU-OPS framework amendments harden data integrity requirements for cloud-connected recorders, forcing contract revalidations. Hamburg's aerospace corridor concentrates quick access recorder manufacturing and MRO integration services.
France
Air France-KLM's condition-based maintenance transition accelerates analytics platform adoption for engine health monitoring convergence. CSRD disclosure obligations press operators toward auditable data governance architectures that extend procurement cycles. Toulouse's aerospace cluster anchors flight data processor design and certification expertise.
United Kingdom
British Airways and low-cost carriers deploy hybrid processing architectures balancing airborne edge detection with ground-based analytics. The Civil Aviation Authority enforces parallel FOQA requirements to FAA standards, sustaining mandatory infrastructure investment. Farnborough's defense aviation concentration drives military-grade secure data link procurement.
Japan
ANA and JAL pursue unified fleet diagnostics integrating turbofan sensor streams with airframe parameter logs. METI's industrial policy supports domestic avionics capability development through strategic procurement preferences. Nagoya's Chubu aerospace cluster hosts flight recorder subsystem manufacturing for regional aircraft programs.
Flight Data Monitoring and Analysis (FDMA) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and service contract duration. The vendor base spans three tiers: integrated aerospace conglomerates bundling hardware-software stacks, specialized avionics houses with embedded data acquisition heritage, and software-native analytics platforms. Consolidation pressures intensify as predictive analytics capabilities become table stakes. Dominant competitive moves include backward integration into sensor manufacturing and long-term service contract anchoring with legacy fleet operators.
Within the integrated systems tier, Teledyne Controls and GE Aerospace exemplify contrasting strategic positions. Teledyne Controls leverages its embedded data acquisition heritage to anchor long-term service relationships. GE Aerospace occupies a position defined by engine health monitoring convergence, bundling flight data outputs with predictive maintenance workflows. Safran Electronics & Defense represents the defense-specialist archetype, with its secure data link capabilities creating differentiation in military aviation procurement cycles.
| Leading Market Players |
|---|
| Teledyne Controls |
| GE Aerospace |
| Honeywell International Inc |
| Leonardo S.p.A |
| Collins Aerospace |
| Safran Electronics & Defense |
| Curtiss-Wright Corporation |
| Flight Data Services Ltd |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Edge computing migration in airborne processors is compressing hardware cost curves while concentrating procurement power among Taiwanese semiconductor foundries and German avionics integrators. FAA and EASA certification tiers now stratify pricing power, with latency-critical real-time systems commanding substantial premiums over batch-processed post-flight alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates real-time monitoring systems with sub-second latency guarantees from predictive analytics platforms and basic post-flight analysis tools. Price differentiation rests on DO-178C certification grade and bundled after-sales service duration. Pricing pressure stems from modular unbundling trends that let fleet operators procure quick access recorder hardware separately from software subscriptions. Regional turboprop operators exhibit highest price sensitivity due to constrained IT infrastructure budgets, while United States network carriers under FOQA mandates show lowest sensitivity for safety-critical tiers.
Supply Chain Analysis
Dual-sourcing requirements mandated by major United States network carriers and European flag carriers force flight recorder processor vendors to qualify secondary foundry partners beyond primary Taiwanese suppliers. Component supply draws from Taiwan for specialized processors, Germany for precision avionics assemblies, and Japan for high-reliability memory modules. Raw material dependencies include aerospace-grade aluminum enclosures, radiation-hardened semiconductors, and ARINC-compliant connector systems. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through authorized avionics distributors with FAA repair station certifications, channeling hardware to MRO facilities and OEM integration lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDMA market compounds steadily as regulatory mandates for continuous flight monitoring create non-cyclical baseline demand insulated from airline profitability swings.
For Market Incumbents: Deploy long-term service contract anchoring with legacy fleet operators to counter modular unbundling threats from emerging software-native analytics platforms. Deepen backward integration into sensor manufacturing to capture engine health telemetry convergence value pools. Fortify certification engineering capabilities against pending EASA cybersecurity standards that will disqualify non-compliant vendors from European procurement cycles. For New Entrants and Emerging Players: Capture urban air mobility design-win competitions for lightweight eVTOL parameter logging systems where entrenched incumbents lack installed base advantages. Target cargo operator segments with high-utilization schedules that intensify predictive maintenance ROI and accelerate platform procurement decisions. Lead with cloud-native architectures pre-certified to emerging EASA data integrity baselines to bypass legacy vendor upgrade cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among software-native analytics platforms lacking hardware manufacturing scale but possessing machine learning inference capabilities transferable to predictive turbulence alerting applications. Long-term viability favors vendors with dual-use military-civilian certification pathways as defense aviation procurement cycles lengthen. Watch EASA EU-OPS cybersecurity certification clarity as the inflection signal that will determine which cloud transmission architectures capture European operator upgrade budgets.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early alignment with EASA cybersecurity standards captures European procurement cycles before competitors revalidate. |
| Edge Computing Integration | Embedded inference engines bypass terrestrial network builds for regional carriers with limited IT infrastructure. |
| Service Contract Unbundling | Hardware-software separation lets fleet operators pilot multiple analytics vendors before enterprise commitments. |
| Engine Health Convergence | Unified turbofan and airframe telemetry reduces unscheduled removals for United States network carriers. |
| Urban Air Mobility Design Wins | eVTOL parameter logging competitions open without incumbent legacy fleet lock-in advantages. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flight operations executives, avionics procurement managers, MRO integration specialists, and regulatory compliance officers with secondary validation against FAA advisory circulars, EASA certification specifications, airline FOQA program disclosures, and avionics manufacturer technical documentation. Bottom-up fleet installation estimates triangulated against top-down carrier IT spending patterns.
Segment-weighted modeling distributed value across real-time monitoring systems, predictive analytics platforms, post-flight analysis software, and automated reporting tools, with deployment mode and end-user vertical as cross-cutting dimensions. CAGRs derived from carrier fleet expansion schedules, regulatory mandate enforcement timelines, and condition-based maintenance transition rates across the analysis window. Forecast inputs included turbofan sensor data stream integration velocity and urban air mobility platform certification pathways.
Underlying measurement precision varies by segment; real-time monitoring systems carry tighter precision than emerging predictive analytics categories due to established procurement reporting. Forecasts reflect documented assumptions regarding EASA cybersecurity certification timing and semiconductor supply normalization. Deviation in FAA mandate enforcement intensity or Taiwan foundry capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aviation Analytics Market