
 Aerospace Turbojet Market | 2026-2036
Aerospace Turbojet Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Turbojet Market Insights
Power-by-the-hour maintenance contracts is recalibrating revenue recognition across the aerospace turbojet supply chain. Pratt & Whitney leverages its geared turbofan service network to lock in long-term aftermarket streams. Rolls-Royce anchors its TotalCare program as a benchmark for outcome-based engine management. GE Aviation competes through its OnPoint solution suite, which extends manufacturer influence deep into airline operations.
An aerospace turbojet is a gas turbine engine that compresses incoming air through axial or centrifugal compressors, ignites fuel in a combustion chamber, and expels exhaust through a nozzle to generate thrust via Newton's third law, typically achieving specific fuel consumption below 1.0 lb/lbf-hr in modern designs. High-bypass turbojet variants dominate commercial airliner applications where fuel efficiency dictates fleet economics, while afterburning turbojet configurations retain structural importance in military fighter segments where supersonic dash capability commands procurement priority. Ceramic matrix composites within the technology dimension are displacing nickel superalloys in hot-section components, concentrating margin pools among suppliers with proven thermal barrier coating integration.
The FAA's Part 33 certification framework and the EU's EASA CS-E standards govern airworthiness requirements, while ICAO's Annex 16 Volume I sets international noise and emissions boundaries that manufacturers must satisfy for market access. EPA regulations on aircraft engine pollutants complement these aviation-specific regimes, creating layered compliance obligations that shape R&D allocation. Stakeholders must monitor how sustainable aviation fuel compatibility requirements will redefine combustor design specifications and aftermarket retrofit economics.
Market Dynamics
Ceramic matrix composites are absorbing thermal loads once managed by nickel superalloys, compressing margin pools among suppliers lacking proven thermal barrier coating integration while redistributing competitive advantage toward materials specialists.
Growth Catalysts
- FAA Part 33 Certification Updates:Tightened noise and emissions thresholds are forcing combustor redesigns that favor OEMs with integrated testing infrastructure. Military aviation divisions in the United States are expanding procurement of advanced propulsion systems.
- Power-by-the-Hour Contracts:Outcome-based maintenance models are locking airlines into long-term aftermarket relationships with engine manufacturers. This recalibrates revenue recognition across the entire aerospace turbojet supply chain.
- France Production Concentration:Demand is concentrating where Safran Aircraft Engines and Rolls-Royce sustain major production facilities, creating cluster effects in maintenance training and supplier co-location.
Market Restraints
- Nickel Superalloy Supply Concentration:Hot-section component sourcing depends on a limited supplier base for specialized alloys, exposing manufacturers to input cost volatility and geopolitical disruption risk.
- ICAO Annex 16 Compliance Costs:International noise and emissions boundaries require expensive redesign cycles that compress R&D budgets for smaller engine programs.
- Electric Propulsion Substitution Threat:Battery-electric and hybrid-electric alternatives are capturing R&D attention in regional aviation segments, diverting investment from incremental turbojet improvements.
Strategic Opportunities
- Sustainable Aviation Fuel Compatibility:Combustor retrofits for SAF blends represent a retrofit revenue stream as EPA regulations on aircraft engine pollutants tighten. Aftermarket economics will favor early movers in fuel-flexible designs.
- Additive Manufacturing Convergence:3D-printed turbine blades combined with topology optimization are enabling part-count reduction and lead-time compression for low-volume military engine variants.
- Digital Twin Integration:Real-time engine health monitoring through embedded sensors is creating new software and analytics revenue layers beyond hardware sales.
Industry Challenges
- Thermal Barrier Coating Integration Complexity:Ceramic matrix composite adoption requires specialized application expertise that remains scarce in the maintenance technician workforce, extending turnaround times for hot-section overhauls.
- EASA CS-E Certification Timeline Compression:Dual certification demands from FAA and European regulators are stretching engineering resources thin, delaying new engine program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Turbojet Market |
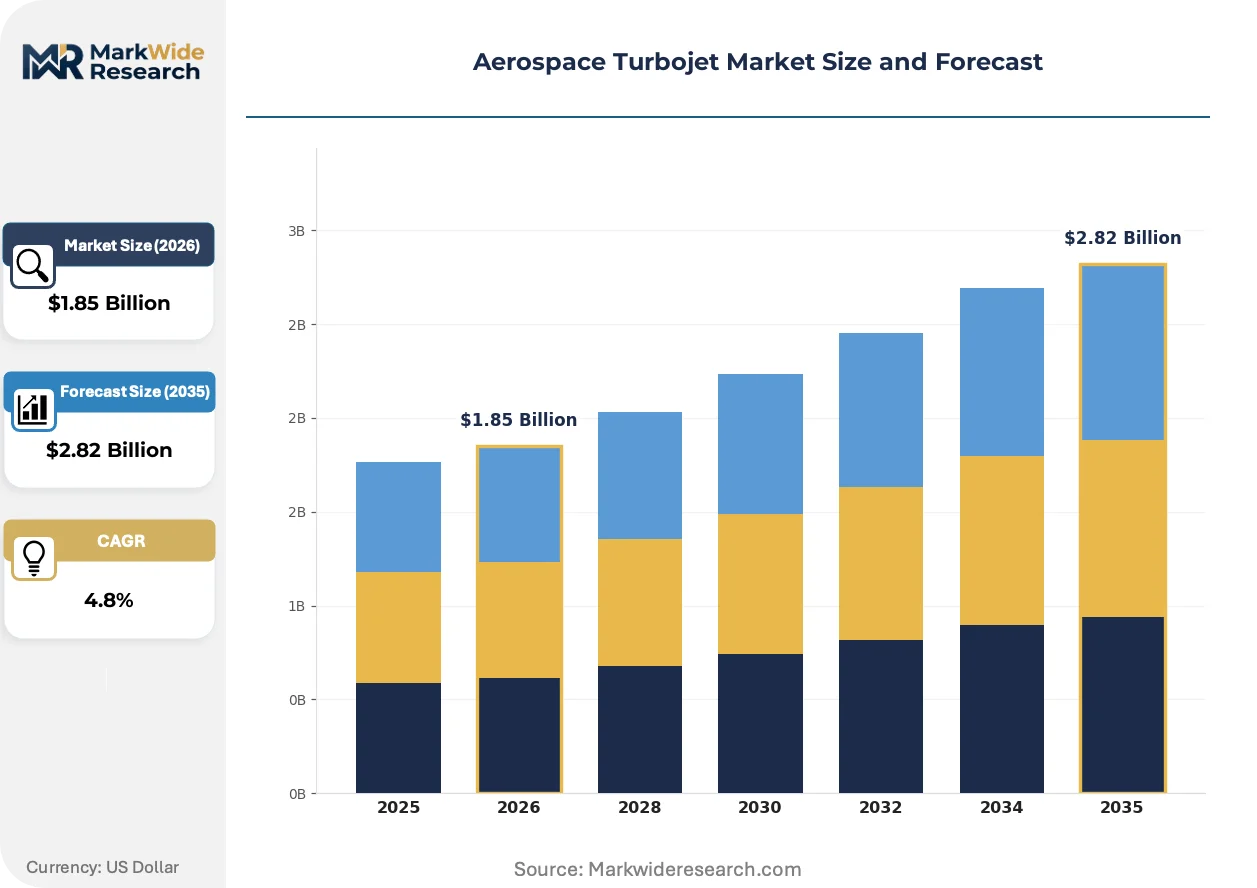
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Bypass Turbojet, Low-Bypass Turbojet, Afterburning Turbojet, Turbojet with Variable Geometry, Non-Afterburning Turbojet Technology: Advanced Combustion, FADEC Control Systems, Ceramic Matrix Composites, Lightweight Materials, Noise Reduction Technologies Application: Military Fighters, Business Jets, Commercial Airliners, UAVs, Experimental Aircraft End User: Aircraft Manufacturers, Military Aviation Divisions, Private Jet Operators, Unmanned Vehicle Developers |
| Companies Covered | Pratt & Whitney, Rolls-Royce, GE Aviation, Safran Aircraft Engines, CFM International, Williams International, PBS Group, AMT Netherlands, Kratos Defense & Security Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Turbojet Market Trends and Innovations
Propulsion architecture is bifurcating between efficiency-optimized commercial designs and performance-maximizing military configurations, with materials science becoming the primary competitive battleground.
Ceramic matrix composites are absorbing thermal stress in turbine vanes and combustor liners, enabling higher operating temperatures without proportional cooling airflow penalties. Commercial airliner engine programs are adopting these materials fastest where fuel efficiency dictates fleet economics. The technology is absorbing margin from conventional nickel superalloy suppliers while concentrating value among coating specialists with proven deposition expertise.
EPA regulations on aircraft engine pollutants are tightening in parallel with ICAO's carbon intensity targets, creating layered compliance obligations that shape combustor R&D allocation. Manufacturers must satisfy multiple certification regimes simultaneously, stretching engineering resources across FAA Part 33 and EASA CS-E frameworks. Narrowbody engine segments face the steepest redesign costs as they serve the highest-volume, most price-sensitive airline customers.
Airline fleet planners are unbundling engine maintenance from airframe purchases, negotiating power-by-the-hour contracts that transfer operational risk to manufacturers. Long-haul carriers with concentrated widebody fleets are driving this behavioral shift, demanding guaranteed availability metrics rather than component warranties. France and the United States host the most mature aftermarket service networks where this model has achieved critical scale.
Aerospace Turbojet Market Segmentation
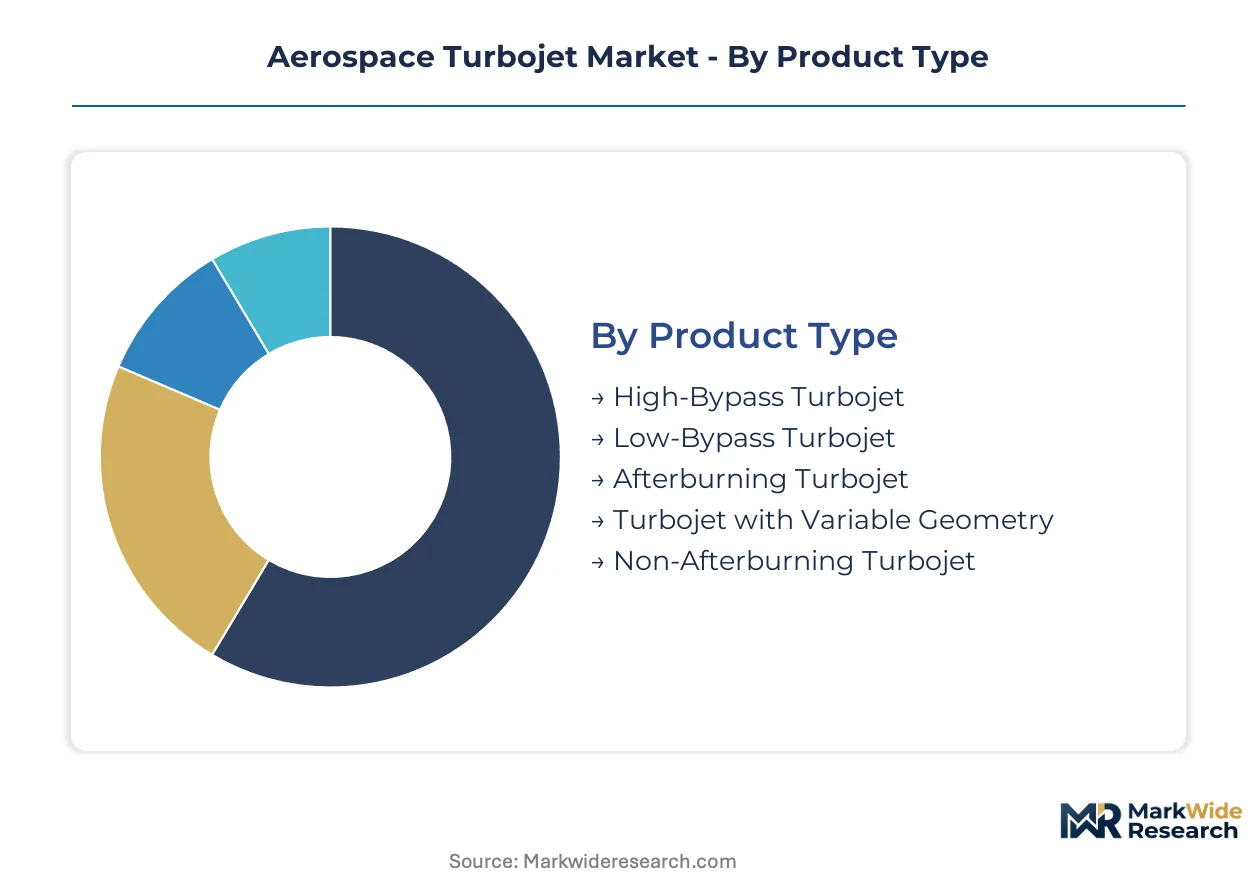
Turbojet segmentation reveals how upgrade cycles and replacement timelines concentrate investment across distinct propulsion architectures. Fleet modernization schedules differ sharply between commercial operators seeking fuel efficiency and military divisions prioritizing thrust-to-weight ratios.
Product Type:
Engine replacement cycles vary dramatically by bypass ratio and afterburning configuration, with commercial fleets retiring high-bypass units on 15-20 year timelines while military afterburning engines face accelerated obsolescence from operational stress.
- High-Bypass Turbojet:These engines achieve bypass ratios exceeding 5:1, diverting most airflow around the core for propulsive efficiency. Demand concentrates among long-haul carriers operating Airbus A320neo and Boeing 737 MAX fleets where fuel burn dictates route economics. Pratt & Whitney's geared turbofan architecture dominates this segment through power-by-the-hour contract penetration.
- Afterburning Turbojet:Supersonic dash capability requires fuel injection downstream of the turbine, generating raw thrust at severe fuel consumption penalties. Procurement clusters in United States military aviation divisions modernizing F-35 and F-22 propulsion systems where performance thresholds override operating cost concerns.
- Low-Bypass Turbojet:Moderate bypass ratios suit regional jet applications where runway length and climb performance balance efficiency requirements.
- Turbojet with Variable Geometry:Adjustable inlet guide vanes and nozzle configurations optimize performance across Mach regimes for multirole fighter platforms.
- Non-Afterburning Turbojet:Simplified hot-section architectures serve trainer aircraft and subsonic reconnaissance platforms where cost minimization drives selection.
Volume placements concentrate in High-Bypass Turbojet; the faster expansion belongs to Afterburning Turbojet.
Technology:
Technology tiers separate by development maturity and certification burden, with production-ready solutions commanding premium placement against experimental materials still navigating FAA Part 33 validation cycles.
- Ceramic Matrix Composites:Silicon carbide fiber reinforcements in silicon carbide matrices withstand temperatures exceeding 2400°F, enabling reduced cooling airflow and improved thermal efficiency. Adoption concentrates in France where Safran Aircraft Engines integrates CMC turbine shrouds into LEAP engine production, though thermal barrier coating application expertise remains scarce in the maintenance workforce.
- FADEC Control Systems:Full Authority Digital Engine Control replaces hydromechanical fuel metering with software-governed thrust management, enabling precise fuel scheduling and automatic surge protection. Demand clusters among business jet operators in the United States seeking reduced pilot workload and enhanced diagnostic visibility for dispatch reliability.
- Advanced Combustion:Lean-premixed prevaporized designs reduce NOx formation for ICAO Annex 16 compliance.
- Lightweight Materials:Titanium aluminide intermetallics and polymer matrix composites reduce fan case and nacelle mass.
- Noise Reduction Technologies:Acoustic liners and serrated nozzle chevrons address community noise restrictions at capacity-constrained airports.
Certification completions favor FADEC Control Systems; steepest expansion trajectory belongs to Ceramic Matrix Composites.
Application:
Application segments diverge by procurement authority and budget cycle timing, with military appropriations subject to congressional authorization while commercial fleet decisions respond to passenger traffic recovery and financing availability.
- Commercial Airliners:Narrowbody and widebody platforms require propulsion systems certified to EASA CS-E and FAA Part 33 standards with demonstrated ETOPS capability. Orders concentrate at Airbus and Boeing final assembly lines where engine selection precedes airframe delivery by 18-24 months, locking in supplier relationships through lease-backed financing structures.
- Military Fighters:Supersonic combat aircraft demand thrust vectoring and supercruise capability without afterburner engagement. Procurement flows through United States Department of Defense appropriations with Pratt & Whitney and GE Aviation competing for F-35 propulsion sustainment and sixth-generation engine development contracts.
- Business Jets:Fractional ownership and corporate flight departments prioritize cabin quietness and dispatch reliability over absolute fuel efficiency.
- UAVs:Unmanned platforms accept higher fuel consumption for reduced procurement cost and simplified logistics.
- Experimental Aircraft:Testbed configurations validate novel propulsion concepts prior to commercial certification.
Delivery volumes concentrate in Commercial Airliners; gaining share fastest is Military Fighters.
End User:
End user categories reflect capital access and risk tolerance, with original equipment manufacturers integrating engines at production while aftermarket operators negotiate availability guarantees.
- Aircraft Manufacturers:Airbus, Boeing, and Bombardier source propulsion systems through competitive RFP processes where technical performance, delivery schedule, and aftermarket support terms determine selection. Engine OEMs defend position through exclusive supplier arrangements and airframe-specific thrust ratings.
- Military Aviation Divisions:United States Air Force, Navy, and Marine Corps procurement commands operate under congressional appropriations cycles with multi-year sustainment contracts. Performance specifications prioritize combat radius and survivability over life-cycle cost optimization.
- Private Jet Operators:NetJets and Flexjet negotiate fleet-wide maintenance agreements transferring operational risk to engine manufacturers.
- Unmanned Vehicle Developers:Defense contractors and intelligence agencies procure specialized propulsion for endurance and stealth-optimized platforms.
Contract value concentrates in Aircraft Manufacturers; climbing the fastest is Military Aviation Divisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in France and the United States, while consumption spreads across NATO-aligned military operators and Asia-Pacific commercial carriers. Manufacturing gravity pulls toward established engine clusters, drawing specialized suppliers into co-location patterns. Regional divergence reflects procurement authority differences between state-owned military programs and privately financed airline fleets.
United States
Department of Defense appropriations drive military turbojet demand through F-35 and sixth-generation engine development programs. FAA Part 33 certification timelines shape commercial engine introduction schedules, with Boston and Hartford maintaining dense engineering talent pools for propulsion R&D. Connecticut's Pratt & Whitney facilities anchor the geared turbofan service network expansion.
France
Safran Aircraft Engines and Rolls-Royce sustain major production facilities that concentrate European turbojet manufacturing. EASA CS-E standards govern certification alongside FAA reciprocity agreements, creating dual-compliance engineering burdens. The Toulouse-Paris corridor clusters maintenance training infrastructure and thermal barrier coating specialists.
United Kingdom
Rolls-Royce's Derby and Bristol operations sustain military and commercial engine final assembly. UK Ministry of Defence procurement cycles for Typhoon and Tempest programs drive afterburning turbojet specifications. Derby's manufacturing base integrates ceramic matrix composite supply chains from continental European specialists.
Japan
IHI Corporation and Kawasaki Heavy Industries participate in international engine risk-sharing partnerships for narrowbody programs. METI industrial policy supports domestic propulsion capability retention through XF9 fighter engine development. Nagoya's aerospace manufacturing district hosts precision casting suppliers for turbine blade production.
Germany
MTU Aero Engines supplies low-pressure turbine modules and maintenance services for global engine programs. German Air Force Tornado replacement timelines influence European military propulsion requirements. Munich's engineering concentration supports combustion system R&D for ICAO Annex 16 compliance.
Aerospace Turbojet Market Competitive Landscape
Top-tier vendors anchor integrated propulsion system supply, while specialized component suppliers and regional maintenance providers occupy supporting positions. Market structure consolidates around original equipment manufacturers with certification infrastructure and aftermarket service networks. Strategic archetypes include full-system integrators, module risk-sharing partners, and aftermarket-exclusive operators. Competitive moves center on power-by-the-hour contract penetration and ceramic matrix composite supply chain capture.
Within the full-system integrator tier, Pratt & Whitney and Rolls-Royce exemplify divergent aftermarket strategies—Pratt & Whitney through its geared turbofan service network, Rolls-Royce through outcome-based engine management programs. GE Aviation occupies a position spanning commercial and military propulsion with integrated digital solutions. Safran Aircraft Engines, through its CFM International partnership, represents the joint venture archetype for narrowbody engine development.
| Leading Market Players |
|---|
| Pratt & Whitney |
| Rolls-Royce |
| GE Aviation |
| Safran Aircraft Engines |
| CFM International |
| Williams International |
| PBS Group |
| AMT Netherlands |
| Kratos Defense & Security Solutions |
| Others |
Pricing and Supply Chain Analysis
Captive thermal barrier coating integration within France and the United States anchors both supply security and pricing power for hot-section component suppliers, concentrating margin capture among OEMs with in-house deposition expertise while squeezing independent coating houses on cost recovery timelines.
Pricing Analysis
Cost-down pressure on aftermarket service contracts accelerates because power-by-the-hour agreements transfer operational risk to manufacturers and compress margin buffers on unscheduled removals. Pricing stratifies across OEM-authorized overhaul, independent MRO, and parts broker tiers based on FAA Part 33 traceability documentation and thermal barrier coating warranty coverage. Narrowbody fleet operators exhibit acute price sensitivity on per-flight-hour rates, while military aviation divisions prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle procurement for high-bypass turbojet production programs, with distribution running through long-term offtake agreements for nickel superalloy castings and ceramic matrix composite preforms. Supply concentrates in France, the United Kingdom, and the United States, drawing specialized turbine blade foundries into co-location patterns around Safran and Rolls-Royce final assembly. Raw material flows hinge on single-source silicon carbide fiber production and rhenium alloying elements, exposing the chain to geopolitical disruption risk from concentrated rare earth processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal barrier coating application capacity scarcity props pricing for hot-section overhauls, constraining aftermarket throughput and sustaining OEM service contract premiums.
For Market Incumbents: Lock in ceramic matrix composite supply through backward integration into silicon carbide fiber production or exclusive offtake with Japanese suppliers. Expand FAA Part 33 certification infrastructure to compress dual-compliance timelines with EASA CS-E, defending service network density against emerging MRO challengers from the Middle East. For New Entrants and Emerging Players: Digital aftermarket platforms for surplus engine parts offer route penetration into price-sensitive regional carrier segments underserved by OEM power-by-the-hour coverage. Target unmanned vehicle propulsion retrofits where certification burden remains lighter and military procurement cycles favor rapid qualification pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to aerospace conglomerates seeking thermal management capabilities, with IPO windows narrowing for pure-play coating specialists. Monitor ICAO Annex 16 carbon intensity target acceleration as inflection signal for SAF-compatible combustor retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Supply Integration | Captive silicon carbide fiber production secures hot-section component margin pools against raw material volatility. |
| Power-by-the-Hour Contract Expansion | Long-term aftermarket agreements with United States military aviation divisions lock in revenue visibility through multi-year appropriations cycles. |
| Dual Certification Infrastructure Investment | Parallel FAA Part 33 and EASA CS-E testing capability compresses new engine program launch timelines for narrowbody applications. |
| Sustainable Aviation Fuel Combustor Retrofit | EPA-aligned fuel-flexible designs capture aftermarket revenue as pollutant regulations tighten on legacy engine fleets. |
| Digital Twin Platform Deployment | Real-time health monitoring through embedded sensors creates software revenue layers beyond hardware sales for GE Aviation and Pratt & Whitney. |
Research Methodology
Document review covered FAA certification databases, EASA CS-E regulatory filings, and Department of Defense appropriations records, complemented by interviews with propulsion engineering directors, aftermarket service managers, and thermal barrier coating specialists. Secondary validation drew from ICAO emissions monitoring reports, EPA aircraft engine pollutant inventories, and SEC disclosures from listed aerospace suppliers. Bottom-up build-ups of fleet replacement schedules and top-down cross-checks against OEM production backlogs were triangulated to anchor volume assumptions.
Historical delivery patterns were cross-referenced against expert panel input on military procurement cycle timing and commercial airline financing availability. The analytical framework modeled segmentation across product type, technology tier, application, and end user, with CAGRs derived from regression analysis of fleet age distributions and regulatory compliance deadlines. Forecast inputs incorporated ceramic matrix composite adoption curves and power-by-the-hour contract penetration rates by operator archetype.
The model holds under stable FAA and EASA reciprocity agreements; deviation in bilateral certification recognition timelines or sudden nickel superalloy supply disruption would shift engine program launch schedules. Periodic stress-testing of base assumptions against military appropriation volatility and sustainable aviation fuel blending mandate acceleration is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Docking System Market
Aircraft
Latin America General Aviation Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Afterburner Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
North America General Aviation Market
Aircraft
Asia-Pacific Military Helicopters Market