
 Aircraft Attitude Indicators Market | 2026-2036
Aircraft Attitude Indicators Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Attitude Indicators Market Analysis
Buyer concentration among commercial aviation operators and military procurement agencies is shifting toward integrated avionics suites rather than standalone instrument purchases. Garmin International sustains technology leadership through its federated glass cockpit architectures. Astronautics Corporation of America anchors defense contracts with specialized attitude reference systems for military platforms. Mid-Continent Instruments & Avionics competes in the general aviation aftermarket with certified replacement instruments for legacy fleets.
Aircraft attitude indicators are flight instruments that display an aircraft's orientation relative to Earth's horizon, typically incorporating gyroscopic mechanisms with pitch and roll reference markings calibrated to ±0.1 degree accuracy for instrument flight rules operations. These instruments serve as primary or standby references for pilots during visual degradation, terrain avoidance, and automated flight control engagement. Digital indicators and integrated displays now dominate new aircraft deliveries, while analog indicators retain substantial aftermarket demand from general aviation operators with cost-sensitive retrofit budgets. Solid-state sensor technology based on microelectromechanical systems is displacing traditional gyroscopic instruments in modern platforms due to reduced maintenance intervals and elimination of vacuum system dependencies.
FAA Part 23 and Part 25 airworthiness standards govern attitude indicator certification in the United States, while EASA CS-23 and CS-25 technical standards apply across European jurisdictions, with both agencies tightening minimum performance specifications for standby instrument redundancy. The EU AI Act and emerging machine-learning validation frameworks are beginning to shape requirements for attitude indicators with predictive fault detection algorithms. Stakeholders must monitor evolving certification pathways for solid-state architectures and assess supply chain exposure to rare earth elements used in precision MEMS fabrication.
Market Dynamics
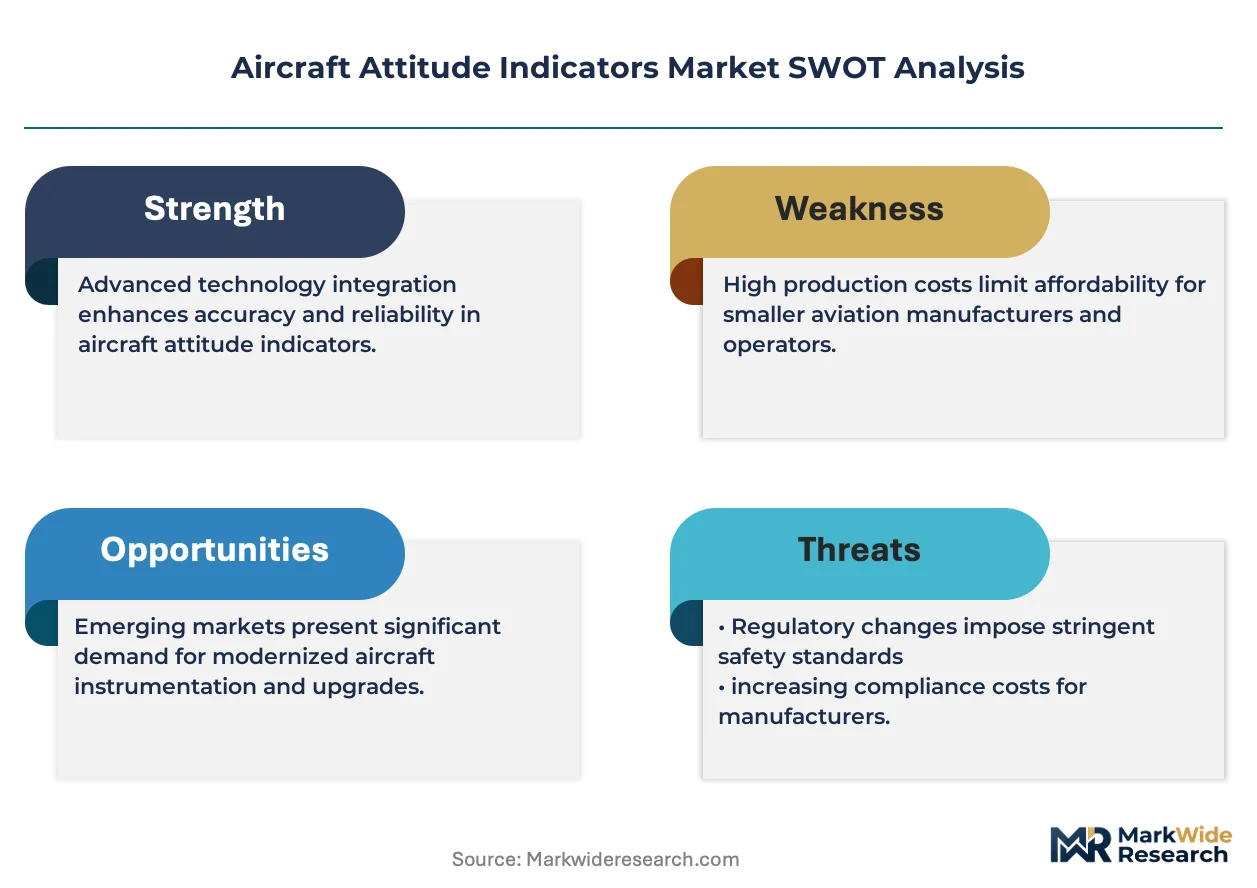
Solid-state MEMS sensor architectures are compressing maintenance intervals and eliminating vacuum system dependencies, forcing electromechanical gyroscope manufacturers to recertify legacy designs or exit the general aviation aftermarket entirely.
Growth Catalysts
- FAA Part 25 mandates:Enhanced standby instrument redundancy requirements for transport-category aircraft are accelerating glass cockpit retrofits across Part 121 operator fleets.
- MEMS fabrication advances:Microelectromechanical systems production scaling is reducing unit costs for attitude reference units in light sport and experimental aircraft segments.
- Military platform modernization:Defense procurement agencies in the United States are funding next-generation attitude reference systems for rotorcraft and unmanned aerial vehicle programs.
Market Restraints
- Rare earth supply concentration:Precision MEMS fabrication depends on neodymium and dysprosium sourced primarily through Chinese processing facilities, creating geopolitical exposure.
- Certification cost barriers:FAA Technical Standard Order C4c compliance for new attitude indicator designs requires flight testing budgets exceeding general aviation manufacturer capitalization.
- Electromechanical substitute persistence:Vacuum-driven attitude indicators retain installed base dominance in legacy Cessna and Piper fleets due to minimal retrofit incentives.
Strategic Opportunities
- EASA CS-25 pathway harmonization:Streamlined dual-certification protocols between FAA and European regulators reduce time-to-market for solid-state attitude reference systems.
- Urban air mobility integration:Electric vertical takeoff and landing aircraft developers require compact attitude reference units with redundant inertial measurement.
- Aftermarket service unbundling:Independent maintenance organizations are capturing calibration and repair revenue previously retained by original equipment manufacturers.
Industry Challenges
- Embedded software validation:EU AI Act emerging requirements for machine-learning fault detection algorithms demand new verification methodologies without established precedents.
- Legacy interface compatibility:Digital attitude indicators must emulate analog signal outputs to integrate with existing autopilot systems in retrofitted aircraft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Attitude Indicators Market |
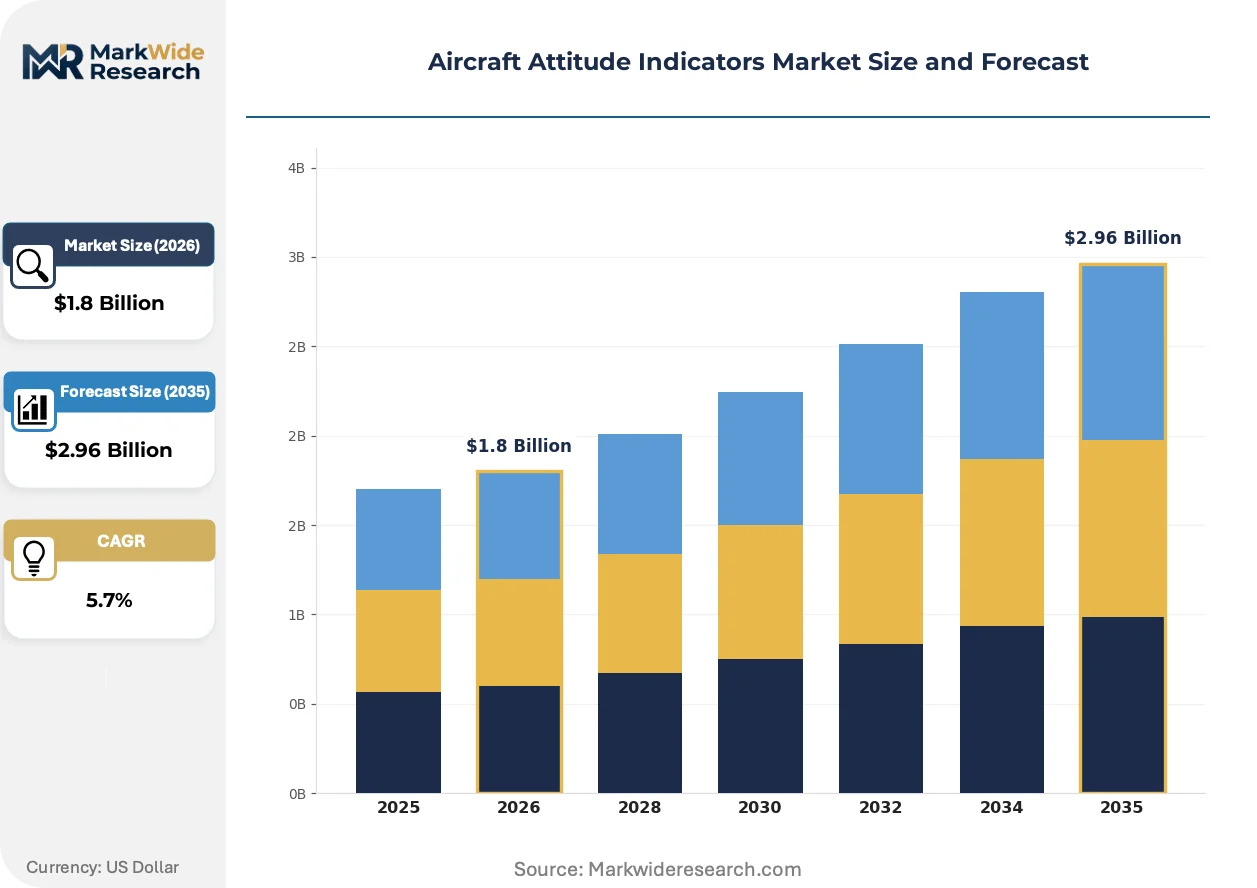
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Indicators, Digital Indicators, Standby Instruments, Integrated Displays Technology: Gyroscopic Instruments, Microelectromechanical Systems, Solid-State Sensors, Federated Systems End User: Commercial Aviation, Military Aviation, General Aviation, OEMs Application: Flight Control, Navigation Assistance, Safety Systems, Simulator Training |
| Companies Covered | Astronautics Corporation of America, Garmin International, Inc, Century Flight Systems, Mid-Continent Instruments & Avionics, Inc, Kelly Manufacturing Company, BendixKing, Suzhou Changfeng Instruments Co., Ltd, Mikrotechna Praha a.s, Sigma Tek, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Attitude Indicators Market Emerging Trajectories
Attitude indicator architectures are converging toward federated glass cockpit systems where standalone instruments disappear into integrated primary flight displays, compressing the addressable market for discrete component suppliers.
Attitude and heading reference systems (AHRS) are unifying previously separate pitch, roll, and yaw sensing into single solid-state units with Kalman-filtered sensor fusion. Regional airlines and business jet operators are adopting these consolidated platforms to reduce line replaceable unit counts. This unification is compressing the aftermarket for standalone attitude indicators as integrated avionics suites dominate new aircraft deliveries.
EASA's tightening CS-23 and CS-25 technical standards for standby instrument reliability are mandating dual-channel redundancy in attitude reference systems for newly certified aircraft. Manufacturers must demonstrate mean time between failures exceeding ten thousand hours under accelerated life testing protocols. Light business aircraft and commuter turboprop segments are absorbing the steepest certification cost increases as they transition from single to dual-architecture designs.
Commercial aviation procurement departments are consolidating avionics purchasing into fleet-wide integrated suite contracts rather than discrete instrument orders. Airlines negotiating Boeing and Airbus delivery positions now specify attitude reference capabilities as part of comprehensive flight deck packages. This consolidation is most visible among United States-based low-cost carriers and major network airlines with standardized narrowbody fleets.
Aircraft Attitude Indicators Market Segmentation
Attitude indicator procurement splits sharply between legacy fleet retrofits demanding cost-efficient replacements and new aircraft programs specifying integrated avionics architectures. Understanding where volume concentrates versus where margins expand reveals which technology transitions will reshape supplier positioning over the forecast window.
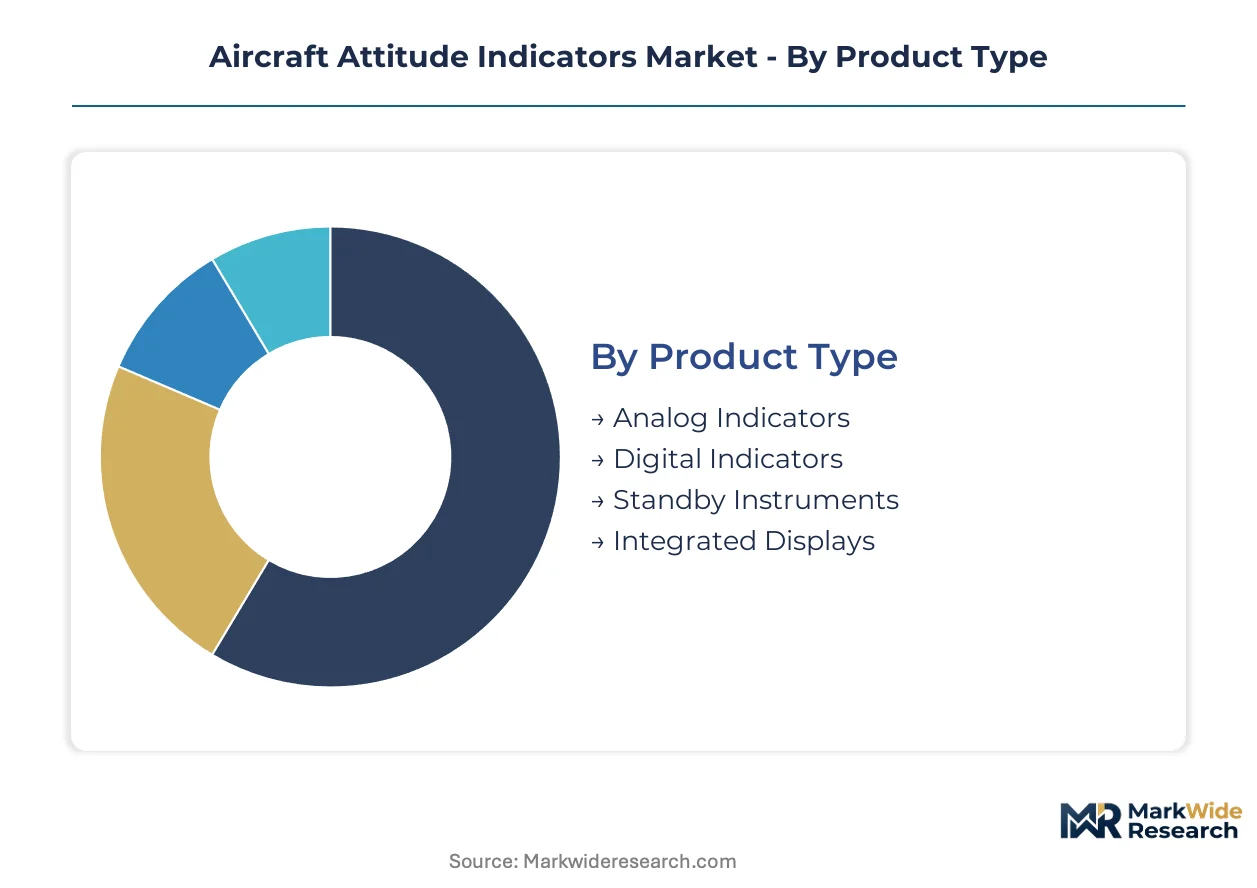
Product Type:
Volume concentrates in certified replacement instruments for aging general aviation fleets, while premium value accumulates in integrated glass cockpit systems for transport-category deliveries.
- Digital Indicators:Solid-state architectures with MEMS inertial cores deliver pitch and roll data through LCD or OLED interfaces, eliminating vacuum system dependencies entirely. Commercial aviation operators in the United States are specifying these for Part 121 fleet retrofits as FAA standby redundancy mandates tighten. Digital indicators command price premiums three to four times above analog equivalents but compress total ownership costs through extended calibration intervals.
- Integrated Displays:Federated glass cockpit systems embed attitude reference functions within primary flight displays, eliminating discrete instrument form factors. Airbus and Boeing now specify these exclusively for new narrowbody and widebody deliveries. Integrated displays represent the steepest expansion trajectory as regional airlines and business jet operators consolidate avionics purchasing into fleet-wide suite contracts.
- Analog Indicators:Vacuum-driven electromechanical gyroscopes with mechanical gimbal mounts retain substantial installed base in Cessna 172 and Piper PA-28 fleets.
- Standby Instruments:Battery-powered attitude reference units provide emergency backup when primary systems fail, mandated under EASA CS-25 for newly certified transport aircraft.
Today's leader: Integrated Displays. Tomorrow's challenger: Digital Indicators.
Technology:
MEMS fabrication scaling is collapsing cost curves for light aircraft applications while federated architectures capture value in integrated flight decks.
- Microelectromechanical Systems:Silicon-based inertial sensors fabricated through semiconductor processes measure Coriolis acceleration to derive attitude data without rotating mechanical components. Light sport aircraft and experimental kit builders in the United States are adopting MEMS-based attitude reference units as unit costs fall below five hundred dollars. MEMS eliminates the six-hundred-hour inspection intervals required for vacuum gyroscopes.
- Federated Systems:Distributed computing architectures consolidate attitude, heading, air data, and engine parameters into unified display suites with redundant data buses. Business jet OEMs and military platform integrators specify federated systems to reduce line replaceable unit counts and simplify logistics chains. These systems demand sophisticated software validation protocols that extend development timelines but lock in long-term aftermarket service revenue.
- Gyroscopic Instruments:Spinning mass gyroscopes mounted on gimbals provide mechanical attitude reference, dominating legacy fleet installations.
- Solid-State Sensors:Ring laser gyro and fiber optic gyro technologies deliver navigation-grade precision for military and commercial transport applications.
MEMS owns volume expansion. Federated Systems owns value capture.
End User:
Military procurement agencies fund development of next-generation reference architectures while general aviation absorbs price-sensitive aftermarket demand.
- Commercial Aviation:Part 121 operators and regional airlines drive glass cockpit retrofit programs across Boeing 737 NG and Airbus A320ceo fleets. United States-based low-cost carriers are consolidating attitude indicator procurement into comprehensive avionics suite negotiations with airframe OEMs. Commercial aviation demands dual-channel redundancy and mean time between failures exceeding ten thousand hours.
- Military Aviation:Defense procurement agencies in the United States fund attitude reference system modernization for rotorcraft and unmanned aerial vehicle programs. Military specifications prioritize shock resistance, electromagnetic hardening, and GPS-denied navigation capabilities that exceed commercial requirements. These programs sustain specialized suppliers with captive engineering expertise in ruggedized packaging.
- General Aviation:Owner-operators and flight schools in the United States represent fragmented demand for certified replacement instruments.
- OEMs:Airframe manufacturers specify attitude reference capabilities as integrated subsystems rather than discrete components.
Commercial Aviation commands procurement scale. Military Aviation commands technology leadership.
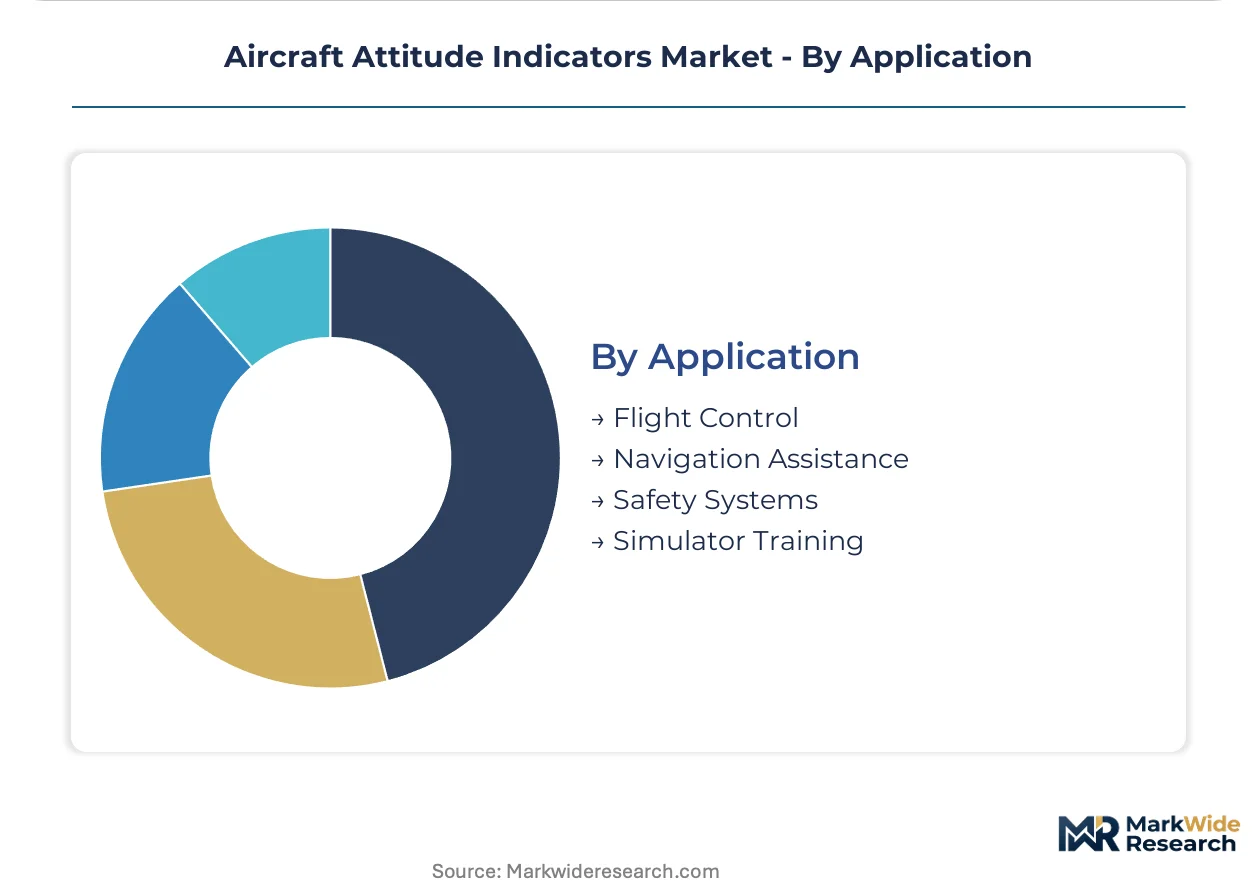
Application:
Safety-critical redundancy requirements are expanding addressable demand beyond primary flight reference into standby and training systems.
- Flight Control:Primary attitude reference inputs enable autopilot engagement and flight director commands during instrument meteorological conditions. Transport-category aircraft require dual independent attitude sources with automatic cross-monitoring. Flight control applications demand the highest certification grades and sustain premium pricing through regulatory compliance barriers.
- Safety Systems:Standby attitude indicators provide essential reference during primary system failures, with EASA and FAA mandating enhanced reliability standards for newly certified aircraft. Helicopter emergency medical services and offshore oil transport operators are specifying triple-redundant attitude architectures. Safety system procurement is accelerating fastest among commuter turboprop operators transitioning to dual-channel designs.
- Navigation Assistance:Attitude data feeds into inertial reference systems for position calculation during GPS outages.
- Simulator Training:Flight training devices replicate attitude indicator behavior for pilot certification and recurrent training.
Flight Control anchors revenue. Safety Systems anchors growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes substantially exceed German aerospace investment, while Chinese civil aviation expansion and Japanese precision manufacturing create distinct competitive dynamics across major aviation markets.
United States
Defense contractors anchor demand for next-generation attitude reference systems through rotorcraft and unmanned aerial vehicle modernization programs. FAA Part 23 and Part 25 airworthiness standards tighten compliance thresholds for standby instrument redundancy. Wichita, Kansas and Dallas-Fort Worth host concentrated avionics integration facilities serving both commercial retrofits and military platforms.
Germany
Business jet OEMs drive specifications for federated glass cockpit architectures in light and mid-size aircraft segments. EASA CS-23 and CS-25 technical standards mandate enhanced reliability certification for newly certified aircraft. Bavaria's aerospace corridor around Munich sustains specialized suppliers with captive engineering expertise in ruggedized sensor packaging.
China
Commercial aviation fleet expansion generates procurement scale for integrated flight deck systems across COMAC narrowbody programs. The country's national aviation regulator aligns certification protocols with international standards while prioritizing domestic supplier development. Shanghai and Xi'an host emerging avionics manufacturing clusters serving indigenous aircraft production.
Japan
Precision MEMS fabrication capabilities support attitude sensor component supply for global avionics integrators. METI industrial policy channels funding toward aerospace sensor miniaturization and reliability enhancement. Nagoya's Chubu region concentrates precision manufacturing expertise serving both commercial and defense applications.
Aircraft Attitude Indicators Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the attitude indicator value chain, creating a tiered structure where scale-driven integrators and technology-focused component suppliers occupy distinct competitive positions. The vendor base segments into three strategic archetypes: federated system architects, specialized attitude reference manufacturers, and aftermarket service providers. Dominant competitive moves include strategic partnerships between sensor technology developers and airframe OEMs, plus portfolio diversification into adjacent inertial measurement applications.
Within the specialized attitude reference tier, Astronautics Corporation of America and Mid-Continent Instruments & Avionics, Inc exemplify distinct strategic positions—one anchoring defense procurement relationships, the other capturing general aviation aftermarket demand. Garmin International, Inc occupies a position spanning both integrated system architecture and discrete instrument supply. Suzhou Changfeng Instruments Co., Ltd represents Chinese manufacturing scale in precision instrument fabrication.
| Leading Market Players |
|---|
| Astronautics Corporation of America |
| Garmin International, Inc |
| Century Flight Systems |
| Mid-Continent Instruments & Avionics, Inc |
| Kelly Manufacturing Company |
| BendixKing |
| Suzhou Changfeng Instruments Co., Ltd |
| Mikrotechna Praha a.s |
| Sigma Tek, Inc |
| Others |
Supply Flow & Price Mechanics
Commercial aviation operators consolidating avionics procurement into fleet-wide suite contracts exercise substantial pricing leverage over discrete attitude indicator suppliers, compressing margins for standalone instrument manufacturers while elevating value capture for integrated system architects. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentials, with dual-channel redundant systems commanding substantial premiums over single-architecture alternatives.
Pricing Analysis
Capacity additions in China's precision MEMS fabrication sector are reshaping price floors for light aircraft attitude reference units, forcing incumbent electromechanical gyroscope manufacturers toward cost compression or exit. Certification grade and volume scale drive price differentiation, with FAA Technical Standard Order C4c-compliant instruments sustaining premiums against experimental-category alternatives. Pricing pressure stems from MEMS unit cost declines below five hundred dollars, eroding legacy vacuum gyroscope aftermarket economics. General aviation owner-operators exhibit highest price sensitivity, while transport-category Part 121 operators prioritize reliability specifications over unit cost.
Supply Chain Analysis
FAA Technical Standard Order and EASA CS-25 certification requirements gate supply chain participation, limiting qualified suppliers to firms with demonstrated flight testing capabilities and established regulatory relationships. Manufacturing concentrates in the United States, Germany, and Japan, with precision MEMS fabrication drawing from semiconductor-grade silicon wafer supplies and rare earth elements including neodymium and dysprosium. Single-source vulnerability in Chinese rare earth processing facilities creates geopolitical exposure for solid-state sensor production. Distribution runs through airframe OEM integrated suite contracts, avionics integrator channels, and independent maintenance organizations serving aftermarket retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft attitude indicators represent a late-cycle quality story as FAA and EASA mandates shift procurement toward dual-channel redundant architectures with ten-thousand-hour mean time between failures specifications, elevating technical barriers and consolidating supplier tiers.
For Market Incumbents: Extend certification portfolio breadth to capture EASA CS-25 pathway harmonization benefits, accelerating dual-certification timelines for solid-state attitude reference systems. Deepen backward integration into MEMS sensor fabrication to offset rare earth supply concentration risks from Chinese processing facilities. Lock in long-term service contracts with regional airlines transitioning to federated glass cockpit architectures, capturing recurring calibration and repair revenue streams.
For New Entrants and Emerging Players: Begin with urban air mobility developer relationships, where electric vertical takeoff and landing aircraft programs demand compact attitude reference units without established incumbent relationships. Target experimental and light sport aircraft segments in the United States, where MEMS cost compression enables price-competitive entry against legacy vacuum gyroscope alternatives. Pursue unbundled aftermarket service positioning, capturing calibration revenue from independent maintenance organizations seeking alternatives to OEM-captive repair networks.
For Investors and Strategic Acquirers: Avionics integrators pursuing platform consolidation are the most active acquirer in this space, seeking specialized attitude reference capabilities to complete federated system portfolios. Five-to-ten year viability hinges on MEMS technology transition completion and regulatory certification barrier sustainability. Monitor EASA and FAA harmonization progress on standby instrument redundancy mandates as inflection indicator for solid-state architecture adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | EASA CS-25 and FAA TSO C4c alignment reduces time-to-market for solid-state attitude reference systems. |
| MEMS Fabrication Scale-Up | Semiconductor-grade production expansion in Japan and the United States compresses unit costs for light aircraft segments. |
| Aftermarket Service Unbundling | Independent maintenance organizations capture calibration revenue previously retained by Garmin and Astronautics. |
| Urban Air Mobility Partnership | Electric vertical takeoff and landing developers require compact redundant attitude reference without legacy incumbent relationships. |
| Rare Earth Supply Diversification | Alternative processing facility development outside China reduces geopolitical exposure for precision MEMS fabrication. |
Methodological Framework
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each aviation manufacturing cluster combining structured interviews with avionics integration engineers, FAA certification specialists, airline procurement directors, and military platform program managers alongside secondary validation. FAA airworthiness directive filings, EASA certification databases, COMAC supplier disclosures, and METI aerospace funding announcements inform supply-side assessment. Bottom-up unit demand modeling triangulates against top-down fleet expansion projections from airframe OEM delivery schedules.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon, with analytical framework incorporating product type transitions from analog to digital to integrated display architectures, technology migration from gyroscopic to MEMS to federated systems, and end-user consolidation from discrete instrument purchasing to suite-level procurement. Segmentation dimensions include platform category, certification tier, and aftermarket versus OEM attach rates. CAGRs derive from installed base turnover velocity and new aircraft delivery specifications, with urban air mobility adoption curves and military modernization program funding trajectories as industry-specific forecast inputs.
Caveats apply where FAA or EASA regulatory delays, rare earth supply disruptions, or urban air mobility program cancellations could materially shift the outlook. Forecasts reflect assumptions regarding certification timeline adherence and MEMS cost curve progression. A model refresh is warranted upon material change in dual-certification harmonization progress or significant rare earth processing facility relocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Aircraft Control Software Market