
 Automated Composite Structure Inspection Systems for Aerospace Market | 2026-2036
Automated Composite Structure Inspection Systems for Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Composite Structure Inspection Systems for Aerospace Market Insights
The gap between premium automated inspection suites and commodity handheld units is realigning procurement patterns across aerospace supply chains. Ingersoll Machine Tools leverages its gantry-based laser scanning platforms to dominate large-structure wing inspection lines. Waygate Technologies anchors its position through deep integration of computed tomography with robotic manipulation for engine nacelle applications. Eddyfi Technologies differentiates by specializing in portable phased-array systems that penetrate tier-two component supplier shops where capital budgets constrain full automation.
Automated composite structure inspection systems for aerospace encompass robotic platforms, sensor arrays, and analysis software that detect subsurface defects in fiber-reinforced polymer components without destructive sectioning, typically resolving delaminations below 1 mm through ultrasonic pulse-echo or thermal diffusion measurements. These systems verify structural integrity after manufacturing and during maintenance to prevent catastrophic failure in flight-critical assemblies. Ultrasonic systems lead product category revenue due to decades of calibration data and operator familiarity, while thermographic cameras represent the fastest-growing segment as flash-heating protocols cut inspection cycle times for large aerostructures. Digital radiography commands premium margins in damage detection applications where through-thickness void mapping supports airworthiness certification.
The FAA mandates damage tolerance assessments under 14 CFR Part 25, while EASA enforces comparable composite-specific continued airworthiness requirements through CS-25 amendments; both frameworks directly shape inspection interval frequency and equipment qualification standards. The EU AI Act introduces conformity obligations for machine-learning defect classification modules embedded in newer automated platforms, potentially fragmenting software deployment across regulatory jurisdictions. Stakeholders must monitor whether emerging standards for autonomous inspection decision-making consolidate or splinter between FAA, EASA, and CAAC certification pathways.
Market Dynamics
Fleet renewal mandates from Boeing and Airbus are compressing inspection cycle times, forcing MRO networks to replace manual ultrasonic probe methods with robotic gantry systems that slash wing box inspection hours from days to hours.
Growth Catalysts
- FAA Airworthiness Directives:Composite damage tolerance mandates under 14 CFR Part 25 are compelling North American MRO facilities to automate delamination detection protocols for Boeing 787 and Airbus A350 fleets.
- Phased-array ultrasonic systems:These platforms penetrate tier-one aerostructure suppliers in Hamburg and Toulouse, where Airbus production lines demand sub-millimeter defect resolution for wing skin laminates.
- Flash thermography:Heating protocols are cutting inspection times for full wing sections, driving adoption at Spirit AeroSystems and GKN Aerospace facilities.
Market Restraints
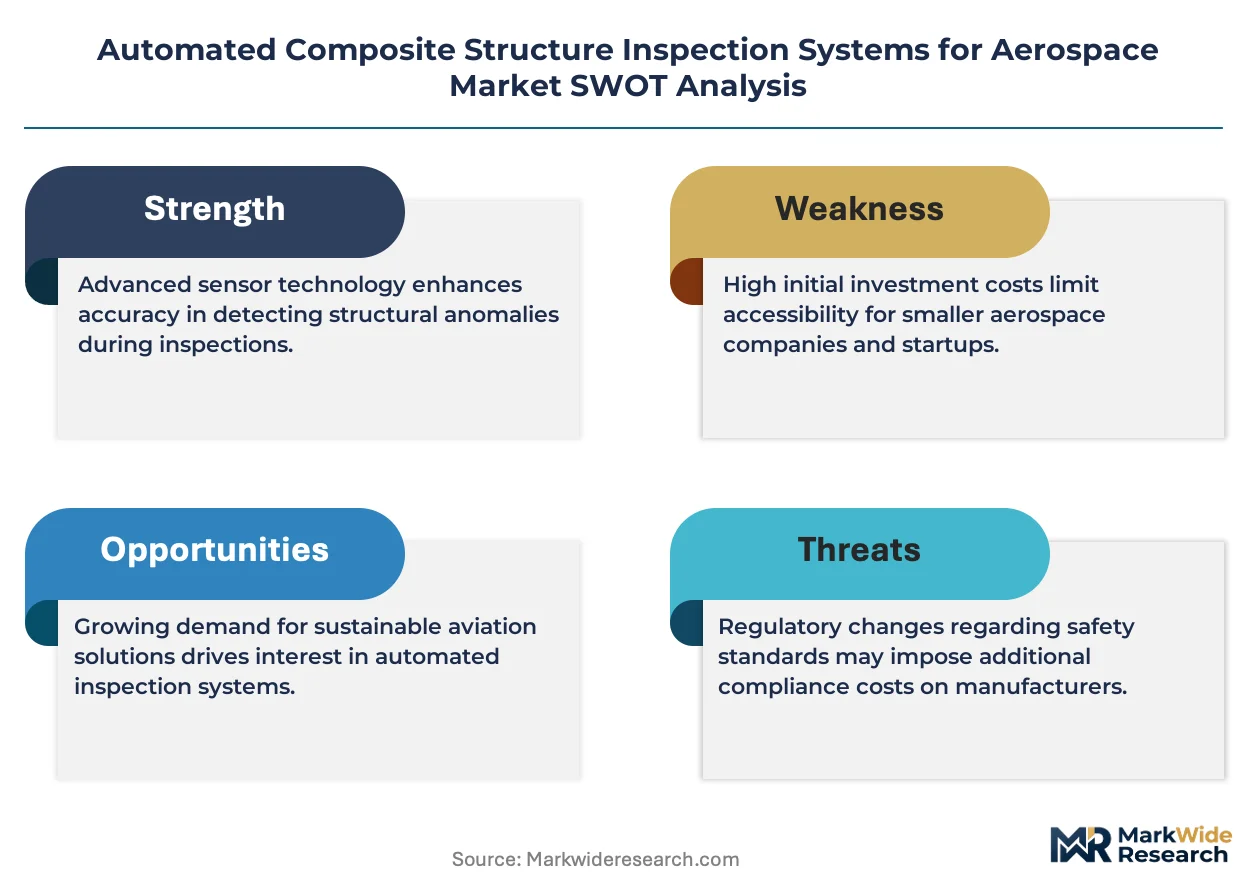
- Capital intensity of gantry cells:Large-structure robotic inspection platforms require $2-5 million deployment costs, freezing out tier-three component shops.
- Calibration data scarcity:Thermographic systems lack decades of defect signature libraries that ultrasonic methods possess, slowing certification acceptance by EASA.
- Skilled operator shortage:Phased-array interpretation demands certified Level III technicians, creating bottlenecks at German and French MRO hubs.
Strategic Opportunities
- India defense aerospace:Hindustan Aeronautics Limited's Tejas production line presents untapped demand for automated composite inspection as indigenous fighter output scales.
- EU AI Act conformity:Machine-learning defect classification modules face emerging compliance obligations, creating first-mover advantage for software-integrated platform vendors.
- Urban air mobility:eVTOL manufacturers like Joby and Archer require high-throughput inspection cells for carbon fiber propulsion housings, opening adjacent demand.
Industry Challenges
- Legacy MRO integration:Brownfield hangar facilities struggle to retrofit robotic gantry systems into existing jigs designed for manual probe access.
- Cross-regional certification divergence:FAA, EASA, and CAAC are developing incompatible autonomous inspection decision-making standards, fragmenting software deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Composite Structure Inspection Systems for Aerospace Market |
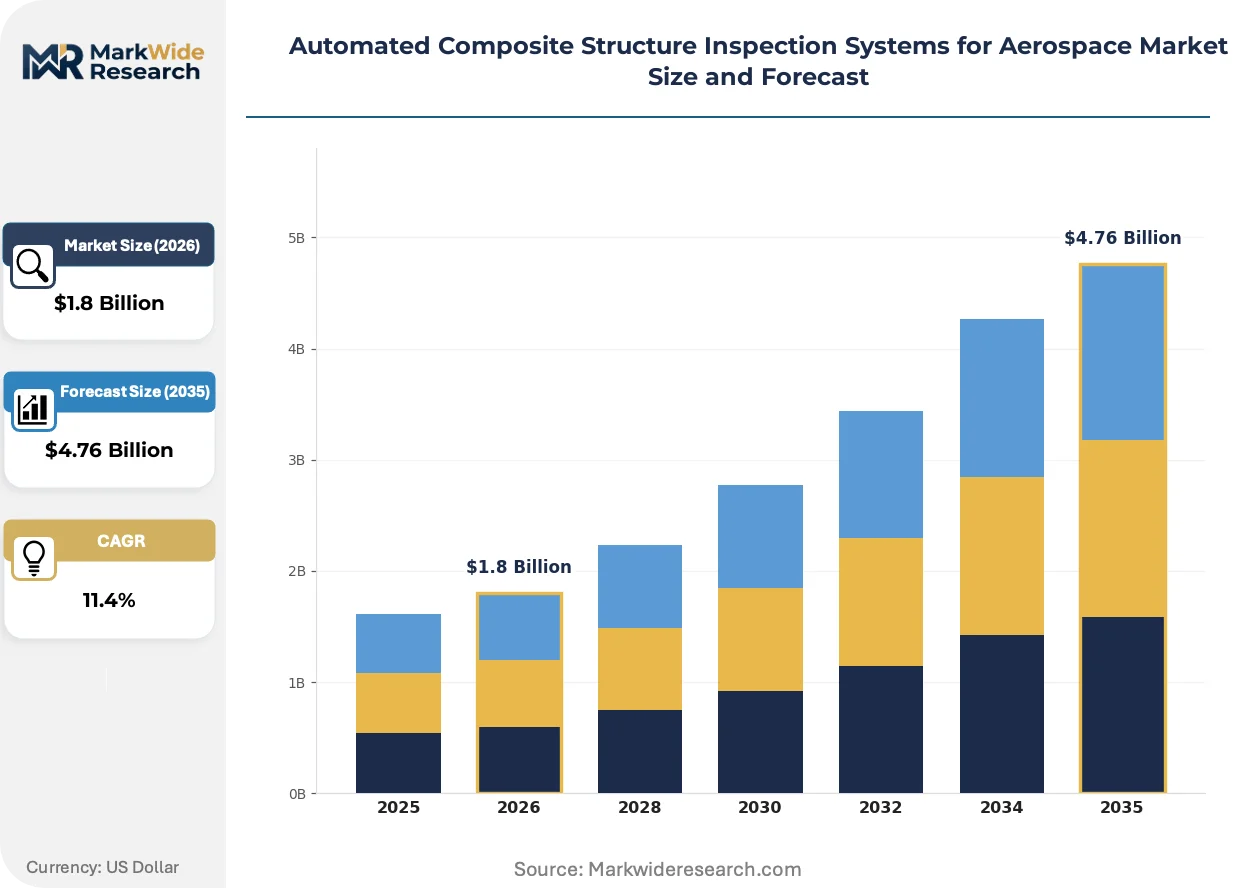
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Laser Scanners, Ultrasonic Systems, Thermographic Cameras, Eddy Current Devices, X-ray Computed Tomography Technology: Phased Array Ultrasound, Pulsed Thermography, Laser Shearography, Digital Radiography, Guided Wave Testing Application: Structural Integrity Analysis, Damage Detection, Delamination Characterization, Void Identification, Fiber Orientation Assessment End User: OEM Manufacturers, Component Suppliers, MRO Facilities, Aviation Regulatory Bodies, Aerospace Research Institutes |
| Companies Covered | Ingersoll Machine Tools, TWI, Waygate Technologies, Evident, Zetec, Eddyfi Technologies, FOERSTER, ScanMaster Systems, Nikon Metrology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Composite Structure Inspection Systems for Aerospace Market Trends and Innovations
Inspection hardware is separating from analysis software, enabling sensor-agnostic platforms that swap ultrasonic, thermographic, and radiographic modules without full system replacement.
Computed tomography is modularizing for engine nacelle applications, allowing Pratt & Whitney and Rolls-Royce service centers to reconfigure inspection cells between fan case and combustor liner geometries without gantry reconstruction. This flexibility compresses capital deployment timelines from 18 months to 6 months for multi-program MRO facilities.
EASA's CS-25 amendments on composite continued airworthiness are tightening inspection interval documentation, forcing European operators to deploy continuous-monitoring sensor networks rather than periodic manual checks. Airlines including Lufthansa Technik and Air France Industries are retrofitting A350 fleets with permanently bonded ultrasonic transducers that stream delamination data to predictive maintenance platforms.
Airlines are unbundling inspection service contracts from OEM maintenance agreements, creating direct procurement relationships with automated system vendors. Delta TechOps and United Airlines have established in-house composite inspection capabilities at Atlanta and San Francisco hubs, bypassing traditional third-party MRO channels for Boeing 787 wing repairs.
Automated Composite Structure Inspection Systems for Aerospace Market Segmentation
Segmentation in automated composite inspection reveals how capital intensity, certification requirements, and defect resolution needs fragment procurement across aerospace supply chains. Buyers select inspection modalities based on structural geometry, material thickness, and regulatory documentation obligations rather than price alone.
Product Type:
Capital deployment thresholds and inspection throughput requirements separate procurement tiers across aerospace manufacturing and MRO networks.
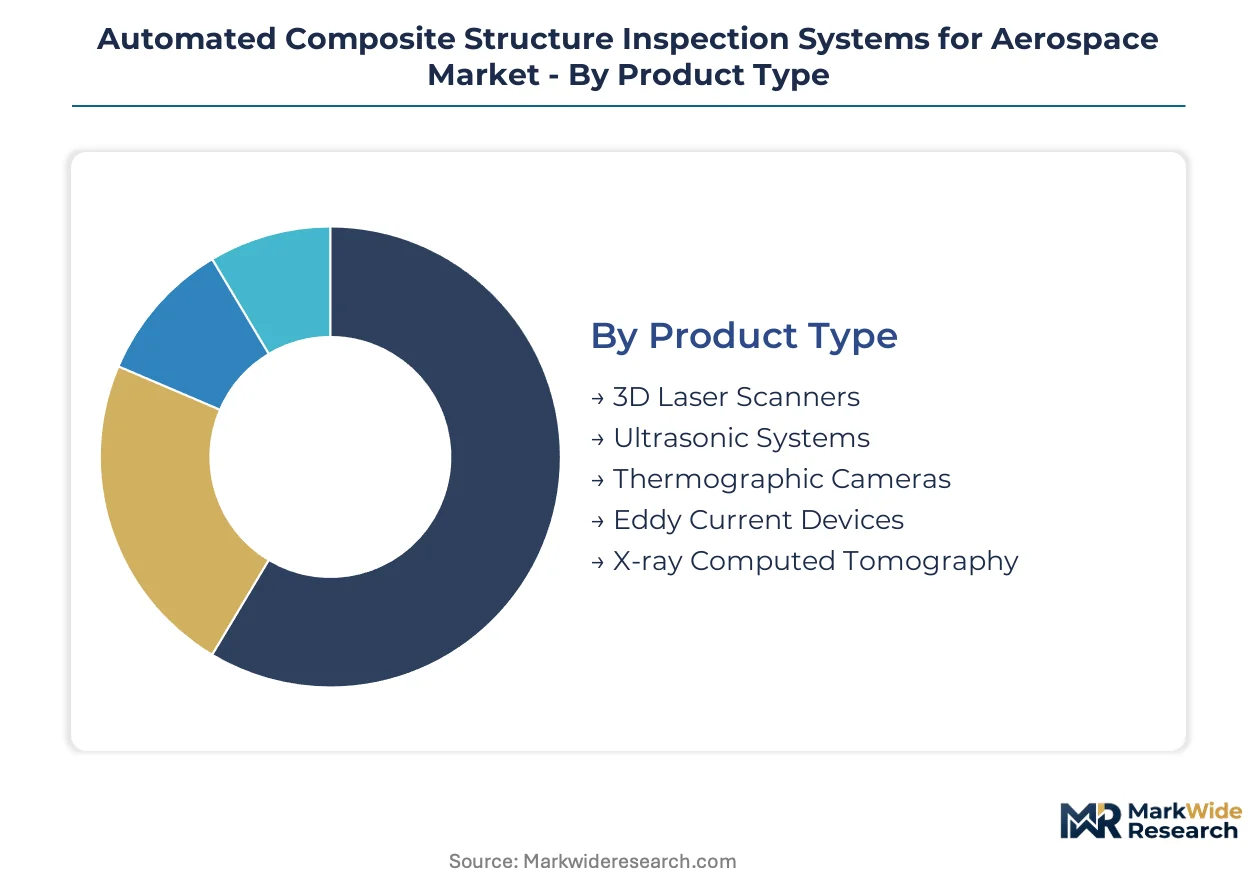
- Ultrasonic Systems:Pulse-echo and phased-array configurations transmit high-frequency acoustic waves through carbon fiber laminates to resolve subsurface delaminations below one millimeter. Airbus Hamburg and Premium Aerotec anchor European demand for gantry-mounted ultrasonic cells that automate wing skin inspection across production lines. FAA damage tolerance mandates under 14 CFR Part 25 compel North American MRO facilities to replace manual probe methods with robotic ultrasonic platforms for Boeing 787 fleet support.
- Thermographic Cameras:Infrared sensors capture thermal diffusion patterns after flash-heating protocols to detect voids and disbonds in large aerostructures without contact coupling. Spirit AeroSystems and GKN Aerospace deploy flash thermography for full wing section inspection, cutting cycle times from days to hours compared to ultrasonic raster scanning. EASA acceptance lags due to sparse calibration libraries, slowing certification for European operators.
- 3D Laser Scanners:Structured light and time-of-flight sensors map surface geometry deviations in composite tooling and finished components.
- Eddy Current Devices:Electromagnetic induction probes detect surface-breaking cracks and conductivity variations in metallic lightning protection layers embedded in composite skins.
- X-ray Computed Tomography:Rotating source-detector pairs reconstruct volumetric void maps for damage tolerance certification of flight-critical assemblies.
Ultrasonic systems lead volumes today; thermographic cameras are gaining share fastest.
Technology:
Physics-based detection mechanisms compete on defect type specificity, penetration depth, and automation compatibility.
- Phased Array Ultrasound:Electronically steered beam angles enable single-pass inspection of complex curvatures without mechanical probe repositioning. German and French MRO hubs including Lufthansa Technik and Air France Industries deploy phased-array systems for A350 wing box maintenance, though Level III technician shortages constrain throughput expansion.
- Pulsed Thermography:Millisecond flash heating combined with high-speed infrared imaging visualizes subsurface defects through thermal contrast decay analysis.
- Digital Radiography:Flat-panel detectors capture through-thickness X-ray attenuation for void mapping in thick composite sections where ultrasonic attenuation limits penetration.
- Laser Shearography:Speckle pattern interferometry measures surface strain under vacuum loading to reveal disbonds and core damage in sandwich structures.
- Guided Wave Testing:Low-frequency ultrasonic modes propagate along plate structures to screen large areas from single sensor positions.
Phased array ultrasound dominates current installations; pulsed thermography shows steepest expansion trajectory.
Application:
Defect taxonomy and airworthiness criticality determine inspection modality selection and documentation rigor.
- Damage Detection:Post-impact assessment protocols identify barely visible impact damage that compromises compression-after-impact strength in flight-critical structures. Delta TechOps and United Airlines have established in-house composite inspection capabilities at Atlanta and San Francisco hubs specifically for Boeing 787 wing damage detection, bypassing traditional third-party MRO channels.
- Structural Integrity Analysis:Manufacturing verification ensures laminate stack-up conformity and cure quality before airworthiness certification.
- Delamination Characterization:Quantification of interlaminar crack propagation under cyclic loading supports damage tolerance calculations.
- Void Identification:Porosity mapping validates resin infusion completeness in resin transfer molded components.
- Fiber Orientation Assessment:Ultrasonic velocity anisotropy measurements verify ply angle alignment against design specifications.
Damage detection commands premium pricing; structural integrity analysis scales across highest unit volumes.
End User:
Procurement authority and capital access separate captive manufacturing inspection from third-party maintenance service provision.
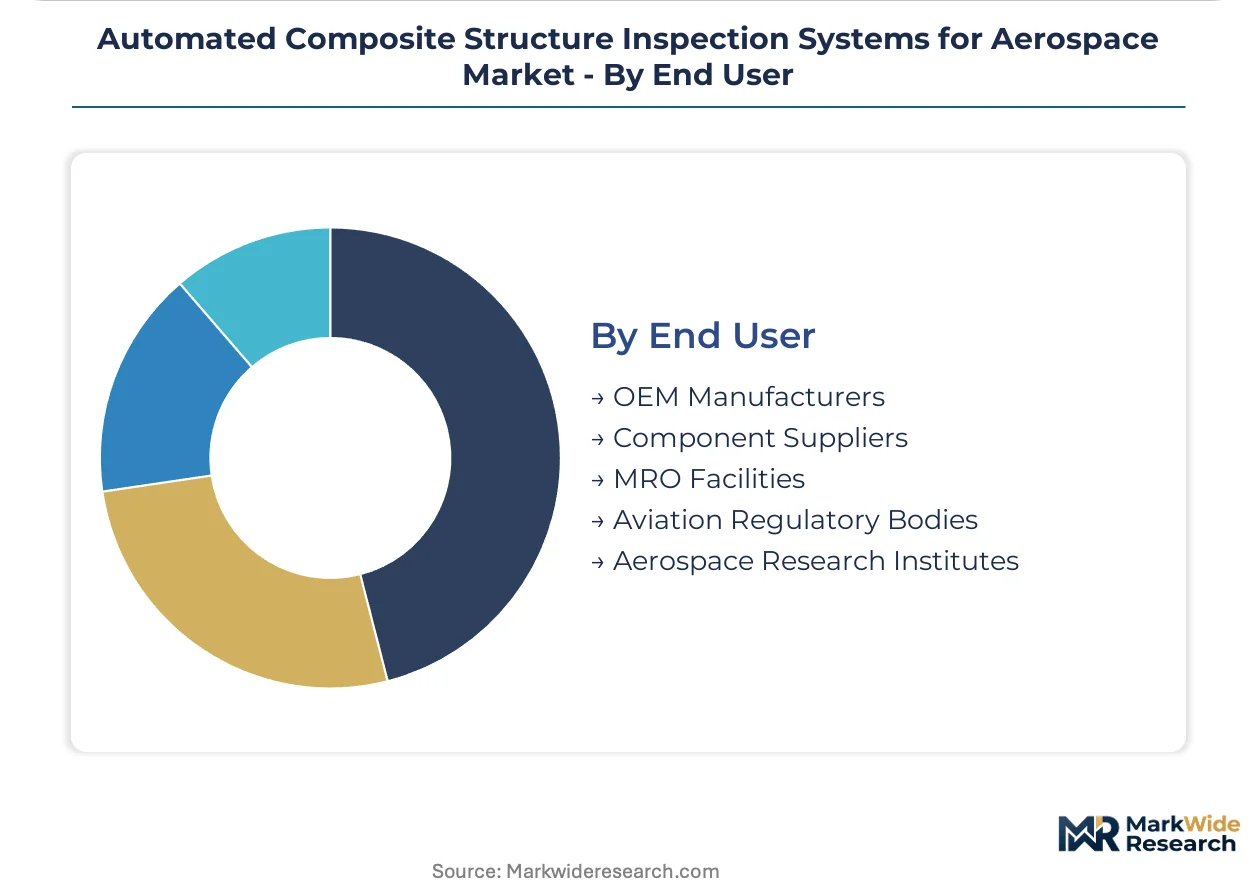
- MRO Facilities:Third-party maintenance networks including Lufthansa Technik and Air France Industries retrofit A350 fleets with permanently bonded ultrasonic transducers that stream delamination data to predictive maintenance platforms. EASA CS-25 amendments on composite continued airworthiness tighten inspection interval documentation, forcing European operators toward continuous-monitoring sensor networks rather than periodic manual checks.
- OEM Manufacturers:Boeing and Airbus production lines specify automated inspection cells for incoming material qualification and in-process verification.
- Component Suppliers:Tier-two aerostructure vendors face capital constraints that favor portable phased-array systems over gantry cells.
- Aviation Regulatory Bodies:FAA and EASA equipment qualification programs establish calibration standards and operator certification requirements.
- Aerospace Research Institutes:National laboratories advance machine-learning defect classification algorithms subject to emerging EU AI Act conformity obligations.
MRO facilities drive replacement demand; OEM manufacturers anchor new equipment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest installed base of gantry-mounted ultrasonic cells, while the United States leads in MRO automation adoption driven by FAA mandates. France, the United Kingdom, and India represent distinct growth vectors shaped by OEM production lines, defense procurement, and emerging indigenous manufacturing.
United States
Delta TechOps and United Airlines have established in-house composite inspection capabilities at Atlanta and San Francisco hubs specifically for Boeing 787 wing repairs. FAA airworthiness directives under 14 CFR Part 25 compel North American MRO facilities to automate delamination detection protocols. Seattle and Charleston production clusters anchor demand from Boeing's 787 and 777X assembly lines.
Germany
Airbus Hamburg and Premium Aerotec facilities anchor European adoption of phased-array ultrasonic systems for A350 wing skin laminates. EASA CS-25 amendments on composite continued airworthiness tighten inspection interval documentation across German MRO networks. Munich and Hamburg industrial corridors concentrate tier-one supplier investment in robotic gantry cells.
France
Air France Industries deploys permanently bonded ultrasonic transducers on A350 fleets streaming delamination data to predictive maintenance platforms. EASA mandates on damage tolerance documentation accelerate continuous-monitoring sensor network deployment. Toulouse aerospace cluster drives phased-array system procurement for in-production wing box verification.
United Kingdom
Rolls-Royce service centers reconfigure modular CT inspection cells between fan case and combustor liner geometries without gantry reconstruction. The country's national aerospace regulator aligns equipment qualification standards with EASA frameworks. Bristol and Derby maintenance hubs specialize in engine nacelle composite inspection automation.
India
Hindustan Aeronautics Limited's Tejas production line presents untapped demand for automated composite inspection as indigenous fighter output scales. The country's national defense procurement program prioritizes technology transfer requirements for inspection system vendors. Bangalore and Hyderabad defense aerospace clusters emerge as adoption frontiers for phased-array platforms.
Automated Composite Structure Inspection Systems for Aerospace Market Competitive Landscape
Top-tier vendors anchor multi-million-dollar gantry cell deployments, while mid-tier specialists occupy portable and modular niches. The market structures around capital intensity gradients separating OEM-integrated platforms from MRO-serviceable units. Three archetypes dominate: gantry-based large-structure specialists, CT-integrated engine component vendors, and portable phased-array providers for tier-two suppliers. Competitive moves concentrate on sensor-agnostic platform development and software-integrated defect classification modules.
Within the large-structure automation tier, Ingersoll Machine Tools and Waygate Technologies exemplify divergent technical anchoring strategies. Eddyfi Technologies occupies a position representing portable system specialization for capital-constrained component shops. TWI, as a research and technology organization, sits within the standards-development and certification-support archetype rather than pure equipment supply. These three entities collectively illustrate how vendor positioning fragments across production-scale, maintenance-flexibility, and regulatory-enablement vectors.
| Leading Market Players |
|---|
| Ingersoll Machine Tools |
| TWI |
| Waygate Technologies |
| Evident |
| Zetec |
| Eddyfi Technologies |
| FOERSTER |
| ScanMaster Systems |
| Nikon Metrology |
| Others |
Pricing and Supply Chain Analysis
Level III phased-array technician concentration in Hamburg and Toulouse creates labor-cost differentials that widen pricing-tier spreads between European gantry-cell deployments and North American MRO service contracts. Capital intensity at tier-one OEM facilities supports premium pricing for integrated robotic platforms, while tier-two suppliers face compressed margins on portable systems.
Pricing Analysis
The bundled-versus-unbundled service split separates OEM-integrated inspection cells from third-party MRO procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification-grade differentiation and after-sales software support intensity. Pricing pressure stems from airline unbundling of inspection contracts from OEM maintenance agreements, forcing vendors to compete on standalone service economics. Tier-three component shops exhibit highest price sensitivity due to capital constraints, while tier-one aerostructure suppliers prioritize defect resolution over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Airbus and Boeing mandate multi-supplier qualification for ultrasonic transducer arrays and robotic gantry subsystems, fragmenting procurement across German, Japanese, and US component vendors. Supply chains draw from precision-machined aluminum extrusions, piezoelectric ceramic elements, and machine-vision camera modules. Single-source vulnerability concentrates in high-frequency phased-array probe manufacturing, where specialized ceramics production rests on limited qualified suppliers. Distribution runs through direct OEM integration contracts and regional MRO service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as FAA and EASA damage tolerance mandates tighten inspection interval requirements across commercial fleets, embedding recurring equipment refresh cycles into airline operational planning.
For Market Incumbents: Lock in long-term service contracts with Delta TechOps and United Airlines before competing vendors establish in-house MRO capabilities at additional hub locations. Deepen software-integrated defect classification modules to meet emerging EU AI Act conformity obligations, creating switching costs for European operators. Vertical integration into phased-array probe manufacturing reduces exposure to ceramic element supply constraints.
For New Entrants and Emerging Players: EU AI Act conformity requirements in Europe open a window for software-native entrants to leapfrog hardware-incumbent certification delays. Target India's defense aerospace segment, where Hindustan Aeronautics Limited's Tejas production line lacks established automated inspection vendor relationships. Pursue partnership-based go-to-market models with national aerospace research institutes to accelerate regulatory qualification.
For Investors and Strategic Acquirers: Tier-one aerostructure suppliers are the most active acquirer in this space, seeking to internalize inspection capabilities and capture margin from OEM customers. Five-to-ten-year viability hinges on platform sensor-agnostic architecture that accommodates modality shifts without full system replacement. Watch for EASA-FAA certification divergence on autonomous inspection decision-making standards as inflection indicator for software deployment fragmentation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Agnostic Platform Development | Enables ultrasonic, thermographic, and radiographic module swapping without gantry reconstruction at Pratt & Whitney service centers. |
| EU AI Act Compliance Investment | Positions machine-learning defect classification modules for European market access ahead of regulatory enforcement. |
| Continuous-Monitoring Sensor Network Deployment | Supports EASA CS-25 amendment documentation requirements at Lufthansa Technik and Air France Industries. |
| Portable System Specialization | Penetrates tier-two component supplier shops where capital budgets constrain full gantry automation. |
| Modular CT Cell Configuration | Compresses capital deployment timelines for Rolls-Royce service centers reconfiguring between fan case and combustor geometries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MRO operations directors, OEM quality assurance leads, phased-array Level III technicians, and aerospace regulatory affairs specialists with secondary validation against FAA airworthiness directives, EASA CS-25 amendment documentation, customs equipment import records, and SEC filings from publicly traded automation vendors. Bottom-up equipment deployment tallies and top-down market sizing triangulated across manufacturing capacity announcements and airline fleet renewal schedules.
Historical reference periods anchored the forecast window to documented gantry-cell installations and MRO automation adoption curves across the analysis window. Segmentation dimensions modeled include inspection modality, technology physics, application criticality, and end-user procurement authority, with CAGRs derived from equipment replacement cycles and fleet expansion trajectories. Forecast inputs incorporated Boeing and Airbus production rate announcements alongside FAA damage tolerance directive implementation timelines.
Revisions become necessary when regulatory certification timelines for autonomous inspection decision-making diverge materially between FAA, EASA, and CAAC pathways, or when airline unbundling of inspection contracts accelerates beyond current hub-deployment patterns. Deviation in ceramic element supply availability or phased-array technician training throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market