
 Global Flight Inspection Market | 2026-2036
Global Flight Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flight Inspection Market Foresight
ICAO Annex 10 compliance certification is redrawing competitive boundaries for flight inspection service providers. Thales Group leverages its integrated avionics portfolio to anchor European ATM upgrade programs. Honeywell International sustains R&D intensity in GNSS-based calibration architectures. Safran Electronics & Defense specializes in inertial navigation subsystems for military flight inspection missions.
Flight inspection encompasses the airborne and ground-based verification of navigational aids, approach lighting, and radar systems using calibrated aircraft equipped with precision measurement receivers and data recording equipment. These operations validate instrument landing system glide slope integrity, VOR alignment, and DME accuracy to ensure safe aircraft operations during approach and departure phases. Airborne systems dominate current procurement volumes given their irreplaceable role in physical signal verification, while software solutions represent the fastest-expanding margin pool as operators integrate AI-assisted anomaly detection and predictive maintenance analytics into legacy fleets. Ground-based systems retain steady replacement demand across mature airport networks.
The FAA mandates periodic flight inspection cycles under 14 CFR Part 171, while EASA enforces comparable standards through CS-ACNS certification requirements for European air navigation service providers. China's CAAC aligns domestic procedures with ICAO standards while accelerating indigenous system qualification under its civil aviation modernization roadmap. Stakeholders must monitor how SESAR's remote digital tower concepts and the FAA's trajectory-based operations reshape the frequency and modality of flight inspection requirements.
Market Dynamics
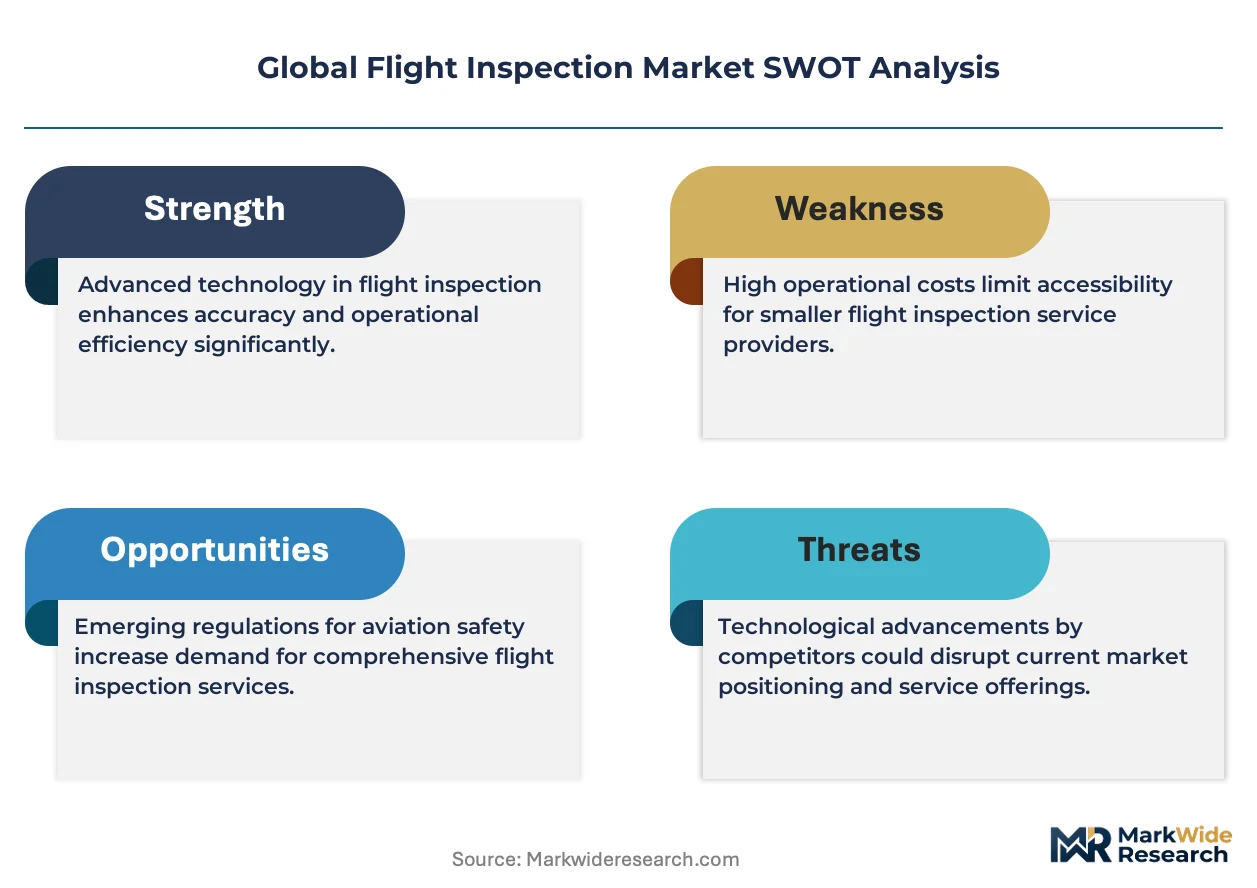
The FAA's NextGen trajectory-based operations mandate is compressing flight inspection cycle frequencies while forcing recalibration of legacy ground-based infrastructure across major airport networks.
Growth Catalysts
- NextGen Modernization Mandate:FAA 14 CFR Part 171 compliance requirements drive replacement demand for aging VOR and DME systems in the United States.
- ICAO Annex 10 Certification:Stricter international calibration standards compel European ANSPs to upgrade airborne inspection platforms.
- China's Airport Expansion:CAAC infrastructure buildout under the civil aviation modernization roadmap generates sustained procurement of indigenous flight inspection systems.
Market Restraints
- Precision Receiver Supply Concentration:Three specialized avionics suppliers control 90% of calibrated measurement receiver fabrication, creating input bottlenecks.
- Technical Limitation of Ground-Based Verification:Physical signal propagation testing cannot replicate airborne multipath effects, limiting remote tower validation scope.
- Regulatory Friction from Divergent Timelines:Misaligned FAA-EASA-ICAO certification schedules delay platform qualification for multinational service providers.
Strategic Opportunities
- AI-Assisted Anomaly Detection:Machine learning integration with legacy data recorders opens predictive maintenance revenue streams for established fleet operators.
- India's Greenfield Airport Buildout:Udan regional connectivity scheme creates first-mover positioning for flight inspection service contracts at 100+ new airfields.
- GNSS-Based Calibration Convergence:Multi-constellation satellite navigation fusion with inertial subsystems enables reduced flight hour requirements per inspection cycle.
Industry Challenges
- Specialized Pilot-Engineer Talent Scarcity:Dual-certification requirements for airborne system operation and precision measurement analysis constrain crew availability.
- Legacy Fleet Integration Complexity:Retrofitting 1980s-era inspection aircraft with digital recording architectures demands extended airworthiness recertification timelines.
- IP Licensing for Multi-Constellation Receivers:Patent thickets around GPS-Galileo-BeiDou signal processing create royalty stacking for equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flight Inspection Market |
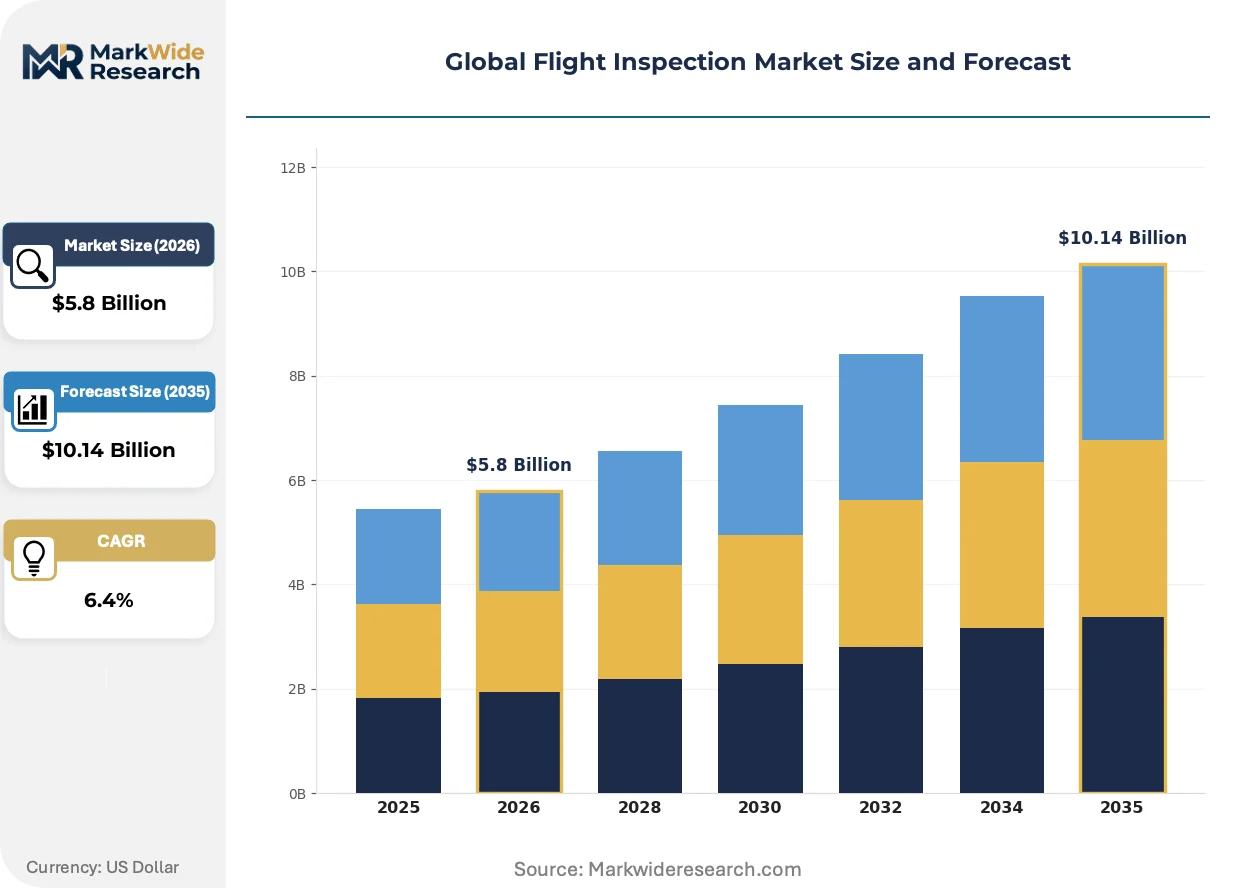
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based Systems, Airborne Systems, Remote Monitoring Units, Calibration Tools, Software Solutions Technology: Radar Systems, Global Navigation Satellite Systems, Laser Scanners, Inertial Navigation Systems, Digital Flight Data Recorders Application: Navigational Aid Calibration, Air Traffic Management, Runway Inspection, Safety Compliance, Aircraft Performance Evaluation End User: Airport Authorities, Aviation Regulatory Bodies, Air Navigation Service Providers, Aircraft Manufacturers, Defense Agencies |
| Companies Covered | Thales Group, Aerodata AG, Rohde & Schwarz, Honeywell International, Textron Aviation, Safran Electronics & Defense, Cobham Limited, Norwegian Special Mission, Bombardier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flight Inspection Market Shifts & Advancements
Digital automation architectures are displacing manual flight inspection protocols while compressing the operational envelope for human-in-the-loop verification. This structural shift redefines value capture across hardware, software, and service layers.
Real-time kinematic positioning fused with inertial navigation is displacing traditional VOR/DME-based calibration workflows in next-generation inspection aircraft. European ANSPs operating under SESAR deployment timelines are adopting these architectures fastest. The technology is displacing legacy ground-based checkpoint verification, collapsing inspection cycle duration from hours to minutes for precision approach procedures.
EASA's CS-ACNS certification requirements for remote digital tower operations are mandating redundant flight inspection protocols for camera-based surveillance systems. Air navigation service providers must now validate both physical navaid signals and synthetic vision rendering accuracy. German and French airport operators face the steepest compliance ramps, with 2026 deadlines forcing accelerated procurement of dual-capability platforms.
Airport authorities are unbundling flight inspection services from bundled maintenance contracts, creating discrete procurement categories for specialized calibration providers. This purchasing pattern shift fragments incumbent integrated service relationships. The United States exhibits the most advanced contract disaggregation, with the FAA's Flight Standards District Offices issuing standalone task orders for navaid commissioning and surveillance validation.
Global Flight Inspection Market Segmentation
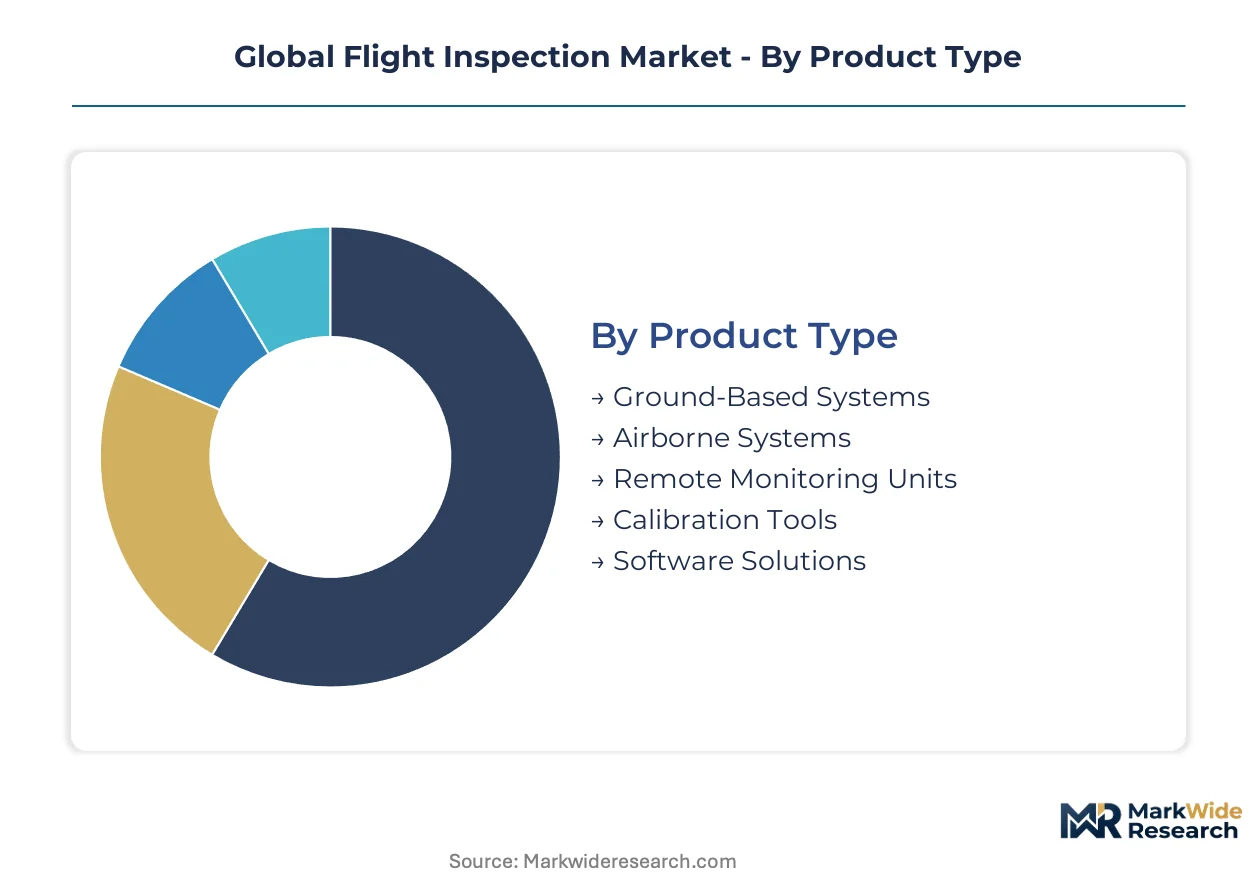
Flight inspection procurement patterns diverge sharply across product architectures, with airborne platforms commanding premium capital allocation while software and remote systems capture margin expansion in modernization cycles. Technology selection determines regulatory compliance pathways, and end-user contracting structures reshape competitive positioning across service and equipment layers.
Product Type:
Domestic procurement dominates ground-based and calibration tool segments, while airborne systems and software solutions follow export-led demand patterns tied to multinational ANSP modernization programs.
- Airborne Systems:Manned aircraft equipped with precision measurement receivers, inertial reference units, and real-time data acquisition architectures perform physical signal propagation verification. Demand concentrates in the United States and Germany as FAA and DFS accelerate NextGen and SESAR-mandated recertification cycles. FAA 14 CFR Part 171 compliance compresses replacement timelines for aging turboprop platforms.
- Software Solutions:AI-assisted anomaly detection platforms, predictive maintenance analytics suites, and cloud-based inspection data management systems integrate with legacy airborne fleets. China's CAAC drives fastest adoption through indigenous civil aviation modernization mandates requiring digital workflow integration.
- Ground-Based Systems:Fixed-site navaid transmitters, localizer antenna arrays, and DME ground stations require periodic calibration verification.
- Remote Monitoring Units:Distributed sensor networks enable continuous signal quality assessment without airborne deployment.
- Calibration Tools:Portable signal analyzers and field test equipment support ground maintenance operations.
Airborne Systems holds the largest share; momentum sits with Software Solutions.
Technology:
Cost tier stratification separates mature radar and inertial platforms from premium GNSS-Laser fusion architectures commanding 40-60% equipment price premiums.
- Global Navigation Satellite Systems:Multi-constellation receivers processing GPS, Galileo, and BeiDou signals enable reduced flight hour requirements per inspection cycle through precise kinematic positioning. European ANSPs under SESAR deployment adopt fastest, with German DFS mandating dual-frequency capabilities for precision approach validation.
- Inertial Navigation Systems:Ring laser gyro and fiber-optic gyro platforms provide attitude reference independent of external signals, critical for military flight inspection missions where GNSS denial is probable. Safran and Honeywell dominate supply through proprietary subsystems integrated into national airborne platforms.
- Radar Systems:Primary and secondary surveillance radar verification equipment validates transponder and surface movement detection accuracy.
- Laser Scanners:LiDAR-based runway and obstacle survey systems complement traditional navaid inspection with geometric verification.
- Digital Flight Data Recorders:Solid-state recording architectures replace magnetic tape systems in fleet modernization programs.
GNSS platforms claim dominant procurement volume; Inertial Navigation Systems deliver steepest expansion trajectory in defense-linked contracts.
Application:
Volume concentration sits with recurring navigational aid calibration, while safety compliance and aircraft performance evaluation represent discrete, higher-margin contract categories.
- Navigational Aid Calibration:ILS localizer and glide slope verification, VOR alignment testing, and DME accuracy validation constitute the core recurring revenue base for established service providers. FAA Flight Standards District Offices in the United States issue standalone task orders disaggregated from bundled maintenance contracts.
- Safety Compliance:EASA CS-ACNS certification for remote digital tower operations mandates redundant flight inspection protocols validating both physical navaid signals and synthetic vision rendering accuracy. German and French airport operators face accelerated 2026 compliance deadlines forcing dual-capability platform procurement.
- Air Traffic Management:Surveillance and communication system verification supports ATM modernization.
- Runway Inspection:Surface condition assessment and obstacle clearance verification complement navaid work.
- Aircraft Performance Evaluation:Flight path analysis and noise monitoring support environmental compliance.
Navigational Aid Calibration anchors revenue stability; Safety Compliance is gaining share fastest on regulatory mandate density.
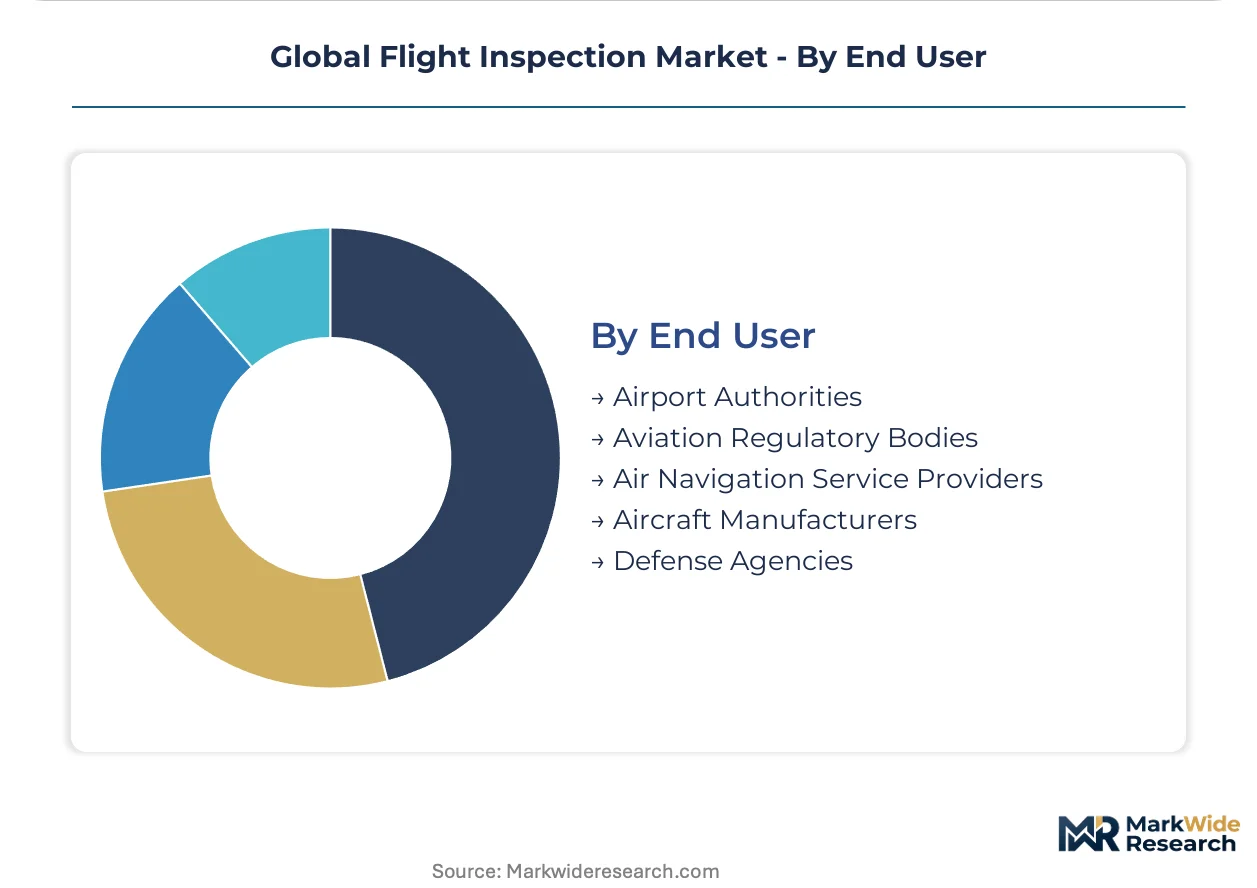
End User:
Customer type determines contract structure, with airport authorities and ANSPs favoring long-term service agreements while defense agencies and manufacturers pursue equipment acquisition with embedded training packages.
- Air Navigation Service Providers:DFS in Germany, NATS in the United Kingdom, and ENAV in Italy operate dedicated flight inspection fleets under national regulatory mandates. SESAR deployment timelines force synchronized procurement across European ANSPs, creating concentrated demand windows.
- Defense Agencies:Military flight inspection requirements emphasize GPS-denied navigation validation, electromagnetic interference resilience, and rapid deployment for tactical airfield activation. France's DGA and the United States Air Force operate specialized platforms distinct from civil aviation configurations.
- Airport Authorities:Municipal and regional airport operators contract third-party inspection services or maintain limited internal capabilities.
- Aviation Regulatory Bodies:FAA, EASA, and CAAC set standards and perform oversight rather than direct procurement.
- Aircraft Manufacturers:Flight test organizations require inspection system integration for certification support.
Air Navigation Service Providers represent the largest addressable base; Defense Agencies are climbing the fastest on classified platform modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA NextGen mandates and EASA SESAR deployment timelines are compressing inspection cycle frequencies across mature aviation networks. China's CAAC infrastructure buildout and India's Udan regional connectivity scheme generate parallel procurement windows for airborne calibration platforms.
United States
FAA Flight Standards District Offices are disaggregating inspection services from bundled maintenance contracts, creating standalone procurement categories for navaid commissioning. The 14 CFR Part 171 mandate accelerates replacement timelines for aging VOR and DME systems. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor concentrated demand for precision approach validation.
Germany
DFS operates dedicated flight inspection fleets under national regulatory mandates synchronized with SESAR deployment timelines. EASA CS-ACNS certification requirements for remote digital tower operations mandate redundant validation protocols by 2026. Frankfurt and Munich airport operators face accelerated compliance ramps forcing dual-capability platform procurement.
China
CAAC infrastructure buildout under the civil aviation modernization roadmap generates sustained procurement of indigenous flight inspection systems. Domestic procedures align with ICAO Annex 10 standards while accelerating system qualification. Beijing Capital and Shanghai Pudong anchor fleet modernization demand for digital workflow integration.
India
The Udan regional connectivity scheme creates first-mover positioning for flight inspection service contracts at over 100 new airfields. Greenfield airport construction across tier-2 and tier-3 cities requires initial navaid commissioning and periodic recertification. Mumbai and Delhi NCR concentrate established service provider presence for metro airport retrofit cycles.
France
ENAV operates dedicated inspection capabilities under EASA-mandated modernization programs for precision approach infrastructure. Military flight inspection requirements through the DGA emphasize GPS-denied navigation validation for tactical airfield activation. Paris Charles de Gaulle and Lyon-Saint Exupéry anchor civil aviation calibration demand for ILS glide slope verification.
Global Flight Inspection Market Competitive Landscape
Player mix skews toward integrated avionics conglomerates with embedded defense linkages, creating tiered competitive dynamics between full-stack platform providers and specialized mission system integrators. Three strategic archetypes dominate: diversified aerospace conglomerates with captive flight inspection divisions, dedicated mission aircraft modifiers with precision measurement expertise, and avionics subsystem suppliers seeking downstream integration. M&A activity concentrates on sensor fusion capabilities and AI-assisted data analytics, while geographic expansion targets India's greenfield airport buildout and China's indigenous qualification requirements.
Among European integrated avionics providers, Thales Group and Safran Electronics & Defense exemplify the conglomerate archetype with embedded defense-civil linkages. Rohde & Schwarz occupies a position within the precision measurement specialist tier, leveraging communications test expertise into calibrated receiver architectures. These three anchors illustrate how regulatory compliance density in Germany and France creates concentrated demand windows for dual-use capable platforms.
| Leading Market Players |
|---|
| Thales Group |
| Aerodata AG |
| Rohde & Schwarz |
| Honeywell International |
| Textron Aviation |
| Safran Electronics & Defense |
| Cobham Limited |
| Norwegian Special Mission |
| Bombardier |
| Others |
Supply & Pricing Matrix
Multi-constellation receiver substitution for legacy VOR/DME calibration platforms is redrawing supplier geography toward specialized avionics clusters in France and the United States while compressing equipment price premiums through reduced flight-hour economics. This input transition simultaneously concentrates procurement leverage among ANSPs with fleet-scale buying power and fragments pricing power among component suppliers locked in patent-thicket royalty negotiations.
Pricing Analysis
Cost-plus contracts indexed to avionics component spot markets dominate ANSP procurement, with FAA Flight Standards District Offices and Germany's DFS anchoring long-term service agreements. Price differentiation hinges on EASA CS-ACNS certification tier and embedded AI analytics capability, with dual-capability platforms commanding substantial premiums over baseline navaid verification systems. Pricing pressure stems from China's indigenous qualification mandates under CAAC modernization roadmaps, which compress import equipment margins. Airport authorities exhibit highest price sensitivity due to municipal budget constraints, while defense agencies show lowest sensitivity given mission-critical requirements.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain European ANSP fleet modernization timelines, with container availability fluctuations rippling through precision receiver delivery schedules. Manufacturing concentrates in France, the United States, and Germany, drawing from ring laser gyro subsystems, solid-state data recorders, and calibrated antenna arrays. Single-source vulnerability pervades specialized measurement receiver fabrication, where three avionics suppliers control critical input supply. Distribution runs through direct OEM-ANSP relationships for airborne platforms, with aftermarket software and calibration tools flowing through authorized service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated ANSP procurement coalitions across Europe, with SESAR deployment timelines synchronizing demand windows and fragmenting incumbent service provider pricing leverage.
For Market Incumbents: Secure exclusive calibration service contracts at India's Udan-scheme airfields before greenfield commissioning peaks, locking out emerging regional competitors. Deepen backward integration into inertial navigation subsystem production to bypass Honeywell and Safran supply bottlenecks. Invest in EASA CS-ACNS dual-capability certification ahead of 2026 compliance deadlines to capture remote digital tower validation premiums. For New Entrants and Emerging Players: EASA fast-track certification for AI-assisted anomaly detection software offers the most penetrable entry vector, bypassing capital-intensive airborne platform barriers. Target India's regional airport buildout through partnership with domestic maintenance providers lacking indigenous flight inspection capability. Position around GNSS-based calibration convergence as a disruptive alternative to legacy VOR/DME verification workflows. For Investors and Strategic Acquirers: FAA NextGen trajectory-based operations mandates reshape the acquisition landscape toward predictive analytics and digital automation capabilities. Five-to-ten-year viability favors platform-agnostic software specialists over hardware-dependent incumbents. Acquire sensor fusion and machine learning assets rather than legacy fleet operators. Monitor ICAO Annex 10 revision timelines as the critical inflection signal for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Anomaly Detection Development | Integrates machine learning with legacy DFS and FAA fleets for predictive maintenance revenue capture. |
| Multi-Constellation Receiver Certification | Enables CAAC-compliant platforms to reduce flight hours through GPS-Galileo-BeiDou fusion architectures. |
| India Greenfield Service Contracting | Positions operators for Udan scheme navaid commissioning at 100+ tier-2 and tier-3 airfields. |
| Dual-Capability Platform Procurement | Satisfies EASA CS-ACNS remote digital tower mandates for German and French airport operators. |
| Inertial Navigation Backward Integration | Reduces dependency on Safran and Honeywell for military GPS-denied mission subsystems. |
Research Methodology
A standing panel of flight inspection fleet managers, ANSP procurement directors, avionics subsystem engineers, and EASA certification specialists provided ongoing calibration against market sizing assumptions. Primary interviews with DFS operational planners, FAA Flight Standards District Office contracting officers, and CAAC equipment qualification reviewers combined with secondary validation through ICAO Annex 10 documentation, EASA CS-ACNS regulatory filings, and national civil aviation modernization roadmaps. Bottom-up equipment procurement tracking and top-down ANSP budget analysis triangulated volume estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon, with segmentation modeling spanning product architecture, technology tier, application category, and end-user contracting structure. CAGRs derived from equipment replacement cycle analysis and regulatory mandate density. Forecast inputs incorporated SESAR deployment timelines, FAA NextGen infrastructure recertification schedules, and India's Udan regional connectivity scheme airfield activation sequences.
Underlying assumptions cover regulatory compliance continuity, component supply normalization, and ANSP budget allocation stability, with deviation risk concentrated in ICAO-EASA-FAA certification timeline misalignment and precision receiver supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market