
 Aerospace Data Recorder Market | 2026-2036
Aerospace Data Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Data Recorder Market Analysis
Project finance tied to fleet renewal programs is rewriting capital deployment patterns across the aerospace data recorder supply chain. Honeywell International Inc. leverages its integrated avionics portfolio to bundle recorder systems with flight management platforms. L3Harris Technologies anchors military aviation demand through ruggedized recorders built to MIL-STD-810 specifications. Curtiss-Wright Corporation competes on crash-protected memory modules that sustain data integrity through extreme thermal and impact events.
An aerospace data recorder is a crash-hardened device engineered to capture flight parameters, audio from the cockpit, and system status at sampling rates exceeding 256 words per second, with housings forged from stainless steel or titanium alloys rated for 3,400 g impact and 1,100 degrees Celsius fire exposure. Solid-state technology dominates new installations due to its absence of moving parts and superior data retrieval rates after submerged recovery events. Magnetic tape persists in retrofit markets and aging cargo fleets where replacement cycles lag commercial aviation by seven to ten years. Commercial aviation generates the deepest margin pools as original equipment manufacturers bundle recorders with avionics suites on narrow-body platforms.
The FAA mandates 25-hour cockpit voice recording and 25-hour flight data recording under updated Part 121 regulations, while EASA enforces equivalent requirements through its Air Operations Regulation. ICAO standards for underwater locator beacon transmission duration have extended to 90 days, forcing hardware refresh cycles across installed bases. Stakeholders must monitor divergence between FAA and EASA certification timelines for next-generation recorder architectures integrating real-time data streaming capabilities.
Market Dynamics
Solid-state memory architectures are compressing replacement cycles across installed commercial fleets as FAA and EASA mandates force hardware refreshes ahead of traditional obsolescence timelines.
Growth Catalysts
- Extended Recording Mandates:FAA Part 121 now requires 25-hour cockpit voice and flight data retention, forcing upgrades across narrow-body and wide-body platforms operating in US airspace.
- China's Fleet Expansion:COMAC final assembly lines in Shanghai are driving original equipment procurement for C919 and ARJ21 platforms entering commercial service.
- Underwater Locator Beacon Standards:ICAO's 90-day transmission duration requirement is digitizing hardware specifications across crash-survivable memory modules.
Market Restraints
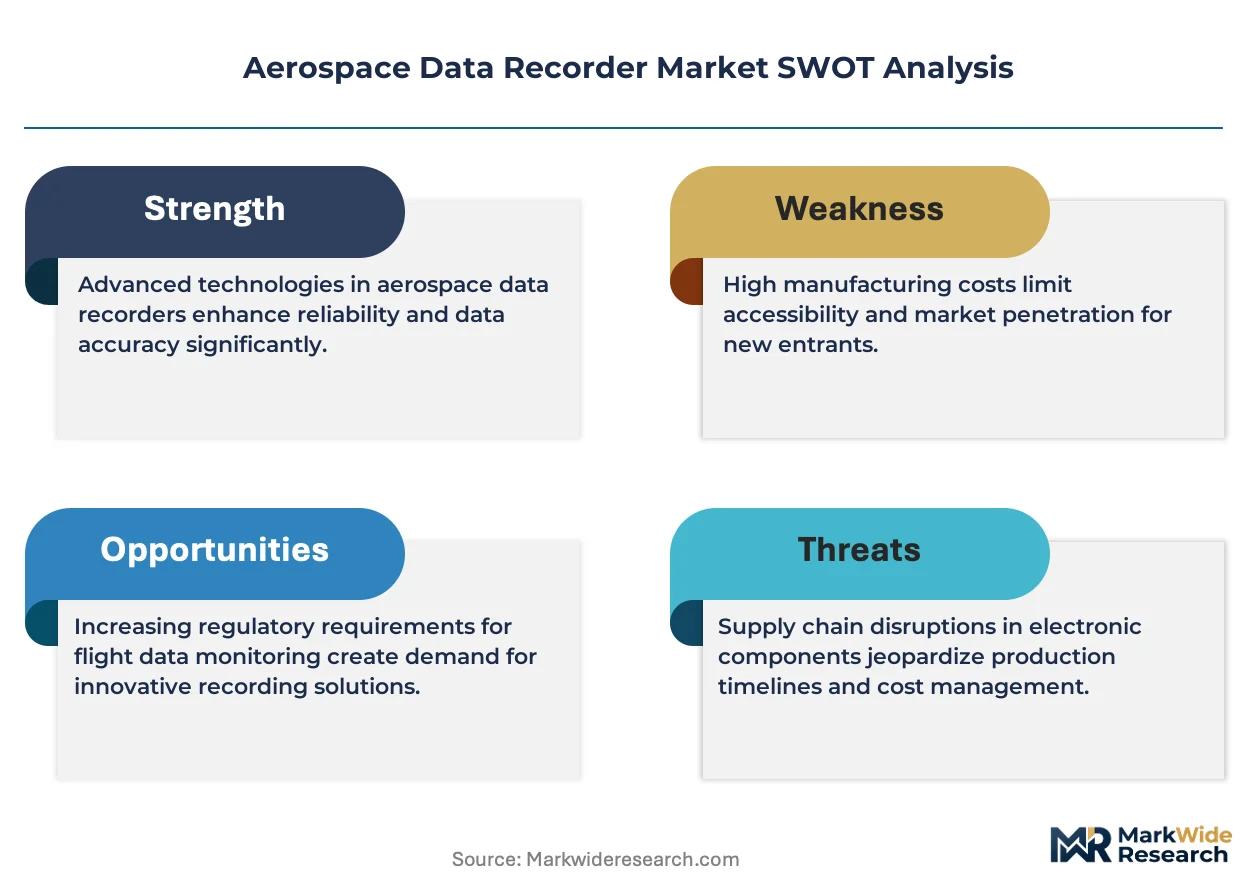
- Titanium Alloy Supply Concentration:Crash-protected housings depend on aerospace-grade titanium feedstock concentrated in Russian and Chinese smelter capacity, exposing manufacturers to geopolitical input volatility.
- Certification Timeline Friction:Divergence between FAA and EASA approval pathways for real-time streaming recorders is extending time-to-revenue for next-generation architectures.
- Magnetic Tape Persistence:Aging cargo fleets and retrofit markets retain legacy tape systems where replacement cycles lag commercial aviation by seven to ten years, fragmenting addressable demand.
Strategic Opportunities
- Real-Time Data Streaming:Satellite connectivity integration with recorder systems opens predictive maintenance revenue streams for engine OEMs and fleet operators.
- Military Platform Modernization:MIL-STD-810 ruggedized specifications create insulated demand pools as defense procurement decouples from commercial aviation cyclicality.
- India's Fleet Growth:IndiGo and Air India narrow-body orders are concentrating MRO and original equipment demand in Mumbai and Delhi maintenance clusters.
Industry Challenges
- Embedded Software Expertise Scarcity:Crash-survivable firmware development requires specialized talent pools concentrated at Honeywell, L3Harris, and Curtiss-Wright, constraining new vendor entry.
- Retrofit Integration Complexity:Solid-state recorders must interface with legacy ARINC 573 and ARINC 717 data buses on aging Boeing 737NG and Airbus A320ceo fleets without airframe recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Data Recorder Market |
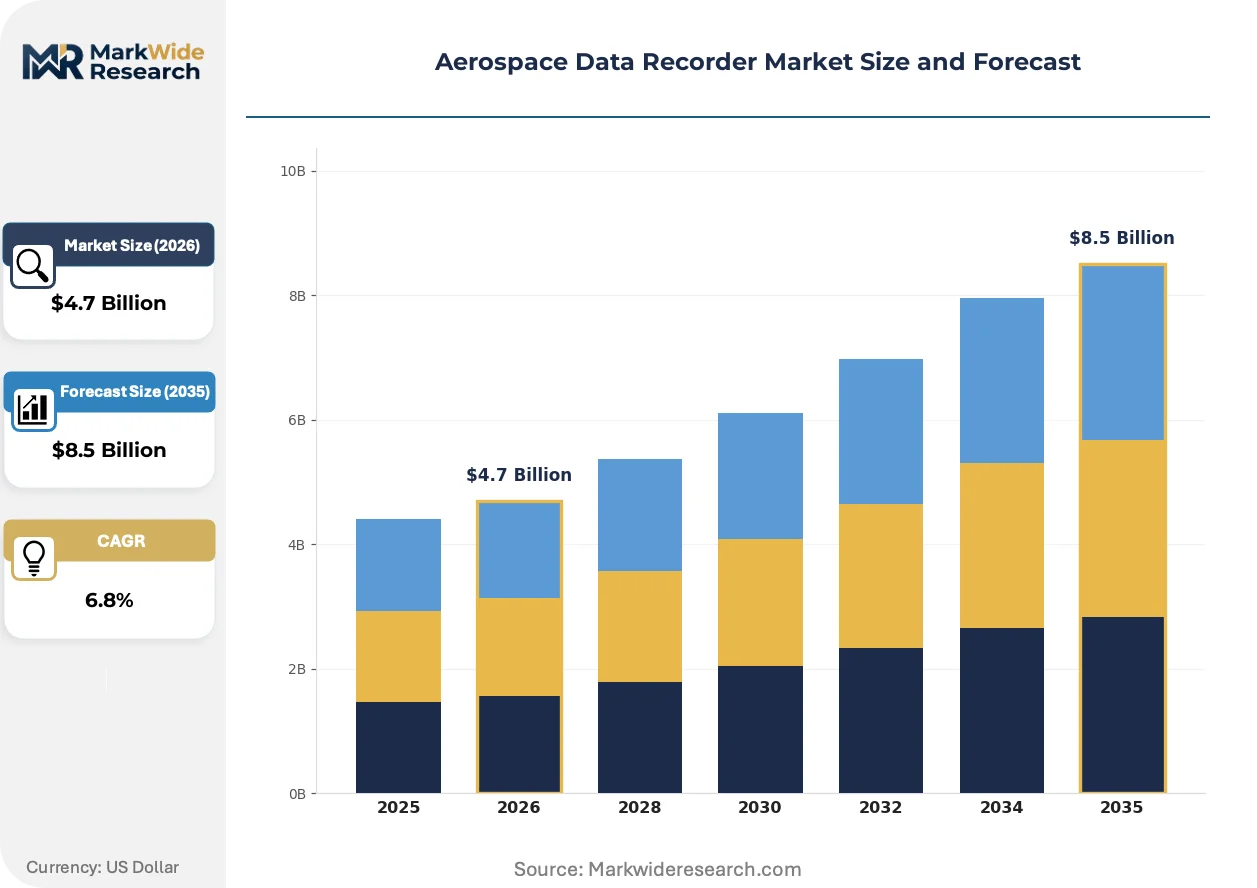
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Data Recorder, Cockpit Voice Recorder, Underwater Locator Beacon, Quick Access Recorder End User: Commercial Aviation, Military Aviation, Private Aviation, Cargo Operations Technology: Solid-State, Magnetic Tape, Optical, Hybrid Systems Application: Crash Investigation, Performance Monitoring, Regulatory Compliance, Maintenance Planning |
| Companies Covered | Honeywell International Inc., L3Harris Technologies, Curtiss-Wright Corporation, Teledyne Technologies, Leonardo DRS, Universal Avionics Systems Corporation, RUAG AG, AstroNova Inc., FLYHT Aerospace Solutions Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Data Recorder Market Emerging Trajectories
Recorder architectures are converging with connectivity platforms, compressing the boundary between crash-survivable storage and operational data infrastructure. Three developments are restructuring competitive positioning.
Edge computing integration is digitizing how flight parameter data is processed before storage. Solid-state recorders now embed pre-crash analytics engines that filter and compress data streams at 256 words per second sampling rates. Commercial airlines are adopting these modules to reduce post-incident download latency from hours to minutes.
EASA's Air Operations Regulation amendments are mandating synchronized cockpit image recording alongside audio and parametric data. This policy expansion is forcing recorder manufacturers to expand memory capacity by 40% without increasing housing dimensions. Wide-body platforms serving European routes are prioritizing compliance ahead of 2027 enforcement deadlines.
Airlines are unbundling recorder maintenance from avionics suite contracts. Carriers now source crash-protected memory module replacements through independent MRO channels rather than OEM-locked service agreements. This shift is most visible in the United States where Delta TechOps and American Airlines maintenance divisions have established standalone procurement authority for recorder subsystems.
Aerospace Data Recorder Market Segmentation
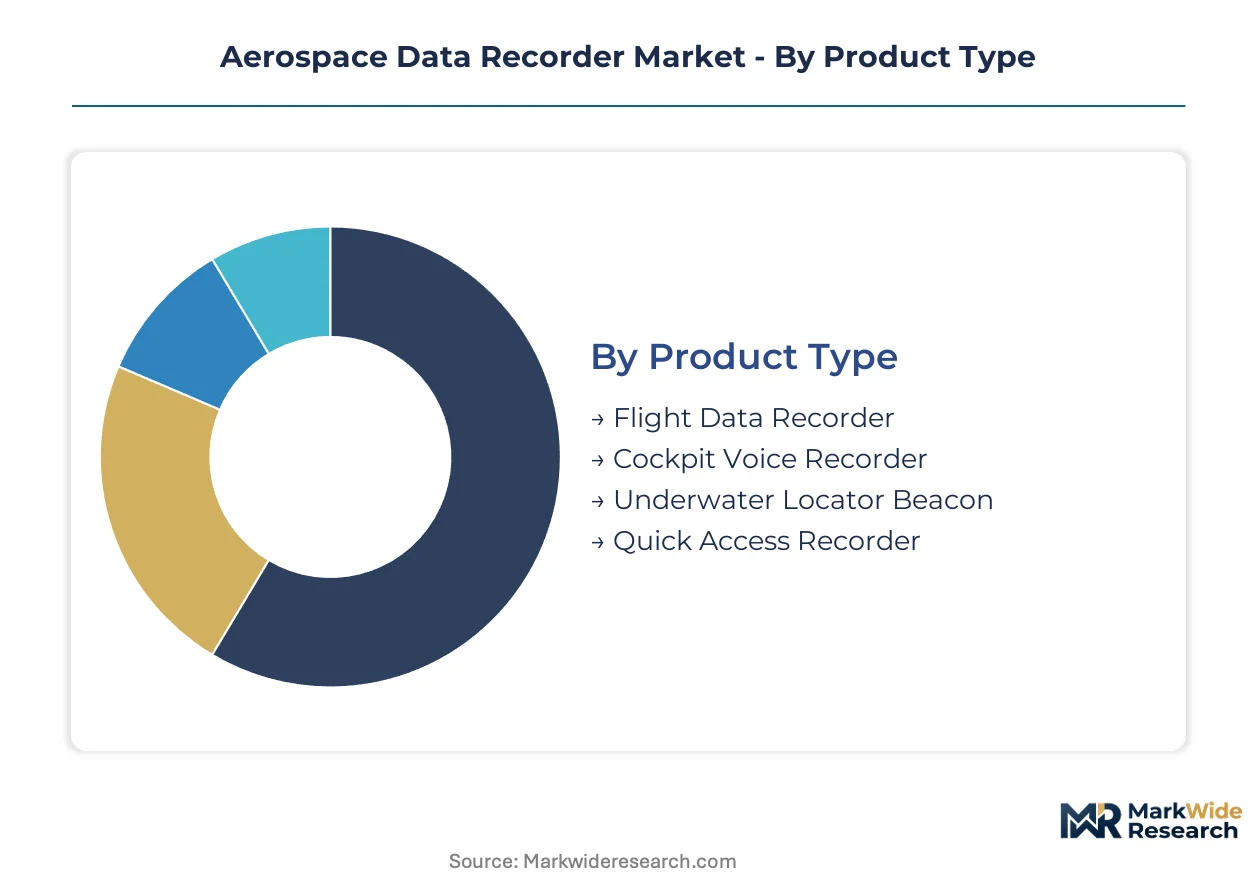
Aerospace data recorder procurement patterns diverge sharply across operational contexts, with regulatory mandates, fleet age profiles, and connectivity requirements fragmenting demand into distinct technology and end-use clusters. Understanding these fault lines reveals where capital deployment concentrates and where replacement cycles accelerate.
Product Type:
Flight deck architectures demand specialized recording systems calibrated to distinct data capture requirements, crash survivability standards, and retrieval protocols.
- Flight Data Recorder:Solid-state memory modules sample flight parameters at 256 words per second, with titanium housings rated for 3,400 g impact. Narrow-body platforms at Boeing and Airbus final assembly lines in the United States and France anchor original equipment demand.
- Cockpit Voice Recorder:Multi-channel audio capture systems retain 25 hours of crew communications under FAA Part 121 mandates. Retrofit demand concentrates in aging narrow-body fleets where hardware refresh cycles precede airframe retirement.
- Underwater Locator Beacon:Acoustic pingers transmit at 37.5 kHz for 90 days per ICAO standards, forcing hardware refreshes across installed commercial bases.
- Quick Access Recorder:Removable solid-state cartridges enable rapid data download for routine performance analysis without crash-protected housing overhead.
The dominant share belongs to Flight Data Recorder systems, while Cockpit Voice Recorder retrofit demand is closing the gap fastest as 25-hour mandates extend across jurisdictions.
End User:
Procurement authority and budget cycles vary dramatically between scheduled passenger operators, defense procurement channels, and cargo fleet managers.
- Commercial Aviation:Scheduled carriers bundle recorder procurement with avionics suite contracts at airframe delivery. Narrow-body fleet expansion at COMAC final assembly in Shanghai concentrates original equipment demand.
- Military Aviation:MIL-STD-810 ruggedized specifications drive specialized procurement through defense acquisition channels insulated from commercial cyclicality.
- Private Aviation:Business jet operators face lighter regulatory mandates but adopt solid-state architectures for insurance premium reductions.
- Cargo Operations:Aging freighter fleets retain magnetic tape systems where replacement cycles lag passenger aviation by seven to ten years.
Commercial Aviation commands the deepest procurement volumes, though Military Aviation offers the most stable demand trajectory through multi-year defense appropriations.
Technology:
Memory architecture selection determines crash survivability, data retrieval latency, and interface compatibility with legacy flight deck systems.
- Solid-State:Flash memory arrays with no moving parts sustain data integrity through 1,100 degrees Celsius fire exposure and deep-sea pressure. FAA and EASA mandates are forcing displacement of legacy architectures across narrow-body and wide-body platforms.
- Magnetic Tape:Helical scan recording persists in retrofit markets and cargo conversions where capital constraints delay hardware refresh.
- Optical:Write-once media architectures serve specialized military applications requiring tamper-evident data chains.
- Hybrid Systems:Dual-memory configurations bridge solid-state primary storage with tape backup for transitional fleet architectures.
Solid-State architectures dominate new installations, while Hybrid Systems are gaining share fastest among operators managing mixed-generation fleets.
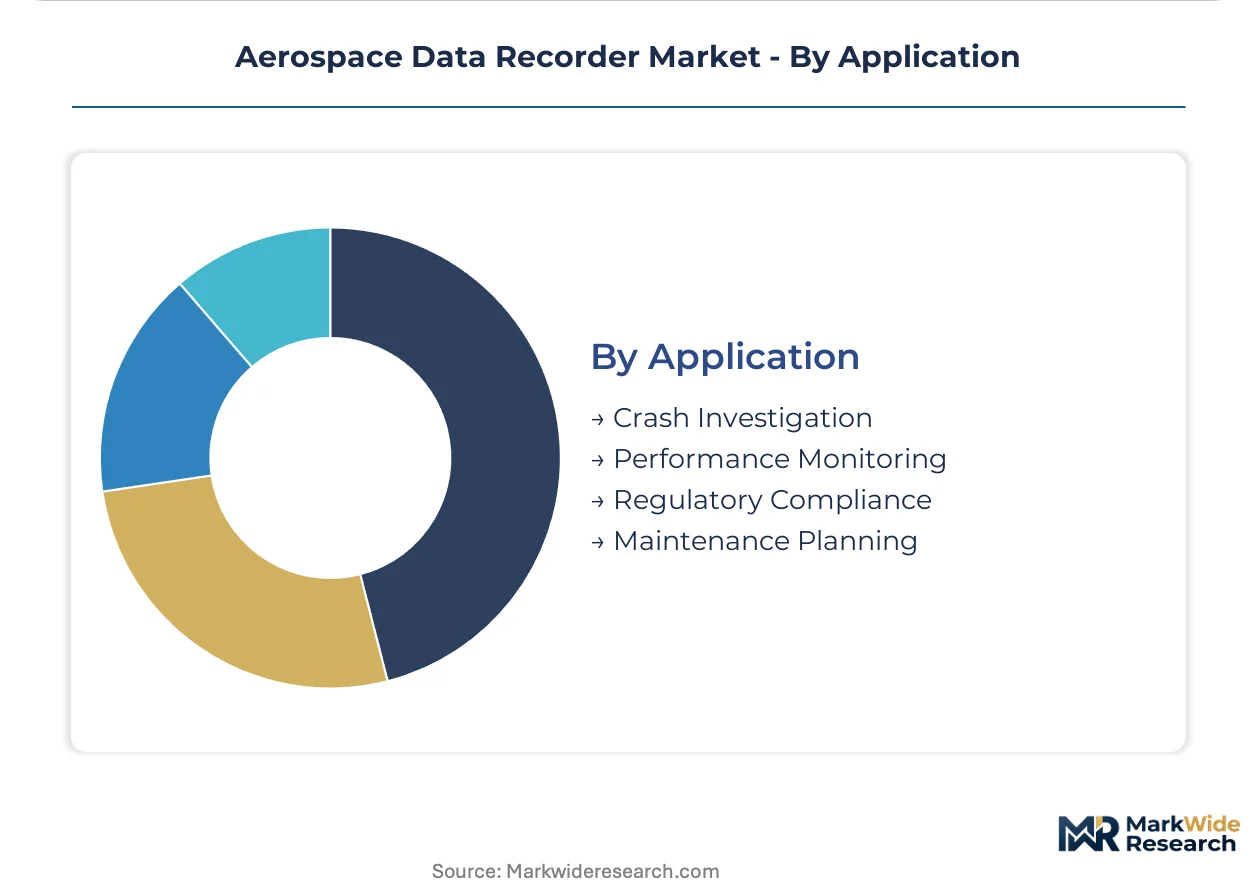
Application:
Data retrieval purpose shapes recorder specification, with post-incident investigation demanding higher crash survivability than operational performance analysis.
- Crash Investigation:Crash-protected memory modules must survive 3,400 g impact and prolonged saltwater immersion. ICAO's 90-day underwater locator beacon mandate is digitizing hardware specifications.
- Performance Monitoring:Quick access recorders enable engine health monitoring and fuel efficiency optimization without crash-hardened housing costs.
- Regulatory Compliance:FAA Part 121 and EASA Air Operations Regulation mandates drive baseline recorder installation across all certificated operations.
- Maintenance Planning:Predictive algorithms applied to flight parameter data reduce unscheduled downtime for narrow-body operators.
Regulatory Compliance underpins baseline demand, yet Performance Monitoring applications are expanding most quickly as airlines unbundle recorder data for operational analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of aerospace data recorders track final assembly line locations, with the United States, France, and China posting structural trade surpluses in crash-protected memory modules. Import dependence concentrates among MRO hubs in India and Southeast Asia where narrow-body fleet expansion outpaces domestic manufacturing capacity.
United States
Boeing's final assembly lines in Everett and Charleston drive original equipment procurement for 737 MAX and 787 platforms. FAA Part 121 mandates for 25-hour cockpit voice and flight data recording force hardware refreshes across domestic carrier fleets. Dallas-Fort Worth and Atlanta maintenance clusters concentrate retrofit demand as American Airlines and Delta Air Lines unbundle recorder procurement from OEM service agreements.
France
Airbus final assembly in Toulouse anchors European demand for solid-state flight data recorders on A320neo and A350 programs. EASA Air Operations Regulation amendments mandating synchronized cockpit image recording expand memory capacity requirements by 2027. Paris-Saclay aerospace engineering corridor houses specialized firmware development talent for crash-survivable architectures.
China
COMAC C919 and ARJ21 certification drives domestic procurement through Shanghai final assembly lines. MIIT standards for indigenous avionics systems prioritize local recorder suppliers for state-owned carrier fleets. Chengdu and Xi'an aerospace clusters develop titanium housing forging capacity to reduce import dependence for crash-protected enclosures.
India
IndiGo and Air India narrow-body orders concentrate MRO demand in Mumbai and Delhi maintenance hubs. DGFT import licensing for avionics components creates procurement friction for solid-state recorder retrofits on aging A320ceo fleets. Bangalore aerospace park attracts subsystem suppliers seeking proximity to Hindustan Aeronautics Limited military platform programs.
United Kingdom
Rolls-Royce engine health monitoring programs drive quick access recorder adoption for performance analytics on long-haul fleets. UK CAA alignment with EASA extended recording mandates forces hardware upgrades ahead of Brexit-adjusted certification timelines. Broughton and Bristol aerospace clusters specialize in underwater locator beacon integration for wide-body export programs.
Aerospace Data Recorder Market Vendor Landscape
On the supply side, the industry is consolidated around three dominant integrated avionics suppliers with captive recorder divisions, supplemented by specialized crash-protected memory module fabricators. Strategic archetypes divide between full-flight-deck integrators bundling recorders with flight management systems, standalone recorder specialists competing on crash survivability specifications, and connectivity platform vendors embedding storage within satellite communications architectures. Competitive moves center on vertical integration into titanium alloy housing supply and technology licensing partnerships for real-time data streaming capabilities.
Within the integrated avionics tier, Honeywell International Inc. and L3Harris Technologies exemplify full-system bundling strategies that lock recorder procurement into broader flight deck contracts. Curtiss-Wright Corporation occupies a position among standalone specialists competing on MIL-STD-810 ruggedization and extreme environment data integrity. These three anchors demonstrate how competitive positioning splits between bundled avionics suites and specialized crash-survivable subsystems.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| L3Harris Technologies |
| Curtiss-Wright Corporation |
| Teledyne Technologies |
| Leonardo DRS |
| Universal Avionics Systems Corporation |
| RUAG AG |
| AstroNova Inc. |
| FLYHT Aerospace Solutions Ltd. |
| Others |
Supply Flow & Price Mechanics
Chengdu and Xi'an aerospace clusters in China are forging titanium housings for crash-protected memory modules, concentrating upstream metallurgical capacity and amplifying pricing leverage for domestic recorder suppliers serving COMAC final assembly lines. This geographic supply concentration shapes procurement economics across the aerospace data recorder value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across FAA/EASA dual-certified premium tiers, single-jurisdiction standard tiers, and cargo retrofit economy tiers. Price differentiation hinges on crash survivability certification grade and titanium alloy sourcing origin. Cost compression in the economy tier is intensifying as magnetic tape retrofit demand fragments. Cargo fleet managers exhibit highest price sensitivity, while military procurement channels show lowest sensitivity due to MIL-STD-810 specification rigidity.
Supply Chain Analysis
Aerospace-grade titanium feedstock draws from Russian and Chinese smelter capacity, with solid-state memory chips resting on Taiwanese and South Korean semiconductor fabrication. Crash-protected housing forging depends on precision machining equipment anchored in German and Japanese supply bases. Single-source vulnerability concentrates in titanium alloy procurement channels. Distribution runs through avionics OEM bundling agreements and independent MRO procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time data streaming integration with satellite connectivity platforms is redefining recorder architectures as edge-computing nodes within flight operations ecosystems, creating interoperability dependencies between crash-survivable storage and predictive maintenance infrastructure.
For Market Incumbents: Insulate bundled avionics-recorder contracts against unbundling trends by embedding firmware-level integration with flight management systems that standalone specialists cannot replicate. Deepen backward integration into titanium housing forging capacity to neutralize Russian and Chinese feedstock volatility. Prioritize EASA cockpit image recording certification ahead of enforcement deadlines to lock out retrofit competitors.
For New Entrants and Emerging Players: Build out independent MRO channel relationships with Delta TechOps and American Airlines maintenance divisions where procurement authority has decoupled from OEM service agreements. Target India's Mumbai and Delhi maintenance clusters where DGFT licensing friction delays incumbent solid-state retrofits. Pursue quick access recorder specialization for engine health monitoring applications with lower crash survivability overhead.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors crash-survivable firmware developers with embedded software expertise scarcity concentrated at established suppliers. Long-term viability hinges on real-time streaming architecture patents and satellite connectivity integration capabilities. Watch for divergence between FAA and EASA certification timelines as inflection indicator for next-generation recorder revenue recognition delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Data Streaming Integration | Opens predictive maintenance revenue streams for engine OEMs and fleet operators through satellite connectivity. |
| Backward Integration into Titanium Forging | Neutralizes geopolitical feedstock volatility from Russian and Chinese smelter concentration. |
| EASA Cockpit Image Recording Certification | Captures 40% memory capacity expansion demand ahead of 2027 enforcement deadlines. |
| Independent MRO Channel Development | Exploits unbundling trend where carriers source recorder subsystems outside OEM-locked agreements. |
| MIL-STD-810 Ruggedization Specialization | Creates insulated demand pools as defense procurement decouples from commercial aviation cyclicality. |
Methodological Framework
Cross-validation between primary interviews with avionics procurement directors, fleet maintenance managers, and crash-survivable firmware engineers and secondary validation through FAA Part 121 regulatory filings, EASA Air Operations Regulation amendments, and ICAO standards documentation anchors the qualitative findings. Bottom-up triangulation against customs trade data for titanium alloy imports and top-down reconciliation with avionics OEM revenue disclosures solidifies demand quantification.
Calibration across the projection horizon applies segment-specific CAGRs derived from fleet renewal program schedules, regulatory mandate enforcement timelines, and technology displacement curves for solid-state versus magnetic tape architectures. Modeled dimensions span product type, end user, memory technology, and application purpose. Forecast inputs incorporate narrow-body delivery schedules at Boeing, Airbus, and COMAC final assembly lines alongside military platform modernization appropriations.
Stress conditions across titanium alloy supply disruption, FAA-EASA certification timeline divergence, and real-time streaming technology adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fleet replacement cycle timing. Material shifts in ICAO underwater locator beacon standards or COMAC C919 production ramp would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market