
 Epilepsy Treatment Market | 2026-2036
Epilepsy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Epilepsy Treatment Market Intelligence
The development of therapies for drug-resistant epilepsy is reorganizing the competitive landscape for antiepileptic drugs. UCB Pharma leverages its established portfolio and clinical expertise in treating both focal and generalized seizures. Eisai differentiates through its focus on novel mechanisms of action, while Xenon Pharmaceuticals competes by advancing its pipeline of precision medicine candidates for rare genetic epilepsies.
Epilepsy treatment involves interventions to control seizures from abnormal brain electrical activity, primarily using pharmacological agents that modulate neurotransmitter activity. These agents, such as sodium channel blockers, form the core of therapy. Antiepileptic drugs represent the largest product segment, with oral medications as the standard delivery mode. Treatments for focal seizures command the largest share, but demand for neurostimulation devices for refractory cases is increasing.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency (EMA) dictates market access, demanding extensive clinical data for new drug approvals. China's NMPA and Japan's PMDA are also streamlining review processes to accelerate therapy availability. Stakeholders must navigate the transition from broad-spectrum antiepileptics to genetically targeted treatments and new reimbursement models.
Market Dynamics
The transition from broad-spectrum antiepileptics to genetically targeted therapies is the central force shaping the epilepsy treatment market. This shift creates new value pools in diagnostics and precision medicine, while demanding new clinical trial designs and regulatory engagement strategies.
Growth Catalysts
- Targeted Genetic Therapies:The advancement of genomic sequencing is enabling the development of drugs for specific genetic mutations linked to epilepsy, such as SCN1A, improving treatment efficacy for rare and severe forms of the condition.
- Public Health Initiatives:Government-led programs in China and India are expanding neurological care infrastructure and improving access to diagnosis and treatment, particularly in rural and underserved areas, which addresses a large patient population.
- Regulatory Streamlining:Fast-track and priority review designations offered by regulators like the US FDA and Japan's PMDA reduce development timelines for novel therapies addressing significant unmet needs in drug-resistant epilepsy.
Market Restraints
- High Treatment Costs:The significant expense associated with developing and manufacturing novel biologics and gene therapies creates substantial pricing and reimbursement hurdles, limiting patient access in markets without robust coverage mechanisms.
- Generic Drug Erosion:The patent expiration of many first- and second-generation antiepileptic drugs leads to intense price competition from generic manufacturers, pressuring revenue for branded incumbents and reducing funds for new research.
- Diagnostic Gaps:In many regions, a lack of access to advanced neuroimaging and genetic testing facilities prevents accurate diagnosis of specific epilepsy syndromes, hindering the adoption of targeted and more effective treatments.
Strategic Opportunities
- Neurostimulation Devices:The market for implantable devices like vagus nerve stimulation (VNS) and responsive neurostimulation (RNS) is underpenetrated, especially in Latin America and Southeast Asia, for treating refractory epilepsy cases.
- Digital Health Integration:The convergence of wearable seizure detection devices with telehealth platforms offers a new channel for long-term patient monitoring, data collection for clinical trials, and personalized care management.
- Orphan Drug Incentives:Regulatory frameworks like the Orphan Drug Act in the United States provide market exclusivity and financial incentives, creating a favorable business case for developing treatments for rare pediatric epilepsies.
Industry Challenges
- Reimbursement Complexity:Securing favorable reimbursement status for high-cost, innovative treatments from diverse public and private payers requires extensive health economic outcome data, delaying market access after regulatory approval.
- Specialized Talent Scarcity:A shortage of clinical trial specialists, epileptologists, and genetic counselors trained in precision medicine limits the capacity to conduct complex studies and effectively deliver new genetic therapies to patients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epilepsy Treatment Market |
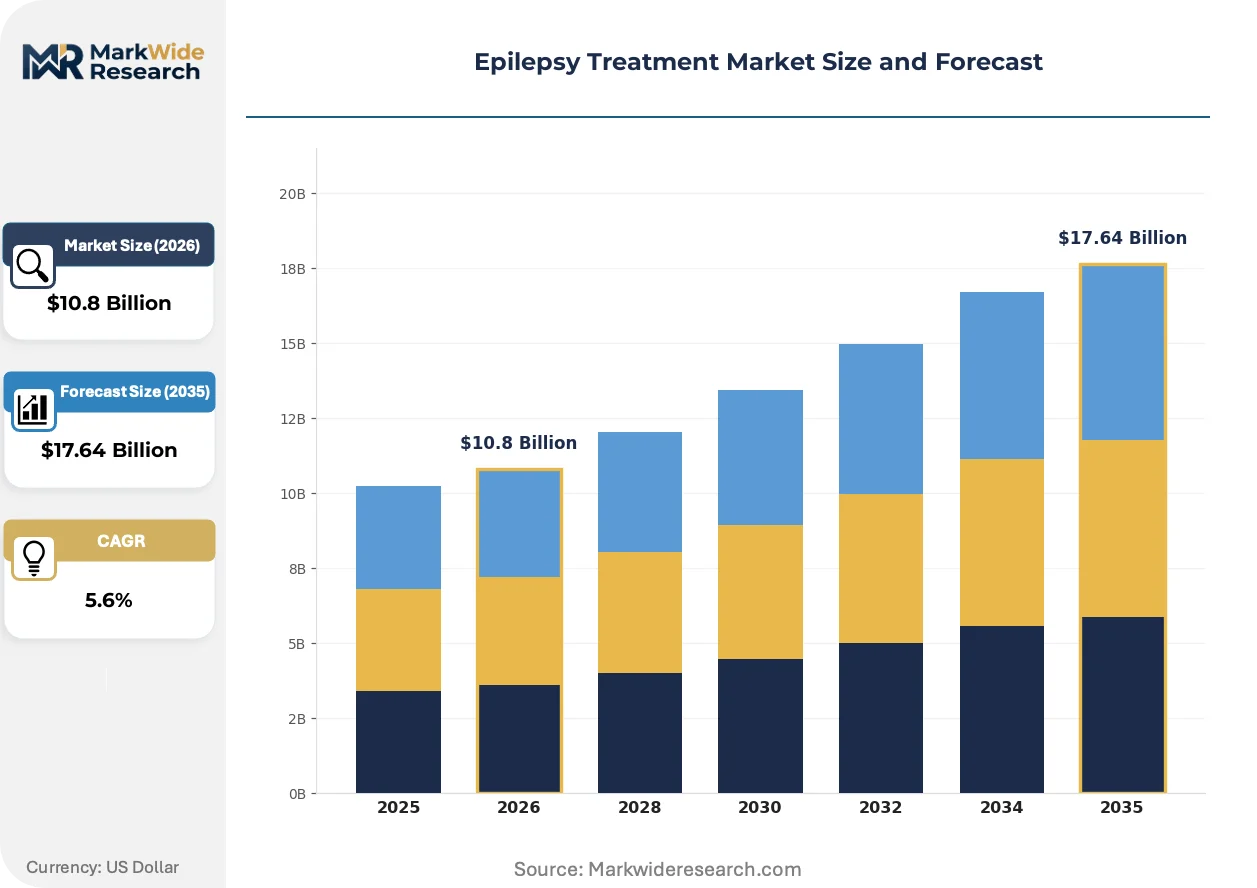
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Focal Seizures, Generalized Seizures, Absence Seizures, Myoclonic Seizures, Atonic Seizures, Tonic-Clonic Seizures Product Type: Antiepileptic Drugs, Surgical Devices, Neurostimulation Devices, Biosensors, Diagnostic Equipment, Supportive Care Products End User: Neurology Clinics, Specialized Hospitals, Rehabilitation Centers, Diagnostic Labs, Research Institutes Delivery Mode: Oral Medication, Intravenous Injection, Implantable Devices, Wearable Devices, Transdermal Patches |
| Companies Covered | Pfizer, UCB Pharma, Novartis, GlaxoSmithKline, Eisai, Jazz Pharmaceuticals, Takeda, Xenon Pharmaceuticals, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epilepsy Treatment Market Strategic Shifts & Innovations
Personalization is redefining the therapeutic approach to epilepsy, moving the focus from generalized seizure suppression toward correcting underlying etiologies. This evolution influences everything from drug discovery platforms to patient care models, with an emphasis on long-term outcomes beyond seizure frequency.
Implantable neurostimulation systems provide an alternative for patients with drug-resistant epilepsy. These devices, which deliver electrical pulses to modulate brain activity, are seeing wider use in specialized epilepsy centers. The technology is miniaturizing, which enables less invasive surgical procedures and improves patient comfort, paving the way for next-generation closed-loop systems.
Regulatory frameworks are adapting to the rise of precision medicine. The EMA's PRIME (PRIority MEdicines) scheme, for example, provides early and enhanced support to developers of medicines targeting unmet needs. This pathway facilitates dialogue and expedites the assessment of promising therapies for severe or rare epilepsies, directly affecting development strategies for gene-based treatments.
Patient engagement in treatment decisions is becoming more structured, moving beyond simple adherence to active collaboration. The use of genetic testing results empowers patients and their families to participate in choosing therapies, especially when multiple options for a specific genetic mutation exist. This shift is most visible in the pediatric epilepsy communities within the United States and Europe.
Epilepsy Treatment Market Segmentation
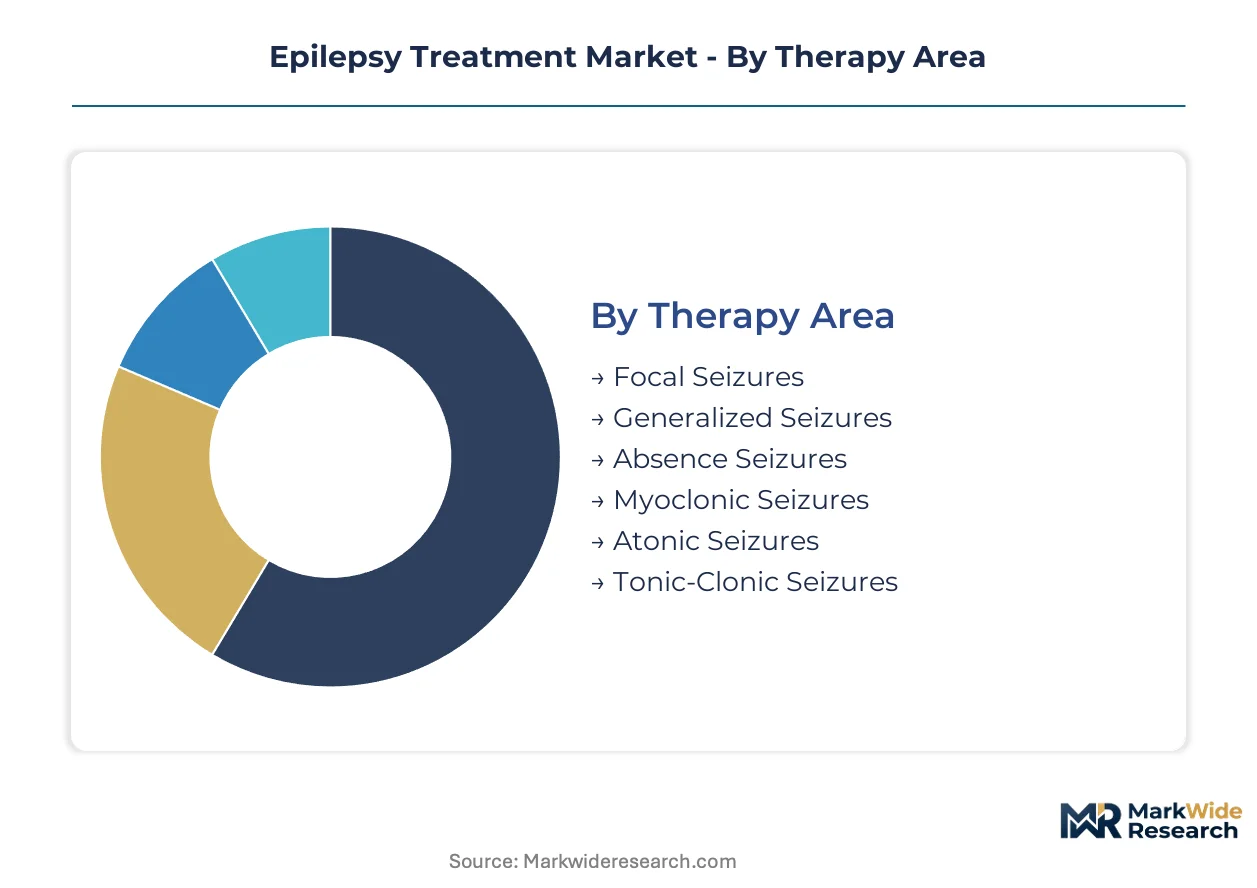
Understanding the segmentation of the epilepsy treatment market is critical for stakeholders to identify areas of concentrated demand and emerging therapeutic preferences. This analysis dissects the market by therapy area, product type, end user, and delivery mode, revealing how different treatment modalities and patient populations shape commercial strategies.
Therapy Area:
The market for epilepsy treatment is influenced by regional prevalence rates of specific seizure types, which dictates demand for specialized therapies across different geographies.
- Focal Seizures:These seizures originate in one area of the brain, affecting specific functions. Treatments for focal seizures command the largest market share, particularly in developed economies like the United States where diagnosis is more precise.
- Generalized Seizures:Characterized by widespread electrical activity across both brain hemispheres, these seizures require broad-spectrum antiepileptic drugs. Public health initiatives in China and India are expanding access to diagnosis and treatment for this patient group.
- Absence Seizures:Brief, sudden lapses of consciousness, often seen in childhood.
- Myoclonic Seizures:Sudden, brief jerks or twitches of a muscle or group of muscles.
- Atonic Seizures:Characterized by a sudden loss of muscle tone, causing the individual to fall.
- Tonic-Clonic Seizures:Formerly known as grand mal seizures, involving stiffening and rhythmic jerking.
Focal Seizures holds the largest share; momentum sits with Generalized Seizures.
Product Type:
Product type segmentation reflects varying investment levels in research and development, with high-cost innovative solutions coexisting with established, more affordable options.
- Antiepileptic Drugs:These pharmacological agents modulate neurotransmitter activity to control seizures, forming the core of epilepsy therapy. Generic drug erosion pressures revenue for branded incumbents, particularly in markets like Germany and the United Kingdom.
- Neurostimulation Devices:Implantable devices such as vagus nerve stimulators and responsive neurostimulation systems deliver electrical pulses to modulate brain activity. Demand for these devices is increasing for refractory cases across North America and Western Europe.
- Surgical Devices:Tools and equipment used in resective surgery or other neurosurgical procedures for epilepsy.
- Biosensors:Wearable or implantable sensors designed for real-time seizure detection and patient monitoring.
- Diagnostic Equipment:Advanced neuroimaging and genetic testing facilities crucial for accurate epilepsy syndrome diagnosis.
- Supportive Care Products:Products and services aimed at improving patient quality of life and managing co-morbidities.
Antiepileptic Drugs lead in market volume; Neurostimulation Devices are experiencing the steepest expansion trajectory.
End User:
The end-user landscape illustrates the primary points of patient care delivery, highlighting specialized facilities versus broader healthcare settings for epilepsy management.
- Neurology Clinics:These specialized outpatient facilities provide diagnosis, treatment, and long-term management for epilepsy patients. Expanding access within these clinics in countries like Japan improves patient outcomes.
- Specialized Hospitals:Tertiary care centers with dedicated epilepsy monitoring units and surgical capabilities for complex cases. These hospitals often serve as referral centers in major urban areas, including Paris and London.
- Rehabilitation Centers:Facilities offering physical, occupational, and cognitive therapy to patients recovering from severe seizures or epilepsy surgery.
- Diagnostic Labs:Laboratories performing advanced genetic testing and biomarker analysis for epilepsy.
- Research Institutes:Academic and commercial entities focused on discovering new epilepsy treatments and understanding disease mechanisms.
Neurology Clinics represent the largest segment; Specialized Hospitals are gaining share fastest.
Delivery Mode:
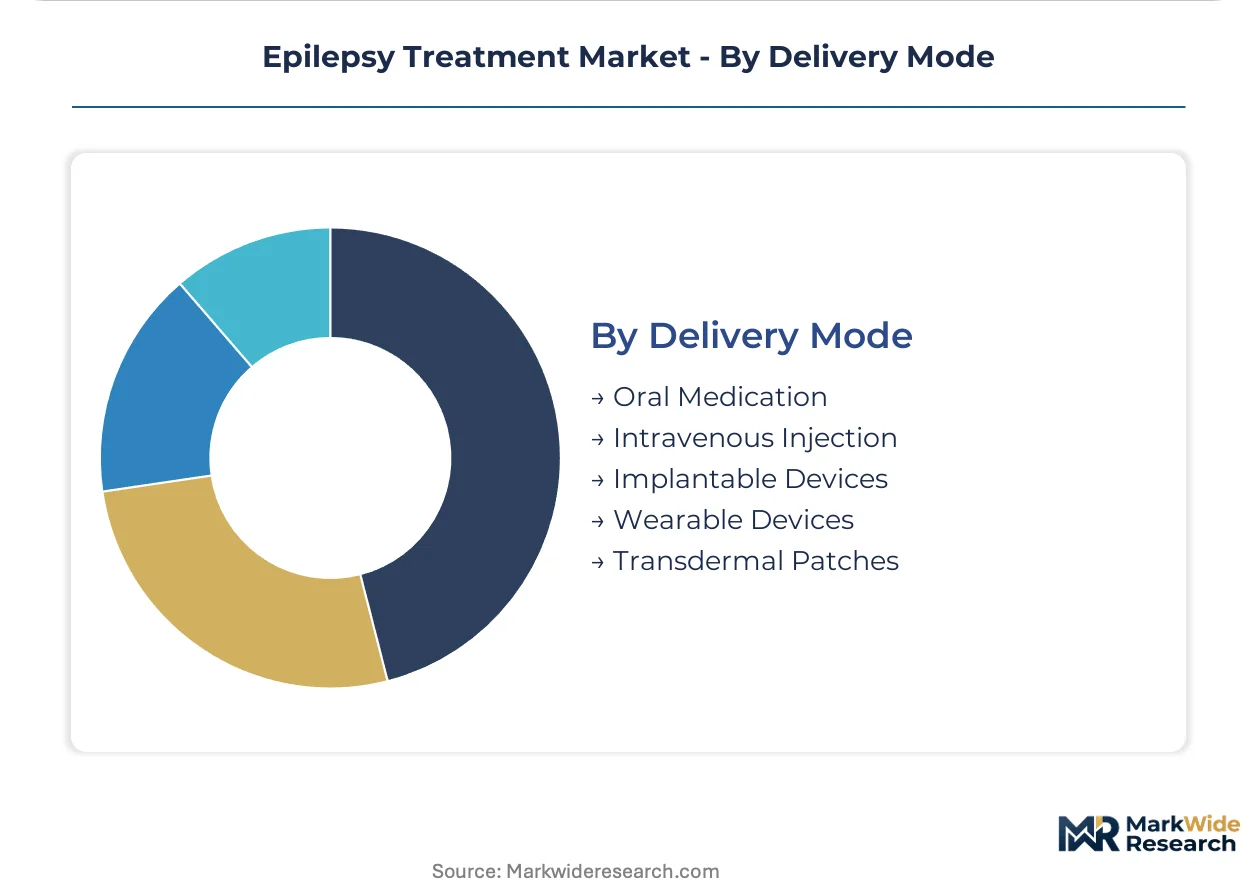
Delivery mode segmentation reveals patient preference and clinical efficacy for administering antiepileptic treatments, ranging from traditional oral forms to advanced implantable technologies.
- Oral Medication:Tablets, capsules, and liquids taken by mouth represent the standard and most common delivery method for antiepileptic drugs. This mode dominates across all major markets due to convenience and cost-effectiveness.
- Implantable Devices:These include neurostimulation devices and drug delivery systems surgically placed within the body for long-term seizure control. Their adoption is growing in regions with advanced healthcare infrastructure, such as Germany and the United States.
- Intravenous Injection:Used for rapid seizure control in acute settings, particularly in hospital emergency departments.
- Wearable Devices:Non-invasive sensors and monitors designed for seizure detection and patient data collection outside clinical settings.
- Transdermal Patches:Skin patches that deliver medication continuously through the skin, offering an alternative for patients with adherence issues.
Oral Medication commands the highest usage; Implantable Devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for epilepsy treatments is evident in regions with advanced pharmaceutical manufacturing capabilities and robust research infrastructure. These areas drive innovation in targeted genetic therapies and neurostimulation devices. This concentration underpins global market dynamics and shapes access to advanced treatments.
United States
Demand for advanced epilepsy treatments in the United States is driven by high prevalence of drug-resistant cases and strong investment in R&D. The US FDA's fast-track designations accelerate the availability of novel therapies for unmet needs. Major pharmaceutical hubs like Boston and San Francisco are centers for developing precision medicine candidates.
China
Extensive public health initiatives and a rapidly aging population fuel demand for antiepileptic drugs and expanded neurological care in China. The NMPA is streamlining review processes to accelerate therapy availability across the country. Large urban centers such as Shanghai and Beijing are expanding specialized neurology clinics.
Germany
Germany's demand for epilepsy treatments stems from its advanced healthcare system and a focus on high-quality patient management. The European Medicines Agency (EMA) influences market access, requiring extensive clinical data for new drug approvals. Pharmaceutical clusters in regions like Bavaria and North Rhine-Westphalia are active in developing new antiepileptic drugs.
Japan
Japan's market for epilepsy treatment is characterized by expanding access within specialized neurology clinics and a focus on long-term patient management. The PMDA streamlines review processes, accelerating therapy availability for novel treatments. Research institutions in Tokyo and Osaka are advancing neurostimulation device technologies.
India
Government-led public health programs in India are improving access to diagnosis and treatment, particularly in rural and underserved areas. The CDSCO is working to ensure the availability of essential antiepileptic drugs across diverse patient populations. Pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad contribute significantly to generic drug supply.
Epilepsy Treatment Market Key Industry Players
Concentration sits with established pharmaceutical companies leveraging extensive portfolios and clinical expertise in epilepsy treatment. The market exhibits a tiered structure, with large incumbents and specialized biotech firms driving innovation. Companies are actively pursuing strategic partnerships for pipeline acceleration, particularly in genetic therapies, and geographic expansion into emerging markets. Portfolio diversification into targeted genetic therapies and neurostimulation devices also represents a key competitive move.
Specialists in novel mechanisms and precision medicine candidates, such as Eisai and Xenon Pharmaceuticals, differentiate through their focus on unmet needs in drug-resistant epilepsy. Eisai emphasizes developing drugs with unique modes of action to address refractory cases, while Xenon Pharmaceuticals advances a pipeline of precision medicine candidates for rare genetic epilepsies. UCB Pharma represents a major player, leveraging its established portfolio and extensive clinical expertise across both focal and generalized seizures. These companies navigate complex regulatory frameworks, including priority review designations, to bring innovative treatments to market, impacting patient care and competitive dynamics.
| Leading Market Players |
|---|
| Pfizer |
| UCB Pharma |
| Novartis |
| GlaxoSmithKline |
| Eisai |
| Jazz Pharmaceuticals |
| Takeda |
| Xenon Pharmaceuticals |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Generic drug erosion, as a substitution dynamic for branded antiepileptics, simultaneously reshapes the global supply chain towards cost-efficient manufacturing hubs and drives significant pricing compression across established drug classes. This shift reallocates value within the market.
Pricing Analysis
US FDA and European Medicines Agency (EMA) regulations dictate the pricing tier structure for new epilepsy treatments, demanding extensive clinical data for premium approvals. Value-based pricing models are emerging for genetically targeted therapies, driving differentiation based on efficacy for specific mutations and after-sales service for devices. Pricing stratifies across premium novel biologics and cost-effective generic antiepileptic drugs, with brand premium and certification level influencing price differentiation. Pricing pressure stems from generic drug erosion, particularly impacting first and second-generation antiepileptic drugs, making public health programs in China highly price-sensitive compared to private payers in the United States.
Supply Chain Analysis
India and China anchor generic antiepileptic drug manufacturing, supplying active pharmaceutical ingredients (APIs) and finished formulations globally. Advanced neurostimulation devices and novel biologics primarily source from specialized facilities in the United States and Germany. The supply chain relies on a diverse range of chemical raw materials for drug synthesis and microelectronics for device components. Single-source vulnerability for specific rare disease genetic therapies presents a significant supply chain risk, while distribution runs through pharmaceutical wholesalers and specialized medical device distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epilepsy treatment market represents a defensive-moat story, primarily due to significant regulatory entrenchment requiring extensive clinical data and specialized expertise for market access. This structural advantage limits new competition and stabilizes revenue streams for established players.
For Market Incumbents: Consolidate fragmented precision medicine pipelines through targeted acquisitions, particularly in rare genetic epilepsies, to counter the threat of specialized biotech firms. Invest in next-generation neurostimulation device R&D to maintain a competitive edge against increasing generic drug erosion. Reinforce clinical expertise across a broad portfolio to manage complex patient populations, leveraging existing relationships with neurology clinics. Expand market access for novel treatments by navigating evolving reimbursement models in key geographies.
For New Entrants and Emerging Players: US FDA fast-track designations and EMA's PRIME scheme offer a critical pathway for new entrants to target unmet needs in drug-resistant and rare pediatric epilepsies. Focus on developing novel mechanisms of action or precision medicine candidates for specific genetic mutations, which represents the most penetrable segment. Integrate digital health solutions, such as wearable seizure detection devices with telehealth platforms, to offer a differentiated go-to-market strategy. Leverage orphan drug incentives to secure market exclusivity and accelerate development timelines.
For Investors and Strategic Acquirers: The market sits at a transformative growth phase that favors specialized biotech firms with strong intellectual property in genetic therapies and neurostimulation. Long-term viability over the next 5-10 years remains strong, driven by persistent unmet needs in drug-resistant cases and an aging global population. Identify acquisition targets with robust pipelines in precision medicine, particularly those approaching late-stage clinical trials. The signal to watch is the increasing number of regulatory approvals for gene-based treatments for specific epilepsy syndromes.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel genetic therapies addressing specific SCN1A mutations. |
| Regulatory Approval Pathway | Streamlines access to priority review designations for innovative treatments in the United States. |
| Manufacturing Scale-Up | Ensures efficient production of complex biologics and advanced neurostimulation devices. |
| Strategic Partnership | Integrates digital health platforms for enhanced patient monitoring and data collection. |
| Pipeline Diversification | Expands therapeutic offerings into underpenetrated neurostimulation devices for refractory cases. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with robust secondary validation to inform the analysis. Engagements included epileptologists, regulatory affairs leads, hospital procurement managers, and genetic counselors. Secondary data sources encompassed FDA filings, EMA submissions, ClinicalTrials.gov, and specialized neurology society reports. This approach ensured comprehensive bottom-up and top-down triangulation of market insights.
Across the analysis window, the market was segmented by therapy area, product type, end user, and delivery mode. Volume and value outputs reflect a triangulated approach, with compound annual growth rates (CAGRs) derived from historical trends and future projections. Key forecast inputs included the antiepileptic drug R&D pipeline and anticipated regulatory approvals for novel genetic therapies. This framework provides a granular view of market evolution.
Underlying assumptions cover regulatory stability and R&D success rates, with deviation risk concentrated in unforeseen clinical trial failures or significant changes in reimbursement policies. Forecasts reflect these documented assumptions, acknowledging the dynamic nature of therapeutic innovation. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market