
 United States Dry Eye Syndrome Market | 2026-2036
United States Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dry Eye Syndrome Market Intelligence
Hyaluronic acid is expanding its share in artificial tear formulations as manufacturers replace older cellulose-based viscosifiers with polymer systems that extend ocular surface retention. Novartis AG leverages its ophthalmology heritage to sustain premium positioning in prescription anti-inflammatory segments. Bausch + Lomb anchors the retail channel through broad distribution of over-the-counter lubricant drops. Alcon Inc. differentiates via integrated diagnostic-to-treatment platforms that bundle tear film analysis with targeted therapy selection.
Dry eye syndrome denotes a multifactorial disorder of the tear film characterized by hyperosmolarity, inflammation, and ocular surface damage, typically quantified by tear break-up time below ten seconds and osmolarity exceeding 308 mOsm/L; its primary purpose is to restore homeostasis to the ocular surface and prevent progressive corneal epitheliopathy. Artificial tears constitute the volume foundation of the market while anti-inflammatory drugs capture disproportionate margin pools due to chronic therapy requirements and specialist gatekeeping. Punctal plugs remain a procedural niche with concentrated utilization in academic medical centers, whereas lipid-based drops are gaining share as meibomian gland dysfunction recognition improves among optometrists.
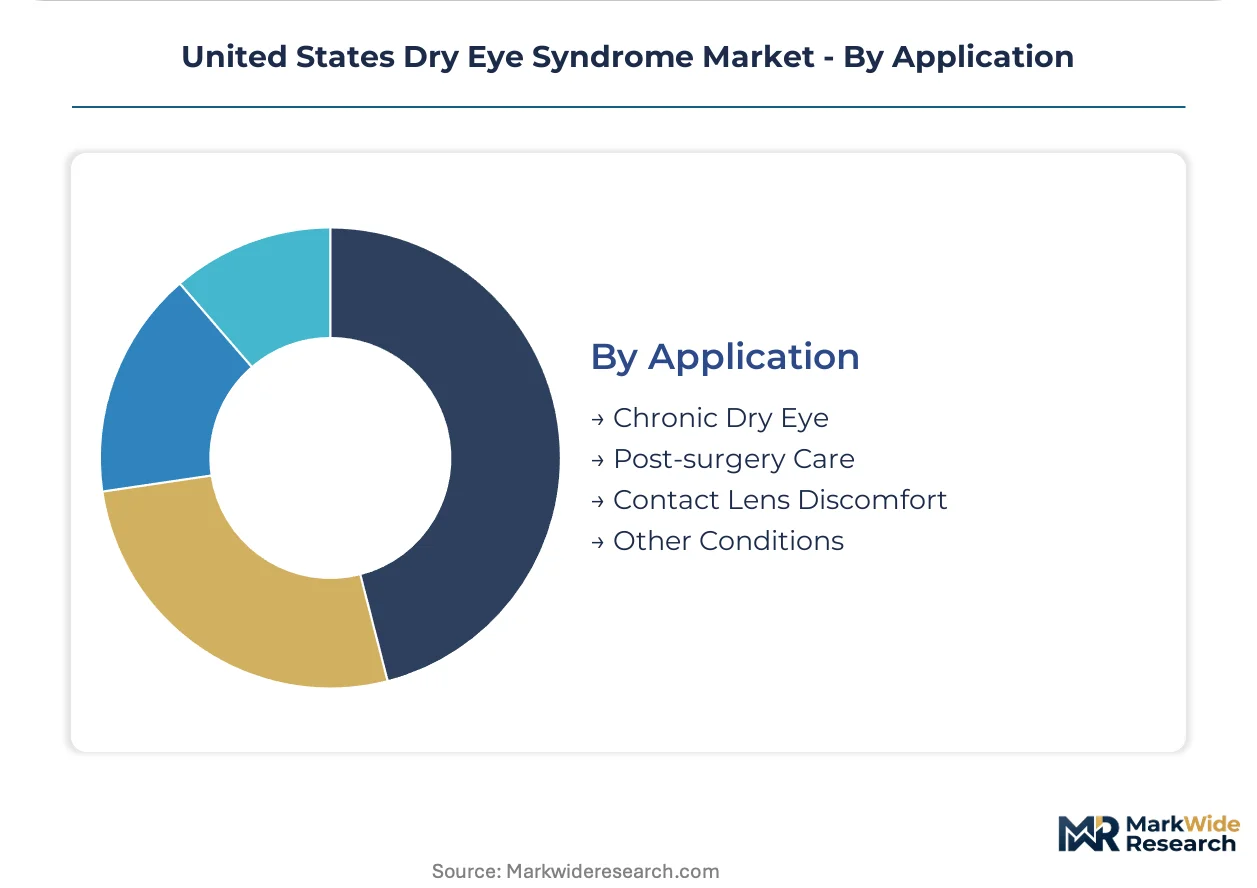
FDA oversight of ophthalmic preservatives, particularly benzalkonium chloride concentration limits, shapes formulation strategies and accelerates preservative-free line extensions. The EPA regulates manufacturing discharge from active pharmaceutical ingredient facilities, influencing domestic production economics for cyclosporine and lifitegrast intermediates. State pharmacy boards in California, Texas, and Florida enforce distinct compounding standards for office-use biologics that fragment access patterns. Stakeholders must monitor whether FDA advanced manufacturing designations for continuous processing will reshape cost structures for topical ophthalmic production.
Market Dynamics
The FDA's tightening benzalkonium chloride concentration limits are forcing domestic manufacturers into preservative-free reformulation cycles, reshaping production economics and accelerating line-extension investments across artificial tear portfolios.
Growth Catalysts
- Sun Belt Demographics:Aging populations in Arizona, Texas, and Florida concentrate disease prevalence where arid climates compound evaporative dry eye pathology, driving specialist service-line expansion.
- Meibomian Gland Recognition:Optometrists now diagnose meibomian gland dysfunction at higher rates, pulling lipid-based formulations into earlier treatment protocols and expanding addressable patient pools.
- Continuous Manufacturing Designations:FDA advanced manufacturing programs for topical ophthalmic production promise unit cost compression that domestic cyclosporine and lifitegrast suppliers are positioning to capture.
Market Restraints
- API Manufacturing Discharge Costs:EPA effluent regulations on active pharmaceutical ingredient facilities elevate domestic production economics for immunomodulator intermediates versus offshore alternatives.
- Specialist Gatekeeping:Prescription anti-inflammatory therapy requires ophthalmologist or optometrist authorization, constraining volume velocity relative to over-the-counter lubricant access.
- Cellulose Viscosifier Obsolescence:Older artificial tear formulations face raw material sourcing compression as suppliers prioritize hyaluronic acid polymer systems.
Strategic Opportunities
- Integrated Diagnostic Platforms:Tear film analysis hardware bundled with targeted therapy selection creates stickier provider relationships and higher-margin revenue capture.
- California Compounding Standards:State pharmacy board office-use biologics regulations fragment access patterns, creating niche positioning for compliant regional manufacturers.
- Punctal Plug Procedural Uptake:Academic medical centers demonstrate concentrated utilization that community ophthalmology clinics can replicate with proper training infrastructure.
Industry Challenges
- Osmolarity Testing Calibration:Tear film osmolarity measurement standardization gaps between diagnostic platforms create treatment protocol inconsistency and reimbursement friction.
- Preservative-Free Packaging Scale:Unit-dose vial manufacturing capacity constraints limit line-extension velocity for reformulated artificial tear portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dry Eye Syndrome Market |
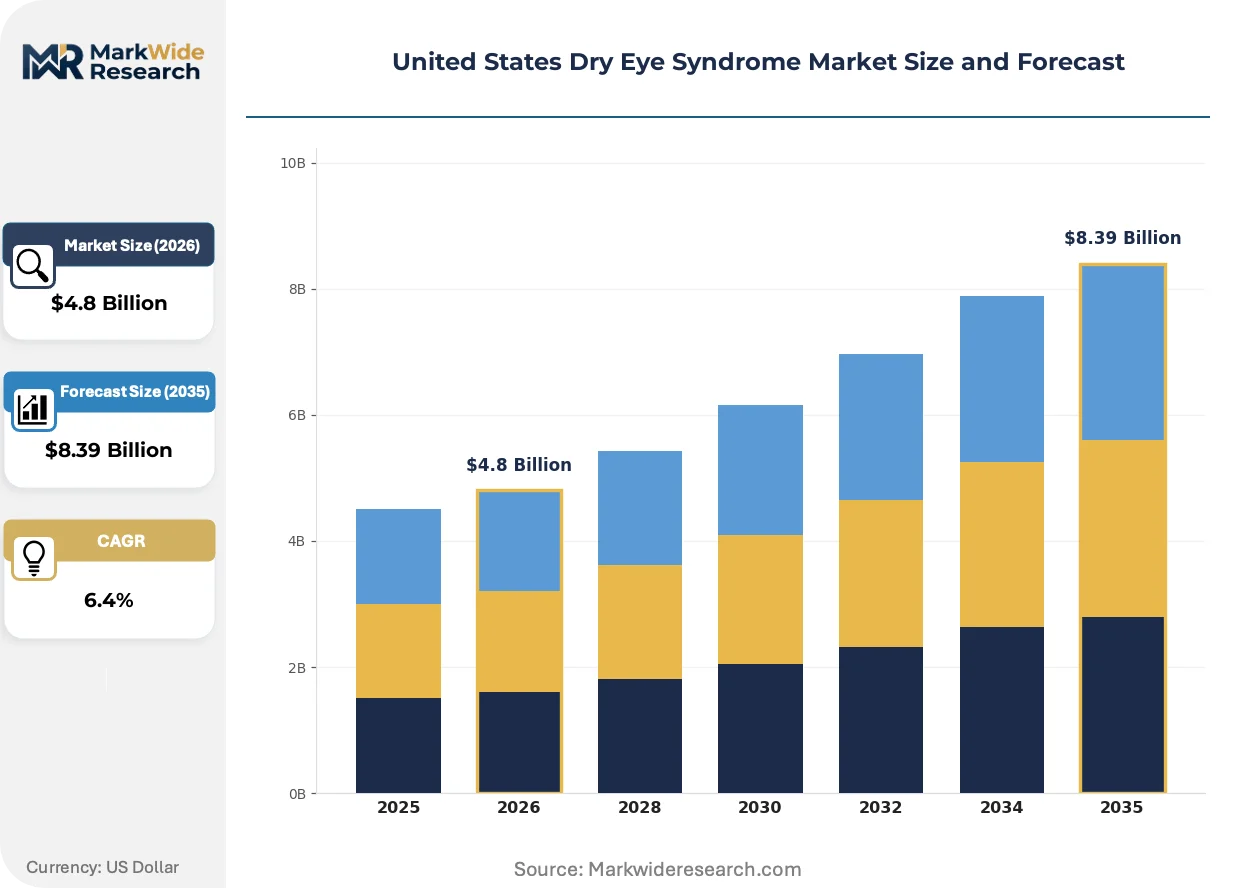
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-inflammatory Drugs, Punctal Plugs, Lipid-based Drops Delivery Mode: Topical, Oral, Injectable, Surgical End User: Ophthalmology Clinics, Hospitals, Homecare, Pharmacies Application: Chronic Dry Eye, Post-surgery Care, Contact Lens Discomfort, Other Conditions |
| Companies Covered | AbbVie Inc., Novartis AG, Bausch + Lomb, Santen Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., Alcon Inc., Johnson & Johnson, OASIS Medical, Inc., Viatris Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dry Eye Syndrome Market Strategic Shifts & Innovations
Reformulation investments are concentrating around polymer chemistry advances and diagnostic integration, with manufacturers racing to align portfolios with evolving FDA preservative guidance and specialist workflow preferences.
Hyaluronic acid polymer systems are electrifying artificial tear formulation strategies by extending ocular surface retention beyond cellulose-based viscosifier performance. Ophthalmology clinics and optometry practices are adopting these reformulations at accelerating pace as first-line therapy. The technology is electrifying margin structures by supporting premium positioning against commoditized lubricant drops while reducing dosing frequency compliance burdens.
EPA discharge regulations on active pharmaceutical ingredient manufacturing are elevating domestic production economics for cyclosporine and lifitegrast intermediates. Facilities in high-compliance-cost jurisdictions face capital intensity pressures that reshape sourcing decisions for topical immunomodulators. Prescription anti-inflammatory segments bear the greatest impact, with manufacturers exploring continuous processing investments to offset regulatory-driven cost structures.
Specialist channel consolidation is compressing the traditional retail-to-prescription patient journey for moderate-to-severe dry eye cases. Integrated ophthalmology service lines are displacing fragmented optometry-to-pharmacy handoffs, particularly in metropolitan Sun Belt markets where dedicated dry eye centers capture higher therapy adherence rates. This behavioral shift is most visible in Florida and Texas, where health system vertical integration into ophthalmology accelerates diagnostic-to-treatment platform adoption.
United States Dry Eye Syndrome Market Segmentation
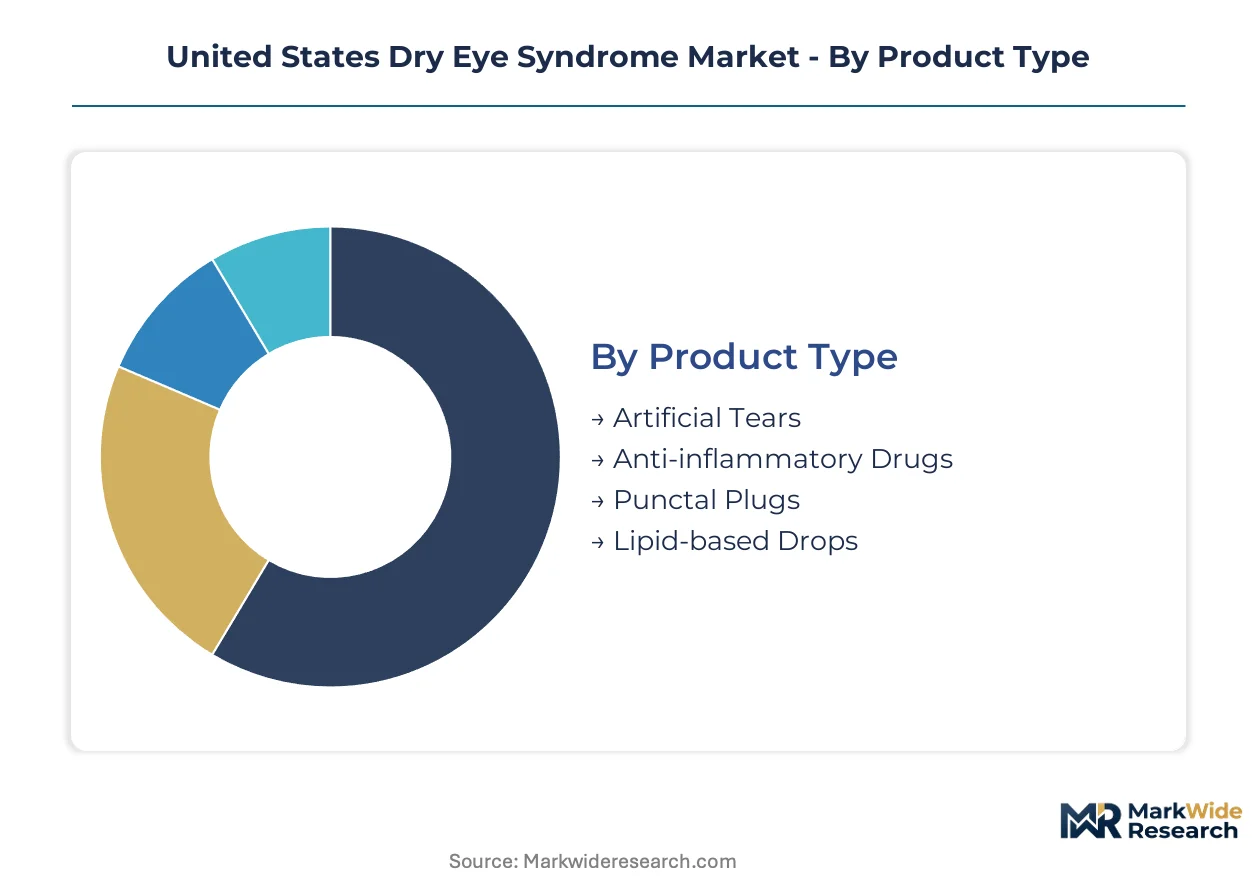
Dry eye syndrome treatment pathways fragment across product chemistry, delivery mechanism, care setting, and disease severity. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across the United States.
Product Type:
Capital intensity varies sharply across this category, with anti-inflammatory drug manufacturing demanding specialized active pharmaceutical ingredient facilities while artificial tear production scales through conventional formulation infrastructure.
- Artificial Tears:Hyaluronic acid polymer systems now dominate new formulation investments, displacing cellulose-based viscosifiers in premium line extensions. Arizona, Texas, and Florida concentrate volume demand where arid climates compound evaporative pathology and drive higher dosing frequency.
- Anti-inflammatory Drugs:Cyclosporine and lifitegrast formulations require immunomodulator synthesis capabilities under FDA current good manufacturing practice. EPA discharge regulations on API manufacturing elevate domestic production economics versus offshore alternatives, compressing margin structures for prescription segments.
- Punctal Plugs:Silicone and collagen-based occlusion devices involve lower capital barriers but demand sterile manufacturing validation.
- Lipid-based Drops:Meibomian gland dysfunction recognition pulls these formulations into earlier treatment protocols without requiring new manufacturing infrastructure.
Artificial tears absorb the bulk of installed capacity; lipid-based drops are expanding most quickly.
Delivery Mode:
Route of administration determines reimbursement coding complexity and patient compliance economics, with topical formulations capturing volume leadership and surgical modalities commanding procedural premiums.
- Topical:Eye drops and ointments constitute the volume foundation, with preservative-free unit-dose vials driving manufacturing capacity investments. Ophthalmology clinics in Sun Belt states prioritize these formulations for first-line therapy given climate-driven evaporative stress.
- Oral:Systemic omega-3 and tetracycline derivatives address meibomian gland dysfunction through dermatological pathways. Homecare settings concentrate demand where patient self-administration reduces specialist visit burden.
- Injectable:Corticosteroid and biologic injections serve refractory cases in academic medical centers with procedural infrastructure.
- Surgical:Punctal cautery and salivary gland transplantation remain concentrated in tertiary referral networks with specialized surgical volume.
Topical delivery anchors volume throughput; surgical modalities generate the highest per-procedure revenue capture.
End User:
Channel economics diverge between institutional procurement and retail access, with specialist gatekeeping constraining prescription velocity versus over-the-counter lubricant availability.
- Ophthalmology Clinics:Dedicated dry eye service lines bundle diagnostic hardware with targeted therapy selection. Florida and Texas health systems demonstrate accelerating vertical integration into these service lines, displacing fragmented optometry-to-pharmacy handoffs.
- Hospitals:Post-surgical dry eye protocols and inpatient ophthalmology consultations drive cyclical demand tied to cataract and refractive surgery volumes.
- Homecare:Chronic therapy maintenance concentrates here, with mail-order pharmacy and direct-to-patient subscription models gaining traction for preservative-free artificial tear replenishment.
- Pharmacies:Retail channel access for over-the-counter lubricants faces margin compression as ophthalmology clinics capture moderate-to-severe cases upstream.
Ophthalmology clinics command the highest therapy adherence rates; homecare channels are scaling fastest through direct distribution models.
Application:
Disease severity and etiology determine treatment intensity, with chronic cases requiring sustained immunomodulator exposure and acute post-surgical applications demanding rapid intervention protocols.
- Chronic Dry Eye:Long-duration anti-inflammatory therapy and punctal occlusion dominate this segment. Meibomian gland dysfunction recognition in Texas and Arizona optometry practices is expanding addressable pools for lipid-based interventions.
- Post-surgery Care:Cataract and LASIK procedures generate acute demand for preservative-free lubricants and short-course corticosteroids. Hospital outpatient departments concentrate this episodic volume.
- Contact Lens Discomfort:Daily disposable lens wearers and silicone hydrogel adopters drive lubricant companion sales through retail optical channels.
- Other Conditions:Sjogren's syndrome, graft-versus-host disease, and medication-induced dry eye represent smaller addressable populations with specialized therapeutic requirements.
Chronic dry eye absorbs the majority of ongoing prescription volume; post-surgery care delivers the most concentrated per-patient revenue events.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry eye syndrome prevalence clusters in the Sun Belt states where aging demographics intersect with arid climate conditions. Texas, Florida, Arizona, and California concentrate both patient volume and specialist service-line expansion.
Texas
Houston and Dallas metropolitan areas host expanding ophthalmology service lines targeting evaporative dry eye pathology. State pharmacy board regulations on office-use biologics compounding create compliance differentiation for regional manufacturers. The Texas Medical Center in Houston anchors diagnostic-to-treatment platform adoption among academic referral networks.
Florida
Retiree migration from the Northeast elevates disease prevalence in Tampa and Miami metropolitan corridors. FDA preservative guidance drives reformulation investments by distribution centers serving the southeastern prescription channel. Health system vertical integration into ophthalmology accelerates in Orlando and Jacksonville markets.
Arizona
Phoenix and Tucson concentrate the nation's highest per-capita dry eye diagnosis rates due to desert climate exposure. EPA discharge regulations on API manufacturing elevate domestic production economics for immunomodulator intermediates. The Mayo Clinic Arizona campus in Scottsdale demonstrates concentrated punctal plug utilization that community clinics seek to replicate.
California
Los Angeles and San Francisco Bay Area ophthalmology practices lead adoption of tear film analysis hardware. State pharmacy board standards for compounded biologics fragment access patterns, favoring compliant regional manufacturers. Stanford and UCLA medical centers drive continuous processing investment interest among topical ophthalmic suppliers.
Southeast (Georgia/Carolinas)
Atlanta and Charlotte emerging markets show accelerating specialist recruitment for dedicated dry eye centers. Medicare reimbursement calibration for osmolarity testing creates protocol standardization opportunities. Emory and Duke ophthalmology departments anchor referral patterns that shape regional therapy selection norms.
United States Dry Eye Syndrome Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers extend preservative-free line offerings and bundle diagnostic hardware with therapeutic selections. The vendor base structures across three tiers: multinational pharmaceutical conglomerates with ophthalmology heritage, mid-cap specialty eye care companies, and regional compounding pharmacies serving state-specific biologics regulations. Strategic archetypes include integrated diagnostic-to-treatment platform operators, polymer chemistry specialists driving hyaluronic acid formulation advances, and channel-anchored retail lubricant distributors. M&A activity concentrates on tear film analysis technology acquisitions, while capacity expansion targets unit-dose vial manufacturing for preservative-free portfolios.
Among Swiss-based pharmaceutical conglomerates, Novartis AG occupies the premium prescription anti-inflammatory tier. Bausch + Lomb, a Canadian-heritage eye care specialist, anchors retail channel distribution through over-the-counter lubricant scale. Alcon Inc., the Swiss-American surgical and vision care company, exemplifies the integrated diagnostic platform archetype through tear film analysis bundling. These three entities represent distinct competitive vectors: heritage pharmaceutical innovation, mass-market accessibility, and technology-integrated service line capture.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Bausch + Lomb |
| Santen Pharmaceutical Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Alcon Inc. |
| Johnson & Johnson |
| OASIS Medical, Inc. |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
EPA discharge mandates on active pharmaceutical ingredient manufacturing gate qualified supply for cyclosporine and lifitegrast intermediates while simultaneously compressing margin structures that feed premium-tier pricing for prescription anti-inflammatory segments. Domestic manufacturers absorbing these compliance costs pass through selective pricing power to ophthalmology clinic channels, whereas artificial tear producers face raw material sourcing compression that limits economy-tier flexibility.
Pricing Analysis
Volume concentration in artificial tears runs counter to margin capture in anti-inflammatory drugs, creating a bifurcated pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates preservative-free hyaluronic acid formulations from cellulose-based legacy products and private-label commoditized drops. Price differentiation hinges on polymer chemistry sophistication and FDA compliance tier, with reformulation cycles intensifying cost compression in mid-market segments. Ophthalmology clinics exhibit lowest price sensitivity due to bundled diagnostic platform economics, while retail pharmacy channels face acute margin pressure from direct-to-patient subscription models.
Supply Chain Analysis
Domestic-content mandates embedded in FDA current good manufacturing practice standards reshape sourcing decisions for immunomodulator synthesis, elevating United States-based production economics versus offshore alternatives. Active pharmaceutical ingredient manufacturing draws from specialized facilities in the United States, India, and Switzerland, with cyclosporine and lifitegrast intermediates resting on fermentation-derived and synthetic chemistry inputs. Single-source vulnerability concentrates in sterile unit-dose vial manufacturing capacity, constraining preservative-free line-extension velocity. Distribution runs through health system vertical integration in Sun Belt metropolitan markets, displacing traditional wholesale-to-pharmacy pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA preservative guidance and EPA discharge compliance are systematically eliminating sub-scale domestic manufacturers lacking reformulation capital.
For Market Incumbents: Anticipate accelerated M&A activity targeting tear film analysis technology providers to complete diagnostic-to-treatment platform bundling. Alcon Inc.'s integrated hardware-therapy model demonstrates the defensive value of sticky provider relationships against retail channel margin erosion. Backward integration into hyaluronic acid polymer supply secures formulation flexibility as cellulose viscosifier sourcing compresses. For New Entrants and Emerging Players: Launch via California compounding pharmacy networks exploiting state pharmacy board office-use biologics regulations that fragment access patterns and create compliant regional positioning. White-space concentration sits in lipid-based drops for meibomian gland dysfunction cases migrating from optometry to earlier specialist intervention, particularly in Texas and Arizona metropolitan corridors. Direct-to-patient subscription models for preservative-free artificial tears bypass retail margin compression entirely. For Investors and Strategic Acquirers: FDA advanced manufacturing designations for continuous processing are the leading indicator that unit cost compression will reshape competitive economics for topical ophthalmic production. The five-to-ten year viability window favors platform-integrated operators over standalone formulation players. Acquisition targets should display tear film analysis hardware development capabilities or captive hyaluronic acid polymer supply. Watch for EPA enforcement actions on API facility discharge as the inflection signal for domestic production cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Line Extension | FDA benzalkonium chloride guidance accelerates reformulation investments by Novartis AG and Bausch + Lomb. |
| Diagnostic Platform Integration | Alcon Inc.'s tear film analysis bundling creates higher-margin revenue capture in ophthalmology clinics. |
| Continuous Manufacturing Scale-Up | Advanced processing designations promise unit cost compression for domestic cyclosporine suppliers. |
| Regional Compounding Compliance | California, Texas, and Florida pharmacy board standards fragment biologics access for compliant manufacturers. |
| Sun Belt Service Line Expansion | Health system vertical integration into ophthalmology accelerates in Houston, Dallas, and Tampa markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with ophthalmology clinic directors, formulary managers at health systems, GPO contracts specialists, and FDA regulatory affairs consultants provided ground-truth validation. Secondary sources encompassed FDA 510(k) and NDA submissions, EPA effluent compliance databases, state pharmacy board compounding regulations, and Medicare reimbursement schedules. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-validated segment estimates.
Granularity-level modeling operated at the intersection of product chemistry, delivery mechanism, and care setting dimensions across the projection horizon. Treatment line stratification separated artificial tears, anti-inflammatory drugs, punctal plugs, and lipid-based drops, with further disaggregation by preservative status and polymer system. Administration route captured topical, oral, injectable, and surgical modalities. CAGRs derived from patient prevalence trends, dosing frequency assumptions, and therapy adherence patterns calibrated against Medicare claims data and health system procurement records.
Regulatory enforcement intensity, EPA discharge cost pass-through elasticity, and specialist channel consolidation velocity are the dominant revision risks to forecast assumptions. Competitive responses to FDA advanced manufacturing designations and hyaluronic acid raw material sourcing disruptions introduce additional uncertainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Fungal Eye Infection Market